
 Polyvinyl Chloride (PVC) Market | 2026-2036
Polyvinyl Chloride (PVC) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Chloride (PVC) Market Intelligence
The rise of custom formulation services is rebalancing the PVC value proposition from a pure commodity to a performance-driven material solution. Shin-Etsu Chemical Co., Ltd. leverages its significant manufacturing scale to compete across both commodity and specialty grades. Westlake Corporation specializes in integrated production, from feedstock to finished PVC products, securing its supply chain. INEOS Group Holdings S.A. operates a broad portfolio across multiple chemical segments, providing resilience.
Polyvinyl chloride is a synthetic thermoplastic polymer produced through the polymerization of vinyl chloride monomer. Its properties are modified with plasticizers and additives, enabling its use in applications ranging from rigid pipes to flexible films. Rigid PVC dominates the product type landscape, primarily due to its extensive use in the construction sector for pipes, window profiles, and siding. The packaging application segment, while smaller, shows consistent demand for flexible PVC films.
Regulatory frameworks such as the EU's REACH legislation and the US EPA's standards for vinyl chloride emissions directly impact manufacturing processes and material composition. In China, national GB standards govern the quality and safety of PVC products for construction and consumer use. Future profitability will depend on navigating environmental regulations and investing in circular economy models for PVC recycling and production.
Market Dynamics
The central dynamic shaping the Polyvinyl Chloride market is the conflict between the need for large-scale, cost-efficient production centered in Asia and the increasing regulatory pressure in developed markets for sustainable, specialized formulations with non-hazardous additives.
Growth Catalysts
- Infrastructure Investment:Sustained government spending on urban development and water management projects in countries like India and Brazil directly stimulates demand for rigid PVC pipes, conduits, and profiles.
- Medical Device Advancement:The unique combination of chemical resistance, flexibility, and sterilizability of medical-grade PVC supports its use in blood bags, tubing, and catheters, with demand tied to healthcare system expansion. *Plasticizer Innovation: The development and commercialization of non-phthalate and bio-based plasticizers are creating new, premium-priced PVC compounds that meet stringent regulations and open access to sensitive applications.
Market Restraints
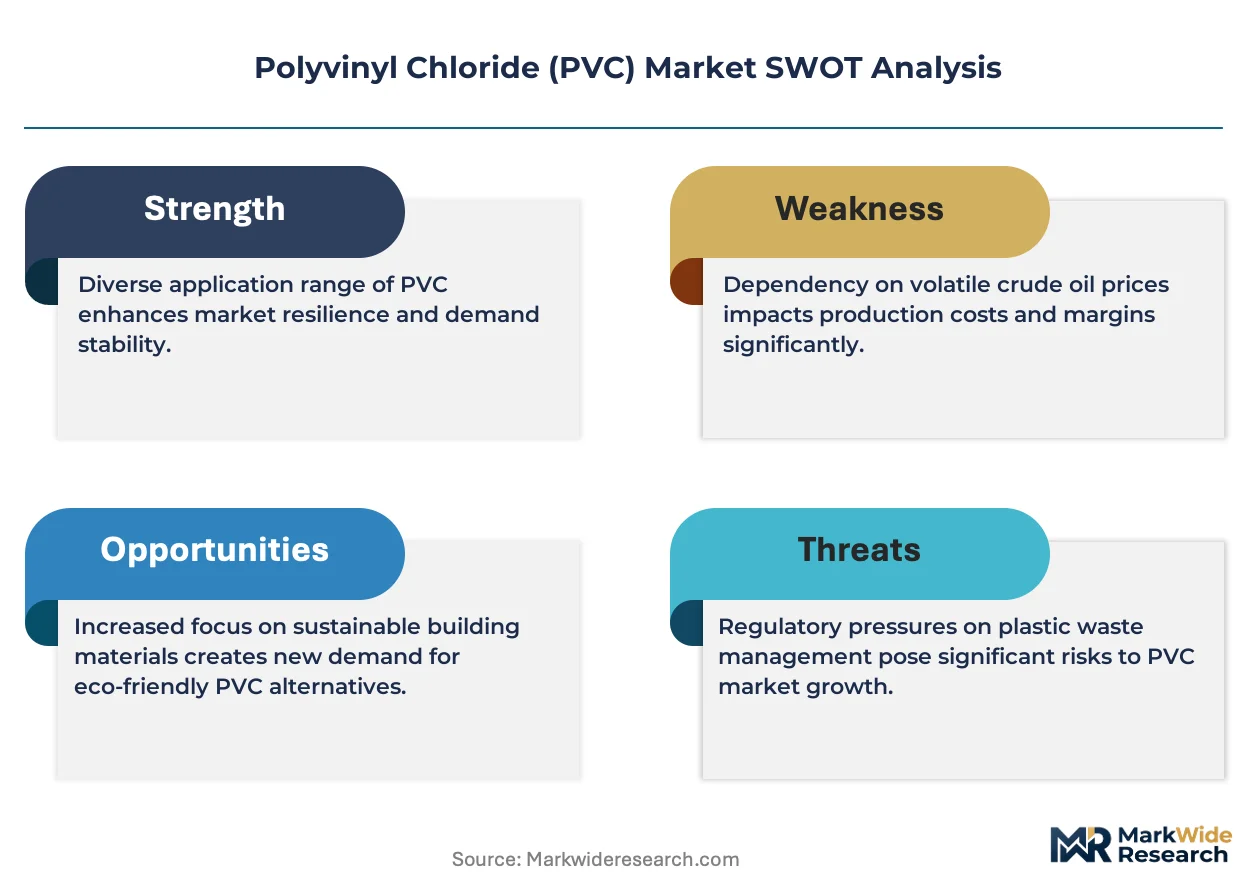
- Feedstock Price Volatility:PVC production costs are directly linked to fluctuating prices of ethylene and chlorine, creating margin pressure and pricing instability for manufacturers without backward integration into feedstock.
- Stringent Environmental Regulations:Rules such as the US EPA's National Emission Standards for Hazardous Air Pollutants for vinyl chloride and the EU's Industrial Emissions Directive impose significant compliance costs on VCM and PVC production facilities.
- Material Substitution:In applications like pressure pipes and window frames, PVC faces intense competition from alternative materials such as high-density polyethylene (HDPE), cross-linked polyethylene (PEX), and aluminum.
Strategic Opportunities
- Circular Economy Integration:Establishing closed-loop recycling systems for post-consumer rigid PVC from construction and demolition waste presents a major opportunity to create a sustainable supply of recycled PVC (rPVC).
- Bio-Based PVC Formulations:Research into producing vinyl chloride monomer from bio-based ethanol instead of fossil fuels offers a pathway to reduce the carbon footprint of PVC and appeal to sustainability-focused customers.
- Expansion in Renewable Energy:The build-out of solar and wind energy infrastructure creates new demand for durable, weather-resistant PVC in applications like cable insulation, conduit, and protective coatings.
Industry Challenges
- Recycling Complexity:The presence of diverse additives and plasticizers in flexible PVC products complicates mechanical recycling, often leading to downcycling and limiting the economic viability of recovery operations. *Public Health Perception: Lingering public and regulatory concern over legacy additives like lead stabilizers and certain phthalate plasticizers creates reputational risk and can restrict market access for consumer-facing goods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Chloride (PVC) Market |
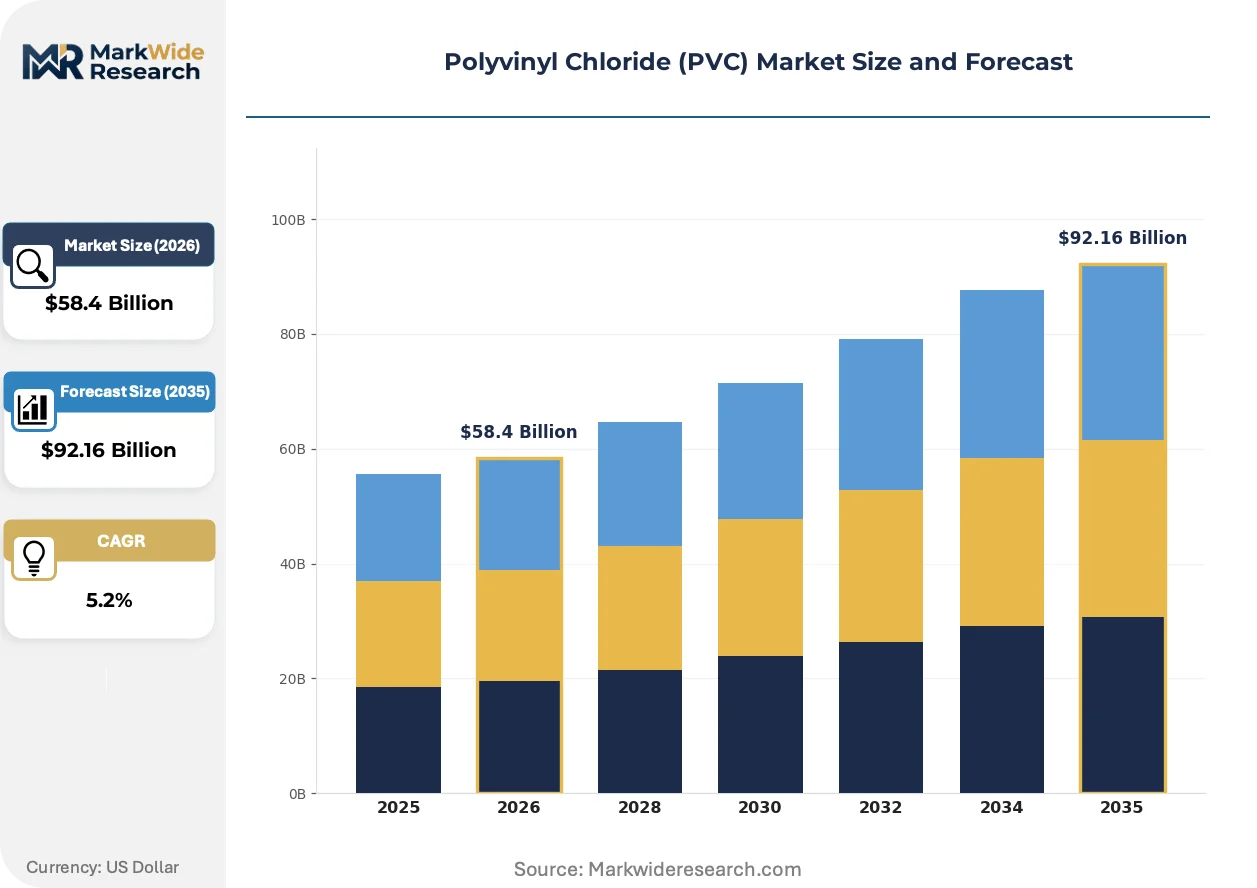
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $92.16 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, Chlorinated PVC, PVC Compounds, PVC Resins Application: Construction, Electrical Insulation, Packaging, Medical Equipment, Consumer Goods Manufacturing Stage: Polymerization, Formulation, Compounding, Processing, Fabrication End User Industry: Building Contractors, Electrical Manufacturers, Packaging Firms, Medical Device Makers, Consumer Product Companies |
| Companies Covered | Shin-Etsu Chemical Co., Ltd., Formosa Plastics Corporation, Westlake Corporation, INEOS Group Holdings S.A., Orbia, OxyChem, LG Chem, China Lesso Group Holdings Limited, Chemplast Sanmar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Chloride (PVC) Market Strategic Shifts & Innovations
Material science advancements are enabling PVC to evolve from a monolithic commodity into a highly adaptable material platform. This shift is driven by a convergence of regulatory mandates for safer materials and end-user demands for specific performance characteristics in finished products.
Advanced compounding techniques allow for the precise tuning of PVC properties using sophisticated additive packages. The medical and automotive sectors are rapidly adopting these custom formulations to meet exacting performance and safety standards. This development is modularizing the value chain, enabling compounders to offer bespoke solutions for specific applications rather than forcing customers to design around general-purpose grades.
European Union regulations under REACH have progressively restricted the use of specific high-molecular-weight phthalate plasticizers. This action has compelled a large-scale reformulation effort across the continent's flexible PVC industry. The consumer goods, wire and cable, and flooring sectors are most affected, accelerating their transition to alternative plasticizers like DOTP or bio-based variants.
A significant behavioral shift is occurring as specifiers in the construction industry increasingly require life-cycle data for building materials. This disrupts traditional cost-based purchasing, creating a preference for suppliers who provide certified Environmental Product Declarations (EPDs) and can guarantee recycled content. This trend is most visible in Northern Europe, where green building certification schemes are widely adopted.
Polyvinyl Chloride (PVC) Market Segmentation
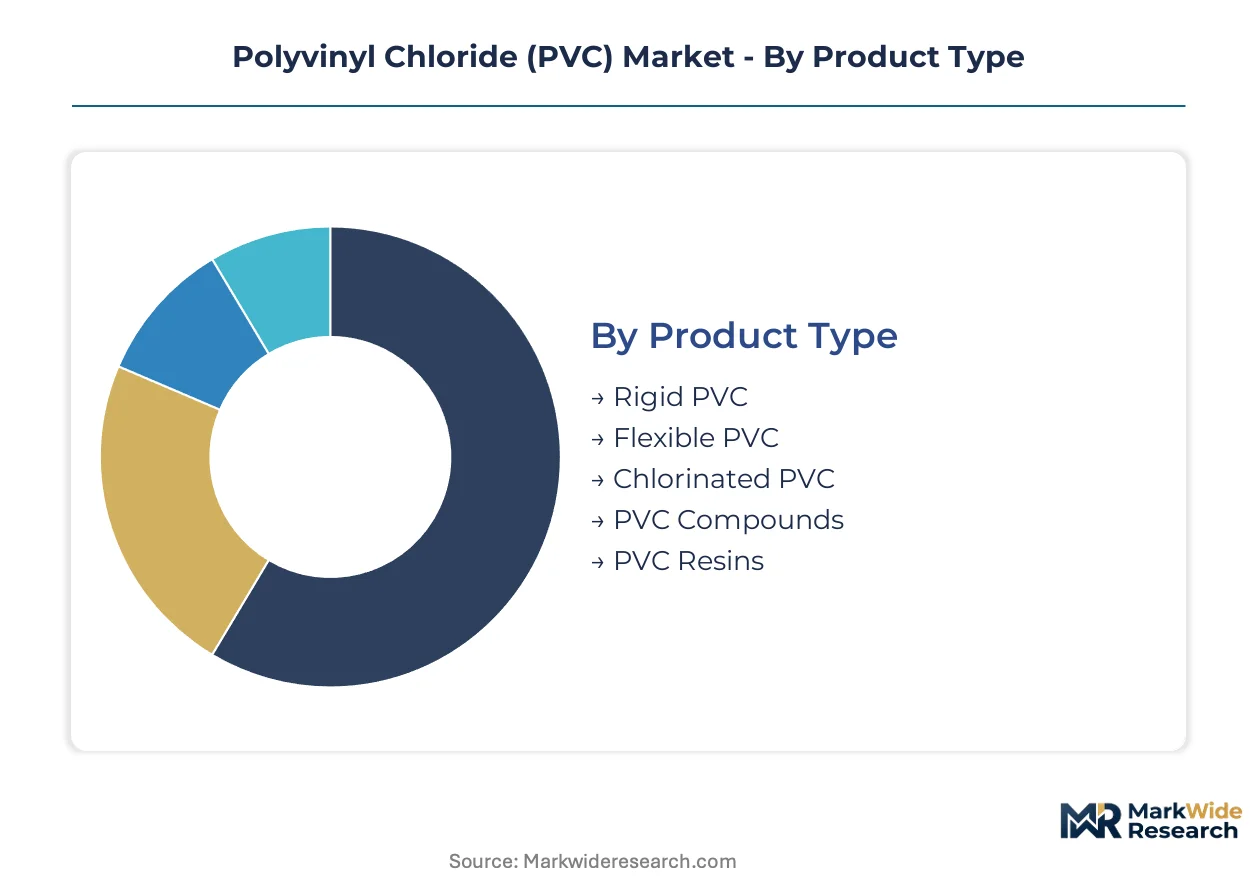
The Polyvinyl Chloride market's segmentation reflects its diverse material properties and extensive application scope, moving beyond a basic commodity. Understanding these distinct segments is crucial for manufacturers to align production capabilities with evolving end-user demands and regulatory pressures. Tailored solutions for specific performance requirements define market value across various product types and applications.
Product Type:
Capital-intensive investments define the production landscape for different PVC product types, influencing market entry and scale for specialized offerings.
- Rigid PVC:This unplasticized form of PVC offers high strength, durability, and chemical resistance. Demand concentrates in the construction sector for pipes, window profiles, and siding, driven by infrastructure development in India and Brazil.
- PVC Compounds:These are custom blends of PVC resin with specific additives, tailored for precise performance characteristics. The medical and automotive sectors in Europe and North America increasingly adopt these custom formulations to meet exacting performance and safety standards.
- Flexible PVC:Modified with plasticizers, this PVC variant offers elasticity and softness for applications like films, sheets, and cable insulation.
- Chlorinated PVC:CPVC exhibits enhanced heat resistance and chemical inertness compared to standard PVC, primarily used in hot water piping systems.
- PVC Resins:This is the raw polymer form, serving as the foundational material for all subsequent PVC product types and compounds.
Rigid PVC absorbs the bulk of installed capacity; PVC Compounds are expanding most quickly.
Application:
The functional requirements of specific applications dictate the performance characteristics demanded from PVC formulations.
- Construction:This segment is the largest consumer of PVC, utilizing rigid PVC for pipes, fittings, window frames, and flooring. Sustained urban development projects in China and Southeast Asia drive significant volume here.
- Medical Equipment:Requires high-grade, biocompatible PVC for blood bags, tubing, and catheters due to its sterilizability and chemical inertness. Healthcare system expansion in emerging economies fuels this specialized demand.
- Packaging:Flexible PVC films find use in blister packaging, shrink wraps, and food wraps due to their barrier properties and clarity.
- Electrical Insulation:PVC's excellent dielectric properties make it suitable for insulating wires and cables in residential, commercial, and industrial settings.
- Consumer Goods:This broad category includes items like footwear, toys, and sports equipment, often utilizing flexible PVC for durability and moldability.
Construction applications command the largest volume share, while Medical Equipment exhibits significant value growth.
Manufacturing Stage:
Volume throughput and specialized expertise differentiate the various stages across the PVC manufacturing chain.
- Polymerization:This upstream process involves the chemical reaction of vinyl chloride monomer to produce PVC resin. Large-scale chemical plants in China and the US dominate this energy-intensive stage.
- Compounding:This stage involves blending PVC resin with various additives such as plasticizers, stabilizers, and pigments to achieve desired material properties. Custom compounders in Germany and Japan provide specialized solutions for high-performance applications.
- Formulation:This refers to the scientific design and recipe development for specific PVC compounds, preceding the physical blending process.
- Processing:This stage involves converting PVC compounds into finished or semi-finished products through methods like extrusion, calendering, and injection molding.
- Fabrication:This final stage involves assembling or modifying processed PVC components into finished goods, such as window frames or medical devices.
Polymerization represents the foundational step for all PVC production, with Compounding adding critical value for specialized end-uses.
End User Industry:
Procurement patterns vary significantly among end-user industries, influencing demand for specific PVC grades and services.
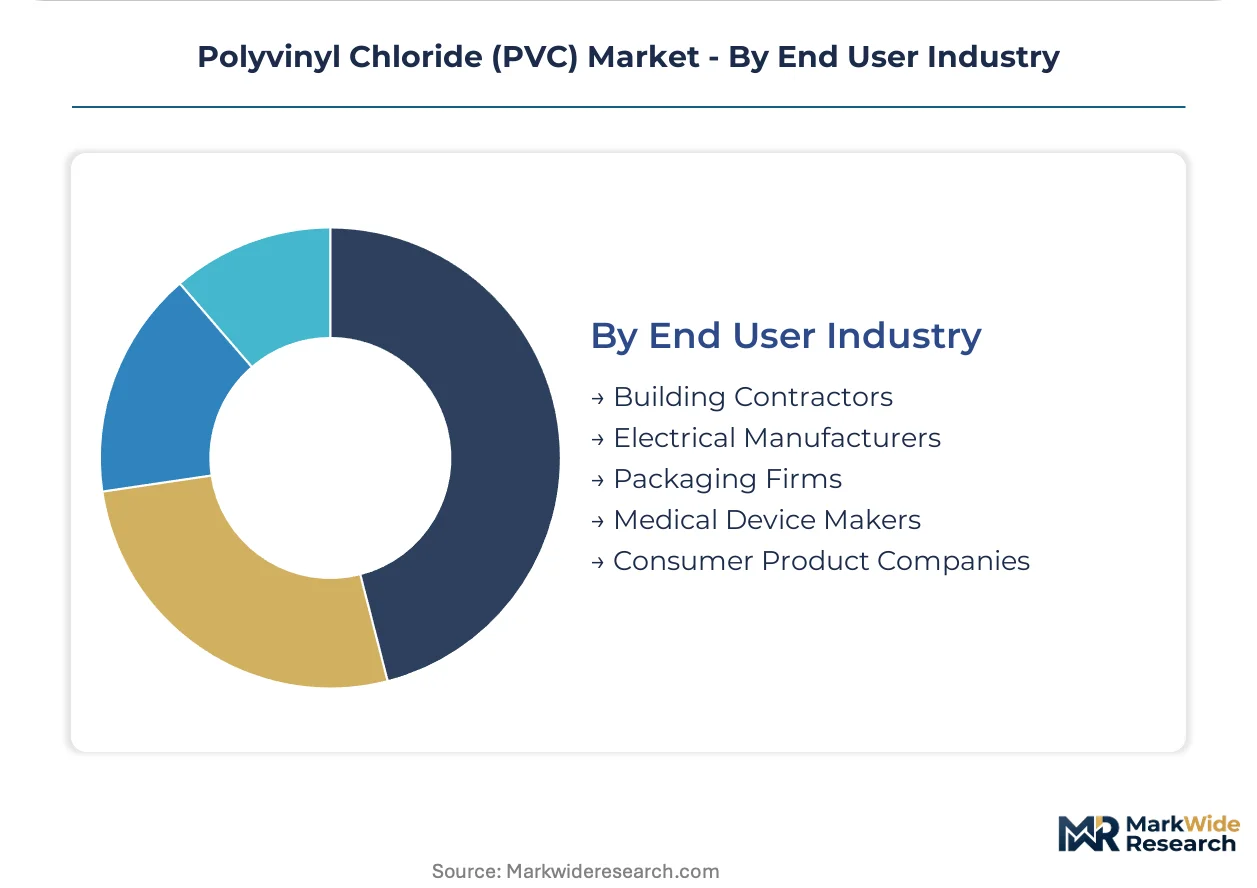
- Building Contractors:These entities procure substantial volumes of rigid PVC products for residential, commercial, and infrastructure projects. Their purchasing decisions are often driven by project specifications, cost, and material availability.
- Medical Device Makers:This industry requires highly regulated, sterile, and biocompatible PVC for critical applications. Compliance with standards from the FDA and European Medicines Agency is paramount for material selection.
- Electrical Manufacturers:These companies utilize PVC for wire and cable insulation, conduits, and junction boxes in various electrical systems.
- Packaging Firms:These businesses demand flexible PVC films for a range of packaging solutions, prioritizing clarity, barrier properties, and cost-effectiveness.
- Consumer Product Companies:This sector uses PVC in diverse products, from toys and apparel to household items, valuing its versatility and durability.
Building Contractors represent the largest purchasing segment, whereas Medical Device Makers drive demand for the highest-specification materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Polyvinyl Chloride market experiences a significant divide between concentrated production hubs and geographically dispersed consumption centers. This dynamic interplay drives trade flows and influences regional pricing structures across the global PVC landscape.
China
Extensive demand for PVC originates from China's large-scale building and manufacturing industries. National GB standards govern the quality and safety of PVC products for construction and consumer use. The Yangtze River Delta region hosts extensive PVC production and processing facilities, serving domestic and export markets.
United States
Construction and electrical insulation applications drive consistent PVC demand across the United States. The US EPA's National Emission Standards for Hazardous Air Pollutants directly impact vinyl chloride monomer production processes. The Gulf Coast region maintains significant VCM and PVC polymerization capacity, benefiting from feedstock availability.
India
Sustained government spending on urban development and water management projects stimulates demand for rigid PVC pipes in India. BIS standards ensure product quality and safety for construction materials. Gujarat serves as a key hub for chemical manufacturing and PVC processing units, supporting national infrastructure goals.
Germany
High-performance PVC compounds are crucial for Germany's automotive and medical sectors. European Union regulations under REACH influence the formulation of specialized PVC products, particularly regarding plasticizers. The Rhine-Ruhr area specializes in advanced compounding and the manufacturing of bespoke PVC solutions.
Brazil
Infrastructure investment and civil construction projects generate substantial PVC demand across Brazil. ABNT standards for PVC pipes and fittings ensure product compliance in the construction sector. São Paulo state contains a significant concentration of PVC pipe manufacturers and construction material suppliers.
Polyvinyl Chloride (PVC) Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share across the Polyvinyl Chloride value chain. The market features a tiered structure, with integrated chemical conglomerates dominating upstream polymerization and specialized compounders adding value downstream. Competitive moves include capacity expansion to meet regional demand and strategic partnerships to develop new formulations.
Integrated chemical giants like Shin-Etsu Chemical Co., Ltd. represent a significant manufacturing scale, competing across both commodity and specialty grades. Westlake Corporation exemplifies integrated production, securing its supply chain from feedstock to finished PVC products. INEOS Group Holdings S.A. operates a broad portfolio across multiple chemical segments, providing resilience through diversification.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Co., Ltd. |
| Formosa Plastics Corporation |
| Westlake Corporation |
| INEOS Group Holdings S.A. |
| Orbia |
| OxyChem |
| LG Chem |
| China Lesso Group Holdings Limited |
| Chemplast Sanmar |
| Others |
Cost & Logistics Intelligence
Integrated production models anchor the supply position and pricing power for major PVC manufacturers. This vertical integration from feedstock to polymer production mitigates raw material price volatility, offering a competitive advantage.
Pricing Analysis
Cost-down pressure on commodity PVC grades accelerates because of overcapacity in Asian markets. The dominant pricing structure is a hybrid model, combining long-term contract-based offtake for large volumes with spot market transactions for immediate needs. Price differentiation stems from quality grade, particularly for medical and automotive compounds, and customization level for specialty formulations. Building contractors represent the most price-sensitive buyers, while medical device makers prioritize specification compliance over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical PVC components ensure supply resilience for downstream manufacturers. Geographic supply concentration centers on China, the United States, and India, reflecting large-scale polymerization capacity. The supply chain draws from critical raw material dependencies including ethylene and chlorine for vinyl chloride monomer production. Commodity price volatility for these feedstocks presents a structural risk. Distribution runs through a network of regional distributors and direct sales channels to large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Polyvinyl Chloride market is becoming a consolidation play, with stringent environmental regulations forcing smaller, less compliant producers to exit.
For Market Incumbents: To counter material substitution from alternative polymers, deepen vertical integration into bio-based feedstock production. Invest in advanced compounding R&D to develop novel non-phthalate plasticizers and enhance the performance of rPVC. Secure long-term supply agreements with key end-users in construction and medical sectors to stabilize demand and pricing.
For New Entrants and Emerging Players: Direct-to-customer e-commerce platforms offer a pathway to penetrate niche markets for specialized PVC compounds. Target the European medical and automotive sectors, which demand high-specification, compliant formulations. Focus on value-added services like custom formulation and certified life-cycle data provision. A go-to-market angle emphasizing sustainability credentials and circular economy integration will differentiate new players.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized compounders with proprietary formulations or advanced recycling technologies. Long-term viability hinges on navigating evolving regulatory landscapes and capturing value from circular economy initiatives. Focus on companies with strong intellectual property in non-phthalate plasticizers or bio-based PVC. A signal to watch is the adoption rate of certified recycled PVC in mainstream construction projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Specialty Grades | Increases market share in high-margin segments demanding advanced PVC formulations. |
| Investment in Bio-Based Feedstocks | Reduces carbon footprint, appealing to sustainability-focused customers and regulators. |
| Development of Advanced Recycling Technologies | Enables closed-loop systems for post-consumer PVC, creating a sustainable supply. |
| Strategic Partnerships for Custom Compounding | Expands product portfolio and caters to specific performance requirements in niche applications. |
| Acquisition of Non-Phthalate Plasticizer Producers | Secures supply of compliant additives for flexible PVC products in regulated markets. |
Research Approach
Document review covered industry reports, company annual filings, and government publications from the US EPA, EU REACH, and China's GB standards, complemented by interviews with PVC plant managers, procurement leads, and R&D directors. This primary and secondary research was triangulated using both bottom-up and top-down approaches to ensure data consistency.
Historical data was cross-referenced with expert panel input to project market trends and forecast growth across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, manufacturing stage, and end-user industry, alongside regional regulatory impacts. Compound annual growth rates were derived from a weighted average of segment-specific projections, incorporating feedstock price fluctuations as a key input.
The model holds under current regulatory and macroeconomic conditions; deviation in global infrastructure spending or environmental policy would shift market dynamics. Forecasts reflect assumptions regarding technological advancements in compounding and recycling. A model refresh is warranted upon material change in feedstock availability or major legislative updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
India Plastic Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Recycled Plastic and Plastic Waste to Oil Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
China Plastics Market
Recycled Plastics
Solvent-Based Plastic Recycling Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Bioplastic Recycling Market
Recycled Plastics
North America Plastic Waste Management Market