
 Seed Polymers Market | 2026-2036
Seed Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Seed Polymers Market Analytics
Modular seed treatment bundling is realigning how growers purchase polymer-enhanced seed coatings alongside biologicals and micronutrients. BASF SE leverages its Crop Science division to integrate polymer binders with fungicide portfolios, sustaining cross-selling momentum across North American corn and soybean belts. Bayer AG anchors its position through direct channel relationships with major agricultural distributors, while Syngenta Group competes via technology leadership in film-coating uniformity and dust-off reduction.
Seed polymers are synthetic or bio-based compounds applied as coatings, encapsulants, or binders to seeds, typically functioning at application rates of grams per kilogram of seed to improve flowability, moisture retention, and active ingredient adhesion. Polyethylene dominates product type demand due to its cost efficiency and established supply chains in film-coating applications, while polyurethane is gaining share in specialty coatings requiring elasticity and weather resistance. The agriculture end use industry occupies the largest value pool, though packaging-grade formulations for seed storage films represent a concentrated margin segment.
The EPA regulates polymer-coated seeds under pesticide device and inert ingredient frameworks, while the USDA oversees treated seed labeling and transport compliance; REACH in Europe restricts certain petrochemical additives, pushing reformulation toward bio-based alternatives. China's MEE enforces stricter volatile organic compound limits on coating operations, reshaping export qualification requirements for multinational suppliers. Stakeholders must monitor evolving biodegradability certification standards and polymer registration pathways as sustainability criteria harden across major agricultural import jurisdictions.
Market Dynamics
Modular bundling of seed treatments is compressing standalone polymer margins while elevating integrated formulation suppliers. The shift from commodity film-coating to precision-engineered encapsulation systems is redistributing value toward R&D-intensive players with biological-polymer hybrid capabilities.
Growth Catalysts
- Precision Agriculture Adoption:Variable-rate seeding equipment in the United States requires polymer coatings with uniform flowability and reduced dust-off, pulling demand for advanced film-coating formulations.
- REACH Restrictions on Petrochemical Additives:European reformulation mandates are accelerating bio-based polymer development, creating first-mover advantages for suppliers with certified biodegradable portfolios.
- Polyurethane Elasticity Advantages:Specialty crop applications requiring weather-resistant coatings are displacing conventional polyethylene in high-value vegetable and horticultural seed segments.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and propylene price swings directly compress polymer coating margins, particularly for cost-sensitive commodity grain applications.
- Chinese Supply Concentration:MEE enforcement of volatile organic compound limits on coating operations has consolidated qualified export capacity among fewer multinational suppliers.
- Biodegradability Performance Gap:Current bio-based alternatives exhibit inferior moisture retention and active ingredient adhesion compared to synthetic benchmarks, limiting substitution rates.
Strategic Opportunities
- Brazilian Soybean Expansion:Underpenetrated polymer coating adoption in South American large-scale farming presents volume expansion potential for suppliers establishing local formulation facilities.
- Biological-Polymer Convergence:Integration of microbial inoculants with protective polymer matrices creates premium positioning in regenerative agriculture segments.
- USDA Treated Seed Labeling Harmonization:Simplified compliance pathways for polymer-coated biological combinations reduce registration barriers and accelerate commercialization timelines.
Industry Challenges
- Formulation Chemistry Talent Scarcity:Cross-disciplinary expertise combining polymer science with agricultural active ingredient compatibility remains concentrated among legacy agricultural chemical firms.
- Biodegradability Certification Timelines:OECD and ISO standard testing protocols for seed coating polymers extend validation cycles, delaying market entry for novel bio-based formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seed Polymers Market |
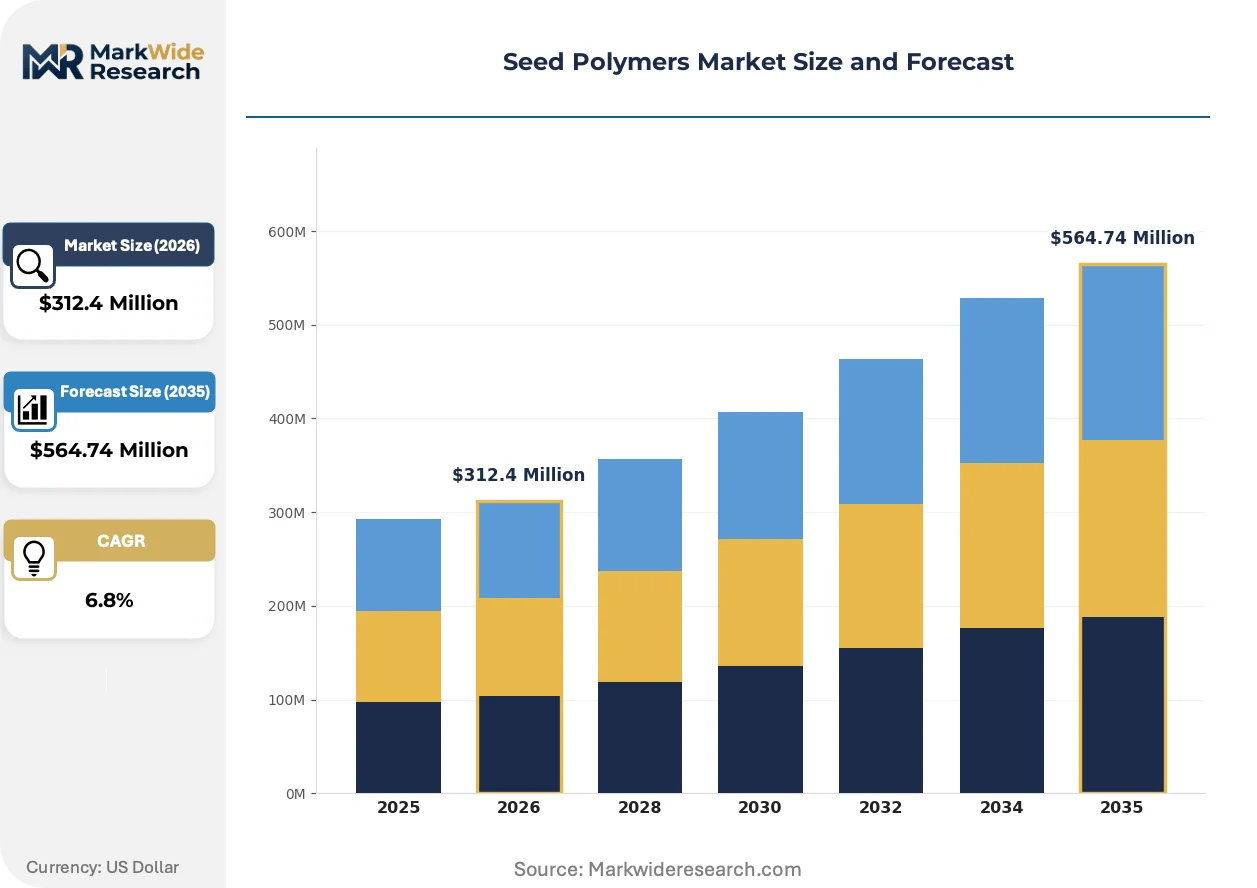
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Polyurethane End Use Industry: Agriculture, Automotive, Construction, Packaging Grade: High Purity, Medical Grade, Food Grade, Industrial Grade Form: Pellets, Granules, Powders, Films |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, Croda International, Germains Seed Technology, Clariant, Sensient Technologies, Chromatech Incorporated, Precision Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seed Polymers Market Evolving Landscape
Active ingredient delivery systems are converging with environmental release control mechanisms, reshaping how polymer coatings function beyond physical protection. This convergence is elevating coating formulations from commodity inputs to differentiated technology platforms.
Bio-based polyurethane formulations derived from agricultural waste streams are converging with controlled-release nitrogen stabilization technologies. Specialty vegetable seed producers in the Netherlands and Spain are adopting these hybrid systems at accelerated rates. The technology is converging with precision planting equipment requirements, compressing demand for conventional single-function polyethylene coatings.
EPA's framework for polymer-coated seeds as pesticide devices is tightening inert ingredient disclosure requirements for imported formulations. Manufacturers must now submit complete polymer compositional data previously treated as proprietary. Agricultural distributors in the United States are restructuring supplier qualification protocols to preempt registration delays.
Large-scale grain operations are consolidating procurement through direct manufacturer relationships, disintermediating traditional agricultural distributor channels. Corn and soybean belt cooperatives in Iowa and Illinois are negotiating volume-based polymer coating contracts with integrated suppliers. This concentration is most visible in the United States, where precision agriculture adoption correlates with buyer scale and technical specification sophistication.
Seed Polymers Market Segmentation
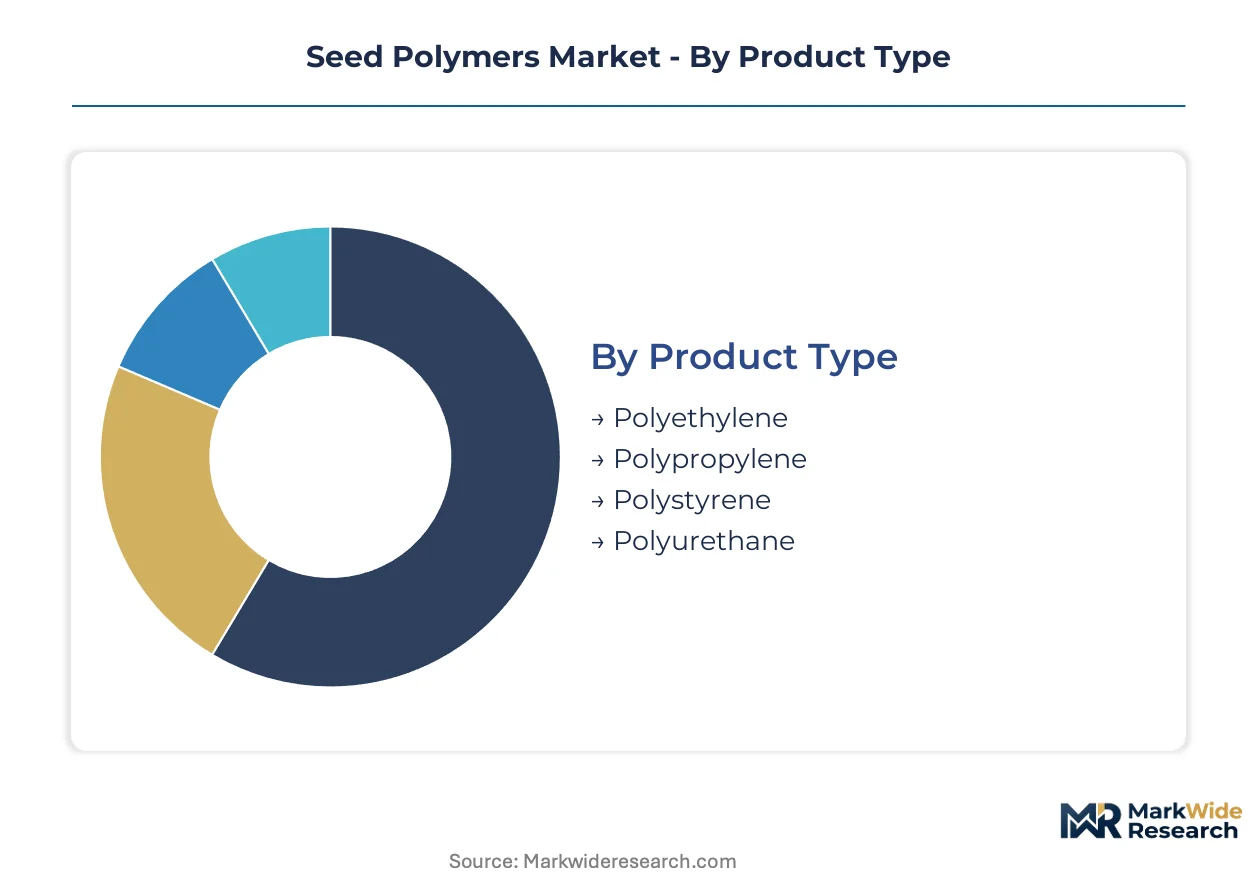
Segmentation in seed polymers reveals how regulatory pathways, application requirements, and performance specifications fragment procurement patterns across agricultural and industrial buyers. Understanding these divisions exposes where formulation investments concentrate and which certification burdens create competitive moats.
Product Type:
EPA pesticide device registration and REACH inert ingredient disclosures impose distinct compliance loads on synthetic versus bio-based polymer categories, reshaping supplier qualification protocols.
- Polyethylene:Linear low-density formulations dominate film-coating applications due to cost efficiency and established supply chains. Corn and soybean belt cooperatives in Iowa and Illinois source polyethylene coatings at scale for precision planting equipment requiring uniform flowability.
- Polyurethane:Elastic, weather-resistant properties enable specialty vegetable and horticultural seed applications where moisture retention and active ingredient adhesion prove critical. Netherlands and Spain vegetable seed producers adopt these formulations at accelerated rates under REACH petrochemical additive restrictions.
- Polypropylene:Higher melting point suits thermal stress environments in seed storage and transport logistics.
- Polystyrene:Rigid encapsulation properties serve niche applications in controlled-release nitrogen stabilization technologies.
Polyethylene sits at the top of the volume ranking, with polyurethane climbing the fastest.
End Use Industry:
Cost tiers separate commodity agricultural coatings from premium packaging-grade formulations commanding concentrated margins.
- Agriculture:Film-coating, encapsulation, and binder applications for field crops, vegetables, and specialty seeds. USDA treated seed labeling requirements and EPA pesticide device frameworks govern procurement, with Brazil soybean expansion driving volume growth for local formulation facilities.
- Packaging:Seed storage films and protective wraps represent a concentrated margin segment with technical specifications distinct from field-application coatings.
- Automotive:Limited seed polymer adoption in bio-based component prototyping and research applications.
- Construction:Emerging use in geotextile seeding for erosion control and green infrastructure projects.
Agriculture captures the dominant value pool, while packaging commands the steepest margin premiums.
Grade:
Application maturity determines which purity tiers face active ingredient compatibility testing versus basic industrial compliance.
- Industrial Grade:Standard formulations for commodity grain coatings where cost sensitivity dominates procurement decisions and petrochemical feedstock volatility directly compresses margins.
- Food Grade:Stringent migration limits and contact safety certifications required for seed coatings in food crop applications entering human consumption supply chains.
- High Purity:Specialized formulations for biological-polymer hybrid systems where microbial inoculant compatibility demands minimal contaminant thresholds.
- Medical Grade:Rare seed polymer applications in pharmaceutical crop research and controlled-environment agriculture requiring sterile propagation protocols.
Industrial Grade holds the volume lead, with Food Grade gaining share fastest under tightening food safety harmonization.
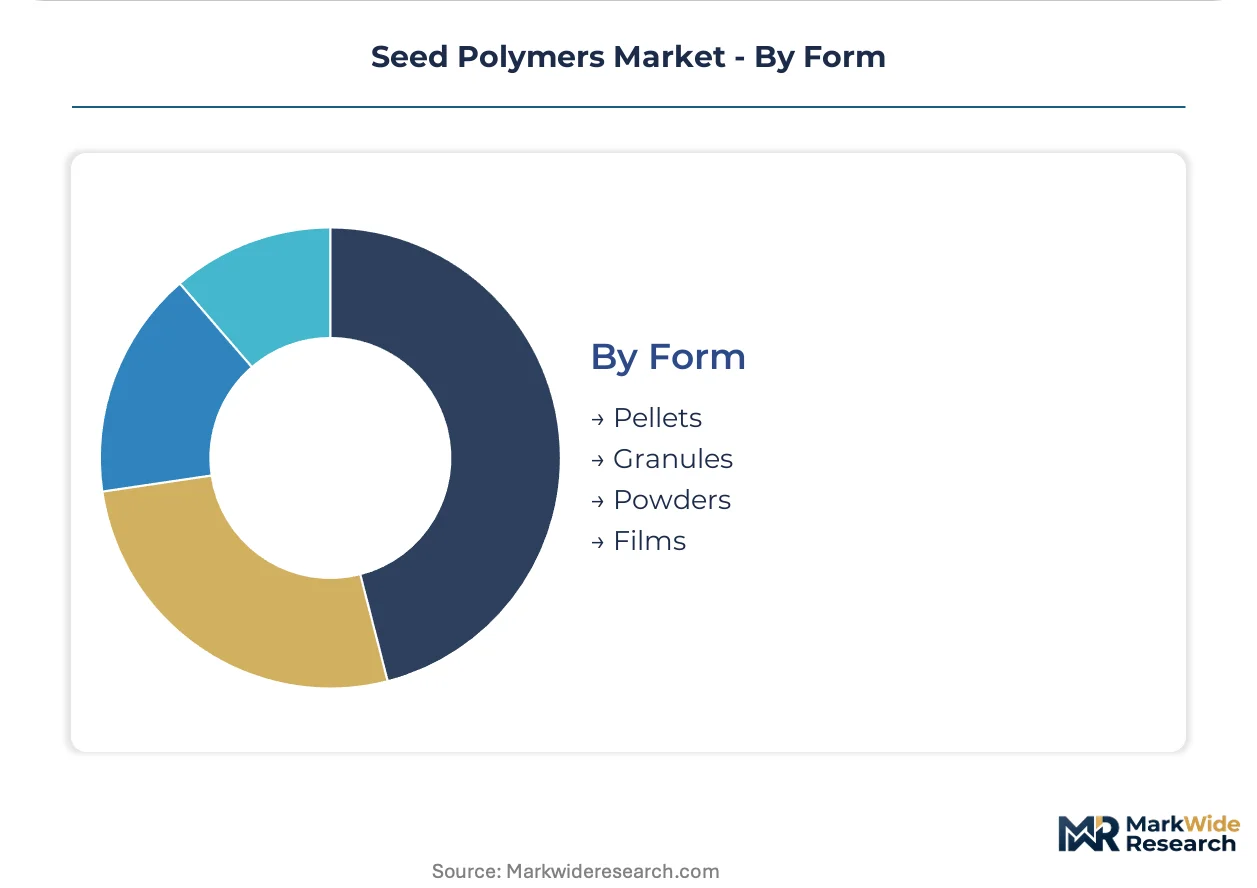
Form:
Supply concentration in Chinese coating operations has consolidated qualified export capacity for specific physical formats under MEE volatile organic compound enforcement.
- Films:Dominant format for precision agriculture flowability requirements, with dust-off reduction specifications driving film-coating uniformity investments by major agricultural distributors.
- Pellets:Standardized dosing units for large-scale grain operations consolidating procurement through direct manufacturer relationships.
- Granules:Intermediate processing format for regional formulation facilities serving underpenetrated South American markets.
- Powders:Niche applications requiring rapid dissolution or integration with micronutrient bundling systems.
Films lead in value terms, with Pellets expanding most quickly through cooperative volume contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial polymer chemistry in the early twentieth century, establishing the technical foundation for modern seed coating formulations. BASF SE and Bayer AG scaled agricultural polymer applications from Ludwigshafen and Leverkusen, exporting film-coating technologies to North American and South American markets. This European industrial lineage continues shaping regulatory standards and bio-based formulation development worldwide.
United States
Iowa and Illinois corn-soybean cooperatives drive precision agriculture procurement for polymer-coated seeds compatible with variable-rate planting equipment. The EPA regulates these formulations under pesticide device frameworks, tightening inert ingredient disclosure requirements for imported products. Chicago-based agricultural distributors now qualify suppliers through direct manufacturer relationships, bypassing traditional channel intermediaries.
Brazil
Mato Grosso and Paraná soybean operations present underpenetrated polymer coating adoption among large-scale farming enterprises. ANVISA oversees agricultural chemical registration while the Ministry of Agriculture enforces treated seed transport compliance. Local formulation facilities in São Paulo state are expanding to serve South American volume growth and reduce import dependency.
China
Shandong and Jiangsu provinces concentrate domestic polymer production capacity for regional seed coating applications. The MEE enforces volatile organic compound limits on coating operations, consolidating qualified export capacity among fewer multinational suppliers. Qingdao-based formulation plants are upgrading environmental compliance systems to maintain European and North American market access.
Netherlands
Vegetable seed producers in Westland and Flevoland polders adopt bio-based polyurethane formulations under REACH petrochemical additive restrictions. The Dutch national implementation of EU Green Deal sustainability criteria accelerates biodegradable polymer certification timelines. Wageningen University research clusters partner with industry on controlled-release nitrogen stabilization technologies.
India
Punjab and Haryana wheat-rice belt farmers increasingly specify polymer-coated seeds for moisture retention in variable monsoon conditions. The FSSAI and Ministry of Agriculture coordinate on treated seed labeling harmonization with food safety supply chain requirements. Hyderabad-based seed companies are integrating polymer binders with micronutrient bundling systems for smallholder market penetration.
Seed Polymers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity tiers, with integrated agricultural chemical conglomerates commanding pricing power in proprietary film-coating systems. The vendor base separates into three strategic archetypes: diversified chemical majors with crop science divisions, specialized seed technology pure-plays, and regional formulation contractors serving price-sensitive grain markets. Competitive dynamics center on backward integration into polymer resin production and technology licensing partnerships for biological-polymer hybrid systems.
Among European-based chemical conglomerates, BASF SE and Bayer AG exemplify the diversified major archetype with integrated crop science portfolios spanning polymer binders through active ingredient formulations. Syngenta Group represents the technology-led specialist position, competing through film-coating uniformity and dust-off reduction capabilities. These three companies anchor the premium formulation tier where R&D intensity and regulatory navigation capabilities determine competitive position.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| Croda International |
| Germains Seed Technology |
| Clariant |
| Sensient Technologies |
| Chromatech Incorporated |
| Precision Laboratories |
| Others |
Value Network & Pricing Analysis
Polymer chemist concentrations in Ludwigshafen and Leverkusen create labor-cost differentials that widen pricing-tier spreads between European premium formulations and Asian commodity coatings. REACH compliance investments and MEE environmental upgrades embed fixed-cost premiums that synthetic benchmark suppliers pass through to precision agriculture buyers in Iowa and Illinois.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates R&D-intensive biological-polymer hybrids from commodity polyethylene film-coatings. Price differentiation hinges on REACH biodegradability certification status and precision planting equipment compatibility testing. Pricing pressure stems from ethylene and propylene feedstock volatility compressing margins in cost-sensitive commodity grain segments. Large-scale cooperatives exhibit lowest price sensitivity, while smallholder markets in India and Brazil remain most cost-constrained.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Chicago, and São Paulo anchor hub-and-spoke patterns for formulated polymer coatings. Manufacturing concentrates in Germany, China, and the United States, with Shandong and Jiangsu provinces feeding domestic Asian demand. Raw material dependencies center on ethylene and propylene petrochemical streams, bio-based agricultural waste feedstocks, and specialty isocyanates for polyurethane elasticity. Single-source vulnerability in Chinese coating capacity under MEE enforcement creates qualification bottlenecks for multinational suppliers. Distribution runs through agricultural distributor networks consolidating toward direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Seed Polymers Market functions as a geographic-arbitrage play where REACH-driven reformulation costs in Europe exceed MEE compliance investments in China, creating cost-advantaged export capacity for qualified Asian producers.
For Market Incumbents: Anchor defensive positioning through backward integration into bio-based resin production and captive supply of agricultural waste feedstocks. BASF SE and Bayer AG should deepen channel control via direct relationships with Iowa and Illinois cooperatives, neutralizing distributor disintermediation threats from volume-based procurement consolidation.
For New Entrants and Emerging Players: Smallholder wheat-rice farmers in Punjab and Haryana represent the most penetrable buyer archetype currently underserved by premium-tier suppliers. Local formulation partnerships with Hyderabad-based seed companies enable micronutrient bundling entry, while Brazilian soybean expansion offers volume scale without incumbent channel saturation.
For Investors and Strategic Acquirers: Agricultural chemical conglomerates with dormant crop science divisions are the most active acquirer in this space, seeking biological-polymer hybrid capabilities. The long-term viability window favors targets with certified biodegradable portfolios and ANVISA pre-registration in Brazil. Watch for OECD and ISO certification timeline acceleration as the inflection signal for bio-based formulation market entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Captive agricultural waste feedstock supply secures REACH-compliant formulation cost advantages. |
| Local Formulation Facility Expansion | São Paulo capacity buildout reduces Brazilian soybean market import dependency and logistics exposure. |
| Biological-Polymer Hybrid R&D Partnership | Wageningen University collaboration accelerates controlled-release nitrogen stabilization technology commercialization. |
| Direct Channel Relationship Development | Iowa and Illinois cooperative contracting bypasses distributor margin extraction in precision agriculture segments. |
| Biodegradability Certification Investment | OECD and ISO standard pre-validation compresses novel bio-based formulation market entry timelines. |
Research Methodology
Coverage spans North America, Europe, South America, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with polymer R&D directors, agricultural distributor procurement leads, seed company formulation managers, and EPA regulatory affairs specialists informed demand-side and compliance dynamics. Secondary sources include EPA pesticide device registration filings, REACH inert ingredient disclosures, USDA treated seed labeling databases, and customs trade data for polymer resin flows. Bottom-up volume modeling triangulated against top-down chemical industry expenditure benchmarks.
Granularity extends to product-type, end-use industry, grade tier, and form dimensions across the analysis window. Polyethylene, polyurethane, polypropylene, and polystyrene categories were modeled separately with distinct feedstock cost pass-through assumptions. Agriculture, packaging, automotive, and construction end-uses carried differentiated regulatory compliance cost burdens. CAGRs derived from segment-level volume trajectories weighted by regional precision agriculture adoption curves and REACH reformulation mandate timelines.
Underlying measurement precision varies by segment; polyethylene film-coating volumes carry tighter precision than emerging bio-based polyurethane categories. Forecasts reflect documented assumptions on petrochemical price stability, certification timeline progression, and Brazilian soybean acreage expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Global Bio Polyols Market