
 Semi-Rigid Spray Polyurethane Foam Market | 2026-2036
Semi-Rigid Spray Polyurethane Foam Market Size, Share, and Industry Trends Forecast 2026-2036
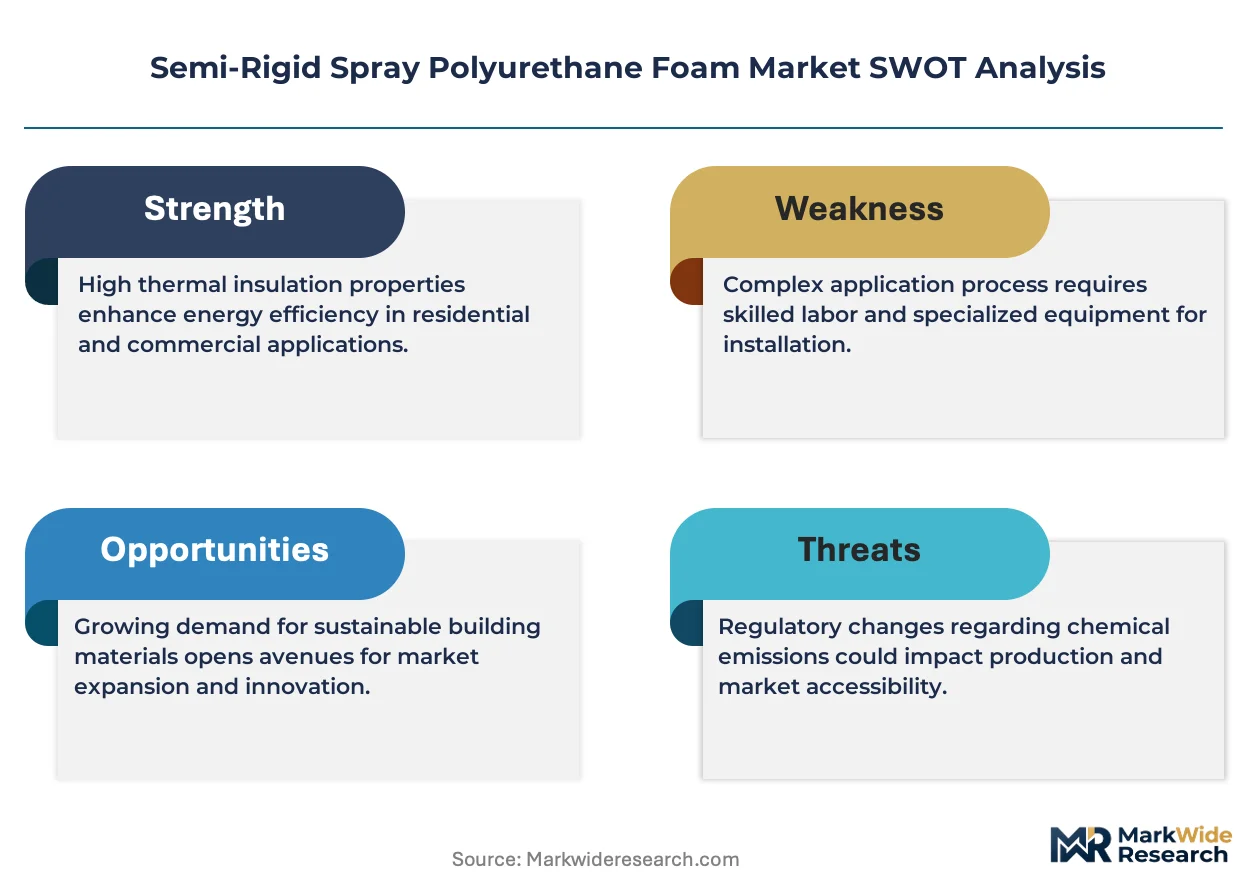
Semi-Rigid Spray Polyurethane Foam Market Analysis
Application-grade maintenance and re-coating services is consolidating around established chemical suppliers and specialty applicators rather than standalone hardware sales. BASF Corporation leverages its upstream polyol and isocyanate production to secure cost positions in closed-cell formulations. Lapolla Industries Inc. anchors its position through a North American contractor training network that locks in specification loyalty. CertainTeed Corporation differentiates by bundling SPF with complementary building envelope products through its roofing and insulation distribution channels.
Semi-rigid spray polyurethane foam is a thermoset cellular plastic applied on-site through high-pressure plural-component equipment, typically achieving densities between 0.5 and 1.5 pounds per cubic foot with compressive strengths suited to cavity-fill and continuous insulation applications. Its primary purpose is to create an air-impermeable thermal barrier that simultaneously addresses conductive heat flow, convective air leakage, and moisture vapor drive in building assemblies. Closed cell foam commands premium positioning in below-grade and exterior applications where hydrostatic resistance and structural adhesion justify higher material costs. The construction end-user segment remains the volume anchor, though marine and HVAC niches are expanding fastest as OEMs seek lightweight, monolithic insulation solutions. Hybrid foam formulations represent an emerging margin pool by bridging the thermal performance of closed cell with the yield economics of open cell.
The EPA's SNAP program and OSHA's isocyanate exposure standards jointly determine permissible chemistries and worker protection protocols for on-site SPF installation. The International Code Council's IECC and ASHRAE 90.1 energy standards create demand pull by mandating continuous insulation and air sealing in commercial and residential construction. Stakeholders must monitor evolving state-level HFC phase-down schedules and low-rise building fire performance requirements, as these will determine which foam densities and ignition barrier combinations remain specification-viable across jurisdictions.
Market Dynamics
The EPA's Significant New Alternatives Policy program is forcing wholesale reformulation of blowing agent chemistries, compressing margins for producers unable to pivot toward lower-GWP alternatives while rewarding early movers with specification lock-in across southern US building codes.
Growth Catalysts
- IECC Continuous Insulation Mandates:ASHRAE 90.1 and International Energy Conservation Code revisions now require continuous insulation layers in commercial envelopes, directly specification-pulling semi-rigid SPF into new construction and deep retrofit workflows.
- Residential Retrofit Contractor Networks:Homeowner prioritization of envelope sealing and humidity control is expanding trained applicator bases across the southern United States where condensation risks drive material selection.
- Hybrid Foam Chemistry Advances:Bridging formulations combining closed-cell thermal performance with open-cell yield economics are opening specification pathways in cost-sensitive multi-family residential and light commercial segments.
Market Restraints
- Isocyanate Input Cost Volatility:Methylene diphenyl diisocyanate and polymeric MDI pricing tracks crude oil and benzene derivatives, exposing applicators to margin squeeze during petrochemical upcycles.
- OSHA Respiratory Protection Requirements:Enhanced isocyanate exposure standards mandate supplied-air respirators and medical surveillance programs, elevating labor costs and contractor qualification barriers.
- Ignition Barrier Complexity:Fire performance requirements for low-rise residential applications vary across jurisdictions, fragmenting product portfolios and complicating inventory management for national distributors.
Strategic Opportunities
- Marine OEM Lightweighting Demand:Boat builders and shipyards are adopting monolithic SPF insulation for hull and deck applications where weight reduction and moisture resistance justify premium positioning.
- HVAC Equipment Integration:Original equipment manufacturers are specifying semi-rigid foam for ductwork and air handling units, creating captive demand channels outside traditional construction distribution.
- State HFC Phase-Down Acceleration:California and northeastern states implementing accelerated hydrofluorocarbon reduction schedules are creating regulatory windows for next-generation blowing agent formulations to capture specification share.
Industry Challenges
- Certified Applicator Pipeline Constraints:Manufacturer training programs and OSHA competent person requirements create bottlenecks in scaling installation capacity to match demand growth in high-growth metropolitan areas.
- Re-coating Service Model Transition:Application-grade maintenance is consolidating around chemical suppliers and specialty applicators, forcing standalone distributors to develop service capabilities or cede margin to integrated providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi-Rigid Spray Polyurethane Foam Market |
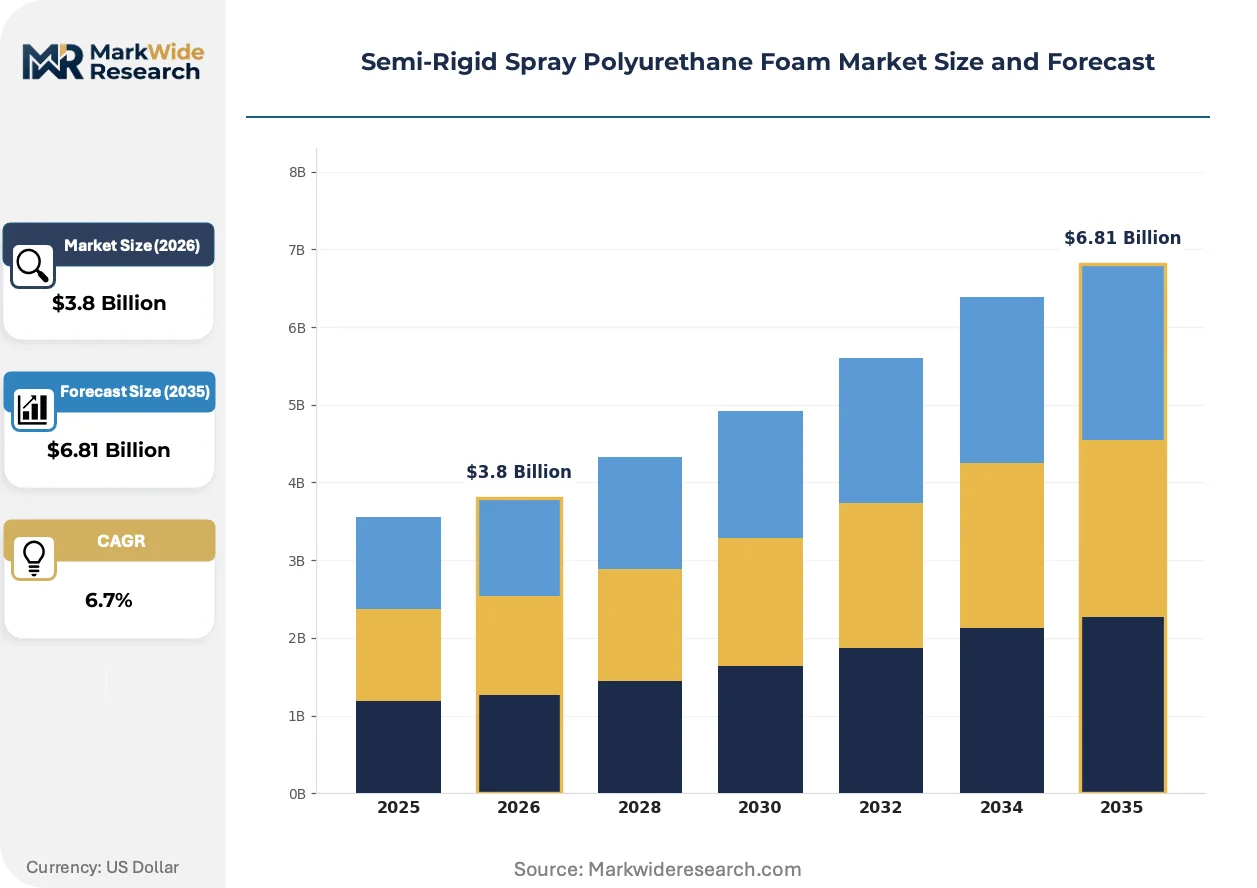
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Cell Foam, Closed Cell Foam, Hybrid Foam, Rigid Foam Application: Insulation, Coating, Sealant, Soundproofing End User: Construction, Automotive, Marine, HVAC Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | Gaco Western, Lapolla Industries Inc., Rhine Linings Corporation, BASF Corporation, Premium Spray Products, Mitex International, Honeywell, CertainTeed Corporation, Foam Supplies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi-Rigid Spray Polyurethane Foam Market Emerging Trajectories
Formulation chemistry, installation equipment, and procurement models are simultaneously evolving as regulatory pressure and end-use diversification reshape competitive requirements across the value chain.
Water-blown and hydrofluoroolefin-based blowing agents are expanding into below-grade and exterior continuous insulation specifications where hydrostatic resistance and thermal bridging elimination justify material premiums. Regional home builders in humid climate zones are specifying these reformulated products at accelerating rates to preempt code compliance risks. The technology is expanding into specification portfolios previously dominated by extruded polystyrene and mineral wool in foundation and below-grade applications.
REACH and the EU F-Gas Regulation are restricting high-GWP blowing agents in imported building materials, creating compliance friction for North American producers serving European project specifications. Industrial consequence includes accelerated R&D allocation toward fourth-generation foam chemistries with sub-150 GWP ratings. Marine and cold-storage segments in Northern Europe are responding by qualifying alternative formulations ahead of anticipated import restriction tightening.
Specification bundling is compressing standalone hardware sales as building envelope contractors consolidate procurement around integrated roofing, insulation, and air barrier packages. Distributors with captive applicator networks are displacing traditional two-step distribution in commercial retrofit channels. The pattern is most visible in the southern United States where humidity-driven building durability concerns elevate contractor specification authority over architect-driven material selection.
Semi-Rigid Spray Polyurethane Foam Market Segmentation
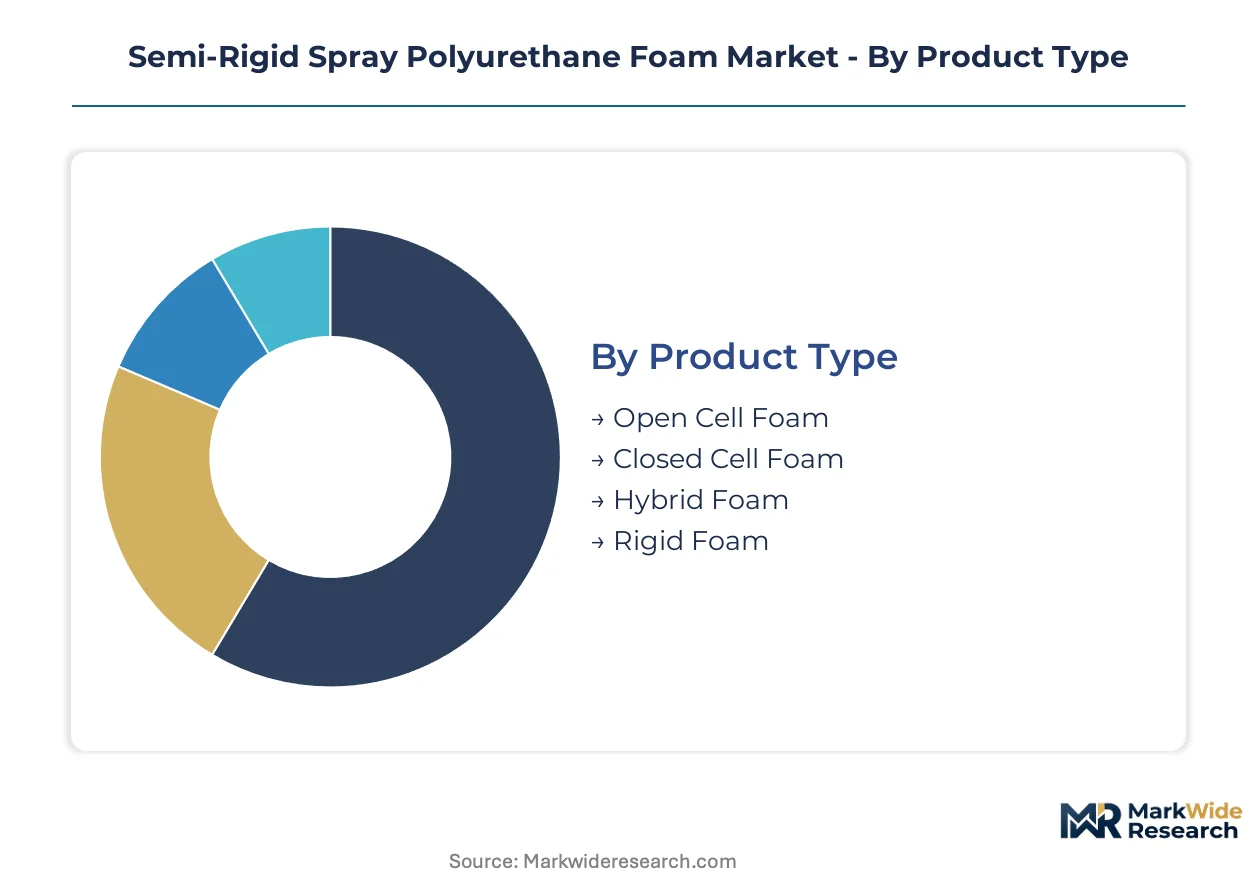
Segmentation in semi-rigid SPF reveals how formulation chemistry, application method, and procurement channel each carry distinct regulatory burdens and margin structures. Contractors, specifiers, and distributors navigate these boundaries when qualifying products for specific building assemblies or end-use environments.
Product Type:
Certification requirements vary sharply by cellular structure: closed cell demands ignition barrier compliance for residential cavities under IECC, while open cell faces stricter VOC thresholds under EPA SNAP reformulation timelines. Hybrid formulations currently occupy a regulatory gray zone as code officials evaluate thermal performance claims against established fire test protocols.
- Closed Cell Foam:Denser thermoset structure with trapped blowing agent gas delivers compressive strength above 15 psi and moisture resistance below 1.0 perms. Demand clusters in below-grade foundation walls across Florida, Texas, and Louisiana where hydrostatic pressure and termite exclusion drive specification. EPA SNAP-compliant HFO formulations now dominate new stock.
- Open Cell Foam:Lower-density cellular matrix with permeable structure allows moisture vapor diffusion, making it suitable for attic floor applications in mixed-humidity climates. Residential retrofit contractors in Georgia and the Carolinas favor this chemistry for cost-sensitive envelope sealing where ignition barriers are not triggered.
- Hybrid Foam:Bridging formulations attempt to capture closed-cell R-value at open-cell yield rates; currently limited by inconsistent code recognition across jurisdictions.
- Rigid Foam:Pre-formed board stock competing with spray-applied systems in commercial continuous insulation specifications; faces headwinds from labor cost advantages of field-applied SPF.
Leading the category by volume: Closed Cell Foam. Growing fastest: Hybrid Foam.
Application:
Application method determines equipment investment and crew certification tiers. Insulation work requires plural-component rigs and OSHA competent person training, while coating applications demand surface preparation protocols that filter out casual entrants.
- Insulation:Thermal barrier installation in walls, roofs, and foundations represents the core revenue pool. New construction in southern US metropolitan areas and deep energy retrofits of 1970s housing stock drive specification volume. Continuous insulation mandates in ASHRAE 90.1 and IECC directly pull material through this channel.
- Coating:Protective and reflective roof coatings over SPF substrates create recurring maintenance revenue. Demand concentrates in commercial building portfolios where facility managers bundle re-coating with warranty extensions.
- Sealant:Air barrier detailing at penetrations and transitions; lower equipment barrier attracts smaller contractors but compresses margins.
- Soundproofing:Niche specification in multi-family residential and home theater installations; open cell dominates for acoustic absorption performance.
Insulation commands the largest share. Coating applications are climbing the fastest as building owners extend asset lifecycles.
End User:
End-user verticals segment by performance specification intensity and procurement sophistication. Construction maintains fragmented demand across project types, while marine and HVAC OEMs consolidate volume around fewer, larger contracts with stringent qualification requirements.
- Construction:Residential retrofit contractors represent the most dynamic demand segment as homeowners prioritize envelope sealing and humidity control. Southern US building codes with continuous insulation mandates and condensation risk management requirements specification-pull SPF ahead of fiberglass alternatives.
- HVAC:Original equipment manufacturers specify semi-rigid foam for ductwork insulation and air handling unit casings where lightweight, monolithic coverage outperforms fibrous materials. This channel is expanding fastest as OEMs seek factory-applied solutions reducing field labor.
- Marine:Boat builders and shipyards adopt SPF for hull and deck insulation where weight reduction and moisture resistance justify premium positioning. Qualification timelines are longest in this segment due to fire performance and outgassing requirements.
- Automotive:Limited penetration confined to specialty vehicle and refrigerated transport applications; faces competition from molded PU and expanded polystyrene.
Construction dominates absolute volume. HVAC OEM integration shows the steepest expansion trajectory.
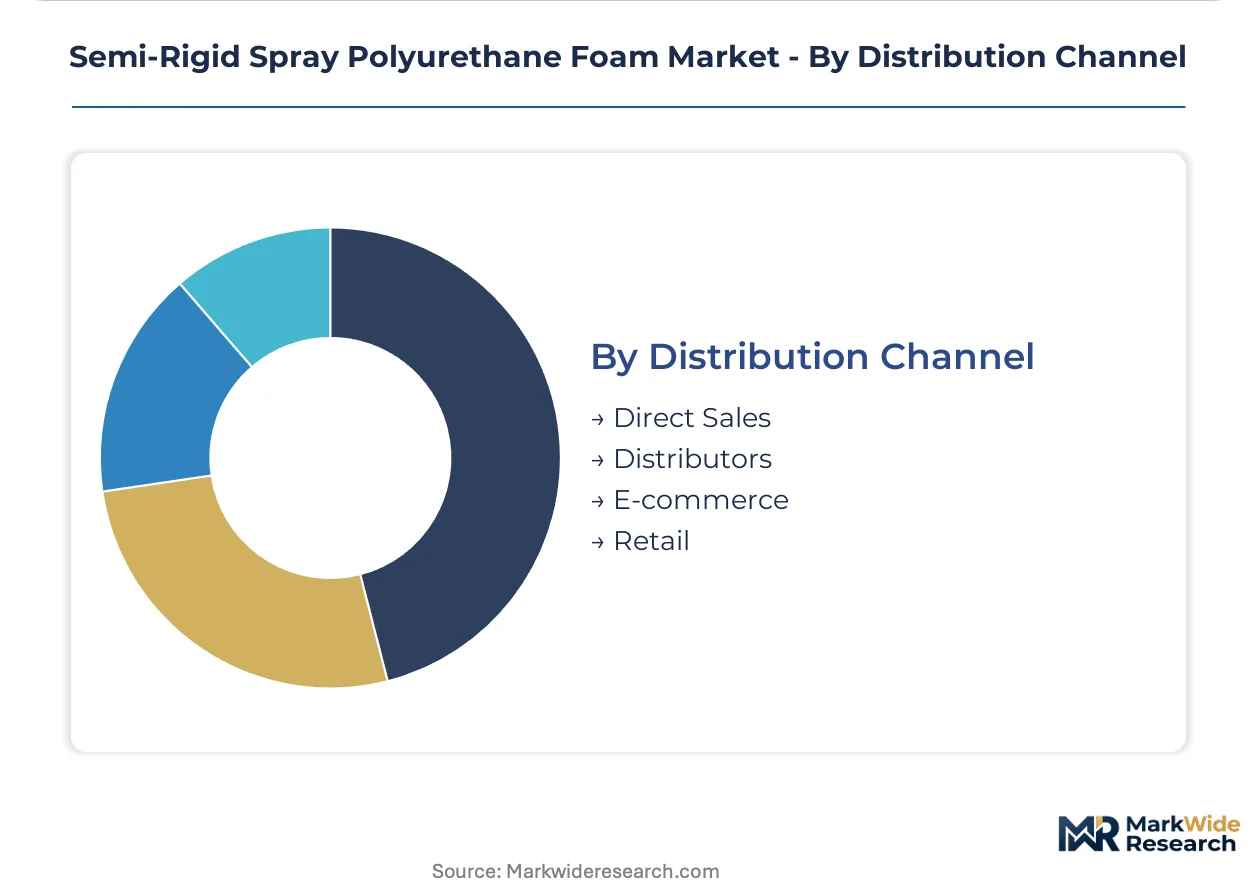
Distribution Channel:
Channel selection reflects customer scale and service intensity requirements. Large contractors with predictable volume favor direct relationships, while smaller applicators and one-time buyers default to distributor or retail access.
- Distributors:Two-step distribution through roofing and insulation specialists remains the volume anchor for commercial construction. Distributors with captive applicator networks are displacing traditional arm's-length relationships in southern US retrofit markets.
- Direct Sales:National accounts and multi-location contractors procure directly from chemical suppliers to secure volume pricing and technical support. This channel concentrates among the largest SPF contractors with OSHA-compliant training infrastructure.
- E-commerce:Emerging channel for DIY-oriented open cell kits and accessory products; limited by equipment complexity and safety training requirements for professional-grade formulations.
- Retail:Hardware and home center presence confined to low-pressure disposable canisters for small-scale air sealing; marginal to professional SPF economics.
Distributors move the most material. Direct sales are gaining share fastest as contractor consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States and Germany, while consumption growth accelerates across humid climate zones where building envelope durability drives specification. The southern United States absorbs disproportionate volume due to condensation risk management requirements in residential retrofit markets.
United States
Residential retrofit contractors in Florida, Texas, and Louisiana specification-pull closed-cell formulations for below-grade foundation walls where hydrostatic pressure and termite exclusion intersect. The EPA's SNAP program mandates HFO-based blowing agents, compressing margins for late reformulators while rewarding early movers. Houston and Miami metropolitan clusters anchor installation capacity scaling.
Germany
Marine OEMs in Northern Germany specify monolithic SPF for hull insulation where weight reduction justifies premium positioning. The EU F-Gas Regulation restricts high-GWP blowing agents in imported materials, accelerating R&D toward sub-150 GWP chemistries. Hamburg shipyards drive qualification timelines for fourth-generation foam formulations.
Canada
Cold climate construction in Ontario and Quebec prioritizes continuous insulation mandates under provincial energy codes. Health Canada's PMRA oversees chemical registration for building materials entering the supply chain. Toronto's commercial retrofit channel consolidates procurement around integrated roofing and air barrier packages.
Japan
HVAC equipment manufacturers in the Kanto region specify factory-applied semi-rigid foam for ductwork insulation reducing field labor. METI energy efficiency standards create demand pull for lightweight monolithic solutions. Nagoya industrial corridors concentrate OEM qualification programs.
Australia
Building envelope contractors in New South Wales and Queensland adopt SPF for humidity control in coastal residential construction. The country's national building code regulator mandates continuous insulation layers in commercial envelopes. Sydney metropolitan applicator networks expand training infrastructure to match demand.
Semi-Rigid Spray Polyurethane Foam Market Vendor Landscape
Top-tier vendors anchor formulation chemistry and upstream raw material positions, while mid-tier applicator networks compete on installation capacity and regional code expertise. The vendor base stratifies across three archetypes: integrated chemical producers with captive polyol and isocyanate supply, specialty applicators with certified training infrastructure, and building envelope bundlers with multi-product distribution channels. Dominant competitive moves include backward integration into blowing agent technology and geographic expansion through contractor network acquisitions.
Among integrated chemical producers, BASF Corporation and Honeywell occupy positions spanning upstream raw materials through downstream formulation. Lapolla Industries Inc. exemplifies the specialty applicator archetype with its North American contractor training network. CertainTeed Corporation anchors the building envelope bundler segment through integrated roofing and insulation distribution channels. These three patterns represent the structural fault lines along which competitive positioning consolidates.
| Leading Market Players |
|---|
| Gaco Western |
| Lapolla Industries Inc. |
| Rhine Linings Corporation |
| BASF Corporation |
| Premium Spray Products |
| Mitex International |
| Honeywell |
| CertainTeed Corporation |
| Foam Supplies |
| Others |
Supply Flow & Price Mechanics
Certified applicator concentration across Houston, Miami, and Dallas-Fort Worth metropolitan clusters drives labor-cost differentials that separate premium contractor networks from economy-tier installation bids. OSHA respiratory protection mandates elevate base labor rates, compressing margins for standalone distributors unable to bundle training certification with material supply.
Pricing Analysis
Margin tightening in economy-tier open-cell formulations reflects methylene diphenyl diisocyanate and polymeric MDI feedstock volatility tracking benzene derivative markets. Three-tier pricing structure across premium certified-applicator, standard distributor-channel, and economy DIY-kit levels differentiates by ignition barrier compliance grade and OSHA training documentation. Price erosion runs through standard-tier channels as captive-applicator networks displace arm's-length distribution in southern US retrofit markets. Residential retrofit contractors exhibit highest price sensitivity, while marine OEMs accept premium positioning for fire-performance-qualified formulations.
Supply Chain Analysis
Regional distribution centers in Houston, Charleston, and Los Angeles anchor hub-and-spoke patterns serving contractor networks across humidity-driven demand zones. Upstream polyol and isocyanate production concentrates in the United States, Germany, and Belgium, with blowing agent chemistry innovation tethered to EPA SNAP and EU F-Gas Regulation compliance timelines. Raw material dependencies rest on crude oil derivatives, hydrofluoroolefin feedstocks, and specialized catalyst packages. Single-source vulnerability in HFO blowing agent supply creates qualification bottlenecks for reformulated products. Distribution runs through roofing and insulation specialists with captive applicator networks displacing traditional two-step channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semi-rigid SPF market sits in a blowing agent technology-transition phase as hydrofluoroolefin formulations displace legacy hydrofluorocarbon chemistries under regulatory phase-down schedules.
For Market Incumbents: Anticipate margin compression in late-reformulated product lines as EPA SNAP enforcement hardens specification requirements for HFO-based alternatives. Prioritize backward integration into blowing agent technology partnerships to secure cost positions against feedstock volatility. Defend specification lock-in by accelerating certified applicator network expansion across Florida, Texas, and Louisiana metropolitan clusters before competitor qualification programs mature. For New Entrants and Emerging Players: California's accelerated HFC phase-down schedule under Title 17 opens a window for next-generation foam formulations to capture specification share in commercial retrofit channels ahead of national code adoption. Target HVAC OEM integration opportunities in the Kanto and Nagoya industrial corridors where factory-applied insulation demand outpaces qualified supplier bases. Enter through technical partnership models with equipment manufacturers seeking captive foam supply rather than competing head-to-head with established applicator networks. For Investors and Strategic Acquirers: Re-rating potential sits with specialty applicators possessing OSHA-compliant training infrastructure and captive southern US contractor relationships given consolidation pressure on standalone distributors. Long-term viability favors assets with demonstrated HFO formulation qualification timelines and marine OEM fire-performance certifications. Monitor state-level HFC phase-down adoption velocity as the inflection signal for reformulation capex cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Technology | Captive HFO supply secures margin protection against EPA SNAP-driven feedstock cost volatility. |
| Certified Applicator Network Expansion | OSHA competent person training infrastructure locks in specification loyalty across southern US retrofit markets. |
| Marine OEM Qualification Programs | Hamburg and Northern European shipyard certifications open premium positioning in weight-sensitive hull applications. |
| HVAC Equipment Integration Partnerships | Factory-applied foam specifications in Kanto region OEMs create captive demand outside construction distribution. |
| Hybrid Foam Formulation R&D | Bridging closed-cell thermal performance with open-cell yield economics penetrates cost-sensitive multi-family residential segments. |
Methodological Framework
Independent corroboration across applicator contractor interviews, chemical supplier technical directors, and building code official consultations underwrites the qualitative findings. Primary fieldwork engaged certified SPF installers, roofing distributor procurement leads, marine OEM specification engineers, and HVAC equipment manufacturing directors. Secondary validation drew from EPA SNAP program filings, OSHA isocyanate exposure standard documentation, IECC and ASHRAE 90.1 code revision records, and customs trade data for polyol and isocyanate import flows. Bottom-up demand modeling across construction, marine, and HVAC verticals triangulated against top-down chemical production capacity assessments.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by cellular structure chemistry, application method, end-user vertical, and procurement channel. The analytical framework models closed-cell, open-cell, hybrid, and rigid foam product types against insulation, coating, sealant, and soundproofing applications. CAGRs derive from regression analysis of historical formulation shipment data, regulatory compliance timeline impacts, and continuous insulation mandate adoption curves. Industry-specific forecast inputs include certified applicator pipeline capacity constraints and state-level HFC phase-down implementation schedules.
Caveats apply where OSHA enforcement intensity, petrochemical feedstock price spikes, or ignition barrier code fragmentation could materially shift the outlook. Forecasts reflect base-case assumptions regarding HFO blowing agent supply scale-up and contractor training program expansion rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market