
 Phthalate and Non-Phthalate Plasticizers Market | 2026-2036
Phthalate and Non-Phthalate Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Phthalate and Non-Phthalate Plasticizers Market Analytics
Automotive interiors is decoupling from legacy phthalate dependence as OEMs rewrite material specifications. BASF SE leverages its specialty ester portfolio to anchor supply relationships with tier-one seating suppliers. Eastman Chemical Company differentiates through non-phthalate innovation targeting medical-grade film applications. ExxonMobil Chemical Company dominates commodity-scale dioctyl terephthalate production for wire and cable jacketing.
Phthalate and non-phthalate plasticizers are organic ester additives that intercalate between polyvinyl chloride polymer chains to reduce glass transition temperature and impart flexibility, with molecular weights typically spanning 300 to 600 g/mol and compatibility governed by solubility parameter matching. Their primary purpose centers on converting rigid thermoplastic resins into processable, durable elastomeric materials for extrusion and calendering operations. Non-phthalate esters now command the fastest trajectory as regulatory pressure elevates their cost premium into an acceptable range for healthcare and consumer goods. Flexible PVC formulations still occupy the largest volume pool, though thermoplastic elastomer compounding is expanding as processors seek phthalate-free alternatives without sacrificing process efficiency. Flooring and medical devices represent contrasting margin profiles, with the latter extracting value from extraction and migration testing compliance.
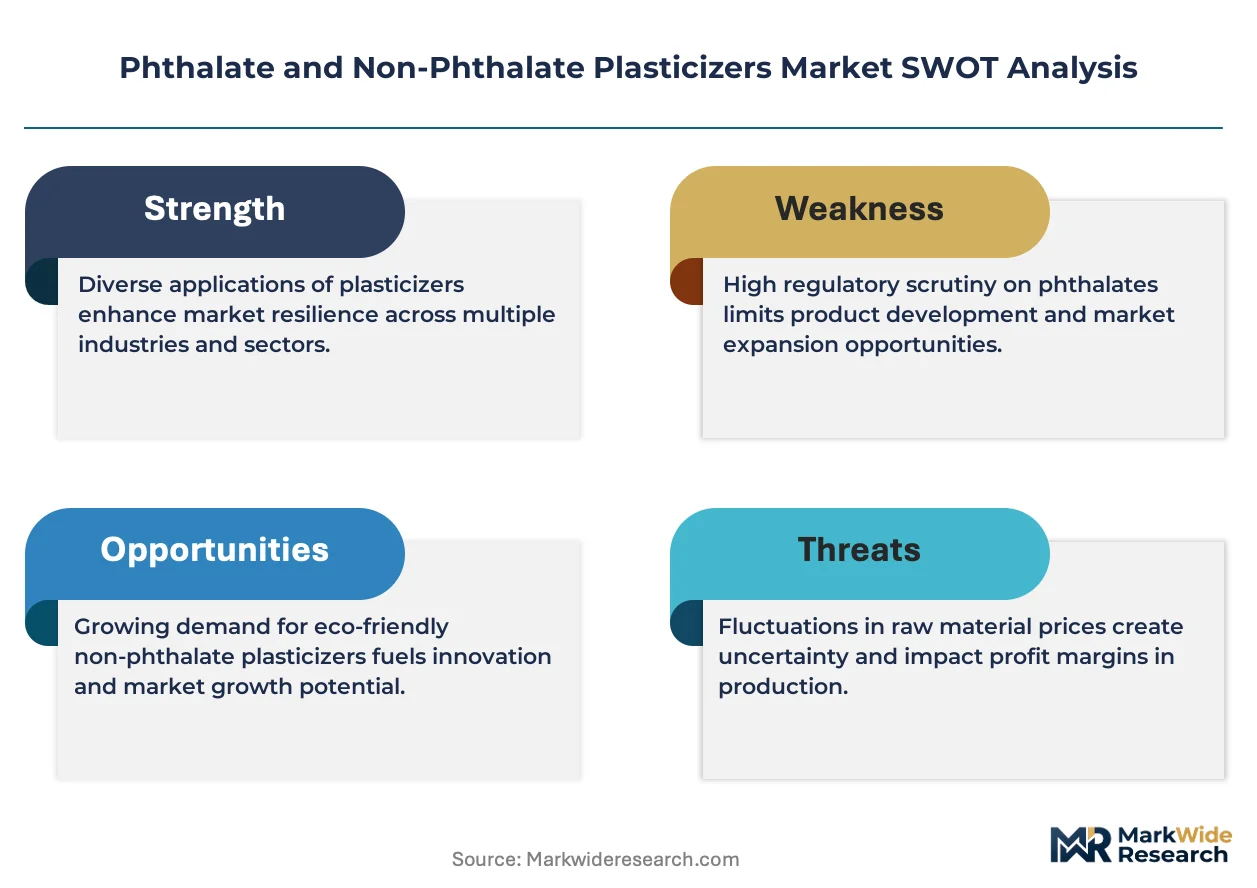
The EPA administers TSCA Section 6 authority over phthalate risk evaluation, while REACH Annex XVII restrictions in Europe constrain diethylhexyl phthalate in articles with prolonged skin contact. ECHA's ongoing substance evaluation of additional ortho-phthalates is tightening the window for legacy chemistries. China's MEE implements GB standards for plasticizer emissions from compounding facilities, shaping local production economics. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets.
Market Dynamics
REACH Annex XVII restrictions on diethylhexyl phthalate are forcing compounders to reformulate entire product lines, redirecting capital toward terephthalate and adipate ester chemistries while stranding legacy ortho-phthalate assets across European flexible PVC supply chains.
Growth Catalysts
- Grid modernization mandates:Utilities in the United States and Germany are replacing aging wire and cable infrastructure, driving specification upgrades to high-performance non-phthalate insulation compounds that withstand elevated thermal loads.
- REACH regulatory pressure:ECHA's ongoing substance evaluation of additional ortho-phthalates is accelerating OEM timelines for phthalate-free automotive interior certification.
- Automotive supply chain concentration:Flexible PVC compounding capacity expansion in China's Yangtze River Delta continues to outpace other regions, anchoring regional demand for plasticizer inputs.
Market Restraints
- Feedstock volatility:Propylene and 2-ethylhexanol price swings compress margins for dioctyl terephthalate producers dependent on naphtha-derived intermediates.
- Technical performance gaps:Non-phthalate alternatives still exhibit inferior low-temperature flexibility compared to legacy diethylhexyl phthalate in certain calendered film applications.
- Substitution pressure from TPEs:Thermoplastic elastomer compounds are displacing flexible PVC in medical tubing and consumer goods, eroding addressable volume for ester plasticizers.
Strategic Opportunities
- Medical-grade certification expansion:US FDA and European MDR biocompatibility testing requirements for extraction and migration profiles create premium pricing tiers for compliant non-phthalate formulations.
- Biobased ester development:Convergence of catalytic esterification processes with renewable feedstock sourcing enables carbon intensity reduction claims for sustainability-driven brand owners.
- Direct compounder relationships:Bypassing traditional distributor networks to secure formulation partnerships with tier-one automotive seating suppliers locks in multi-year offtake agreements.
Industry Challenges
- Reformulation timeline compression:Accelerated regulatory deadlines force simultaneous compatibility testing across multiple polymer systems without extended validation periods.
- Cross-jurisdictional compliance complexity:Divergent GB standards from China's MEE, EPA TSCA Section 6 authority, and REACH restrictions require parallel technical dossiers that strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phthalate and Non-Phthalate Plasticizers Market |
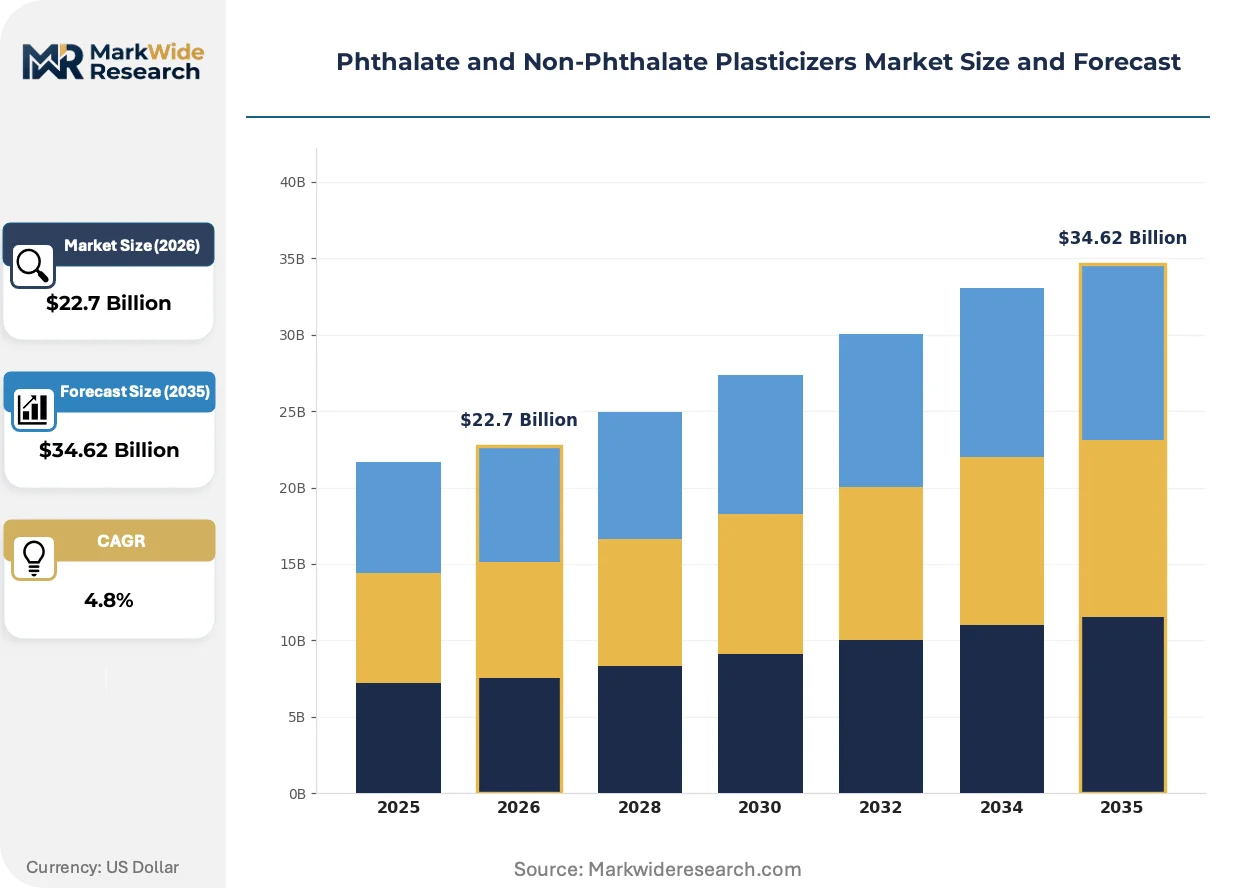
| Market Size in 2026 | $22.7 Billion |
| Market Size in 2035 | $34.62 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diethylhexyl Phthalate, Butyl Benzyl Phthalate, Dioctyl Terephthalate, Non-Phthalate Esters Application: Flooring, Automotive Interiors, Medical Devices, Consumer Goods End User: Construction, Healthcare, Manufacturing, Electronics Formulation Type: Flexible PVC, Rigid PVC, Thermoplastic Elastomers, Gelatin |
| Companies Covered | BASF SE, Eastman Chemical Company, ExxonMobil Chemical Company, Arkema Inc., Lanxess AG, DIC Corporation, Evonik Industries AG, KLJ Group, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phthalate and Non-Phthalate Plasticizers Market Evolving Landscape
Reformulation chemistry is converging with sustainability metrics and digital supply chain verification, compressing development cycles while raising the technical bar for market entry.
Reactive plasticization technology is unifying covalent bonding approaches with conventional additive intercalation, enabling permanent flexibility without migration risk. Medical device manufacturers in Switzerland and Germany are piloting these systems for implantable-grade tubing. The structural consequence is unifying performance permanence with regulatory compliance in a single platform, compressing the traditional trade-off between processability and durability.
ECHA's expanding candidate list evaluation for endocrine-disrupting properties is tightening the window for legacy ortho-phthalate chemistries. Compounders serving European automotive and consumer goods markets are accelerating qualification of terephthalate and cyclohexanoate alternatives. Wire and cable jacketing specifications in Germany and France are now explicitly excluding diethylhexyl phthalate from new infrastructure tenders.
Automotive OEMs are consolidating approved material lists around pre-certified compound libraries, compressing supplier qualification from multi-year cycles to 18-month windows. Tier-one seating and interior trim suppliers in Michigan and Bavaria now demand bundled technical data packages covering migration, fogging, and odor performance. This pattern is most visible in premium electric vehicle programs where cabin air quality claims support brand differentiation.
Phthalate and Non-Phthalate Plasticizers Market Segmentation
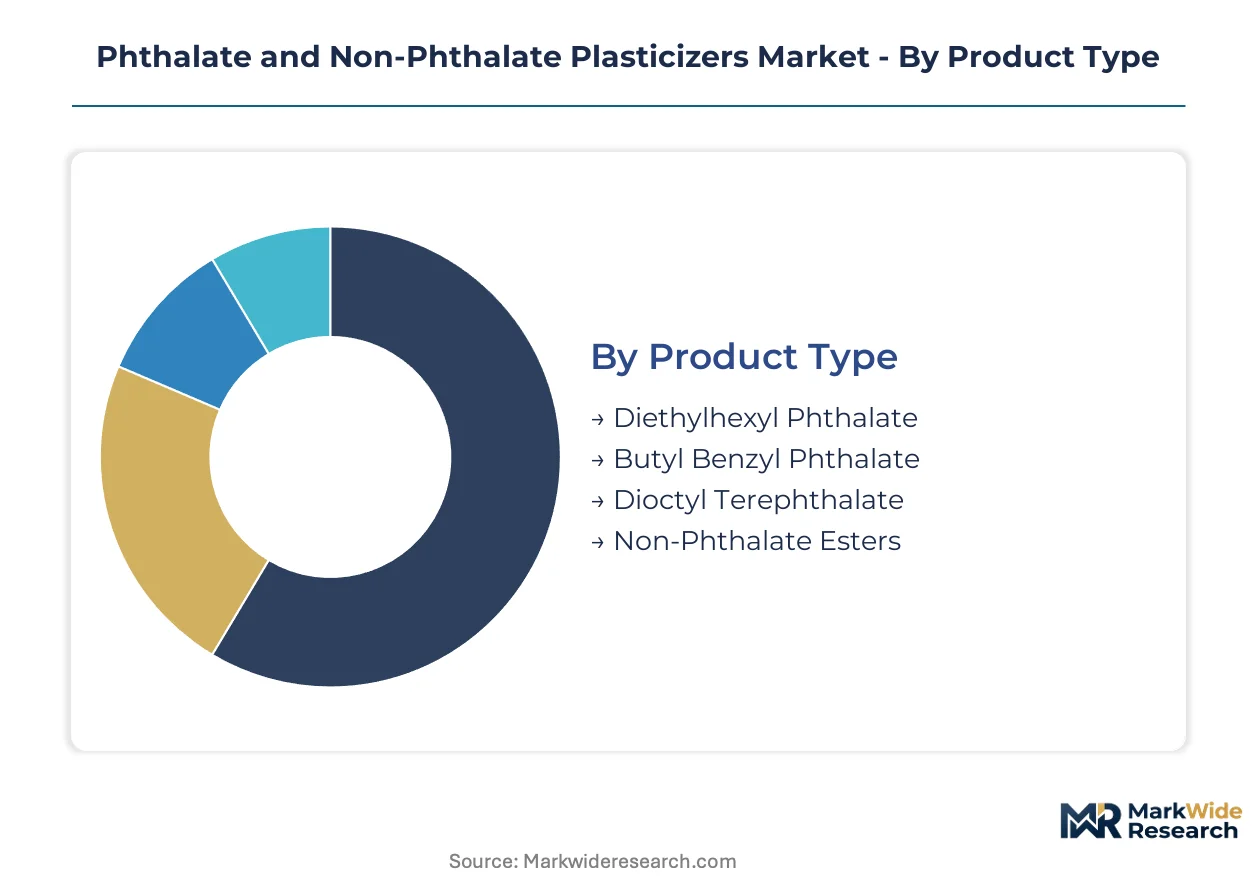
Plasticizer segmentation reveals divergent margin structures across chemistries and end-uses. Product type determines regulatory exposure, while application segments separate commodity volume from premium certification requirements.
Product Type:
Volume concentration sits with legacy ortho-phthalates, while premium pricing attaches to migration-resistant alternatives.
- Diethylhexyl Phthalate:The dominant ortho-phthalate ester exhibits excellent compatibility with suspension-grade PVC resins and superior low-temperature flexibility. Demand is concentrating in Asian wire and cable jacketing where REACH-equivalent restrictions remain phased. ECHA's Annex XVII constraints are forcing accelerated substitution timelines in European automotive supply chains.
- Non-Phthalate Esters:Adipate, terephthalate, and cyclohexanoate chemistries command certification premiums for medical tubing and pediatric toy applications. Demand is concentrating in German and Swiss medical device manufacturing where US FDA and European MDR biocompatibility testing creates defensible pricing tiers.
- Dioctyl Terephthalate:The primary phthalate-free alternative for wire insulation compounds, offering comparable electrical properties without endocrine-disruptor classification.
- Butyl Benzyl Phthalate:Niche specialty ester retained in flooring adhesives and sealant formulations where fast-fuse characteristics justify continued use despite regulatory pressure.
Today's leader: Diethylhexyl Phthalate. Tomorrow's challenger: Non-Phthalate Esters.
Application:
Application segments separate infrastructure replacement cycles from consumer-driven specification changes.
- Automotive Interiors:Seating, door panels, and instrument cluster skins require low-fogging, low-odor formulations with migration resistance. OEMs in Michigan and Bavaria are consolidating approved material lists around pre-certified compound libraries, compressing supplier qualification windows.
- Medical Devices:Tubing, blood bags, and IV connectors demand extraction and migration testing compliance under US FDA and European MDR frameworks. Swiss and German manufacturers are piloting reactive plasticization systems for implantable-grade applications.
- Flooring:Sheet and tile products balance cost efficiency with abrasion resistance in commercial installations.
- Consumer Goods:Toys and food contact articles face the strictest ortho-phthalate limits, driving rapid terephthalate adoption.
Medical Devices extract the highest margins. Automotive Interiors is expanding most quickly.
End User:
End user concentration reflects divergent procurement sophistication and specification authority.
- Healthcare:Hospital systems and device OEMs mandate certificate of analysis documentation for every lot, with biocompatibility testing costs embedded in supplier pricing.
- Construction:Flooring and wire insulation demand scales with residential and commercial building permits.
- Manufacturing:Tier-one automotive suppliers and flexible PVC compounders anchor volume procurement with multi-year offtake agreements.
- Electronics:Cable jacketing for data centers and telecommunications infrastructure requires flame-retardant additive packages.
Healthcare commands specification authority. Manufacturing anchors volume scale.
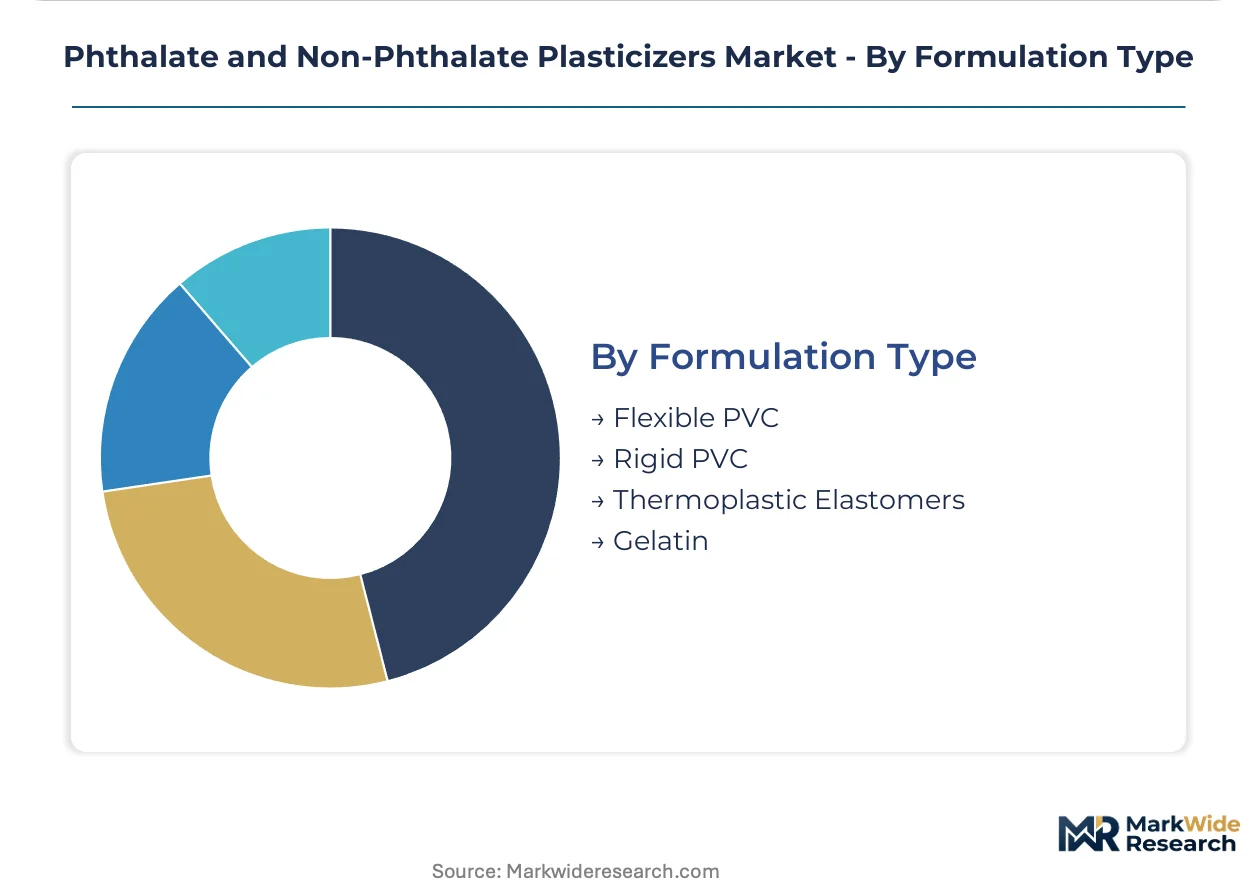
Formulation Type:
Formulation chemistry determines plasticizer loading levels and permanence requirements.
- Flexible PVC:The largest volume pool, with plasticizer loadings of 30-50 phr converting rigid resin into elastomeric compounds for extrusion and calendering operations.
- Thermoplastic Elastomers:Phthalate-free alternatives displacing flexible PVC in medical tubing and consumer goods, eroding ester plasticizer addressable volume.
- Rigid PVC:Minimal plasticizer content for impact modification in pipe and profile applications.
- Gelatin:Specialty softgel pharmaceutical capsules utilizing plasticizer-plasticizer blends for controlled release properties.
Flexible PVC retains volume dominance. Thermoplastic Elastomers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting compounding investments toward jurisdictions with phased compliance timelines, creating divergent cost structures for phthalate-dependent versus phthalate-free formulations across major producing regions.
China
Automotive supply chain concentration in the Yangtze River Delta drives plasticizer demand as flexible PVC compounding capacity expands for EV interior programs. The MEE enforces GB standards on emissions from compounding facilities, elevating environmental compliance costs for local producers. Tianjin and Shanghai host the largest specialty ester manufacturing clusters serving domestic medical device exporters.
Germany
Wire and cable infrastructure modernization across Bavaria and North Rhine-Westphalia accelerates specification shifts to dioctyl terephthalate for grid resilience projects. ECHA's REACH Annex XVII restrictions on diethylhexyl phthalate force compounders to reformulate automotive interior lines ahead of 2025 certification deadlines. The Cologne-Leverkusen chemical corridor anchors terephthalate ester production for European medical tubing manufacturers.
United States
Utility grid replacement programs in Texas and California drive non-phthalate insulation compound procurement for high-temperature transmission lines. The EPA administers TSCA Section 6 authority over phthalate risk evaluation, creating regulatory uncertainty for legacy ortho-phthalate formulations. The Gulf Coast petrochemical complex supplies naphtha-derived intermediates for dioctyl terephthalate producers serving wire and cable jacketing markets.
India
Construction sector expansion in Maharashtra and Gujarat sustains flooring and wire insulation demand for flexible PVC applications. BIS standards for plasticizer content in consumer goods face gradual alignment with REACH-equivalent restrictions, compressing reformulation timelines for export-oriented compounders. The Vadodara-Ankleshwar industrial belt concentrates adipate ester production for domestic automotive seating suppliers.
Switzerland
Medical device manufacturing precision in Basel and Zurich sustains premium pricing for migration-tested non-phthalate formulations in implantable-grade tubing. Swissmedic maintains stringent biocompatibility requirements that exceed EU MDR baselines, creating certification premiums for compliant suppliers. The Basel pharmaceutical cluster pilots reactive plasticization systems for controlled-release drug delivery applications.
Phthalate and Non-Phthalate Plasticizers Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical conglomerates dominating commodity-scale terephthalate production while specialty ester houses capture medical-grade premiums. The vendor base stratifies into three tiers: multinational diversified chemicals with captive feedstock integration, regional compounders serving automotive tier-one suppliers, and niche formulators certified for healthcare applications. Strategic moves center on backward integration into 2-ethylhexanol supply and direct partnerships with compounders to bypass distributor networks.
Within the diversified chemical tier, BASF SE, Eastman Chemical Company, and ExxonMobil Chemical Company occupy positions reflecting distinct strategic emphases. BASF SE exemplifies the specialty ester archetype through its portfolio breadth, while Eastman Chemical Company represents non-phthalate innovation positioning, and ExxonMobil Chemical Company anchors commodity-scale production capacity. These three entities collectively illustrate how feedstock access, regulatory anticipation, and end-use certification requirements determine competitive positioning in plasticizer supply.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| ExxonMobil Chemical Company |
| Arkema Inc. |
| Lanxess AG |
| DIC Corporation |
| Evonik Industries AG |
| KLJ Group |
| Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
Reactive plasticization technology maturation simultaneously compresses formulation development cycles and concentrates premium production among Swiss and German medical device compounders with certified cleanroom capabilities. This shift bifurcates cost structures between legacy ester additive production and covalent-bonding systems that command certification premiums for implantable-grade applications.
Pricing Analysis
Distributor margins in legacy ortho-phthalate supply chains face compression as tier-one automotive seating suppliers negotiate direct compounder relationships. Three-tier pricing structure across medical-grade, automotive-certified, and commodity wire insulation levels reflects extraction testing costs and REACH compliance documentation. Pricing pressure stems from 2-ethylhexanol feedstock volatility transmitted through naphtha-derived intermediate costs. Healthcare device OEMs exhibit lowest price sensitivity due to embedded biocompatibility testing requirements, while construction flooring buyers prioritize volume discounts.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs and Swiss medical device manufacturers require qualified backup suppliers for terephthalate and adipate ester formulations. Geographic concentration centers on China, Germany, and the United States, with the Yangtze River Delta, Cologne-Leverkusen corridor, and Gulf Coast petrochemical complex anchoring capacity. Raw material dependencies rest on propylene, 2-ethylhexanol, and purified terephthalic acid feedstocks. Single-source vulnerability concentrates in specialized medical-grade certification holders. Distribution runs through regional compounder networks with direct OEM qualification bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between REACH-equivalent restrictions in Europe and phased compliance timelines in Asia creates formulation cost arbitrage opportunities for compounders with multi-continental production footprints.
For Market Incumbents: Anchor supply relationships through captive 2-ethylhexanol production or long-term offtake agreements with naphtha crackers. Invest in parallel REACH and FDA certification dossiers to preempt regulatory timeline compression. Defend against thermoplastic elastomer substitution by embedding reactive plasticization R&D within tier-one automotive partnerships.
For New Entrants and Emerging Players: Specialty distributors serving mid-tier medical device manufacturers in India and Southeast Asia represent the most penetrable channel entry point. Target biobased ester development partnerships with sustainability-focused brand owners seeking carbon intensity reduction claims. Pursue direct formulation collaboration with EV interior programs in China's Yangtze River Delta where qualification windows remain open.
For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with automotive seating certifications because OEM consolidation around pre-approved material libraries concentrates purchasing power among qualified suppliers. The five-to-ten year viability window favors targets with dual REACH-FDA certification capabilities. Monitor ECHA candidate list expansion velocity as the inflection signal for accelerated ortho-phthalate asset stranding.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into 2-Ethylhexanol | Captive feedstock supply insulates margin compression from naphtha price volatility for DOT producers. |
| Medical-Grade Certification Expansion | US FDA and European MDR biocompatibility testing creates defensible pricing tiers for compliant non-phthalate formulations. |
| Direct Compounder Partnerships | Bypassing distributor networks locks in multi-year offtake agreements with tier-one automotive seating suppliers. |
| Biobased Ester Development | Renewable feedstock sourcing enables carbon intensity reduction claims for sustainability-driven brand owners in packaging. |
| Reactive Plasticization Scale-Up | Covalent bonding systems address migration compliance for implantable-grade tubing in Swiss and German medical device manufacturing. |
Research Methodology
Direct dialogue with flexible PVC compounders, automotive tier-one procurement directors, medical device regulatory affairs leads, and specialty ester plant managers grounded qualitative insights in operational reality. Secondary validation drew from ECHA substance evaluation dossiers, EPA TSCA Section 6 risk evaluation documents, SEC 10-K filings of diversified chemical producers, and customs trade data tracking plasticizer intermediate flows. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Segment-level projections incorporated chemistry type, end-use application, formulation system, and regional regulatory cluster dimensions throughout the forecast period. CAGRs emerged from elasticity-adjusted demand curves and capacity expansion announcements. Key inputs included REACH Annex XVII implementation timelines, MEE GB standard enforcement intensity, and automotive OEM material specification revision cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA endocrine-disruptor classification expansion and thermoplastic elastomer substitution rates in medical tubing. Deviation in Chinese EV interior program growth or naphtha-to-ethylene cracker economics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Cement Additives Market
Additives
Global Metal Scavenging Agents Market
Additives
Dipotassium Guanylate Market
Additives
Chelating Agents Market
Additives
Asia Pacific Plastic Additives Market
Additives
South America Concrete Admixtures Market
Additives
Calcium Diglutamate Market
Additives
Plastic Additives Market
Additives
Global Synthetic Tackifier Market
Additives
Extruded Inclusions Market
Additives
Sorbitan Esters Market
Additives
FD and C Lakes Market
Additives
Silicone Additives Market
Additives
Water-Borne Coating Additives Market
Additives
Packaging Coating Additives Market
Additives
North America Phosphate Esters Market