
 Concrete Containing Polymer Market | 2026-2036
Concrete Containing Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Containing Polymer Market Outlook
ISO 9001 quality management certification is reorganizing supplier qualification protocols for infrastructure-grade polymer concrete systems. BASF SE leverages its integrated polymer chemistry platform to control raw material consistency across regional batch plants. Sika AG anchors its position through specialized anchoring and waterproofing formulations that dominate European tunnel specifications. Wacker Chemie AG competes on silicone-polymer hybrid binders that sustain flexibility across freeze-thaw cycles.
Concrete containing polymer denotes Portland cement matrices modified with latex, epoxy, or acrylic dispersions, typically incorporating 5–20% polymer solids by weight of cement to enhance tensile strength, reduce permeability, and improve bond to deteriorated substrates. The primary industrial purpose centers on rehabilitating chloride-contaminated bridge decks, wastewater treatment structures, and industrial flooring where conventional concrete fails from chemical attack or cracking. Polymer Modified Concrete leads product type volume due to decades of Department of Transportation approval history and established contractor familiarity, while Self-Compacting Concrete captures the fastest specification growth in precast elements where labor constraints and complex reinforcement geometries demand flowability without vibration. Structural Applications concentrate margin pools through performance-based specifications that command premium pricing for certified compliance.
The Federal Highway Administration mandates minimum flexural strength and chloride permeability thresholds for polymer overlays on federally aided bridge projects, filtering out uncertified applicators. EPA stormwater regulations under the Clean Water Act shape demand for permeable polymer concrete pavements that reduce runoff volume from commercial developments. ASTM C1439 standard test methods for polymer-modified mortar and concrete further gate market access by requiring documented freeze-thaw durability and adhesion performance. Stakeholders must monitor evolving state-level Buy America provisions that threaten polymer supply chains dependent on imported latex emulsions.
Market Dynamics
Federal bridge rehabilitation mandates are compressing contractor qualification windows while polymer latex supply chains face mounting scrutiny under domestic sourcing rules. The collision between performance-based specifications and import-dependent raw material streams is forcing specification rewrites across Department of Transportation portfolios.
Growth Catalysts
- EPA Stormwater Resilience Mandates:The EPA's Clean Water Act enforcement is mandating permeable pavement systems for commercial developments exceeding certain impervious surface thresholds. Polymer-modified concrete delivers the freeze-thaw durability and void structure that conventional porous asphalt cannot sustain.
- German Federal Transport Budget Prioritization:Bridge deck rehabilitation commands dedicated funding lines in Germany's federal infrastructure allocation. Durability specifications favor polymer-modified overlays with documented chloride impermeability exceeding 2000 coulombs.
- Labor-Constrained Precast Manufacturing:Self-compacting polymer concrete is eliminating vibration requirements in complex reinforcement geometries. Precast producers facing skilled labor shortages are specifying flowable mixes that reduce placement time and rework rates.
Market Restraints
- Styrene-Butadiene Latex Price Volatility:Petrochemical feedstock fluctuations transmit directly to polymer modifier costs. Contractors absorbing material escalation risk in fixed-price bridge rehabilitation contracts face margin compression when latex prices spike.
- Import-Dependent Supply Concentration:High-performance acrylic and epoxy dispersions concentrate among Asian chemical producers. Buy America provisions in US federally aided projects threaten specification compliance when domestic qualified suppliers number fewer than three.
- Curing Temperature Sensitivity:Epoxy-modified systems require sustained ambient temperatures above 10°C for proper crosslinking. Northern climate applications face seasonal installation windows that compress annual utilization rates for specialized applicator fleets.
Strategic Opportunities
- India Smart City Infrastructure:Urban flood management investments under India's Smart Cities Mission are creating specification pathways for permeable polymer pavement. Municipal corporations in Bengaluru and Chennai are piloting stormwater harvesting integrated with polymer-modified pervious concrete.
- Carbon-Capture Concrete Convergence:Mineralized CO2 curing of polymer-modified precast elements is combining durability enhancement with embodied carbon reduction. Precast producers serving LEED-targeting commercial developments are positioning this hybrid technology for specification advantage.
- Digital Specification Platforms:Cloud-based construction procurement networks are enabling real-time polymer concrete mix verification against certified performance databases. DOT maintenance divisions are piloting blockchain-anchored batch records for warranty enforcement.
Industry Challenges
- Specialized Applicator Certification Bottlenecks:Bridge deck overlay warranties require applicator certification to manufacturer-specific protocols. Training pipeline capacity constraints are extending project mobilization timelines by 4-8 weeks in high-demand regions.
- Multi-Standard Compliance Complexity:Projects spanning federal, state, and municipal jurisdictions must satisfy overlapping ASTM, AASHTO, and agency-specific test methods. Testing laboratory backlogs for freeze-thaw durability and bond strength verification are delaying project closeouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Containing Polymer Market |
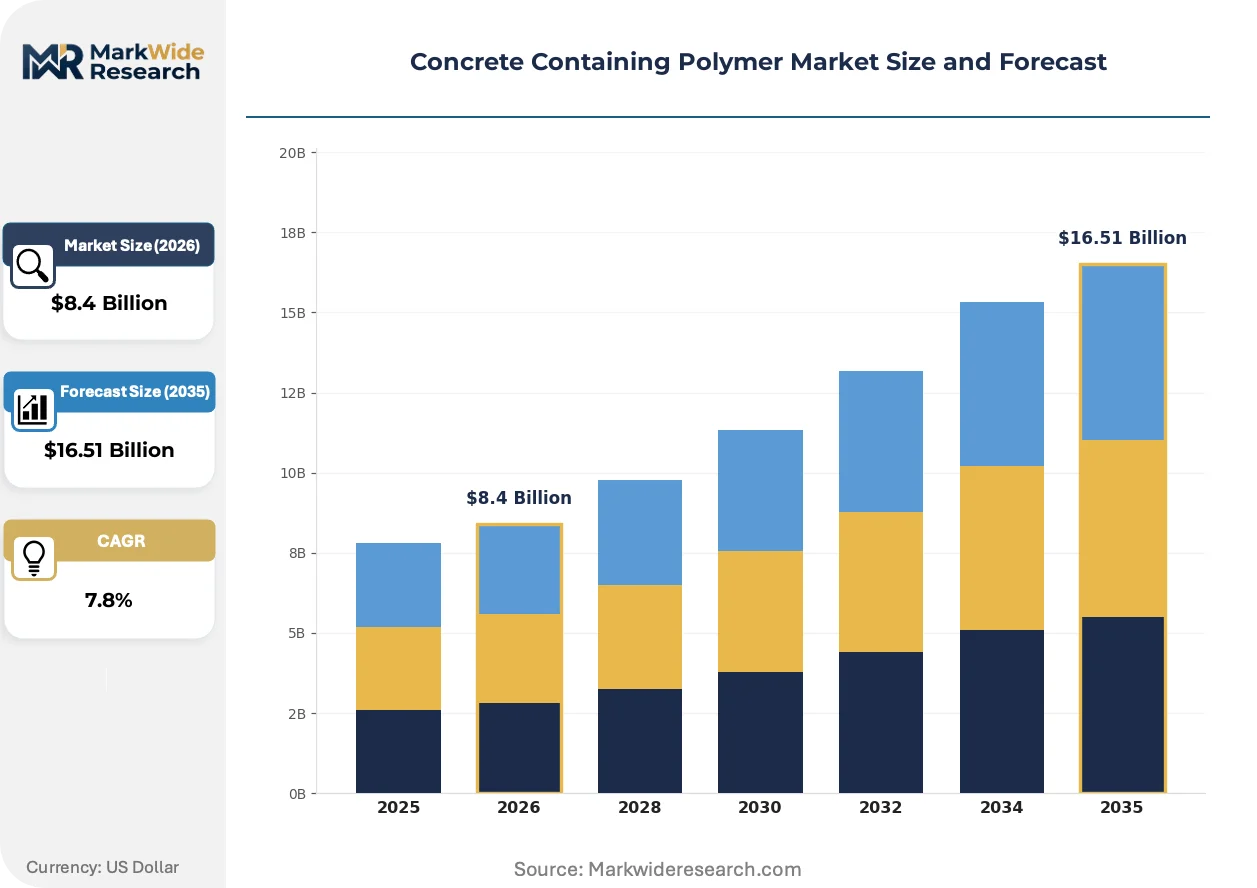
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Modified Concrete, Fiber Reinforced Concrete, Self-Compacting Concrete, High-Performance Concrete Application: Structural Applications, Pavements, Precast Elements, Underground Structures End User: Construction Companies, Real Estate Developers, Government Agencies, DIY Enthusiasts Technology: 2D Printing, Traditional Methods, Reinforcement Techniques, Eco-Friendly Binder |
| Companies Covered | BASF SE, Sika AG, Wacker Chemie AG, MAPEI S.p.A., Forte Composites Inc., Interplastic Corporation, Dudick Inc., Fosroc International Limited, ACO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Containing Polymer Market Strategic Shifts
Specification protocols are digitizing while material chemistries converge with carbon management objectives. The intersection of performance verification technology and environmental accountability is restructuring how polymer concrete qualifies for infrastructure awards.
Silane-siloxane hybrid surface treatments are displacing conventional acrylic sealers in bridge deck protection schemes. State DOT maintenance divisions facing 50-year service life targets are specifying penetrating treatments that chemically bond with substrate alkalinity. The displacement of film-forming sealers is compressing the maintenance reapplication cycle from 5-7 years to 10-15 years, altering lifecycle cost calculations in public procurement.
The EPA's evolving stormwater infrastructure resilience criteria are tightening permeability retention requirements after freeze-thaw cycling. Commercial developers in jurisdictions with municipal separate storm sewer system permits must demonstrate pavement void structure maintenance over 20-year design lives. Polymer-modified pervious concrete formulations with enhanced aggregate-paste bonding are capturing specification share in Mid-Atlantic and Pacific Northwest markets where winter maintenance chemical exposure is most severe.
Asset owners are unbundling material supply from installation warranties in large-scale rehabilitation programs. State bridge authorities are separating polymer modifier procurement from applicator selection, forcing material suppliers to certify performance independent of named installation contractors. This disintermediation is most advanced in California and Texas, where design-build delivery models have fragmented traditional single-source warranty structures.
Concrete Containing Polymer Market Segmentation
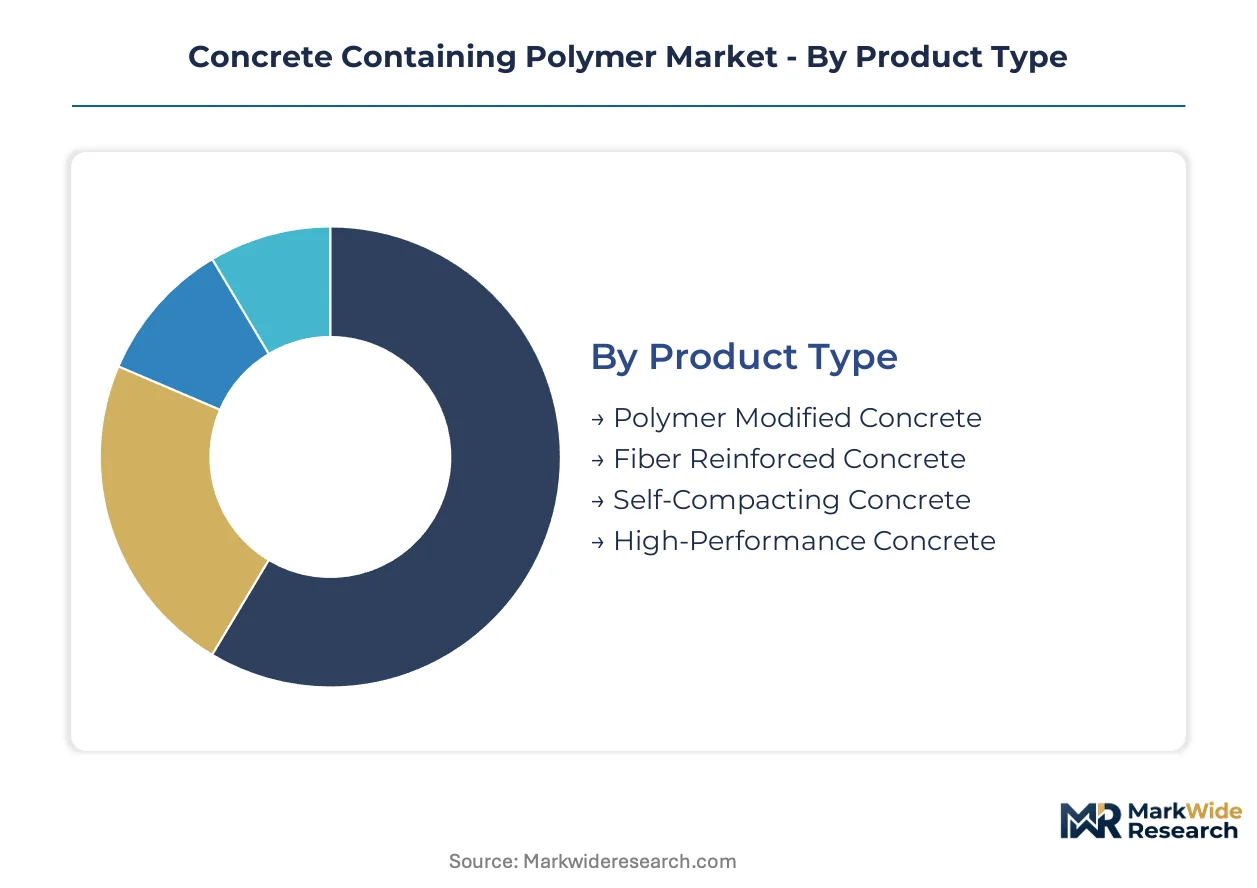
Polymer concrete specification pathways diverge sharply across regulatory jurisdictions, with ASTM C1439 compliance filtering product categories for federally aided US projects while EN 1504 standards govern European rehabilitation tenders. Understanding segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
EPA stormwater mandates and FHWA bridge rehabilitation specifications create divergent performance thresholds that reshape product qualification economics across categories.
- Polymer Modified Concrete:Portland cement matrices incorporating 5–20% latex, epoxy, or acrylic dispersions by weight of cement. Department of Transportation portfolios in Germany and the United States specify this category for chloride-contaminated bridge deck overlays where flexural strength thresholds exceed conventional concrete capabilities. Federal aid requirements cement its position as the default specification for infrastructure rehabilitation.
- Self-Compacting Concrete:Flowable polymer-modified matrices eliminating vibration requirements through tailored rheology. Precast manufacturing in Japan and labor-constrained North American markets specify this category for complex reinforcement geometries where skilled placement labor is scarce. The elimination of mechanical compaction reduces placement time and surface defect rates in architectural precast elements.
- Fiber Reinforced Concrete:Polymer-modified matrices with dispersed synthetic or steel fibers enhancing post-crack tensile capacity.
- High-Performance Concrete:Ultra-low permeability formulations targeting extreme chemical exposure environments.
Polymer Modified Concrete handles the majority of throughput; Self-Compacting Concrete is the fastest mover on share.
Application:
Cost tier differentiation separates warranty-backed structural rehabilitation from lower-specification paving installations.
- Structural Applications:Load-bearing rehabilitation of bridge decks, columns, and beams where polymer-modified overlays must achieve documented bond strength and chloride impermeability. German federal transport budgets prioritize this application category with dedicated funding lines for durable bridge deck solutions exceeding 2000 coulomb rapid chloride permeability thresholds. Performance-based specifications command premium pricing for certified compliance.
- Precast Elements:Factory-cured polymer concrete components including architectural cladding, utility vaults, and drainage structures. Japanese and North American precast producers facing skilled labor shortages specify self-compacting formulations to reduce vibration requirements and accelerate form turnover. Complex reinforcement geometries in tunnel segments and bridge girders drive specification growth.
- Pavements:Permeable polymer-modified systems for stormwater management in commercial developments.
- Underground Structures:Wastewater treatment tanks, utility tunnels, and mining infrastructure requiring chemical resistance.
Structural Applications concentrate margin through performance specifications; Precast Elements are expanding most quickly as labor constraints reshape manufacturing economics.
End User:
Customer type determines procurement sophistication, with public agencies enforcing certified applicator networks that private developers often bypass.
- Construction Companies:General and specialty contractors executing DOT bridge rehabilitation, commercial paving, and industrial flooring installations. US federal projects mandate applicator certification to manufacturer-specific protocols, compressing qualified contractor pools and extending mobilization timelines. Warranty requirements tie material selection to approved installation networks.
- Government Agencies:State DOTs, municipal bridge authorities, and federal highway administrations specifying polymer overlays for infrastructure asset management. California and Texas authorities are unbundling material supply from installation warranties, forcing material suppliers to certify performance independent of named contractors. Procurement shifts favor lowest-life-cycle-cost over lowest-bid awards.
- Real Estate Developers:Commercial and residential project sponsors specifying polymer concrete for parking structures, plaza decks, and stormwater management.
- DIY Enthusiasts:Small-scale residential repair and decorative concrete applications.
Construction Companies handle the majority of throughput; Government Agencies are gaining specification authority fastest as procurement centralizes.
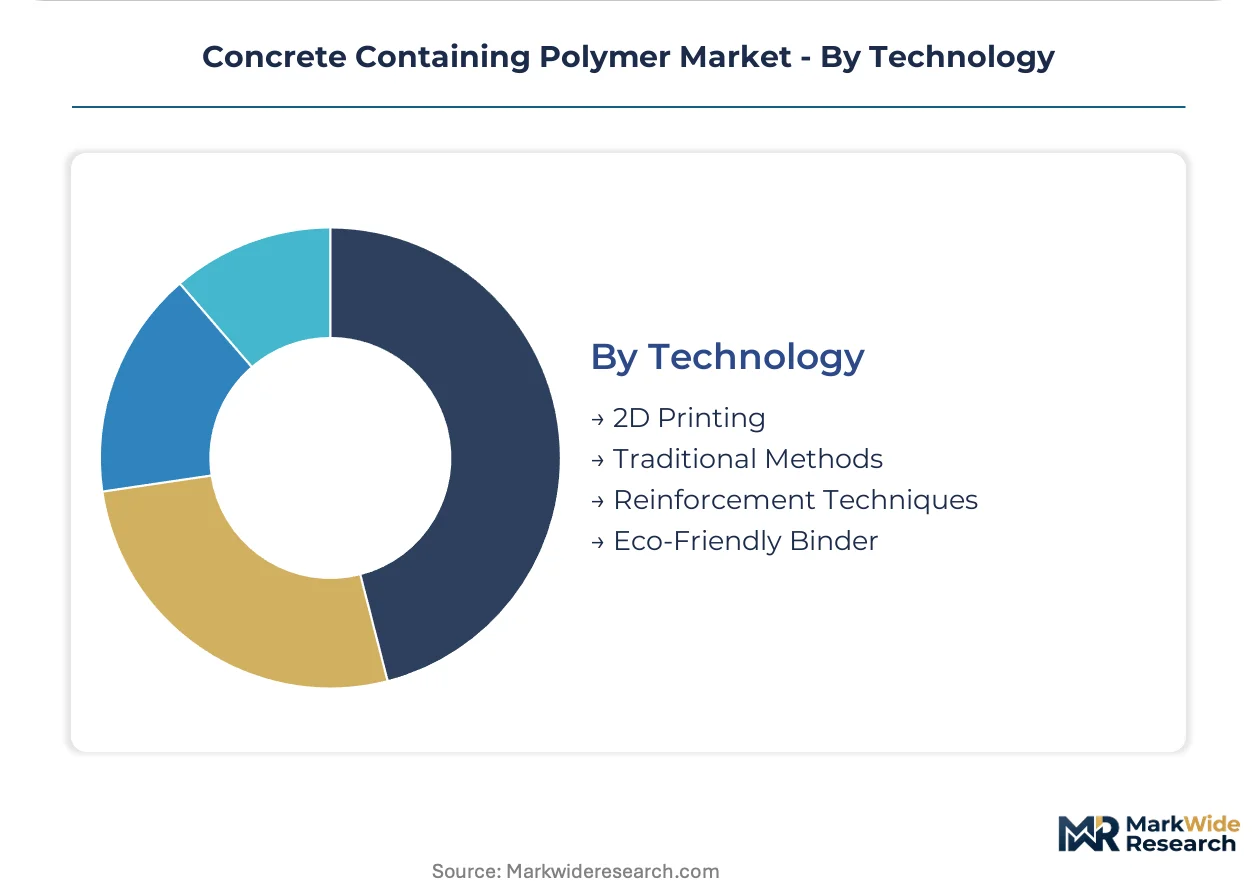
Technology:
Volume concentration favors established placement methods while emerging techniques capture niche specification pockets.
- Traditional Methods:Conventional batching, placement, finishing, and curing of polymer-modified concrete using standard ready-mix and precast infrastructure. This technology pathway dominates DOT bridge rehabilitation and commercial paving where contractor familiarity and equipment availability reduce execution risk. Decades of specification history create inertia against novel placement techniques.
- Eco-Friendly Binder:Polymer-modified systems incorporating supplementary cementitious materials, CO2 mineralization, or bio-based polymer components. Precast producers serving LEED-targeting commercial developments in North America and Europe are piloting carbon-capture curing of polymer-modified elements to combine durability enhancement with embodied carbon reduction. Municipal green procurement criteria accelerate specification in public projects.
- 2D Printing:Automated extrusion-based deposition of polymer concrete for architectural and structural elements.
- Reinforcement Techniques:Advanced fiber integration and post-tensioning methods for specialized structural applications.
Traditional Methods handle the majority of throughput; Eco-Friendly Binder is climbing the fastest as carbon accountability reshapes procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State bridge authorities and municipal stormwater managers constitute the dominant buyer archetypes, with procurement authority concentrating among DOT maintenance divisions and commercial developers facing EPA permit thresholds.
United States
Federal Highway Administration bridge rehabilitation mandates and EPA Clean Water Act enforcement drive specification volume. State DOTs in California and Texas unbundle material supply from installation warranties, fragmenting traditional procurement. Gulf Coast petrochemical corridors anchor domestic latex emulsion production for modifier supply.
Germany
Federal transport budgets prioritize durable bridge deck solutions exceeding rapid chloride permeability thresholds. EN 1504 standards govern European rehabilitation tender specifications, filtering product categories for infrastructure awards. Industrial clusters along the Rhine-Ruhr corridor concentrate polymer chemistry manufacturing for construction-grade dispersions.
China
Urban flood management investments and high-speed rail infrastructure expansion create specification pathways for polymer-modified systems. GB standards and MIIT industrial policy shape domestic qualification protocols for infrastructure materials. Yangtze River Delta manufacturing bases anchor precast element production for complex reinforcement geometries.
India
Smart Cities Mission allocations target stormwater harvesting integration with pervious concrete in Bengaluru and Chennai municipal pilots. BIS certification requirements and central government infrastructure spending reshape contractor qualification windows. Western Maharashtra industrial corridors concentrate precast manufacturing capacity for transportation infrastructure.
Japan
Seismic retrofit programs and aging bridge inventory maintenance sustain specification demand for high-performance overlays. METI energy efficiency guidelines and JIS standards govern material qualification for public works tenders. Kanto region precast producers specify self-compacting formulations to address skilled labor constraints in complex tunnel segments.
Concrete Containing Polymer Market Competitive Environment
Player mix skews toward integrated chemical conglomerates and specialized construction chemical formulators. The vendor base stratifies across three tiers: multinational polymer chemistry platforms controlling raw material consistency, regional waterproofing specialists anchoring specification positions in tunnel and bridge applications, and niche applicators capturing localized installation warranties. Competitive moves concentrate on backward integration into latex emulsion production and geographic expansion through certified applicator network development.
Among European chemical platforms, BASF SE and Sika AG occupy positions reflecting distinct strategic archetypes. BASF exemplifies integrated polymer chemistry control spanning regional batch plant networks. Sika anchors specialized anchoring and waterproofing formulation dominance in European tunnel specifications. Wacker Chemie AG sits within the silicone-polymer hybrid segment, representing flexibility retention capabilities across freeze-thaw cycling applications. These three entities illustrate how raw material control, application specialization, and hybrid chemistry innovation define competitive positioning in infrastructure-grade polymer concrete systems.
| Leading Market Players |
|---|
| BASF SE |
| Sika AG |
| Wacker Chemie AG |
| MAPEI S.p.A. |
| Forte Composites Inc. |
| Interplastic Corporation |
| Dudick Inc. |
| Fosroc International Limited |
| ACO Group |
| Others |
Value Chain & Pricing Dynamics
ISO 9001 certification protocols gate both supplier qualification and price differentiation in infrastructure-grade polymer concrete systems, compressing uncertified competitors into commodity tiers while accredited producers command performance-based premiums for documented freeze-thaw durability and chloride impermeability compliance.
Pricing Analysis
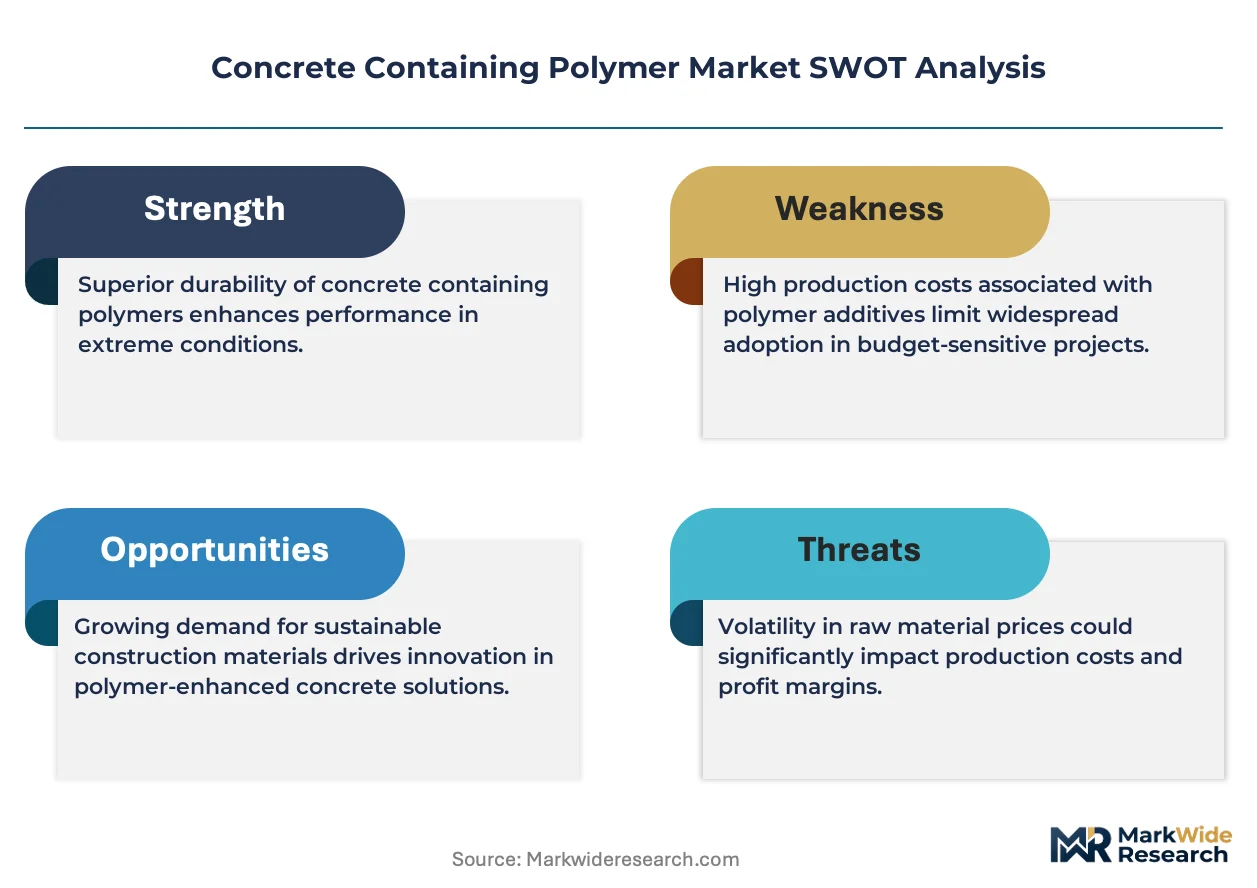
Cost-plus contracts with styrene-butadiene latex indexation dominate bridge rehabilitation procurement, transmitting petrochemical feedstock volatility directly to contractor margins. Three-tier pricing structure across certified-premium, standard-ASTM-compliant, and economy-unbranded tiers separates warranty-backed structural applications from lower-specification paving installations. Pricing pressure stems from fixed-price DOT contracts absorbing material escalation risk during latex price spikes. Government agencies exhibit lowest price sensitivity due to lifecycle-cost procurement mandates, while commercial developers face highest sensitivity from competing permeable asphalt alternatives.
Supply Chain Analysis
Strategic stockpiling of acrylic and epoxy dispersions prevails among precast manufacturers facing seasonal curing windows, while just-in-time latex delivery dominates ready-mix operations with shorter placement cycles. Supply concentrates in Germany's Rhine-Ruhr chemical corridor, China's Yangtze River Delta manufacturing bases, and US Gulf Coast petrochemical hubs. Raw material flows draw from imported Asian epoxy dispersions, domestic SBR latex emulsions, and European silicone-polymer hybrids. Single-source vulnerability concentrates in high-performance acrylic modifiers where qualified domestic suppliers number fewer than three. Distribution runs through certified applicator networks for structural warranties and direct bulk supply for precast manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from ultra-high-performance concrete and advanced composite overlays in bridge rehabilitation specifications, where competing materials threaten to displace polymer-modified systems in durability-critical applications.
For Market Incumbents: Shield specification position by deepening backward integration into captive latex emulsion production, eliminating import-dependent exposure to Buy America compliance gaps. Secure EN 1504 and ASTM C1439 certification moats against emerging hybrid-cement substitutes. Prioritize applicator training pipeline capacity to compress mobilization timelines and capture DOT maintenance division centralization.
For New Entrants and Emerging Players: Anchor in India's Smart Cities Mission stormwater harvesting pilots, where municipal corporations in Bengaluru and Chennai lack established supplier relationships for permeable polymer pavement. Target carbon-capture curing technology convergence as a specification wedge for LEED-targeting commercial developments. Pursue digital specification platform partnerships for real-time mix verification against certified performance databases.
For Investors and Strategic Acquirers: EPA stormwater infrastructure resilience mandate tightening reshapes the acquisition landscape toward specialty applicators with certified installation networks and documented 20-year permeability retention performance. Long-term viability centers on suppliers capable of bridging material chemistry with carbon accountability credentials. Watch for state-level Buy America enforcement thresholds as the signal triggering supply chain restructuring and consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Latex Emulsion Production | Captive SBR supply secures Buy America compliance for federally aided bridge projects. |
| Certified Applicator Network Expansion | Manufacturer-specific protocol training compresses DOT mobilization timelines against competitors. |
| Carbon-Capture Curing Technology Deployment | Mineralized CO2 precast elements capture LEED-specification share in commercial developments. |
| Digital Specification Platform Partnership | Blockchain-anchored batch records enable real-time warranty enforcement for DOT maintenance divisions. |
| Silane-Siloxane Hybrid Formulation Development | Penetrating surface treatments displace acrylic sealers in 50-year service life bridge protection schemes. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, SEC 10-K filings, AASHTO specification databases, and EN 1504 compliance registries. Interviews with DOT maintenance division chiefs, precast plant managers, polymer chemistry procurement leads, and certified applicator network directors inform demand-side validation. Bottom-up project pipeline analysis triangulates against top-down chemical consumption estimates from regional batch plant surveys.
Segmentation dimensions modeled span product type, application category, end-user procurement sophistication, and technology pathway across the projection horizon. CAGRs derive from elasticity-adjusted volume projections tied to federal transport budget allocations and EPA enforcement intensity indices. Industry-specific inputs include chloride permeability threshold adoption curves and skilled labor constraint indices in precast manufacturing.
Decision-makers should treat outputs as directional under assumptions of sustained federal infrastructure spending and stable petrochemical feedstock availability; material deviation would warrant model refresh. Revision becomes warranted when Buy America domestic content thresholds cross enforcement intensity thresholds or when carbon-curing technology achieves cost parity with conventional curing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Novolac Resins Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Global Linear Low Density Polyethylene Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Global Thermosetting Polymer Market