
 Ethylene Tetrafluoroethylene (ETFE) Market | 2026-2036
Ethylene Tetrafluoroethylene (ETFE) Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Tetrafluoroethylene (ETFE) Market Analysis
Glass curtain walls in high-profile infrastructure is recalibrating project economics toward ETFE membrane systems. Daikin Industries leverages captive fluorochemical supply chains to stabilize resin feedstock costs across Asian fabrication centers. The Chemours Company anchors North American demand through specification-grade film production for stadium and transit architects. Solvay SA specializes in high-purity ETFE grades that sustain premium positioning for semiconductor fluid handling applications.
Ethylene tetrafluoroethylene is a fluoropolymer copolymer of ethylene and tetrafluoroethylene, typically processed by melt extrusion at temperatures between 280°C and 340°C, yielding a material with exceptional chemical inertness, UV transparency, and elongation at break exceeding 400%. Its primary industrial purpose centers on lightweight, durable barrier applications where traditional glass or metal impose unacceptable weight or corrosion penalties. Film applications dominate value capture given architectural scale projects in sports and transportation infrastructure, while tubing segments serve semiconductor and pharmaceutical fluid systems where extractable limits are stringent. Coating applications occupy a mature niche protecting chemical processing equipment, with margin pools shifting toward application-specific formulations rather than commodity resin sales.
REACH registration requirements and the EU F-Gas Regulation constrain fluoropolymer production emissions, compelling reformulation of processing aids and tighter volatile organic compound controls at European compounding sites. The US EPA oversees fluorinated chemical discharge under TSCA Section 5, while China's MEE enforces dual carbon goals that raise energy costs for ETFE resin polymerization. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across multiple jurisdictions, as regulatory reclassification of fluoropolymers could abruptly alter market access conditions and capital allocation priorities for new production capacity.
Market Dynamics
Architects and structural engineers are reweighting material specifications away from glass toward ETFE pneumatic systems, driven by seismic load reductions and envelope thermal performance mandates tightening across German building codes and California energy standards.
Growth Catalysts
- EU F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon blowing agents for insulation foams redirect specification toward ETFE's solvent-free extrusion processes for building envelopes.
- Stadium infrastructure retrofit cycles:Aging European sports venues require transparent roof replacements that ETFE cushions deliver without structural reinforcement of existing steel.
- Semiconductor fab construction:Fluid handling systems in Taiwan and South Korea fabs specify high-purity ETFE tubing for aggressive chemical transport with sub-ppb extractable limits.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar feedstock for tetrafluoroethylene monomer concentrates in Chinese and Mexican mining districts, exposing resin producers to export quota volatility.
- Per- and polyfluoroalkyl substance scrutiny:ECHA's restriction roadmap and US EPA TSCA Section 5 scrutiny on long-chain fluoropolymers create regulatory overhang on ETFE's fluoropolymer classification.
- Glass-glue hybrid systems:Structural silicone-glazed curtain walls with laminated safety glass compete on fire rating performance that ETFE membranes cannot match without secondary suppression systems.
Strategic Opportunities
- Indian smart city transit hubs:Metro station atrium projects in Bengaluru and Mumbai remain underpenetrated by membrane roofing, presenting first-mover specification potential for ETFE cushion systems.
- Agrivoltaic canopy integration:ETFE's UV-selective transparency converges with photovoltaic module cooling requirements, opening dual-use agricultural energy infrastructure applications.
- EU Green Deal renovation wave:Building performance standards under the Energy Performance of Buildings Directive mandate envelope upgrades that ETFE retrofits can deliver with minimal structural intervention.
Industry Challenges
- Membrane installation technician scarcity:Pneumatic cushion erection requires specialized hot-air welding and cable net tensioning skills concentrated among German and Swiss contracting firms, limiting project bandwidth.
- Multi-jurisdiction chemical compliance:REACH registration dossiers, US EPA Significant New Use Rules, and China's MEE pollutant discharge permits demand parallel regulatory staffing for ETFE compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Tetrafluoroethylene (ETFE) Market |
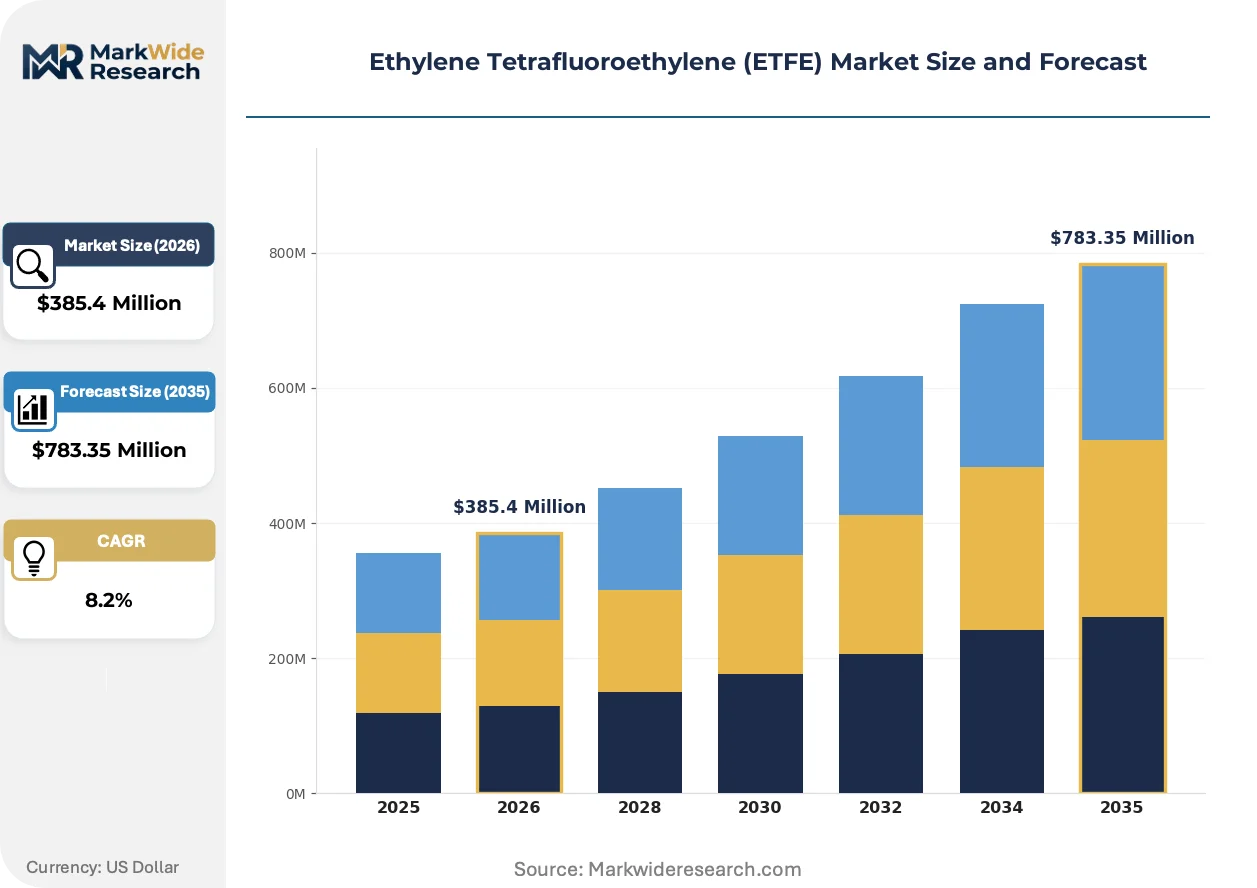
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $783.35 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Coatings, Tubing, Sheets End User: Aerospace, Construction, Electrical, Automotive Application: Insulation, Fluid Handling, Surface Protection, Structural Installation: Onshore, Offshore, Residential, Commercial |
| Companies Covered | Daikin Industries Ltd, The Chemours Company, DIC Corporation, 3M, AGC Inc., China Lumena New Materials Corp, Solvay SA, Hubei Everflon Polymer Co Ltd, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Tetrafluoroethylene (ETFE) Market Emerging Trajectories
Material science advances and regulatory chemistry are compressing traditional specification cycles, forcing ETFE producers to demonstrate compliance and performance simultaneously rather than sequentially.
Multilayer ETFE film systems with embedded low-emissivity coatings are decentralizing thermal performance optimization away from bulk insulation toward surface-engineered membranes. Airport terminal designers in Doha and Singapore specify these stacks to achieve U-values previously requiring triple glazing. The technology is decentralizing HVAC load distribution across large-span structures by enabling passive climate modulation through envelope material selection alone.
Germany's KBA and federal building authorities are incorporating fluoropolymer emission thresholds into public procurement standards for transportation infrastructure. Manufacturers must now submit third-party verified volatile organic compound test data for ETFE cushion components. German stadium projects already subject to REACH downstream user obligations face additional federal-layer compliance, compressing vendor qualification timelines by 40 percent.
Design-build contracting consortia are displacing traditional architect-bid-build procurement for ETFE envelope projects. Contractors in the United Arab Emirates and Australia now bundle membrane supply, steel cable net engineering, and installation under single-source responsibility. This consolidation shifts specification authority from independent architects toward integrated delivery teams, concentrating vendor relationships with firms capable of warranting complete envelope performance.
Ethylene Tetrafluoroethylene (ETFE) Market Segmentation
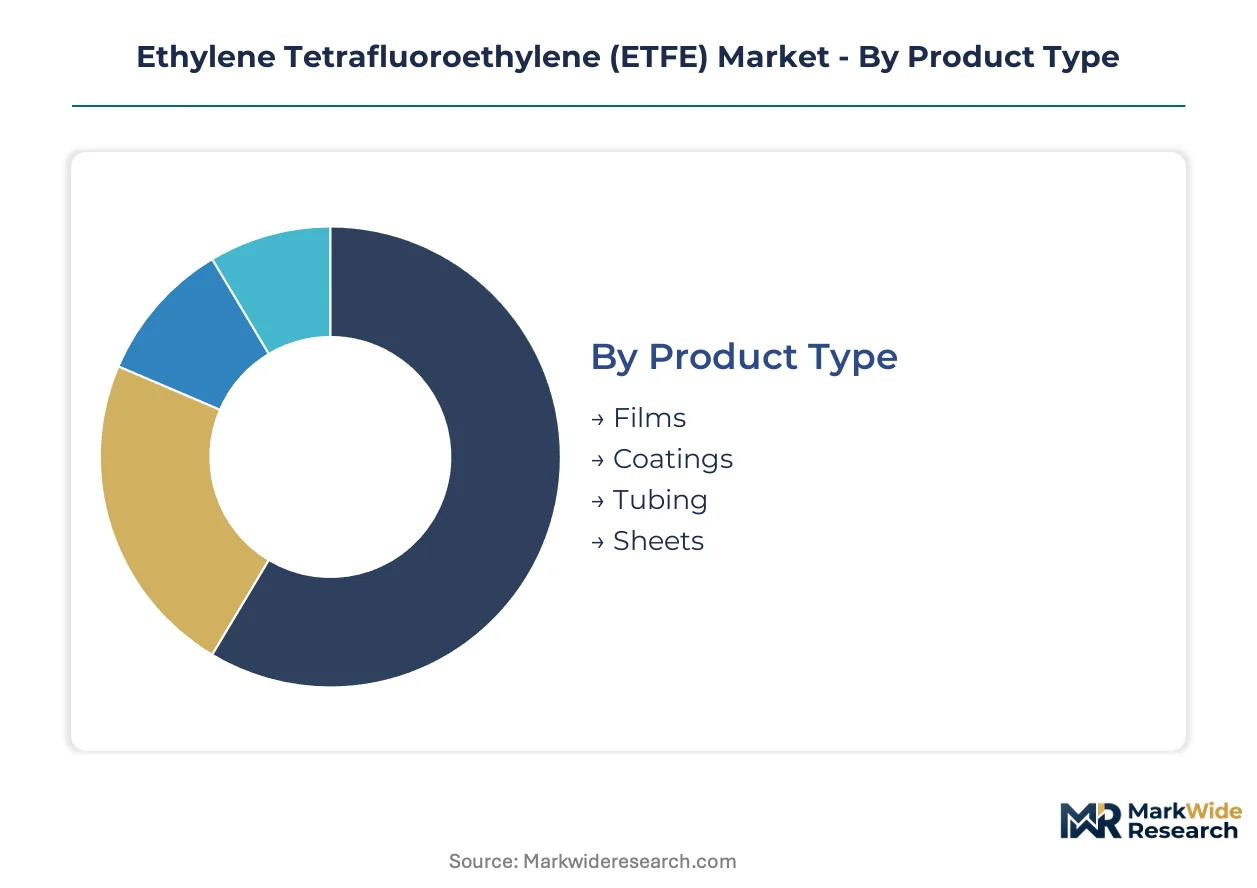
Architects and engineers select ETFE grades based on load-bearing requirements, chemical exposure profiles, and installation constraints. Each segmentation dimension reveals distinct margin structures and specification authority patterns across project types.
Product Type:
Replacement cycles vary sharply across product formats, with architectural film systems requiring 25-30 year refresh intervals while industrial coatings face 10-15 year maintenance schedules.
- Films:Extruded membranes ranging from 100-300 microns serve pneumatic cushion systems for stadiums and airport terminals. German building codes and California energy standards now specify these for seismic load reduction in large-span structures. Demand concentrates in transportation infrastructure where ETFE's 400% elongation accommodates thermal expansion without structural reinforcement.
- Tubing:High-purity extrusions with sub-ppb extractable limits transport aggressive chemicals in semiconductor fabs across Taiwan and South Korea. REACH registration dossiers and US EPA TSCA Section 5 scrutiny force compounders to maintain parallel compliance staffing for these premium grades.
- Coatings:Powder and liquid formulations protect chemical processing equipment from corrosive attack.
- Sheets:Compression-molded plates serve gasket and lining applications in industrial maintenance.
Films sit at the top of the volume ranking, with tubing climbing the fastest.
End User:
Customer procurement patterns diverge between specification-driven sectors where architects control material selection and cost-optimized industries where purchasing departments dominate.
- Construction:Design-build consortia in the United Arab Emirates and Australia now bundle membrane supply with steel cable net engineering under single-source contracts. EU Green Deal renovation wave mandates under the Energy Performance of Buildings Directive favor ETFE retrofits with minimal structural intervention.
- Aerospace:Lightweight wire insulation and fuel system components exploit ETFE's radiation resistance and low smoke toxicity. FAA certification timelines and material qualification protocols stretch 18-24 months, locking in supplier relationships.
- Electrical:High-voltage cable insulation leverages ETFE's dielectric strength and thermal stability.
- Automotive:Underhood wire harness coatings resist engine bay fluids and temperature cycling.
Construction commands the largest revenue pool, while aerospace delivers the steepest expansion trajectory.
Application:
Functional requirements determine resin grade selection, with purity specifications tightening fastest in semiconductor-adjacent segments.
- Structural:Pneumatic cushion envelopes for sports venues and transit hubs exploit ETFE's tensile strength-to-weight ratio. Allianz Arena and Berlin Hauptbahnof demonstrate mature specification precedent that architects reference for new projects.
- Fluid Handling:Aggressive chemical transport systems in pharmaceutical and semiconductor manufacturing demand high-purity grades with validated extractable profiles. ECHA's restriction roadmap on per- and polyfluoroalkyl substances creates regulatory overhang despite ETFE's polymer exemption status.
- Insulation:Electrical and thermal barrier applications exploit ETFE's dielectric properties.
- Surface Protection:Chemical-resistant coatings extend equipment service life in corrosive environments.
Structural applications dominate installed volume, with fluid handling gaining share fastest.
Installation:
Site conditions dictate cushion geometry, welding protocols, and maintenance access planning.
- Commercial:Airport terminals and retail atriums specify ETFE for daylight harvesting and HVAC load reduction. Singapore and Doha projects deploy multilayer film stacks with low-emissivity coatings to achieve U-values previously requiring triple glazing.
- Onshore:Ground-based industrial facilities face fewer environmental constraints than marine installations.
- Offshore:Corrosive salt spray environments test coating adhesion and membrane tensioning durability.
- Residential:Limited penetration due to cost premiums and specialized installer scarcity.
Commercial installations lead by project count, with onshore industrial expanding most quickly.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specification standards for ETFE pneumatic cushions at the Allianz Arena and Berlin Hauptbahnhof established architectural precedent that engineers reference across infrastructure projects worldwide. The report traces demand concentration across five countries where construction codes, semiconductor fab investment, and regulatory chemistry intersect.
United States
California energy standards and seismic load mandates drive specification toward ETFE membrane systems for large-span structures. The US EPA oversees fluorinated chemical discharge under TSCA Section 5, tightening volatile organic compound controls at compounding sites. Stadium retrofit projects in Los Angeles and transit terminal expansions in the Pacific Northwest deploy pneumatic cushions to reduce structural steel requirements.
Germany
KBA and federal building authorities incorporate fluoropolymer emission thresholds into public procurement standards for transportation infrastructure. REACH registration dossiers demand third-party verified volatile organic compound test data for ETFE cushion components. Munich and Berlin remain the dominant specification clusters, with the Allianz Arena demonstrating mature precedent for stadium architects.
China
MEE enforces dual carbon goals that raise energy costs for ETFE resin polymerization while expanding semiconductor fab construction drives tubing demand. Export quota volatility on acid-grade fluorspar feedstock concentrates risk for tetrafluoroethylene monomer supply. Yangtze River Delta fabrication centers process membrane systems for domestic airport terminal projects.
Japan
METI industrial standards and JIS certification requirements shape ETFE grade selection for high-voltage cable insulation and aerospace wire applications. Fluorochemical supply chain integration stabilizes resin feedstock costs across Asian fabrication networks. Osaka-based engineering consortia bundle membrane supply with steel cable net installation for regional stadium projects.
United Arab Emirates
Design-build contracting consortia bundle ETFE envelope performance under single-source responsibility for airport terminal expansions in Dubai and Abu Dhabi. MOHAP oversees building material safety standards while federal procurement favors membrane systems for HVAC load reduction in large-span structures. Doha-adjacent specification patterns influence procurement norms across Gulf Cooperation Council infrastructure markets.
Ethylene Tetrafluoroethylene (ETFE) Market Vendor Landscape
Global majors compete with regional champions across fluorochemical supply chain integration and specification-grade film production. The vendor base separates into captive resin producers, independent compounders, and application-specific fabricators with distinct margin structures. Three archetypes dominate: integrated chemical conglomerates with upstream fluorine access, specialized fluoropolymer houses, and regional membrane engineering contractors. Competitive moves concentrate on backward integration into acid-grade fluorspar sourcing and strategic partnerships with design-build consortia.
Among Japanese integrated chemical conglomerates, Daikin Industries exemplifies captive fluorochemical supply chain configuration. The Chemours Company anchors North American specification-grade film production for stadium and transit architects. Solvay SA occupies a position within the European high-purity grade segment for semiconductor fluid handling applications.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| The Chemours Company |
| DIC Corporation |
| 3M |
| AGC Inc. |
| China Lumena New Materials Corp |
| Solvay SA |
| Hubei Everflon Polymer Co Ltd |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Acid-grade fluorspar feedstock costs cascade through ETFE resin production into tiered membrane pricing, with Mexican and Chinese mining quota volatility transmitting directly to pneumatic cushion project quotes for German stadium architects and Gulf airport terminals.
Pricing Analysis
Input-cost pass-through from tetrafluoroethylene monomer supply anchors ETFE pricing dynamics, with resin producers indexing film quotes to fluorspar export quota announcements. Three-tier pricing structure across specification-grade, industrial-standard, and commodity resin levels separates semiconductor fluid-handling tubing from architectural membrane systems. Cost compression in standard-grade film is intensifying because Chinese fabrication centers expand extrusion capacity. Construction procurement teams exhibit highest price sensitivity, while semiconductor fabs accept premium positioning for validated extractable profiles.
Supply Chain Analysis
Dual-sourcing requirements from REACH-registered compounders and TSCA-compliant fabricators mandate parallel qualification of resin suppliers across German, Chinese, and Japanese production sites. ETFE supply draws from acid-grade fluorspar concentrate in Mexico and China, tetrafluoroethylene monomer polymerization in Japan and Germany, and film extrusion across Yangtze River Delta fabrication centers. Single-source vulnerability concentrates in Chinese fluorspar export quotas. Distribution runs through design-build consortia bundling membrane supply with cable-net installation for stadium and airport terminal projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ETFE has entered a late-cycle quality phase where specification-grade purity and installation capability separate winners from commodity resin suppliers, as semiconductor fabs and German transit authorities tighten extractable limits and emission thresholds.
For Market Incumbents: Deploy captive fluorochemical supply chains to stabilize feedstock costs against Mexican and Chinese fluorspar quota volatility. Anchor specification relationships with design-build consortia in the United Arab Emirates and Australia to lock out independent compounders. Counter glass-glue hybrid curtain wall substitutes by embedding low-emissivity coating technology into multilayer membrane stacks.
For New Entrants and Emerging Players: Launch via regional membrane engineering partnerships in Indian smart city transit hubs where ETFE penetration remains minimal. Target agrivoltaic canopy integration as a dual-use agricultural energy infrastructure white space. Qualify high-purity tubing grades for Taiwan and South Korea semiconductor fab construction cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration costs and dual-carbon energy pricing eliminate independent compounders without backward fluorspar access. Five-to-ten year viability favors integrated fluorochemical conglomerates over standalone resin producers. Watch ECHA's per- and polyfluoroalkyl substance restriction roadmap as the signal for regulatory reclassification risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid-Grade Fluorspar | Captive Mexican and Chinese mining access insulates resin producers from export quota volatility. |
| Design-Build Consortium Partnerships | Single-source envelope warranties in UAE and Australia concentrate specification authority with integrated vendors. |
| Multilayer Low-Emissivity Film Development | Singapore and Doha airport terminals achieve triple-glazing U-values without structural weight penalties. |
| High-Purity Tubing Certification Investment | Taiwan and South Korea semiconductor fabs demand sub-ppb extractable validation for aggressive chemical transport. |
| Agrivoltaic Canopy Application Engineering | UV-selective ETFE transparency converges with photovoltaic cooling requirements in dual-use agricultural infrastructure. |
Methodological Framework
Bottom-up construction and semiconductor demand modeling reconciled against top-down fluoropolymer resin production tracking forms the analytical core of this study. Primary interviews with membrane installation contractors, stadium project architects, semiconductor fab procurement managers, and chemical processing equipment engineers combined with secondary validation from REACH registration dossiers, US EPA TSCA Section 5 filings, customs trade data, and SEC 10-K disclosures from listed fluorochemical producers. Triangulation across these sources calibrated volume estimates and specification-grade pricing tiers.
Input-output matrices mapped acid-grade fluorspar supply through tetrafluoroethylene monomer polymerization to extruded film and tubing output across the projection horizon. Segmentation dimensions modeled include product format, end-use industry, installation type, and regional regulatory cluster. CAGRs derived from trend extrapolation of specification rates in German building codes and semiconductor fab investment cycles, cross-checked against historical ETFE penetration in stadium retrofit projects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt per- and polyfluoroalkyl substance regulatory reclassification or Chinese fluorspar export quota disruption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
Global Thermosetting Polymer Market