
 Petroleum Resins Market | 2026-2036
Petroleum Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Petroleum Resins Market Intelligence
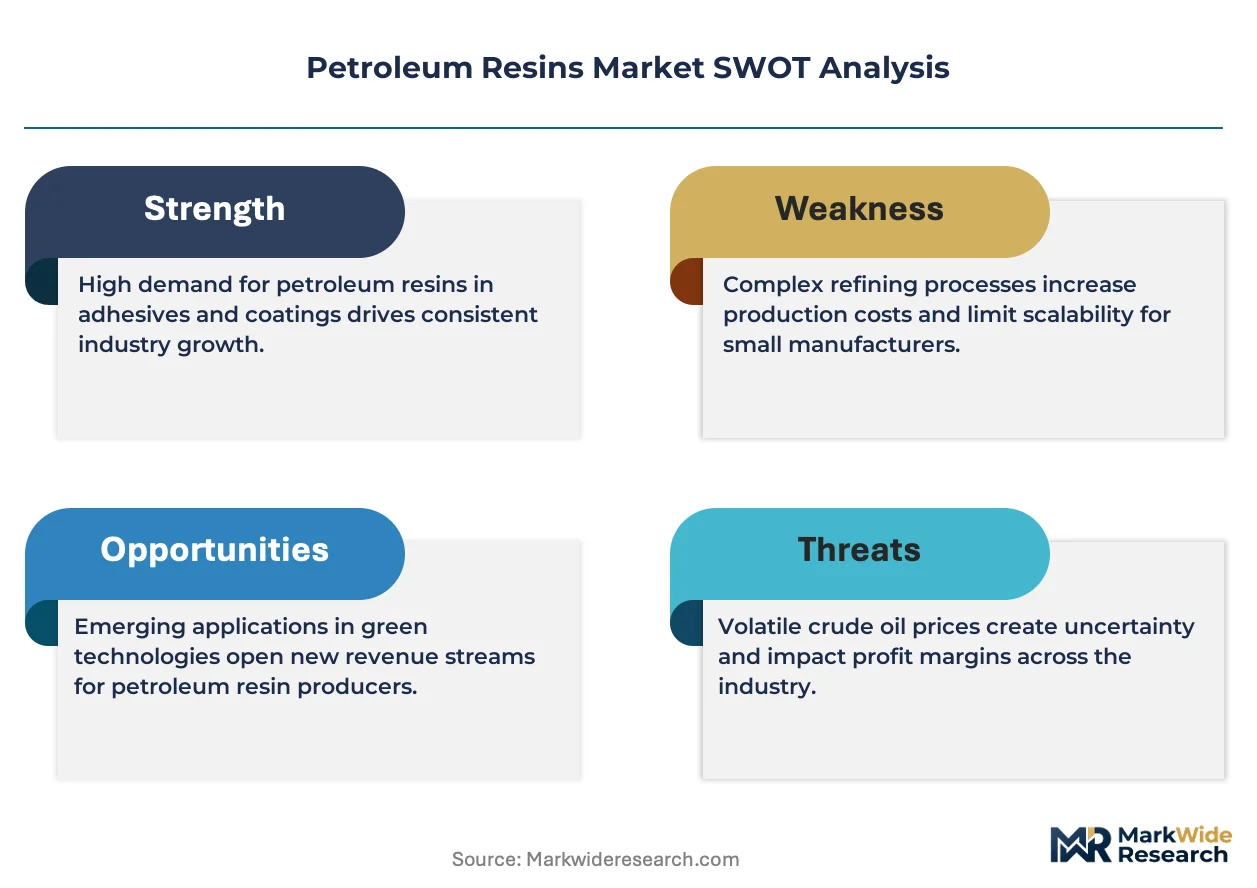
Asset-light toll manufacturing partnerships is reconfiguring competitive entry barriers for mid-scale producers in the petroleum resins sector. ExxonMobil Corporation leverages backward integration into refinery feedstocks to sustain margin stability across cyclical crude swings. Eastman Chemical Company anchors its position through specialized hydrogenated hydrocarbon resin technology for premium adhesive grades. Arakawa Chemical Industries Ltd. differentiates via long-standing channel control in Asian rosin-modified resin blends.
Petroleum resins comprise thermoplastic oligomers synthesized from C5 aliphatic, C9 aromatic, or DCPD cycloaliphatic petroleum distillate fractions, typically exhibiting softening points between 90°C and 140°C and serving primarily as tackifiers, binders, and performance enhancers in formulated products. Aliphatic C5 resins dominate volume throughput in pressure-sensitive adhesive applications where balanced tack and peel strength command stable margin pools. Aromatic C9 resins occupy mature, price-sensitive segments in rubber compounding and low-grade coatings, while modified hydrogenated grades capture accelerated growth in food-contact packaging and electronic encapsulants demanding low color and oxidative stability.
EPA regulations on hazardous air pollutant emissions from coating operations constrain solvent-borne formulation choices and redirect demand toward compliant hot-melt systems incorporating petroleum resin tackifiers. REACH registration requirements and RoHS substance restrictions in Europe shape product migration patterns toward hydrogenated and purified resin grades with documented substance safety profiles. Stakeholders must monitor feedstock volatility from refinery operating rate decisions and assess captive hydrogenation capacity as a determinant of participation in higher-margin specialty segments.
Market Dynamics
Hot-melt adhesive formulations in packaging applications are compressing solvent-borne alternatives and concentrating petroleum resin demand around hydrogenated C5 and C9 grades with compliant VOC profiles. EPA hazardous air pollutant rules and China's GB standards are forcing simultaneous reformulation across North American and Asian coating operations.
Growth Catalysts
- EPA HAP regulations:Emission controls on coating operations redirect formulation demand toward hot-melt systems incorporating petroleum resin tackifiers, expanding compliant-grade resin offtake.
- India infrastructure spending:Road marking, construction adhesives, and protective coatings for new transport corridors absorb growing volumes of C9 aromatic resins.
- Hydrogenation technology maturation:Advances in selective hydrogenation enable water-white resin production for food-contact and electronic encapsulant applications.
Market Restraints
- Crude-linked feedstock volatility:C5 and C9 stream availability tracks refinery operating rates and naphtha cracking economics, compressing margin predictability for non-integrated producers.
- Southeast Asian supply concentration:A significant share of hydrogenated specialty capacity clusters in Japan and South Korea, creating geographic dependency for premium-grade procurement.
- Bio-based tackifier substitution:Rosin ester and terpene resin alternatives capture niche share in pressure-sensitive adhesive applications sensitive to renewable content claims.
Strategic Opportunities
- India domestic production gap:Import-dependent regional supply creates white space for local C5/C9 fractionation and resin finishing investments.
- EU Green Deal chemical transition:Sustainability taxonomy incentives favor hydrogenated resins with documented carbon intensity profiles over conventional aromatic grades.
- E-commerce corrugated packaging:Tape and label adhesive consumption for box sealing is accelerating faster than GDP in North American and European logistics hubs.
Industry Challenges
- REACH registration timelines:Extended substance evaluation periods for novel hydrogenated resin chemistries delay European market entry and tie up regulatory capital.
- Hydrogen supply security:Captive hydrogenation capacity requires reliable hydrogen offtake agreements or on-site electrolysis investment, raising capital intensity for specialty-grade participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Petroleum Resins Market |
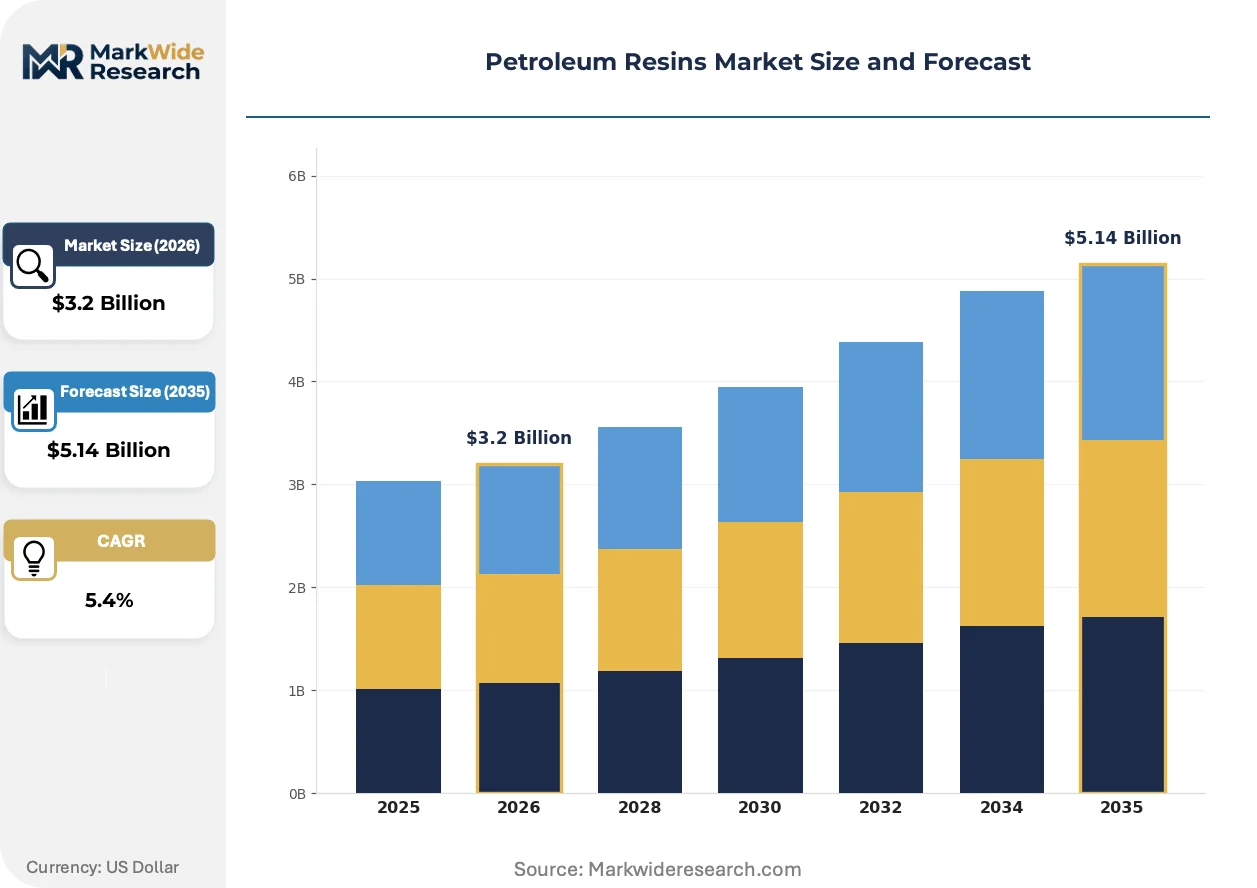
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic, Aromatic, Cycloaliphatic, Modified Application: Coatings, Adhesives, Inks, Sealants End User: Construction, Automotive, Packaging, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | ExxonMobil Corporation, Eastman Chemical Company, Arakawa Chemical Industries Ltd., Kolon Industries Inc., Neville Chemical Company, Lesco Chemical Limited, Synthomer PLC, Henan Anglxxon Chemical Co. Ltd., INNOVA (Tianjin) Chemical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Petroleum Resins Market Strategic Shifts & Innovations
Digital formulation platforms and predictive compatibility modeling are compressing product development cycles. Regulatory pressure on volatile emissions is simultaneously pulling hydrogenated grades into premium segments and pushing conventional aromatic resins toward commoditization.
Advanced molecular simulation software is virtualizing the traditional trial-and-error approach to tackifier-resin compatibility testing. Adhesive formulators at major tape and label manufacturers now screen petroleum resin candidates through in-silico polymer interaction modeling before physical validation. This compression of R&D iteration is enabling faster product line refreshes and reducing obsolete inventory risk.
China's GB standards for volatile organic compound emissions in coatings are tightening formulation requirements and disqualifying conventional solvent-borne systems from state procurement tenders. Domestic resin producers are responding with accelerated hydrogenation capacity additions and partnerships with Korean technology licensors. The regulatory friction is most acute in architectural coatings and automotive refinish segments serving state-owned construction and transport fleets.
Specification-driven procurement is consolidating buying power among multinational adhesive formulators who now demand batch-level certification data and carbon footprint documentation. Distributors serving mid-scale compounders are losing share to direct manufacturer relationships with integrated resin suppliers. This channel compression is most visible in European pressure-sensitive adhesive markets where sustainability scoring determines supplier qualification.
Petroleum Resins Market Segmentation
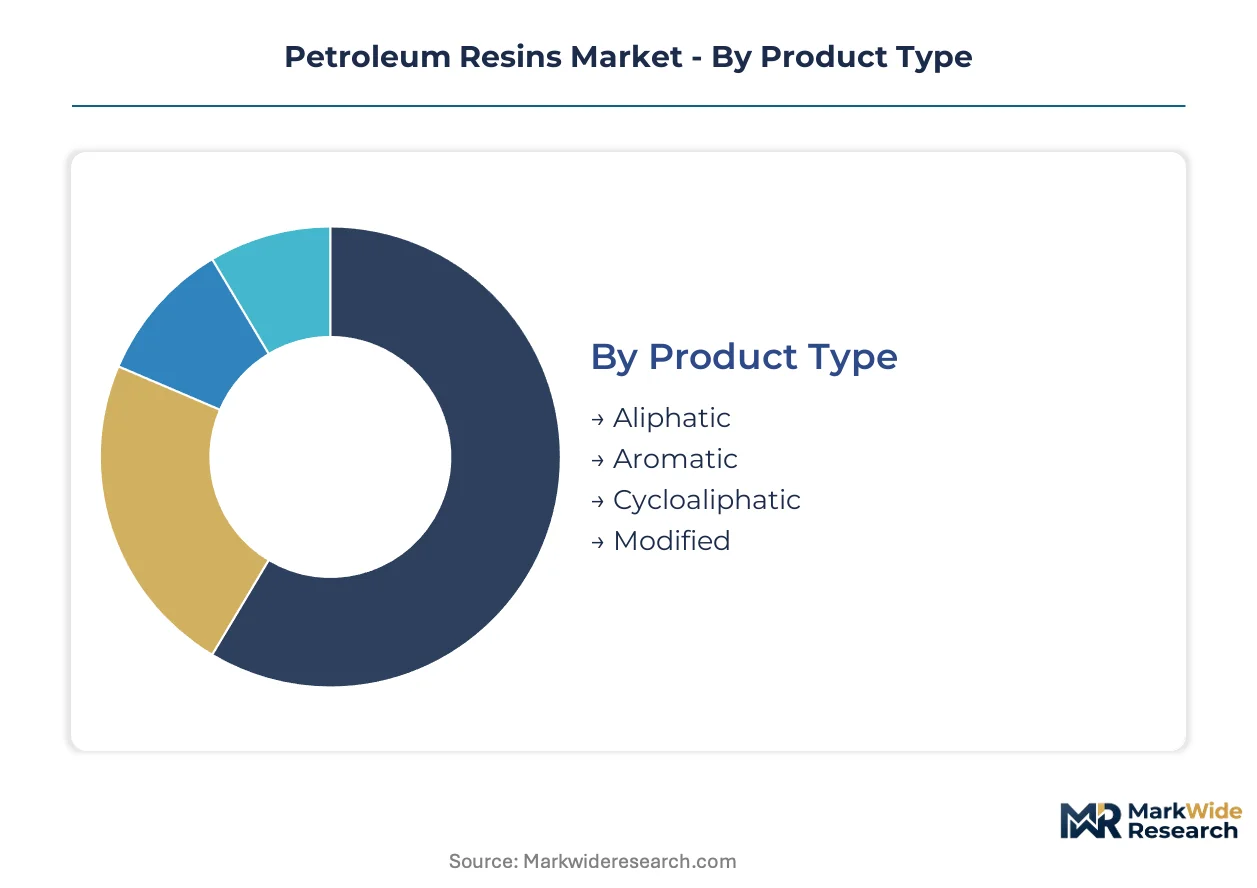
Petroleum resin segmentation reveals divergent margin profiles and technical requirements across product chemistry and end-use application. Understanding where formulation cycles compress versus where specification lock-in persists enables targeted capacity allocation and partnership prioritization.
Product Type:
Aliphatic C5 resins turn inventory fastest in pressure-sensitive adhesive formulations, while hydrogenated specialty grades tie up working capital through extended qualification timelines with food-contact and electronics customers.
- Aliphatic:C5 aliphatic resins deliver balanced tack and peel adhesion through controlled molecular weight distribution. Demand concentrates in North American tape and label manufacturing where ExxonMobil and Eastman anchor supply relationships with direct technical service support.
- Aromatic:C9 aromatic resins operate on commoditized pricing in rubber compounding and industrial coatings. Indian road marking and construction adhesive applications absorb expanding volumes as infrastructure spending accelerates domestic offtake.
- Cycloaliphatic:DCPD-based resins serve specialized applications requiring thermal stability and low color.
- Modified:Hydrogenated and esterified variants command premium positioning in regulatory-sensitive segments.
Aliphatic resins dominate installed base. Modified grades are where expansion concentrates.
Application:
Cost tier stratification separates formulation-grade procurement: hot-melt adhesives command integrated supply relationships, while solvent-borne coatings retreat toward spot purchasing.
- Adhesives:Hot-melt formulations in corrugated packaging and e-commerce logistics drive fastest volume growth. EPA hazardous air pollutant regulations and China's GB VOC standards simultaneously compress solvent-borne alternatives and redirect specification demand toward compliant hydrogenated tackifiers.
- Coatings:Architectural and automotive refinish segments face reformulation pressure from emission controls. European REACH registration requirements and substance restrictions favor purified resin grades with documented safety profiles over conventional aromatic alternatives.
- Inks:Publication and packaging ink applications require specific solubility and gloss characteristics.
- Sealants:Construction and automotive sealing applications demand elastic recovery and weathering resistance.
Adhesives command the steepest expansion trajectory. Coatings retain the largest incumbent volume position.
End User:
Customer type determines procurement modality: multinational packaging formulators demand batch certification and carbon documentation, while regional construction compounders prioritize availability and credit terms.
- Packaging:E-commerce corrugated box sealing and label adhesives accelerate faster than GDP in logistics hubs. Direct manufacturer relationships are displacing distributor intermediaries as sustainability scoring determines supplier qualification.
- Construction:Road marking, flooring adhesives, and protective coatings for transport corridors absorb C9 aromatic resin volumes. India's import-dependent supply creates white space for domestic fractionation and finishing investments.
- Automotive:Tire compounding and interior assembly adhesives require consistent quality and thermal stability.
- Electronics:Encapsulant and potting compound applications demand water-white color and oxidative stability achievable only through selective hydrogenation technology.
Packaging leads volume growth acceleration. Construction maintains the broadest geographic footprint.
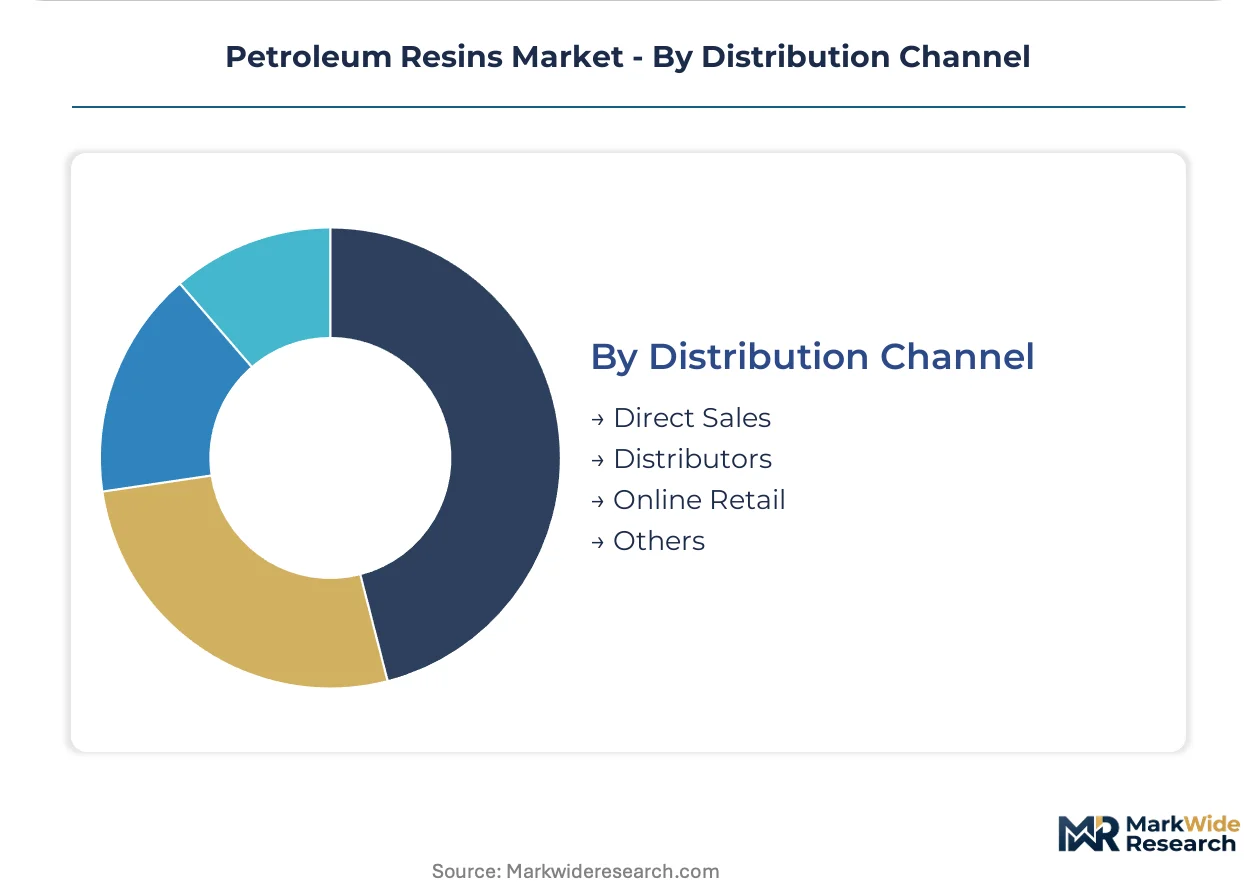
Distribution Channel:
Supply concentration in Japan and South Korean hydrogenated specialty capacity shapes channel access for premium grades, while commoditized C9 resins flow through fragmented distributor networks.
- Direct Sales:Integrated resin suppliers cultivate direct relationships with multinational adhesive formulators. Specification-driven procurement consolidates buying power and demands batch-level certification data that distributors cannot reliably provide.
- Distributors:Mid-scale compounders in fragmented regional markets depend on distributor inventory and technical support. Channel compression is most visible in European pressure-sensitive adhesive markets where sustainability scoring determines supplier qualification.
- Online Retail:Emerging channel for standardized grades and small-lot procurement.
- Others:Agent-based and toll-manufacturing arrangements for specialized applications.
Direct sales capture premium-grade value. Distributors retain commodity-grade reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational adhesive formulators concentrate procurement power in Germany, China, Japan, and India, while regional compounders in Brazil and Mexico access supply through distributor intermediaries. EPA hazardous air pollutant rules, China's GB VOC standards, and EU REACH registration requirements create divergent compliance costs across manufacturing locations. Local hydrogenation capacity and refinery feedstock access determine which geographies capture premium-grade resin value.
United States
Corrugated packaging demand from e-commerce logistics hubs absorbs expanding volumes of hydrogenated C5 tackifiers. EPA hazardous air pollutant regulations on coating operations redirect formulation procurement toward compliant hot-melt systems. The Gulf Coast petrochemical corridor supplies C5 and C9 feedstock streams to integrated resin producers with captive hydrogenation assets.
China
GB standards for volatile organic compound emissions in architectural coatings disqualify conventional solvent-borne systems from state procurement tenders. Domestic resin producers are accelerating hydrogenation capacity additions through partnerships with Korean technology licensors. The Yangtze River Delta concentration of tape and label manufacturers drives specification demand for water-white resin grades.
Germany
Automotive interior assembly and tire compounding applications require REACH-registered resin grades with documented substance safety profiles. The EU Green Deal chemical transition favors hydrogenated resins with certified carbon intensity metrics over conventional aromatic alternatives. The Ruhr industrial basin hosts specialized hydrogenation facilities serving food-contact packaging formulators.
India
Road marking, construction adhesives, and protective coatings for transport infrastructure absorb growing C9 aromatic resin volumes. Import-dependent regional supply creates white space for domestic fractionation and resin finishing investments. The Gujarat petrochemical cluster is attracting capital for C5/C9 stream processing to serve western and southern construction markets.
Japan
Electronics encapsulant and potting compound applications demand water-white color and oxidative stability achievable only through selective hydrogenation technology. METI industrial standards shape qualification timelines for resin grades entering semiconductor packaging supply chains. The Osaka-Kobe manufacturing belt concentrates specialty hydrogenated capacity for premium adhesive and coating segments.
Petroleum Resins Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. Integrated petrochemical majors leverage backward integration into refinery feedstocks to sustain margin stability through crude price cycles. Mid-scale regional producers depend on toll-manufacturing partnerships and distributor networks for market access. Dominant competitive moves include capacity expansion in hydrogenated specialty grades and strategic partnerships with Korean and Japanese technology licensors.
Within the integrated-major archetype, ExxonMobil Corporation anchors supply relationships through direct technical service support to North American tape and label manufacturers. Eastman Chemical Company exemplifies the technology-specialist position through hydrogenated hydrocarbon resin capabilities. Arakawa Chemical Industries Ltd. represents the Asia-Pacific channel-control model with established distribution in rosin-modified resin blends. Kolon Industries Inc. and Neville Chemical Company occupy positions within the specialty-grade and regional-compounder tiers respectively.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Eastman Chemical Company |
| Arakawa Chemical Industries Ltd. |
| Kolon Industries Inc. |
| Neville Chemical Company |
| Lesco Chemical Limited |
| Synthomer PLC |
| Henan Anglxxon Chemical Co. Ltd. |
| INNOVA (Tianjin) Chemical Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Crude-linked feedstock volatility compresses margin predictability for non-integrated producers and simultaneously widens pricing spreads between hydrogenated specialty grades and conventional aromatic resins while reshaping procurement patterns toward long-term offtake contracts with refinery-tethered suppliers.
Pricing Analysis
Cost-plus contracts indexed to naphtha cracking spreads dominate procurement between integrated majors and multinational adhesive formulators. Price differentiation rests on hydrogenation certification grade and captive refinery access rather than brand premium. Pricing pressure stems from Southeast Asian hydrogenated capacity additions flooding premium segments. Regional construction compounders exhibit acute price sensitivity, while food-contact packaging formulators prioritize batch certification over unit cost.
Supply Chain Analysis
Extended payment terms from Korean and Japanese hydrogenation specialists to European distributors illustrate supplier-financing concentration in premium-grade channels. Feedstock draws from US Gulf Coast, Chinese Yangtze Delta, and Indian Gujarat petrochemical clusters. Raw material dependencies center on C5/C9 refinery streams, hydrogen offtake agreements, and palladium catalyst supply. Single-source vulnerability concentrates in Japanese electronics-grade hydrogenation capacity. Distribution runs through direct manufacturer relationships for multinational formulators and fragmented distributor networks for mid-scale regional compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The petroleum resins sector enters a cyclical recovery phase as refinery operating rate normalization and infrastructure spending in India restore feedstock availability and downstream offtake.
For Market Incumbents: Build regulatory certification moats by accelerating REACH registration for novel hydrogenated chemistries and securing captive hydrogen supply through electrolysis partnerships. Defensive consolidation should prioritize backward integration into C5/C9 fractionation capacity in the US Gulf Coast and Indian Gujarat corridors to offset margin compression from Korean technology licensors. Channel control investments in direct technical service relationships with North American tape and label manufacturers anchor pricing power against distributor disintermediation. For New Entrants and Emerging Players: Establish a beachhead in India's import-dependent C9 aromatic resin segment through toll-manufacturing partnerships with domestic refiners lacking downstream finishing assets. White-space targets include road marking and construction adhesive applications serving western and southern Indian transport corridors. A specialized go-to-market angle centers on rapid batch certification turnaround for mid-scale compounders underserved by integrated majors. For Investors and Strategic Acquirers: EPA hazardous air pollutant rule implementation reshapes the acquisition landscape by redirecting formulation demand toward compliant hydrogenated grades and stranding conventional aromatic capacity. Long-term viability favors targets with documented carbon intensity profiles and established Korean or Japanese technology licensing relationships. The signal to watch is domestic Chinese hydrogenation capacity ramp rates as GB VOC standard enforcement accelerates import substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Feedstocks | Captive C5/C9 stream access insulates margin stability from naphtha cracking volatility. |
| Hydrogenation Capacity Expansion | Selective hydrogenation technology unlocks food-contact and electronics encapsulant premium segments. |
| REACH Registration Acceleration | Documented substance safety profiles enable European market entry before competitor evaluation completion. |
| Toll-Manufacturing Partnerships | Asset-light market access reduces capital intensity for mid-scale producers targeting India's infrastructure buildout. |
| Direct Technical Service Relationships | Integrated supply relationships with multinational formulators displace distributor intermediaries in sustainability-scored procurement. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with refinery operations managers, adhesive formulator procurement leads, hydrogenation technology licensors, and distributor channel partners; and secondary validation through customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory dockets. Bottom-up triangulation across resin grade production volumes and top-down cross-check against end-use consumption patterns anchored forecast integrity.
Forecast inputs considered crude price trajectory assumptions, refinery operating rate projections, and regulatory implementation timelines across the analysis window. Segmentation dimensions modeled include resin chemistry tier, hydrogenation grade certification, end-use application, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs incorporated naphtha cracking spread forecasts and GB standard enforcement schedules.
Stress conditions across crude price bands, refinery utilization floors, and regulatory delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about feedstock availability and hydrogen supply security. Macroeconomic contraction, accelerated bio-based substitution, or unanticipated regulatory stringency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
Amorphous Polyolefin Market