
 Polyglycerates Market | 2026-2036
Polyglycerates Market Size, Share, and Industry Trends Forecast 2026-2036
Polyglycerates Market Analytics
China is rewriting capacity dynamics in polyglycerates as new esterification plants come online near Shanghai and Guangzhou. BASF SE leverages backward integration into glycerol feedstock to secure margin control across European supply chains. Croda International Plc anchors its position through specialized pharmaceutical-grade polyglycerol fatty acid esters. Evonik Industries competes on R&D intensity in high-purity polyglycerol monostearate for nutraceutical encapsulation.
Polyglycerates comprise esterified oligomers of glycerol with fatty acids, typically containing two to ten glycerol units and exhibiting HLB values from 3 to 14 depending on esterification degree. These compounds function primarily as non-ionic surfactants, emulsifiers, and dispersing agents in formulations requiring stable oil-water interfaces. Polyglycerol esters dominate volume due to their versatility across food emulsification and personal care applications, while polyglycerol ricinoleate commands premium positioning in pharmaceutical coatings where hydrophobic-lipophilic balance precision determines bioavailability. Liquid formulations lead in processing convenience for beverage and cosmetics manufacturers, though powder forms are gaining traction in nutraceutical tableting operations.
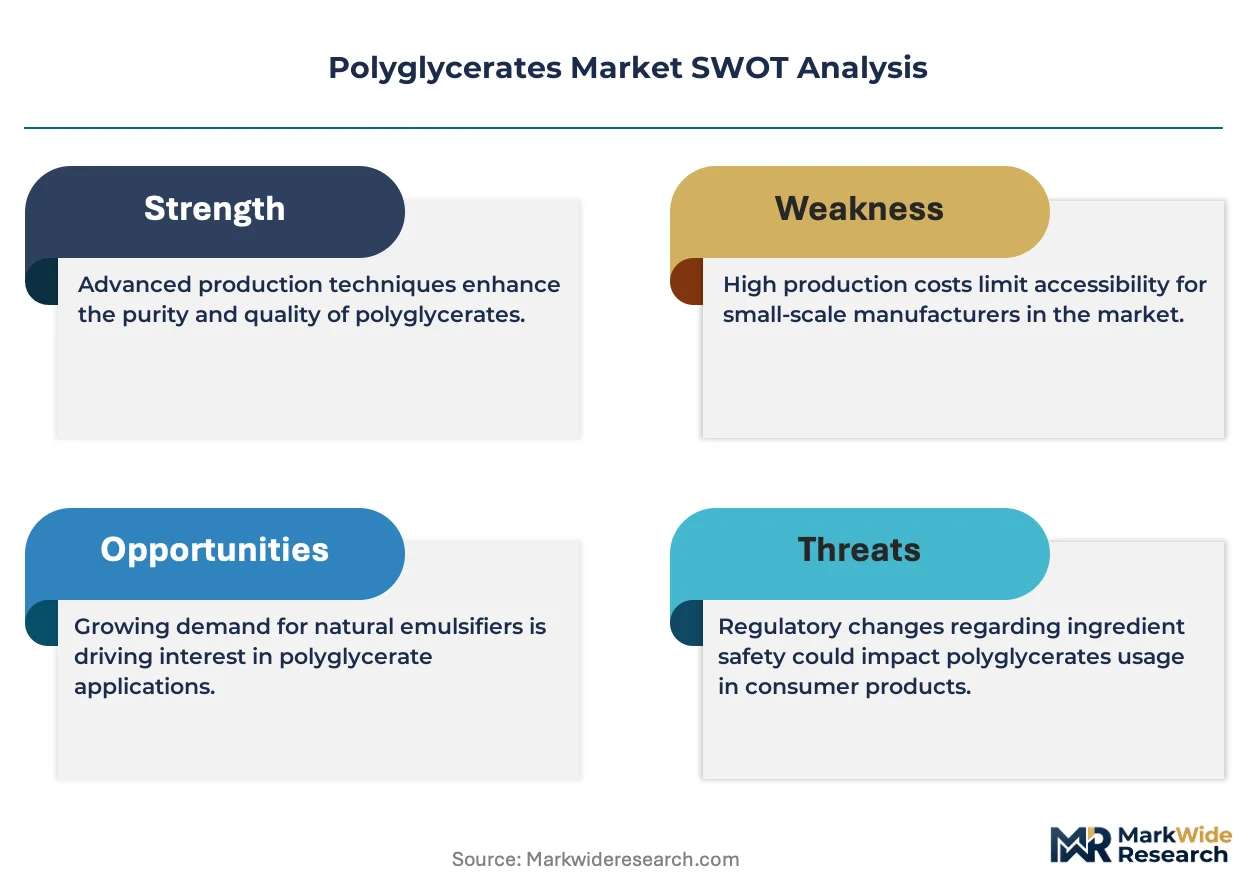
REACH registration requirements and the EU Green Deal sustainability criteria are elevating bio-based feedstock thresholds for polyglycerate imports into Europe. The FDA food additive regulations and FSSC 22000 certification standards shape compliance costs for suppliers targeting North American food and beverage channels. Japan's Ministry of Health, Labour and Welfare maintains distinct specifications for polyglycerol fatty acid esters used in quasi-drug cosmetics. Stakeholders must monitor feedstock volatility in vegetable oil markets and assess regional purity standard divergence when allocating R&D budgets across formulation portfolios.
Market Dynamics
Clean-label emulsification mandates from food manufacturers are compressing formulation windows for polyglycerate suppliers, forcing simultaneous upgrades in bio-based feedstock ratios and purity benchmarks across multiple certification schemes.
Growth Catalysts
- REACH registration thresholds:ECHA's escalating purity requirements for polyglycerol ester imports are locking out marginal producers and consolidating volume among compliant suppliers serving European food channels.
- Pharmaceutical encapsulation:Nutraceutical manufacturers in Germany and Japan are specifying high-grade polyglycerol monostearate for lipid-based drug delivery systems requiring precise hydrophobic-lipophilic balance control.
- Esterification capacity expansion:New glycerol oligomerization plants near Shanghai and Guangzhou are redirecting regional supply flows and altering import dependency patterns for Asian formulators.
Market Restraints
- Vegetable oil feedstock volatility:Palm and coconut oil price swings directly compress polyglycerate producer margins, with limited pass-through elasticity in contract structures.
- European supply concentration:Backward-integrated glycerol producers in Germany control critical feedstock nodes, creating bottleneck risk for non-integrated compounders.
- Sorbitan ester substitution:Established emulsifier chemistries maintain formulation inertia in cost-sensitive beverage applications, slowing polyglycerate penetration.
Strategic Opportunities
- Quasi-drug cosmetics in Japan:MHLW specifications for polyglycerol fatty acid esters create a certification moat for suppliers willing to navigate distinct testing protocols.
- FSSC 22000 certification arbitrage:North American food manufacturers seeking supplier consolidation favor multi-certified producers, rewarding early compliance investments.
- Dual carbon alignment:China's SAMR bio-based labeling requirements are opening premium positioning for polyglycerates with verified renewable carbon content.
Industry Challenges
- Analytical chemistry talent scarcity:HLB value verification and oligomer distribution characterization require specialized chromatography expertise that competes with pharmaceutical sector hiring.
- Multi-jurisdiction dossier maintenance:Simultaneous FDA food additive petitions, REACH registrations, and MHLW filings strain regulatory affairs capacity without guaranteed approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyglycerates Market |
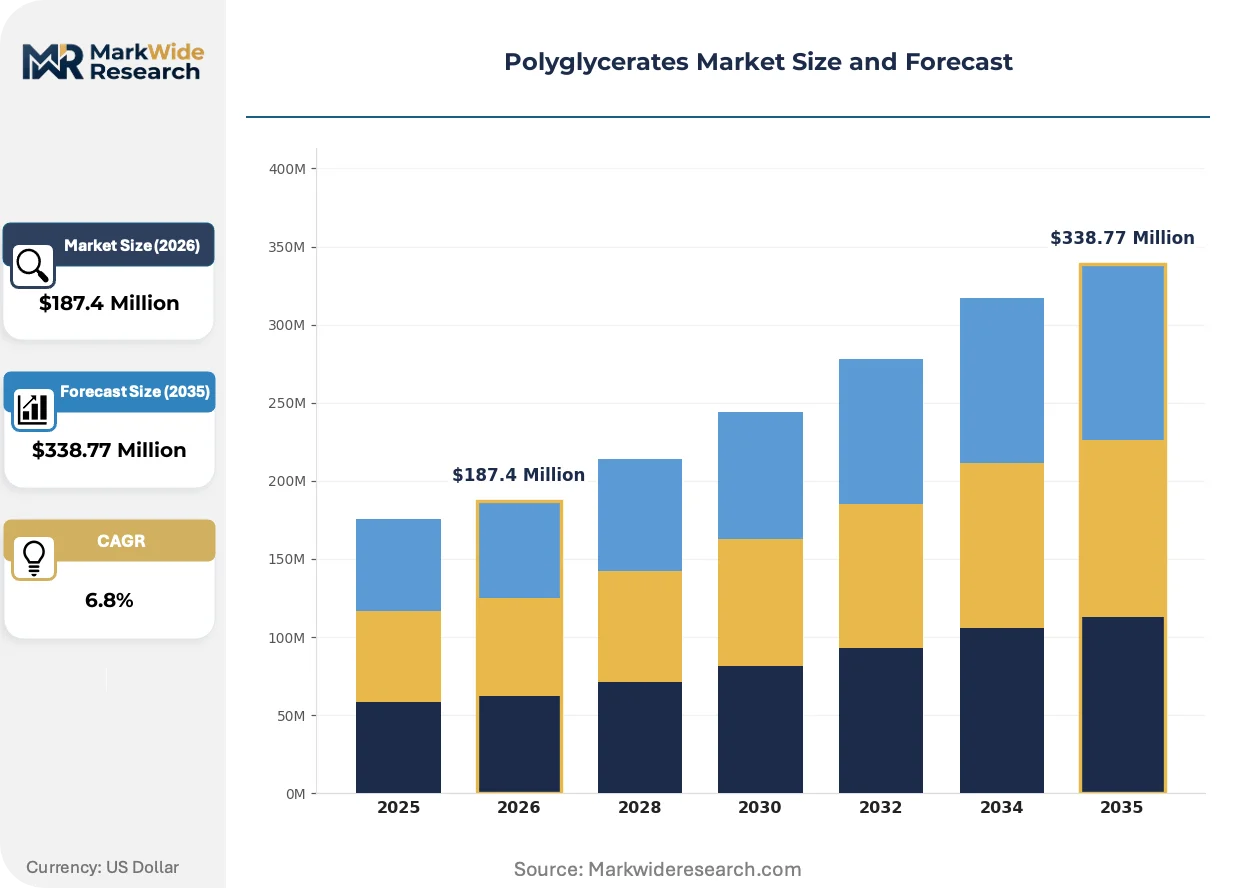
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyglycerol Esters, Polyglycerol Fatty Acid Esters, Polyglycerol Monostearate, Polyglycerol Ricinoleate Application: Food Industry, Personal Care, Pharmaceuticals, Agriculture End Use Industry: Beverages, Cosmetics, Nutraceuticals, Coatings Form: Liquid, Powder, Emulsion, Solid |
| Companies Covered | Mitsubishi Chemical Holdings Corporation, Estelle Chemicals Pvt. Ltd., Lonza, Oleon NV, DuPont, BASF SE, Evonik Industries, Croda International Plc, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyglycerates Market Evolving Landscape
Enzymatic esterification routes are displacing traditional chemical processes, altering capital requirements and product purity profiles while enabling temperature-sensitive fatty acid incorporation previously excluded from polyglycerate formulations.
Directed enzyme catalysis is collapsing the temperature differential between reaction stages, allowing processors to handle heat-labile unsaturated fatty acids without oxidation degradation. Cosmetics formulators in South Korea are adopting these grades for sensitive-skin emulsions where thermal history affects tolerability. The technology is compressing the premium gap between standard and pharmaceutical-grade specifications.
EU Green Deal sustainability criteria are mandating mass-balance certification for bio-based feedstock claims, forcing suppliers to implement blockchain-tracked supply chain documentation. Food manufacturers sourcing for European retail channels now require third-party verification of renewable carbon percentages. German and French importers are rejecting uncertified shipments regardless of analytical purity.
Specification-driven procurement is consolidating buyer power among multinational food and personal care manufacturers, displacing spot-market purchasing for strategic emulsifier categories. Tier-one suppliers are responding with dedicated technical service teams embedded at major formulator R&D centers. This concentration is most visible in United States and German markets where FSSC 22000 certification serves as a vendor qualification gate.
Polyglycerates Market Segmentation
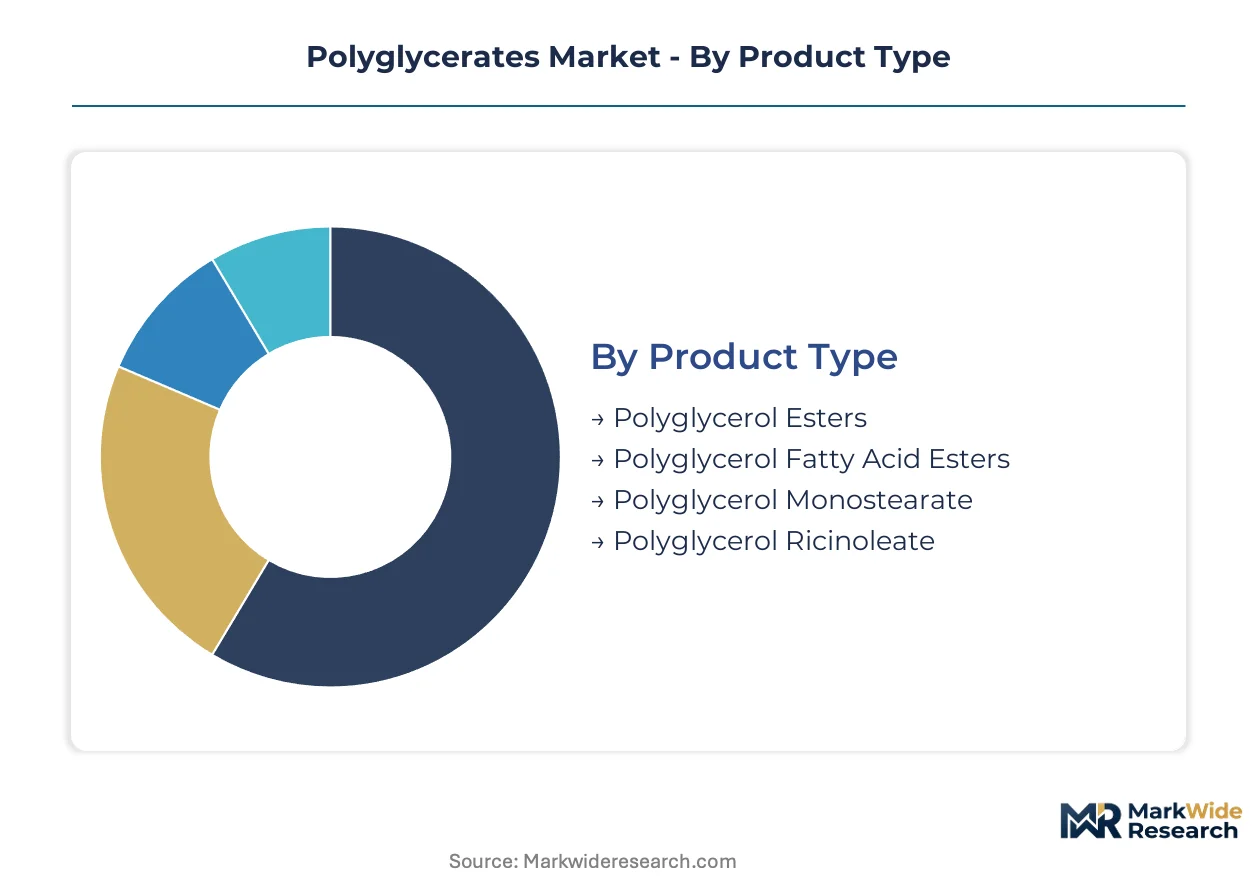
Polyglycerate suppliers navigate divergent purity benchmarks and certification requirements across food, pharmaceutical, and personal care channels. Segmentation reveals where formulation complexity drives premium positioning versus where commodity emulsification tolerates standard grades.
Product Type:
Cost tier differentiation separates pharmaceutical-grade specifications from industrial emulsification grades, with feedstock integration determining margin capture across each tier.
- Polyglycerol Esters:These comprise esterified oligomers of glycerol with fatty acids, typically containing two to ten glycerol units with HLB values spanning 3 to 14. Demand concentrates in Germany and Japan where food manufacturers specify non-ionic surfactants for clean-label emulsification under tightening ECHA purity thresholds.
- Polyglycerol Fatty Acid Esters:Broader molecular weight distributions enable versatility across personal care and food applications with varying oil-phase requirements. Formulators in South Korea and France are rotating specifications toward these grades for sensitive-skin cosmetics where thermal processing history affects tolerability.
- Polyglycerol Monostearate:Narrow HLB precision suits lipid-based drug delivery systems requiring hydrophobic-lipophilic balance control.
- Polyglycerol Ricinoleate:Hydrophobic-lipophilic balance precision commands premium positioning in pharmaceutical coatings where bioavailability depends on coating integrity.
Polyglycerol esters hold installed capacity. Polyglycerol ricinoleate is rotating up the share rankings.
Application:
Application focus determines regulatory pathway complexity, with pharmaceutical and food channels imposing distinct purity verification protocols versus agricultural tolerance for broader specifications.
- Food Industry:Clean-label mandates from manufacturers in Germany and the United States are compressing formulation windows, forcing simultaneous upgrades in bio-based feedstock ratios and FSSC 22000 certification compliance.
- Personal Care:South Korean and Japanese cosmetics formulators specify grades with verified thermal history for sensitive-skin emulsions, with MHLW quasi-drug specifications creating certification moats for compliant suppliers.
- Pharmaceuticals:Nutraceutical encapsulation in Germany and Japan requires high-grade specifications for lipid-based delivery systems.
- Agriculture:Cost-sensitive formulations tolerate broader oligomer distributions with less stringent purity verification.
Food industry applications anchor volume demand. Pharmaceuticals is climbing the fastest on value per kilogram.
End Use Industry:
Customer type stratification separates multinational manufacturers with embedded technical service requirements from regional compounders purchasing on specification sheets alone.
- Beverages:Liquid processing convenience dominates procurement criteria, though sorbitan ester substitution maintains formulation inertia in cost-sensitive applications.
- Cosmetics:South Korean and Japanese manufacturers specify enzymatically esterified grades for temperature-sensitive formulations where oxidation degradation affects product stability.
- Nutraceuticals:Powder forms are gaining traction in tableting operations requiring precise flow characteristics and compression behavior.
- Coatings:Pharmaceutical coating applications demand hydrophobic-lipophilic balance precision for controlled release functionality.
Beverages holds installed capacity. Nutraceuticals is rotating up the share rankings.
Form:
Physical form selection hinges on processing equipment compatibility and downstream handling economics, with powder investments rising where tableting and dry-blending operations expand.
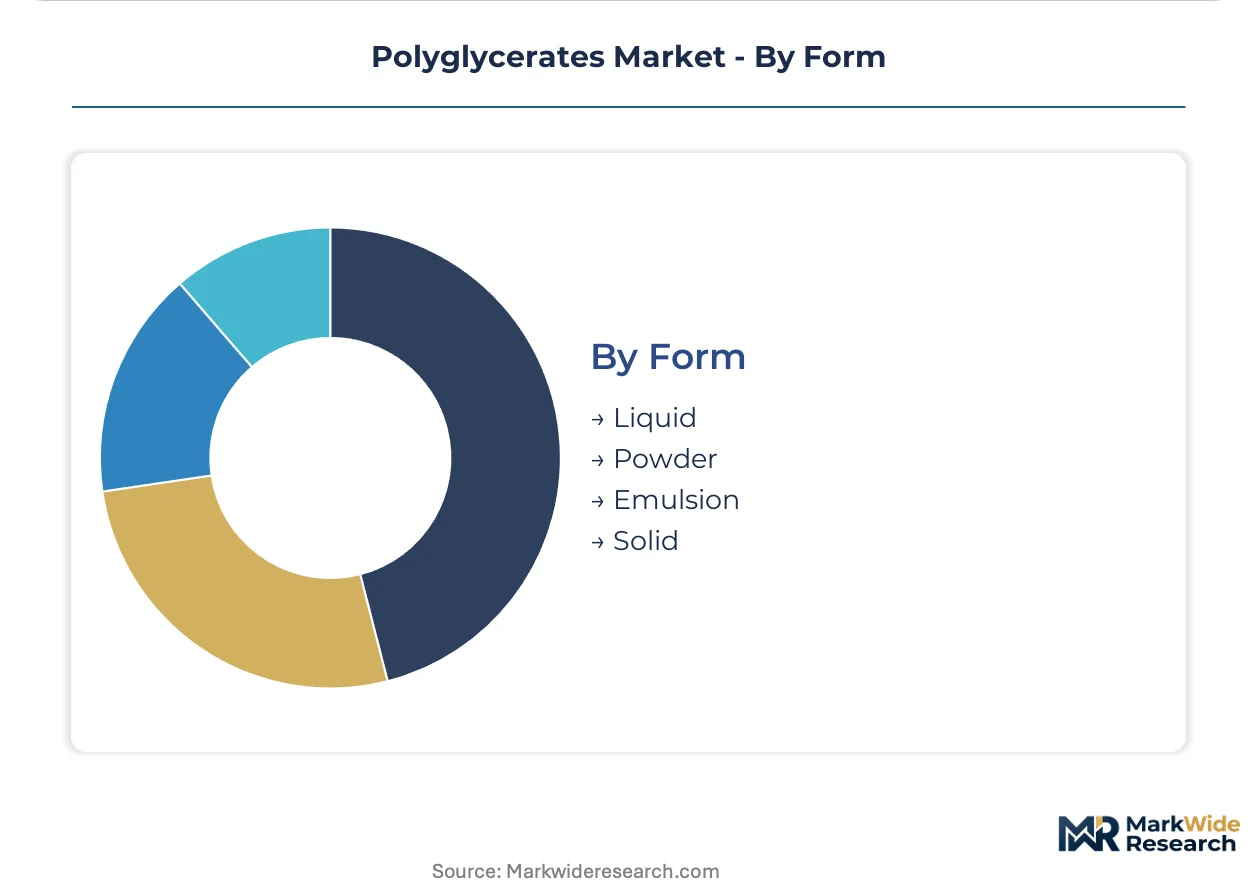
- Liquid:Processing convenience dominates for beverage and cosmetics manufacturers with existing liquid handling infrastructure, though cold-chain considerations limit geographic reach.
- Powder:Dry forms enable nutraceutical tableting and bakery premix applications where moisture sensitivity constrains liquid alternatives.
- Emulsion:Pre-dispersed formats reduce manufacturing step complexity for small-batch cosmetics compounders.
- Solid:Flake and pellet forms suit high-temperature processing environments where melt incorporation is preferred.
Liquid holds installed capacity. Powder is expanding most quickly on nutraceutical investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Backward-integrated glycerol producers in Germany control critical feedstock nodes that shape regional supply security. ECHA purity thresholds and EU Green Deal sustainability criteria are elevating bio-based certification requirements across European import channels. New esterification capacity near Shanghai and Guangzhou is redirecting Asian supply flows and altering import dependency patterns for regional formulators.
Germany
Food manufacturers specify non-ionic surfactants for clean-label emulsification under tightening ECHA purity thresholds. REACH registration requirements lock out marginal producers and consolidate volume among compliant suppliers. The Rhine-Ruhr industrial corridor hosts backward-integrated producers leveraging captive glycerol supply to secure margin control across European supply chains.
United States
North American food and beverage channels demand FSSC 22000 certification as a vendor qualification gate for strategic emulsifier categories. FDA food additive regulations shape compliance costs for suppliers targeting premium formulation applications. Midwest manufacturing clusters concentrate liquid processing infrastructure for beverage manufacturers seeking processing convenience.
China
New glycerol oligomerization plants near Shanghai and Guangzhou expand domestic esterification capacity for regional formulators. SAMR bio-based labeling requirements open premium positioning for polyglycerates with verified renewable carbon content. Yangtze River Delta chemical parks attract investment in enzymatic esterification routes enabling temperature-sensitive fatty acid incorporation.
Japan
Nutraceutical manufacturers specify high-grade polyglycerol monostearate for lipid-based drug delivery systems requiring precise hydrophobic-lipophilic balance control. MHLW maintains distinct specifications for polyglycerol fatty acid esters used in quasi-drug cosmetics. Kanto region formulators rotate procurement toward enzymatically esterified grades for sensitive-skin emulsions where thermal history affects tolerability.
South Korea
Cosmetics formulators adopt enzymatically esterified grades for temperature-sensitive formulations where oxidation degradation affects product stability. MFDS regulatory frameworks align with regional premium positioning for pharmaceutical-grade specifications. Seoul Capital Area R&D centers embed dedicated technical service teams from tier-one suppliers responding to specification-driven procurement consolidation.
Polyglycerates Market Competitive Landscape
Specialized pharmaceutical-grade suppliers and diversified chemical conglomerates split the market across premium and volume tiers. Three strategic archetypes dominate: backward-integrated feedstock controllers, enzymatic process technology specialists, and multi-certified compliance leaders. Competitive moves concentrate on capacity expansion near demand clusters and portfolio diversification into pharmaceutical-grade specifications.
Within the diversified chemical conglomerate tier, BASF SE and Evonik Industries exemplify European producers leveraging scale and R&D intensity. BASF SE anchors its position through backward integration into glycerol feedstock. Evonik Industries occupies a position focused on high-purity polyglycerol monostearate for nutraceutical encapsulation. Croda International Plc represents the specialized pharmaceutical-grade archetype, with its UK-based structure signaling premium positioning in fatty acid ester chemistry.
| Leading Market Players |
|---|
| Mitsubishi Chemical Holdings Corporation |
| Estelle Chemicals Pvt. Ltd. |
| Lonza |
| Oleon NV |
| DuPont |
| BASF SE |
| Evonik Industries |
| Croda International Plc |
| Cargill |
| Others |
Value Network & Pricing Analysis
German backward-integrated glycerol producers controlling Rhine-Ruhr feedstock nodes capture margin pools downstream in pharmaceutical-grade polyglycerol monostearate, while Asian compounders without captive supply face persistent cost compression in standard emulsification tiers.
Pricing Analysis
REACH registration dictates the pricing tier structure across European import channels, separating FSSC 22000-certified pharmaceutical grades from uncertified industrial specifications. Three-tier pricing stratifies across premium certified, standard food-grade, and economy industrial levels, with enzymatic process premiums collapsing as South Korean cosmetics adoption scales. Cost compression in standard grades intensifies because vegetable oil feedstock volatility lacks contract pass-through elasticity. Beverage manufacturers exhibit highest price sensitivity, while German nutraceutical encapsulators tolerate premium positioning for HLB precision.
Supply Chain Analysis
EU Green Deal mass-balance certification requirements restrict uncertified bio-based feedstock flows into European retail channels, redirecting supply toward compliant producers. Manufacturing concentrates in Germany, China, and Japan, with new esterification capacity near Shanghai and Guangzhou altering Asian import dependency. Glycerol oligomers, palm-derived fatty acids, and coconut oil fractions anchor raw material sourcing. Single-source vulnerability runs through German backward-integrated glycerol nodes controlling European feedstock access. Distribution runs through technical service teams embedded at major formulator R&D centers rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational food and personal care manufacturers with specification-driven procurement, consolidating vendor relationships and compressing spot-market access for non-certified suppliers.
For Market Incumbents: Build certification moats around REACH-registered pharmaceutical-grade capacity to defend against enzymatic process entrants. Secure backward integration into glycerol feedstock or long-term offtake agreements with Rhine-Ruhr producers to mitigate raw material volatility. Expand dedicated technical service teams in Seoul Capital Area R&D centers to lock in South Korean cosmetics formulator relationships before process technology premiums erode.
For New Entrants and Emerging Players: Quasi-drug cosmetics specifications in Japan represent the most penetrable entry point for specialized suppliers willing to navigate distinct MHLW testing protocols. Agricultural applications tolerate broader oligomer distributions with less stringent purity verification, offering volume footholds without certification burden. Lead with enzymatic esterification technology positioning to differentiate on thermal history credentials for sensitive-skin formulations.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European compounders lacking feedstock integration but holding REACH registration dossiers. Five-to-ten year viability hinges on successful certification arbitrage across FSSC 22000 and MHLW frameworks rather than commodity emulsification scale. Monitor enzymatic process cost parity as the inflection signal for pharmaceutical-grade margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycerol Feedstock | Rhine-Ruhr producers secure margin control across European supply chains through captive supply. |
| Enzymatic Esterification Capacity Expansion | Yangtze River Delta plants enable temperature-sensitive fatty acid incorporation for cosmetics applications. |
| Multi-Certification Compliance Investment | REACH-registered FSSC 22000 suppliers consolidate multinational food manufacturer vendor relationships. |
| Embedded Technical Service Teams | Seoul Capital Area R&D presence locks in specification-driven procurement from tier-one cosmetics formulators. |
| Pharmaceutical-Grade Specification Diversification | German nutraceutical encapsulators specify high-grade polyglycerol monostearate for lipid-based drug delivery. |
Research Methodology
A spread of perspectives from plant managers at esterification facilities, procurement leads at downstream food and cosmetics manufacturers, technical R&D directors, and distribution channel partners converged on the working assumptions. Primary interview insights combined with secondary validation from ECHA registration databases, FDA food additive petitions, customs and trade flow data, and SEC filings from diversified chemical conglomerates. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Demand-supply balance modeling anchored the forecast framework across product type, application channel, end-use industry, and regional production hub segmentation. CAGRs derived from fitted growth curves applied to verified capacity expansions and substitution elasticity estimates. Industry-specific inputs included enzymatic process adoption rates in South Korean cosmetics and REACH registration timeline bottlenecks for marginal producers.
Practitioners should monitor feedstock volatility in vegetable oil markets and regulatory divergence across ECHA, FDA, and MHLW frameworks for early signals. Forecasts reflect assumptions about certification adoption timelines and enzymatic process cost trajectories. Material shifts in bio-based feedstock availability or purity standard harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market