
 Polychlorotrifluoroethylene (PCTFE) Market | 2026-2036
Polychlorotrifluoroethylene (PCTFE) Market Size, Share, and Industry Trends Forecast 2026-2036
Polychlorotrifluoroethylene (PCTFE) Market Analytics
REACH compliance is hardening the cost-of-entry calculus for European PCTFE producers, forcing reformulation investments and third-party certification costs that smaller compounders cannot absorb. Solvay leverages its integrated chlor-alkali chain to control feedstock costs across Belgian and Italian production sites. Daikin Industries Ltd anchors Asian supply through its Osaka-based fluoropolymer complex, while Chemours Company competes via its North American vertical integration into chlorotrifluoroethylene monomer production.
Polychlorotrifluoroethylene is a semi-crystalline fluoropolymer synthesized from chlorotrifluoroethylene monomer via free-radical polymerization, exhibiting near-zero moisture absorption, exceptional chemical inertness, and cryogenic ductility down to -240°C. Its primary industrial purpose centers on hermetic sealing, pharmaceutical blister packaging, and aerospace fluid containment where permeation resistance proves critical. Film-grade PCTFE dominates pharmaceutical barrier applications due to superior water vapor transmission rates, while extruded sheets sustain margins in semiconductor fab infrastructure. Granule formulations for injection molding represent the fastest-growing product category as medical device OEMs qualify PCTFE for single-use fluid handling assemblies.
The EPA regulates PCTFE manufacturing emissions under Section 112 of the Clean Air Act, while Japan's METI enforces fluorocarbon phase-down schedules affecting feedstock availability. The EU F-Gas Regulation progressively restricts hydrofluorocarbon use, indirectly pressuring chlorotrifluoroethylene supply chains and accelerating bio-based fluoropolymer R&D. Stakeholders must monitor regulatory divergence between Brussels and Washington to anticipate which product grades will retain market access across jurisdictions.
Market Dynamics
REACH compliance and the EU F-Gas Regulation are restructuring PCTFE production economics, forcing compounders to absorb reformulation costs and third-party certification expenses that reshape competitive viability across European supply chains.
Growth Catalysts
- Aerospace cryogenic demand:North American and European aerospace manufacturers are expanding PCTFE adoption for seals and barrier films in liquid hydrogen containment systems, driven by hydrogen aviation initiatives.
- EU F-Gas Regulation phase-down:The regulatory push toward low-GWP fluoropolymers is redirecting R&D investment into next-generation PCTFE formulations with reduced environmental footprint.
- Semiconductor equipment qualification:Japan's semiconductor fab infrastructure is driving granule formulation demand for single-use fluid handling assemblies in advanced node manufacturing.
Market Restraints
- Chlorotrifluoroethylene feedstock concentration:Captive monomer production by integrated chemical majors limits supply flexibility for independent compounders.
- REACH certification cost barrier:Third-party testing and substance registration expenses disproportionately burden smaller European producers.
- Perfluoroalkoxy alkane substitution threat:PFA materials compete for pharmaceutical barrier applications where processing temperatures permit alternative fluoropolymer use.
Strategic Opportunities
- German chemical processing corridor expansion:Industrial gas containment and pharmaceutical packaging demand in the Rhine-Ruhr and Ludwigshafen clusters offers white-space growth for film-grade PCTFE.
- Medical device OEM channel development:Direct qualification programs with injection molding houses bypass traditional distributor markups and accelerate specification lock-in.
- Bio-based fluoropolymer R&D convergence:Electrochemical fluorination advances and bio-feedstock polymerization routes promise regulatory-compliant alternatives to conventional synthesis.
Industry Challenges
- Fluoropolymer compounding skill scarcity:Specialized expertise in cryogenic ductility optimization and moisture barrier tuning remains concentrated among veteran formulation chemists nearing retirement.
- Multi-jurisdiction compliance synchronization:Divergent EPA Section 112, METI phase-down, and REACH timelines force parallel certification tracks that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polychlorotrifluoroethylene (PCTFE) Market |
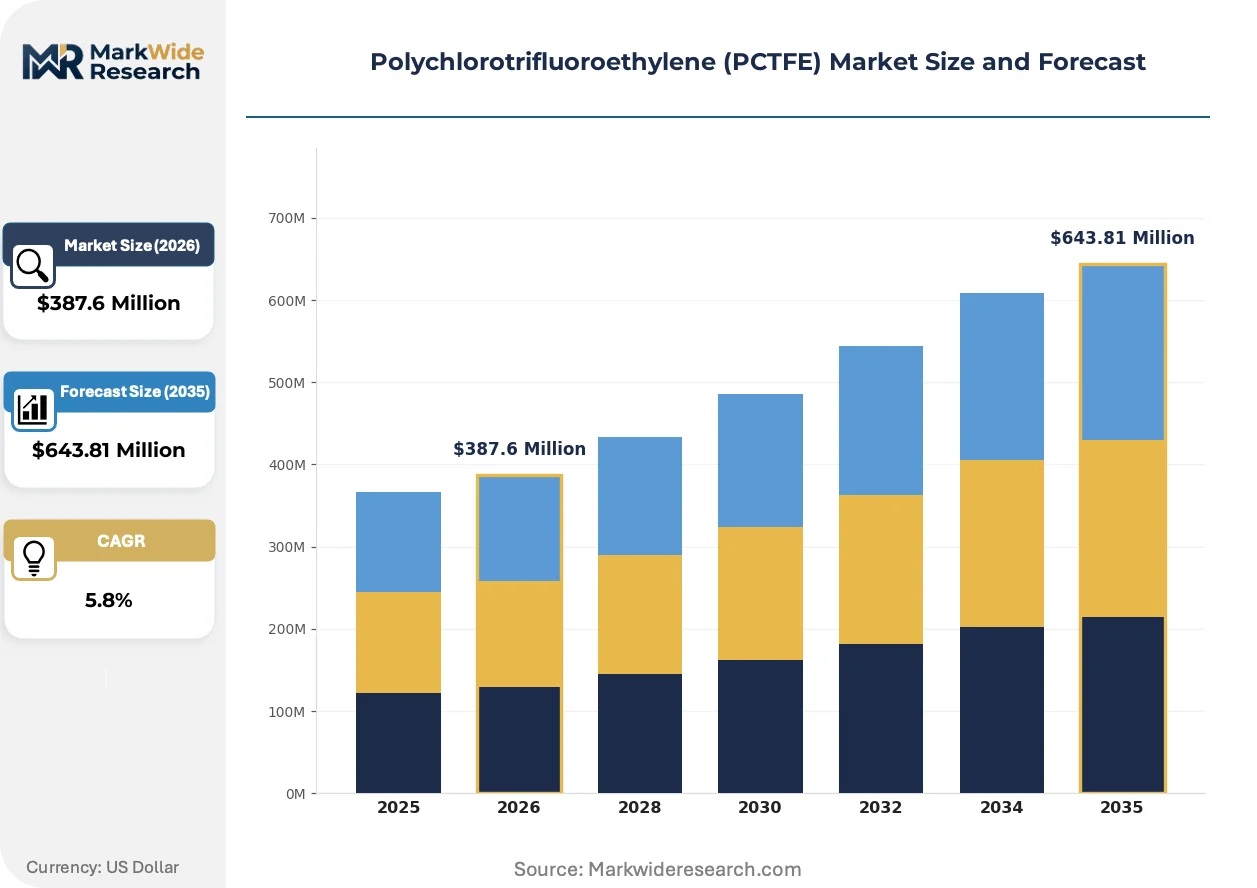
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Sheets, Films, Coatings End Use Industry: Aerospace, Electrical Insulation, Pharmaceuticals, Food Packaging Application: Gaskets, Seals, Pipe Linings, Insulation Technology: Extrusion, Coating, Molding, Blow Molding |
| Companies Covered | Solvay, Saint-Gobain, Daikin Industries Ltd, Zhejiang Juhua Co., Ltd., Chemours Company, Honeywell International Inc., HaloPolymer, DuPont, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polychlorotrifluoroethylene (PCTFE) Market Evolving Landscape
Process automation and regulatory stringency are converging to compress PCTFE production batch variability while fragmenting supply chain configurations across jurisdictional compliance boundaries.
Closed-loop polymerization control systems are automating molecular weight distribution consistency in free-radical PCTFE synthesis. Pharmaceutical packaging film producers in Germany and Japan are deploying these systems to eliminate batch-to-batch permeation variance. The technology is automating quality assurance overhead that previously required manual rheological testing.
The EU F-Gas Regulation's progressive hydrofluorocarbon restrictions are indirectly pressuring chlorotrifluoroethylene feedstock availability. European compounders are responding by diversifying monomer sourcing and accelerating qualification of recycled-content PCTFE grades. Film and sheet producers serving pharmaceutical blister packaging face the most acute reformulation timelines.
Specification-driven procurement is compressing supplier qualification cycles as medical device OEMs consolidate vendor bases. Direct material qualification between PCTFE compounders and injection molding houses is displacing traditional distributor-mediated relationships. This pattern is most visible in Japan's semiconductor equipment supply chain and Germany's pharmaceutical packaging cluster.
Polychlorotrifluoroethylene (PCTFE) Market Segmentation
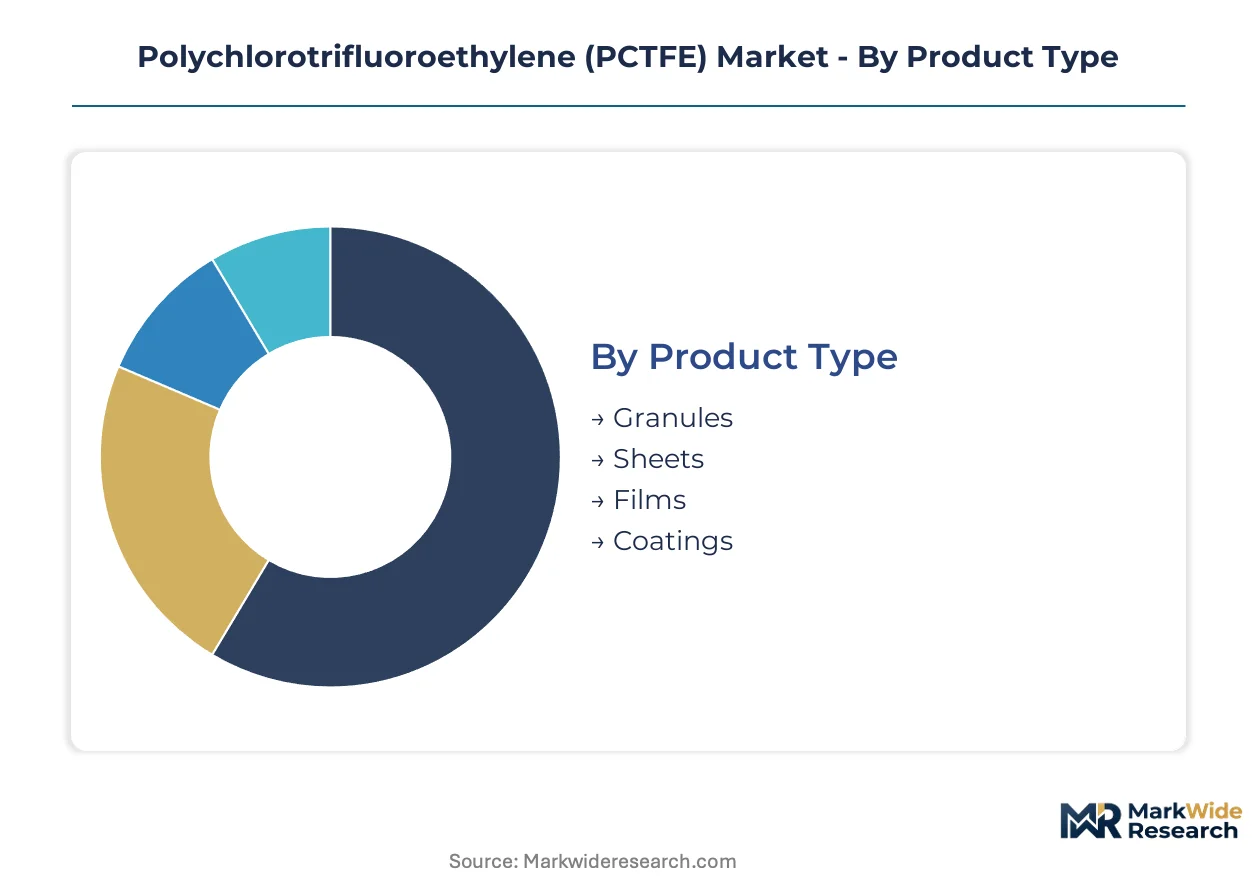
PCTFE's performance characteristics vary sharply across physical forms and processing routes. Specification requirements from aerospace cryogenics and pharmaceutical barrier applications drive divergent product development priorities across each segment axis.
Product Type:
Standardization dominates granule and sheet production, while film and coating grades demand extensive customer-specific formulation tuning.
- Films:Ultra-thin calendered or cast structures engineered for water vapor transmission rates below 0.01 g/m²/day. Pharmaceutical blister packaging in Germany's Rhine-Ruhr corridor and Japan's Kanto region absorbs the majority of output, with qualification cycles extending 18-24 months for new medical device submissions.
- Granules:Injection-molding feedstock with controlled melt flow indices between 1-10 g/10min. Medical device OEMs in Japan's semiconductor equipment supply chain are qualifying these for single-use fluid handling assemblies, driving the steepest capacity additions among all product types.
- Sheets:Extruded plates and blocks serving semiconductor fab infrastructure and chemical processing equipment. Osaka-based fabricators maintain substantial inventory positions for etch tool lining applications.
- Coatings:Dispersion-based surface treatments for metal substrates requiring chemical inertness. Aerospace valve manufacturers in the US and France specify these for cryogenic fuel system components.
Most installed capacity flows through Films. Expansion is steepest in Granules.
End Use Industry:
Volume concentration sits with mature industrial applications, while margin capture concentrates in regulated life-science sectors.
- Pharmaceuticals:Barrier packaging for moisture-sensitive therapeutics and diagnostic reagents. FDA and EMA submission requirements enforce batch-to-batch permeation consistency that only integrated compounders can reliably deliver.
- Aerospace:Cryogenic seals and gaskets for liquid hydrogen containment systems. Boeing and Airbus supplier qualification programs in the US, Germany, and France are expanding specification callouts for PCTFE as hydrogen aviation initiatives accelerate.
- Electrical Insulation:Wire coatings and connector housings for high-frequency signal transmission. Japanese automotive electronics suppliers in Aichi Prefecture represent the primary demand concentration.
- Food Packaging:High-barrier films for aroma-sensitive products. REACH compliance costs have compressed European participation, shifting production toward US Gulf Coast compounding facilities.
Pharmaceuticals commands the highest average selling prices. Aerospace is climbing the fastest.
Application:
Component criticality determines specification stringency, with hermetic sealing applications tolerating zero permeation variance.
- Seals:O-rings, gaskets, and static seals for extreme-temperature fluid containment. Cryogenic ductility down to -240°C makes these irreplaceable in liquid hydrogen infrastructure across US Space Coast and French Guiana launch facilities.
- Gaskets:Flange and joint seals for chemical processing equipment. Germany's Ludwigshafen chemical cluster maintains long-term supply agreements with Belgian compounders for standard and custom geometries.
- Pipe Linings:Corrosion-resistant interior coatings for aggressive chemical transport. Japanese petrochemical complexes in Chiba and Yokkaichi specify these for chlorine and fluorine handling systems.
- Insulation:Dielectric barriers in high-voltage electrical equipment. Transformer manufacturers in the US Midwest and China's Jiangsu Province represent the primary demand nodes.
Seals absorb the largest share of current formulation output. Gaskets are gaining share fastest.
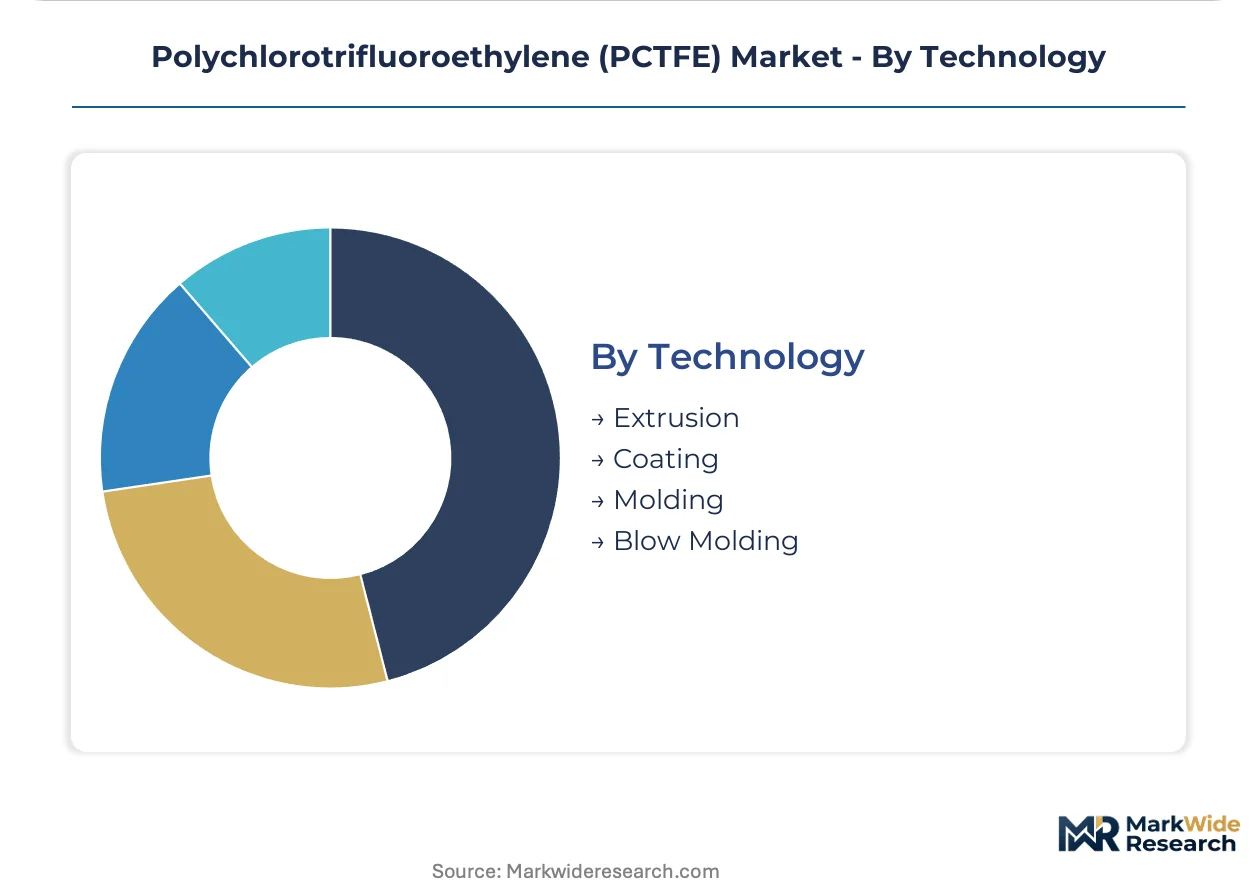
Technology:
Process maturity varies inversely with part complexity, with blow molding representing the frontier application requiring specialized equipment investment.
- Extrusion:Continuous profile and sheet production with tight molecular weight distribution control. Film and sheet producers in Germany and Japan deploy closed-loop automation to eliminate batch-to-batch permeation variance.
- Molding:Injection and compression forming for precision-engineered components. Medical device OEMs are consolidating supplier bases around compounders offering direct material qualification, bypassing traditional distributor relationships.
- Coating:Dispersion application for metal substrate protection. Aerospace primes in France and the US specify electrostatic spray or dip-coating processes depending on component geometry.
- Blow Molding:Hollow-form production for specialized containment vessels. Limited installed capacity concentrates in Osaka and Houston among compounders with captive monomer supply.
Extrusion hosts the broadest installed base. Molding is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fluoropolymer formulation chemists cluster in Germany's Rhine-Ruhr corridor, Japan's Osaka-Kobe industrial zone, and the US Gulf Coast chemical belt, anchoring PCTFE production expertise in three distinct regulatory jurisdictions.
United States
Aerospace cryogenic seals and pharmaceutical barrier films drive demand from Boeing supplier networks in Seattle and Space Coast launch facilities. EPA Section 112 emissions controls shape manufacturing compliance costs for chlorotrifluoroethylene producers. Houston-Galveston petrochemical complexes maintain captive monomer production integrated with downstream PCTFE compounding.
Germany
Industrial gas containment systems and pharmaceutical blister packaging absorb the majority of European film-grade output. REACH substance registration and ECHA authorization requirements force reformulation investments that smaller compounders cannot absorb. Ludwigshafen's chemical processing corridor hosts integrated producers serving FDA and EMA submission requirements.
Japan
Semiconductor equipment OEMs in Tokyo-Yokohama and Osaka qualify granule formulations for single-use fluid handling assemblies in advanced node manufacturing. METI fluorocarbon phase-down schedules constrain chlorotrifluoroethylene feedstock availability. Osaka-based fabricators maintain substantial inventory positions for etch tool lining applications.
Belgium
Integrated chlor-alkali operations support captive monomer production for pharmaceutical and aerospace compounders. EU F-Gas Regulation hydrofluorocarbon restrictions redirect investment toward low-GWP alternative formulations. Antwerp-Rotterdam chemical cluster facilities serve EMA-regulated packaging demand across continental Europe.
China
Electrical insulation wire coatings and connector housings for automotive electronics suppliers concentrate demand in Jiangsu and Zhejiang provinces. National standards under MIIT and dual carbon goals pressure conventional fluoropolymer synthesis routes. Yangtze River Delta chemical parks attract capacity expansion for domestic semiconductor equipment supply chains.
Polychlorotrifluoroethylene (PCTFE) Market Competitive Landscape
The competitive structure tilts toward integrated chemical majors with captive chlorotrifluoroethylene monomer supply. Three to five producers control the majority of global capacity through backward integration into feedstock production. Two strategic archetypes dominate: diversified fluoropolymer portfolio players leveraging cross-product R&D, and regional specialists concentrating on pharmaceutical or aerospace qualification niches. Capacity expansion and direct OEM qualification programs represent the primary competitive vectors as distributors lose share to compounder-customer relationships.
Among integrated chemical majors, Solvay and Daikin Industries Ltd exemplify the diversified portfolio archetype with multi-site fluoropolymer production networks. Chemours Company occupies a position within the North American vertical integration tier, while Saint-Gobain and Arkema Group represent European-based specialists competing on pharmaceutical and aerospace certification depth. Zhejiang Juhua Co., Ltd. anchors Chinese supply capacity serving domestic electrical insulation and emerging semiconductor equipment demand.
| Leading Market Players |
|---|
| Solvay |
| Saint-Gobain |
| Daikin Industries Ltd |
| Zhejiang Juhua Co., Ltd. |
| Chemours Company |
| Honeywell International Inc. |
| HaloPolymer |
| DuPont |
| Arkema Group |
| Others |
Value Network & Pricing Analysis
Chlorotrifluoroethylene monomer spot pricing cascades through PCTFE compounding economics, compressing margins for non-integrated compounders while enabling captive producers to maintain three-tier pricing stratification across aerospace qualification, pharmaceutical barrier, and industrial grades. REACH certification costs and EPA Section 112 compliance investments amplify spread differentials between Belgian-integrated supply and independent European compounders.
Pricing Analysis
Bundled technical service and qualification support commands 15-25% premiums over unbundled resin-only transactions, particularly for pharmaceutical film grades requiring batch-to-batch permeation documentation. Price differentiation rests on EMA/FDA submission support depth and cryogenic ductility certification tier. Cost compression in standard industrial grades is intensifying as Chinese electrical insulation suppliers scale capacity. Medical device OEMs exhibit lowest price sensitivity due to 18-24 month qualification lock-in, while food packaging converters face acute margin pressure from REACH-driven reformulation costs.
Supply Chain Analysis
Dual-sourcing mandates from Boeing and Airbus supplier programs force aerospace compounders to qualify secondary monomer streams from Belgium and Japan, fragmenting procurement leverage. Geographic supply concentration centers on Belgium, Japan, and the United States, with Osaka-Kobe and Houston-Galveston clusters anchoring captive production. Feedstock dependencies encompass chlor-alkali chlorine, anhydrous hydrogen fluoride, and trichloroethylene. Single-source vulnerability concentrates in Japanese METI-regulated fluorocarbon phase-down timelines. Distribution runs through direct compounder-OEM relationships displacing traditional distributor channels in pharmaceutical and semiconductor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCTFE functions as a late-cycle quality story where specification stringency is accelerating demand migration toward premium-grade formulations with documented cryogenic performance and regulatory submission support.
For Market Incumbents: Acquire specialized fluoropolymer compounding expertise concentrated among veteran formulation chemists nearing retirement. Deepen backward integration into chlorotrifluoroethylene monomer production to neutralize feedstock cost volatility from METI phase-down schedules. Expand capacity in Germany's Rhine-Ruhr corridor to capture EMA-regulated pharmaceutical packaging demand as REACH compliance costs eliminate smaller European competitors. For New Entrants and Emerging Players: EU F-Gas Regulation in Europe opens a window for bio-based fluoropolymer formulations with reduced environmental footprint. Target medical device OEM direct qualification programs in Japan's semiconductor equipment supply chain, where granule demand for single-use fluid handling assemblies is climbing fastest. Pursue partnership-based entry with Osaka-based fabricators lacking captive monomer supply. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists holding deep pharmaceutical or aerospace certification libraries rather than diversified commodity fluoropolymer portfolios. Five-to-ten-year viability favors compounders with demonstrated EMA/FDA submission track records and integrated chlor-alkali feedstock positions. Monitor METI fluorocarbon phase-down acceleration as the critical inflection signal for Japanese supply availability and global pricing spreads.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive chlorotrifluoroethylene supply neutralizes METI phase-down exposure for Belgian and US producers. |
| Direct OEM Qualification Programs | Bypassing distributor channels locks in pharmaceutical and semiconductor device specifications at full margin. |
| Bio-Based Fluoropolymer R&D Investment | Electrochemical fluorination advances address EU F-Gas Regulation compliance for European film-grade output. |
| Regional Capacity Expansion | Rhine-Ruhr and Osaka-Kobe clusters position suppliers for EMA-regulated and semiconductor equipment demand. |
| Specialized Compounding Talent Acquisition | Cryogenic ductility optimization expertise scarcity creates defensive moats as veteran chemists retire. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade data. Primary interviews engaged plant managers at fluoropolymer compounding facilities, procurement leads at aerospace OEMs and pharmaceutical packaging converters, technical R&D directors specializing in cryogenic materials, and distribution channel partners serving semiconductor equipment supply chains. Secondary sources encompassed EPA Section 112 enforcement records, ECHA REACH registration databases, METI fluorocarbon phase-down schedules, customs and trade flow data, and SEC filings from integrated chemical majors. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators.
Granularity-level modeling operated at product-type, end-use industry, application, technology, and regional production hub dimensions. Volume and value outputs across the projection horizon reflect segment-specific demand elasticity and substitution threat parameters. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and qualification cycle timelines. Industry-specific forecast inputs incorporated aerospace hydrogen aviation initiative momentum, semiconductor node advancement schedules, and pharmaceutical packaging submission pipeline visibility.
Revisions become necessary when METI accelerates fluorocarbon phase-down timelines, EPA tightens Section 112 emissions thresholds, or EMA introduces novel pharmaceutical barrier packaging requirements. Deviation in chlorotrifluoroethylene feedstock availability from any major producing region would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Polyglycerates Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market