
 Electronic-Grade Polysilicon Market | 2026-2036
Electronic-Grade Polysilicon Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic-Grade Polysilicon Market Analysis
China's polysilicon capacity expansion is tilting the supply balance toward electronic-grade material. Daqo New Energy Corp. leverages integrated manufacturing from metallurgical-grade feedstock to 9N+ polysilicon. Wacker Chemie AG anchors European supply through its Burghausen facility with decades of semiconductor customer qualification. Tongwei Co., Ltd. dominates solar-grade volumes but extends into electronic-grade through dedicated Siemens reactor lines.
Electronic-grade polysilicon is hyper-pure silicon with impurity levels below one part per billion, produced via the Siemens process or fluidized bed reactor methods for semiconductor wafer manufacturing. The 9N to 11N purity bands command premium positioning due to stringent chipmaker qualification cycles spanning multiple years. Application segmentation shows semiconductors absorbing the highest-margin volumes while photovoltaics pulls larger tonnages at lower purity thresholds. Purity level segmentation reveals 8N material leading current revenue pools as advanced node logic and memory fabs standardize on this grade.
China's MIIT enforces GB standards for polysilicon energy consumption per kilogram, while the EU's REACH framework governs trichlorosilane handling across the supply chain. These regulations shape capital intensity for new entrants and filter market access toward producers with certified environmental management systems. Stakeholders must monitor how tightening carbon border adjustments and semiconductor subsidy eligibility criteria reshape geographic sourcing decisions.
Market Dynamics
Semiconductor fabrication capacity expansion in East Asia is concentrating polysilicon offtake among fewer, larger wafer manufacturers with multi-year qualification requirements. This buyer consolidation is forcing purification specialists to lock in dedicated reactor lines and absorb certification timelines that stretch across three to five years.
Growth Catalysts
- Advanced node migration:Logic fabs below 7nm require 9N+ polysilicon feedstock for epitaxial wafer growth. Taiwan Semiconductor Manufacturing Company and Samsung Foundry are qualifying new suppliers for 2nm ramp-ups.
- China's dual carbon goals:MIIT energy-intensity standards for polysilicon production are accelerating retirement of coal-powered Siemens reactors. Cleaner electricity sourcing is becoming a procurement filter for domestic semiconductor fabs.
- Fluidized bed reactor advances:FBR methods are reducing specific energy consumption per kilogram of electronic-grade output. REC Silicon and smaller specialists are piloting continuous production runs for solar-to-electronic grade crossover material.
Market Restraints
- Trichlorosilane price volatility:Feedstock costs swing with chlor-alkali co-product markets and energy tariffs. European producers face particular exposure through TCS import dependencies.
- Geographic supply concentration:Over 70 percent of metallurgical-grade silicon feedstock originates from Xinjiang and Yunnan provinces. Carbon border adjustments in destination markets threaten cost structures for China-integrated producers.
- Extended qualification cycles:Semiconductor customer certification spans 36 to 60 months for new 9N+ entrants. This timeline blocks rapid capacity monetization and strains capital deployment planning.
Strategic Opportunities
- India's semiconductor subsidy corridors:Gujarat and Tamil Nadu are offering land and power concessions for polysilicon purification investments. The PLI scheme for electronic components extends to upstream material localization.
- Silicon carbide convergence:Power electronics for electric vehicles require high-purity polysilicon precursors for SiC crystal growth. Automotive tier-one suppliers are entering direct offtake negotiations.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases in etching and cleaning processes are elevating polysilicon purity requirements. This regulatory tailwind favors suppliers with verified low-carbon process chains.
Industry Challenges
- Reactor engineering talent scarcity:Siemens process optimization and FBR scale-up require specialized chemical engineering profiles. Universities in Germany and Japan produce limited annual graduates with relevant semiconductor-materials training.
- Legacy equipment integration:Brownfield expansions must retrofit existing chlorosilane distillation trains for 11N purity targets. Compatibility testing with established safety systems extends commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic-Grade Polysilicon Market |
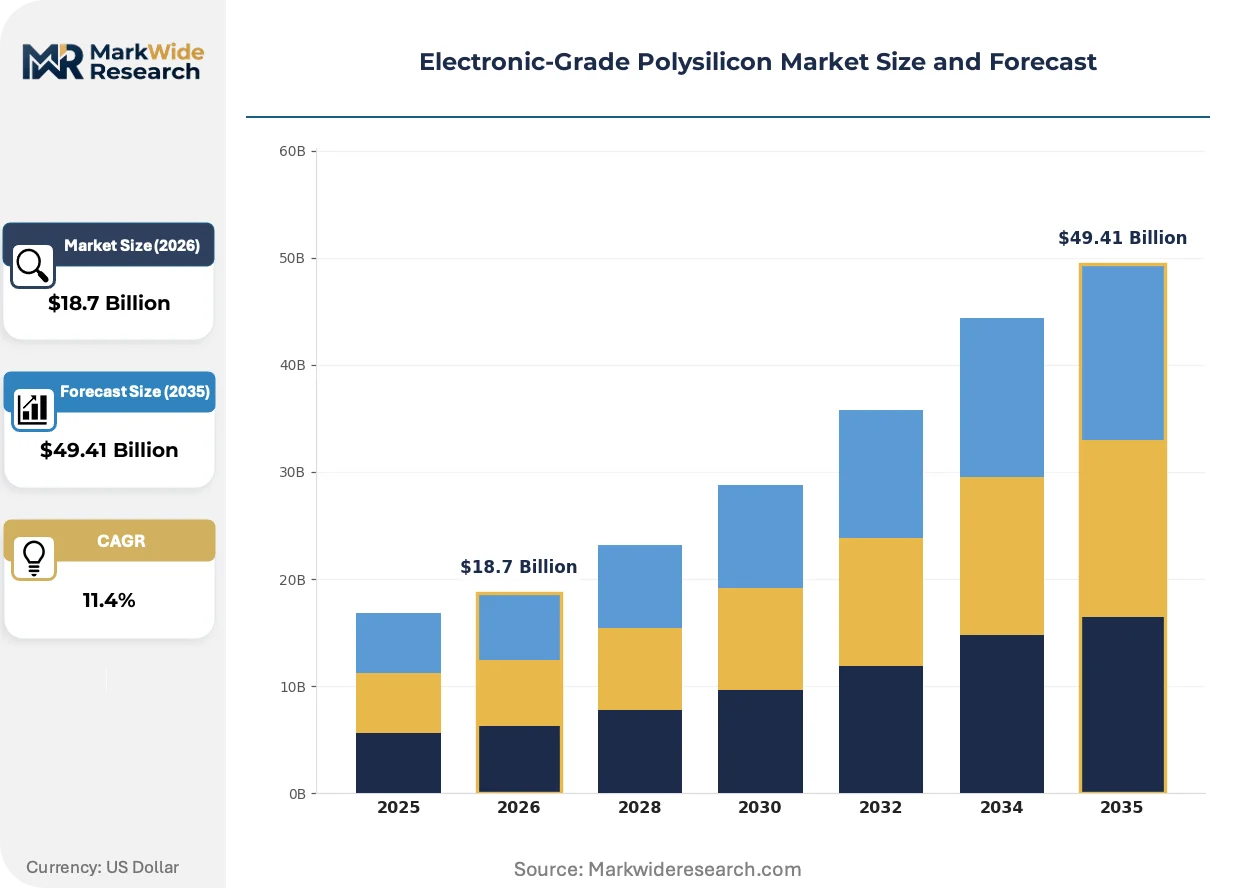
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, Solar Grade, Electronic Grade, Recycled Grade Application: Solar Cells, Semiconductors, Display Panels, Photovoltaics Purity Level: 2N, 4N, 6N, 8N Delivery Mode: Bulk Supply, Customized Supply, Long-term Contracts, Spot Market Sales |
| Companies Covered | OCI Company Ltd., Daqo New Energy Corp., Wacker Chemie AG, East Hope Group, Tongwei Co., Ltd., Hemlock Semiconductor, REC Silicon ASA, Mitsubishi Materials, Tokuyama Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic-Grade Polysilicon Market Emerging Trajectories
Process digitization and closed-loop quality control are compressing impurity detection timelines from batch sampling to real-time spectroscopic monitoring. These advances are reshaping how polysilicon producers manage customer qualification data and reactor parametric control.
Digital twin platforms are digitizing Siemens reactor operations across temperature, pressure, and gas-flow parameters. Leading wafer manufacturers now require suppliers to share live process data through secure API connections. This transparency is digitizing contractual quality assurance and reducing incoming inspection burdens at fabs.
The EU's F-Gas Regulation is tightening reporting requirements for fluorinated compounds used in polysilicon etching and chamber cleaning. Producers are reformulating process chemistries to reduce NF3 and SF6 intensities. German and French semiconductor clusters are piloting closed-loop recycling systems to maintain compliance without sacrificing throughput.
Long-term supply agreements are displacing spot market transactions for electronic-grade volumes. Memory and logic fabs are locking in five to seven year contracts with fixed purity-grade specifications. This contractual shift is most visible in South Korea's Gyeonggi Province, where Samsung and SK Hynix are consolidating supplier panels to three to four qualified partners per purity tier.
Electronic-Grade Polysilicon Market Segmentation
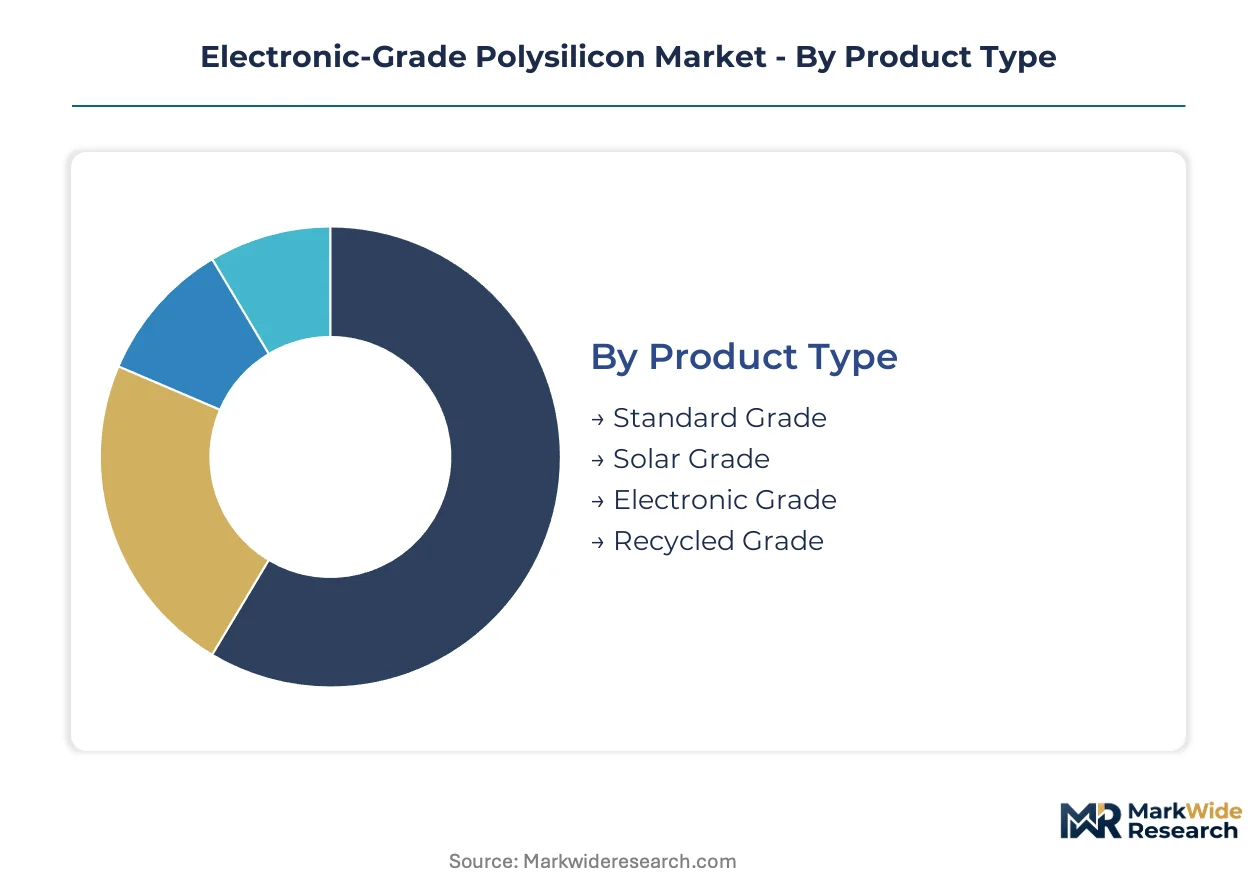
Electronic-grade polysilicon segmentation reveals how purity thresholds, delivery commitments, and end-use specifications fragment procurement patterns across semiconductor and solar value chains. Understanding these divides exposes where reactor capacity earns premium returns versus commodity pricing.
Product Type:
Cycle times vary dramatically: recycled grade turns inventory weekly while electronic grade locks capital for years in qualification pipelines.
- Electronic Grade:Hyper-pure silicon at 9N to 11N purity bands serves epitaxial wafer growth for advanced logic chips. Taiwan Semiconductor Manufacturing Company and Samsung Foundry concentrate demand here for nodes below 7nm, absorbing three-to-five-year supplier certification timelines.
- Solar Grade:6N to 7N purity material dominates photovoltaic ingot pulling with faster customer onboarding. Tongwei Co., Ltd. and Daqo New Energy Corp. anchor supply into the Yangtze River Delta cluster where domestic solar wafer expansion concentrates offtake.
- Standard Grade:Metallurgical-grade feedstock for industrial silicon applications operates on spot pricing with minimal purification overhead.
- Recycled Grade:Reclaimed polysilicon from semiconductor kerf loss and ingot tops feeds lower-tier solar and metallurgical markets.
Electronic grade anchors the volume base while recycled grade gains share at the steepest rate as circular economy mandates tighten across the EU and China.
Application:
Cost tier segmentation separates qualification-heavy semiconductor demand from price-sensitive photovoltaic procurement.
- Semiconductors:Memory and logic fabs in Gyeonggi Province and Taiwan lock in five-to-seven-year contracts with fixed 9N+ specifications. Samsung and SK Hynix now consolidate supplier panels to three qualified partners per purity tier.
- Solar Cells:Photovoltaic manufacturers prioritize tonnage over trace impurity thresholds, purchasing 6N material through annual framework agreements.
- Display Panels:TFT-LCD and OLED fabs consume mid-purity polysilicon for thin-film transistor deposition.
- Photovoltaics:Utility-scale module assembly pulls larger tonnages at lower purity thresholds than semiconductor applications.
Photovoltaics anchors the volume base while semiconductors gains share at the steepest rate as advanced node migration accelerates.
Purity Level:
Customer type fragmentation splits between memory fabs standardizing on 8N and logic foundries pushing toward 11N for 2nm ramps.
- 8N:Advanced node logic and memory fabs standardize on this grade for current-generation wafer manufacturing. Wacker Chemie AG's Burghausen facility anchors European supply with decades of customer qualification.
- 6N:Solar cell manufacturers and display panel fabs accept this threshold where energy consumption per kilogram drops significantly.
- 2N:Industrial silicon applications require minimal purification.
- 4N:Intermediate grade serves specialty electronics and research applications.
8N anchors the volume base while 11N-equivalent specifications gains share at the steepest rate as 2nm qualification cycles advance.
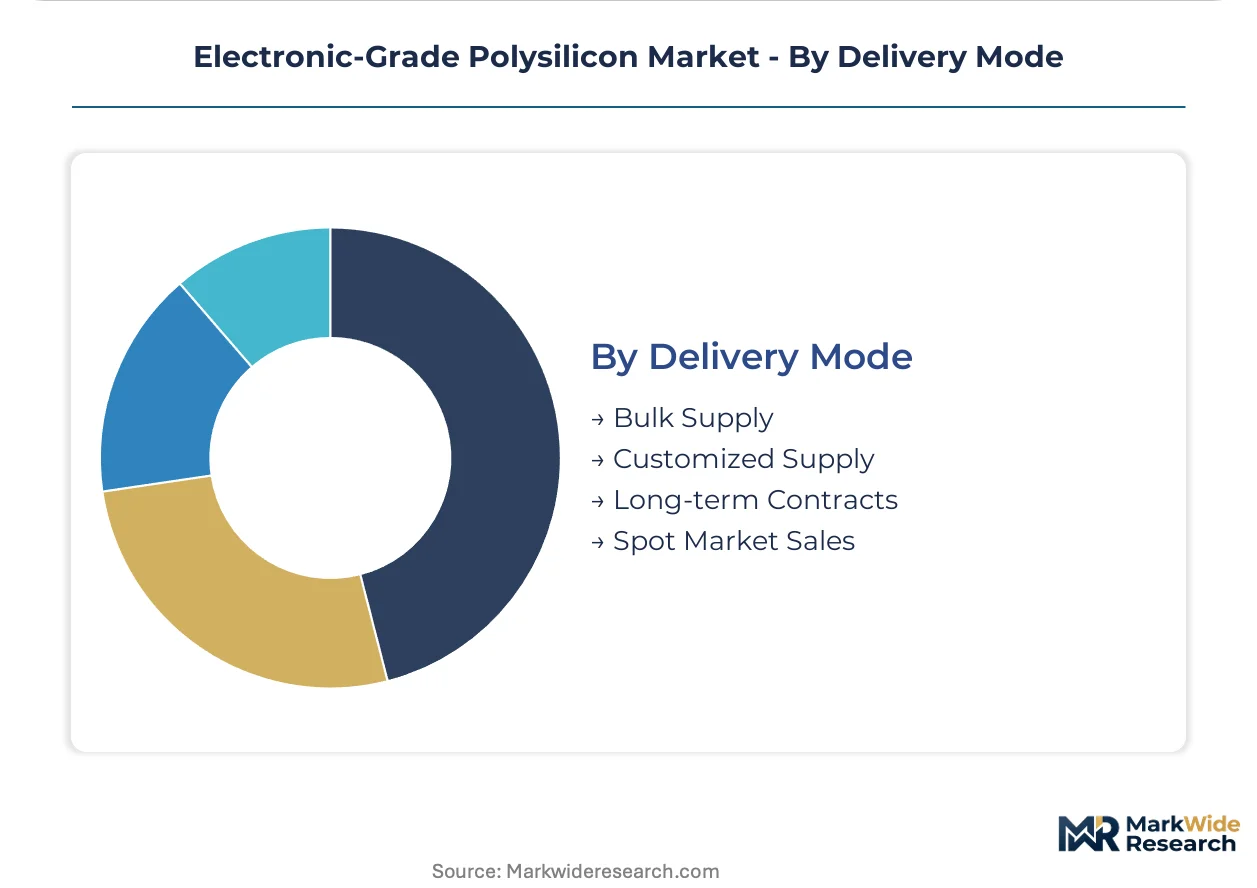
Delivery Mode:
Supply concentration shapes contractual structures: bulk supply dominates solar while semiconductors demand customized lot tracking.
- Long-term Contracts:Memory and logic fabs in South Korea's Gyeonggi Province displace spot transactions with five-to-seven-year agreements. Samsung and SK Hynix now require live process data sharing through secure API connections.
- Customized Supply:Semiconductor customers demand lot-level impurity certificates and parametric reactor data for each batch.
- Bulk Supply:Photovoltaic manufacturers purchase undifferentiated tonnage on quarterly pricing.
- Spot Market Sales:Traders and smaller solar assemblers absorb surplus inventory during capacity overbuilds.
Long-term contracts anchors the volume base while customized supply gains share at the steepest rate as digital twin integration spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT energy-intensity standards and dual carbon goals are reshaping purification capacity deployment across East Asia. Semiconductor fabs in Taiwan and South Korea are tightening supplier qualification requirements while European carbon border adjustments threaten cost structures for China-integrated producers.
China
Yangtze River Delta fabs are absorbing expanded electronic-grade output from Xinjiang and Inner Mongolia purification complexes. MIIT enforces GB standards for energy consumption per kilogram of polysilicon produced. Daqo New Energy Corp. and Tongwei Co., Ltd. anchor supply through dedicated Siemens reactor lines serving domestic semiconductor foundries.
South Korea
Samsung Foundry and SK Hynix are consolidating supplier panels to three qualified partners per purity tier for Gyeonggi Province memory and logic fabs. The Korean government extends semiconductor material subsidies through K-Semiconductor Belt initiatives. Pyeongtaek and Yongin clusters now require live process data sharing through secure API connections from polysilicon vendors.
Taiwan
TSMC's 2nm ramp-up in Hsinchu Science Park is driving 9N+ qualification cycles spanning three to five years. The National Science and Technology Council coordinates supply chain security reviews for critical materials. Southern Taiwan Science Park expansion in Tainan is absorbing dedicated reactor lines from new polysilicon entrants.
Germany
Wacker Chemie AG's Burghausen facility anchors European electronic-grade supply with decades of customer qualification heritage. The EU F-Gas Regulation and REACH framework govern trichlorosilane handling and fluorinated compound reporting. Saxony's Silicon Saxony cluster in Dresden links polysilicon purification to advanced wafer manufacturing for automotive power electronics.
United States
Hemlock Semiconductor maintains polysilicon purification operations serving domestic semiconductor fabs amid CHIPS Act subsidy deployment. EPA regulations and OSHA standards shape chlorosilane handling protocols across Michigan and Tennessee production sites. Arizona's Phoenix metro semiconductor corridor is absorbing new electronic-grade supply commitments for Intel and TSMC fabs under construction.
Electronic-Grade Polysilicon Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where purification specialists and integrated energy-materials conglomerates occupy distinct competitive spaces. The market consolidates around four to six qualified suppliers per major semiconductor fab cluster, with entry barriers rising through extended certification timelines. Two strategic archetypes dominate: Siemens process specialists with decades of customer qualification heritage, and integrated producers leveraging captive metallurgical-grade silicon feedstock. Competitive moves center on long-term contract lock-ins with memory and logic fabs, plus geographic diversification to escape carbon border exposure.
Among German-anchored purification specialists, Wacker Chemie AG exemplifies the qualification-heavy archetype with Burghausen facility heritage. Chinese integrated producers Daqo New Energy Corp. and Tongwei Co., Ltd. represent the scale-driven tier, leveraging upstream metallurgical-grade control into electronic-grade reactor expansion. South Korea's OCI Company Ltd. occupies a position between these poles with regional customer proximity advantages. These three company types illustrate how geographic feedstock integration, legacy qualification assets, and fab-cluster proximity define competitive positioning in electronic-grade supply.
| Leading Market Players |
|---|
| OCI Company Ltd. |
| Daqo New Energy Corp. |
| Wacker Chemie AG |
| East Hope Group |
| Tongwei Co., Ltd. |
| Hemlock Semiconductor |
| REC Silicon ASA |
| Mitsubishi Materials |
| Tokuyama Corporation |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Busan container freight corridors carry metallurgical-grade silicon feedstock and trichlorosilane precursors that determine landed cost spreads between Yangtze River Delta purification complexes and Gyeonggi Province wafer fabs. These logistics cost dynamics concentrate pricing power with integrated producers controlling both Xinjiang smelting and coastal reactor operations, while fragmenting procurement leverage among memory and logic fabs locked into multi-year qualification cycles.
Pricing Analysis
Geographic price spreads between China-integrated output and European-qualified material reflect certification heritage premiums and carbon border exposure risks. Three-tier pricing structure across 11N premium, 9N standard, and 6N economy levels separates semiconductor epitaxial wafer contracts from solar-grade framework agreements. Cost compression in 6N solar material is intensifying because Tongwei and Daqo are diverting reactor capacity toward electronic-grade qualification. Memory fabs in South Korea exhibit least price sensitivity due to five-to-seven-year contract lock-ins, while photovoltaic assemblers in the Yangtze Delta remain most price-sensitive with quarterly spot negotiations.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for polysilicon purification specialists. Metallurgical-grade silicon feedstock concentrates in Xinjiang and Yunnan provinces, while chlorosilane distillation capacity clusters in Jiangsu and Sichuan. Reactor engineering talent draws from German and Japanese university pipelines with semiconductor-materials training. Single-source vulnerability persists for 9N+ qualification heritage concentrated at Wacker Chemie AG's Burghausen facility. Distribution runs through long-term contract structures for semiconductor customers and bulk quarterly shipments for photovoltaic offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic-grade polysilicon procurement is shifting toward platform-economics dynamics where live process data sharing through secure API connections creates supplier-fab interoperability. This ecosystem inflection rewards purification specialists investing in digital twin integration ahead of Samsung and TSMC mandating real-time parametric transparency.
For Market Incumbents: Build qualification moats by extending 11N reactor line dedication to TSMC's 2nm ramp-up and Samsung Foundry's advanced logic expansion. Anchor defensive positioning through backward integration into Xinjiang metallurgical-grade silicon smelting to escape carbon border adjustment exposure. Prioritize certification investment in India's Gujarat semiconductor subsidy corridor before PLI scheme windows narrow. Channel control through exclusive long-term supply agreements with SK Hynix and Micron Technology blocks emerging entrant access.
For New Entrants and Emerging Players: Establish a beachhead in India's Tamil Nadu polysilicon purification corridor where land and power concessions reduce capital intensity for Siemens reactor deployment. Target silicon carbide precursor supply for automotive power electronics as the most penetrable segment, bypassing three-to-five-year semiconductor fab qualification timelines. Pursue joint venture structures with REC Silicon for fluidized bed reactor technology licensing to compress process development cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with dormant chlorosilane distillation assets and existing semiconductor customer relationships. Long-term viability over the next decade hinges on verified low-carbon process chains qualifying for EU F-Gas Regulation compliance and CHIPS Act subsidy eligibility. Watch for inflection signals when carbon border adjustment mechanisms in destination markets trigger geographic sourcing shifts away from Xinjiang-integrated supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five-to-seven-year contracts with Samsung and SK Hynix lock in 9N+ volume commitments. |
| Backward Integration | Captive Xinjiang metallurgical-grade silicon smelting insulates Daqo from carbon border exposure. |
| Digital Twin Integration | Live API data sharing with TSMC and Samsung Foundry reduces incoming inspection burdens. |
| Fluidized Bed Reactor Scale-Up | REC Silicon pilots continuous production runs reducing specific energy consumption per kilogram. |
| Geographic Diversification | Gujarat and Tamil Nadu investments escape carbon border adjustments threatening China-integrated cost structures. |
Methodological Framework
A standing panel of polysilicon plant managers, semiconductor procurement leads at memory and logic fabs, chlorosilane distribution channel partners, and technical R&D directors at purification specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from MIIT energy-intensity disclosures, EU REACH framework filings, SEC 10-K extracts from listed producers, and Korean semiconductor material subsidy program documentation. Bottom-up reactor capacity modeling and top-down wafer fab consumption estimates were triangulated against customs trade data for metallurgical-grade silicon flows.
Scenario-bracketing framed projections across the analysis window by modeling conservative, baseline, and accelerated advanced node migration paths. Segmentation dimensions included purity level tiers, application splits between semiconductors and photovoltaics, delivery mode structures, and regional production hub configurations. CAGRs were derived from regression analysis of historical capacity expansion against wafer fab equipment spending patterns. Industry-specific forecast inputs incorporated MIIT dual carbon policy implementation timelines and EU F-Gas Regulation phase-down schedules.
Stress conditions across trichlorosilane price volatility bands, carbon border adjustment trigger thresholds, and semiconductor fab qualification cycle extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Siemens reactor energy efficiency improvements and fluidized bed reactor commercialization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Electronic Ceramics Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Gallium Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Semiconductor Grade Neon Gas Market