
 Global Semiconductor Thermal Evaporators Market | 2026-2036
Global Semiconductor Thermal Evaporators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor Thermal Evaporators Market Outlook
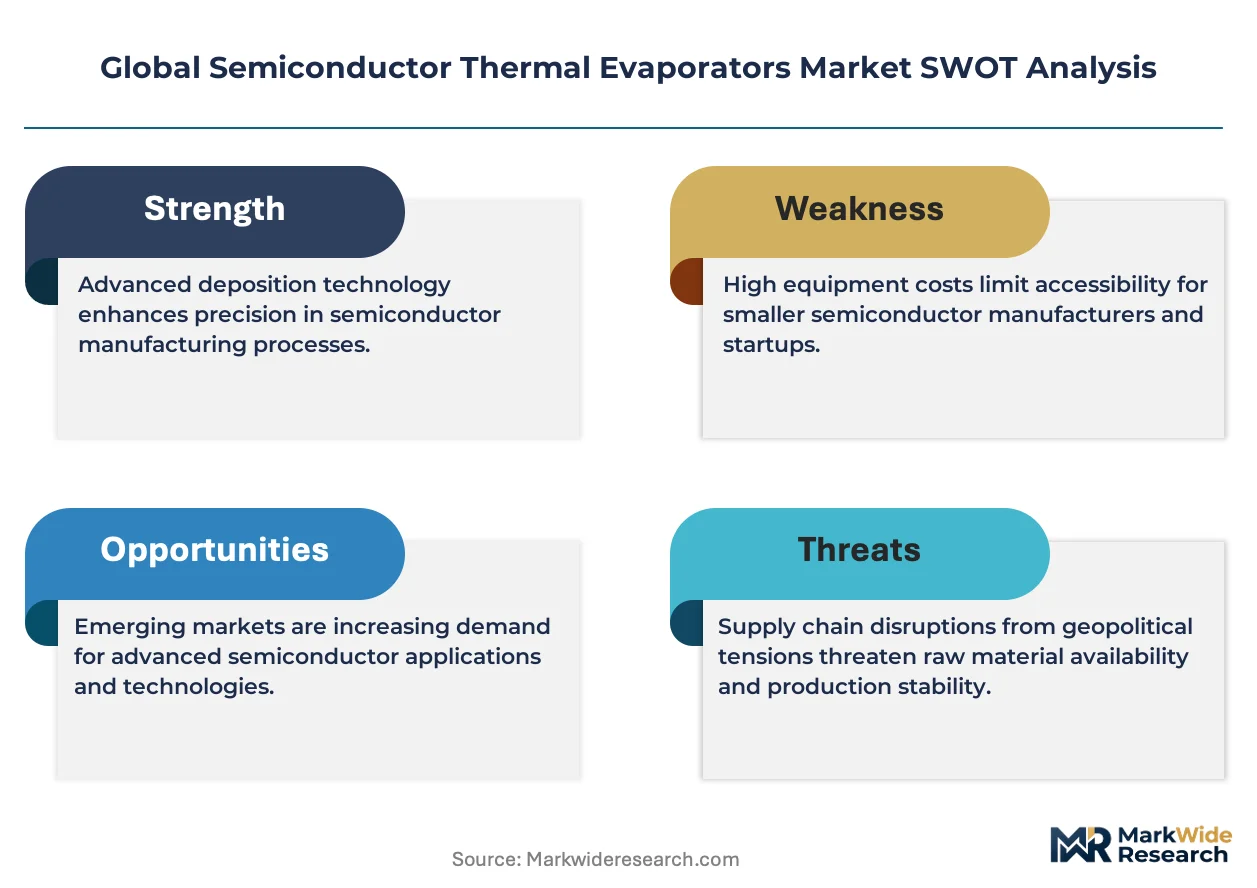
Transition to gate-all-around transistor architectures is reshaping thin-film deposition requirements across leading-edge fabs. AJA International leverages its Massachusetts-based engineering base to sustain dominance in precision multi-source systems for research laboratories. Kurt J. Lesker Company anchors North American supply through its extensive catalog of thermal evaporation components and chamber integrations. Denton Vacuum differentiates via specialized configurations serving compound semiconductor foundries with exacting uniformity specifications.
Semiconductor thermal evaporators are vacuum deposition systems that heat source materials to their evaporation point, typically operating at pressures below 10^-6 Torr, to form controlled thin films on wafer substrates for device metallization and barrier layers. The equipment serves as foundational infrastructure for creating ohmic contacts, Schottky barriers, and protective coatings essential to functional chip performance. E-beam thermal evaporators command premium positioning due to their compatibility with refractory metals and alloys demanded by advanced memory device stacks. Foundry end users represent the most concentrated demand pool, with integrated device manufacturers trailing in absolute equipment procurement volume but exhibiting higher average selling prices for customized configurations.
REACH compliance in Europe and EPA hazardous substance guidelines in the United States constrain permissible evaporation source chemistries and chamber material specifications, elevating equipment qualification burdens for vendors seeking cross-border sales. Japan's METI semiconductor revitalization framework and South Korea's K-Semiconductor Belt initiative channel public investment toward domestic thermal evaporation capabilities, altering traditional procurement patterns. Stakeholders must monitor how export control expansions affecting deposition technology alter competitive access to Chinese fabs, which remain the largest volume purchasers despite geopolitical friction.
Market Dynamics
Gate-all-around transistor architectures are forcing thermal evaporator vendors to retool deposition precision specifications, as leading-edge fabs demand atomic-layer uniformity across three-dimensional fin structures that legacy planar tools cannot achieve.
Growth Catalysts
- Advanced Node Expansion:Taiwan and South Korea foundries are scaling 2nm-class production lines, each requiring thermal evaporation systems for barrier metal stacks. Equipment procurement cycles from these clusters drive sustained order volume.
- EU Chips Act Capital Flows:The European framework redirects public investment toward domestic semiconductor equipment manufacturing, creating qualified demand for thermal evaporator vendors establishing EU-based assembly and service operations.
- Refractory Metal Compatibility:E-beam thermal evaporators enable deposition of tungsten and molybdenum alloys essential for advanced memory device architectures, pulling upgrade demand from DRAM and NAND flash manufacturers.
Market Restraints
- High-Purity Source Material Volatility:Prices for sputtering-grade aluminum and titanium pellets fluctuate with mining output constraints, compressing equipment margins when vendors absorb input cost spikes.
- East Asian Supply Concentration:Over 70% of precision vacuum chamber fabrication capacity resides in Japan and South Korea, exposing non-regional vendors to extended lead times and freight cost escalation.
- Refractory Metal Deposition Limitations:Conventional resistive heating sources cannot achieve evaporation temperatures for high-melting-point alloys, forcing costly e-beam upgrades that price out mid-tier fabs.
Strategic Opportunities
- India Semiconductor Ecosystem:The country's PLI scheme and semiconductor fabrication incentives create virgin demand territory as domestic fabs commission their first thermal evaporation lines for trailing-edge logic and power devices.
- Compound Semiconductor Divergence:Silicon carbide and gallium nitride device foundries require specialized thermal evaporation configurations for ohmic contact formation, opening premium customization revenue streams distinct from silicon CMOS commodity sales.
- Remote Diagnostics Integration:Predictive maintenance platforms leveraging chamber sensor telemetry enable vendors to unbundle service contracts and capture recurring software revenue from fab operators prioritizing uptime guarantees.
Industry Challenges
- Vacuum Technology Talent Scarcity:The specialized skill set combining thin-film physics, cryogenic engineering, and ultra-high-voltage safety certification faces generational attrition, constraining vendor R&D and field service scaling.
- Legacy Chamber Integration Complexity:Retrofitting 200mm-era thermal evaporators with modern source crucible configurations demands extensive mechanical redesign, prolonging qualification timelines for fabs seeking capital preservation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor Thermal Evaporators Market |
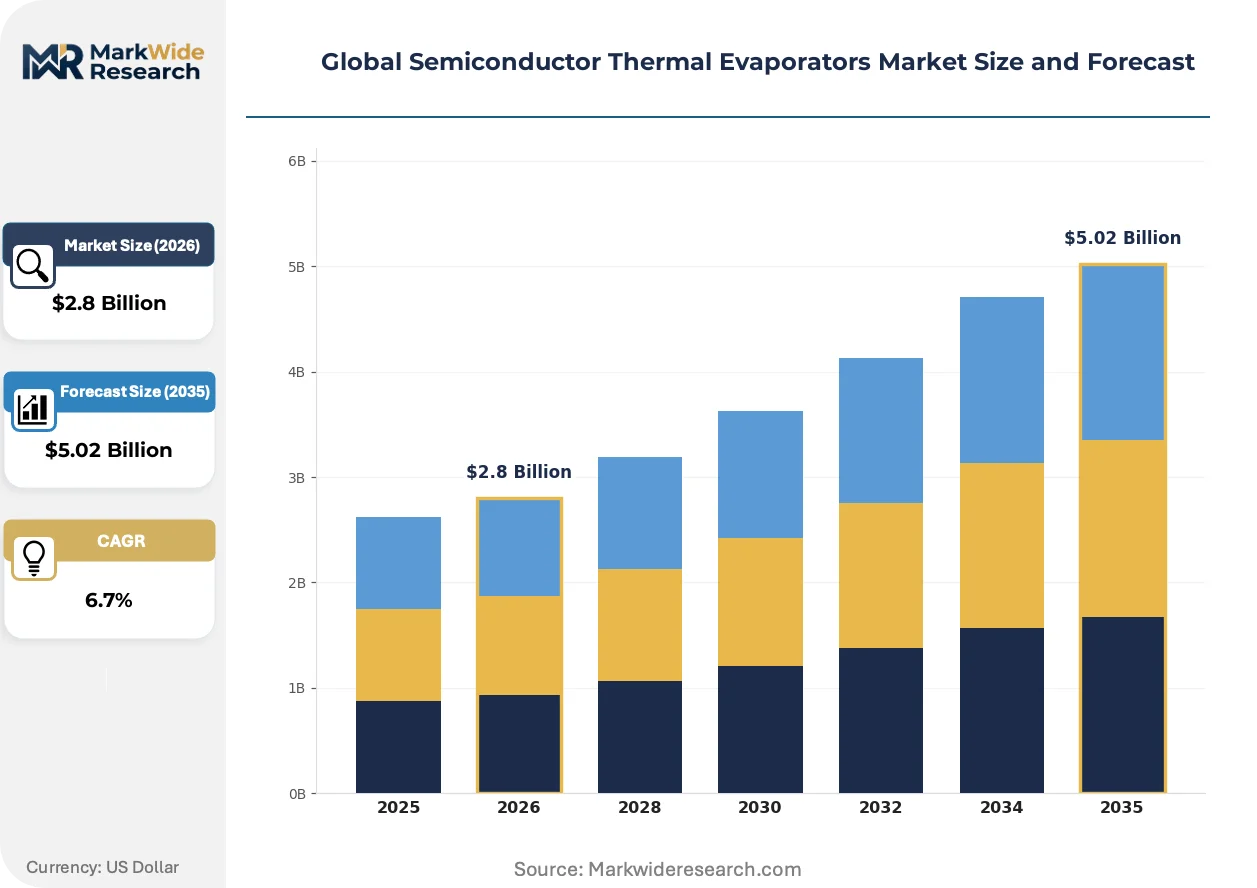
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Source, Dual Source, Multi Source, E-Beam End User: Foundries, Integrated Device Manufacturers, Research Laboratories, Electronics Manufacturers Technology: Conventional, Flash, Pulsed Laser, Molecular Beam Application: Memory Devices, Display Technology, Power Devices, Photovoltaics |
| Companies Covered | AJA International, Kurt J. Lesker Company, Denton Vacuum, Temescal, Semicore Equipment, CHA Industries, PVD Products, Mustang Vacuum Systems, Blue Wave Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor Thermal Evaporators Market Strategic Shifts
Thin-film deposition equipment is undergoing functional specialization as process windows tighten and fab operators demand tool-level data integration. Three convergent developments are redefining competitive positioning.
Multi-source thermal evaporation is migrating from batch-oriented research configurations toward continuous in-line systems for compound semiconductor production. GaN-on-SiC foundries in the United States and Japan are adopting these platforms to reduce wafer handling contamination. The technology is migrating from discrete chamber architectures toward integrated cluster tools that combine evaporation with in-situ metrology, compressing cycle time and qualification overhead.
REACH substance restrictions in Europe and EPA hazardous waste guidelines in the United States are constraining permissible evaporation source chemistries and mandating closed-loop material recovery systems. Equipment vendors must now engineer chamber designs compatible with reclaimed precursor materials, elevating R&D expenditure. Compound semiconductor fabs in Germany and France face the steepest compliance burdens as regulators tighten reporting thresholds for heavy metal residues.
Consolidated procurement consortia among memory manufacturers are unbundling equipment purchasing from long-term service agreements, forcing vendors to compete on upfront capital cost while margin pressure migrates toward aftermarket parts and software subscriptions. This purchasing model shift is most visible among South Korean DRAM producers, who now negotiate multi-fab framework contracts with centralized technical specifications and decentralized installation scheduling.
Global Semiconductor Thermal Evaporators Market Segmentation
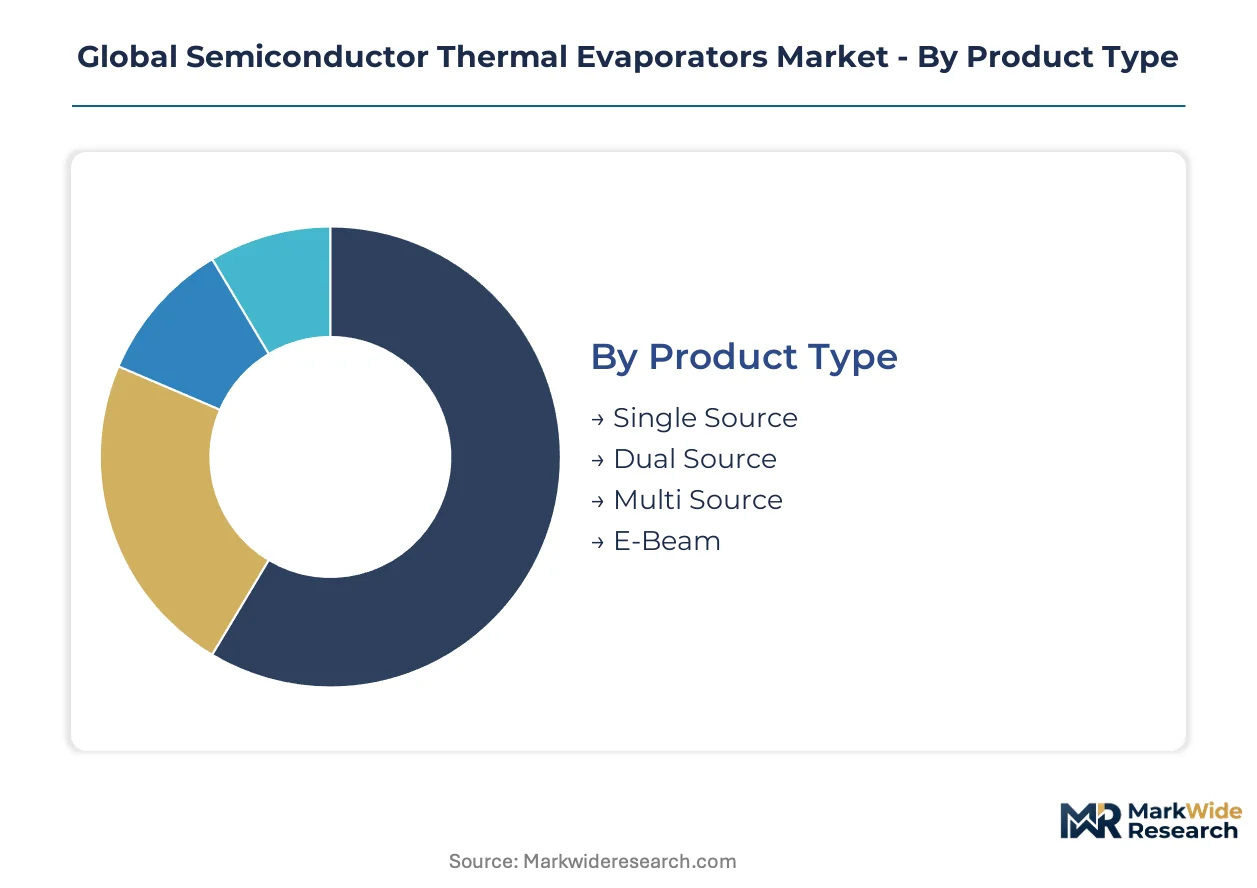
Thermal evaporator segmentation reveals how equipment specifications diverge across customer sophistication levels and process requirements. Configuration choices directly determine compatibility with advanced node roadmaps and compound semiconductor manufacturing protocols.
Product Type:
Equipment cost tier and deposition complexity drive the product type hierarchy, with source multiplicity correlating to wafer throughput and film stack sophistication.
- E-Beam:Electron beam heating achieves temperatures exceeding 3000°C for refractory metal deposition, enabling tungsten and molybdenum alloys essential for DRAM capacitor electrodes and NAND wordline stacks. Taiwan foundries command the dominant procurement volume as 2nm-class memory production scales.
- Multi Source:Simultaneous or sequential evaporation from four to eight crucible positions supports complex barrier metal stacks without vacuum breaks. South Korea's memory manufacturers favor these configurations for high-volume throughput in 3D NAND fabrication.
- Dual Source:Two-position crucible arrangements serve mid-tier logic foundries depositing binary alloy contacts. The configuration balances capital efficiency against film stack flexibility for trailing-edge nodes.
- Single Source:Single-crucible systems dominate research laboratory installations and pilot line qualification. Universities in Germany and Japan deploy these platforms for materials science exploration.
E-Beam holds installed capacity across leading-edge memory fabs. Multi Source is rotating up the share rankings as compound semiconductor foundries adopt co-evaporation for ohmic contact optimization.
End User:
Customer type determines pricing tolerance, customization depth, and service contract structures across the equipment base.
- Foundries:Pure-play wafer manufacturers operate thermal evaporators at utilization rates exceeding 85%, driving premium specifications for mean-time-between-failures and automated wafer handling. Taiwan Semiconductor Manufacturing and Samsung Foundry anchor procurement volume with framework agreements spanning multiple fab sites.
- Research Laboratories:Academic and national laboratory installations prioritize deposition flexibility over throughput, accepting manual wafer loading and extensive recipe parameter adjustment. MIT.nano and Japan's NIMS facilities represent concentrated demand clusters for precision multi-source configurations.
- Integrated Device Manufacturers:Captive fab operators at Texas Instruments and Infineon Technologies blend high-volume production with proprietary process integration, requiring vendor collaboration on chamber customization.
- Electronics Manufacturers:Contract assemblers and subsystem producers deploy thermal evaporation for packaging metallization and interconnect fabrication, typically at lower purity grades than wafer-level processing.
Foundries hold installed capacity. Research Laboratories is rotating up the share rankings as government semiconductor initiatives expand materials science infrastructure.
Technology:
Deposition physics and energy delivery mechanism define the technology landscape, with each approach commanding distinct process windows.
- Molecular Beam:Ultra-high vacuum conditions below 10^-9 Torr enable epitaxial film growth with atomic-layer precision. GaN-on-SiC foundries in the United States and Japan adopt these systems for high-electron-mobility transistor fabrication.
- Flash:Rapid thermal pulse evaporation minimizes interdiffusion in delicate multilayer stacks. Memory device manufacturers apply this technique for ferroelectric capacitor deposition.
- Pulsed Laser:Laser ablation transfer enables stoichiometric compound film deposition from ceramic targets. Oxide semiconductor research programs in France and South Korea drive niche adoption.
- Conventional:Resistive heating remains the cost-optimized standard for aluminum and gold metallization. Mature logic nodes and packaging applications sustain residual demand.
Molecular Beam holds installed capacity. Flash is rotating up the share rankings as ferroelectric memory architectures advance toward commercialization.
Application:
Device category determines metal stack composition, thickness uniformity requirements, and contamination sensitivity thresholds.
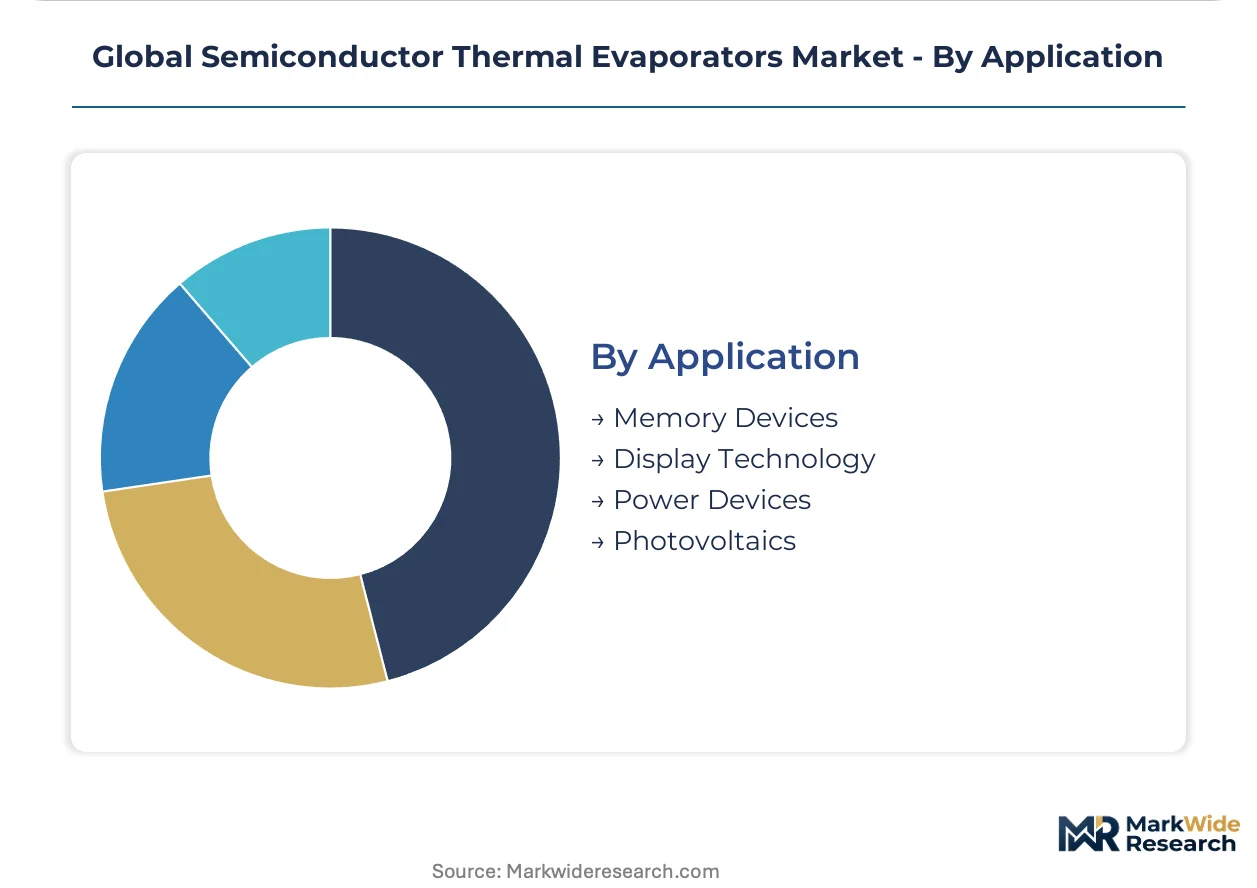
- Memory Devices:DRAM and NAND flash production consumes thermal evaporators for capacitor electrode, wordline, and barrier metal deposition. Three-dimensional cell stacking demands conformal coverage across extreme aspect ratios. South Korean producers Samsung and SK Hynix anchor demand concentration.
- Power Devices:Silicon carbide MOSFETs and IGBTs require nickel-based ohmic contacts and thick aluminum interconnects. Wolfspeed's expansion in North Carolina and Infineon's Kulim facility drive specialized equipment procurement.
- Display Technology:OLED and microLED manufacturing employs thermal evaporation for organic emitter layers and transparent electrode deposition. South Korea's display panel producers sustain regional demand concentration.
- Photovoltaics:Solar cell metallization applies thermal evaporation for back-surface-field and contact grid formation. PERC and TOPCon cell architectures in China sustain volume requirements.
Memory Devices holds installed capacity. Power Devices is rotating up the share rankings as silicon carbide capacity expansion accelerates across automotive-qualified foundries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese vacuum chamber fabricators export precision components to Taiwanese foundry clusters, sustaining a trade corridor that channels thermal evaporator subsystems toward Hsinchu and Tainan production facilities.
United States
Domestic compound semiconductor foundries in North Carolina and Texas drive specialized equipment procurement for silicon carbide device fabrication. The CHIPS and Science Act directs federal investment toward domestic deposition tool manufacturing. MIT.nano and Lawrence Berkeley National Laboratory anchor research demand in Greater Boston and the San Francisco Bay Area.
Taiwan
TSMC and United Microelectronics operate thermal evaporators at utilization rates exceeding 85% across advanced node production lines. The National Development Council coordinates public-private partnerships for domestic equipment supply chain development. Hsinchu Science Park concentrates the highest density of multi-source thermal evaporation installations worldwide.
South Korea
Samsung Foundry and SK Hynix scale 2nm-class memory production requiring e-beam thermal evaporators for refractory metal deposition. The K-Semiconductor Belt initiative channels government funding toward domestic thermal evaporation capabilities. Pyeongtaek and Yongin host concentrated fab complexes driving framework procurement agreements.
Japan
Tokyo Electron and Canon subsidiary operations sustain precision vacuum component fabrication for export markets. METI's semiconductor revitalization framework subsidizes domestic equipment vendor R&D programs. Kyoto and Osaka prefectures maintain specialized chamber manufacturing clusters serving global OEM integration.
Germany
Infineon Technologies and Bosch expand 300mm power device fabrication requiring customized thermal evaporation configurations. REACH compliance mandates constrain permissible evaporation source chemistries and elevate equipment qualification burdens. Dresden and Regensburg anchor the Saxony and Bavarian fab concentrations.
Global Semiconductor Thermal Evaporators Market Competitive Environment
On the supply side, the industry is tiered between precision multi-source specialists and volume-oriented standard system fabricators. Massachusetts-based engineering operations and South Korean manufacturing scale represent distinct capability anchors. Strategic archetypes include research-laboratory precision vendors, memory-fab high-throughput suppliers, and compound-semiconductor customization specialists. Dominant competitive moves encompass geographic expansion into Indian and European greenfield markets and technology licensing partnerships for remote diagnostics integration.
Within the precision multi-source tier, AJA International and Denton Vacuum exemplify engineering-intensive positioning anchored in North American fabrication. Kurt J. Lesker Company occupies a distinct catalog-based position serving component and chamber integration demand across research and production segments. These three entities represent contrasting strategic postures: AJA International and Denton Vacuum sit within specialized configuration domains, while Kurt J. Lesker Company anchors a broader supply function across thermal evaporation subsystems.
| Leading Market Players |
|---|
| AJA International |
| Kurt J. Lesker Company |
| Denton Vacuum |
| Temescal |
| Semicore Equipment |
| CHA Industries |
| PVD Products |
| Mustang Vacuum Systems |
| Blue Wave Semiconductors |
| Others |
Value Chain & Pricing Dynamics
Japanese precision vacuum chamber fabricators export over seventy percent of global capacity, concentrating margin capture upstream while equipment OEMs face compressed assembly margins and extended lead time penalties. Taiwan and South Korea foundries absorb these cost escalations through framework procurement agreements that lock in volume commitments against price volatility.
Pricing Analysis
Next-generation e-beam thermal evaporators command substantial premiums over conventional resistive-heating systems, while legacy single-source configurations face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels separates molecular beam epitaxy platforms from multi-source production tools and basic research-grade units. Price differentiation rests on chamber uniformity specifications and mean-time-between-failures guarantees. Cost compression in mid-tier dual-source equipment is intensifying because South Korean memory manufacturers are consolidating procurement consortia. Research laboratories exhibit lowest price sensitivity, prioritizing deposition flexibility over capital efficiency.
Supply Chain Analysis
Export control expansions affecting deposition technology are limiting competitive access to Chinese fabs, fragmenting traditional procurement corridors and forcing vendors to duplicate certification efforts across regulatory jurisdictions. Precision vacuum chamber fabrication concentrates in Japan and South Korea, with specialized source crucible suppliers anchored in Germany and the United States. Raw material dependencies include sputtering-grade aluminum pellets, titanium sponge, and refractory metal wire feedstock. Single-source vulnerability around Japanese chamber fabricators exposes non-regional vendors to freight cost escalation. Distribution runs through direct OEM sales for leading-edge foundries and catalog distributors serving research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as thermal evaporator vendors unbundle hardware from predictive maintenance software, creating recurring revenue ecosystems that mirror semiconductor equipment industry-wide shifts toward outcome-based service models.
For Market Incumbents: Harden defensive moats by deepening backward integration into precision vacuum chamber fabrication, capturing margin pools currently retained by Japanese subsystem suppliers. Accelerate certification investment for REACH-compliant closed-loop material recovery systems before European qualification thresholds tighten. Consolidate channel control through exclusive service partnerships with Taiwan foundry clusters to forestall emerging entrant access.
For New Entrants and Emerging Players: Pursue virgin demand territory in India's semiconductor ecosystem, where domestic fabs commission first thermal evaporation lines without incumbent vendor relationships. Target compound semiconductor customization for silicon carbide ohmic contact formation, a premium segment distinct from commoditized silicon CMOS sales. Establish go-to-market presence through technology licensing partnerships for remote diagnostics integration rather than capital-intensive hardware manufacturing.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision multi-source specialists possessing Massachusetts-based engineering talent and established research laboratory customer bases. Long-term viability hinges on software subscription revenue attachment rates and aftermarket parts penetration rather than cyclical equipment sales. Watch for inflection signals in e-beam thermal evaporator upgrade cycles tied to 2nm-class memory production scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Chamber Fabrication | Captures margin pools retained by Japanese subsystem suppliers while reducing lead time exposure. |
| Remote Diagnostics Platform Launch | Enables vendors to unbundle service contracts and capture recurring software revenue from TSMC and Samsung. |
| REACH-Compliant Chamber Certification | Opens qualified demand from Infineon and Bosch as European regulators tighten heavy metal reporting thresholds. |
| India Greenfield Manufacturing Footprint | Positions vendors to serve domestic fabs commissioning first thermal evaporation lines under PLI incentives. |
| Compound Semiconductor Customization Partnership | Creates premium revenue streams from Wolfspeed and Coherent for silicon carbide ohmic contact optimization. |
Study Parameters
A spread of perspectives from equipment procurement directors at Taiwan foundries, vacuum technology R&D leads, chamber fabrication specialists in Japan, and compound semiconductor process engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings from deposition equipment OEMs, METI semiconductor revitalization framework disclosures, and EU Chips Act implementation reports. Bottom-up equipment shipment tallies triangulated against top-down fab capacity expansion announcements.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation across product type, end user, technology, and application dimensions. CAGRs derived from equipment procurement cycle analysis and foundry capital expenditure trajectories. Industry-specific inputs included e-beam thermal evaporator upgrade rates tied to memory node transitions and molecular beam epitaxy adoption curves for GaN-on-SiC fabrication.
Sensitivities concentrate around export control enforcement intensity, refractory metal source material price volatility, and generational attrition in vacuum technology talent pools. Forecasts reflect documented assumptions regarding foundry utilization rates and government subsidy program continuity. Material shifts in Sino-American technology access restrictions or sudden Japanese chamber fabrication capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Photolithography Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
Asia-Pacific Semiconductor Etch Equipment Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Global Equipment Front End Module (EFEM) Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Europe Chip Mounter Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
Die Bonder Machinery Market
Semiconductor Equipment
Analog and Digital IC Development Tools Market