
 Global Smartphone Cover Glass Market | 2026-2036
Global Smartphone Cover Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smartphone Cover Glass Market Outlook
Southeast Asia is fragmenting as a manufacturing zone for cover glass fabrication, with Vietnam and Thailand attracting secondary capacity from Chinese suppliers seeking tariff diversification. Corning Incorporated leverages its proprietary fusion draw process to sustain premium substrate supply across multiple OEM tiers. Biel Crystal Manufactory Limited anchors high-volume tempered glass output for mid-range device programs, while Lens Technology Co Ltd dominates vertically integrated cutting and finishing operations for domestic Chinese brands.
Smartphone cover glass constitutes a chemically strengthened, optically transparent protective barrier typically fabricated from aluminosilicate compositions through ion-exchange processes that create surface compression layers exceeding 800 MPa. Its primary function is to shield underlying display stacks from mechanical damage while maintaining optical clarity and touch sensitivity. Gorilla Glass and tempered glass categories occupy the highest volume tiers, with sapphire glass commanding concentrated margin pools in ultra-premium segments. Foldable phone applications represent the fastest-growing structural demand vector, requiring ultra-thin chemically treated substrates capable of repeated flexural stress.
REACH in Europe, GB standards administered by SAMR in China, and RoHS directives collectively govern chemical composition limits, heavy metal content, and end-of-life recyclability for cover glass materials. These frameworks elevate compliance costs for non-integrated suppliers while advantaging producers with in-house chemical treatment and certification capabilities. Stakeholders must monitor evolving dual carbon goals in China and prospective EU battery-and-device sustainability rules that will extend material traceability requirements upstream into glass supply chains.
Market Dynamics
Foldable display architectures are forcing substrate suppliers to reengineer ion-exchange depth profiles and surface compression mechanics, compressing development cycles while elevating performance thresholds beyond conventional chemically strengthened glass specifications.
Growth Catalysts
- Foldable Device Proliferation:Ultra-thin flexible glass substrates capable of withstanding 200,000+ bending cycles are capturing design wins across flagship smartphone programs, expanding addressable substrate area per device.
- REACH Chemical Compliance:European ECHA mandates on heavy metal content and recyclability are accelerating substitution of legacy soda-lime compositions with advanced aluminosilicate formulations that satisfy material passport requirements.
- Vietnam Display Cluster Expansion:Samsung Display and BOE Technology are concentrating module assembly in Bac Ninh and Thai Nguyen provinces, pulling cover glass finishing operations into proximate supplier parks.
Market Restraints
- Alumina Raw Material Volatility:High-purity aluminum oxide prices fluctuate with bauxite export restrictions from Guinea and Australian mining consolidation, compressing margin buffers for non-integrated tempering houses.
- Chinese Supplier Concentration:Three vertically integrated manufacturers control over 70% of global ion-exchange salt bath capacity, creating single-source vulnerability for European and North American finishers.
- Thickness-Performance Tradeoff:Substrates below 0.3mm exhibit insufficient surface compression layer depth for drop-test certification, limiting penetration into ultra-slim device architectures.
Strategic Opportunities
- India Domestic Manufacturing:PLI scheme incentives for display module assembly under the Ministry of Electronics and Information Technology are attracting cover glass tempering investments in Uttar Pradesh and Tamil Nadu.
- Automotive Display Convergence:Curved instrument cluster and center-stack screens are adopting smartphone-derived chemically strengthened substrates, opening a parallel demand channel with longer product lifecycles.
- EU Battery Regulation Traceability:Upcoming material passport requirements for device sustainability will advantage glass suppliers with certified closed-loop recycling and batch-level chemical documentation systems.
Industry Challenges
- Ion-Exchange Process Engineering Talent:Deep expertise in potassium-for-sodium substitution kinetics and compression layer metrology resides with a narrow cohort of specialists concentrated in Japanese and Korean research institutes.
- Flexural Fatigue Certification Timelines:Foldable glass qualification protocols require 18-24 months of cyclic bending validation under Samsung and Huawei proprietary test matrices, delaying revenue recognition for new substrate entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smartphone Cover Glass Market |
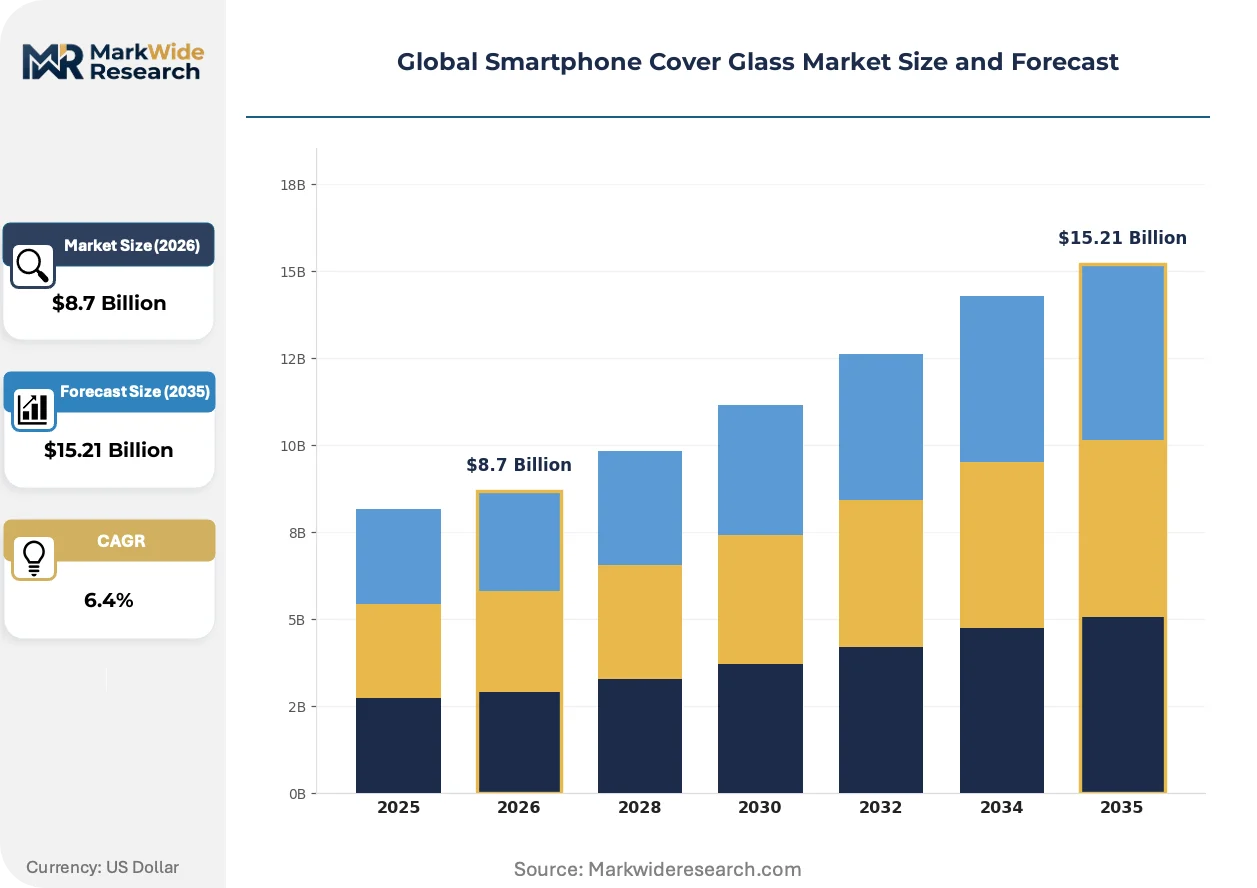
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Sapphire Glass, Plastic Film, Gorilla Glass, Dragontrail Glass Technology: Oleophobic Coating, Anti-Scratch, Anti-Glare, Hydrophobic Coating, UV Protection, Anti-Fingerprint Application: Flagship Models, Mid-Range Devices, Entry-Level Phones, Foldable Phones, Rugged Smartphones End User: Mobile OEMs, Aftermarket Suppliers, Repair Centers, Electronic Retailers, Online Marketplaces |
| Companies Covered | SCHOTT AG, Biel Crystal Manufactory Limited, Corning Incorporated, AvanStrate Inc, TPK, AGC Inc, Lens Technology Co Ltd, Fuyao Glass Industry Group Co Ltd, Nippon Electric Glass Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smartphone Cover Glass Market Strategic Shifts
Material science breakthroughs are compressing the boundary between rigid protection and flexible functionality, with substrate architectures evolving from passive barriers to active components of display system performance.
Laser-induced deep strengthening is virtualizing conventional salt bath ion-exchange limitations by enabling localized compression zone engineering without thermal deformation. Samsung Display and LG Display are piloting this technique for foldable inner-screen substrates. The process is virtualizing the traditional tradeoff between surface hardness and substrate thickness, permitting sub-0.1mm implementations that retain 900 MPa compression layers.
China's SAMR-administered GB standards for electronic product recyclability are mandating separable adhesive layers and heavy metal disclosure in cover glass stack compositions. Domestic brands including Xiaomi and OPPO are reformulating optical clear adhesive specifications to satisfy batch traceability requirements. Mid-range device programs face the steepest compliance cost elevation as they lack in-house materials laboratories possessed by premium-tier competitors.
Smartphone OEMs are consolidating cover glass procurement under display module suppliers rather than direct substrate negotiations, compressing the supplier interface from three tiers to two. This pattern concentrates volume leverage with Samsung Display, BOE, and Tianma Micro-electronics. The shift is most pronounced in Chinese domestic brand supply chains, where module houses now specify glass chemistry and finishing tolerances previously set by device manufacturers.
Global Smartphone Cover Glass Market Segmentation
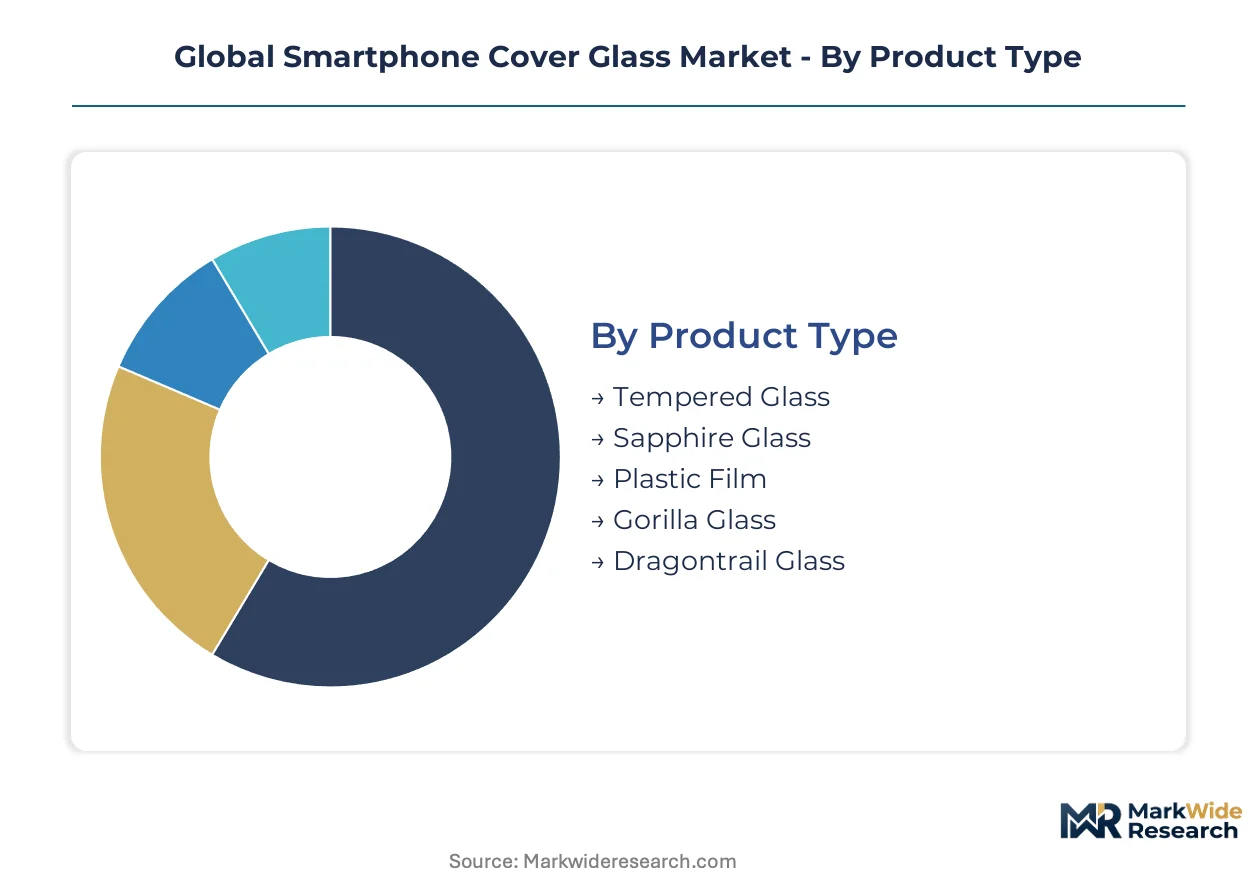
Smartphone cover glass segmentation reflects divergent performance requirements across device tiers and manufacturing economics. Each dimension—substrate chemistry, surface engineering, target device class, and channel structure—carries distinct margin profiles and supplier qualification barriers that shape competitive positioning.
Product Type:
Substrate chemistry spans a cost-performance spectrum from commodity tempered formulations to synthetic crystalline alternatives, with ion-exchange depth and alumina content determining mechanical resilience.
- Tempered Glass:Thermally or chemically strengthened soda-lime compositions dominate entry-level and mid-range device programs through cost-optimized tempering processes. Procurement concentrates in Vietnam and Thailand as Chinese suppliers diversify tariff exposure.
- Gorilla Glass:Proprietary aluminosilicate substrates engineered through fusion draw and ion-exchange achieve surface compression exceeding 800 MPa for premium flagship programs. Samsung and Apple specifications drive chemistry standardization across supply chains.
- Sapphire Glass:Single-crystal aluminum oxide grown through Kyropoulos methods delivers extreme scratch resistance for camera lens covers and ultra-premium limited editions. Kyocera and GT Advanced Materials anchor production in Japan and the US.
- Dragontrail Glass:Asahi Glass Company’s chemically strengthened formulation competes in mid-premium tiers through asymmetric ion-exchange profiles. Japanese automotive display programs increasingly adopt this substrate for curved instrument clusters.
- Plastic Film:Polyethylene terephthalate and thermoplastic polyurethane alternatives serve temporary protection and foldable hinge zones where glass fracture risk exceeds acceptable thresholds. BOE and Samsung Display specify film stacks for inner-screen bend radii below 3mm.
Established volume favors Gorilla Glass; emerging adoption favors Dragontrail Glass.
Technology:
Surface functionalization layers differentiate user experience through haptic response, optical clarity under ambient light, and resistance to skin oil accumulation.
- Oleophobic Coating:Fluoropolymer deposition reduces fingerprint visibility and drag coefficient for touch gesture responsiveness. Apple and Samsung mandate 8,000+ abrasion cycle durability in supplier specifications.
- Anti-Scratch:Diamond-like carbon and ceramic particle infiltration elevates Mohs hardness resistance above 7 for unprotected pocket and bag environments. Chinese brands Xiaomi and OPPO prioritize this specification for domestic mid-range volumes.
- Anti-Glare:Micro-structured surface etching diffuses specular reflection for outdoor readability in direct sunlight. Automotive display convergence is accelerating transfer of this technology from smartphone to curved cluster applications.
- Hydrophobic Coating:Silane-based water-repellent treatments enable droplet shedding for marine and industrial use-case smartphones. Caterpillar and Samsung XCover rugged programs specify this layer.
- UV Protection:Absorptive dopants in adhesive interlayers filter 380-400nm wavelengths to reduce OLED pixel degradation. LG Display and Tianma Micro-electronics integrate this into module-level stack designs.
- Anti-Fingerprint:Nanostructured topography mimics lotus-leaf surface geometry to minimize contact area with sebaceous oils. Emerging laser interference patterning methods from German equipment suppliers are displacing spray-deposition approaches.
Anti-Scratch coatings command the widest application span; Anti-Glare treatments are climbing the fastest on automotive spillover demand.
Application:
Device architecture dictates substrate thickness, flexural modulus, and edge strength requirements through drop-test protocols and hinge fatigue specifications.
- Foldable Phones:Ultra-thin chemically strengthened glass below 0.1mm thickness enables 200,000+ bending cycles through localized ion-exchange depth engineering. Samsung Galaxy Z and Huawei Mate X programs are expanding addressable substrate area per device through dual-screen configurations.
- Flagship Models:Premium tier devices specify full-coverage aluminosilicate with edge-to-edge compression layers and under-display camera cutout tolerances. Apple iPhone and Samsung Galaxy S procurement sets chemistry benchmarks adopted downstream.
- Mid-Range Devices:Cost-optimized tempered glass with selective edge strengthening satisfies 1-meter drop certification for volume programs in India and Southeast Asia. Biel Crystal anchors supply for OPPO, vivo, and realme domestic brand pipelines.
- Rugged Smartphones:Thickened substrates with laminated polycarbonate backing absorb impact energy for construction, logistics, and military use cases. Caterpillar, Samsung XCover, and Ulefone specify MIL-STD-810H compliance.
- Entry-Level Phones:Soda-lime tempered glass with basic thermal strengthening serves sub-$100 device segments where replacement cost economics favor screen insurance over substrate durability. Indian and African distribution channels concentrate demand.
Flagship Models sustain margin concentration; Foldable Phones are gaining share fastest on expanding design win penetration.
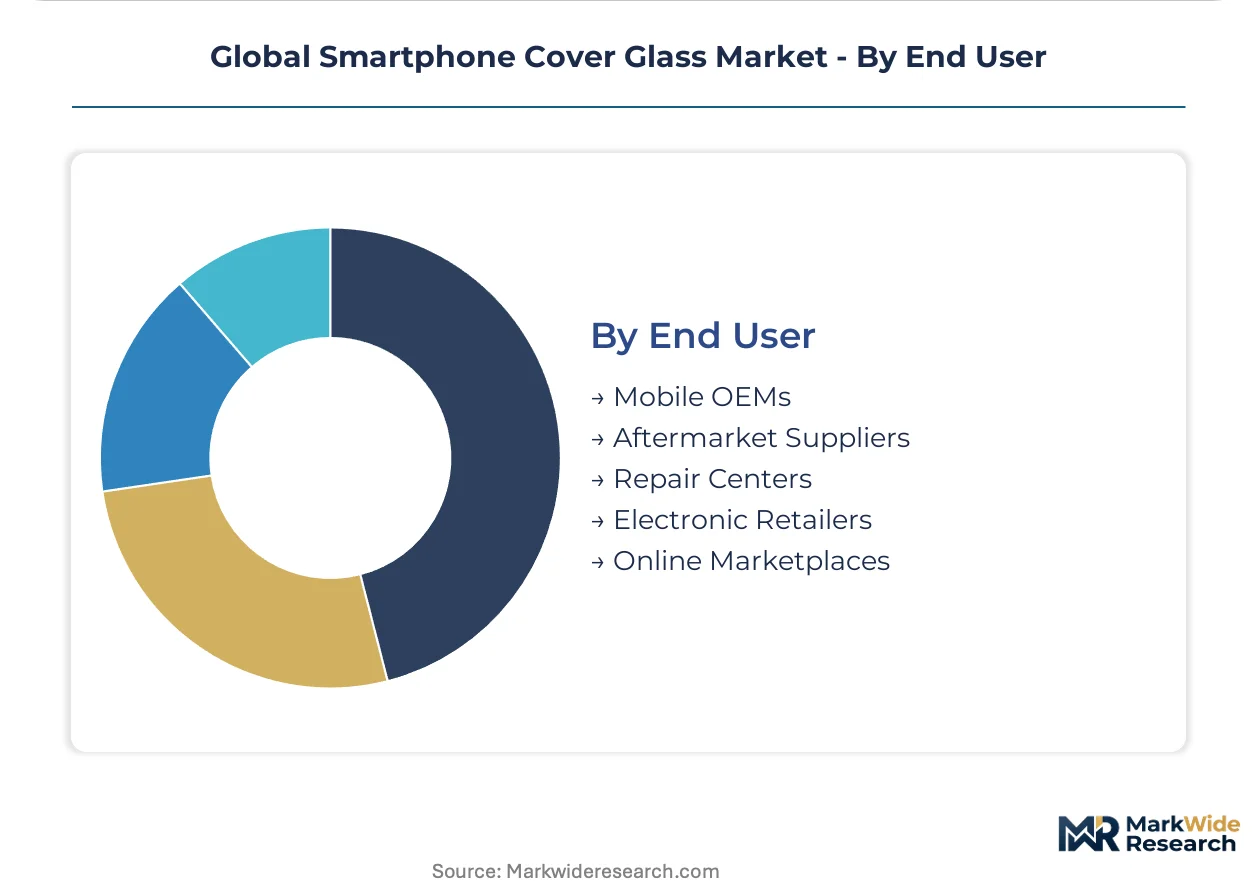
End User:
Channel structure determines specification authority, volume aggregation, and certification burden through direct OEM integration versus aftermarket fragmentation.
- Mobile OEMs:Samsung, Apple, Xiaomi, OPPO, and vivo consolidate procurement through display module suppliers, compressing direct substrate negotiations. Module houses now specify glass chemistry previously set by device manufacturers.
- Aftermarket Suppliers:Screen protector and replacement glass vendors source uncut substrate sheets from Chinese tempering houses for laser cutting and edge finishing. ZAGG, Belkin, and Spigen anchor brand positions in North American retail.
- Repair Centers:Authorized service networks and independent shops stock pre-cut substrates matched to specific device model years. Apple Independent Repair Provider program and Samsung Authorized Service Partner networks standardize parts sourcing.
- Electronic Retailers:Best Buy, MediaMarkt, and Bic Camera operate in-store application services that bundle substrate with installation labor. Japanese and South Korean electronics chains emphasize same-day screen replacement.
- Online Marketplaces:Amazon, Alibaba, and JD.com aggregate unbranded and private-label screen protectors with user-review-driven quality sorting. Direct-to-consumer substrate sales bypass traditional distribution markups.
Mobile OEMs control specification authority; Online Marketplaces are expanding most quickly on logistics infrastructure maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen-Hong Kong-Macau Bridge and adjacent port infrastructure underwrite China's dominance in cover glass supply chains, while Samsung's Gwangju-Yeosu logistics corridor anchors Korean substrate finishing. Vietnam's Haiphong deep-water port expansion and Thailand's Laem Chabang container throughput are pulling secondary tempering capacity southward from Chinese coastal zones.
China
Domestic smartphone brands Xiaomi, OPPO, and vivo consolidate procurement through vertically integrated module suppliers in Dongguan and Suzhou. SAMR-administered GB standards mandate batch-level chemical traceability for recyclability compliance. The Yangtze River Delta cluster around Kunshan houses Lens Technology's captive cutting and finishing operations serving flagship domestic programs.
South Korea
Samsung Display and LG Display concentrate module assembly in Gumi and Paju, specifying aluminosilicate chemistry benchmarks adopted across Asian supply chains. MFDS chemical safety notifications govern ion-exchange salt bath compositions. The Gwangju metropolitan area hosts specialized metrology labs conducting 200,000-cycle foldable glass validation for Galaxy Z programs.
Vietnam
Samsung Electronics and BOE Technology are expanding Bac Ninh and Thai Nguyen display module parks, pulling cover glass tempering investments into adjacent supplier zones. Ministry of Industry and Trade investment licensing prioritizes electronics component localization. Haiphong port's 2024 container terminal expansion reduces transit times for alumina raw material imports from Guinea and Australia.
Japan
Asahi Glass Company's Dragontrail substrate competes in mid-premium tiers through asymmetric ion-exchange profiles developed at Yokohama research facilities. METI circular economy roadmaps mandate separable adhesive layers in display stack designs. The Chubu region around Nagoya hosts automotive display convergence programs adopting smartphone-derived chemically strengthened substrates for curved instrument clusters.
United States
Apple's Cupertino-based procurement teams set premium-tier chemistry specifications adopted downstream by Asian module suppliers. EPA TSCA reporting requirements govern heavy metal content in imported substrate formulations. Corning's Kentucky fusion draw facilities supply proprietary aluminosilicate to flagship OEM programs, with R&D concentrated in New York State's Finger Lakes region.
Global Smartphone Cover Glass Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate chemistry and surface engineering. The vendor base concentrates around three vertically integrated manufacturers controlling ion-exchange salt bath capacity, with mid-tier tempering houses competing on cost-optimized soda-lime formulations. Dominant archetypes include fusion-draw substrate innovators, high-volume tempered glass fabricators, and vertically integrated cutting-finishing operators. Competitive moves center on backward integration into alumina refining and strategic partnerships with display module houses to compress procurement tiers.
Among the named participants, Corning Incorporated exemplifies the fusion-draw substrate archetype through proprietary aluminosilicate supply chains. Biel Crystal Manufactory Limited occupies a position within high-volume tempered glass fabrication for mid-range device programs. Lens Technology Co Ltd represents vertically integrated cutting and finishing operations serving domestic Chinese brand supply chains. These three anchors illustrate how chemistry control, scale economics, and module-level integration define competitive positioning across premium and volume tiers.
| Leading Market Players |
|---|
| SCHOTT AG |
| Biel Crystal Manufactory Limited |
| Corning Incorporated |
| AvanStrate Inc |
| TPK |
| AGC Inc |
| Lens Technology Co Ltd |
| Fuyao Glass Industry Group Co Ltd |
| Nippon Electric Glass Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese ion-exchange salt bath capacity compresses both margin buffers and supplier diversification options across pricing tiers. REACH compliance costs and alumina raw material volatility from Guinea and Australian mining consolidation determine spreads between premium aluminosilicate substrates and commodity tempered glass alternatives.
Pricing Analysis
Volume-discount tiering structures separate Gorilla Glass specifications for Apple and Samsung flagship programs from Dragontrail Glass mid-premium positioning and Biel Crystal's cost-optimized tempered glass for Indian and Southeast Asian mid-range volumes. Certification grade differentiation through 200,000-cycle foldable validation and 800 MPa surface compression thresholds commands substantial premiums over basic 1-meter drop-certified alternatives. Pricing pressure stems from Chinese supplier concentration and raw material volatility compressing margin buffers for non-integrated tempering houses. Aftermarket screen protector vendors exhibit highest price sensitivity, while flagship OEM procurement teams prioritize performance consistency over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for cover glass fabricators diversifying into Vietnam and Thailand. Manufacturing gravity centers on China's Yangtze River Delta around Kunshan and Dongguan, South Korea's Gumi-Paju corridor, and Vietnam's emerging Bac Ninh-Thai Nguyen cluster. Raw material dependencies draw from Guinean and Australian bauxite for high-purity alumina, Japanese and Korean ion-exchange process engineering expertise, and specialty potassium salt formulations. Distribution runs through display module suppliers Samsung Display, BOE, and Tianma Micro-electronics, compressing traditional three-tier procurement into direct module-level specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foldable device proliferation represents an early-cycle expansion story with substrate area per device doubling through dual-screen architectures and 200,000-cycle validation protocols creating qualification barriers for new entrants.
For Market Incumbents: Pre-empt substitution threats from laser-induced deep strengthening virtualization by securing exclusive pilot partnerships with Samsung Display and LG Display for sub-0.1mm implementations. Defend margin position through backward integration into alumina refining and captive ion-exchange salt bath capacity expansion in Vietnam's Bac Ninh supplier parks. Certification investment in SAMR-administered GB standards batch traceability creates switching costs for domestic Chinese brand procurement teams. For New Entrants and Emerging Players: Establish a beachhead in India's Uttar Pradesh and Tamil Nadu PLI scheme zones where display module assembly incentives attract cover glass tempering investments with lower incumbent saturation. Target automotive display convergence applications in Japan's Chubu region around Nagoya, where curved instrument cluster adoption of smartphone-derived substrates offers longer product lifecycles and less consolidated buyer power. Go-to-market angle: specialize in UV protection and anti-glare functionalization layers transferred from mobile to automotive specifications. For Investors and Strategic Acquirers: The market sits at a capacity-constrained expansion phase that favors vertically integrated manufacturers with in-house chemical treatment and module-level finishing capabilities. Long-term viability over the next decade hinges on foldable glass qualification timelines and material passport compliance infrastructure for EU sustainability rules. Acquisition target archetype: mid-tier tempering houses with established SAMR traceability systems and proximate location to Vietnam's Haiphong port expansion. Signal to watch: 18-24 month foldable validation protocol completion rates at Samsung and Huawei test matrices as inflection indicator for new substrate entrant revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Captive supply of high-purity aluminum oxide insulates margin buffers from Guinean export restrictions. |
| Laser-Induced Deep Strengthening Partnership | Samsung Display pilot programs virtualize salt bath limitations for sub-0.1mm foldable substrates. |
| GB Standards Batch Traceability Investment | SAMR recyclability mandates create compliance switching costs for Xiaomi and OPPO supply chains. |
| Vietnam Supplier Park Co-location | Bac Ninh and Thai Nguyen module assembly concentration pulls finishing operations into tariff-diversified zones. |
| Automotive Display Convergence Entry | Curved instrument cluster adoption in Japan's Chubu region opens parallel demand with longer lifecycles. |
Study Parameters
A standing panel of ion-exchange process engineering specialists, display module procurement directors, and SAMR regulatory compliance officers provided ongoing calibration across the study period. Primary interviews with tempering house plant managers, OEM materials laboratory directors, and aftermarket distributor channel heads combined with secondary validation from SEC 10-K filings, Korean MFDS chemical safety notifications, and Vietnam Ministry of Industry and Trade investment licensing records. Bottom-up substrate volume estimates triangulated against top-down display module production forecasts.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include substrate chemistry tier, surface functionalization technology, device architecture class, and channel structure. CAGRs derived from iterative reconciliation of shipment volumes, average substrate area per device, and pricing tier trajectories. Industry-specific forecast inputs incorporated foldable phone design win penetration curves and automotive display content-per-vehicle adoption slopes.
Sensitivities concentrate around Guinea-Australia alumina supply disruptions, 18-24 month foldable validation timeline extensions, and EU Battery Regulation material passport implementation scope. Forecasts reflect documented assumptions on ion-exchange capacity expansion schedules and tariff regime stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Global Tantalum Capacitors Market
Electronic Components
Encoder Market
Electronic Components
USB Retimer Market
Electronic Components
Impulse Relays Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Audio DSP Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Fuel Pump Driver Module Market
Electronic Components
Structural Electronics Market
Electronic Components
TWS and Noise-Cancelling Headphone with MEMS Chip Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
North America Safety Relay and Timers Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Video Surveillance Chip Market
Electronic Components
Multilayer Transparent Conductors Market