
 Hydrogen Thyratron Market | 2026-2036
Hydrogen Thyratron Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Thyratron Market Insights
Asset-light leasing models for high-voltage test equipment is tilting procurement economics toward specialized suppliers rather than integrated systems houses. Richardson Electronics leverages its distribution network to sustain captive demand from North American defense primes. Teledyne e2v anchors its position through in-house production of ceramic-metal envelopes, a process bottleneck that competitors struggle to replicate. Siemens dominates European supply for research-grade units, navigating long qualification cycles that lock out new entrants.
Hydrogen thyratrons are gas-filled switching tubes using a hydrogen reservoir and thermionic cathode to achieve microsecond-scale current rise in high-voltage circuits, typically rated from kilovolts to hundreds of kilovolts. They serve as precision triggers in radar modulators, particle accelerator injection systems, and pulsed laser power supplies where solid-state devices cannot match voltage hold-off or pulse fidelity. High Power units occupy the dominant revenue share due to irreplaceable roles in megawatt radar transmitters, while Subminiature designs represent the fastest-expanding category as miniaturized RF amplifiers penetrate satellite communications payloads. Pulse Modulator technology leads in absolute volume, though High Voltage Switching applications in compact medical linacs are deepening margin pools for qualified vendors.
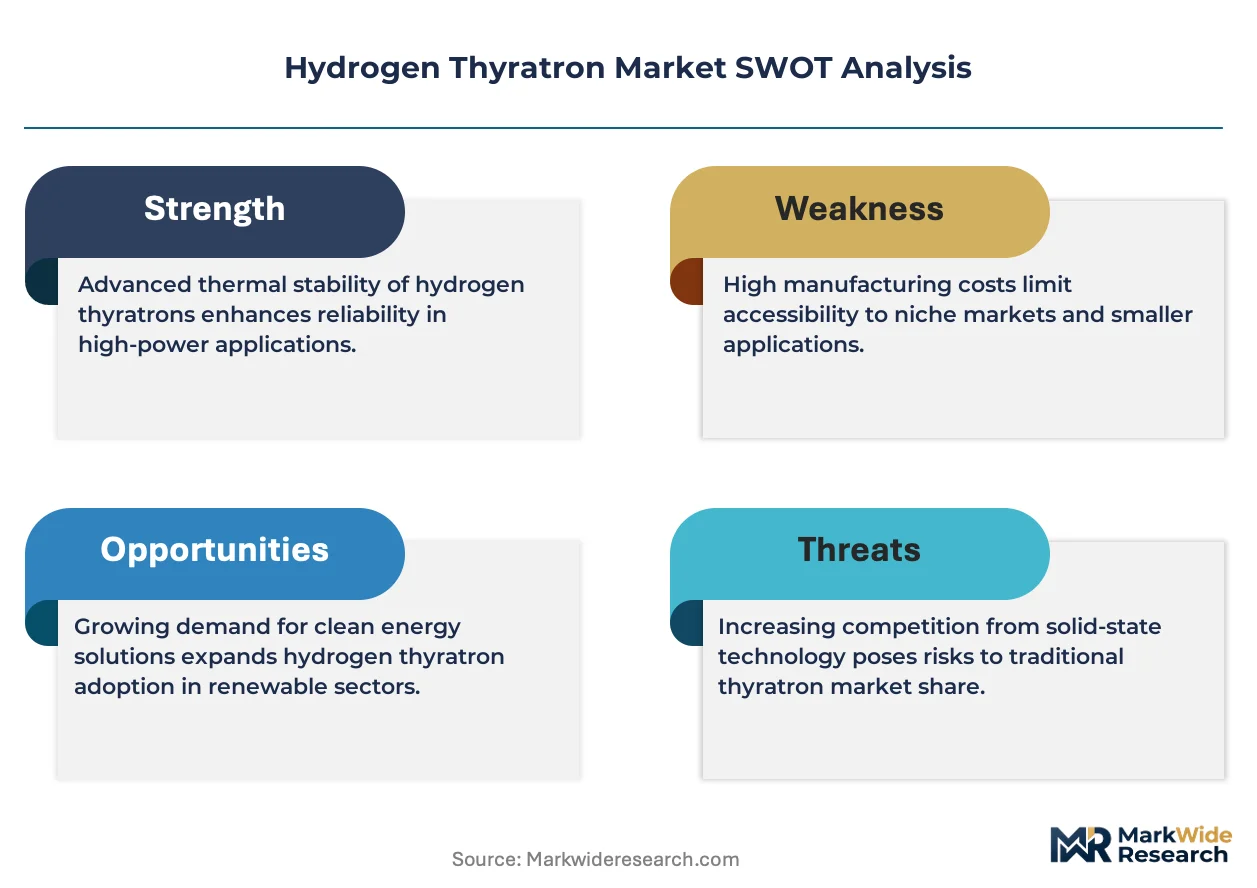
FCC Part 15 emissions rules and EU Electromagnetic Compatibility Directive constrain switching noise thresholds, compelling design investments in shielded housings and filtered trigger circuits. ISO 9001 and IEC 60747 quality frameworks govern aerospace and medical procurement eligibility, effectively filtering supplier bases to pre-qualified manufacturers. Stakeholders must weigh hydrogen reservoir lifetime against solid-state displacement timelines when committing to long-service platform designs.
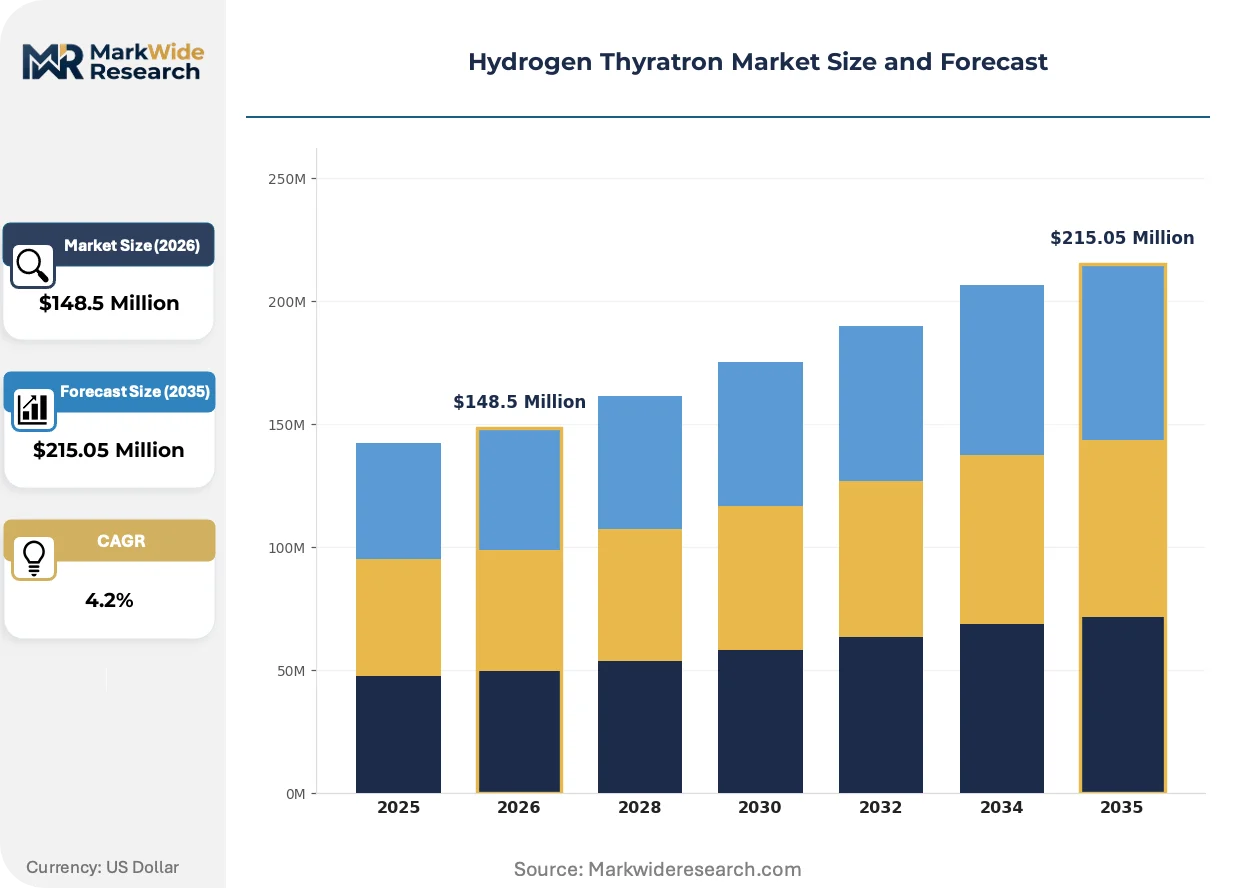
Market Dynamics
Defense procurement cycles for radar-grade hydrogen thyratrons are compressing qualification timelines, forcing suppliers to pre-certify designs against evolving electromagnetic compatibility mandates before contract awards.
Growth Catalysts
- Next-generation radar deployment:United States defense contractors are expanding orders for surveillance systems requiring microsecond-scale switching precision that solid-state alternatives cannot replicate.
- REACH compliance investments:European manufacturers are redesigning ceramic-metal envelopes to eliminate restricted substances, opening procurement eligibility for particle accelerator programs across Germany and France.
- Hydrogen reservoir lifetime extension:Advanced getter materials are extending operational cycles from thousands to tens of thousands of pulses, reducing platform lifecycle costs for satellite payload integrators.
Market Restraints
- Tungsten cathode supply concentration:Primary sourcing for thermionic emitters concentrates in Chinese rare earth processing facilities, exposing cost volatility to Western fabricators.
- FCC Part 15 shielding mandates:Stricter electromagnetic emissions thresholds compel expensive housing redesigns for legacy pulse modulator architectures.
- Solid-state thyristor encroachment:Silicon carbide devices are capturing sub-50 kV switching applications in medical linear accelerators where pulse fidelity requirements have relaxed.
Strategic Opportunities
- Medical linac miniaturization:Compact proton therapy systems in Japan are specifying subminiature thyratron designs for gantry-mounted pulse networks.
- India's PLI scheme for defense electronics:Domestic manufacturing incentives are creating import-substitution openings for qualified component vendors establishing local assembly.
- Digital twin integration:Predictive lifetime modeling software is enabling outcome-based maintenance contracts that unbundle hardware from service revenue streams.
Industry Challenges
- Ceramic-to-metal sealing expertise:The specialized brazing techniques required for hydrogen-tight envelopes face generational knowledge transfer gaps as veteran technicians retire.
- IEC 60747 qualification timelines:Aerospace procurement eligibility requires 18-24 month validation cycles that lock working capital and delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Thyratron Market |
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $215.05 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Power, Low Power, Medium Power, Subminiature Technology: Pulse Modulator, RF Amplifier, Trigger Generator, High Voltage Switching Application: Radar Systems, Particle Accelerators, Laser Systems, Medical Equipment End User Industry: Telecommunications, Research Institutes, Defense Contractors, Energy Sector |
| Companies Covered | Siemens, Richardson Electronics, Teledyne e2v, Stellant Systems, General Electric, ABB, Hitachi, Applied Materials, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Thyratron Market Trends and Innovations
Digital modeling tools are compressing design iteration cycles for hydrogen thyratron architectures, while regulatory pressure on electromagnetic emissions and supply chain reconfiguration are reshaping competitive requirements across defense and medical end-uses.
Virtual prototyping platforms are virtualizing the development pathway for ceramic-metal envelope geometries, allowing Siemens and specialized suppliers to simulate thermal-mechanical stress before physical fabrication. Accelerator laboratories in Germany and Switzerland are adopting these tools to customize pulse-forming networks without prototype lead times. The technology is virtualizing the traditional build-test-iterate cycle that previously consumed twelve to eighteen months per design revision.
The EU Electromagnetic Compatibility Directive's tightened switching noise thresholds are mandating filtered trigger circuit architectures and shielded housing configurations that add material cost but preserve aerospace and medical procurement eligibility. Manufacturers serving European particle accelerator programs are redesigning legacy modulator platforms to meet these specifications ahead of enforcement deadlines. Subminiature designs face the steepest compliance burden due to compact form factors that limit shielding volume.
Asset-light leasing arrangements for high-voltage test equipment are displacing capital purchase patterns among North American defense primes and satellite communications integrators. Richardson Electronics and specialized distributors are capturing recurring revenue through calibrated pulse generator rentals that bundle preventive maintenance. This model concentrates in the United States where rapid platform iteration cycles favor operational expenditure over balance-sheet ownership of qualification hardware.
Hydrogen Thyratron Market Segmentation
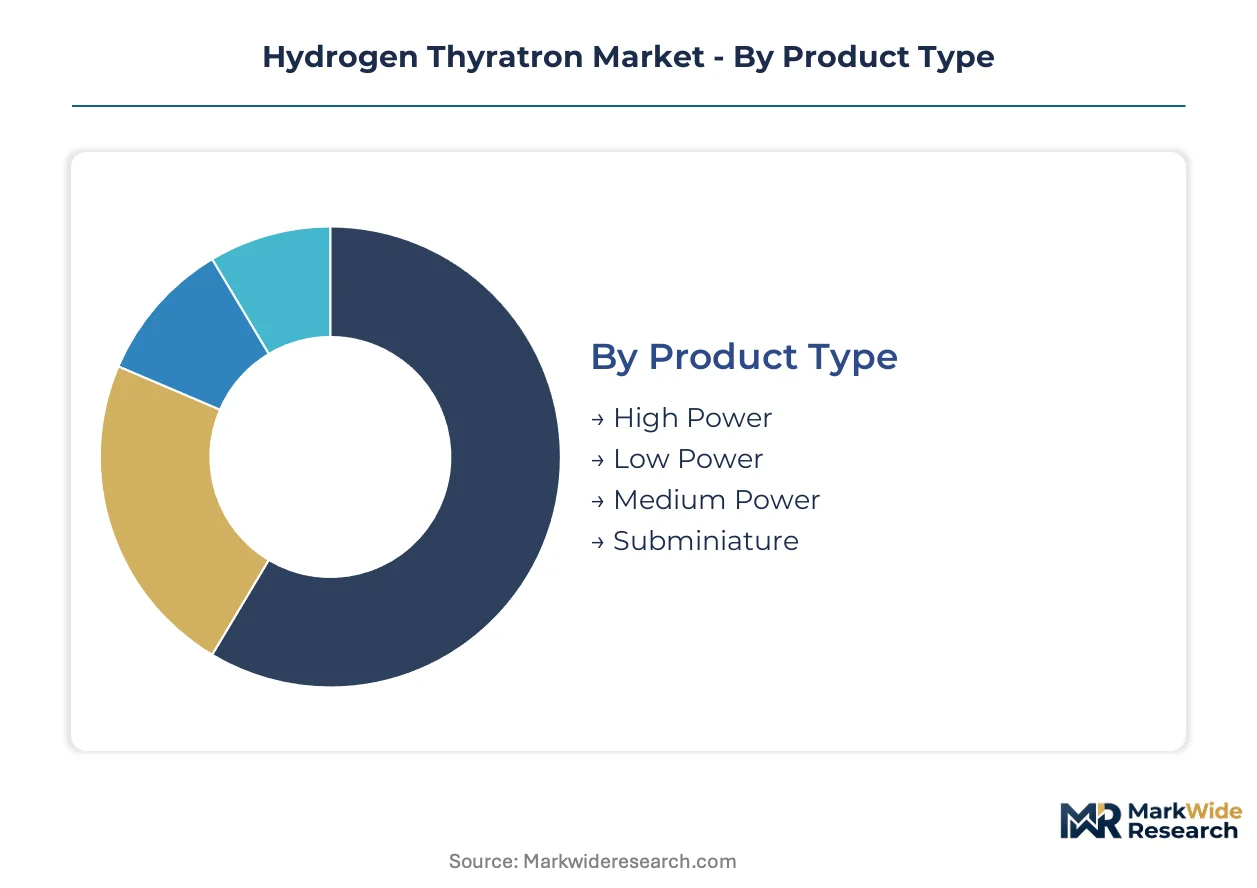
Hydrogen thyratron procurement patterns diverge sharply across power ratings and envelope geometries, with defense radar programs demanding multi-decade service support while satellite integrators prioritize swap-out modularity. Segmentation reveals how after-sales service intensity varies from embedded field engineering for megawatt transmitters to standardized spare-part logistics for subminiature designs.
Product Type:
Service intensity scales inversely with unit miniaturization, as high-power installations require dedicated field technicians while compact designs ship as sealed replacements.
- High Power:Ceramic-metal envelopes rated above 100 kV with forced hydrogen circulation systems demand continuous cathode conditioning support. United States defense contractors anchor procurement for megawatt radar transmitters where FCC Part 15 shielding mandates drive housing redesigns that extend qualification timelines.
- Subminiature:Compact hydrogen reservoirs integrated into satellite RF amplifiers achieve pulse fidelity in volume-constrained payloads. Japanese proton therapy system builders are specifying these designs for gantry-mounted pulse networks where maintenance access is physically restricted.
- Low Power:Laboratory-grade units serve university research programs with standardized trigger interfaces and shorter replacement cycles.
- Medium Power:Industrial laser applications specify these for pulse-forming networks requiring moderate voltage hold-off without full radar-grade qualification overhead.
High Power holds the largest share; momentum sits with Subminiature.
Technology:
Margin structures vary by switching architecture complexity, with pulse modulators commanding premium pricing for electromagnetic compatibility certification while trigger generators compete on component cost.
- Pulse Modulator:Precision-timed hydrogen discharge circuits achieve microsecond-scale current rise for radar modulator duty. German particle accelerator programs specify these for injection kicker systems where pulse-to-pulse jitter tolerance sits below ten nanoseconds.
- High Voltage Switching:Direct anode-cathode switching topologies replace mechanical contactors in compact medical linear accelerators. Silicon carbide thyristors are capturing sub-50 kV applications where pulse fidelity requirements have relaxed, compressing addressable market scope for hydrogen-based alternatives.
- RF Amplifier:Hydrogen thyratrons serve as grid-controlled RF power sources in specialized communications transmitters requiring rapid on-off modulation.
- Trigger Generator:Low-energy discharge circuits provide synchronized firing pulses for multi-tube series configurations in high-voltage stacks.
Pulse Modulator dominates absolute volume; High Voltage Switching faces steepest solid-state displacement pressure.
Application:
End-use qualification burdens segment vendor economics, with aerospace radar programs imposing eighteen-month validation cycles against medical equipment's faster iterative procurement.
- Radar Systems:Megawatt transmitter modulators specify hydrogen thyratrons where solid-state devices fail on voltage hold-off or pulse energy density. United States defense primes are compressing procurement cycles for next-generation surveillance platforms, forcing suppliers to pre-certify against evolving electromagnetic compatibility mandates.
- Medical Equipment:Linear accelerator pulse networks specify subminiature designs for proton therapy gantries. REACH compliance investments are redesigning ceramic-metal envelopes to eliminate restricted substances, opening procurement eligibility across European hospital procurement frameworks.
- Particle Accelerators:Injection and extraction kicker systems demand nanosecond-scale switching precision for beam manipulation.
- Laser Systems:Pumped laser power supplies utilize hydrogen thyratrons for capacitor discharge switching in industrial materials processing.
Radar Systems commands revenue concentration; Medical Equipment is expanding most quickly.
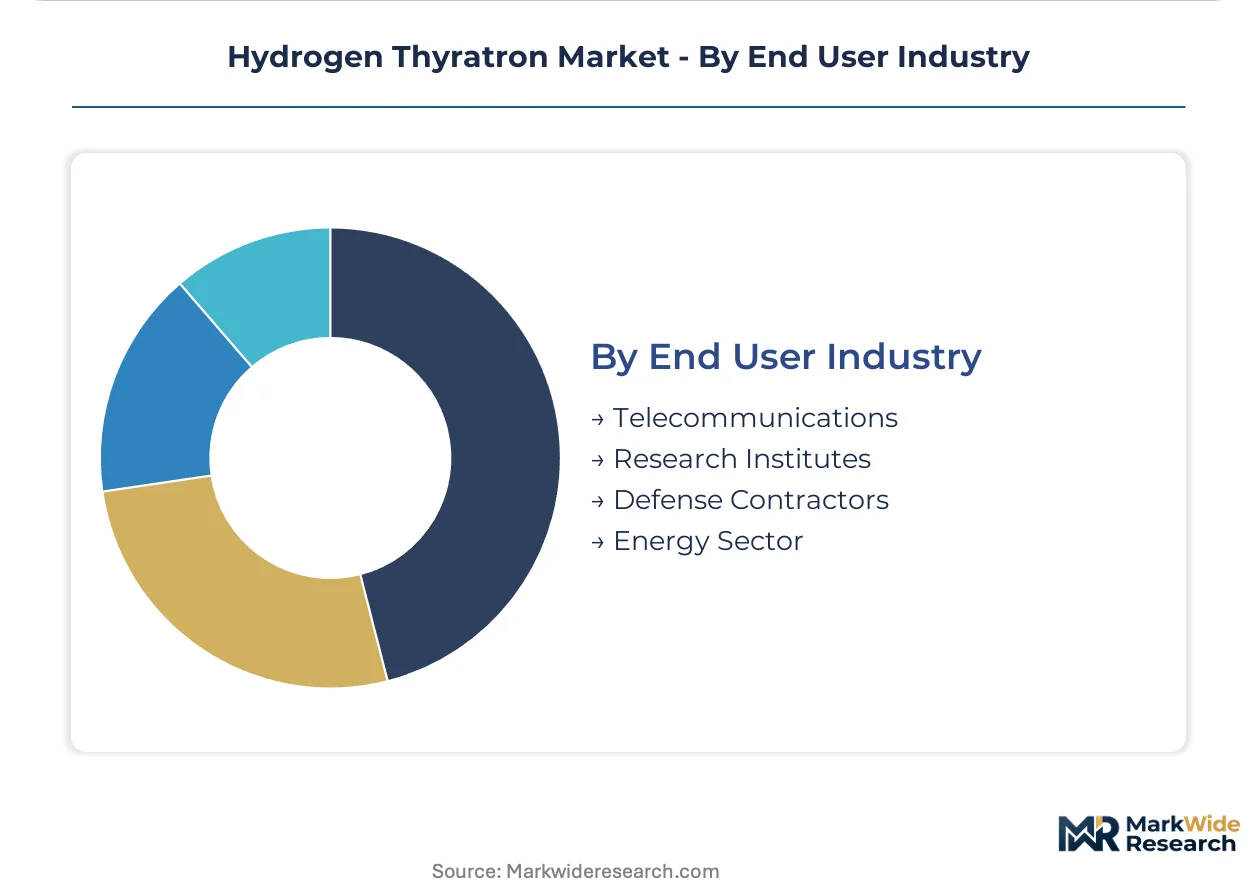
End User Industry:
Procurement centralization patterns differ across buyer types, with defense contractors negotiating multi-year platform contracts against research institutes' project-based spot purchasing.
- Defense Contractors:Long-service radar platform specifications lock in hydrogen thyratron suppliers through sole-source qualification status. India's PLI scheme for defense electronics is creating import-substitution openings for qualified vendors establishing local assembly capabilities.
- Research Institutes:Accelerator laboratories in Germany and Switzerland customize pulse-forming networks through digital twin platforms that virtualize thermal-mechanical stress simulation before physical fabrication.
- Telecommunications:Satellite payload integrators specify subminiature designs with standardized interface specifications for rapid orbital replacement unit swap-out.
- Energy Sector:Pulsed power applications in fusion research and grid-scale testing utilize high-power hydrogen thyratrons for capacitor bank discharge switching.
Defense Contractors anchor revenue stability; Research Institutes are driving fastest design iteration velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in hydrogen thyratrons favor established manufacturing clusters in Germany and the United States, with satellite payload integrators in Japan and defense programs in India emerging as net demand centers. Trade patterns concentrate precision fabrication in mature industrial bases while qualification-intensive procurement spreads across multiple end-use jurisdictions.
United States
Defense contractors anchor procurement for megawatt radar transmitters requiring FCC Part 15 electromagnetic compatibility certification. The Department of Defense accelerates next-generation surveillance platform deployment, compressing supplier qualification timelines. Richardson Electronics sustains captive demand through its North American distribution network serving prime contractors in the defense corridor.
Germany
Siemens anchors European supply for research-grade units serving particle accelerator programs across the continent. REACH compliance investments redesign ceramic-metal envelopes to eliminate restricted substances, preserving procurement eligibility. The precision manufacturing cluster in Bavaria supplies injection kicker systems to accelerator laboratories in Switzerland and France.
Japan
Proton therapy system builders specify subminiature thyratron designs for gantry-mounted pulse networks in compact medical linacs. METI standards govern medical device electromagnetic emissions, mandating shielded housing configurations. Tokyo-based satellite payload integrators drive demand for miniaturized RF amplifiers with standardized interface specifications.
India
The PLI scheme for defense electronics creates import-substitution openings for qualified component vendors establishing local assembly capabilities. BIS certification requirements filter supplier eligibility for domestic radar platform integration. Defense procurement centralization in Delhi-NCR accelerates qualification cycles for foreign manufacturers seeking sole-source status.
Switzerland
Accelerator laboratories in Geneva and Zurich adopt digital twin platforms to customize pulse-forming networks without prototype lead times. Swissmedic-aligned quality frameworks govern medical linear accelerator procurement, extending validation timelines. The research corridor concentrates demand for nanosecond-scale switching precision in beam manipulation systems.
Hydrogen Thyratron Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated systems houses with captive component production, specialized tube manufacturers with ceramic-metal sealing expertise, and distribution-led intermediaries bundling hardware with calibration services. Competitive moves center on pre-certification investments against evolving electromagnetic compatibility mandates and outcome-based maintenance contracts that unbundle hardware from service revenue.
Among diversified industrial conglomerates, Siemens and General Electric exemplify the integrated systems house archetype, leveraging in-house precision fabrication capabilities to navigate long qualification cycles. Richardson Electronics and Teledyne e2v occupy positions within the specialized component tier, with the latter representing ceramic-metal envelope production expertise that competitors struggle to replicate. Stellant Systems anchors defense-aerospace supply relationships through sole-source qualification status on long-service radar platforms.
| Leading Market Players |
|---|
| Siemens |
| Richardson Electronics |
| Teledyne e2v |
| Stellant Systems |
| General Electric |
| ABB |
| Hitachi |
| Applied Materials |
| PerkinElmer |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's hydrogen thyratron logistics costs shape downstream price differentiation between defense contractors and research institutes. Ceramic-metal envelope fabrication concentrates in Germany and the United States, concentrating pricing power with qualified suppliers serving FCC Part 15 and EU Electromagnetic Compatibility Directive mandates.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in hydrogen thyratron procurement. Premium tiers command certification-grade pricing for IEC 60747 aerospace qualification, while standard tiers serve industrial laser applications with reduced after-sales bundling. Cost compression in sub-50 kV segments intensifies because silicon carbide thyristors capture medical linear accelerator switching, making satellite payload integrators the most price-sensitive segment against defense primes with sole-source lock-in.
Supply Chain Analysis
Export control regimes under ITAR and EU dual-use regulations limit ceramic-metal sealing technology transfers, constraining supply expansion. Tungsten cathode sourcing draws from Chinese rare earth processing, ceramic substrate supply rests on German precision manufacturing, and hydrogen reservoir fabrication centers on United States defense-aerospace clusters. Single-source vulnerability concentrates in thermionic emitter supply, with distribution running through Richardson Electronics' North American network and Siemens' European direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen thyratron market rewards outcome-based maintenance contracts that unbundle hardware from predictive lifetime modeling services, a recurring-revenue layer expanding faster than unit sales as satellite operators adopt asset-light leasing.
For Market Incumbents: Entrench sole-source qualification status on long-service radar platforms by pre-certifying designs against evolving FCC Part 15 shielding mandates before contract awards. Deepen backward integration into ceramic-to-metal sealing expertise to offset generational knowledge transfer gaps as veteran technicians retire, protecting margin pools from solid-state displacement in sub-50 kV medical applications. For New Entrants and Emerging Players: Pursue India's PLI scheme for defense electronics by establishing local assembly capabilities for BIS-certified radar-grade units, the most penetrable geography given procurement centralization in Delhi-NCR. Target compact proton therapy system builders in Japan with subminiature designs for gantry-mounted pulse networks, leveraging digital twin integration as a go-to-market angle to compress qualification timelines. For Investors and Strategic Acquirers: Specialized tube manufacturers with captive ceramic-metal envelope production represent the highest-conviction acquisition archetype given irreplaceable process bottlenecks. Long-term viability across a five-to-ten-year window hinges on hydrogen reservoir lifetime extension outpacing solid-state thyristor encroachment. Watch silicon carbide switching fidelity improvements in medical linear accelerators as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification Investment | Pre-qualification against FCC Part 15 preserves sole-source status on defense contracts. |
| Digital Twin Integration | Predictive lifetime modeling enables outcome-based maintenance contracts unbundling hardware from services. |
| Backward Integration | In-house ceramic-metal sealing protects against generational knowledge transfer gaps. |
| Geographic Manufacturing Expansion | India PLI scheme assembly captures import-substitution openings in defense procurement. |
| REACH Compliance Redesign | Eliminating restricted substances preserves European particle accelerator program eligibility. |
Research Methodology
Initial hypotheses were tested against primary input from radar system procurement officers, particle accelerator engineering leads, medical linac maintenance directors, and high-voltage test equipment rental managers and refined through secondary validation. Defense contractor SEC filings, CERN procurement databases, FDA medical device registrations, and IEC standards documentation anchored top-down market sizing. Bottom-up triangulation cross-checked unit shipment estimates against cathode material consumption patterns and hydrogen reservoir production volumes.
Demand-supply balance modeling segmented the market by power rating, envelope geometry, switching architecture, and end-use qualification intensity across the projection horizon. CAGRs derived from installed base replacement cycles, platform life extension investments, and solid-state substitution elasticity in medical versus defense applications. Forecast inputs incorporated REACH compliance investment schedules, PLI scheme disbursement timelines, and FCC electromagnetic compatibility enforcement phase-ins.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon carbide thyristor manufacturers into sub-50 kV medical switching would shift outcomes. Material shifts in tungsten cathode export restrictions or ceramic-to-metal sealing technician availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
USB Wall Charger Market
Electronic Components
Passive Attenuator Market
Electronic Components
Audio CODEC Market
Electronic Components
Screw Washer Market
Electronic Components
Flexible Heater Market
Electronic Components
Global Flexible Electronics and Circuit Market
Electronic Components
Global Capacitor Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Intel Motherboards Market
Electronic Components
Graphics Add-In Board (AIB) Market
Electronic Components
Pulse Width Modulation Controllers Market
Electronic Components
North America USB Retimer Market
Electronic Components
Battery Shunt Resistor Market
Electronic Components
Trackpad Market
Electronic Components
USB Retimer Market