
 Dry Reactor Market | 2026-2036
Dry Reactor Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Reactor Market Insights
The direct sales channel between reactor manufacturers and chemical plant operators is narrowing as engineering-procurement-construction firms consolidate vendor lists. Hitachi Energy leverages its transformer and reactor integration expertise to anchor large industrial contracts in Asia-Pacific markets. Siemens Energy competes through technology leadership in thermal processing reactor systems. ABB sustains its position via geographic dominance across European chemical corridors.
A dry reactor is a vessel engineered for chemical reactions without liquid solvents, typically constructed from corrosion-resistant alloys and operating at controlled temperature-pressure parameters to drive gas-phase or solid-catalyzed transformations. Its primary industrial purpose centers on polymer production, pharmaceutical synthesis, and hazardous waste neutralization where solvent elimination reduces downstream separation costs. Batch reactor configurations retain the largest installed base across chemical manufacturing, though continuous reactor systems are capturing margin pools in high-volume polymer operations. Catalytic processing technology leads current deployment, while advanced oxidation methods are expanding fastest in waste management applications.
FDA oversight shapes pharmaceutical-grade reactor standards in the United States, while REACH and CE marking govern material composition and safety certification across European installations. China's SAMR enforces GB standards for pressure equipment that directly affect reactor design and market access for imported systems. Stakeholders must monitor evolving chemical safety regulations and assess whether captive production or outsourced reactor fabrication better aligns with their geographic expansion plans.
Market Dynamics
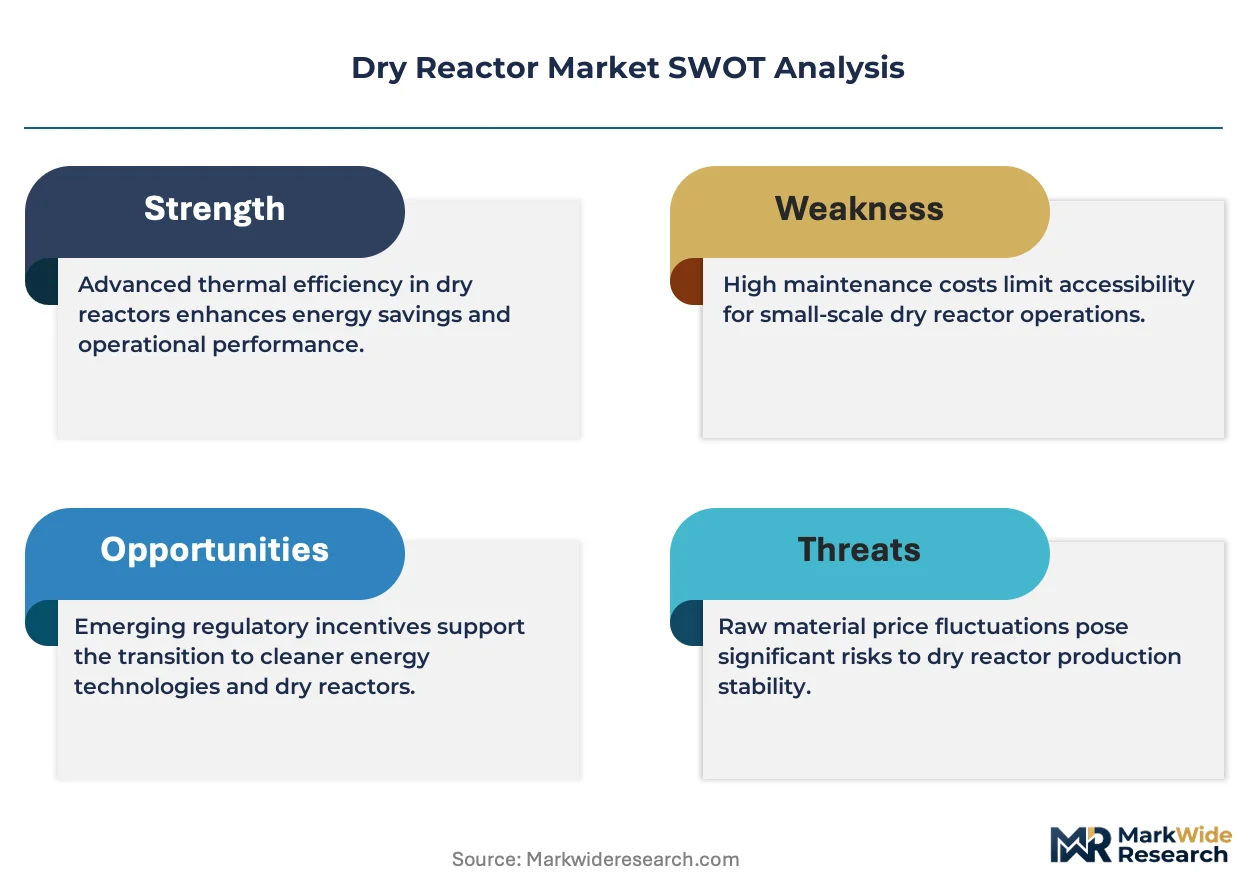
Engineering-procurement-construction firms are consolidating vendor lists and narrowing direct sales channels between reactor manufacturers and chemical plant operators, compressing margin pools for equipment suppliers while favoring integrated system providers with turnkey capabilities.
Growth Catalysts
- REACH compliance frameworks:The EU Green Deal is tightening material safety requirements for reactor vessel construction, forcing upgrades across installed bases and generating replacement demand for certified systems.
- Polymer production expansion:Chemical manufacturing facilities in Germany, China, and India are scaling specialty chemical capacity and adopting dry reactor configurations for solvent-free synthesis processes.
- Catalytic processing technology:Continuous reactor systems are capturing margin pools in high-volume polymer operations where batch configurations previously dominated installed capacity.
Market Restraints
- Corrosion-resistant alloy input costs:Nickel and specialty steel price volatility directly compresses fabrication margins for vessel constructors without long-term supply agreements.
- Pressure equipment certification timelines:China's SAMR enforcement of GB standards creates extended approval cycles for imported systems, delaying market access for foreign manufacturers.
- Advanced oxidation substitutes:Wet scrubbing and solvent-based neutralization methods retain cost advantages in certain hazardous waste applications, limiting dry reactor penetration.
Strategic Opportunities
- Pharmaceutical synthesis applications:FDA oversight of pharmaceutical-grade reactor standards in the United States creates premium positioning for suppliers with validated clean-in-place systems.
- India specialty chemical corridor:CDSCO alignment with international GMP standards is accelerating domestic pharmaceutical manufacturing investment and associated reactor procurement.
- Modular skid-mounted systems:Engineering-procurement-construction firms are specifying pre-integrated reactor packages to reduce field installation timelines and commissioning risk.
Industry Challenges
- ASME pressure vessel certification:Extended audit timelines and inspector availability constraints are delaying project handovers and compressing supplier cash conversion cycles.
- Legacy DCS integration complexity:Brownfield chemical plants require custom control system interfaces to connect new reactor skids with existing distributed control architectures, inflating engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Reactor Market |
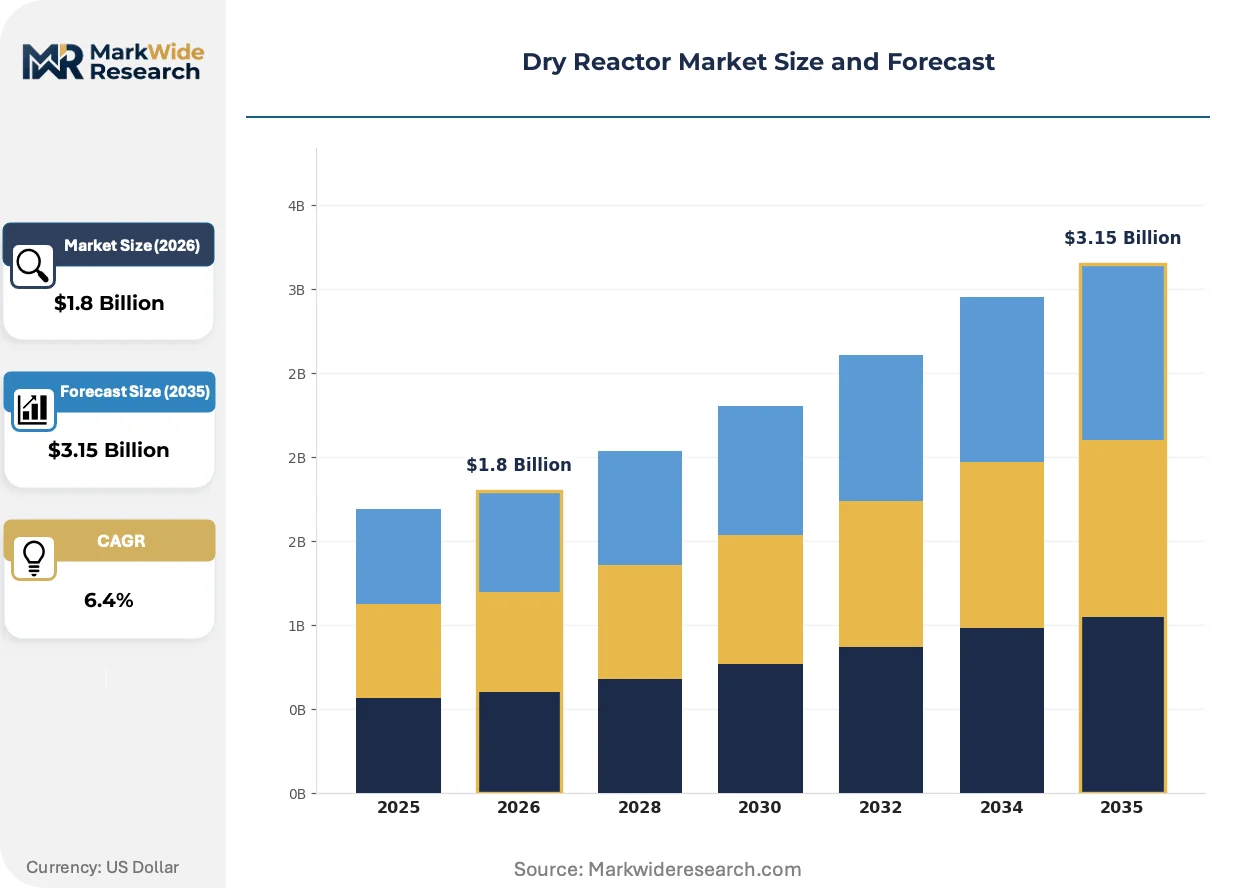
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Reactor, Continuous Reactor, Plug Flow Reactor, Fluidized Bed Reactor Technology: Thermal Processing, Catalytic Processing, Microwave Processing, Advanced Oxidation End User: Chemical Manufacturing, Pharmaceutical, Food & Beverage, Waste Management Application: Polymer Production, Drug Synthesis, Bioremediation, Nutrient Recovery |
| Companies Covered | Hitachi Energy, TBEA, GE Vernova, Siemens Energy, Trench Group, ABB, Rakesh Transformers, Hainan Jinpan Smart Technology, Hada Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Reactor Market Trends and Innovations
Digital twin deployment and predictive maintenance analytics are transforming how reactor operators manage asset performance, shifting capital allocation from reactive spare parts inventory toward software-enabled uptime guarantees.
Additive manufacturing of reactor internals is rendering obsolete traditional casting and machining workflows for complex heat exchanger geometries. Specialty chemical producers in Germany are qualifying laser-sintered components for high-pressure polymerization service. This fabrication method is rendering obsolete six-month lead times for custom manifold assemblies.
REACH authorization requirements for chromium compounds are restricting legacy coating applications on reactor vessels across European installations. Equipment fabricators are accelerating qualification of ceramic-lined alternatives and solid-alloy construction methods. Pharmaceutical manufacturers in Switzerland and Belgium are absorbing premium pricing for compliant systems to maintain CE-marked market access.
After-sales service unbundling is fragmenting traditional maintenance contracts into discrete performance-based modules. Chemical plant operators in India are purchasing remote monitoring subscriptions separately from spare parts agreements, forcing reactor suppliers to build standalone software revenue streams. This model is most visible in continuous polymer operations where unplanned downtime costs exceed preventive maintenance premiums.
Dry Reactor Market Segmentation
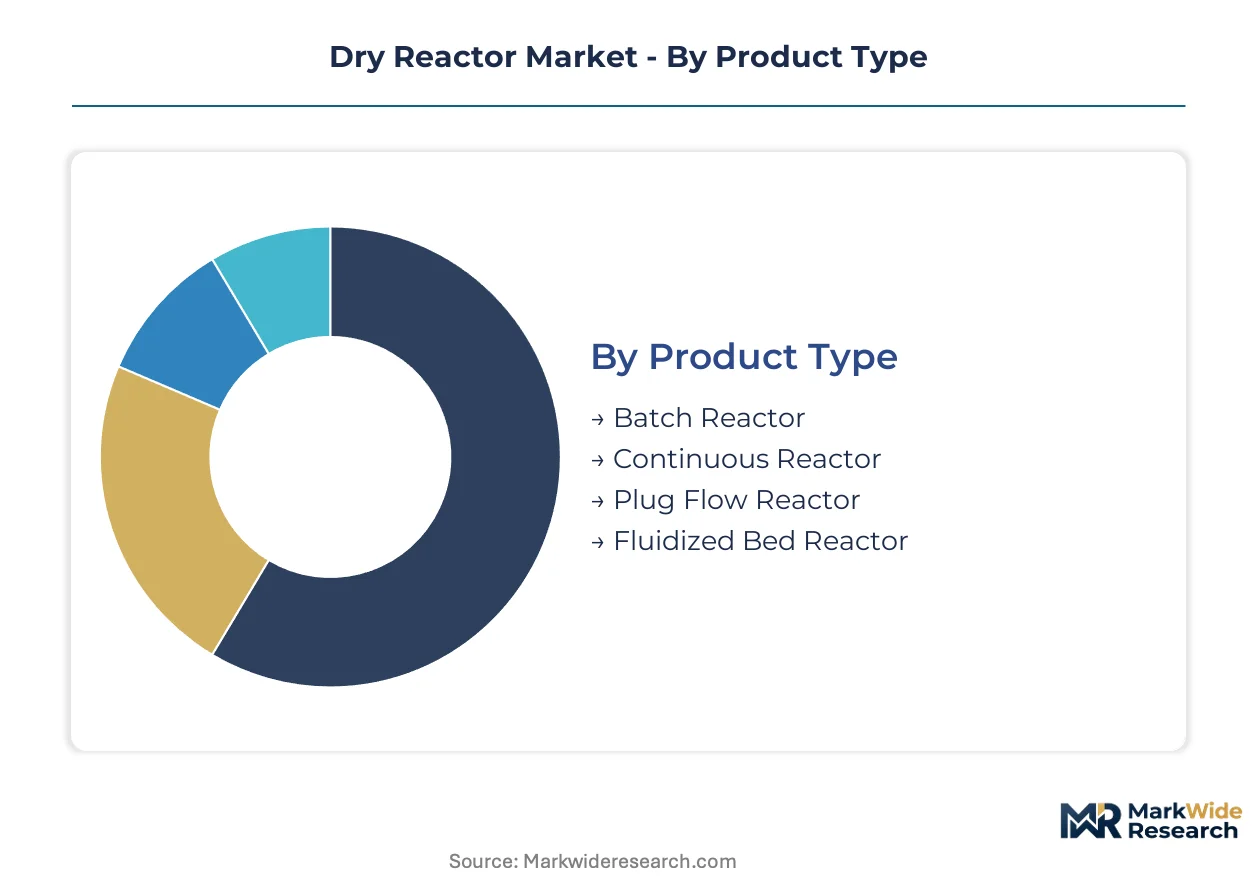
Dry reactor procurement patterns diverge sharply across configuration types and processing technologies, with replacement cycles stretching from three years for modular batch units to fifteen years for integrated continuous systems. Understanding segment-level turnover dynamics enables suppliers to align inventory, service contracts, and R&D roadmaps with actual equipment lifecycles rather than aggregated market averages.
Product Type:
Batch reactors turn over fastest at 5-7 year replacement intervals in high-throughput polymer operations, while continuous systems operate on 12-15 year depreciation schedules that lock in vendor relationships across multiple upgrade cycles.
- Batch Reactor:Vessels designed for discrete loading, reaction, and unloading sequences dominate pharmaceutical synthesis where FDA validation requirements favor proven configurations over novel designs. Chemical manufacturers in Germany and India are retiring legacy carbon-steel units ahead of REACH compliance deadlines, accelerating replacement demand for certified alloy replacements.
- Continuous Reactor:Steady-state processing architectures eliminate intermediate handling for high-volume polymerization, capturing margin pools in operations exceeding 50,000 annual tonnage. China's specialty chemical corridor is specifying continuous systems for new capacity additions, displacing batch configurations that previously dominated installed bases.
- Plug Flow Reactor:Tubular geometries maintain precise residence time distribution for selective catalytic transformations.
- Fluidized Bed Reactor:Solid-gas contacting designs enable uniform temperature distribution for exothermic oxidation processes.
Batch Reactor anchors the volume base while Continuous Reactor gains share at the steepest rate.
Technology:
Cost tiers separate mature thermal methods from premium catalytic systems, with microwave and advanced oxidation commanding 40-60% price premiums that restrict deployment to validation-critical applications.
- Thermal Processing:Direct heating mechanisms using electrical resistance or combustion remain the lowest-capital pathway for temperature-driven reactions, preserving dominance in commodity chemical production. Waste management facilities in India specify thermal processing for hazardous waste neutralization where operational simplicity outweighs energy efficiency considerations.
- Catalytic Processing:Surface-mediated reaction pathways achieve selective conversion at reduced temperature-pressure conditions, cutting energy intensity for polymerization operations. Pharmaceutical manufacturers in Switzerland absorb premium equipment costs to meet EMA yield consistency requirements for active pharmaceutical ingredient synthesis.
- Microwave Processing:Electromagnetic energy delivery enables rapid volumetric heating with precise thermal control.
- Advanced Oxidation:Radical-based contaminant destruction targets recalcitrant organic compounds in water treatment applications.
Thermal Processing retains the broadest installed base while Catalytic Processing commands the highest margin expansion trajectory.
End User:
Customer type determines specification intensity, with pharmaceutical buyers demanding validated clean-in-place systems that chemical manufacturers rarely require.
- Chemical Manufacturing:Polymer and specialty chemical producers represent the largest equipment absorbers, with procurement concentrated among integrated producers and engineering-procurement-construction firms consolidating vendor lists. Capacity expansion in China's Yangtze River Delta and India's Gujarat corridor is driving reactor orders for solvent-free synthesis processes.
- Pharmaceutical:FDA-regulated drug manufacturers impose documentation burdens that disqualify generalist fabricators, creating protected margin pools for qualified suppliers. CDSCO alignment with international GMP standards is accelerating domestic pharmaceutical manufacturing investment and associated reactor procurement in India.
- Food & Beverage:Nutraceutical extraction and enzyme catalysis applications require sanitary-grade surface finishes.
- Waste Management:Hazardous waste neutralization operators prioritize throughput reliability over conversion selectivity.
Chemical Manufacturing absorbs the greatest equipment tonnage while Pharmaceutical generates the highest revenue per unit.
Application:
Maturity gradients separate established polymer production from emerging nutrient recovery, with bioremediation applications still seeking economic validation at commercial scale.
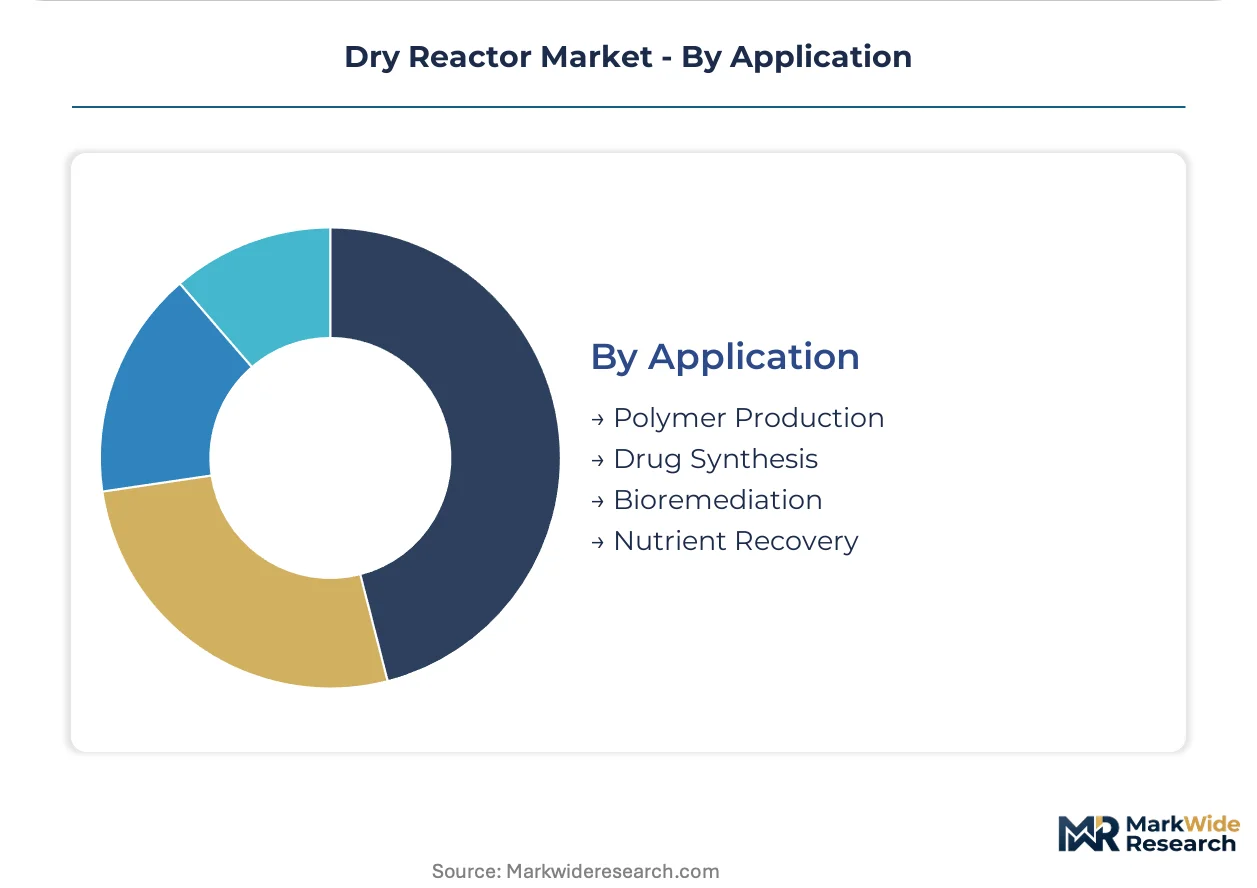
- Polymer Production:Bulk polymerization of polyethylene, polypropylene, and engineering thermoplastics consumes the largest reactor volumes, with continuous processing displacing batch configurations in high-throughput operations. Germany's chemical manufacturing belt is retrofitting existing plants with dry reactor technology to eliminate solvent recovery costs.
- Drug Synthesis:Active pharmaceutical ingredient manufacturing demands precision temperature control and validated cleaning protocols that command equipment premiums. Swiss and Belgian pharmaceutical clusters are absorbing premium pricing for REACH-compliant systems to maintain CE-marked market access.
- Bioremediation:Microbial degradation of soil and groundwater contaminants employs specialized reactor geometries for biofilm support.
- Nutrient Recovery:Phosphorus and nitrogen extraction from waste streams represents an emerging application with unproven scale economics.
Polymer Production dominates current procurement volumes while Drug Synthesis exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium reactor systems in Switzerland and Belgium command pricing premiums exceeding those in Indian manufacturing corridors, creating a bifurcated procurement landscape where regulatory stringency directly translates to vendor margins.
Germany
REACH compliance deadlines are accelerating replacement of legacy carbon-steel batch reactors across the Ruhr chemical manufacturing belt. The EU Green Deal mandates ceramic-lined vessel alternatives, forcing fabricators to absorb qualification costs for solid-alloy construction methods. BASF and Lanxess facilities in Ludwigshafen are retrofitting plants with dry reactor technology to eliminate solvent recovery infrastructure.
China
SAMR enforcement of GB pressure equipment standards extends certification timelines for imported systems, favoring domestic fabricators with established approval pathways. The Yangtze River Delta specialty chemical corridor is specifying continuous reactor configurations for new capacity additions, displacing batch architectures that previously dominated installed bases. Dual carbon goals are tightening energy intensity requirements for polymerization operations.
India
CDSCO alignment with international GMP standards is accelerating pharmaceutical manufacturing investment in the Gujarat corridor. Engineering-procurement-construction firms are consolidating vendor lists, compressing margin pools for equipment suppliers without turnkey capabilities. Reliance Industries and Deepak Nitrite are scaling solvent-free synthesis capacity with dry reactor procurement concentrated among integrated producers.
United States
FDA oversight of pharmaceutical-grade reactor standards creates protected margin pools for suppliers with validated clean-in-place systems. The Gulf Coast petrochemical corridor is absorbing thermal processing equipment for commodity chemical production where operational simplicity outweighs energy efficiency premiums. ASME pressure vessel certification delays are compressing supplier cash conversion cycles.
Switzerland
EMA yield consistency requirements for active pharmaceutical ingredient synthesis command equipment premiums from Roche and Novartis manufacturing networks. REACH authorization restrictions for chromium compounds are accelerating qualification of ceramic-lined reactor alternatives. Swissmedic oversight maintains validation documentation burdens that disqualify generalist fabricators from pharmaceutical procurement.
Dry Reactor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the fabrication stack. The vendor base organizes around three functional tiers: integrated system providers with turnkey capabilities, specialized vessel fabricators with alloy expertise, and regional assemblers serving price-sensitive procurement. Consolidation pressure is narrowing direct sales channels as engineering-procurement-construction firms compress approved vendor lists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with fabricators seeking geographic coverage and certification breadth.
Among Asia-Pacific-based platform integrators, Hitachi Energy leverages transformer and reactor integration expertise to anchor large industrial contracts. Siemens Energy occupies a position within the thermal processing technology tier, while ABB exemplifies geographic dominance across European chemical corridors. These three anchors represent divergent strategic archetypes: system integration leadership, technology specialization, and regional market penetration.
| Leading Market Players |
|---|
| Hitachi Energy |
| TBEA |
| GE Vernova |
| Siemens Energy |
| Trench Group |
| ABB |
| Rakesh Transformers |
| Hainan Jinpan Smart Technology |
| Hada Electric |
| Others |
Pricing and Supply Chain Analysis
China's dominance in nickel and specialty steel production anchors input cost volatility for corrosion-resistant alloy fabricators, compressing margins for vessel constructors without long-term supply agreements while concentrating pricing power among integrated producers with captive metallurgical capacity. This upstream concentration forces downstream reactor manufacturers to absorb qualification costs for REACH-compliant ceramic-lined alternatives or surrender margin to alloy suppliers.
Pricing Analysis
Configured-to-order pricing for validated pharmaceutical-grade systems commands 40-60% premiums over standard thermal processing units for commodity chemical applications. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated clean-in-place systems from REACH-certified industrial units and basic carbon-steel configurations. Cost compression in standard-tier equipment is intensifying because engineering-procurement-construction firms are consolidating vendor lists and demanding turnkey packaging. Chemical manufacturers in India exhibit highest price sensitivity, while Swiss pharmaceutical clusters absorb premium pricing to maintain CE-marked market access.
Supply Chain Analysis
Extended payment terms from engineering-procurement-construction firms are forcing reactor fabricators to utilize supply-chain finance facilities, stretching cash conversion cycles for specialized vessel constructors. Manufacturing concentration rests on China for pressure equipment components, Germany for precision alloy fabrication, and India for modular skid assembly. Raw material dependencies draw from Indonesian nickel, South African chromium, and Japanese specialty steel. Single-source vulnerability around ASME-certified inspector availability creates bottlenecks. Distribution runs through direct vendor relationships with integrated chemical producers and engineering-procurement-construction consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dry reactor incumbents face substitution pressure from advanced oxidation wet scrubbing systems in hazardous waste applications, requiring defensive positioning around solvent-free synthesis validation. Incumbents must pre-empt margin erosion by securing long-term alloy supply agreements and accelerating ceramic-lined vessel qualifications before REACH authorization restrictions tighten.
For Market Incumbents: Pre-empt wet scrubbing substitution by embedding dry reactor technology into engineering-procurement-construction turnkey specifications. Anchor backward integration into nickel and specialty steel supply chains to offset input cost volatility. Accelerate SAMR certification pathways for Chinese market access before domestic fabricators consolidate regional share.
For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat pharmaceutical corridor where CDSCO-GMP alignment is accelerating reactor procurement and vendor lists remain fragmented. Target modular skid-mounted system specifications from engineering-procurement-construction firms seeking reduced field installation timelines. Lead with remote monitoring subscriptions as a standalone software revenue stream.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed vessel fabricators holding ASME certification but lacking turnkey integration capabilities. The five-to-ten-year viability window favors platforms with REACH-compliant ceramic-lined portfolios over legacy chromium-coating dependent operators. Watch for SAMR approval acceleration as inflection signal for foreign manufacturer market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel and specialty steel sourcing insulates margins from commodity volatility. |
| REACH-Compliant Vessel Qualification | Ceramic-lined construction methods secure CE-marked access across European pharmaceutical clusters. |
| Modular Skid-Mounted System Development | Pre-integrated packages reduce commissioning risk for engineering-procurement-construction firms. |
| SAMR Certification Acceleration | GB standards compliance unlocks Yangtze River Delta specialty chemical corridor procurement. |
| Digital Twin Platform Deployment | Predictive maintenance analytics shift revenue from spare parts toward software-enabled uptime guarantees. |
Research Methodology
A spread of perspectives from plant engineers at BASF and Lanxess facilities, procurement leads at Reliance Industries, technical R&D directors at Swiss pharmaceutical manufacturers, and aftermarket service heads at Hitachi Energy converged on the working assumptions. Primary interview insights were validated against customs and trade data, SEC 10-K filings from listed industrial equipment suppliers, Cefic chemical industry reports, and SAMR pressure equipment registration databases. Bottom-up equipment shipment tallies were triangulated with top-down capital expenditure projections from specialty chemical and pharmaceutical manufacturing facilities.
Demand-supply-balance framing across the analysis window modeled reactor procurement against capacity expansion timelines in Germany's Ruhr belt, China's Yangtze River Delta, and India's Gujarat corridor. Segmentation dimensions included reactor configuration type, processing technology tier, end-use industry intensity, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and capital commitment trajectories. Forecast inputs incorporated REACH compliance deadline acceleration and CDSCO-GMP alignment progress.
Sensitivities concentrate around nickel price volatility, ASME inspector availability constraints, and SAMR approval timeline extensions. Forecasts reflect documented assumptions about engineering-procurement-construction vendor consolidation velocity and ceramic-lined vessel qualification rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Middle East Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Single Wafer Wet Cleaning Equipment Market
Semiconductor Equipment
Vacuum Coating Equipment Market
Semiconductor Equipment
Underfill Dispenser Market
Semiconductor Equipment
UV-Based Nanoimprint Lithography (UV-NIL) System Market
Semiconductor Equipment
High Current Ion Implanter Market
Semiconductor Equipment
Semiconductor Photolithography Equipment Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Wafer Processing Equipment Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Semiconductor Wafer Cleaning Equipment Market