
 Electroceramics Market | 2026-2036
Electroceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Electroceramics Market Analysis
Multilayer co-firing of dielectric and electrode materials is rewriting component architecture for next-generation capacitors. Kyocera Corporation leverages decades of alumina substrate expertise to dominate high-reliability ceramic packages for automotive ECUs. TDK Corporation anchors its position through captive ferrite powder production and vertical control over magnetic core supply chains. Murata Manufacturing Co., Ltd. specializes in monolithic ceramic capacitors, sustaining R&D intensity that pushes dielectric layer thickness below one micron.
Electroceramics are inorganic, non-metallic materials engineered to exhibit specific electrical properties including piezoelectricity, ferroelectricity, semiconduction, or superconductivity, typically formulated from barium titanate, lead zirconate titanate, or yttrium-barium-copper oxide and densified through sintering at temperatures exceeding 1,200°C to achieve precise dielectric constants and insulation resistance for electronic, energy, and sensor applications. Piezoelectric ceramics generate the fastest growth as ultrasonic transducers and MEMS resonators displace quartz in timing devices. Dielectric ceramics occupy the largest value pool because multilayer ceramic capacitors consume the majority of electroceramic tonnage across consumer and industrial electronics.
Japan's METI enforces JIS standards for electronic ceramics that constrain import competition and elevate domestic quality benchmarks, while REACH in Europe restricts lead-based piezoelectric formulations and accelerates development of potassium-sodium niobate alternatives. China's GB standards and NMPA medical device rules shape product qualification pathways for ceramic implants and diagnostic sensors. Stakeholders must monitor how evolving chemical restrictions and additive manufacturing qualifications converge to determine which electroceramic technologies gain commercial traction in regulated end-use sectors.
Market Dynamics
Reactive sintering methods and sub-micron dielectric layer engineering are compressing capacitor form factors while stricter chemical compliance regimes force material reformulation across electroceramic supply chains.
Growth Catalysts
- REACH chemical compliance:European restrictions on lead-based piezoelectric formulations accelerate potassium-sodium niobate development, opening patent white space for alternative ceramic compositions.
- 5G infrastructure buildout:Base station densification drives multilayer ceramic capacitor volume for RF filtering and power management modules in network equipment.
- Electric vehicle powertrains:Inverter and onboard charger applications consume high-voltage dielectric ceramics for DC-link capacitors and snubber circuits.
Market Restraints
- Raw material concentration:High-purity barium titanate and rare-earth dopants concentrate among Chinese suppliers, creating price volatility exposure for Japanese and European formulators.
- Technical limitation:Dielectric constant degradation above 150°C constrains ceramic capacitor deployment in engine-bay automotive electronics, capping addressable thermal envelopes.
- Substitution threat:Polymer and film capacitors encroach on low-voltage ceramic applications where volumetric efficiency matters less than cost.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and component production create localized electroceramic demand from contract assemblers.
- Additive manufacturing qualification:Binder jet and vat photopolymerization of technical ceramics enable complex resonator geometries impossible with conventional pressing.
- Medical device sensors:NMPA and FDA pathways for implantable piezoelectric sensors expand addressable markets beyond industrial and consumer electronics.
Industry Challenges
- Process engineering talent scarcity:Sintering atmosphere control and grain boundary engineering expertise concentrates among retiring specialists in Japanese and German research institutes.
- Cleanroom capex intensity:Sub-micron dielectric layer deposition requires Class 1000 or better fabrication environments, raising facility investment thresholds for new entrants.
- Cross-border certification lag:JIS-to-REACH material equivalence documentation delays product launches by 8-14 months for multi-region suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroceramics Market |
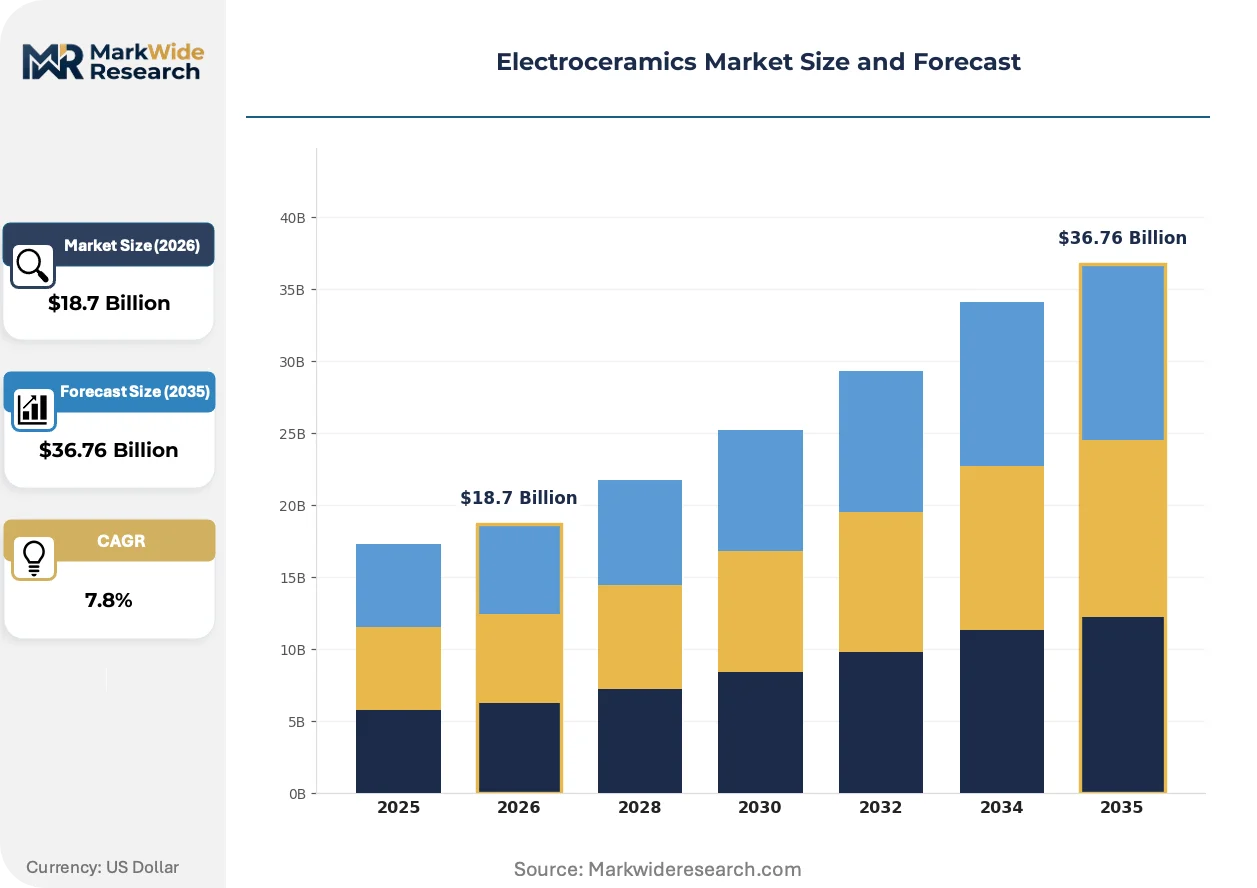
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piezoelectric Ceramics, Dielectric Ceramics, Magnetic Ceramics, Superconducting Ceramics Application: Capacitors, Sensors, Insulators, Transducers End User: Electronics, Automotive, Aerospace, Medical Devices Technology: 3D Printing, Traditional Casting, Reactive Sintering, Hot Pressing |
| Companies Covered | CeramTec GmbH, 3M Company, Kyocera Corporation, TDK Corporation, NGK Spark Plug Co., Ltd., Murata Manufacturing Co., Ltd., Morgan Advanced Materials, Maruwa Co. Ltd, CoorsTek, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroceramics Market Emerging Trajectories
Digital twin integration and closed-loop process control are compressing electroceramic development cycles while regulatory chemical restrictions and buyer consolidation reshape competitive requirements.
Artificial intelligence-driven defect detection is digitizing quality assurance workflows in multilayer ceramic capacitor production. Tier-one automotive suppliers now mandate 100% automated optical inspection for AEC-Q200 qualified components. This technology is digitizing yield optimization by predicting sintering defects from green-tape density variations before kiln entry.
Europe's F-Gas Regulation and REACH restrictions on per- and polyfluoroalkyl substances force reformulation of ceramic processing aids and dielectric coatings. Manufacturers must qualify fluorine-free dispersants and binders without sacrificing layer uniformity. Japanese suppliers with captive chemical synthesis capabilities respond fastest, while smaller European formulators face 18-24 month reformulation timelines.
Automotive tier-one buyers now consolidate electroceramic procurement through direct long-term agreements with Japanese and Korean manufacturers, bypassing traditional distributor channels. This disintermediation concentrates volume with vertically integrated suppliers capable of AEC-Q200, IATF 16949, and customer-specific PPAP documentation. The shift is most visible in Germany and Japan, where powertrain electrification programs demand multi-year supply security.
Electroceramics Market Segmentation
Electroceramic procurement cycles vary dramatically by application, with consumer electronics components turning over in months while aerospace qualification timelines stretch across years. Understanding these velocity differentials helps suppliers align inventory strategies with demand predictability.
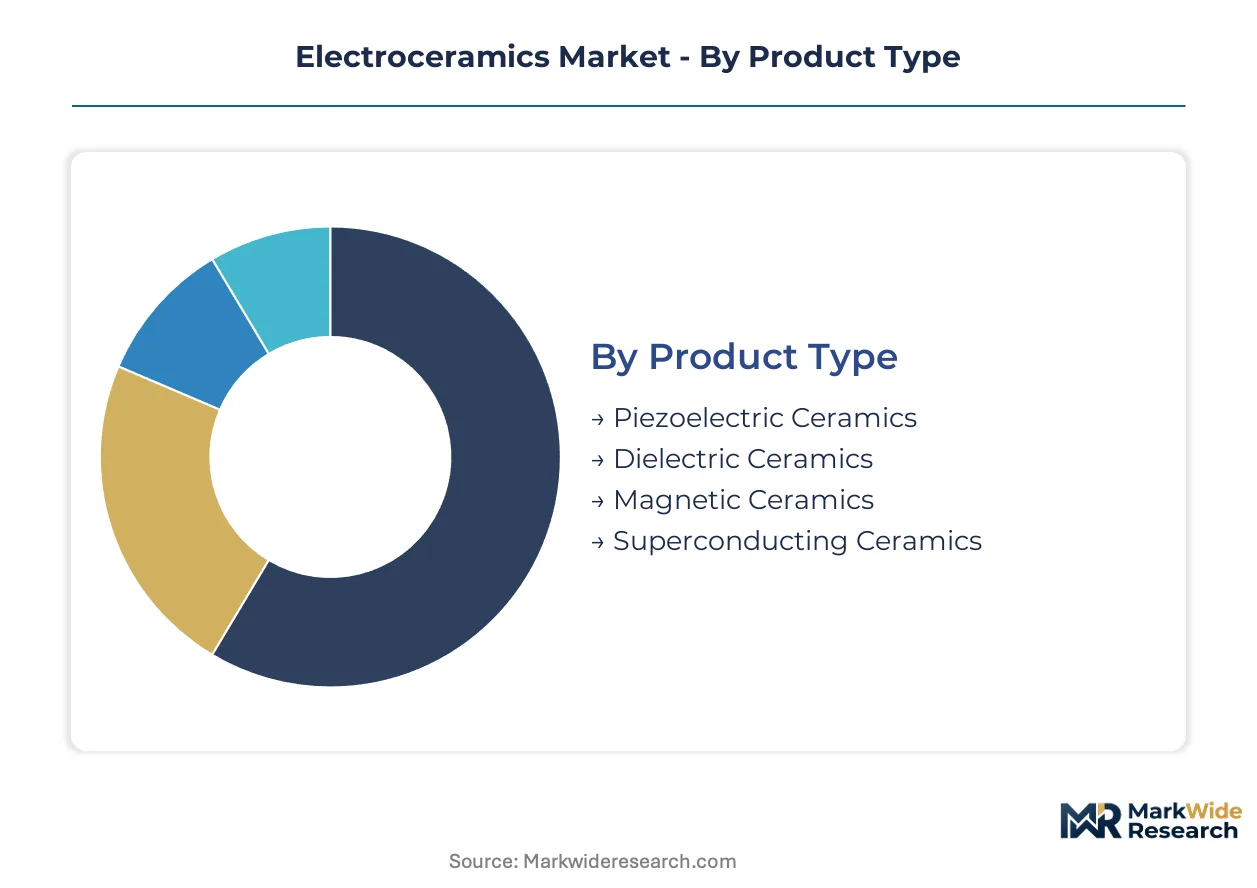
Product Type:
Dielectric ceramics rotate through production fastest due to capacitor demand volatility, while superconducting ceramics move slowest given cryogenic system integration timelines.
- Dielectric Ceramics:Formulated from barium titanate and rare-earth dopants, these materials achieve precise dielectric constants through sintering above 1,200°C. Automotive DC-link capacitors in Germany and Japan consume the highest-specification grades as inverter power densities climb. REACH restrictions on lead-based formulations force continuous material qualification cycles.
- Piezoelectric Ceramics:Lead zirconate titanate and emerging potassium-sodium niobate compositions generate mechanical-electrical energy conversion. Ultrasonic transducers for medical imaging in Japan and MEMS resonators displacing quartz timing devices drive fastest formulation turnover. METI JIS standards constrain import competition and accelerate domestic iteration.
- Magnetic Ceramics:Ferrite powders sintered into magnetic cores filter EMI in power electronics and construct inductor windings.
- Superconducting Ceramics:Yttrium-barium-copper oxide formulations enable lossless current transmission in MRI magnets and fusion research.
Dielectric ceramics dominate installed base. Piezoelectric ceramics are where expansion concentrates.
Application:
Cost tier stratification separates commodity capacitor applications from premium sensor and transducer deployments requiring extended qualification.
- Capacitors:Multilayer ceramic constructions with sub-micron dielectric layers filter noise and store charge in power management modules. 5G base station densification across Japan and South Korea drives volume, while electric vehicle onboard chargers in Germany specify AEC-Q200 qualified grades. Polymer alternatives encroach on low-voltage consumer segments.
- Sensors:Piezoelectric and dielectric ceramics detect pressure, acceleration, and temperature with microsecond response times. Implantable medical devices regulated by FDA and NMPA pathways command premium pricing and extended development cycles. MEMS integration in automotive safety systems accelerates demand.
- Insulators:High-purity alumina substrates isolate high-voltage semiconductor packages and RF transmission lines.
- Transducers:Ultrasonic generators convert electrical signals to mechanical vibration for medical imaging and industrial cleaning.
Capacitors capture highest volume throughput. Sensors deliver steepest expansion trajectory.
End User:
Customer type determines margin structure, with automotive and medical buyers demanding certification documentation that consumer electronics purchasers rarely require.
- Electronics:Smartphone, computing, and network equipment manufacturers specify multilayer ceramic capacitors by the billions annually. Japanese producers Kyocera, TDK, and Murata anchor concentrated supply clusters serving RF filtering and power management modules. Tier-one buyers now consolidate procurement through direct long-term agreements.
- Automotive:Powertrain electrification programs in Germany and Japan consume high-voltage dielectric ceramics for inverters and DC-link capacitors. IATF 16949 and customer-specific PPAP documentation requirements extend supplier qualification timelines. Engine-bay thermal constraints above 150°C limit ceramic capacitor deployment.
- Aerospace:Satellite and avionics applications demand radiation-hardened components with decade-long reliability guarantees.
- Medical Devices:Diagnostic imaging and implantable sensors regulated by FDA, PMDA, and NMPA pathways expand addressable markets beyond industrial applications.
Electronics commands largest installed base. Automotive is where expansion concentrates.
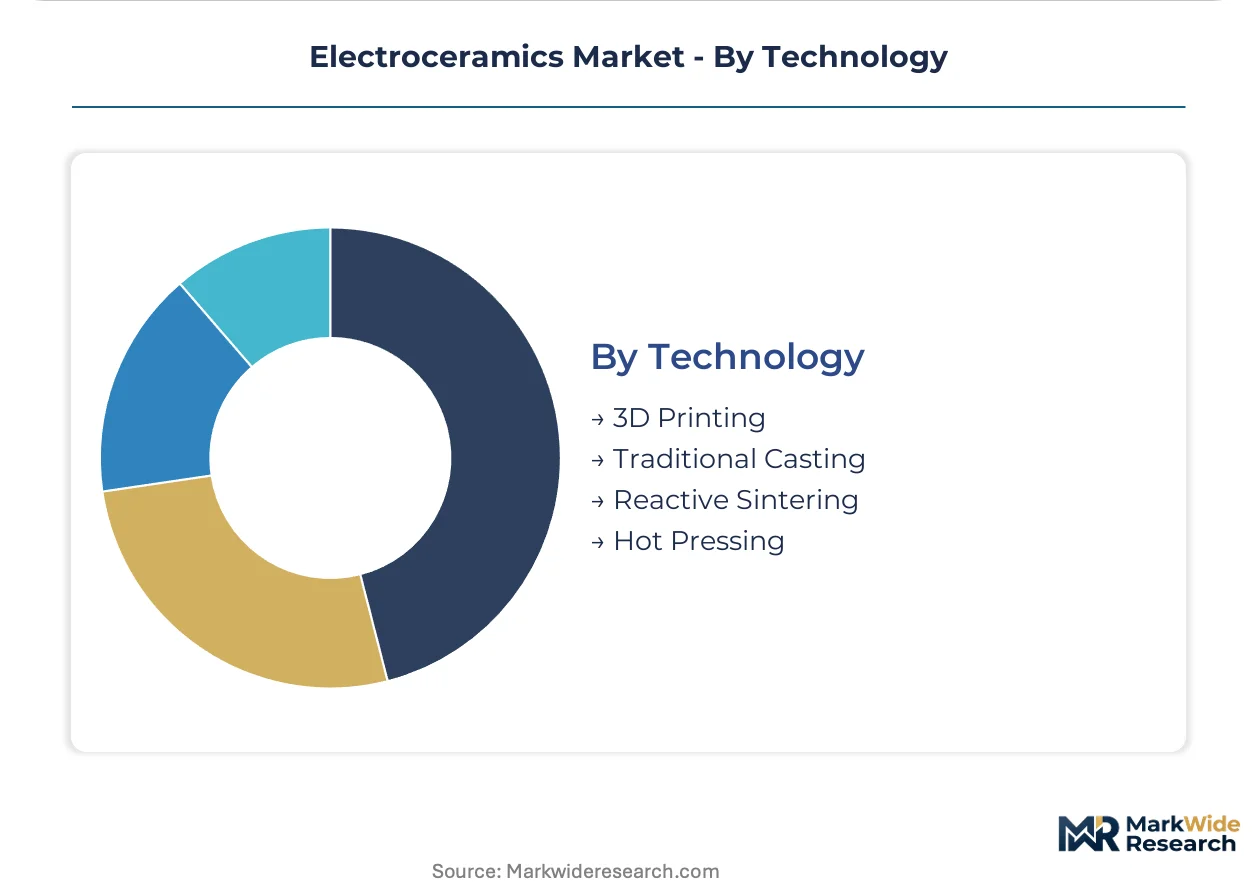
Technology:
Volume concentration favors traditional casting for commodity dielectrics, while emerging additive methods capture premium geometries impossible through pressing.
- Reactive Sintering:Solid-state reactions between constituent oxides densify ceramics at reduced temperatures while preserving fine grain structures. Japanese and German research institutes concentrate expertise in atmosphere control and grain boundary engineering. The method compresses capacitor form factors for 5G and EV applications.
- 3D Printing:Binder jet and vat photopolymerization of technical ceramics enable complex resonator geometries and conformal cooling channels. Medical device and aerospace prototyping accelerates development cycles, though production scale remains limited. Cleanroom capex intensity raises facility investment thresholds.
- Traditional Casting:Tape casting and dry pressing dominate multilayer ceramic capacitor mass production.
- Hot Pressing:Uniaxial pressure during sintering achieves full density in transparent ceramics and specialized piezoelectric compositions.
Traditional casting dominates installed base. Reactive sintering is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese electroceramic exports flow predominantly into German automotive assembly plants and South Korean consumer electronics factories, establishing a tripolar trade architecture that concentrates high-specification dielectric and piezoelectric procurement decisions within these three manufacturing basins.
Japan
Kyoto-Osaka industrial corridor hosts concentrated multilayer ceramic capacitor fabrication for 5G base station and electric vehicle powertrain applications. METI enforces JIS standards that constrain import competition and elevate domestic quality benchmarks for automotive-grade components. Kyocera, TDK, and Murata anchor production clusters in Kansai and Kanto regions, supplying AEC-Q200 qualified ceramics to German tier-one suppliers.
Germany
Powertrain electrification programs at BMW, Volkswagen, and Mercedes-Benz consume high-voltage dielectric ceramics for inverter DC-link capacitors and onboard charger modules. KBA vehicle type-approval requirements and REACH chemical compliance force continuous material qualification cycles for lead-free piezoelectric formulations. Bavaria and Baden-Württemberg concentrate automotive electronics development, with Stuttgart and Munich anchoring supplier qualification hubs.
China
Domestic electric vehicle manufacturers BYD and NIO drive multilayer ceramic capacitor volume for battery management systems and DC-fast charging infrastructure. GB standards and NMPA medical device rules shape qualification pathways for ceramic implants and diagnostic sensors. Yangtze River Delta and Pearl River Delta clusters concentrate both high-purity barium titanate raw material refining and finished component assembly.
South Korea
Samsung Electronics and SK Hynix specify multilayer ceramic capacitors by the billions annually for smartphone and memory module production. MFDS medical device regulations and national semiconductor self-sufficiency initiatives accelerate localized electroceramic sourcing requirements. Seoul Capital Area and Busan-Ulsan industrial zones host concentrated electronics manufacturing demand.
United States
Defense and aerospace applications in satellite communications and radar systems demand radiation-hardened ceramic components with extended reliability guarantees. FDA and FAA certification pathways for implantable sensors and avionics extend development timelines beyond consumer electronics cycles. California and Texas anchor electronics design activity, with Arizona and New Mexico emerging as semiconductor packaging hubs requiring ceramic substrate supply.
Electroceramics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships that favor vertically integrated Japanese and Korean manufacturers capable of AEC-Q200, IATF 16949, and customer-specific PPAP documentation. The structure concentrates volume with formulators possessing captive ferrite powder production and in-house chemical synthesis capabilities. Three archetypes dominate: diversified materials conglomerates with ceramics divisions, pure-play electroceramic specialists, and captive electronics manufacturers with internal ceramic production. Competitive moves center on direct long-term procurement agreements with automotive tier-ones and REACH-compliant material reformulation to capture European regulatory-driven substitution demand.
Among Japanese manufacturers, Kyocera Corporation, TDK Corporation, and Murata Manufacturing Co., Ltd. occupy positions representing the vertically integrated archetype with decades of alumina substrate and ferrite powder expertise. German-based CeramTec GmbH exemplifies the European specialist model focused on medical and industrial ceramic applications. These named entities anchor industry-level commentary on how geographic concentration of sintering expertise and cleanroom fabrication capability shapes competitive access to premium-tier automotive and medical device supply chains.
| Leading Market Players |
|---|
| CeramTec GmbH |
| 3M Company |
| Kyocera Corporation |
| TDK Corporation |
| NGK Spark Plug Co., Ltd. |
| Murata Manufacturing Co., Ltd. |
| Morgan Advanced Materials |
| Maruwa Co. Ltd |
| CoorsTek, Inc. |
| Others |
Supply Flow & Price Mechanics
Chinese high-purity barium titanate refiners and rare-earth dopant suppliers anchor upstream concentration, feeding margin pools to Japanese formulators with captive powder synthesis and AEC-Q200 certification capabilities that command premium positioning in automotive DC-link capacitor procurement.
Pricing Analysis
Sub-micron dielectric layer engineering creates a three-tier pricing structure across premium, standard, and economy levels. Automotive AEC-Q200 qualified grades command substantial premiums over consumer electronics specifications due to IATF 16949 documentation and customer-specific PPAP requirements. Cost compression in low-voltage consumer segments intensifies because polymer film capacitors encroach on volumetric efficiency applications. Electronics contract manufacturers exhibit highest price sensitivity, while German automotive tier-ones prioritize supply security over unit cost.
Supply Chain Analysis
Foxconn, Jabil, and Flex hold concentrated electronics manufacturing services capacity for multilayer ceramic capacitor integration. Japan, South Korea, and China anchor geographic supply concentration. High-purity barium titanate, rare-earth dopants, and nickel electrode pastes constitute critical input dependencies. Single-source vulnerability concentrates in Chinese rare-earth processing. Distribution runs through direct long-term agreements between Japanese formulators and automotive tier-ones, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactive sintering methods and REACH-driven lead-free piezoelectric reformulation constitute a dual technological-regulatory inflection accelerating market disruption. Stakeholders must align capability investments with these converging forces.
For Market Incumbents: Insulate margin pools by deepening backward integration into ferrite powder production and expanding Class 1000 cleanroom capacity in Kansai and Kanto regions. Polymer capacitor substitution in low-voltage consumer segments threatens volume-based cost structures. Prioritize AEC-Q200 and IATF 16949 certification maintenance to defend automotive procurement consolidation. For New Entrants and Emerging Players: Build out potassium-sodium niobate piezoelectric formulation capabilities to exploit patent white space opened by REACH lead restrictions. India's PLI scheme electronics manufacturing incentives represent the most penetrable geography for localized supply. Pursue medical device sensor qualification through FDA and NMPA pathways as differentiation anchor. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sub-micron dielectric layer fabrication due to cleanroom capex requirements. The five-to-ten year viability window favors acquisition of German and Japanese research institute spinouts possessing sintering atmosphere control expertise. Monitor additive manufacturing qualification timelines for ceramic resonator production as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite Powder Production | TDK Corporation's captive magnetic core supply chains demonstrate margin protection against raw material volatility. |
| REACH-Compliant Material Reformulation | Potassium-sodium niobate development opens patent white space for European formulators facing lead restrictions. |
| Direct Long-Term Supply Agreements | Kyocera's AEC-Q200 qualified ceramic packages bypass distributor channels to secure German automotive tier-one volume. |
| Additive Manufacturing Qualification | Binder jet ceramic printing enables complex resonator geometries for medical device and aerospace prototyping. |
| India PLI Scheme Localization | Contract assembler demand from semiconductor packaging hubs creates electroceramic procurement pull. |
Methodological Framework
The analysis maps dielectric ceramics, piezoelectric ceramics, magnetic ceramics, and superconducting ceramics sub-sectors, each validated through capacitor procurement managers, automotive tier-one supplier quality engineers, medical device regulatory affairs leads, and sintering process specialists. Primary interviews with Japanese and German research institute directors combined with secondary validation from SEC 10-K filings, METI industrial statistics, ECHA REACH registration databases, and customs trade data. Bottom-up capacity utilization estimates and top-down end-use demand aggregation provided triangulation.
Fixed assumptions include continued 5G infrastructure buildout, sustained electric vehicle powertrain electrification programs, and stable REACH chemical compliance timelines across the projection horizon. Segmentation dimensions modeled encompass material type, application, end-user industry, and fabrication technology. CAGRs derived from elasticity-adjusted demand curves incorporating content-per-vehicle trajectories for DC-link capacitors and base station densification rates for RF filtering modules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed formulators or accelerated polymer capacitor substitution would shift outcomes. Quarterly review of rare-earth export quotas, JIS-to-REACH material equivalence documentation timelines, and automotive PPAP approval backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Global Gallium Nitride Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
North America Semiconductor Materials Market