
 Asia Pacific Polyvinylidene Fluoride (PVDF) Market | 2026-2036
Asia Pacific Polyvinylidene Fluoride (PVDF) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Polyvinylidene Fluoride (PVDF) Market Intelligence
China's massive expansion of PVDF production capacity is reshaping the competitive positioning of suppliers across Asia Pacific. This build-out directly challenges established non-Chinese producers. Arkema leverages its global R&D network to offer specialized copolymer grades for high-end applications. In contrast, domestic producers like Dongyue Group and Zhejiang Juhua compete on manufacturing scale and cost-efficiency, particularly for the high-volume battery-grade homopolymer market.
Polyvinylidene fluoride is a high-performance, semi-crystalline thermoplastic fluoropolymer created through the polymerization of vinylidene difluoride monomer. Its exceptional chemical inertness, UV resistance, and thermal stability make it essential for components in harsh industrial settings. Homopolymer product types constitute the bulk of production, while copolymers provide flexibility for applications like membranes in water treatment. The powder form is a crucial input for electrode binders, driving demand within the electrical and electronics application segment.
Material quality and safety are governed by national frameworks, including China's GB standards for battery components and Japan's JIS standards for industrial materials. India's BIS certification requirements also impact imported finished goods containing PVDF. These regulations dictate material specifications and influence market access across the region. Consequently, navigating the concentrated supply chain for the vinylidene difluoride monomer precursor remains the primary strategic consideration for producers.
Market Dynamics
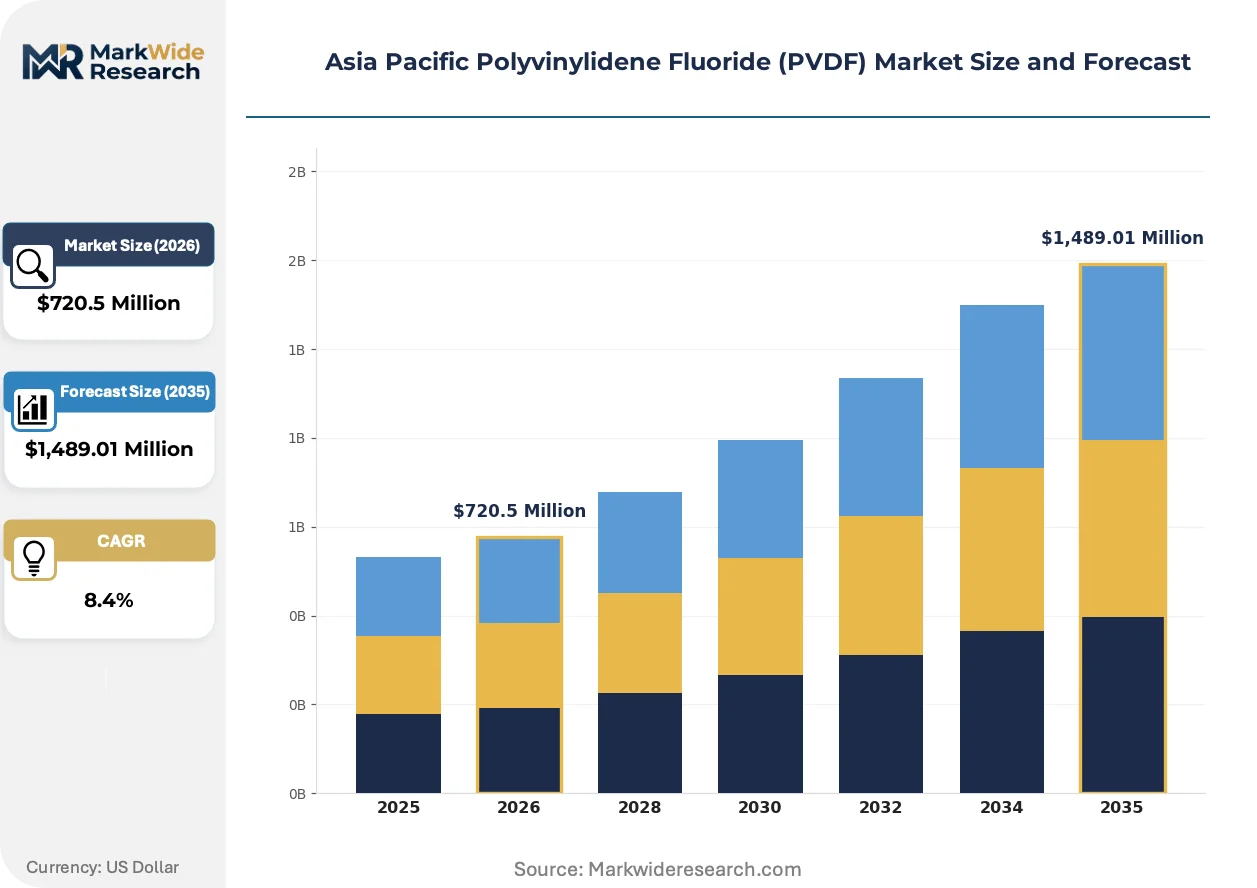
The intense concentration of new production capacity within China, driven by strategic national goals for electric mobility, is the central force defining competitive dynamics and supply chain structures across the Asia Pacific PVDF market.
Growth Catalysts
- Electric Vehicle Policies:Government mandates, particularly China's dual carbon goals, accelerate the transition to electric vehicles, directly boosting consumption of PVDF as a critical binder and separator coating in lithium-ion batteries.
- Water Treatment Sector Expansion:The use of PVDF in high-performance membranes for water purification and desalination is expanding, driven by increasing water scarcity and stringent environmental regulations across Asia.
- Advanced Electronics Manufacturing:Demand for high-purity PVDF grades in the semiconductor and electronics industry for applications like chemical handling systems and cleanroom components provides a stable, high-value growth vector.
Market Restraints
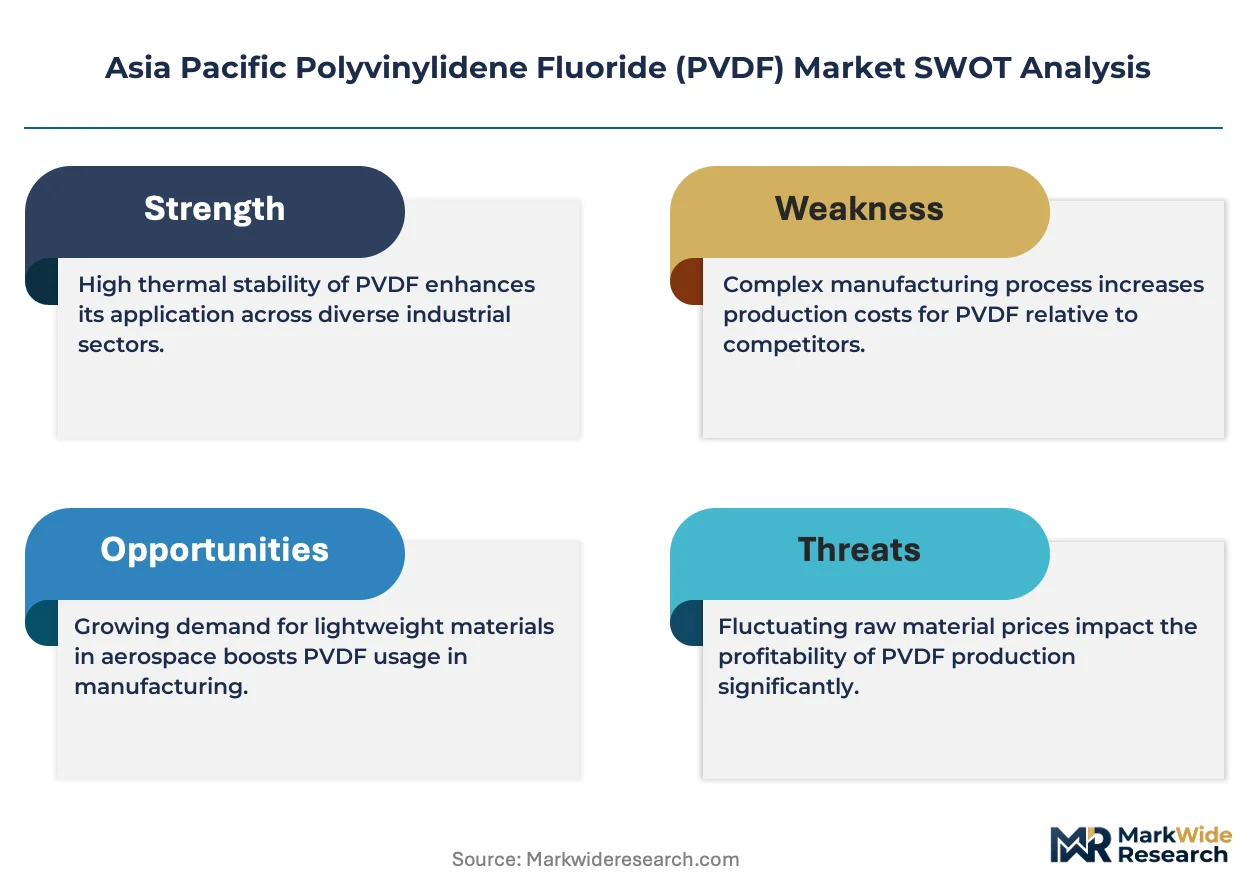
- Precursor Supply Volatility:The supply chain for the essential vinylidene difluoride (VDF) monomer is highly concentrated, exposing PVDF producers to significant price volatility and potential raw material shortages.
- Substitution from Alternative Binders:Ongoing research and development into lower-cost or higher-performance alternative battery binder materials, such as styrene-butadiene rubber (SBR) or novel polymers, presents a long-term substitution threat.
- High Capital Investment:The substantial capital required to construct and commission fluoropolymer production facilities acts as a significant barrier to entry, limiting the number of new competitors.
Strategic Opportunities
- Solid-State Battery Development:The emergence of solid-state batteries creates an opportunity for developing novel PVDF grades or composites that can function as solid electrolytes or binders in next-generation energy storage systems.
- Medical and Healthcare Applications:PVDF's biocompatibility and chemical inertness open opportunities in high-margin medical applications, including sterile filters, membranes for diagnostics, and implantable device components.
- Indian Market Penetration:India's Make in India initiative and growing focus on domestic EV manufacturing present a significant opportunity for PVDF suppliers to establish a footprint in a large, underpenetrated market.
Industry Challenges
- Navigating Regulatory Heterogeneity:Producers face the operational challenge of ensuring products comply with a diverse range of national standards, such as China's GB standards for batteries and Japan's JIS for industrial materials.
- Managing Production Yields:Achieving consistent, high-purity yields for battery and semiconductor-grade PVDF is technically demanding, requiring sophisticated process control and quality assurance to avoid costly batch failures.
- Intellectual Property Protection:In a market characterized by rapid technological advancement and intense competition, protecting proprietary formulations for specialized copolymers and processing techniques is a critical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Polyvinylidene Fluoride (PVDF) Market |
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,489.01 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Terpolymer, Alloy, Compound Application: Electrical & Electronics, Chemical Processing, Water Treatment, Construction, Membranes End User Industry: Semiconductor, Agriculture, Aerospace, Packaging, Textiles Form: Pellets, Powder, Films, Sheets, Coatings |
| Companies Covered | Daikin Industries, Shandong Huaxia Shenzhou New Material, Arkema, Zhejiang Juhua, Shanghai Huayi 3F New Materials, Solvay, Dongyue Group, SINOCHEM LANTIAN, Kureha Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Polyvinylidene Fluoride (PVDF) Market Strategic Shifts & Innovations
Material science advancements are steering the market toward greater specialization. Innovations focus on tailoring PVDF properties to meet the extreme performance requirements of next-generation batteries, advanced filtration systems, and harsh industrial processing environments across the Asia Pacific region.
Specialized Copolymers for High-Performance Applications
PVDF copolymers are engineered to introduce properties like enhanced flexibility or solubility not found in standard homopolymers. Battery and membrane manufacturers are rapidly adopting these specialized grades to improve product durability and processing efficiency. The market for high-value applications is migrating from reliance on generic homopolymers toward these tailored copolymers that deliver specific functional advantages.
Policy-Driven Capacity Expansion in China
China's industrial policies, including its dual carbon goals, serve as a powerful regulatory driver for the PVDF market. These policies create direct incentives and a protected demand base for materials linked to the new energy vehicle supply chain. Consequently, the battery-grade PVDF segment in China is experiencing an unprecedented, state-supported wave of investment in new manufacturing capacity.
Shift Toward Performance-Based Supplier Qualification
End-user procurement in high-tech sectors is moving beyond price, emphasizing material purity, batch-to-batch consistency, and supplier technical support. This shift disrupts traditional commodity sales models, creating an advantage for producers who can provide comprehensive data packages and meet rigorous qualification programs. This trend is most pronounced among leading battery and semiconductor firms in South Korea and Japan.
Asia Pacific Polyvinylidene Fluoride (PVDF) Market Segmentation
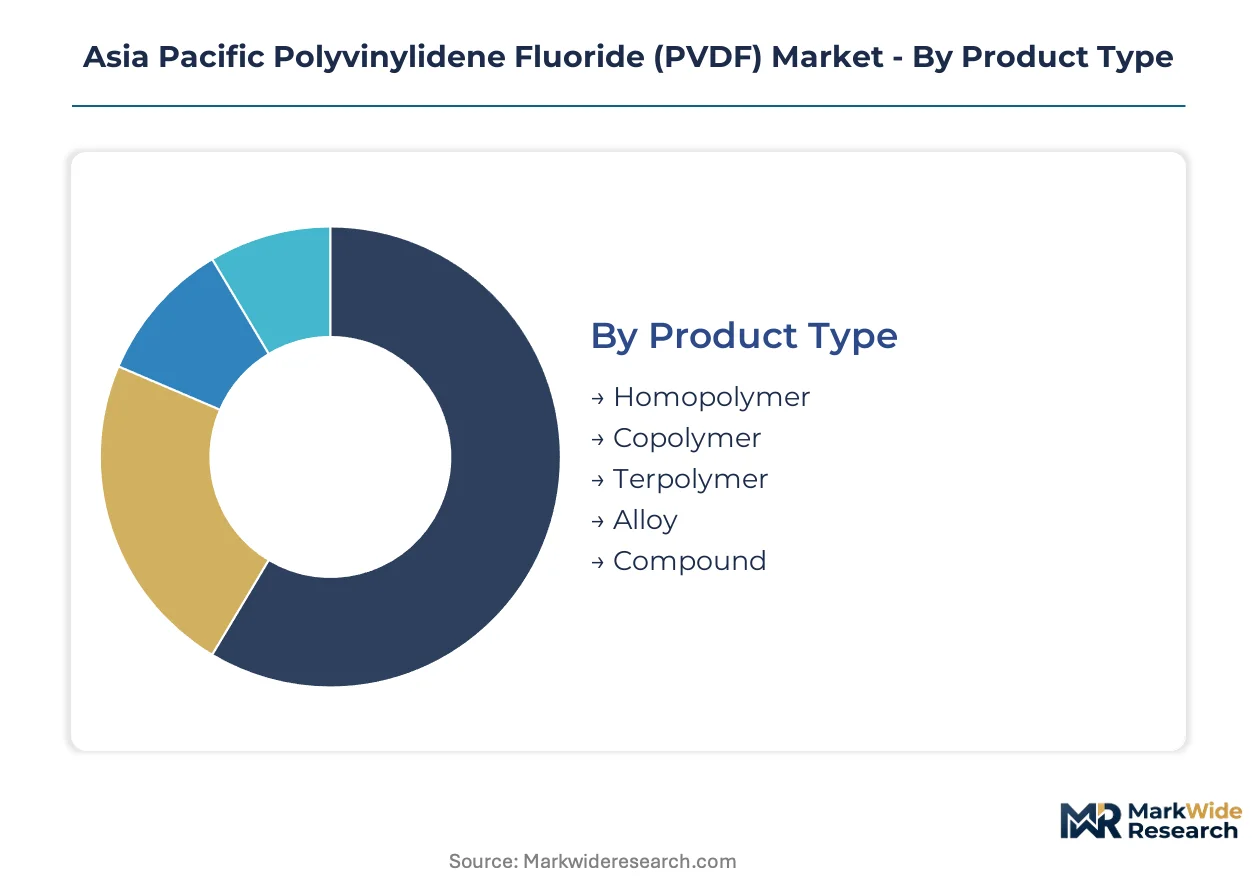
The Asia Pacific PVDF market segmentation highlights the diverse material specifications and application requirements driving demand across the region. Understanding these distinct segments is crucial for producers to align product development and market penetration strategies effectively.
Product Type:
The product type segmentation reveals a mature core alongside emerging specialized variants within the PVDF market.
- Homopolymer:This standard PVDF variant is formed by the polymerization of vinylidene difluoride monomer, known for its high crystallinity and thermal stability. Demand concentrates significantly in China's battery sector, where it serves as a cost-effective binder for lithium-ion battery electrodes.
- Copolymer:Engineered by incorporating additional monomers like hexafluoropropylene, copolymers offer enhanced flexibility, solubility, and lower processing temperatures than homopolymers. These specialized grades are gaining traction in high-end applications such as advanced filtration membranes and specific battery separator coatings across South Korea and Japan.
- Terpolymer:Terpolymers incorporate three distinct monomers, providing highly customized properties like improved impact strength or enhanced chemical resistance for niche applications.
- Alloy:PVDF alloys combine PVDF with other polymers to achieve a synergistic blend of properties, such as improved processability or enhanced mechanical performance for specific industrial uses.
- Compound:PVDF compounds are formulated materials containing additives, fillers, or pigments, tailored to meet precise performance specifications for various end-use products.
Homopolymer retains volume leadership; Copolymer holds the steepest expansion curve.
Application:
Application segments delineate primary volume consumption areas for PVDF across Asia Pacific.
- Electrical & Electronics:This segment includes PVDF's use as a binder in lithium-ion batteries for electric vehicles and portable electronics, alongside its application in semiconductor manufacturing for fluid handling systems. China's new energy vehicle policies directly propel this demand.
- Water Treatment:PVDF is critical for manufacturing high-performance membranes used in ultrafiltration and microfiltration processes for water purification and desalination. Increasing water scarcity and stringent environmental regulations in countries like India and Singapore drive this application.
- Chemical Processing:PVDF's exceptional chemical inertness and corrosion resistance make it ideal for linings, piping, and components in chemical processing equipment. Industries handling aggressive chemicals across Japan and South Korea rely on PVDF for durability.
- Construction:PVDF is utilized in architectural coatings, films, and piping systems due to its excellent UV resistance and weatherability, providing long-lasting protection for building exteriors.
- Membranes:This application specifically refers to PVDF's use in various separation technologies, including those for industrial gas separation and medical diagnostics, beyond just water treatment.
Electrical & Electronics applications command the largest market share, while Water Treatment applications are gaining share fastest.
End User Industry:
End user industries categorize the diverse customer base leveraging PVDF's specialized properties.
- Semiconductor:The semiconductor industry demands ultra-high purity PVDF for components in cleanroom environments, chemical delivery systems, and wafer processing equipment. South Korean and Taiwanese fabs require stringent material specifications.
- Aerospace:PVDF's lightweight nature, high strength-to-weight ratio, and resistance to harsh operating conditions make it suitable for aerospace components and wire insulation. Japanese aerospace manufacturers integrate these materials for performance.
- Agriculture:Specialized PVDF films and components find use in agricultural applications requiring weather resistance and chemical stability, such as greenhouse coverings or irrigation system parts.
- Packaging:PVDF is employed in high-performance packaging films and coatings, offering barrier properties and chemical resistance for sensitive goods or harsh environments.
- Textiles:Technical textiles incorporate PVDF for enhanced durability, chemical resistance, and UV stability in protective apparel or outdoor fabrics.
The Semiconductor industry commands premium pricing, while Packaging represents a high-volume, cost-sensitive segment.
Form:
PVDF is supplied in various forms, each tailored for specific processing techniques and end-use applications.
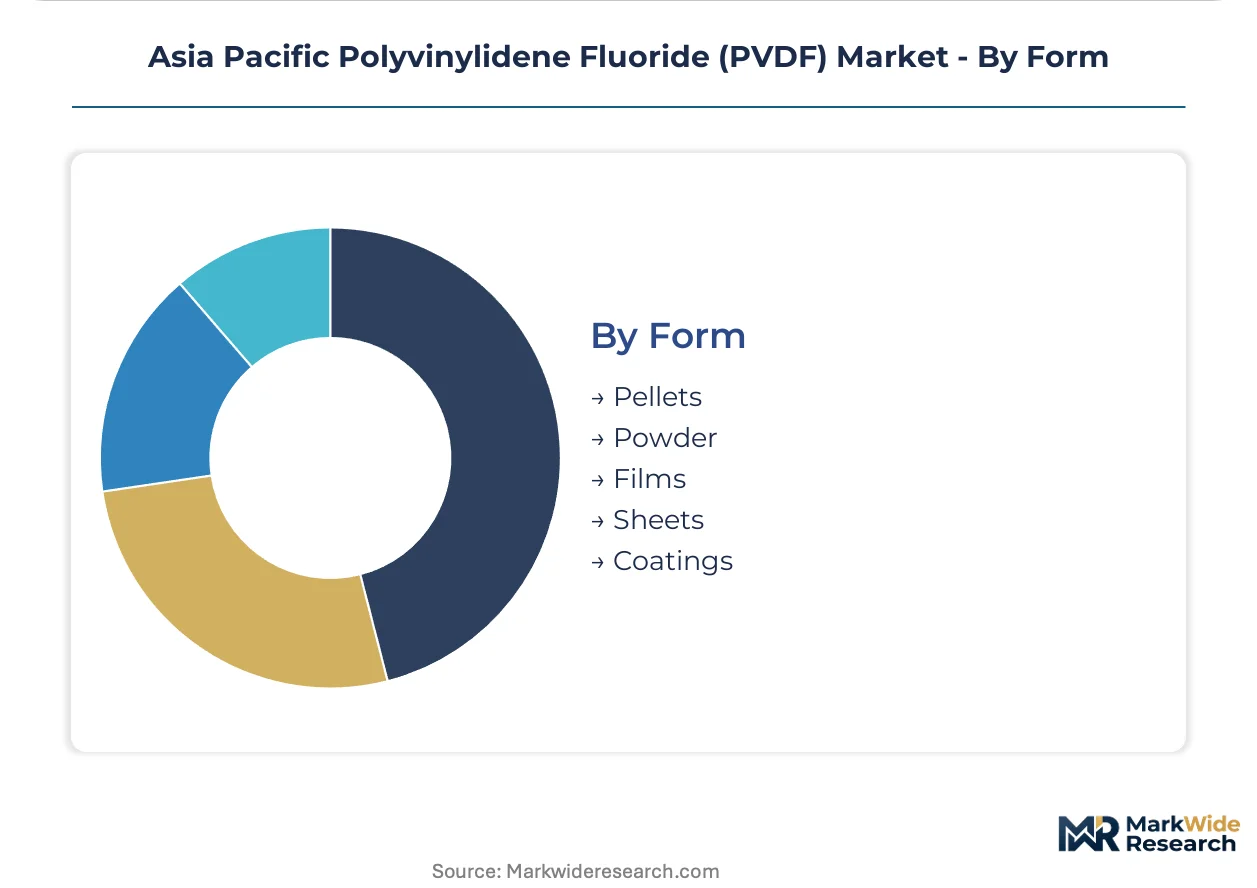
- Powder:PVDF powder is a crucial input for electrode binders in lithium-ion batteries and is also used in specialized coatings and compounding. Its fine particle size facilitates dispersion in slurries for battery electrode manufacturing, particularly in China.
- Pellets:PVDF pellets are the primary form for extrusion, injection molding, and other thermoplastic processing methods to produce sheets, rods, and complex parts. This form is widely used across industrial manufacturing in Japan and Southeast Asia.
- Films:PVDF films are thin, flexible sheets used in applications requiring high chemical resistance, UV stability, and barrier properties, such as architectural laminates or protective layers.
- Sheets:Thicker PVDF sheets are fabricated into industrial components, tank linings, and structural parts where chemical inertness and mechanical strength are paramount.
- Coatings:PVDF is applied as a protective coating in liquid or powder form to provide chemical resistance, weatherability, and aesthetic appeal for metal surfaces and architectural elements.
Powder form is critical for advanced battery manufacturing, whereas Pellets facilitate diverse thermoplastic processing methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals anchor the Asia Pacific PVDF market dynamics, driving significant demand for battery-grade materials. This policy framework accelerates the energy transition across the region, boosting PVDF consumption. Regulatory heterogeneity across other Asian nations also influences market access and material specifications for producers.
China
China's new energy vehicle policies directly propel demand for PVDF as a critical battery binder. The nation's GB standards for battery components dictate material specifications across the industry. Production capacity concentrates heavily within industrial provinces like Jiangsu and Zhejiang, establishing a robust supply base.
Japan
Japanese manufacturers require high-performance PVDF for chemical processing and advanced electronics applications. JIS standards for industrial materials ensure stringent quality and performance requirements. Industrial clusters in regions like Kansai and Kanto integrate PVDF into specialized components.
South Korea
South Korea's semiconductor and advanced battery sectors drive demand for ultra-high purity PVDF grades. The country's regulatory framework ensures stringent material specifications for high-tech applications. Fabs and battery manufacturers in the Seoul Capital Area and Gyeonggi province utilize these specialized fluoropolymers.
India
India's burgeoning electric vehicle market and water treatment infrastructure create a growing demand for PVDF. The BIS certification requirements impact imported finished goods containing PVDF within the country. Automotive manufacturing hubs and industrial zones in Gujarat and Maharashtra are seeing increased PVDF consumption.
Asia Pacific Polyvinylidene Fluoride (PVDF) Market Key Industry Players
Global fluoropolymer specialists and domestic Chinese manufacturers split the Asia Pacific PVDF market. Established international players focus on specialized copolymer grades for high-end applications, leveraging extensive R&D networks. Chinese producers, however, prioritize manufacturing scale and cost-efficiency for the high-volume battery-grade homopolymer market. This dynamic fuels significant capacity expansion and continuous product development across the region.
Within the global fluoropolymer specialist segment, Arkema and Daikin Industries exemplify a focus on advanced material science and application-specific solutions. Dongyue Group, a prominent domestic Chinese producer, occupies a position centered on large-scale production for the burgeoning battery sector. These entities, alongside others like Zhejiang Juhua and Kureha Corporation, collectively navigate the region's evolving demand landscape, adapting their portfolios to specific end-user requirements. Their strategies reflect the diverse market needs across Asia Pacific.
| Leading Market Players |
|---|
| Daikin Industries |
| Shandong Huaxia Shenzhou New Material |
| Arkema |
| Zhejiang Juhua |
| Shanghai Huayi 3F New Materials |
| Solvay |
| Dongyue Group |
| SINOCHEM LANTIAN |
| Kureha Corporation |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping corridor's cost dynamics influence PVDF pricing, where concentrated vinylidene difluoride (VDF) monomer supply in China directly impacts downstream price differentiation for battery-grade materials. This concentration shapes competitive strategies across the Asia Pacific market.
Pricing Analysis
Significant geographic price spreads exist for PVDF, with lower prices in China's high-volume battery homopolymer market compared to specialized copolymer grades in Japan and South Korea. The dominant pricing model combines contract-based long-term offtake agreements with commodity spot pricing influences. Price differentiation stems from quality grade, especially for battery-grade materials adhering to China's GB standards, and volume scale. Pricing pressure originates from China's extensive capacity expansion, making Chinese battery manufacturers the most price-sensitive, while advanced electronics firms prioritize performance.
Supply Chain Analysis
Contract manufacturing capacity for PVDF concentrates heavily within Chinese industrial provinces like Jiangsu and Zhejiang, alongside established producers in Japan and South Korea. The supply chain relies on the vinylidene difluoride (VDF) monomer, which itself has a highly concentrated production base. This creates a significant single-source vulnerability for PVDF producers. Distribution runs primarily through direct sales channels to large industrial end-users, with specialized distributors serving niche applications in advanced electronics and medical sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific PVDF market presents a fragmentation opportunity, driven by the demand-side shift towards specialized copolymers for high-performance battery and membrane applications. This creates distinct niches beyond the high-volume homopolymer segment.
For Market Incumbents: Pre-empt the long-term substitution threat from alternative battery binder materials by investing heavily in R&D for novel PVDF grades suitable for solid-state batteries. Consolidate homopolymer production in cost-efficient Chinese facilities to leverage economies of scale. Pursue strategic certification investment, particularly BIS certification in India, to secure market access in a growing region. Diversify product portfolios to include high-margin medical and healthcare applications.
For New Entrants and Emerging Players: Build out specialized manufacturing capabilities for high-purity PVDF copolymers targeting advanced filtration systems and medical diagnostics. The most penetrable market segment is India's rapidly expanding EV manufacturing sector, driven by domestic policies. Focus on a go-to-market strategy emphasizing technical support and tailored solutions for specific end-user performance requirements. This approach avoids direct competition with established homopolymer producers.
For Investors and Strategic Acquirers: Mid-sized specialists with proprietary copolymer technologies represent attractive acquisition targets for long-term viability within the PVDF market, spanning a 5-10 year window of sustained demand in high-tech applications. These firms often possess unique intellectual property for enhanced flexibility or chemical resistance. Investors should prioritize targets with strong R&D pipelines in niche segments. A signal to watch is the sustained growth in non-battery PVDF applications, indicating market diversification beyond EV reliance.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Establishes a domestic supply base for India's burgeoning EV and water treatment sectors. |
| Advanced Copolymer R&D | Develops specialized grades for next-generation solid-state batteries and high-performance membranes. |
| Raw Material Backward Integration | Secures stable supply of vinylidene difluoride (VDF) monomer, mitigating precursor supply volatility. |
| Digital Supply Chain Management | Enhances visibility and efficiency across complex Asia Pacific logistics, optimizing inventory for producers. |
| Medical Device Component Certification | Unlocks high-margin opportunities in biocompatible PVDF applications, diversifying revenue streams. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings, ensuring robust market insights. The process involved direct discussions with R&D directors, procurement leads at battery manufacturers, membrane system engineers, and regulatory affairs specialists. Secondary validation utilized customs and trade data, company 10-K filings, and industry association reports. This approach employed both bottom-up and top-down triangulation to refine market size and growth estimates.
The analytical framework calibrates market projections by integrating historical data with future demand drivers over the projection horizon. Segmentation dimensions modeled include product type, application, end-user industry, form, and regional production capacity. Compound Annual Growth Rates were derived from a weighted average of segment-specific growth rates. Key forecast inputs include electric vehicle production forecasts and water infrastructure spending trends.
Stress conditions across raw material price volatility and geopolitical trade tensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Quarterly review of VDF monomer prices and new capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
PP Capacitor Films Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Glass Substrate in Semiconductor Market