
 Thermoelectric Materials Market | 2026-2036
Thermoelectric Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoelectric Materials Market Outlook
Automotive waste heat recovery is consolidating as the dominant demand vertical for thermoelectric materials, displacing traditional industrial temperature management applications. Ferrotec Holdings Corporation leverages its vertical integration across bismuth telluride crystal growth and module assembly to anchor supply contracts with Japanese automotive Tier 1s. Laird Thermal Systems competes through specialized thermal management architectures for aerospace cooling, while Gentherm dominates seat climate control applications with proprietary thin-film thermoelectric arrays.
Thermoelectric materials are solid-state compounds that convert thermal gradients into electrical voltage through the Seebeck effect, with bismuth telluride alloys achieving figure-of-merit (ZT) values near 1.0 at room temperature for commercial cooling and power harvesting applications. Bulk thermoelectrics still occupy the largest revenue pool due to mature manufacturing infrastructure, though nanostructured thermoelectrics are extending performance boundaries through phonon scattering engineering that pushes ZT above 1.5 in laboratory demonstrations. Silicon-germanium segments sustain premium pricing in aerospace waste heat recovery where operating temperatures exceed 600°C, while half-Heusler alloys are positioning for industrial power generation where cost-per-watt thresholds constrain material selection.
EPA fuel economy standards and NHTSA corporate average fuel economy rules in the United States are forcing automotive OEMs to qualify thermoelectric generators for exhaust heat recovery, while REACH substance restrictions in Europe are reshaping lead telluride supply chains toward alternative compositions. China's MEE enforces industrial energy efficiency mandates that directly subsidize thermoelectric installation in steel and cement plants. Stakeholders must monitor how evolving rare earth element export controls and semiconductor fabrication capacity expansions alter bismuth and tellurium feedstock availability.
Market Dynamics
Automotive exhaust heat recovery is compressing qualification timelines for thermoelectric generators as NHTSA corporate average fuel economy rules force OEMs to harvest waste thermal energy. This regulatory pressure is restructuring material procurement toward high-temperature silicon-germanium alloys and away from conventional bismuth telluride cooling applications.
Growth Catalysts
- NHTSA CAFE Standards:US automotive OEMs must deploy exhaust-mounted thermoelectric generators to meet fleet fuel economy mandates, accelerating module qualification programs with Tier 1 thermal system suppliers.
- China MEE Industrial Efficiency Mandates:Steel and cement producers receive direct subsidies for thermoelectric installation, creating captive demand for waste heat recovery systems in heavy manufacturing clusters.
- Half-Heusler Alloy Maturation:These intermetallic compounds are crossing cost-performance thresholds for industrial power generation, opening mid-temperature applications previously served by lead telluride.
Market Restraints
- Tellurium Supply Concentration:Over 90% of global tellurium derives from copper anode slime processing in Chinese smelters, exposing bismuth telluride producers to export control volatility and concentrate supply risk.
- Figure-of-Merit Ceiling:Bulk thermoelectrics remain trapped below ZT 1.2 at room temperature, capping conversion efficiency and limiting addressable power harvesting applications against mechanical alternatives.
- REACH Lead Telluride Restrictions:ECHA substance restrictions are forcing reformulation of proven high-temperature materials, imposing R&D recertification costs and supply chain requalification delays.
Strategic Opportunities
- India PLI Scheme Alignment:Electronics manufacturing incentives under India's production-linked initiative are attracting thermoelectric cooling module assembly for semiconductor fabrication equipment and telecom infrastructure.
- Thin-Film Flexible Arrays:Wearable and IoT sensor applications are creating demand for conformal thermoelectric deposition on polymer substrates, bypassing rigid ceramic module limitations.
- Japan METI Hydrogen Economy Integration:Solid oxide fuel cell waste heat recovery specifications are incorporating thermoelectric generators, linking material demand to stationary fuel cell deployment targets.
Industry Challenges
- Phonon Engineering Talent Scarcity:Nanostructured thermoelectric development requires specialized expertise in electron-phonon interaction modeling that concentrates in national laboratory and elite university clusters, constraining commercial R&D scaling.
- Aerospace Qualification Timelines:FAA certification protocols for silicon-germanium generators in aircraft auxiliary power units demand multi-year thermal cycling validation, compressing revenue recognition for developmental materials.
- Legacy HVAC Integration Complexity:Building automation systems lack standardized control interfaces for thermoelectric heat pumps, forcing custom engineering on every commercial installation and inflating project execution risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoelectric Materials Market |
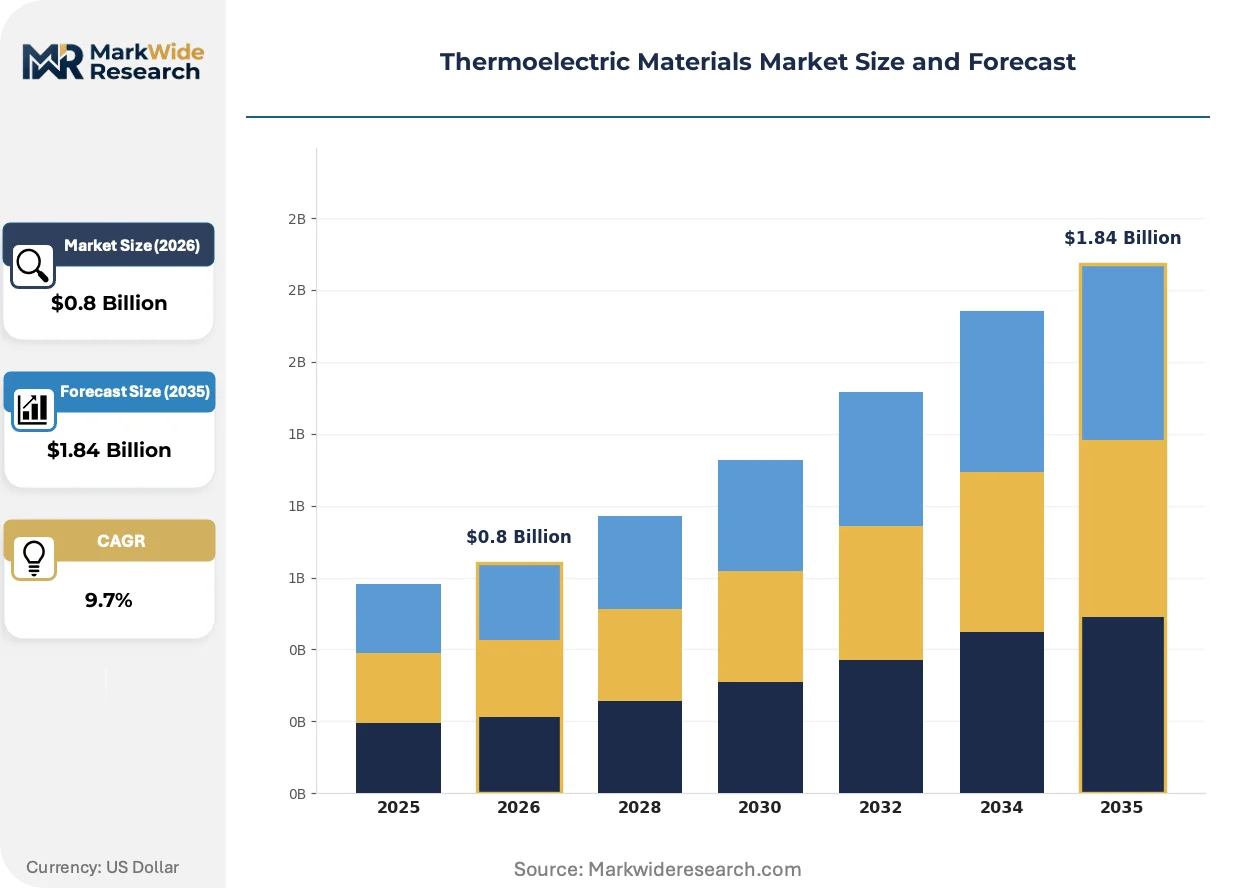
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bismuth Telluride, Lead Telluride, Silicon-Germanium, Half-Heusler Alloys End User: Automotive, Aerospace, Electronics, Industrial Application: Power Generation, Cooling Systems, Waste Heat Recovery, Refrigeration Technology: Bulk Thermoelectrics, Thin-Film Thermoelectrics, Nanostructured Thermoelectrics, Hybrid Systems |
| Companies Covered | Komatsu Ltd., Global Power Technologies Inc., Ferrotec Holdings Corporation, Gentherm, II-VI Incorporated, Kyocera Corporation, Laird Thermal Systems, Hi-Z Technology, Coherent Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoelectric Materials Market Strategic Shifts
Nanostructured material architectures are disrupting century-old bulk thermoelectric manufacturing paradigms. Phonon scattering engineering now enables laboratory ZT values exceeding 1.5, threatening to unlock applications previously uneconomical for solid-state thermal conversion.
Quantum dot superlattices and nanowire arrays are decentralizing thermal management architectures in precision electronics. Japanese semiconductor equipment manufacturers are integrating these materials into localized cooling subassemblies for lithography stages. This topology shift is decentralizing thermal infrastructure away from centralized chiller systems toward point-of-load temperature control.
EPA fuel economy standards are tightening exhaust heat recovery specifications for light-duty vehicles. Automotive OEMs must now demonstrate measurable fuel consumption reductions from thermal energy harvesting systems. Heavy-duty truck platforms in North America are responding first, with sleeper cab climate control and battery thermal management emerging as initial integration targets.
East Asian electronics manufacturers are consolidating thermoelectric procurement through direct material partnerships rather than distributor channels. South Korean memory fabs and Japanese precision instrument makers are establishing captive bismuth telluride supply agreements with crystal growers. This channel compression is eliminating traditional thermal component distributors from high-volume transactions.
Thermoelectric Materials Market Segmentation
Thermoelectric material selection hinges on operating temperature, conversion efficiency targets, and integration constraints that vary sharply across end-use environments. Procurement patterns diverge between high-volume automotive programs demanding cost-optimized bulk modules and aerospace applications tolerating premium pricing for extreme-temperature silicon-germanium alloys.
Product Type:
Buyers differentiate primarily by maximum operating temperature and raw material feedstock security rather than conversion efficiency alone.
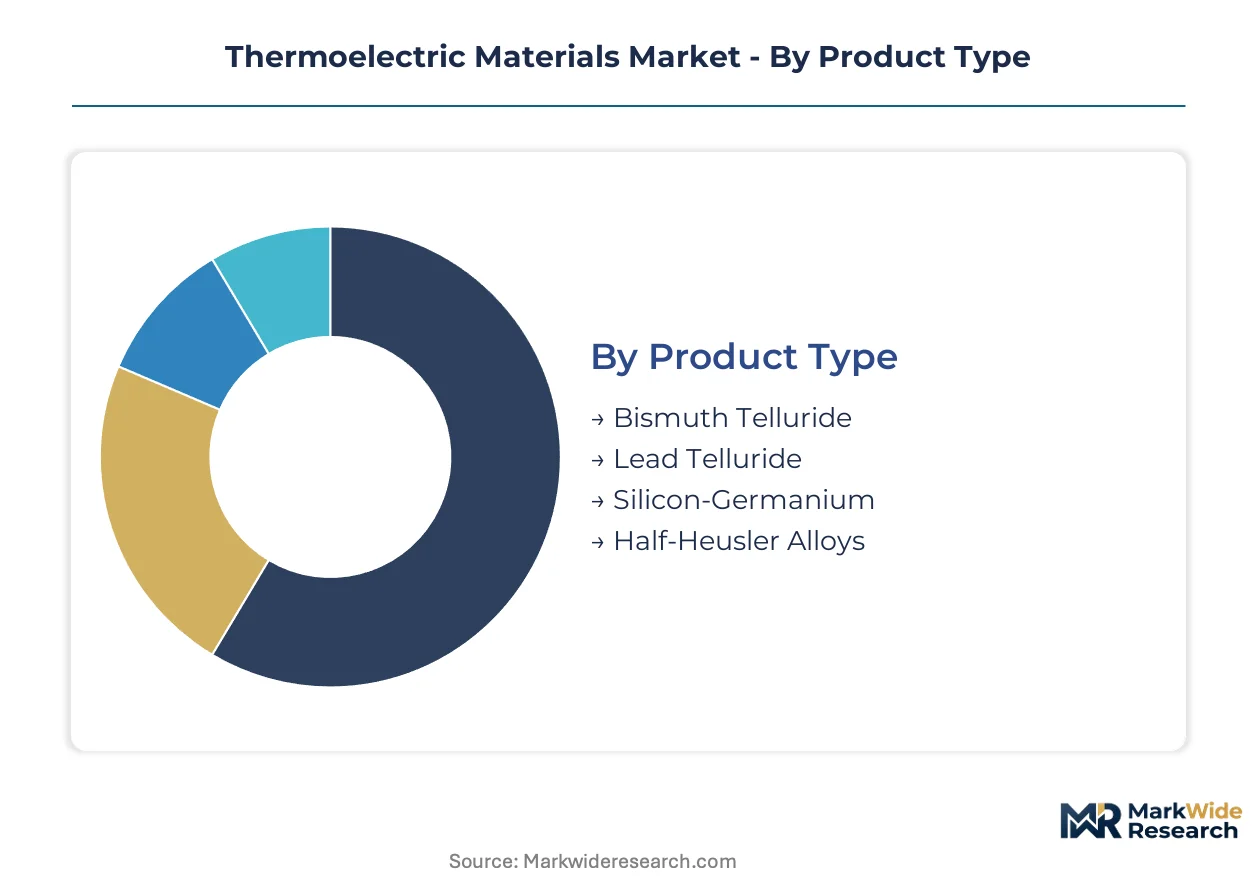
- Bismuth Telluride:Bismuth telluride alloys achieve figure-of-merit values near 1.0 at room temperature through optimized stoichiometry and doping profiles. Japanese automotive Tier 1s dominate procurement volumes for exhaust heat recovery systems as NHTSA CAFE standards tighten fleet fuel economy mandates.
- Silicon-Germanium:These alloys sustain thermoelectric performance above 600°C with superior thermal stability for aerospace auxiliary power units. China's MEE industrial efficiency subsidies are accelerating adoption in steel plant waste heat recovery where operating temperatures exceed bismuth telluride limits.
- Lead Telluride:Mature high-temperature material facing ECHA REACH substance restrictions forcing supply chain reformulation.
- Half-Heusler Alloys:Intermetallic compounds crossing cost-performance thresholds for mid-temperature industrial power generation applications.
Bismuth telluride leads volumes today; half-Heusler alloys are gaining share fastest.
End User:
Volume concentration follows regulatory enforcement intensity rather than inherent thermoelectric suitability.
- Automotive:OEMs deploy exhaust-mounted generators to harvest waste thermal energy from internal combustion powertrains. EPA fuel economy standards and NHTSA rules are compressing qualification timelines as manufacturers chase fleet compliance.
- Electronics:Precision cooling for semiconductor lithography equipment and telecom infrastructure drives demand for compact thermoelectric modules. India's PLI scheme for electronics manufacturing is attracting module assembly capacity for domestic semiconductor fabrication equipment.
- Aerospace:FAA certification protocols demand multi-year thermal cycling validation for auxiliary power unit integration.
- Industrial:Steel and cement producers receive direct subsidies under China's MEE mandates for waste heat recovery installation.
Automotive commands the largest revenue pool; electronics cooling is expanding most quickly.
Application:
Functional requirements separate power harvesting from active cooling on the basis of heat flux direction and control system complexity.
- Waste Heat Recovery:Converts thermal gradients from exhaust streams or industrial processes into electrical output through the Seebeck effect. Heavy-duty truck platforms in North America are integrating sleeper cab climate control and battery thermal management as initial specification targets.
- Cooling Systems:Solid-state refrigeration for precision electronics and medical devices leverages Peltier effect operation without compressor mechanics. South Korean memory fabs are establishing captive supply agreements for localized lithography stage temperature control.
- Power Generation:Stationary fuel cell integration under Japan METI hydrogen economy specifications.
- Refrigeration:Building automation systems lack standardized control interfaces, forcing custom engineering on every commercial installation.
Cooling systems dominate current procurement; waste heat recovery shows the steepest expansion trajectory.
Technology:
Manufacturing maturity and performance boundaries separate bulk architectures from nanostructured alternatives still scaling from laboratory demonstration.
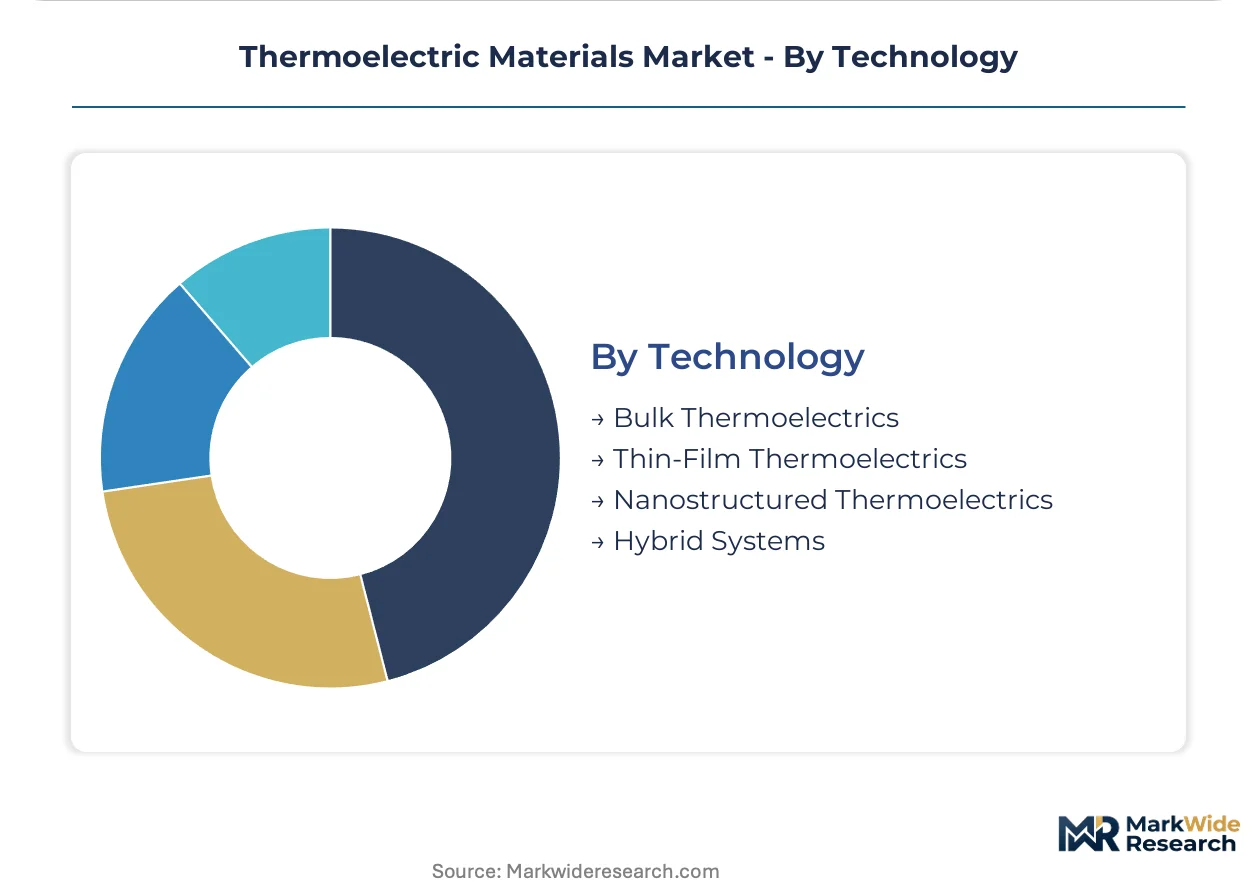
- Bulk Thermoelectrics:Conventional sintered and pressed ingot manufacturing dominates commercial production with established crystal growth infrastructure. Mature cost structures support high-volume automotive module assembly despite figure-of-merit ceilings below 1.2 at room temperature.
- Nanostructured Thermoelectrics:Phonon scattering engineering through quantum dot superlattices and nanowire arrays pushes laboratory ZT values above 1.5. Japanese semiconductor equipment manufacturers are integrating these materials into decentralized thermal management architectures for next-generation lithography systems.
- Thin-Film Thermoelectrics:Conformal deposition on polymer substrates enables wearable and IoT sensor applications bypassing rigid ceramic limitations.
- Hybrid Systems:Combined thermal-electric conversion architectures for specialized aerospace and industrial integration.
Bulk thermoelectrics anchor production volumes today; nanostructured variants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters concentrate thermoelectric procurement volumes, with automotive exhaust recovery and electronics cooling applications driving material demand across Japan, South Korea, and China's industrial corridors.
China
Steel and cement producers in Hebei and Jiangsu provinces deploy silicon-germanium generators for waste heat recovery under MEE industrial efficiency mandates. The country's dual carbon goals accelerate domestic procurement of high-temperature thermoelectric systems. Shanghai and Beijing house the primary R&D centers advancing half-Heusler alloy commercialization for mid-temperature power generation.
Japan
Automotive Tier 1 suppliers in Aichi Prefecture absorb bismuth telluride modules for exhaust heat recovery systems as METI enforces fleet efficiency targets. Solid oxide fuel cell specifications now incorporate thermoelectric generators, linking material demand to stationary fuel cell deployment. Tokyo and Osaka anchor precision electronics cooling procurement for semiconductor lithography equipment.
South Korea
Memory fabrication facilities in Gyeonggi Province establish captive supply agreements for localized lithography stage temperature control. The country's electronics manufacturing incentives attract thermoelectric module assembly capacity for telecom infrastructure cooling. Busan-Ulsan industrial complexes explore waste heat recovery applications for petrochemical processing.
United States
Heavy-duty truck manufacturers in Michigan and Ohio integrate exhaust-mounted generators to satisfy NHTSA corporate average fuel economy rules. EPA fuel economy standards compress qualification timelines for thermoelectric generator deployment. The Pacific Northwest hosts thin-film thermoelectric development for wearable and IoT sensor applications.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria reformulate lead telluride alternatives under ECHA REACH substance restrictions. The country's industrial machinery sector probes thermoelectric integration for precision temperature management in manufacturing equipment. North Rhine-Westphalia steel producers evaluate waste heat recovery systems under EU Green Deal efficiency directives.
Thermoelectric Materials Market Competitive Environment
Strategic partnerships dominate the current landscape as material suppliers align with module assemblers and end-use OEMs. The vendor base organizes around three tiers: integrated crystal growers with captive module production, specialized thermal system architects, and component suppliers focused on specific temperature regimes. Two archetypes prevail—vertically integrated Japanese conglomerates controlling bismuth telluride supply chains, and North American technology licensors specializing in aerospace-grade silicon-germanium. Geographic expansion and technology licensing represent the dominant competitive vectors as players seek to anchor supply contracts with automotive and electronics manufacturers.
Among Japanese fabricators, Ferrotec Holdings Corporation and Kyocera Corporation exemplify the integrated archetype, combining material production with module assembly to serve domestic automotive and electronics demand. Laird Thermal Systems occupies a position within the specialized thermal architecture tier, focusing on aerospace and precision cooling applications. These three companies represent contrasting strategic postures: captive supply chain control versus technology specialization versus application-specific engineering.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| Global Power Technologies Inc. |
| Ferrotec Holdings Corporation |
| Gentherm |
| II-VI Incorporated |
| Kyocera Corporation |
| Laird Thermal Systems |
| Hi-Z Technology |
| Coherent Corp. |
| Others |
Value Chain & Pricing Dynamics
China's MEE industrial efficiency mandates gate qualified supply for high-temperature thermoelectric generators, reserving premium-tier pricing access to silicon-germanium producers with certified waste heat recovery installations in steel and cement plants.
Pricing Analysis
Distributor margins compress as East Asian electronics manufacturers consolidate procurement through direct material partnerships with crystal growers. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-grade specifications reflects NHTSA CAFE-driven volume scale and FAA certification investment. Cost compression in bismuth telluride modules intensifies because automotive OEMs demand fuel economy compliance at mass-market cost points. Electronics cooling buyers exhibit highest price sensitivity; aerospace auxiliary power unit integrators tolerate premium positioning for thermal cycling validation.
Supply Chain Analysis
FAA certification protocols and ECHA REACH substance restrictions gate qualified supply, elongating lead times for reformulated lead telluride alternatives. Tellurium feedstock concentrates in Chinese copper smelters, South Korean electronics manufacturing clusters, and Japanese automotive Tier 1 supply bases. Bismuth ingot, germanium substrate, and rare earth dopant dependencies tether module assemblers to concentrate processing capacity. Single-source vulnerability runs through Chinese anode slime processing for tellurium extraction. Distribution runs through captive supply agreements eliminating traditional thermal component distributors from high-volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thermoelectric materials market reads as a late-cycle quality story as automotive exhaust heat recovery specifications harden toward ZT-performance thresholds that only vertically integrated crystal growers can satisfy.
For Market Incumbents: Anchor supply contracts with Japanese automotive Tier 1s through backward integration into bismuth telluride crystal growth, defending against half-Heusler alloy substitution in mid-temperature applications. Deepen captive module assembly capacity in Gyeonggi Province to intercept South Korean memory fab demand for lithography stage cooling. For New Entrants and Emerging Players: Enter via thin-film flexible array manufacturing for wearable and IoT sensor applications, exploiting the white-space left by rigid ceramic module incumbents. India's PLI scheme for electronics manufacturing offers the most penetrable geography, with semiconductor fabrication equipment cooling as the initial go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for nanostructured thermoelectric specialists because phonon engineering talent concentrates in national laboratory clusters that resist organic replication. Five-to-ten year viability hinges on laboratory ZT-above-1.5 demonstrations crossing into commercial manufacturing. Watch for inflection when Japanese semiconductor equipment manufacturers qualify quantum dot superlattices for next-generation lithography thermal management.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tellurium Refining | Secures feedstock independence from Chinese copper smelter concentrate volatility. |
| FAA Certification Investment | Unlocks aerospace auxiliary power unit revenue pools with multi-year thermal cycling validation. |
| India PLI Scheme Alignment | Captures electronics manufacturing incentives for semiconductor fabrication equipment cooling modules. |
| Half-Heusler Alloy Commercialization | Positions for mid-temperature industrial power generation as REACH restrictions displace lead telluride. |
| Thin-Film Flexible Array Development | Bypasses rigid ceramic limitations for wearable and IoT sensor thermal harvesting applications. |
Study Parameters
Direct dialogue with thermoelectric material procurement managers, automotive Tier 1 thermal system engineers, semiconductor fabrication equipment specialists, and aerospace certification officers grounded qualitative findings. Secondary validation drew from NHTSA CAFE compliance filings, EPA fuel economy standard updates, ECHA REACH substance restriction registers, China MEE industrial efficiency mandate documentation, and Japan METI hydrogen economy specifications. Bottom-up module shipment estimates triangulated against top-down automotive exhaust heat recovery penetration assumptions.
Segmented outputs across material type, end-use vertical, application function, and manufacturing technology dimensions populated the analytical framework over the projection horizon. CAGRs emerged from regression against automotive production volumes, electronics capital expenditure cycles, and industrial energy efficiency subsidy trajectories. Nanostructured thermoelectric laboratory demonstrations and thin-film deposition yield curves informed technology transition timing inputs.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time module pricing disclosure and captive supply agreement terms introduce uncertainty bands around competitive share estimates. Forecasts reflect documented assumptions regarding NHTSA enforcement intensity and China dual carbon goal implementation pace. A model refresh is warranted upon material change in rare earth element export control regimes or semiconductor fabrication capacity expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Germanium Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Semiconductor Glass Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Gallium Trichloride Market
Semiconductor Material
Indium Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Sputtering Target Market