
 Dicing Die Attach Film Market | 2026-2036
Dicing Die Attach Film Market Size, Share, and Industry Trends Forecast 2026-2036
Dicing Die Attach Film Market Intelligence
Automotive-grade reliability specifications is rotating the Dicing Die Attach Film Market toward higher thermal cycling resistance and lower outgassing thresholds. Henkel AG leverages its adhesive chemistry portfolio to dominate European automotive electronics qualifications. Showa Denko Materials anchors Asian supply through vertical integration into epoxy resin synthesis. Nitto Denko Corporation differentiates via laser-release technology leadership for thin-wafer handling.
Dicing die attach film comprises a multilayer polymeric system—typically acrylate, epoxy, or polyimide carrier films with silicone or acrylate pressure-sensitive adhesives—engineered for temporary wafer mounting during dicing and permanent die bonding, with thickness precision controlled within ±2 micrometers to prevent die tilt and edge chipping. Epoxy-based formulations capture the dominant margin pool due to their thermal stability above 260°C for lead-free solder reflow compatibility, while UV-cured technology segments expand fastest as temporary bonding applications multiply for fan-out wafer-level packaging. Semiconductor applications absorb the majority volume, though MEMS applications are gaining structural importance as sensor miniaturization demands films with tailored modulus profiles for fragile suspended structures.
REACH substance restrictions and RoHS hazardous substance limits in Europe constrain halogenated flame retardant use, pushing formulators toward phosphorus-nitrogen synergists. FDA device manufacturing requirements and ISO 10993 biocompatibility standards govern films destined for medical sensor assemblies, creating a certification barrier for non-compliant suppliers. China's GB standards and NMPA oversight add parallel testing burdens for entrants targeting domestic packaging houses. Stakeholders must monitor evolving dual carbon goals from China's MEE and their downstream effects on petrochemical-derived film feedstock availability and pricing.
Market Dynamics
Automotive electronics reliability mandates are compressing qualification cycles for dicing die attach films, forcing formulators to pre-certify thermal cycling performance before design-in rather than after volume commitment.
Growth Catalysts
- Fan-out wafer-level packaging:Temporary bonding applications multiply as chiplet architectures proliferate, expanding UV-cured film specifications for thin-wafer handling.
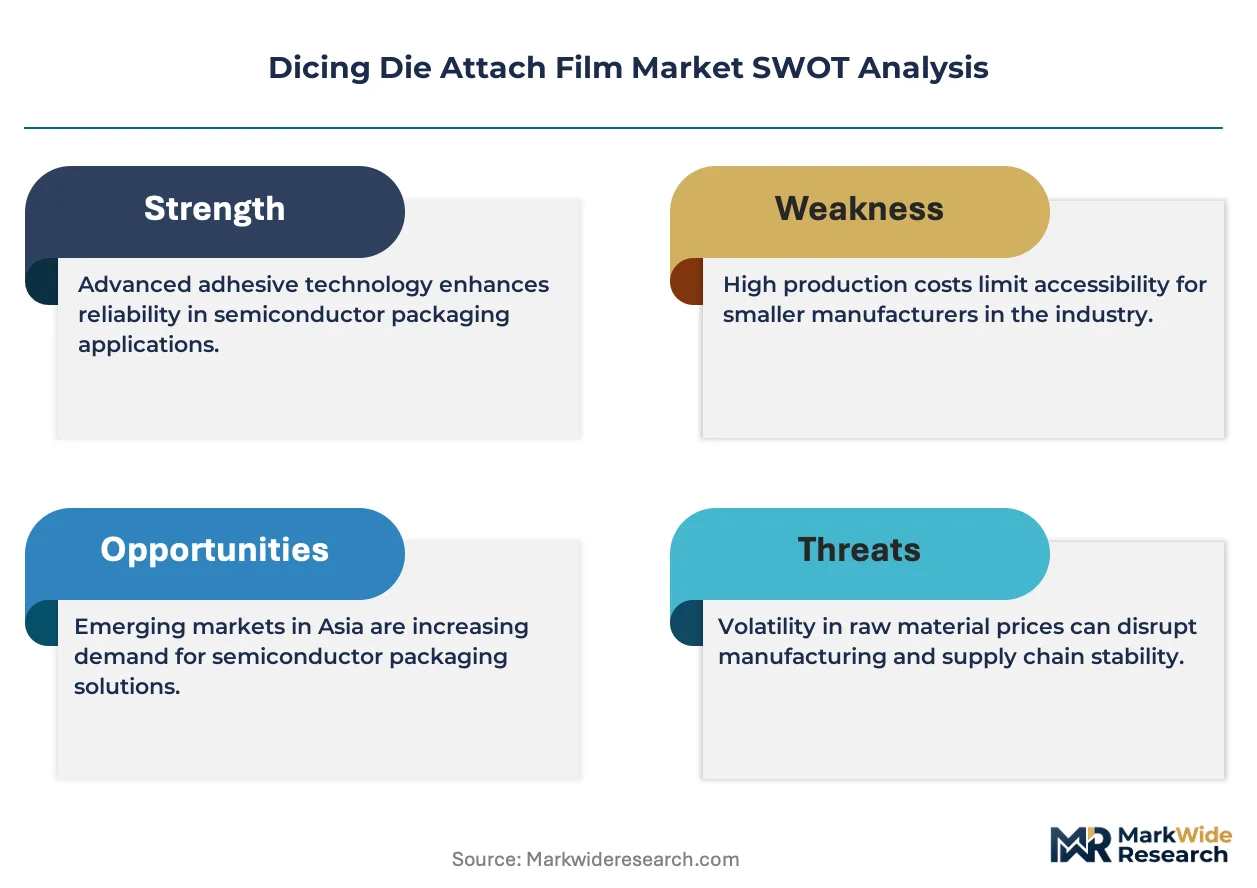
- REACH substance restrictions:Halogenated flame retardant phaseouts in Europe push phosphorus-nitrogen synergist adoption, creating first-mover advantage for compliant formulators.
- South Korea's semiconductor corridor:Concentrated fabrication capacity in Gyeonggi Province concentrates procurement volume, enabling scale economics for localized film production.
Market Restraints
- Epoxy resin feedstock concentration:Petrochemical-derived base materials face dual carbon policy pressure from China's MEE, constraining raw material availability.
- Thickness precision limitations:±2 micrometer tolerance requirements for preventing die tilt create yield loss penalties for non-specialized coaters.
- Medical sensor certification barriers:ISO 10993 biocompatibility testing timelines extend market entry by 18-24 months for films targeting implantable device packaging.
Strategic Opportunities
- MEMS sensor miniaturization:Suspended structure packaging demands modulus-tailored films with sub-5 GPa elastic profiles for fragile polysilicon beams.
- India's PLI scheme for semiconductors:Domestic packaging house incentives create captive demand for localized die attach film supply.
- Laser-release technology convergence:UV thermal debonding integration with existing dicing infrastructure reduces capital retrofit requirements for thin-wafer adoption.
Industry Challenges
- Adhesive chemistry talent scarcity:Formulation expertise spanning epoxy acrylate and polyimide carrier systems concentrates among retiring cohorts at Japanese suppliers.
- Multi-standard compliance complexity:Simultaneous GB standard testing for China, FDA device requirements for US, and REACH registration for Europe fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dicing Die Attach Film Market |
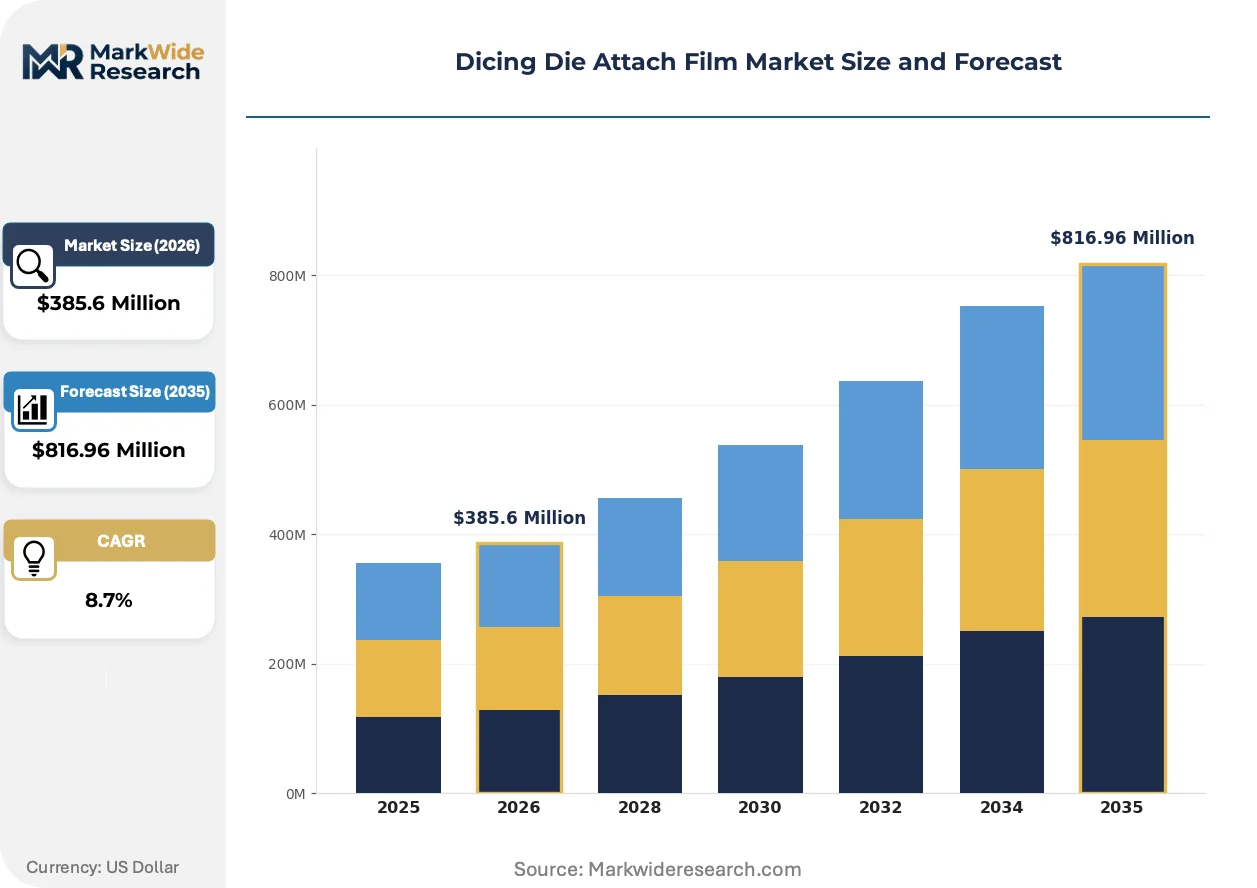
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylate, Epoxy, Polyimide, Silicone Technology: Thermal, Pressure-sensitive, UV-cured, Laser Application: Semiconductors, LEDs, Sensors, MEMS End User: Electronics, Telecommunications, Automotive, Aerospace |
| Companies Covered | Henkel AG, Showa Denko Materials, Nitto Denko Corporation, Sumitomo Bakelite Company, AI Technology, Inc., Lintec Advanced Technologies, Furukawa Electric, Shin-Etsu Chemical, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dicing Die Attach Film Market Strategic Shifts & Innovations
Wafer thinning below 50 micrometers is decomposing traditional mechanical dicing workflows, forcing simultaneous innovation in temporary bonding films and permanent die attach chemistries.
UV-cured temporary bonding technology is decomposing thermal release tape dominance in fan-out packaging. OSATs in Taiwan and Singapore are adopting laser-assisted debonding at 3-5x throughput rates. This is decomposing the historical tradeoff between processing speed and die edge integrity.
ECHA's 2025 candidate list expansion for SVHCs is tightening epoxy hardener formulations. Phosphorus-based flame retardants face substitution pressure from metal hydroxide alternatives. European automotive electronics suppliers are accelerating halogen-free qualification programs ahead of anticipated restriction amendments.
Consolidated procurement by IDMs is compressing supplier qualification from 24 months to 14 months. Direct engagement with packaging engineering teams is displacing traditional distributor technical support. South Korean memory manufacturers are piloting co-development contracts with film formulators for next-generation HBM stacking applications.
Dicing Die Attach Film Market Segmentation
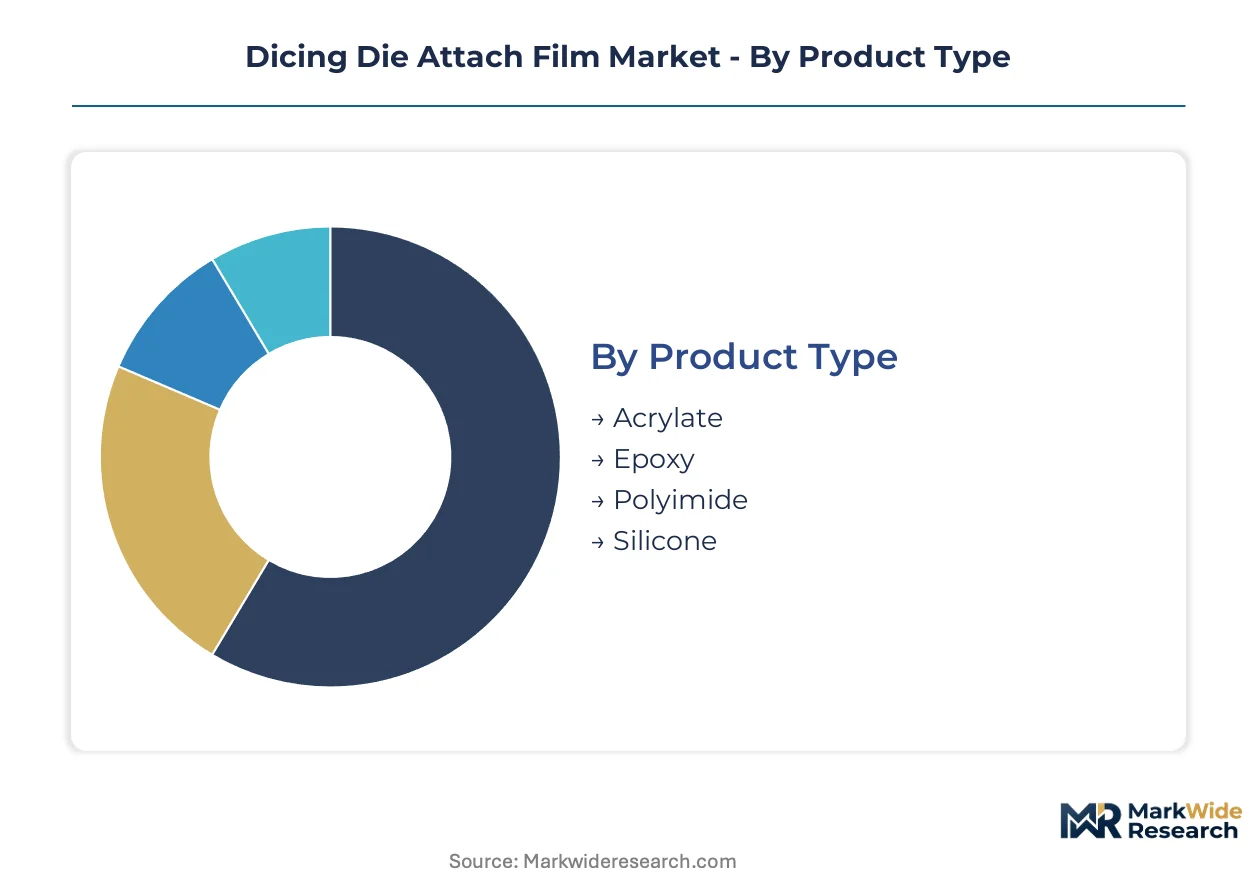
Dicing die attach film segmentation reveals how material chemistry, bonding mechanism, and application stress profiles channel procurement decisions. Each dimension carries distinct qualification barriers and margin structures that reshape supplier positioning across semiconductor packaging tiers.
Product Type:
Channel distribution varies sharply by carrier chemistry—epoxy formulations flow through automotive-qualified distributors, while acrylate and silicone grades dominate high-volume consumer electronics procurement.
- Epoxy:Dominates thermal stability requirements above 260°C for lead-free solder reflow compatibility. Automotive electronics procurement in Germany and South Korea concentrates demand for epoxy-based films with halogen-free flame retardant packages. REACH substance restrictions on halogenated additives accelerate phosphorus-nitrogen synergist adoption in European formulations.
- Acrylate:Pressure-sensitive adhesive systems with tunable modulus profiles serve temporary bonding applications in fan-out wafer-level packaging. Taiwan-based OSATs drive volume for acrylate carrier films with laser-release compatibility for thin-wafer handling below 50 micrometers.
- Polyimide:High-temperature carrier films for extreme thermal cycling environments.
- Silicone:Low-modulus options for stress-sensitive die attach in sensor assemblies.
Epoxy dominates installed base. UV-compatible acrylate is where expansion concentrates.
Technology:
Technology selection tracks wafer thickness evolution—thermal release suits legacy thick-wafer dicing, while pressure-sensitive and laser technologies capture thinning below 100 micrometers.
- UV-cured:Temporary bonding films with photochemical debonding enable throughput rates 3-5x faster than thermal alternatives. Singapore and Taiwan packaging houses adopt UV-cured specifications for chiplet architectures requiring repeated wafer handling cycles.
- Laser:Non-contact debonding preserves die edge integrity for sub-50 micrometer wafers. Nitto Denko's laser-release technology anchors adoption in South Korean memory manufacturer's HBM stacking pilots.
- Thermal:Mature release mechanism for standard thickness wafer dicing.
- Pressure-sensitive:Room-temperature bonding for temperature-sensitive device structures.
Thermal release retains volume share in legacy packaging. Laser debonding is climbing the fastest as wafer thinning accelerates.
Application:
Application segmentation separates high-volume commodity procurement from qualification-intensive specialty tiers with 18-24 month certification cycles.
- Semiconductors:Logic and memory die attach absorbs majority film volume with stringent thickness precision at ±2 micrometers. South Korea's Gyeonggi Province fabrication corridor concentrates procurement for advanced node packaging.
- MEMS:Suspended polysilicon structures demand modulus-tailored films below 5 GPa elastic modulus. Medical sensor applications trigger ISO 10993 biocompatibility requirements that extend market entry timelines.
- LEDs:High-brightness packaging with thermal management requirements.
- Sensors:Environmental and motion sensing with miniaturization stress profiles.
Semiconductors anchor procurement volume. MEMS is gaining share fastest as automotive sensor proliferation multiplies qualified supplier slots.
End User:
End user segmentation exposes diverging reliability standards—automotive mandates 1000+ thermal cycles while consumer electronics prioritize cost compression.
- Automotive:AEC-Q100 reliability specifications mandate thermal cycling resistance and outgassing thresholds below 100 ppm. Henkel AG leverages European automotive electronics qualifications to dominate this tier.
- Electronics:Consumer device packaging with high-volume, rapid-turn procurement patterns.
- Telecommunications:Base station and infrastructure thermal management requirements.
- Aerospace:Extreme environment reliability with extended qualification horizons.
Electronics captures shipment volume. Automotive is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for epoxy resin feedstocks shapes regional production economics, with Asian fabrication corridors running structural surpluses while European and North American packaging houses rely on cross-border supply chains for specialty film grades.
South Korea
Memory manufacturer procurement in Gyeonggi Province drives concentrated demand for laser-release compatible films. MFDS oversight of medical device packaging materials adds parallel certification requirements for films targeting biosensor applications. Samsung and SK Hynix packaging engineering teams in Suwon and Icheon pilot co-development contracts with formulators for HBM stacking architectures.
Germany
Automotive electronics suppliers in Baden-Württemberg and Bavaria mandate REACH-compliant halogen-free formulations for power module packaging. ECHA's 2025 SVHC candidate list expansion tightens epoxy hardener specifications ahead of anticipated restriction amendments. Bosch and Infineon qualification laboratories in Reutlingen and Munich compress supplier certification cycles from 24 months to 14 months through direct engagement protocols.
United States
FDA device manufacturing requirements and ISO 10993 biocompatibility standards govern films for implantable medical sensors, extending market entry timelines by 18-24 months. EPA oversight of petrochemical feedstocks intersects with state-level clean chemistry mandates in California and Massachusetts. Packaging houses in Arizona and Texas concentrate procurement for defense-aerospace applications with extended qualification horizons.
Japan
METI industrial policy supports domestic formulator retention of adhesive chemistry expertise spanning epoxy, acrylate, and polyimide carrier systems. JIS standards for semiconductor materials create baseline specifications that export-oriented suppliers adopt for regional consistency. Nagoya and Osaka industrial corridors maintain captive film production for captive semiconductor fabrication.
China
NMPA GB standards and dual carbon goals from MEE constrain petrochemical-derived feedstock availability for epoxy resin synthesis. Yangtze River Delta packaging houses in Jiangsu and Shanghai provinces absorb majority domestic volume despite import reliance for high-precision thickness control. Local formulators face yield loss penalties meeting ±2 micrometer tolerances without specialized coating infrastructure.
Dicing Die Attach Film Market Key Industry Players
Listed leaders compete with private specialists across technology licensing and captive supply arrangements, producing a tiered structure where scale-driven multinationals anchor premium automotive qualifications while regional fabricators capture consumer electronics volume. Three archetypes dominate: diversified chemical conglomerates with backward integration into resin synthesis, specialized adhesive formulators with laser-release technology leadership, and diversified materials suppliers leveraging cross-divisional technical service capabilities. Capacity expansion in South Korea and strategic partnerships for India PLI scheme participation represent the dominant competitive moves.
Among Japanese specialists, Showa Denko Materials and Shin-Etsu Chemical exemplify the resin-integrated archetype through upstream control over epoxy and silicone feedstocks. Nitto Denko Corporation occupies a position within the technology-differentiated tier, with its corporate name signaling laser-release specialization for thin-wafer handling applications. Henkel AG represents the diversified multinational model, with its European GmbH structure and adhesive-focused corporate identity anchoring automotive electronics qualifications across German OEM supply chains.
| Leading Market Players |
|---|
| Henkel AG |
| Showa Denko Materials |
| Nitto Denko Corporation |
| Sumitomo Bakelite Company |
| AI Technology, Inc. |
| Lintec Advanced Technologies |
| Furukawa Electric |
| Shin-Etsu Chemical |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between South Korean memory manufacturers and epoxy resin suppliers lock in feedstock access and stabilize price visibility across volatile petrochemical cycles. These arrangements concentrate procurement power among vertically integrated formulators while exposing non-integrated competitors to spot market fluctuations in bisphenol-A and epichlorohydrin derivatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade margins for AEC-Q100 automotive qualifications and ISO 10993 biocompatibility, while economy tiers serve high-volume consumer electronics with compressed lead times. Cost compression in standard-grade epoxy formulations is intensifying because China's MEE dual carbon policies constrain domestic resin synthesis capacity. Foundry procurement teams in Gyeonggi Province exhibit lowest price sensitivity due to co-development contract structures, whereas Taiwan-based OSATs drive hardest bargain on acrylate temporary bonding films.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, drawing from Japan and Germany for precision coating equipment and epoxy hardener specialties. Raw material flows center on petrochemical-derived epoxy resins, silicone pressure-sensitive adhesives, and polyimide carrier substrates. Single-source vulnerability concentrates in halogen-free flame retardant additives after REACH substance restrictions phased out brominated alternatives. Distribution runs through qualified automotive electronics distributors in Europe and direct engagement protocols with packaging engineering teams in Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics is reshaping this market as chiplet architectures force interoperability between temporary bonding films and laser-debonding infrastructure. Ecosystem coordination between OSATs and equipment vendors now determines formulator market access more than standalone material specifications.
For Market Incumbents: Fortify backward integration into epoxy resin synthesis to defend margin position against feedstock volatility from China's MEE policies. Expand laser-release technology licensing to equipment vendors, creating switching costs that lock OSATs into proprietary debonding workflows. Prioritize co-development contracts with South Korean memory manufacturers for HBM stacking applications before qualification windows narrow. For New Entrants and Emerging Players: Lead with modulus-tailored silicone formulations for MEMS sensor packaging, where ISO 10993 certification barriers have left incumbent slots unfilled. Target India's PLI scheme beneficiaries with localized production partnerships, bypassing the 18-24 month qualification timelines that constrain import-dependent supply. Pursue technical service differentiation through embedded packaging engineering support rather than distributor intermediation. For Investors and Strategic Acquirers: Capital is best deployed toward resin-integrated specialists with captive epoxy synthesis and existing REACH registrations, as regulatory compliance assets appreciate with each ECHA SVHC expansion. The 5-10 year viability window favors formulators with demonstrated thermal cycling performance above 260°C and established automotive electronics qualifications. Monitor co-development contract announcements from Samsung and SK Hynix as the inflection signal for next-generation HBM film specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Synthesis | Captive feedstock supply from Showa Denko Materials insulates margin against China's MEE dual carbon constraints. |
| Laser-Release Technology Licensing | Nitto Denko's equipment partnerships create proprietary debonding ecosystems that raise OSAT switching costs. |
| Co-Development Contracts for HBM Stacking | Samsung packaging engineering pilots in Suwon establish specification leadership before volume commitments crystallize. |
| REACH-Compliant Halogen-Free Formulation | Henkel AG's European registrations capture automotive electronics procurement as ECHA tightens SVHC candidate lists. |
| Localized Production for India PLI Scheme | Domestic packaging house incentives in Gujarat and Karnataka reduce import dependency and compress lead times. |
Research Approach
Operator-level perspectives from packaging engineering directors, OSAT procurement leads, epoxy resin plant managers, and semiconductor equipment vendors anchored the qualitative base. Secondary validation drew from SEC 10-K filings of listed materials suppliers, customs trade data for epoxy resin flows, and MFDS medical device packaging material registrations. Bottom-up triangulation across wafer dicing throughput estimates and top-down reconciliation against fabrication capacity announcements ensured dimensional consistency.
Sensitivity analysis tested forecast robustness across the projection horizon by varying epoxy resin feedstock pricing assumptions and qualification cycle compression scenarios. Segmentation modeling incorporated product chemistry, debonding technology, application stress profiles, and end-user reliability tiers. CAGRs were derived from installed base evolution in legacy thermal release applications and adoption curves for UV-cured and laser-debonding specifications. Wafer thinning below 50 micrometers and chiplet architecture proliferation served as primary demand elasticity inputs.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor capital expenditure cycles or abrupt REACH restriction amendments would require recalibration. Forecasts reflect documented assumptions about thermal cycling performance thresholds and laser-debonding equipment penetration rates. Recalibration cycles align with material shifts in ECHA regulatory announcements and South Korean memory manufacturer packaging roadmaps.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Indium Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Cadmium Telluride Market