
 Electronic Assembly Materials Market | 2026-2036
Electronic Assembly Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Assembly Materials Market Foresight
Automotive electronics is realigning demand toward thermal-stable solder pastes and underfills that survive powertrain thermal cycling. Henkel Corporation leverages its adhesives portfolio to anchor automotive module assembly lines across German and Chinese plants. H.B. Fuller competes through specialized underfill chemistries for flip-chip packages in telecommunications infrastructure. ITW sustains channel control via direct technical service relationships with tier-one contract manufacturers in North America and Asia.
Electronic assembly materials encompass solder pastes, adhesives, underfills, and encapsulants formulated with precise rheological properties, flux chemistry, and curing profiles to create reliable mechanical and electrical interconnections on printed circuit boards. These materials must meet tight viscosity specifications, typically measured in Pascal-seconds, to ensure repeatable dispensing and reflow performance in high-speed surface mount lines. Solder paste formulations dominate volume consumption due to their ubiquity in surface mount technology assembly, though margin pools concentrate in advanced underfills for flip-chip and wafer-level packaging where technical barriers limit supplier entry. Adhesives and encapsulants represent faster-growing categories as automotive and aerospace end users demand enhanced thermal management and environmental protection for mission-critical electronics.
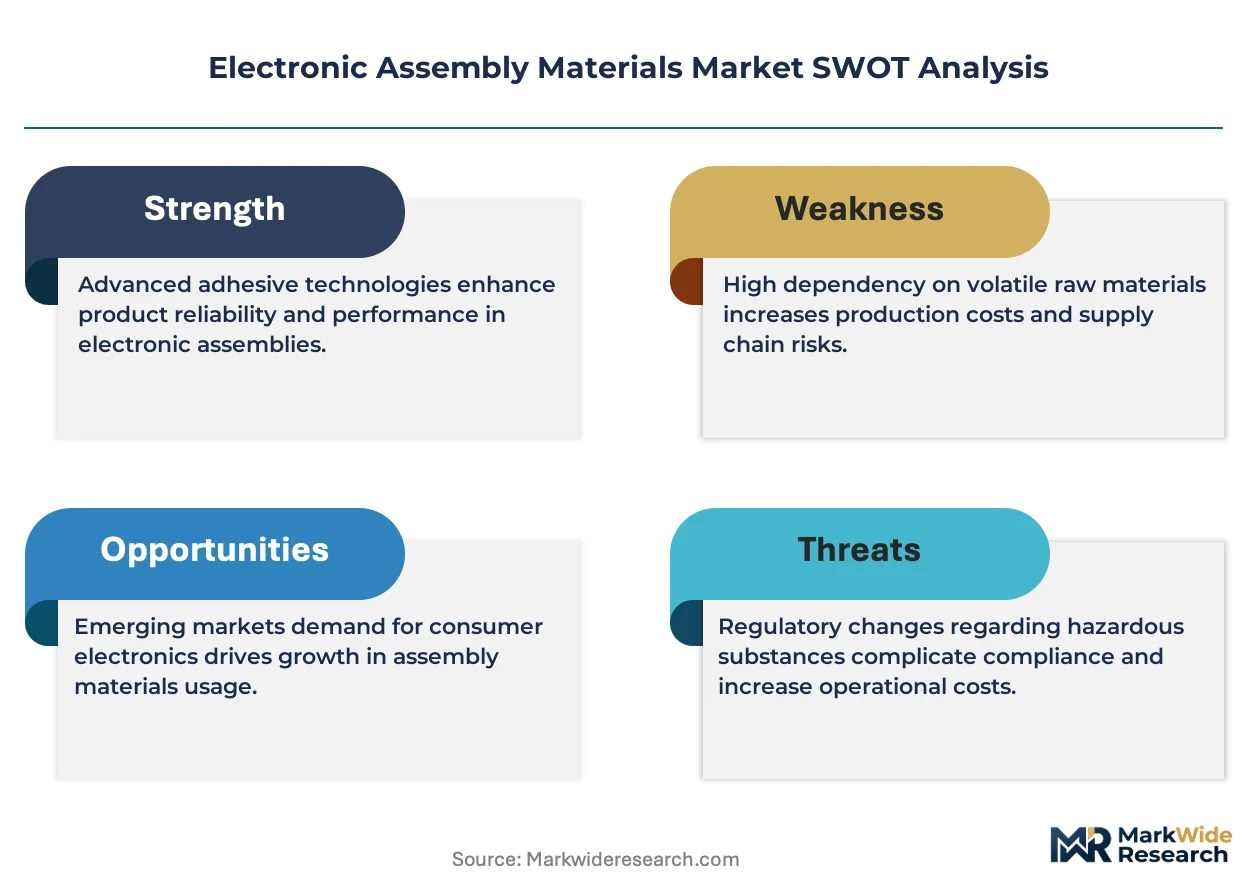
EPA hazardous substance rules and OSHA workplace exposure limits shape formulation choices for solder paste flux systems in the United States, while REACH substance restrictions and RoHS directives in Europe ban specific heavy metals and halogenated compounds from electronic assembly inputs. China's GB standards and MIIT technical guidelines enforce comparable substance controls while promoting domestic supply chain self-sufficiency in electronic chemicals. Stakeholders must monitor evolving dual-use export controls and carbon-border adjustment mechanisms that could redirect sourcing patterns for high-purity assembly materials.
Market Dynamics
Automotive electrification is compressing qualification timelines for thermal-cycling-resistant solder pastes as OEMs consolidate module suppliers and demand single-source material accountability across powertrain and ADAS assemblies.
Growth Catalysts
- RoHS and REACH substance mandates:European directives banning lead and halogenated compounds force reformulation investments that filter qualified suppliers and expand addressable market for compliant chemistry specialists.
- Flip-chip packaging proliferation:High-performance computing and 5G baseband processors drive underfill consumption where capillary flow control and CTE matching determine yield.
- China PCB fabrication concentration:Contract manufacturers in Guangdong and Jiangsu provinces anchor global solder paste volume procurement, creating localized demand density that attracts technical service investments.
Market Restraints
- Silver and tin price volatility:Precious metal and base metal input costs swing with commodity markets, compressing margin visibility for paste formulators on fixed-price automotive contracts.
- Flux chemistry IP concentration:Patent thickets around low-voiding, no-clean flux systems limit new entrant formulation freedom in high-reliability segments.
- Specialized resin supply concentration:Epoxy and anhydride hardener production for underfills clusters with Japanese and Korean chemical suppliers, exposing buyers to geographic risk concentration.
Strategic Opportunities
- India electronics manufacturing expansion:PLI scheme incentives for semiconductor and mobile device assembly create greenfield demand for localized solder paste and adhesive supply.
- Wafer-level packaging integration:Convergence of fan-out wafer-level packaging with system-in-module architectures opens formulation opportunities for temporary bonding and molding compounds.
- Carbon-border adjustment mechanisms:EU CBAM implementation rewards low-carbon intensity material sourcing, advantaging suppliers with renewable energy-tied chemical production.
Industry Challenges
- Reflow profile optimization talent scarcity:Engineers capable of correlating paste rheology with thermal profiling across mixed-technology boards command premium compensation and limit line expansion speed.
- Automotive PPAP timeline compression:Production part approval process documentation for new solder chemistries stretches 18-24 months, misaligning with EV platform development cycles.
- Legacy equipment compatibility:Next-generation lead-free alloys with higher melting points stress aging reflow oven heating element uniformity, forcing capital refresh decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Assembly Materials Market |
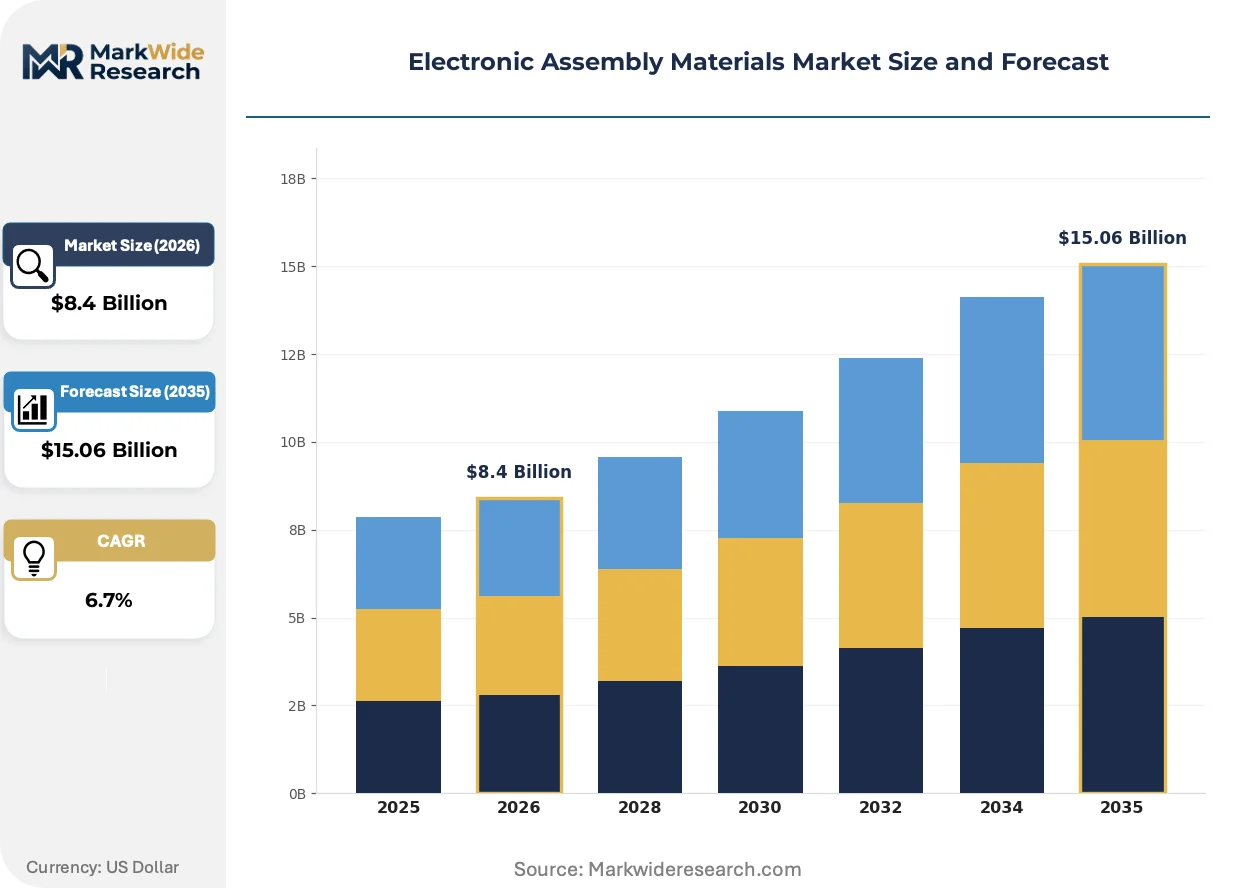
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solder Paste, Adhesives, Underfills, Encapsulants Application: Consumer Electronics, Telecommunications, Automotive, Aerospace Technology: Surface Mount Technology, Through-Hole Technology, Wire Bonding, Flip Chip End User: OEMs, Contract Manufacturers, Repair Services, Prototyping Firms |
| Companies Covered | Henkel Corporation, H.B. Fuller, ITW, Kester, Linde plc, Air Products, Cabot Microelectronics, BASF, Hitachi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Assembly Materials Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are converging to redefine performance benchmarks across interconnect formulations, with thermal management and environmental compliance emerging as the dominant specification drivers.
Low-temperature solder alloys based on bismuth and indium modifications are expanding into flexible electronics and temperature-sensitive substrate applications where traditional SAC alloys risk warpage or component damage. Wearable device manufacturers and medical electronics assemblers have accelerated qualification programs for these formulations over the past eighteen months. The technology is expanding into automotive interior electronics where mixed-material assemblies combine plastics and printed circuit boards.
REACH authorization procedures for substances of very high concern are restricting traditional flux activator chemistries, forcing formulators to validate replacement organic acid systems without sacrificing wetting performance or residue reliability. ECHA's SVHC candidate list expansion creates forward-looking compliance obligations that shape multi-year product roadmaps. European automotive module suppliers are responding by mandating full material disclosure down to 100 ppm thresholds from all assembly material vendors.
Consolidated procurement contracts now bundle solder paste, adhesives, and cleaning chemistries under single-source technical accountability agreements that transfer formulation risk to suppliers. Tier-one contract manufacturers in Taiwan and Mexico have pioneered these integrated supply arrangements, displacing spot purchasing of discrete material categories. Electronics manufacturing services providers in these geographies report reduced line-side inventory complexity and faster root-cause resolution when defects trace to material interactions.
Electronic Assembly Materials Market Segmentation
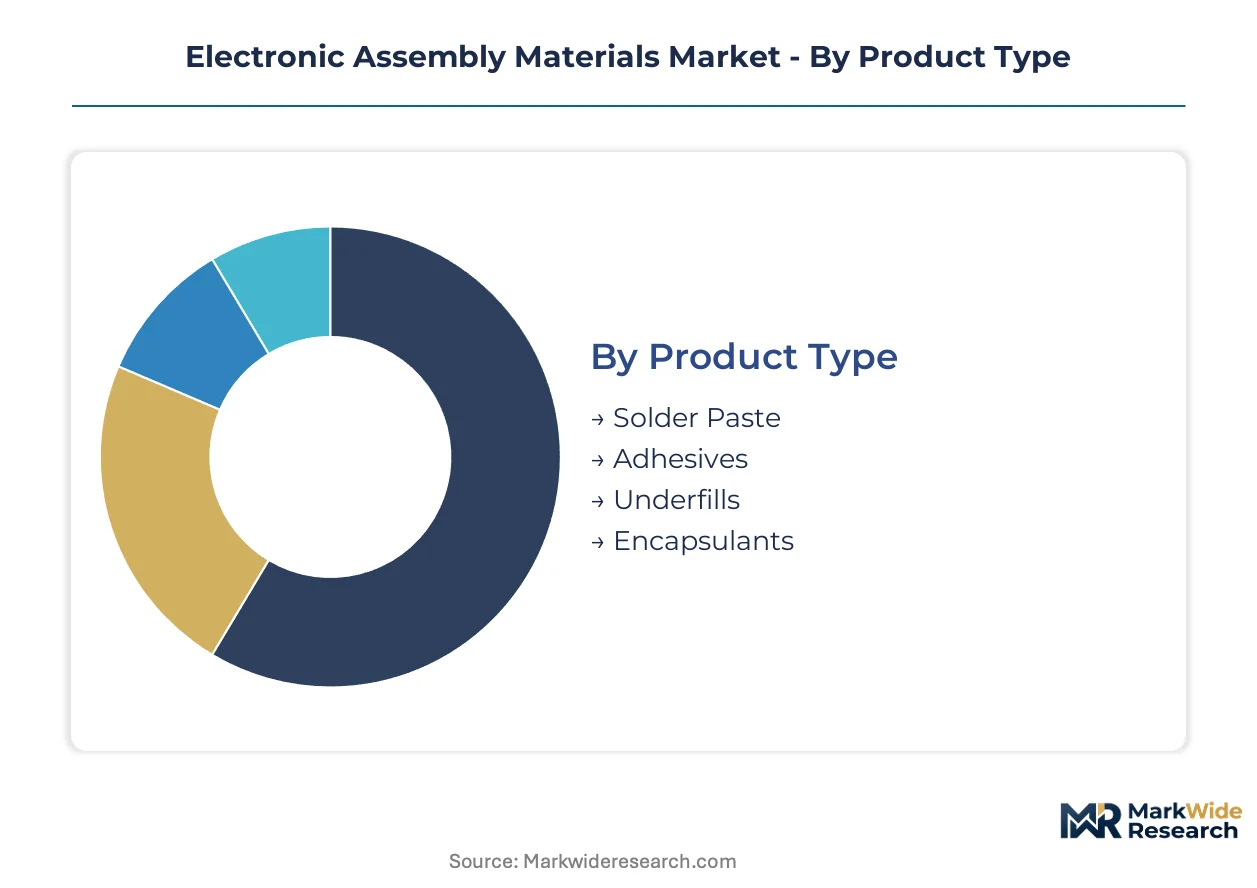
Electronic assembly materials demand fragments across multiple technical and commercial dimensions. Product specifications diverge sharply between high-volume consumer assembly and mission-critical automotive powertrain modules. Understanding segment boundaries clarifies where formulation investments concentrate and where margin pools form.
Product Type:
Upgrade cycles in reflow equipment and substrate technology are pushing formulators to redesign viscosity profiles and flux activation temperatures.
- Solder Paste:Formulations combine alloy powder with flux vehicles to achieve precise rheology for stencil printing and reflow. Volume procurement concentrates with contract manufacturers in Guangdong province as PCB fabrication clusters expand capacity. SAC305 and low-temperature bismuth variants dominate new qualifications.
- Adhesives:Structural and thermally conductive bonding agents secure components where mechanical fixation exceeds solder joint reliability. Automotive camera module suppliers in Germany and Mexico are accelerating epoxy and acrylic adhesive adoption for ADAS sensor mounting.
- Underfills:Capillary-flow epoxies reinforce solder interconnects in flip-chip and BGA packages against thermal cycling stress.
- Encapsulants:Potting compounds and conformal coatings shield assemblies from moisture, vibration, and chemical exposure.
Volume placements concentrate in solder paste; the faster expansion belongs to underfills.
Application:
Cost tier differentiation separates commodity consumer assembly from premium aerospace qualification requirements.
- Consumer Electronics:Smartphone, tablet, and wearable device assembly drives high-volume solder paste consumption with tight viscosity windows for miniaturized components. Manufacturers in Vietnam and India are expanding surface mount lines under PLI scheme incentives.
- Automotive:Powertrain inverters, battery management systems, and ADAS modules demand thermal-cycling-resistant formulations with extended reliability documentation. OEMs in Germany and China are consolidating suppliers under single-source accountability agreements.
- Telecommunications:5G base station and optical network equipment assembly requires low-voiding solder pastes and specialized underfills for high-frequency performance.
- Aerospace:Satellite and avionics applications impose stringent outgassing, vibration, and temperature specifications that limit qualified supplier pools.
Consumer electronics captures the highest paste tonnage; automotive applications are climbing the fastest on electrification timelines.
Technology:
Customer type segmentation reveals divergent procurement patterns between captive OEM lines and merchant contract manufacturers.
- Surface Mount Technology:Stencil-printed solder paste reflow dominates PCB assembly for consumer and automotive volume production. Equipment suppliers in Japan and Germany are advancing inspection and thermal profiling capabilities.
- Flip Chip:Direct die-to-substrate attachment with underfill dispensing serves high-performance processors and baseband chips. Taiwan-based semiconductor packaging houses anchor demand for advanced capillary and no-flow underfill chemistries.
- Through-Hole Technology:Wave soldering and selective soldering persist in power electronics and legacy industrial equipment.
- Wire Bonding:Thermosonic gold and copper interconnects remain essential for power modules and discrete semiconductor packages.
Surface mount technology maintains the installed base; flip chip packaging is gaining share fastest on advanced node proliferation.
End User:
Supply concentration shapes how formulation risk distributes across the value chain.
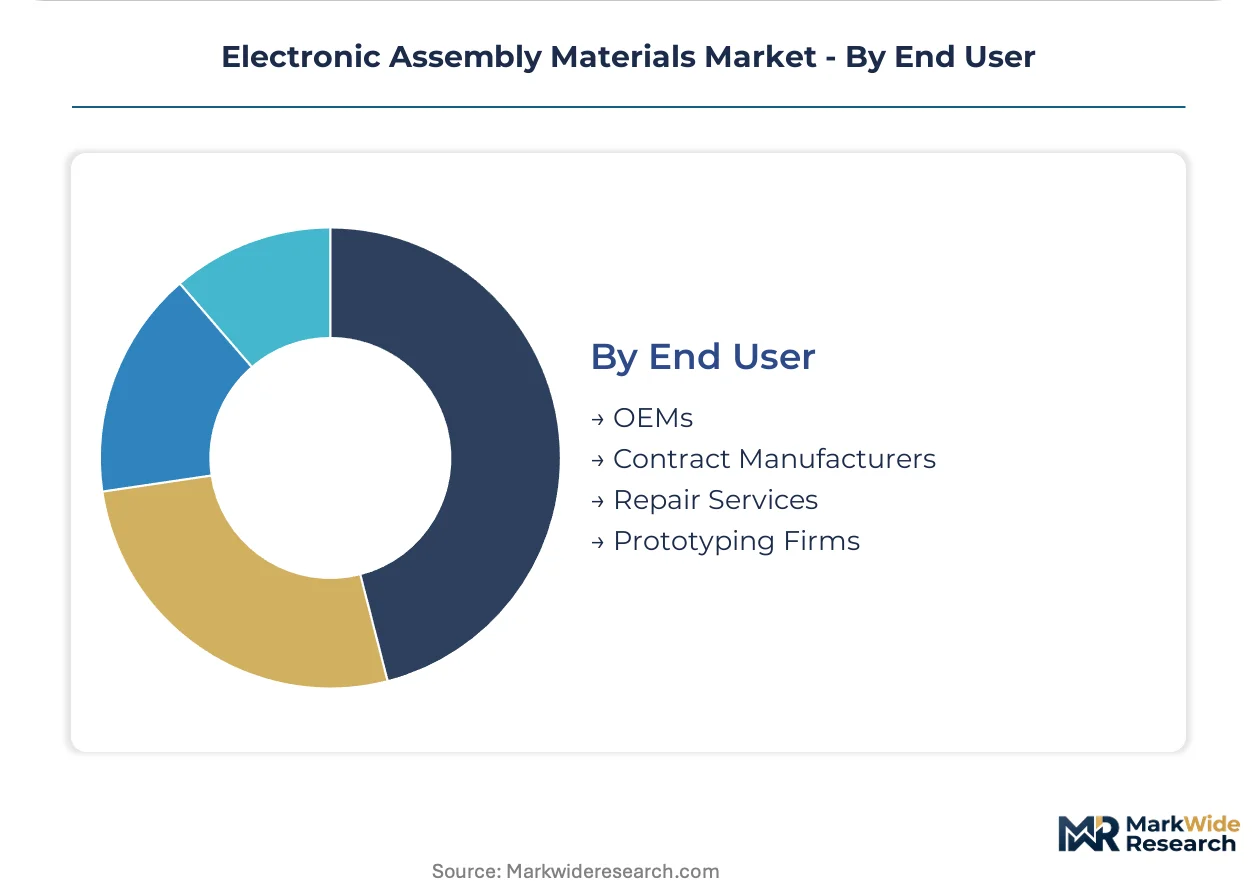
- Contract Manufacturers:Foxconn, Jabil, and Pegatron operations in China, Mexico, and Vietnam consolidate global solder paste procurement through integrated material agreements. These entities drive standardization of flux classifications and qualification protocols.
- OEMs:Tesla, Bosch, and Samsung internal assembly lines specify proprietary paste formulations with direct supplier engineering relationships. Captive production in Germany and South Korea maintains tighter chemistry control than outsourced alternatives.
- Repair Services:Rework stations and depot maintenance operations consume small-batch solder wire, paste, and flux for board-level repair.
- Prototyping Firms:Low-volume electronics developers purchase specialized alloys and no-clean formulations for rapid iteration cycles.
Contract manufacturers command the largest volume commitments; OEM captive lines are expanding most quickly as vertical integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong province anchors global solder paste procurement through concentrated PCB fabrication clusters in Shenzhen and Dongguan. Special economic zones across Asia-Pacific and tax incentives in Mexico's northern border states are redirecting assembly material demand patterns.
China
MIIT technical guidelines enforce substance controls while promoting domestic supply chain self-sufficiency. Guangdong and Jiangsu provinces concentrate contract manufacturing capacity that drives localized solder paste volume procurement. Foxconn and Pegatron operations in Shenzhen anchor technical service investments from multinational formulators.
Germany
REACH and RoHS directives ban specific heavy metals and halogenated compounds from electronic assembly inputs. ECHA's SVHC candidate list expansion shapes multi-year product roadmaps for automotive module suppliers. Bosch and automotive OEMs in Bavaria consolidate suppliers under single-source accountability agreements.
United States
EPA hazardous substance rules and OSHA workplace exposure limits shape solder paste flux system formulations. Tesla's captive assembly lines in Texas and California specify proprietary paste formulations with direct supplier engineering relationships. Contract manufacturers in Mexico's Tijuana-Mexicali corridor serve nearshored electronics assembly.
Japan
METI industrial policy supports advanced packaging material development for semiconductor applications. Epoxy and anhydride hardener production for underfills clusters with Japanese chemical suppliers. Tokyo and Osaka-based packaging houses anchor demand for capillary and no-flow underfill chemistries.
India
PLI scheme incentives for semiconductor and mobile device assembly create greenfield demand for localized solder paste supply. BIS standards enforce comparable substance controls to European directives. Tamil Nadu and Karnataka states are expanding surface mount lines under government manufacturing incentives.
Electronic Assembly Materials Market Competitive Landscape
Top-tier vendors anchor automotive and semiconductor packaging accounts, while mid-tier specialists compete on regional contract manufacturing relationships. The vendor base stratifies across three tiers: multinational chemical conglomerates with adhesives portfolios, specialized solder paste formulators with flux chemistry IP, and regional distributors with technical service capabilities. Dominant competitive moves include capacity expansion in China and India, plus strategic partnerships with tier-one contract manufacturers for integrated material supply agreements.
Among Germany-based chemical conglomerates, Henkel Corporation exemplifies the multinational adhesives portfolio archetype. H.B. Fuller and ITW occupy positions within the specialized formulation tier, with the former representing North American adhesive chemistry capabilities and the latter anchoring direct technical service relationships with contract manufacturers. Kester and Linde plc sit within the industrial gas and materials supply segment, illustrating how diversified industrial players participate in electronic assembly material value chains.
| Leading Market Players |
|---|
| Henkel Corporation |
| H.B. Fuller |
| ITW |
| Kester |
| Linde plc |
| Air Products |
| Cabot Microelectronics |
| BASF |
| Hitachi Chemical |
| Others |
Supply & Pricing Matrix
EU carbon-border adjustment mechanisms gate qualified supply and premium-tier pricing access for electronic assembly materials, as only formulators with renewable energy-tied chemical production secure preferential tariff treatment and OEM qualification slots. Automotive module suppliers in Germany and China now mandate full material disclosure down to 100 ppm thresholds, bifurcating the vendor base between compliant premium suppliers and excluded commodity players.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to thermal-cycling-resistant solder pastes qualified for automotive PPAP timelines, while spot inventory of standard SAC305 alloys trades at discounts to contract offtake agreements. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-economy formulations reflects certification burden and flux chemistry IP concentration. Cost compression in consumer-grade segments is intensifying because contract manufacturers in Vietnam and India consolidate procurement under integrated material agreements. Tier-one automotive OEMs exhibit lowest price sensitivity due to single-source accountability requirements, while prototyping firms and repair services drive spot-market volatility.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Jiangsu provinces limit expansion speed for solder paste blending operations despite concentrated PCB fabrication demand. Raw material supply draws from Japanese and Korean epoxy hardener producers, Chinese tin smelters, and Chilean silver refiners. Single-source vulnerability concentrates in specialized anhydride hardeners for underfill production, where patent-protected synthesis routes limit qualified suppliers to fewer than six global facilities. Distribution runs through direct technical service relationships with Foxconn, Jabil, and Pegatron operations, supplemented by regional distributors serving secondary contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic assembly materials function as a consolidation play where REACH authorization procedures for substances of very high concern force reformulation investments that filter out capital-constrained regional formulators.
For Market Incumbents: Extend flux chemistry IP portfolios through patent filings on low-voiding organic acid activator systems before ECHA SVHC list expansion closes formulation freedom. Backward integration into alloy powder atomization in China and India reduces exposure to silver price volatility and secures supply continuity for fixed-price automotive contracts. Capacity additions in Tamil Nadu and Karnataka capture PLI-scheme-driven demand from semiconductor packaging greenfield projects.
For New Entrants and Emerging Players: Contract manufacturers in Mexico's Tijuana-Mexicali corridor present the most penetrable channel entry point, as nearshored electronics assembly strains existing technical service coverage from incumbent suppliers. Target India electronics manufacturing services providers expanding under government incentives with localized blending operations and rapid qualification support for low-temperature bismuth alloys. Partner with reflow equipment distributors to bundle material supply with thermal profiling optimization services, reducing customer switching costs.
For Investors and Strategic Acquirers: Consolidation of automotive module suppliers under single-source accountability agreements is the leading indicator that formulation risk transfer to material vendors will deepen margin pools for qualified suppliers. Five-to-ten-year viability favors specialized solder paste formulators with established PPAP documentation libraries and direct OEM engineering relationships over commodity distributors. Monitor ECHA authorization timeline announcements for flux activator substances as inflection signals for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Powder Production | Captive atomization capacity in China and India insulates margin from silver and tin commodity swings. |
| Green Manufacturing Certification | Renewable energy-tied chemical production secures EU CBAM preferential access and automotive OEM qualification. |
| Long-term Supply Agreement | Integrated material contracts with Foxconn and Pegatron operations reduce line-side inventory complexity. |
| Joint Venture with Reflow Equipment Supplier | Bundled thermal profiling services accelerate customer acquisition in Vietnam and India expansion markets. |
| Capacity Expansion in Tamil Nadu | Localized blending captures PLI-scheme semiconductor and mobile device assembly demand. |
Research Methodology
Multi-period observation of solder paste procurement volumes, underfill adoption rates in flip-chip packaging, and automotive PPAP qualification timelines anchored the trend analysis, supplemented by interviews with formulation chemists at multinational suppliers, procurement directors at tier-one contract manufacturers, reflow equipment engineers, and regulatory affairs specialists tracking REACH authorization procedures. Secondary validation incorporated MIIT technical guideline publications, ECHA SVHC candidate list updates, customs data on tin and silver alloy powder trade flows, and SEC filings from electronic chemicals divisions. Bottom-up segment sizing triangulated against top-down PCB fabrication capacity estimates across Guangdong, Jiangsu, and emerging Indian states.
Input-output matrices modeled solder paste consumption against surface mount line installations, underfill demand against flip-chip packaging unit forecasts, and encapsulant growth against automotive powertrain electronics content expansion across the projection horizon. Segmentation dimensions included product type, application end-use, packaging technology, and regional production cluster. CAGRs derived from regression analysis of historical procurement patterns correlated with PCB fabrication capacity additions and semiconductor packaging technology transitions. Forecast inputs incorporated reflow equipment upgrade cycles and EV platform development timelines without specifying model years.
Caveats apply where ECHA authorization timeline acceleration, silver price volatility spikes, or automotive OEM supplier consolidation decisions could materially shift the outlook. Forecasts reflect assumptions about REACH compliance cost pass-through rates and contract manufacturer geographic diversification patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Global Electronic Materials Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
EV Capacitor Films Market
Semiconductor Material
Indium Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Europium Market
Semiconductor Material
Semiconductor Silicon Wafer Market
Semiconductor Material
Germanium Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Dicing Die Attach Film Market