
 Quartz Crucible Market | 2026-2036
Quartz Crucible Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Crucible Market Outlook
The quartz crucible industry is recalibrating around a widening gap between semiconductor-grade ultra-high-purity vessels and commodity solar-grade products. Shin-Etsu Chemical Co. Ltd leverages decades of synthetic quartz expertise to dominate premium semiconductor supply chains. Jiangsu Pacific Quartz Co., Ltd anchors volume production for domestic Chinese solar and semiconductor expansion. Heraeus Holding GmbH differentiates through specialized thermal management coatings and custom geometries for advanced crystal growth.
Quartz crucibles are high-silica containers, typically manufactured from fused natural or synthetic quartz with purity levels exceeding 99.995 percent, engineered to withstand temperatures above 1,400 degrees Celsius during silicon ingot pulling and semiconductor wafer fabrication. Semiconductor end users command the highest value per unit, driven by 300mm wafer expansion and advanced node migration. Solar cell applications sustain larger unit volumes though at lower purity thresholds and compressed margins. Chemical vapor deposition applications represent the fastest-growing segment as chipmakers adopt epitaxial processes for power devices and RF components.
China's NMPA and GB standards, Japan's METI semiconductor material directives, and South Korea's MFDS quality frameworks collectively tighten trace-metal specifications and batch certification requirements for crucible suppliers. REACH compliance in Europe and evolving EPA guidelines in the United States further constrain raw material sourcing and waste disposal pathways. Stakeholders must monitor purity standard convergence across East Asian regulators and assess captive quartz sand supply security before committing capacity expansion.
Market Dynamics
Semiconductor foundries are compressing procurement cycles for ultra-high-purity quartz vessels as 300mm wafer expansion accelerates and China's GB standards tighten trace-metal specifications. This dual pressure on supply security and certification velocity is restructuring supplier-buyer relationships across East Asian manufacturing clusters.
Growth Catalysts
- 300mm Wafer Migration:Semiconductor fabs in Taiwan and South Korea are scaling 300mm silicon ingot production, requiring crucibles with sub-10ppb trace-metal thresholds that command premium positioning.
- NMPA Semiconductor Material Directives:China's tightened purity benchmarks under evolving GB standards are disqualifying legacy suppliers and consolidating procurement toward certified domestic and import sources.
- Epitaxial Process Adoption:Chemical vapor deposition applications for power devices and RF components are expanding crucible consumption per wafer start as chipmakers integrate vertical GaN and SiC architectures.
Market Restraints
- Synthetic Quartz Feedstock Concentration:High-purity synthetic quartz sand production concentrates among Japanese and German chemical conglomerates, creating single-source vulnerability for crucible manufacturers outside these supply chains.
- Energy Cost Volatility:Electric arc fusion furnaces consuming 3-4 MWh per metric ton of fused quartz are exposed to industrial electricity pricing swings in manufacturing-intensive Chinese provinces.
- Silicon Carbide Crucible Substitution:Advanced crystal growth for wide-bandgap semiconductors is testing graphite-coated SiC vessels that tolerate higher thermal gradients than quartz in specific nitride deposition sequences.
Strategic Opportunities
- Indian Semiconductor Mission Incentives:India's PLI scheme and semiconductor fabrication subsidies are attracting crucible suppliers to establish qualification programs for emerging fabs in Gujarat and Tamil Nadu.
- Dual-Use Solar-Semiconductor Facilities:Chinese manufacturers with captive polysilicon operations are retrofitting crucible lines to serve both solar ingot and semiconductor wafer specifications, capturing margin arbitrage.
- Coating Technology Convergence:Thermal barrier coatings derived from aerospace CVD processes are integrating with quartz substrates to extend crucible lifecycles in high-pull-rate silicon crystal growth.
Industry Challenges
- Metallurgical Certification Timelines:Batch-level ICP-MS trace analysis and 90-day qualification protocols with semiconductor fabs are extending working capital cycles for crucible producers.
- High-Purity Logistics Infrastructure:Cleanroom packaging, nitrogen-purged shipping containers, and contamination-controlled warehousing require capital deployment that strains mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Crucible Market |
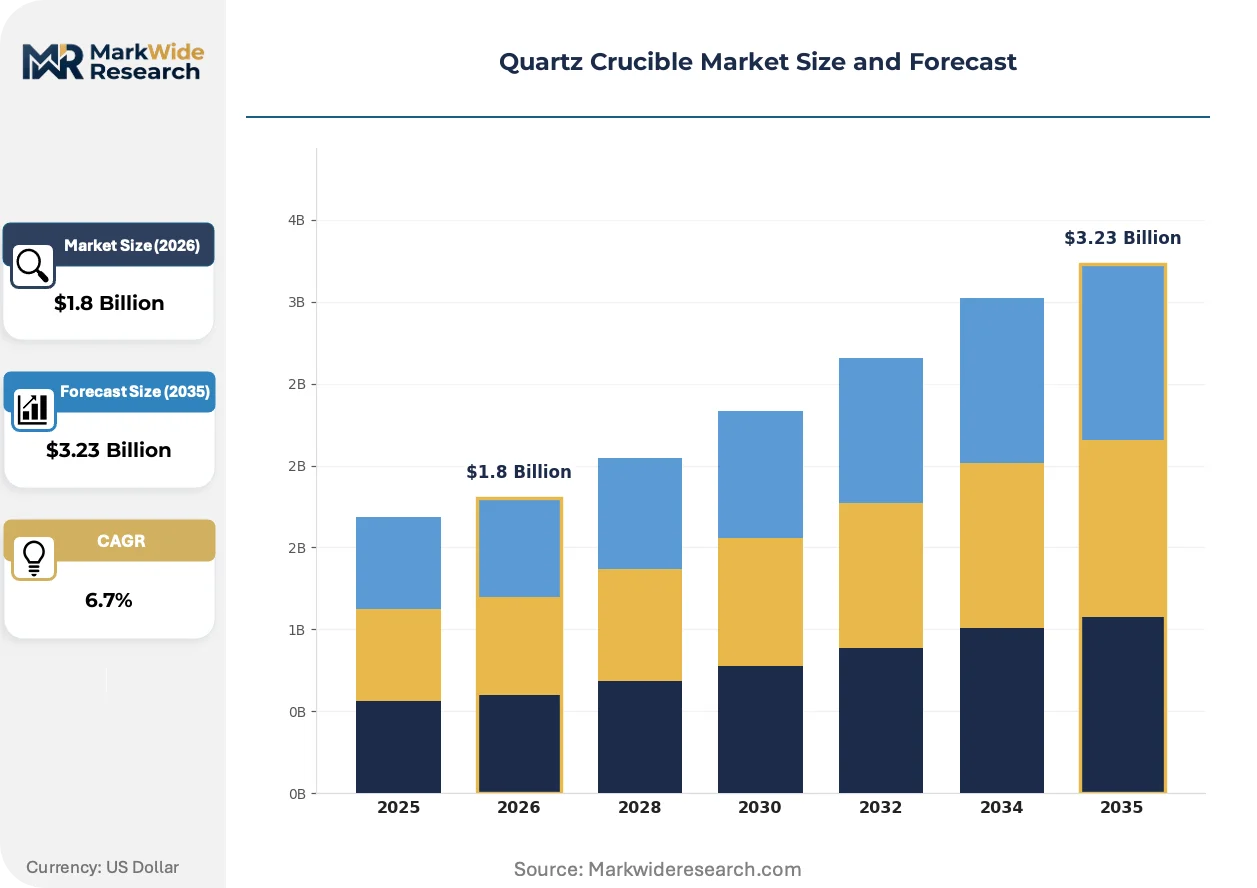
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Polycrystalline, Fused Quartz, High-Purity Quartz End User: Semiconductors, Solar Cells, Optical Components, Laboratory Instruments Application: Casting, Melting, Annealing, Chemical Vapor Deposition Form: Round, Square, Custom Shape, Thin-Walled |
| Companies Covered | Corning Incorporated, Sibelco, Shin-Etsu Chemical Co. Ltd, Tokuyama Corporation, Jiangsu Pacific Quartz Co., Ltd, Momentive Performance Materials, The Quartz Corp., Kyocera Corporation, Heraeus Holding GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Crucible Market Strategic Shifts
Quartz crucible engineering is pivoting from commodity volume production toward application-specific thermal management solutions. Manufacturers are embedding functional coatings and custom geometries to extend service life in aggressive crystal growth environments.
Synthetic fused quartz with engineered bubble structures is integrating into semiconductor-grade crucible cores to reduce thermal shock failure during silicon ingot cooling. Taiwan Semiconductor Manufacturing Company and Samsung Foundry are qualifying these vessels for 300mm epitaxial wafer production. The technology is integrating high-purity silica sourcing with computational thermal modeling to compress crucible replacement cycles.
REACH Annex XVII restrictions on crystalline silica exposure are mandating closed-loop slurry recovery and automated grinding systems at European crucible finishing facilities. German and Czech manufacturers are retrofitting production lines to comply with ECHA occupational exposure limits. Semiconductor-grade product categories face the steepest compliance cost escalation, accelerating consolidation among integrated suppliers with captive environmental infrastructure.
Direct long-term contracting between crucible producers and semiconductor foundries is displacing spot-market procurement and distributor intermediation. Samsung and SK Hynix are negotiating three-year supply agreements with fixed purity tiers and volume flex provisions. South Korean memory and logic fabs are driving this behavioral shift to secure supply continuity ahead of capacity ramps.
Quartz Crucible Market Segmentation
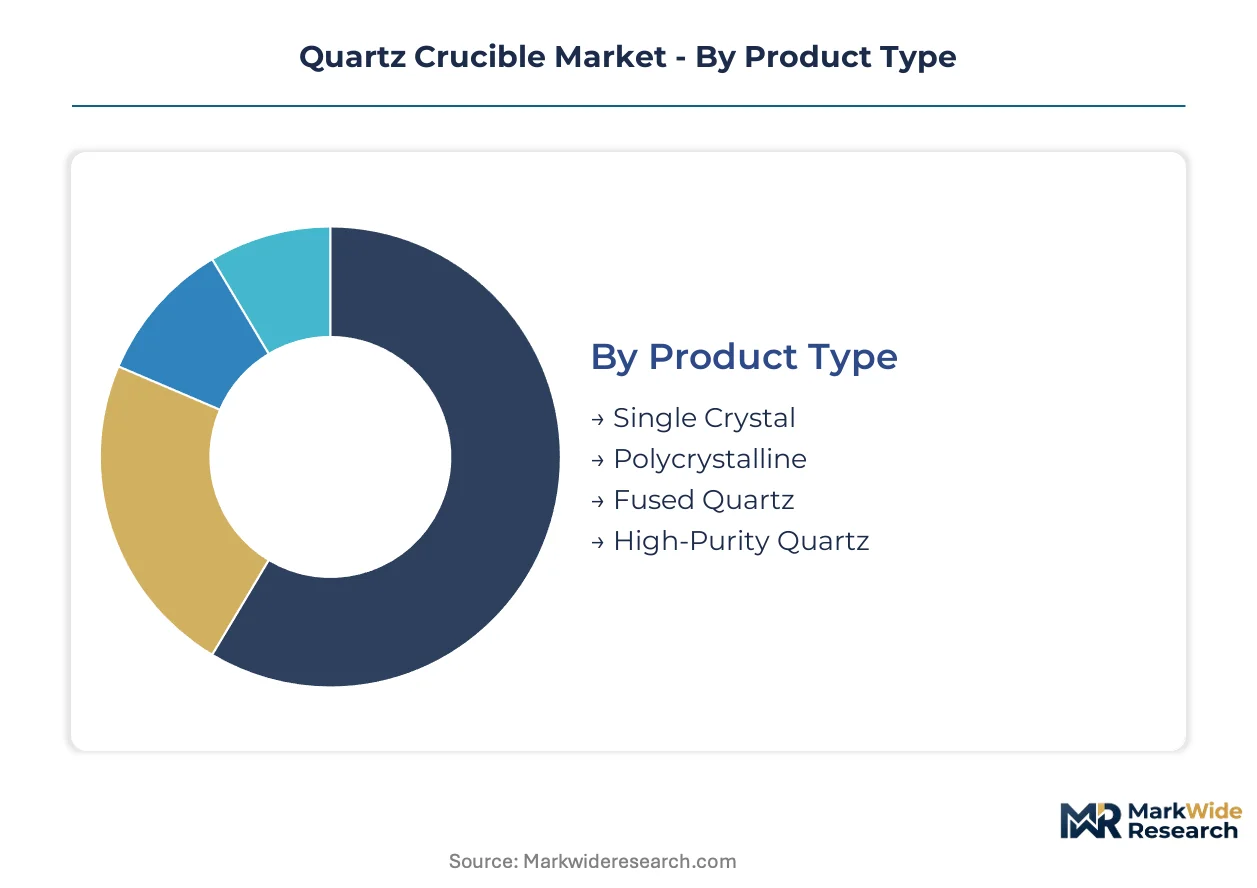
Quartz crucible segmentation reflects diverging purity requirements between semiconductor wafer pulling and solar ingot casting. Upgrade cycles and replacement velocity differ sharply across product grades, driving tiered procurement strategies among foundries and polysilicon producers.
Product Type:
Replacement cycles accelerate as semiconductor fabs demand ever-tighter trace-metal specifications, forcing crucible manufacturers to retire legacy product lines faster than equipment depreciation schedules anticipate.
- Single Crystal:Engineered for monocrystalline silicon ingot growth with sub-10ppb metallic impurity thresholds. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specify these vessels for 300mm epitaxial wafer production, with procurement cycles compressing to 90-day qualification windows under China's tightened GB standards.
- High-Purity Quartz:Synthetic fused silica exceeding 99.999% purity serves chemical vapor deposition sequences for GaN and SiC power devices. Shin-Etsu Chemical dominates feedstock supply, creating single-source vulnerability for crucible producers outside Japanese supply chains.
- Polycrystalline:Lower-purity natural quartz vessels sustain solar cell ingot casting at compressed margins.
- Fused Quartz:Standard-grade containers serve laboratory annealing and general metallurgical applications.
Single Crystal sits at the top of the volume ranking, with High-Purity Quartz climbing the fastest.
End User:
Cost tiers separate semiconductor-grade ultra-purity vessels from commodity solar-grade products, with pricing spreads widening as China's NMPA tightens certification requirements.
- Semiconductors:300mm wafer foundries in South Korea and Taiwan command premium positioning through sub-10ppb trace-metal specifications. Samsung and SK Hynix negotiate three-year supply agreements with fixed purity tiers, displacing spot-market procurement.
- Solar Cells:Polysilicon producers in China's Xinjiang and Inner Mongolia sustain larger unit volumes at lower purity thresholds. Jiangsu Pacific Quartz anchors domestic supply for photovoltaic expansion.
- Optical Components:Precision lens manufacturers require bubble-free synthetic quartz for ultraviolet transmission applications.
- Laboratory Instruments:Research facilities consume standard-grade vessels for materials science and chemistry applications.
Semiconductors command the steepest margin tier, while Solar Cells deliver the largest absolute shipment volumes.
Application:
Application-specific thermal management requirements are fragmenting the supplier base as crystal growth processes diverge in temperature profiles and chemical exposure.
- Chemical Vapor Deposition:Epitaxial processes for power devices and RF components expand crucible consumption per wafer start. Vertical GaN architectures impose thermal cycling demands that accelerate vessel degradation.
- Melting:Silicon ingot pulling at 1,400°C-plus temperatures remains the dominant volume application.
- Annealing:Controlled cooling sequences for stress relief in semiconductor substrates.
- Casting:Metal alloy solidification processes in metallurgical laboratories.
Melting retains the largest installed base, with Chemical Vapor Deposition gaining share fastest.
Form:
Geographic manufacturing clusters favor specific geometries based on dominant crystal growth technologies and local equipment standards.
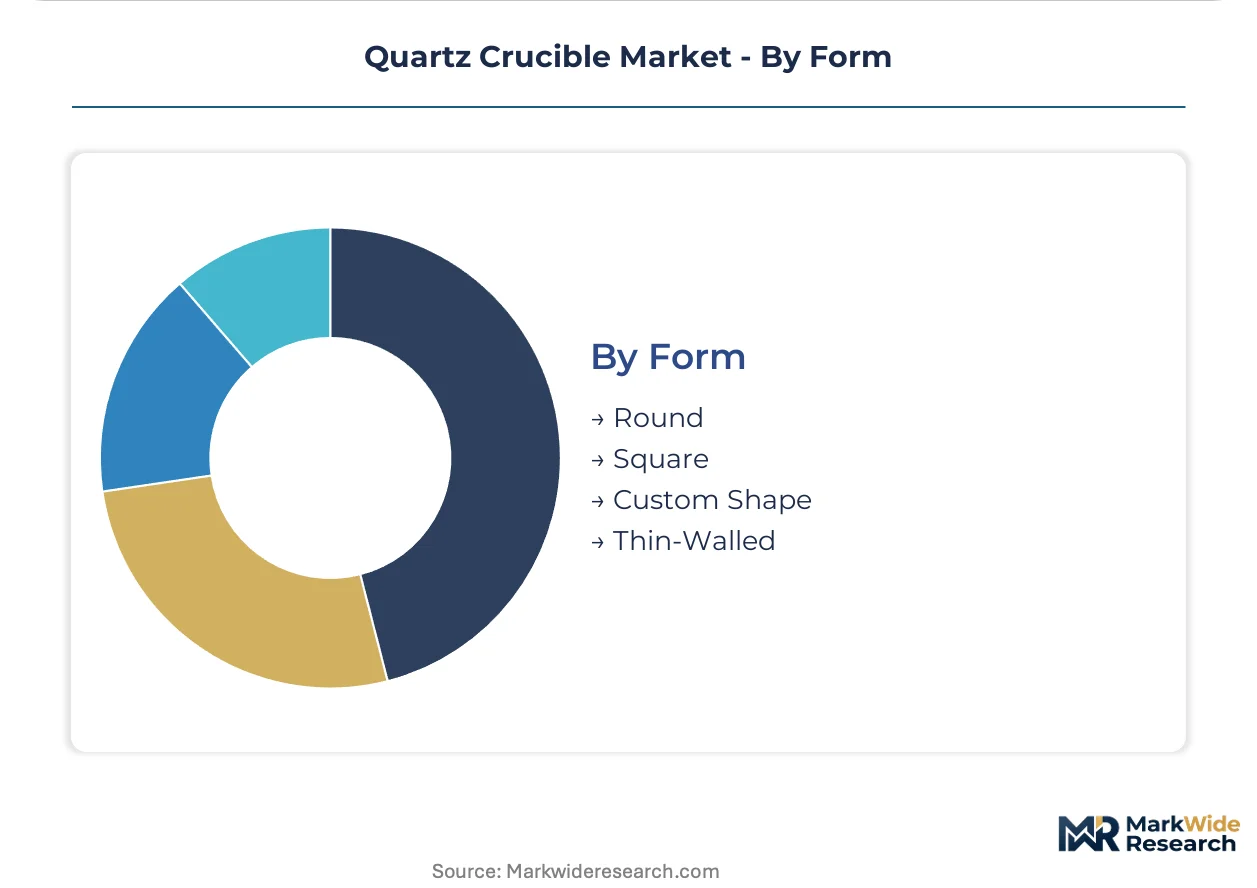
- Round:Dominant geometry for Czochralski silicon pulling, standardized across East Asian semiconductor fabs.
- Custom Shape:Specialized geometries for compound semiconductor crystal growth and research applications.
- Square:Rectangular vessels serve directional solidification furnaces in solar polysilicon casting.
- Thin-Walled:Reduced thermal mass designs for rapid temperature cycling in epitaxial processes.
Round forms anchor procurement volumes, with Custom Shape expanding most quickly in compound semiconductor applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized technicians in high-purity materials processing concentrate in East Asian manufacturing corridors, where semiconductor fabrication clusters demand precision-engineered quartz vessels for silicon crystal growth.
China
Domestic foundries in Shanghai and Hefei are scaling 300mm wafer capacity, requiring crucibles with sub-10ppb trace-metal specifications under tightened GB standards. NMPA semiconductor material directives are disqualifying uncertified suppliers and consolidating procurement toward qualified domestic and import sources. Jiangsu Pacific Quartz anchors volume production in Xuzhou for both solar and semiconductor applications.
South Korea
Samsung Foundry and SK Hynix are compressing procurement cycles for ultra-high-purity vessels as Pyeongtaek and Yongin fabs expand advanced node production. MFDS quality frameworks mandate batch-level ICP-MS trace analysis and extended qualification protocols. The Seoul-Suwon corridor hosts concentrated crucible certification laboratories serving memory and logic chipmakers.
Japan
Shin-Etsu Chemical leverages decades of synthetic quartz expertise to dominate premium semiconductor feedstock supply from Naoetsu and Takefu facilities. METI semiconductor material directives coordinate purity benchmarks across domestic supply chains. The Nagano-Toyama industrial zone concentrates high-purity silica refining and crucible finishing operations for export markets.
Taiwan
TSMC's Tainan and Hsinchu fabs are qualifying engineered bubble-structure crucibles for 300mm epitaxial wafer production. The island's semiconductor equipment ecosystem sources vessels through direct long-term contracting rather than distributor channels. Kaohsiung-based logistics providers operate nitrogen-purged shipping infrastructure for contamination-controlled delivery.
United States
Intel's Arizona and Ohio fabrication investments are attracting crucible suppliers to establish qualification programs for emerging domestic capacity. EPA guidelines constrain raw material sourcing and waste disposal pathways for quartz processing facilities. Corning Incorporated maintains advanced materials research operations in New York state serving specialty semiconductor applications.
Quartz Crucible Market Competitive Environment
Capital-heavy producers compete with asset-light designers across diverging purity tiers, with integrated chemical conglomerates facing independent crucible specialists. The market structure concentrates premium semiconductor-grade supply among Japanese and German synthetic quartz feedstock controllers, while Chinese manufacturers capture volume solar-grade production. Three archetypes dominate: captive feedstock-integrated chemical groups, independent precision fabricators with coating capabilities, and polysilicon producers with backward-integrated crucible lines. Capacity expansion and direct long-term contracting with foundries represent the dominant competitive moves reshaping procurement relationships.
Among Japanese chemical conglomerates, Shin-Etsu Chemical Co. Ltd and Tokuyama Corporation occupy positions anchored by synthetic fused silica feedstock control. Heraeus Holding GmbH exemplifies the European specialist archetype with German-engineered thermal management solutions. Jiangsu Pacific Quartz Co., Ltd represents scale-driven Chinese fabrication serving domestic solar and semiconductor expansion. These three entities illustrate how geographic feedstock concentration and end-market specialization stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Corning Incorporated |
| Sibelco |
| Shin-Etsu Chemical Co. Ltd |
| Tokuyama Corporation |
| Jiangsu Pacific Quartz Co., Ltd |
| Momentive Performance Materials |
| The Quartz Corp. |
| Kyocera Corporation |
| Heraeus Holding GmbH |
| Others |
Value Chain & Pricing Dynamics
Semiconductor foundries in Taiwan and South Korea anchor procurement volumes and impose long-term contracting structures that compress spot-market arbitrage opportunities. Their three-year supply agreements with fixed purity tiers displace distributor intermediation and lock in price predictability for high-grade vessels.
Pricing Analysis
Coating services and certification bundles separate from base crucible pricing. Three-tier pricing structure across semiconductor-grade, solar-grade, and laboratory-grade levels tracks purity thresholds and batch certification intensity. Price differentiation hinges on ICP-MS trace analysis inclusion and cleanroom packaging protocols. Cost compression in solar-grade tiers is intensifying because Chinese manufacturers with captive polysilicon operations capture margin arbitrage through dual-use facility retrofitting. Solar cell producers exhibit the highest price sensitivity; semiconductor fabs accept premium positioning for sub-10ppb trace-metal guarantees.
Supply Chain Analysis
Regional distribution centers in Shanghai, Seoul, and Kaohsiung operate nitrogen-purged shipping infrastructure for contamination-controlled delivery. Synthetic quartz feedstock production concentrates in Japan and Germany, creating single-source vulnerability for crucible manufacturers outside these supply chains. High-purity silica sand, thermal barrier coating precursors, and precision grinding equipment feed into finished vessel production. Tariff exposure on Japanese synthetic quartz imports into China threatens cost structures for domestic fabricators. Distribution runs through direct foundry contracting rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
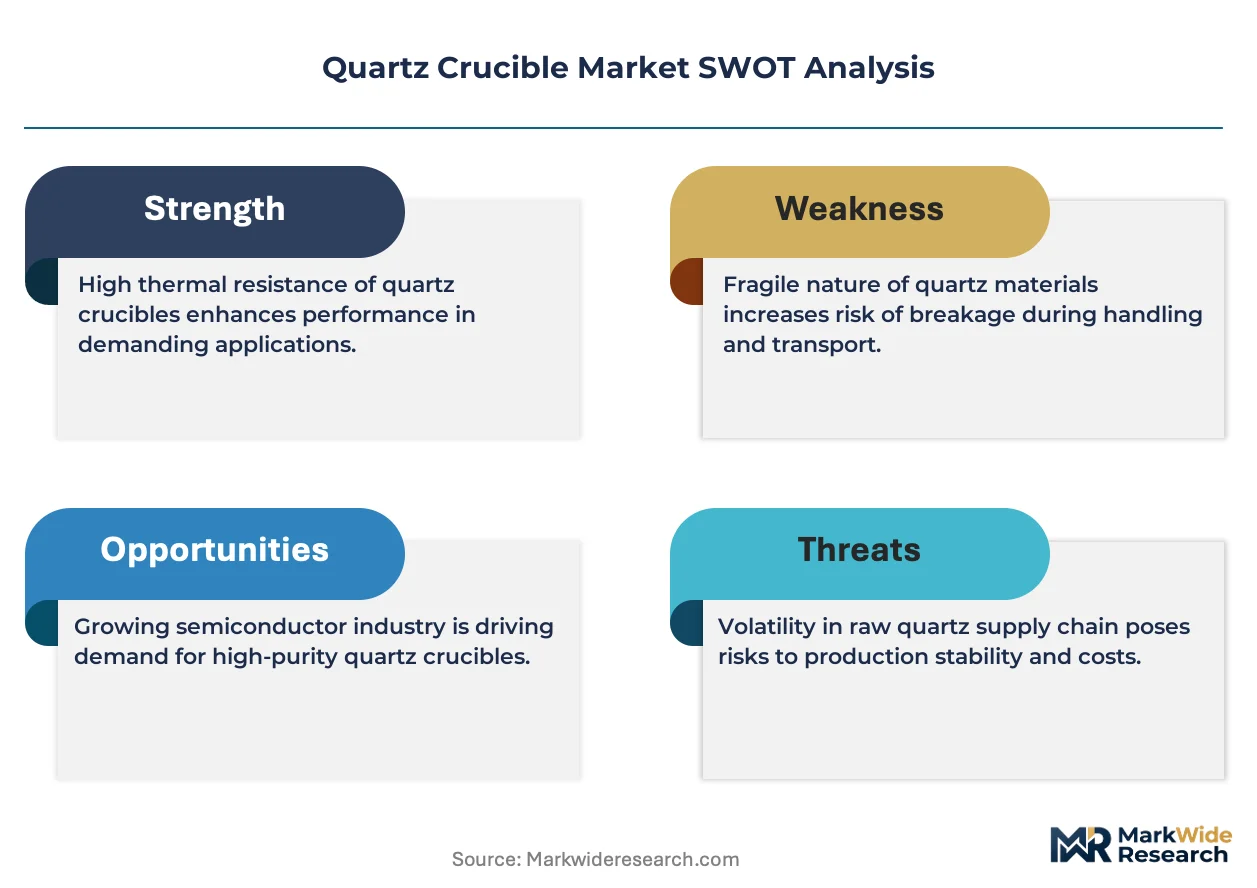
The quartz crucible market functions as a stable compounder anchored by irreversible semiconductor wafer diameter expansion and purity standard tightening that sustains replacement demand velocity.
For Market Incumbents: Lock in feedstock security through captive synthetic quartz supply agreements or equity stakes in Japanese and German chemical conglomerates. Expand coating technology capabilities to extend crucible lifecycles and defend against silicon carbide vessel substitution in wide-bandgap semiconductor crystal growth. Prioritize certification laboratory accreditation in South Korea's Seoul-Suwon corridor to compress qualification timelines with Samsung and SK Hynix. For New Entrants and Emerging Players: The premium-to-economy price gap in semiconductor-grade versus solar-grade vessels offers entry space for mid-purity specialists. Target India's Gujarat and Tamil Nadu semiconductor clusters where PLI scheme subsidies attract fabs without established crucible supplier relationships. Pursue joint qualification programs with emerging foundries before incumbent exclusivity terms harden. For Investors and Strategic Acquirers: Chemical conglomerates with synthetic fused silica feedstock control are the most active acquirer in this space, seeking downstream crucible fabrication capabilities to capture margin stack. The five-to-ten year viability window favors integrated suppliers with captive environmental infrastructure for REACH compliance. Monitor batch-level ICP-MS certification velocity as the inflection indicator for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Quartz Feedstock | Shin-Etsu Chemical's Naoetsu and Takefu facilities demonstrate margin capture through upstream silica control. |
| Coating Technology Licensing | Heraeus Holding's thermal management solutions extend crucible lifecycles in TSMC's high-pull-rate crystal growth. |
| Dual-Use Facility Retrofitting | Jiangsu Pacific Quartz captures arbitrage between solar ingot and semiconductor wafer specifications in Xuzhou operations. |
| Direct Long-Term Contracting | Samsung Foundry's three-year supply agreements with fixed purity tiers displace spot-market procurement channels. |
| Cleanroom Logistics Infrastructure Deployment | Kaohsiung-based providers operate nitrogen-purged shipping containers for contamination-controlled crucible delivery. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged crucible manufacturing plant managers, semiconductor foundry procurement leads, synthetic quartz feedstock specialists, and thermal coating R&D directors across East Asian manufacturing clusters. Secondary validation drew from customs and trade data, SEC 10-K filings of listed materials companies, METI semiconductor material directives, and NMPA GB standard evolution documents. Bottom-up capacity and shipment estimates triangulated against top-down end-use demand modeling from wafer start projections.
Segment-weighting approaches applied differential growth assumptions across purity grades, end-use industries, and regional regulatory clusters. The analytical framework modeled semiconductor-grade versus solar-grade versus laboratory-grade tiers alongside coating technology adoption patterns and direct contracting penetration rates across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles against wafer capacity expansion schedules and purity standard tightening trajectories.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide crucible substitution in GaN and SiC crystal growth would alter the outlook. Forecasts reflect documented assumptions regarding NMPA certification timeline enforcement and synthetic quartz feedstock supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
Europe Semiconductor Materials Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Global Indium Tin Oxide (ITO) Market
Semiconductor Material
Fullerene Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Electronic Thermal Management Materials Market