
 Polymer Microinjection Molding Market | 2026-2036
Polymer Microinjection Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Microinjection Molding Market Intelligence
New capacity investments in Germany and Switzerland are reshaping the competitive positioning for high-precision component manufacturing. Stamm AG leverages its Swiss location to specialize in complex micro-geometries for medical and watchmaking applications. SMC Ltd. competes on a global scale, offering integrated contract manufacturing services for life science and electronics. Accu-Mold LLC differentiates through its focus on high-volume, automated production of micro-sized thermoplastic parts.
Polymer microinjection molding is a manufacturing process producing extremely small plastic parts with high precision and tight tolerances, often measured in microns. The process utilizes specialized machinery to inject molten polymer into micro-scale cavities, creating complex geometries with features as small as 10 microns. The medical device manufacturer end-user segment drives market volume, primarily for microfluidics and diagnostic applications. Thermoplastics like PEEK and LCP dominate material selection, while biopolymers represent the fastest-growing material category for sustainable products.
In the United States, FDA regulations for medical devices dictate material traceability and stringent process validation requirements for molders. The EU's Medical Device Regulation (MDR) and China's NMPA rules impose similar conformity assessments and quality management system audits, impacting market access. Suppliers must decide whether to invest in the cleanroom capabilities and ISO 13485 certifications required for medical applications or focus on industrial segments like telecommunications and aerospace.
Market Dynamics
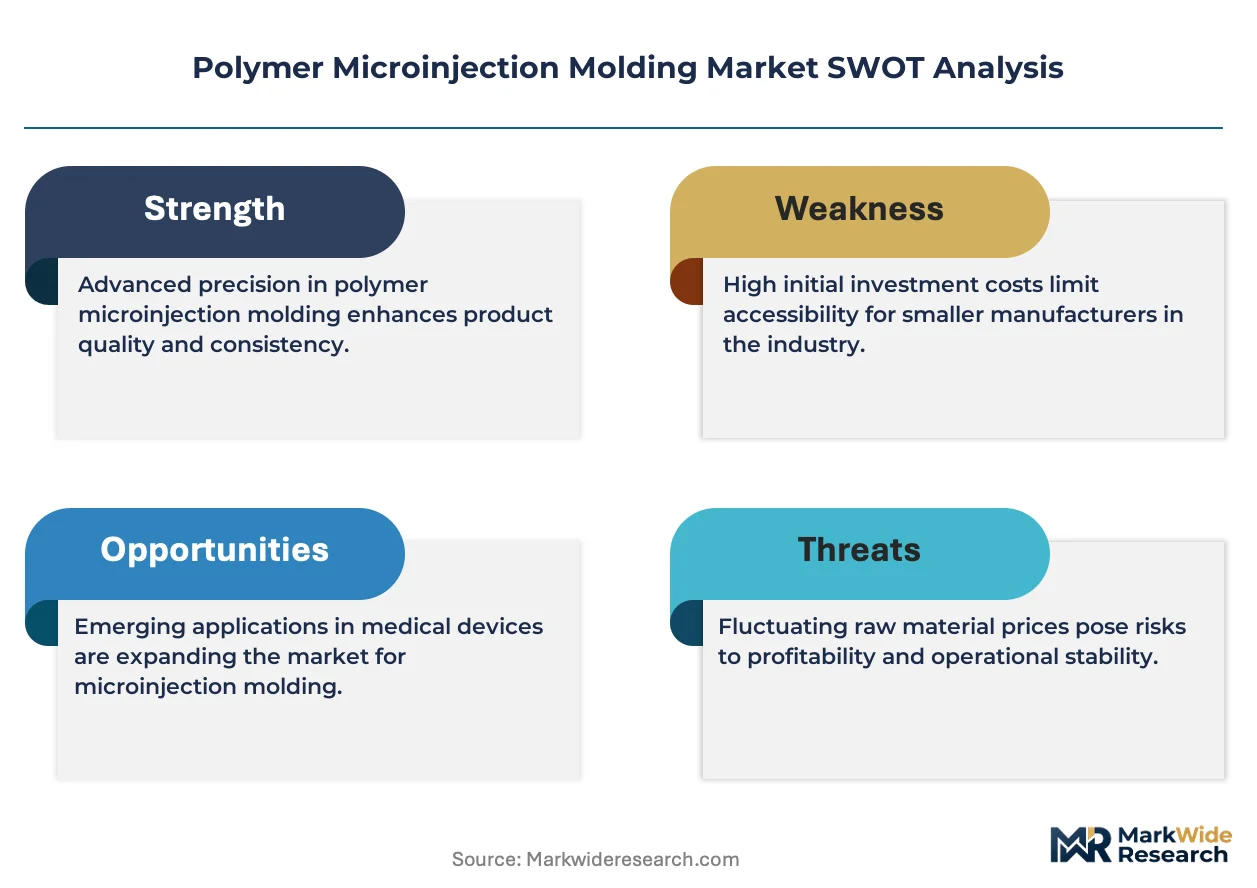
The central force shaping the polymer microinjection molding market is the convergence of medical device miniaturization with tightening regulatory frameworks. Demand for smaller, more complex components for diagnostics and microfluidics is intersecting with stricter quality system requirements under ISO 13485 and regional regulations.
Growth Catalysts
- EU Medical Device Regulation:The EU's MDR imposes stringent conformity assessments and post-market surveillance, creating demand for molders with robust quality management systems and full process documentation for medical components.
- Sustainable Materials Adoption:A push for sustainability in disposable medical products and electronics packaging drives the development and adoption of high-performance biopolymers like bio-based PEEK and PLA, opening new material science frontiers.
- Point-of-Care Diagnostics:The expansion of microfluidic-based point-of-care testing devices creates high-volume demand for precisely molded diagnostic consumables, such as lab-on-a-chip cartridges and sample wells.
Market Restraints
- High Capital Investment:The substantial upfront cost for specialized micro-molding machines, high-precision tooling, and the construction of ISO-certified cleanroom environments acts as a significant barrier to entry.
- Polymer Supply Concentration:A limited number of suppliers for specialty medical-grade polymers, such as PEEK and LCP, creates potential for supply chain bottlenecks and price volatility for molding companies.
- Process Consistency Challenges:Achieving consistent part quality and tight tolerances on features below 20 microns is technically demanding, often leading to high initial scrap rates and complex process optimization cycles.
Strategic Opportunities
- Wearable Drug Delivery:The development of miniaturized, wearable systems for automated insulin or hormone delivery presents a significant opportunity for micro-molded components like pump mechanisms, fluid channels, and needle housings.
- Japanese Electronics Sector:Japan's advanced electronics and automotive sensor industries represent a target market for molders capable of producing micro-connectors, gears, and optical components with extreme precision.
- In-Mold Sensor Integration:Integrating micro-sensors directly into the mold cavity for real-time monitoring of pressure, temperature, and flow offers a path to zero-defect manufacturing and enhanced process control.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of skilled process engineers, metrologists, and toolmakers with expertise in micro-scale polymer science and tooling fabrication constrains capacity expansion for many firms.
- Certification Timelines:The lengthy and resource-intensive process of achieving and maintaining ISO 13485 certification and completing part-specific FDA or MDR validation can delay market entry for new medical products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Microinjection Molding Market |
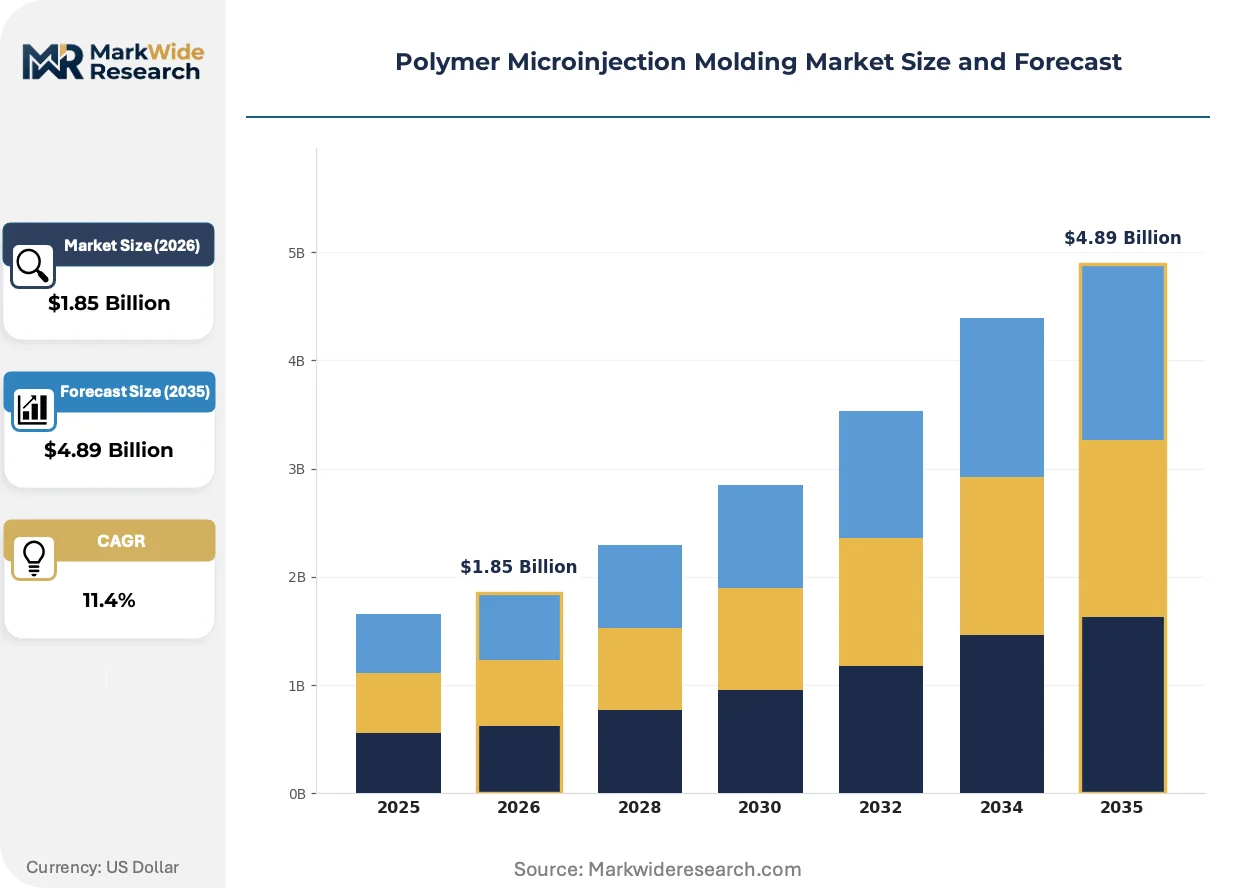
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosets, Elastomers, Biopolymers, Acrylics Technology: Micro-Cavity Molding, Hot Runner System, Cold Runner System, Stack Mold, Two-Color Molding Application: Microfluidics, Optical Components, Telecommunications, Consumer Electronics, Aerospace Devices End User: Medical Device Manufacturers, Electronics Providers, Aerospace Firms, Precision Engineering Companies, Moldmakers |
| Companies Covered | Micromolding Solution Inc., Stack Plastics Inc., Accu-Mold LLC, Sovrin Plastics, Stamm AG, Precipart, Rapidwerks Inc., SMC Ltd., Makuta Technics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Microinjection Molding Market Strategic Shifts & Innovations
Process automation and material science advancements are enabling new levels of part complexity and functional integration. These innovations are shifting the value proposition from simple component production toward integrated manufacturing solutions, particularly in regulated end-markets like medical devices.
Multi-material micro-molding combines two or more polymers, such as a rigid thermoplastic and a soft elastomer, into a single component during one molding cycle. Medical device and electronics manufacturers are adopting this to create integrated seals, soft-touch grips, or flexible hinges. The process is migrating from multi-step assembly and bonding towards a single, integrated manufacturing step, reducing contamination risk and improving part reliability.
Heightened enforcement of the ISO 13485 standard for medical device quality management systems is a significant regulatory driver. This requires molders to implement comprehensive process validation, statistical process control, and end-to-end material traceability from resin lot to finished device. Suppliers to the life sciences sector are most affected, compelling investment in advanced metrology, automated inspection, and digital quality documentation systems.
A notable behavioral shift involves original equipment manufacturers (OEMs) moving away from transactional component purchasing. They now seek molding partners who provide comprehensive services, including early-stage design for manufacturability (DFM), tool building, validation, and automated assembly. This trend favors suppliers with integrated contract manufacturing capabilities over pure-play molders. This pattern is most visible in the North American and European medical diagnostics industries.
Polymer Microinjection Molding Market Segmentation
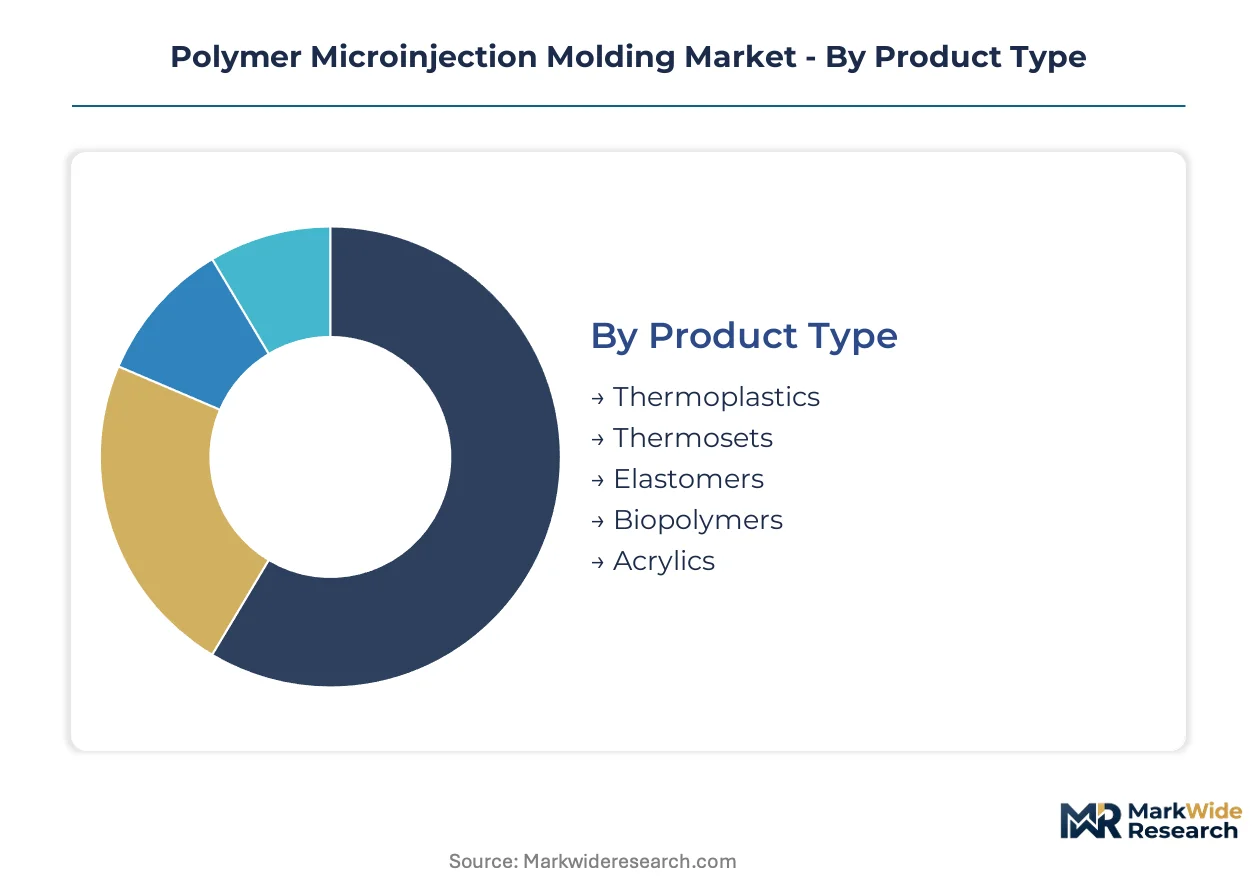
Understanding the Polymer Microinjection Molding Market through segmentation reveals distinct demand patterns and technological priorities across various end-use sectors. Manufacturers tailor their capabilities to specific material requirements and application complexities, influencing competitive strategies. This granular analysis highlights where innovation and investment are most concentrated.
Product Type:
The product type segmentation reflects the material science maturity and sustainability targets within the microinjection molding industry.
- Thermoplastics:These are the most widely utilized polymer materials, offering excellent melt flow characteristics and mechanical properties for micro-molding. Demand concentrates in medical device manufacturing for components like microfluidic chips and diagnostic cartridges, where high precision and biocompatibility are critical.
- Biopolymers:Derived from renewable biomass, biopolymers represent a rapidly expanding segment driven by sustainability initiatives and demand for biodegradable medical and consumer electronic parts. Adoption is accelerating in Europe due to stringent environmental regulations and consumer preference for eco-friendly products.
- Thermosets:These materials undergo irreversible chemical changes during molding, resulting in high thermal stability and chemical resistance for specialized applications.
- Elastomers:Offering flexibility and elasticity, elastomers are crucial for micro-seals, gaskets, and soft-touch components in wearable devices.
- Acrylics:Known for their optical clarity and stiffness, acrylics find use in micro-lenses, light guides, and display components for electronics.
Thermoplastics retains volume leadership; Biopolymers holds the steepest expansion curve.
Technology:
The technology segment highlights the specialized processes required to achieve micron-level precision and complex geometries in polymer microinjection molding.
- Micro-Cavity Molding:This core technology involves injecting molten polymer into extremely small mold cavities, producing parts with features as fine as 10 microns. Its precision is critical for microfluidic components in point-of-care diagnostic devices.
- Hot Runner System:Hot runner systems maintain the polymer in a molten state within the runner, minimizing material waste and cycle times for high-volume production. This technology is vital for efficient manufacturing of diagnostic consumables in North America.
- Cold Runner System:Employing a runner system that cools and solidifies with the part, cold runners are often simpler and less expensive, suitable for lower volume or less complex micro-parts.
- Stack Mold:Stack molds increase production capacity by utilizing multiple parting lines, effectively doubling the output per molding cycle for high-volume micro-components.
- Two-Color Molding:This advanced process combines two different polymers or colors into a single micro-part during one molding cycle, enabling integrated functionality like flexible hinges or sealed interfaces.
Micro-Cavity Molding remains foundational for precision, while Hot Runner Systems drive production efficiency.
Application:
The application segment illustrates the diverse end-use sectors leveraging polymer microinjection molding for miniaturized components.
- Microfluidics:This application involves devices that manipulate small volumes of fluids, including lab-on-a-chip diagnostic systems and drug delivery cartridges. Demand is strong from medical device manufacturers in Switzerland and Germany.
- Optical Components:Micro-molded optical components include lenses, prisms, and light guides for miniaturized cameras, sensors, and fiber optic connectors. High precision is paramount for these parts in Japan's electronics sector.
- Telecommunications:Micro-connectors, fiber optic components, and sensor housings are critical for high-speed data transmission and compact communication devices.
- Consumer Electronics:Small gears, switches, and intricate housings for smartphones, wearables, and other portable devices rely on microinjection molding.
- Aerospace Devices:Lightweight, high-performance micro-components are used in sensor systems, control mechanisms, and interior elements for aerospace applications.
Microfluidics applications generate substantial market volume, while Optical Components capture high-value precision opportunities.
End User:
The end-user segment reveals the primary industries driving demand and shaping the regulatory landscape for polymer microinjection molding services.
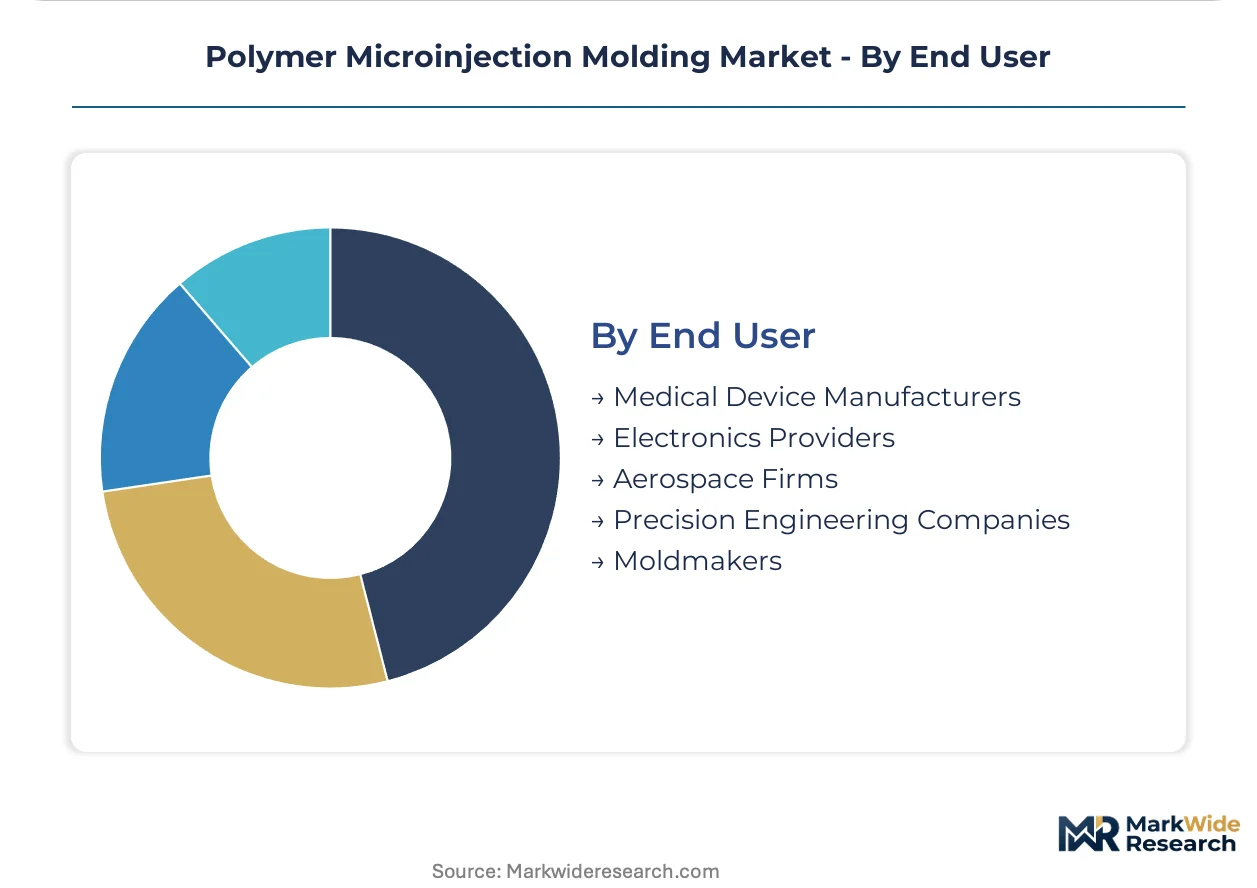
- Medical Device Manufacturers:This segment is the largest consumer, requiring micro-molded parts for diagnostics, surgical instruments, and drug delivery systems. Stringent regulations like ISO 13485 and the EU's MDR compel specialized manufacturing processes.
- Electronics Providers:Electronics companies utilize micro-molding for miniaturized connectors, sensor housings, and intricate internal components in consumer and industrial devices. High-volume production with consistent quality is a key requirement for these manufacturers.
- Aerospace Firms:Aerospace manufacturers demand lightweight, durable, and precision-molded components for critical systems and instrumentation.
- Precision Engineering Companies:These firms often serve multiple industries, requiring custom micro-molded solutions for complex mechanical assemblies and prototypes.
- Moldmakers:While not direct end-users of molded parts, moldmakers are critical partners in the supply chain, designing and producing the high-precision tooling necessary for microinjection molding.
Meeting the rigorous demands of Medical Device Manufacturers shapes industry standards, with Electronics Providers driving innovation in miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration in the Polymer Microinjection Molding Market reveals distinct pockets of manufacturing excellence. These areas leverage specialized expertise and robust regulatory frameworks to serve high-value end-user segments. Precision engineering hubs and medical technology clusters primarily drive demand in key global regions.
Germany
Medical device miniaturization and precision engineering drive significant demand for polymer microinjection molding in Germany. The EU's Medical Device Regulation (MDR) necessitates stringent quality management systems for components. Bavaria and Baden-Württemberg host strong medical technology clusters, fostering innovation in microfluidics and diagnostic consumables.
Switzerland
Switzerland's demand for micro-molded components stems from its advanced medical technology and luxury watchmaking industries. ISO 13485 certification is critical for suppliers to the country's medical device manufacturers. The Neuchâtel region stands as a hub for precision engineering, specializing in complex micro-geometries and high-tolerance parts.
United States
The United States market is characterized by strong demand from medical device manufacturers for diagnostic consumables and drug delivery systems. FDA regulations dictate material traceability and stringent process validation requirements for molders. Biotech hubs in Boston and the San Francisco Bay Area are key centers for microfluidics development and production.
Japan
Advanced electronics and automotive sensor industries generate substantial demand for optical components and micro-connectors in Japan. METI standards for industrial precision and quality guide manufacturing practices for micro-molded parts. The Kanto region, including Tokyo, houses major electronics and automotive firms that require extreme precision in miniaturized components.
China
China's electronics packaging and medical device sectors are driving the need for high-volume, precision micro-molding. NMPA rules impose conformity assessments and quality management system audits for medical devices, influencing local suppliers. The Yangtze River Delta region is a significant manufacturing base, supporting both domestic and export-oriented production of micro-components.
Polymer Microinjection Molding Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the Polymer Microinjection Molding Market. The market exhibits a tiered structure, with a few large integrated contract manufacturers and numerous niche specialists focusing on specific applications. Strategic archetypes include high-volume producers, precision micro-geometry experts, and full-service solution providers catering to demanding sectors. Dominant competitive moves involve significant capital investment in advanced machinery and cleanroom facilities, alongside strategic partnerships for end-to-end service delivery.
Specialization in complex micro-geometries distinguishes firms like Stamm AG, a Swiss-based entity. This company represents a segment focused on intricate parts for medical and watchmaking applications, emphasizing precision in micro-molding. Accu-Mold LLC exemplifies providers specializing in high-volume, automated production of micro-sized thermoplastic components, serving industries requiring consistent large-scale output. SMC Ltd., with its global presence, occupies a position among integrated contract manufacturers. This firm offers comprehensive services for life science and electronics clients, spanning design, molding, and assembly, which is a growing trend among OEMs.
| Leading Market Players |
|---|
| Micromolding Solution Inc. |
| Stack Plastics Inc. |
| Accu-Mold LLC |
| Sovrin Plastics |
| Stamm AG |
| Precipart |
| Rapidwerks Inc. |
| SMC Ltd. |
| Makuta Technics |
| Others |
Cost & Logistics Intelligence
Polymer supply concentration creates potential for price volatility, directly shaping pricing tier spreads and influencing the geographic configuration of microinjection molding supply chains. This dependency impacts both raw material costs and finished component pricing.
Pricing Analysis
ISO 13485 dictates the pricing tier structure for medical-grade micro-molded components, favoring contract-based long-term offtake agreements. Price differentiation stems from certification level, particularly for medical device applications, and the complexity of micro-geometries. Pricing softness reflects high capital investment requirements, which necessitates consistent volume for profitability. Medical device manufacturers are least price-sensitive, prioritizing quality and regulatory compliance, while consumer electronics providers seek cost efficiencies for high-volume parts.
Supply Chain Analysis
Integrated contract manufacturers like SMC Ltd. and specialized firms such as Stamm AG hold significant capacity for polymer microinjection molding. Geographic supply concentration exists in Germany, Switzerland, and Japan, leveraging precision engineering expertise. Supply chains rely on specialty medical-grade polymers, including PEEK and LCP, and high-precision tooling. Specialized talent scarcity represents a structural risk, limiting capacity expansion. Distribution runs through direct partnerships with OEMs, particularly in the medical diagnostics and electronics sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Polymer Microinjection Molding Market offers a fragmentation opportunity, driven by medical device miniaturization creating specialized niches for complex micro-geometries. This demand shift enables focused market entry and growth strategies.
For Market Incumbents: Insulate core market share by investing in advanced metrology and automated inspection to meet heightened ISO 13485 standards. Deepen vertical integration into specialized tooling fabrication to counter process consistency challenges and reduce reliance on external suppliers. This mitigates the threat of new entrants offering lower-cost, less compliant solutions. Capacity addition in Switzerland or Germany further reinforces precision engineering expertise. For New Entrants and Emerging Players: Build out capabilities in high-volume biopolymer molding for sustainable diagnostic consumables. Target the European market, particularly Germany, due to stringent environmental regulations and demand for eco-friendly products. Focus on a go-to-market angle emphasizing rapid prototyping and validation services for emerging point-of-care diagnostic startups. This addresses the high capital investment barrier with specialized, targeted offerings. For Investors and Strategic Acquirers: The market sits at a growth phase that favors niche specialists with deep expertise in medical microfluidics. Long-term viability remains strong over the next decade, driven by ongoing miniaturization trends in healthcare. Target acquisition archetypes include precision micro-molding firms with strong ISO 13485 certifications and established OEM relationships in Switzerland or the US. The signal to watch is the increasing adoption rate of in-mold sensor integration, indicating readiness for advanced manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Cleanroom Facilities | Expanding ISO-certified cleanroom capacity in Germany supports high-volume medical device component production for EU MDR compliance. |
| Biopolymer Material R&D Partnership | Collaborating on biopolymer development with material scientists enables sustainable product offerings for environmentally conscious European consumers. |
| Advanced Metrology System Integration | Integrating automated metrology systems ensures sub-20 micron tolerance verification, critical for high-precision optical components in Japan. |
| Design for Manufacturability (DFM) Services Expansion | Offering early-stage DFM services strengthens OEM partnerships, reducing development cycles for microfluidic diagnostic devices. |
| Skilled Talent Development Programs | Investing in specialized training programs for process engineers addresses the persistent scarcity of micro-molding expertise. |
Research Approach
The analysis maps microfluidics, optical components, and telecommunications sub-sectors, each validated through extensive interviews with R&D directors and procurement managers. Primary insights came from discussions with medical device engineers, specialty polymer suppliers, and toolmakers. Secondary validation involved reviewing NMPA rules, EU MDR guidelines, and company 10-K filings. Both bottom-up market sizing and top-down revenue validations were triangulated for accuracy.
Assumptions held fixed included stable regulatory frameworks and consistent material supply, while variables like technological advancements in multi-material molding were modeled. The analytical framework projected market growth across the analysis window, segmenting by product type, technology, application, end-user, and regional manufacturing capacity. Compound Annual Growth Rates (CAGRs) were derived from historical growth trends and projected demand shifts. Forecast inputs included microfluidic device adoption rates and biopolymer development timelines.
Sensitivities concentrate around unforeseen shifts in medical device regulations and the pace of biopolymer innovation. Forecasts reflect these underlying assumptions, acknowledging potential impacts from global economic volatility or supply chain disruptions. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Antimicrobial Plastics Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
PA66 Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Emulsion PVC Market