
 GCC Polyethylene Terephthalate (PET) Market | 2026-2036
GCC Polyethylene Terephthalate (PET) Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Polyethylene Terephthalate (PET) Market Foresight
Saudi petrochemical producers is consolidating upstream ethylene glycol and purified terephthalic acid supply around the Jubail industrial corridor. SABIC leverages integrated feedstock access to dominate regional resin supply. JBF RAK anchors high-volume bottle-grade output from its Ras Al Khaimah complex. Qatar Petrochemical Company sustains competitive positioning through captive naphtha supply and Gulf-wide distribution reach.
Polyethylene terephthalate is a thermoplastic polymer synthesized from ethylene glycol and terephthalic acid through polycondensation, yielding a material with crystalline melting points near 250°C and excellent barrier properties against moisture and gases. The resin serves primarily as a lightweight, shatter-resistant substrate for beverage bottles, food trays, and synthetic textile fibers across industrial and consumer applications. Packaging-grade PET leads volume demand across the GCC, driven by per-capita bottled water consumption and carbonated soft drink proliferation in Gulf markets. Bottle-grade resin commands premium positioning due to stringent IV (intrinsic viscosity) specifications and food-contact compliance requirements. Fiber-grade PET occupies a mature, cost-competitive segment serving Saudi Arabia's large synthetic textile export base.
Saudi Standards, Metrology and Quality Organization (SASO) mandates food-contact safety certifications and migration testing for all PET packaging entering the Kingdom's consumer goods channel. The UAE's Ministry of Climate Change and Environment enforces extended producer responsibility frameworks that push converters toward rPET incorporation targets. Gulf Cooperation Council customs harmonization is reducing technical barriers to resin trade, though national labeling and recycling-content rules still fragment procurement requirements. Stakeholders must monitor how divergent national circular economy timelines reshape virgin versus recycled resin sourcing strategies.
Market Dynamics
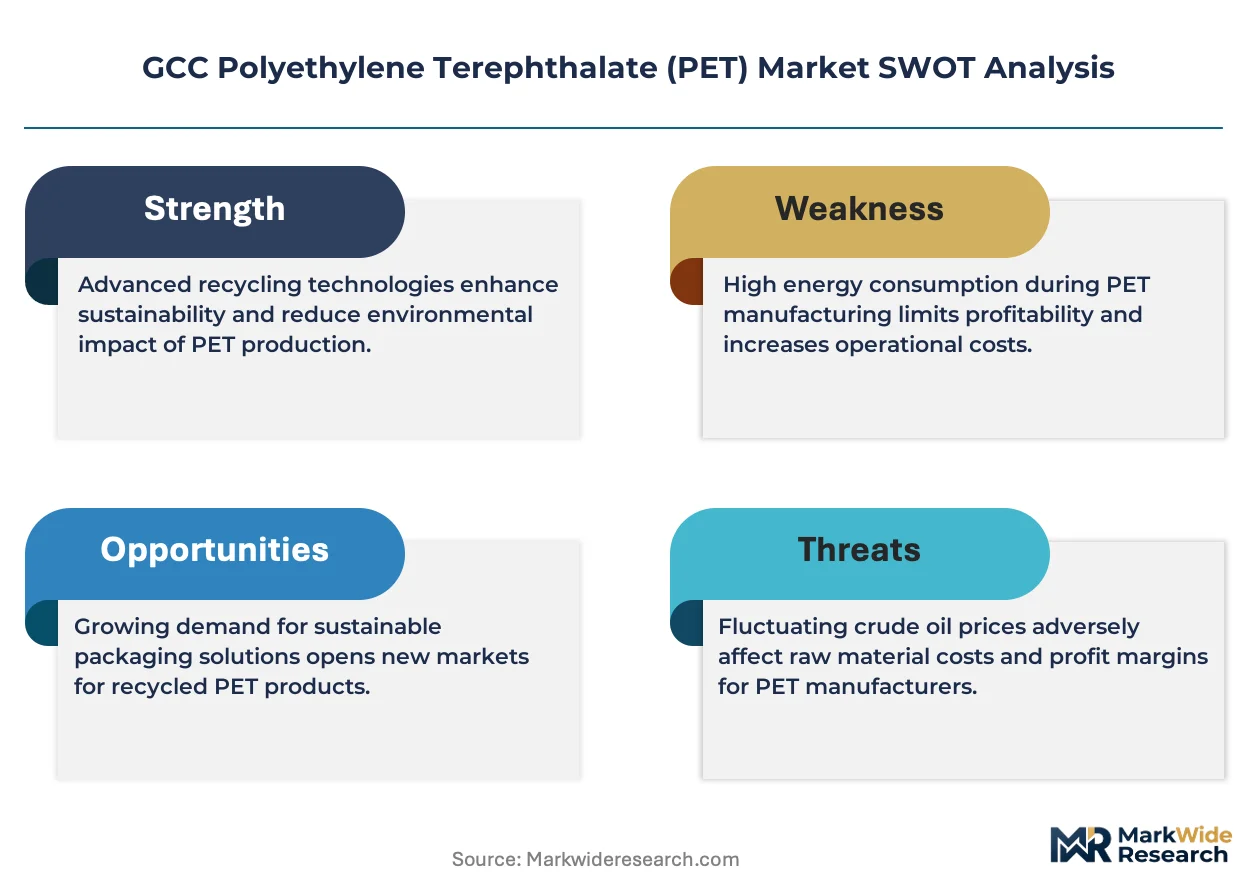
Upstream ethylene glycol and purified terephthalic acid supply is consolidating around Saudi Arabia's Jubail industrial corridor, giving integrated producers captive feedstock leverage over regional converters who lack backward integration into aromatics and olefins.
Growth Catalysts
- Extended Producer Responsibility Mandates:The UAE's Ministry of Climate Change and Environment is enforcing rPET incorporation targets that pull converters toward certified recycled content streams.
- Downstream Beverage Clustering:Large-scale bottling facilities across Saudi Arabia's Eastern Province generate sustained pull for food-contact-grade resin with tight IV specifications.
- Gulf Customs Harmonization:GCC-wide technical barrier reduction is streamlining cross-border resin trade between Saudi Arabia, UAE, and Qatar.
Market Restraints
- Feedstock Cost Volatility:Paraxylene and ethylene glycol prices track naphtha-crude spreads, compressing margin predictability for non-integrated converters.
- Supply Concentration Risk:Three integrated producers control over eighty percent of regional purified terephthalic acid output, creating procurement vulnerability.
- rPET Quality Inconsistency:Post-consumer feedstock variability limits food-contact substitution rates below regulatory targets.
Strategic Opportunities
- Qatar Industrial Expansion:Ras Laffan petrochemical complex expansion plans include dedicated PET-grade aromatics capacity for Gulf distribution.
- Bottle-to-Fiber Chemical Recycling:Pyrolysis-based depolymerization is opening food-contact pathways for contaminated post-consumer streams.
- Lightweighting Technology Convergence:Stretch blow molding advances combined with barrier coating developments enable sub-ten-gram preform weights.
Industry Challenges
- Migration Testing Bottlenecks:SASO certification timelines for new resin grades extend six to nine months, delaying product launches.
- Skilled Polymer Engineering Scarcity:Gulf universities produce limited graduates in polymer rheology and IV control for bottle-grade specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Polyethylene Terephthalate (PET) Market |
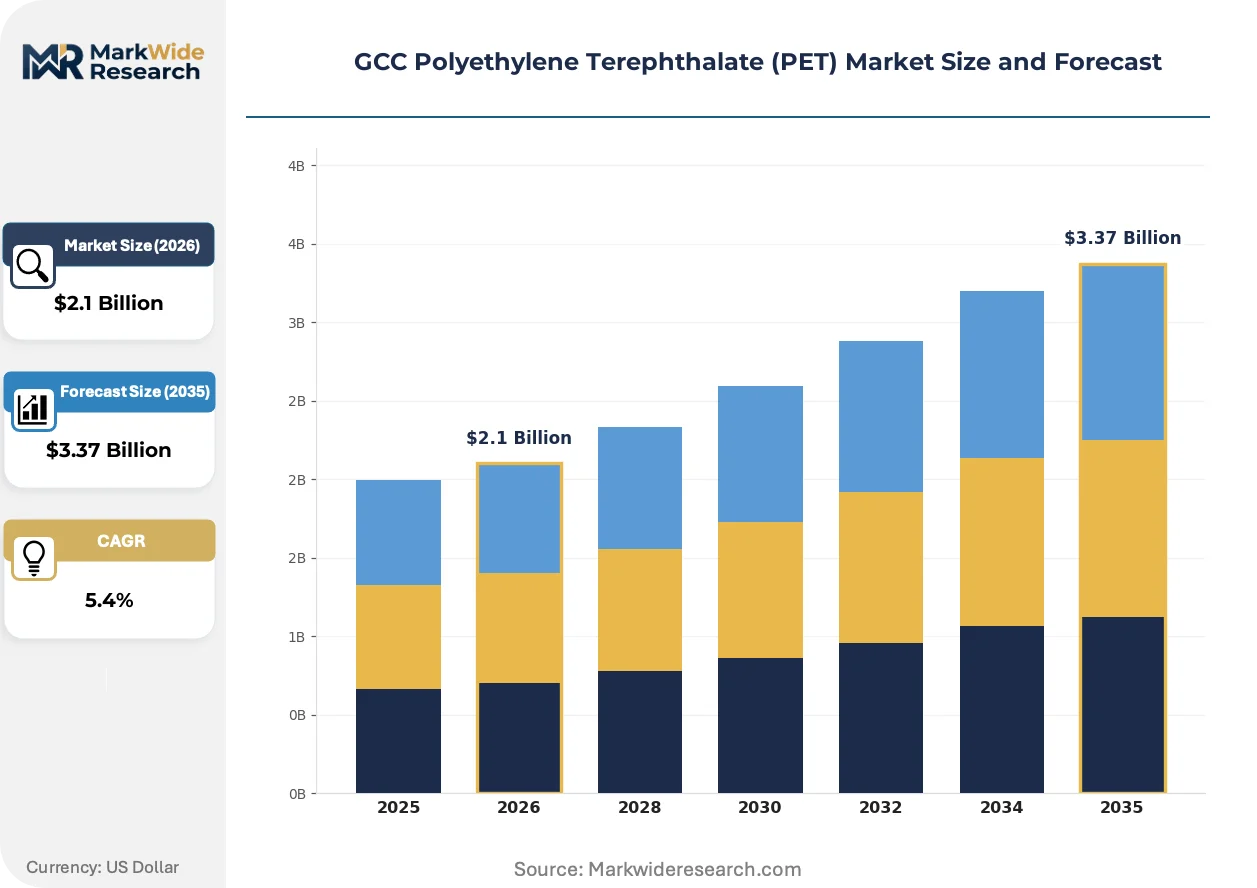
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Grade, Packaging Grade, Film Grade, Bottle Grade, Engineering Grade Application: Textile, Food & Beverage Containers, Electrical Insulation, Automotive Components, Cosmetic Packaging End User: Apparel Manufacturers, Beverage Producers, Electrical Equipment Suppliers, Vehicle Manufacturers, Beauty Product Companies Packaging Type: Bottle, Jar, Blister Pack, Clamshell, Shrink Wrap |
| Companies Covered | JBF RAK, Petkim, OCTAL, Qatar Petrochemical Company, Equate Petrochemical Company, SABIC, National Petrochemical Industrial Company, Alujain Corporation, PAN-ASIA SAUDI CO., LTD, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Polyethylene Terephthalate (PET) Market Shifts & Advancements
Active reshaping of the GCC PET landscape centers on regulatory pressure for circular content, process technology enabling lightweighting, and converter procurement models that privilege supply security over spot-price optimization.
Mono-material barrier coating technology is unifying oxygen and carbon dioxide protection within single-substrate bottles. Saudi bottlers are piloting plasma-enhanced chemical vapor deposition systems at commercial scale. This unifying approach is compressing demand for multilayer co-injection equipment and simplifying recycling streams.
SASO's revised food-contact safety certifications now mandate specific migration thresholds for acetaldehyde and antimony catalyst residues. Converters face reformulation costs to meet the tightened specifications. Bottle-grade resin suppliers with pre-certified product lines are capturing procurement preference across Riyadh and Jeddah manufacturing clusters.
Beverage brand owners are consolidating resin procurement under multi-year offtake agreements with integrated producers. Spot market participation is shrinking among large GCC bottlers. Saudi Arabia's vertically integrated beverage groups are driving this shift most aggressively, trading price flexibility for supply continuity guarantees.
GCC Polyethylene Terephthalate (PET) Market Segmentation
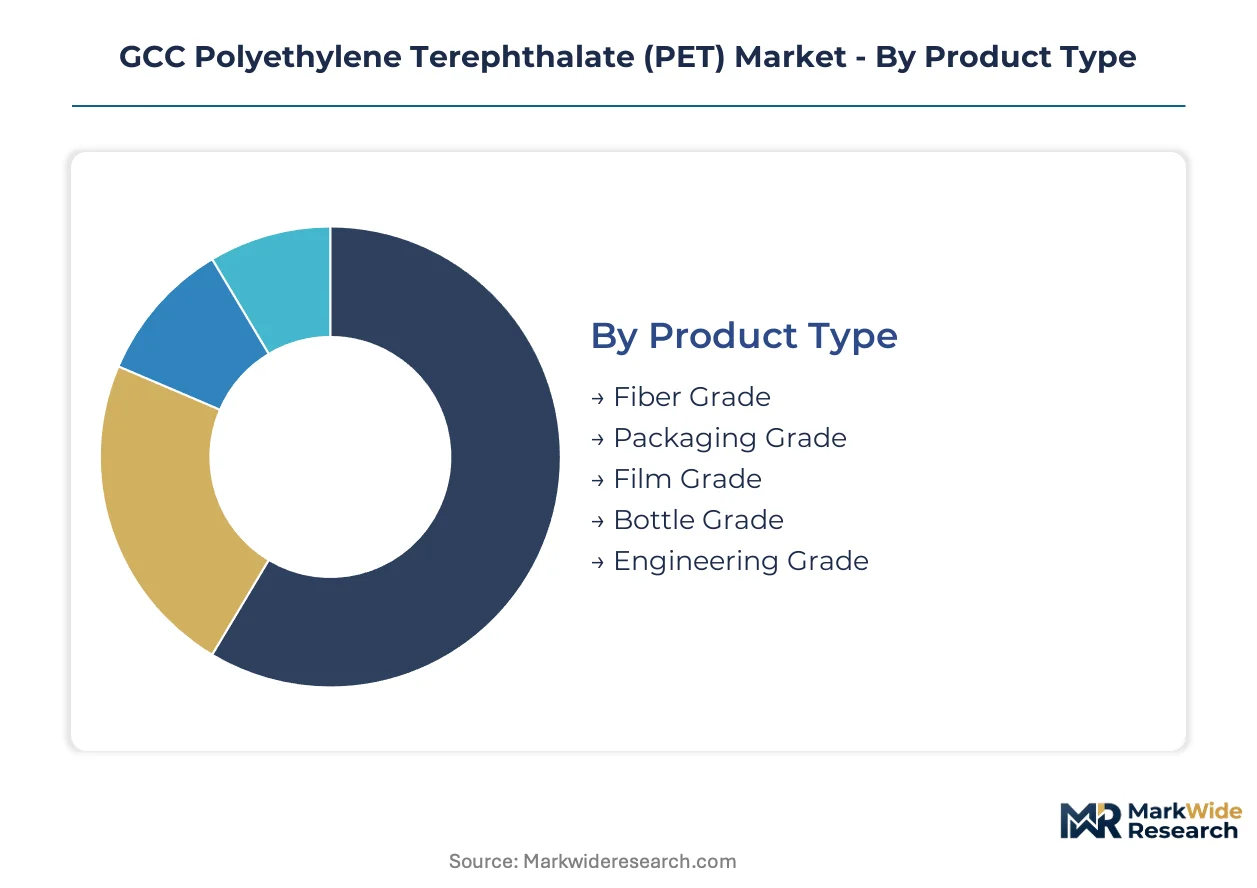
PET grade differentiation dictates procurement economics across the GCC, with intrinsic viscosity specifications and food-contact certifications creating tiered value capture. Segment boundaries increasingly blur as lightweighting and chemical recycling technologies enable cross-grade substitution.
Product Type:
Integration depth varies sharply: packaging and bottle grades operate as standalone specifications with dedicated supply chains, while fiber and film grades embed into downstream textile and industrial systems.
- Packaging Grade:Food-contact-compliant resin with IV specifications between 0.72-0.82 dL/g dominates procurement volumes. Saudi bottlers in the Eastern Province cluster drive sustained demand for SASO-certified material with tight acetaldehyde migration thresholds.
- Bottle Grade:Premium IV control (0.78-0.84 dL/g) enables stretch blow molding of sub-ten-gram preforms. UAE beverage producers under MOCCAE extended producer responsibility mandates are locking into multi-year offtake agreements with integrated suppliers.
- Fiber Grade:Lower IV specifications serve Saudi Arabia's synthetic textile export base through melt-spinning operations.
- Film Grade:Biaxially oriented variants supply flexible packaging converters across Gulf food manufacturing clusters.
- Engineering Grade:Reinforced and filled compounds target automotive underhood applications and electrical connector housings.
Volume placements concentrate in Packaging Grade; the faster expansion belongs to Bottle Grade.
Application:
Cost tier segmentation separates commodity container demand from specialized electrical and automotive specifications requiring compounded performance.
- Food & Beverage Containers:Carbonated soft drink and bottled water packaging absorbs the majority of regional resin output. Per-capita consumption rates in Saudi Arabia and the UAE sustain continuous pull for food-contact-certified material.
- Textile:Polyester fiber production for apparel and industrial yarns anchors demand in Saudi Arabia's Jubail industrial corridor. Synthetic textile exports from Kingdom-based producers compete on scale against Asian supply.
- Electrical Insulation:PET film and molded components serve cable wrapping and capacitor dielectrics in Gulf infrastructure projects.
- Automotive Components:Underhood applications leverage heat-stabilized engineering grades for connector housings and sensor brackets.
- Cosmetic Packaging:Premium jar and bottle applications demand optical clarity and surface finish precision for beauty product differentiation.
Food & Beverage Containers holds the dominant share; Cosmetic Packaging is climbing the fastest.
End User:
Customer type determines procurement leverage, with integrated beverage groups commanding supply security terms while fragmented apparel converters absorb spot price volatility.
- Beverage Producers:Vertically integrated Saudi bottling groups and UAE-based multinational operations consolidate procurement under long-term contracts. SASO certification requirements and MOCCAE rPET targets reshape supplier qualification criteria.
- Apparel Manufacturers:Saudi and Bahrain-based synthetic fiber producers source fiber-grade resin for melt-spinning into polyester yarn. Export-oriented operations compete on feedstock cost against integrated Asian rivals.
- Electrical Equipment Suppliers:Gulf infrastructure contractors specify PET film and molded insulators for power distribution projects.
- Vehicle Manufacturers:Regional automotive assemblers source engineering-grade compounds for underhood electrical and lightweight structural applications.
- Beauty Product Companies:Premium cosmetic houses in Dubai and Riyadh demand optical-grade material for high-clarity jar and bottle packaging.
Beverage Producers anchor volume demand; Beauty Product Companies show the steepest expansion trajectory.
Packaging Type:
Supply concentration clusters around bottle and jar formats, with secondary packaging formats absorbing residual converter capacity.
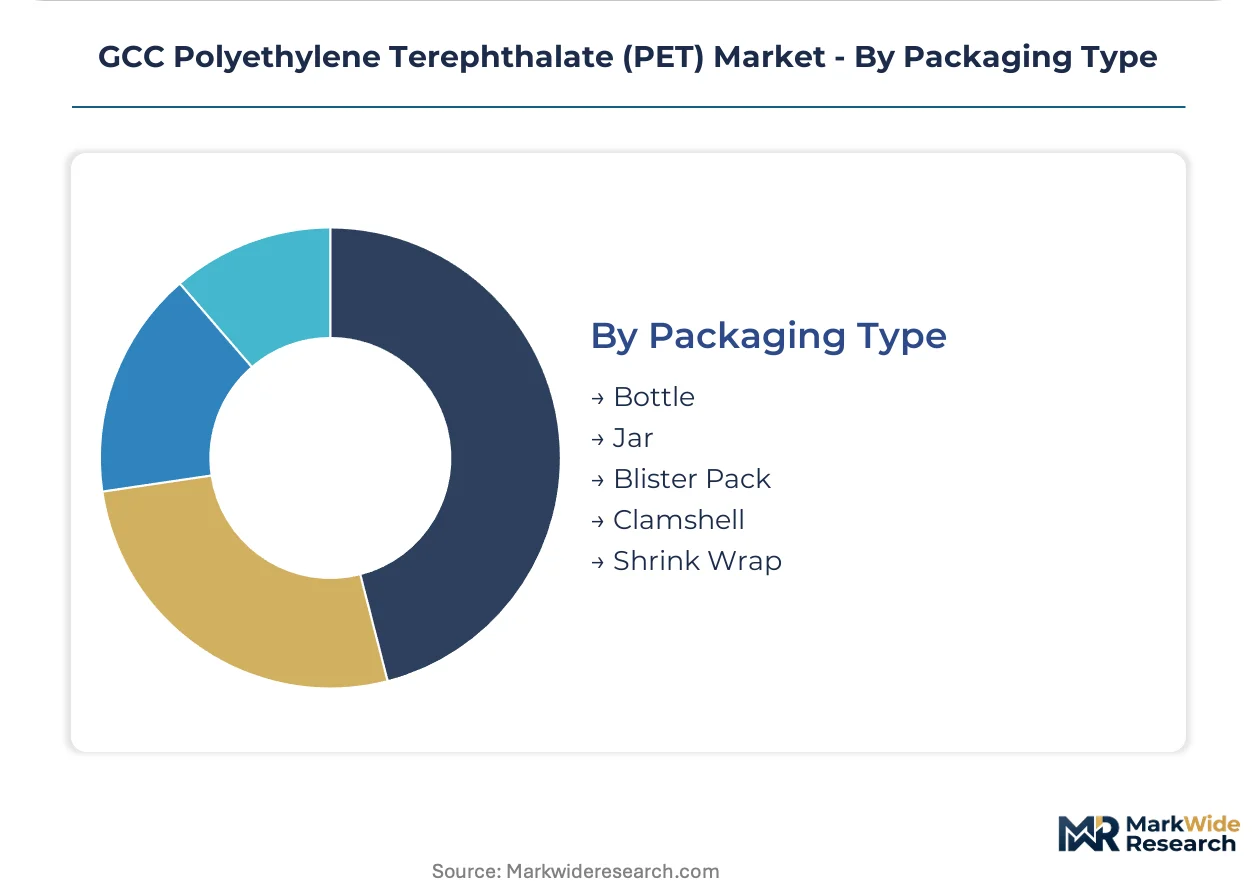
- Bottle:Stretch blow-molded containers for water, carbonated beverages, and edible oils represent the dominant format. Lightweighting advances and mono-material barrier coatings are compressing per-unit resin consumption.
- Jar:Wide-mouth containers for spreads, sauces, and cosmetic creams require modified IV specifications and enhanced wall thickness distribution.
- Blister Pack:Thermoformed pharmaceutical and consumer goods packaging utilizes amorphous PET sheet.
- Clamshell:Dual-cavity thermoformed containers serve fresh produce and electronics retail display applications.
- Shrink Wrap:Oriented film sleeves provide secondary bundling and tamper-evident sealing for multi-pack beverage distribution.
Bottle formats dominate volume placements; Jar applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail's aromatics corridor anchors GCC PET supply through captive paraxylene and ethylene glycol streams. Saudi Arabia's integrated petrochemical base feeds downstream bottle-grade resin production across the Gulf. National circular economy mandates now reshape procurement flows from Kuwait to Oman.
Saudi Arabia
Beverage bottlers in Riyadh and Jeddah drive sustained demand for SASO-certified food-contact resin with tight acetaldehyde thresholds. The Saudi Standards, Metrology and Quality Organization mandates six-to-nine-month migration testing timelines for new grades. Eastern Province manufacturing clusters around Jubail consume the majority of regional packaging-grade output through vertically integrated supply chains.
United Arab Emirates
Dubai and Abu Dhabi beverage producers face MOCCAE extended producer responsibility mandates pushing rPET incorporation targets. The Ministry of Climate Change and Environment enforces circular economy frameworks that privilege certified recycled content streams. Ras Al Khaimah's industrial zone hosts high-volume bottle-grade conversion capacity serving Gulf-wide distribution.
Qatar
Ras Laffan petrochemical complex expansion plans include dedicated PET-grade aromatics capacity for regional supply security. Qatar Petrochemical Company leverages captive naphtha feedstock to sustain competitive positioning across GCC markets. Doha-based converters access Gulf-wide distribution networks through integrated logistics infrastructure.
Kuwait
Equate Petrochemical Company's regional resin supply reaches Kuwaiti converters through harmonized GCC customs frameworks. Local beverage manufacturers source bottle-grade material under multi-year offtake agreements with integrated producers. Shuaiba industrial area hosts downstream packaging conversion for domestic food and beverage distribution.
Oman
SOHAR Port and Freezone attracts PET resin import flows for Omani beverage and food packaging converters. National waste management regulations are developing extended producer responsibility frameworks aligned with UAE and Saudi timelines. Muscat manufacturing clusters rely on cross-border supply from UAE and Saudi integrated producers.
GCC Polyethylene Terephthalate (PET) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue chemical recycling and lightweighting technology licensing. Three integrated players control over eighty percent of regional purified terephthalic acid output, creating a concentrated supply structure. Strategic archetypes include backward-integrated petrochemical majors, regional bottle-grade specialists, and state-linked industrial conglomerates. Competitive moves center on multi-year offtake contracting and captive feedstock expansion rather than spot-market participation.
Among Saudi-based industrial conglomerates, SABIC anchors the integrated petrochemical tier through Jubail corridor feedstock access. JBF RAK exemplifies the regional bottle-grade specialist archetype from its Ras Al Khaimah complex. Qatar Petrochemical Company represents state-linked industrial positioning through Ras Laffan captive naphtha supply and Gulf-wide distribution infrastructure.
| Leading Market Players |
|---|
| JBF RAK |
| Petkim |
| OCTAL |
| Qatar Petrochemical Company |
| Equate Petrochemical Company |
| SABIC |
| National Petrochemical Industrial Company |
| Alujain Corporation |
| PAN-ASIA SAUDI CO., LTD |
| Others |
Supply & Pricing Matrix
SASO certification tiers bifurcate GCC PET procurement into pre-certified premium streams and reformulation-delayed standard grades, with that divergence manifesting in multi-year offtake premiums for migration-tested resin and spot-market vulnerability for converters lacking backward integration into Jubail corridor feedstock.
Pricing Analysis
Certification bundling separates pre-SASO-validated resin from material requiring six-to-nine-month migration testing cycles. Three-tier pricing structure across certified-premium, standard-grade, and spot-market tiers tracks intrinsic viscosity precision and acetaldehyde threshold compliance. Cost compression in standard-grade segments intensifies because converters absorb reformulation expenses to meet tightened SASO antimony residue limits. Fragmented Omani and Kuwaiti bottlers exhibit highest price sensitivity; Saudi vertically integrated beverage groups trade flexibility for supply continuity guarantees.
Supply Chain Analysis
Freight cost differentials from Jubail to Ras Al Khaimah versus direct Qatar Petrochemical Company delivery reshape converter procurement calculus across UAE emirates. Supply concentrates in Saudi Arabia, Qatar, and UAE through integrated paraxylene and ethylene glycol corridors. Raw material dependencies center on naphtha-derived aromatics, ethylene oxide feedstock, and catalyst systems for IV control. Single-source vulnerability runs through three producers controlling over eighty percent of regional purified terephthalic acid output. Distribution runs through Gulf-wide logistics infrastructure anchored at SOHAR Port and Ras Laffan terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive feedstock access and downstream beverage cluster proximity determine margin capture. Players are pursuing upstream aromatics control as the decisive lever.
For Market Incumbents: Deepen captive ethylene glycol capacity around Jubail to offset paraxylene price volatility squeezing non-integrated converters. Expand pre-certified resin inventories to exploit SASO migration testing bottlenecks delaying competitor product launches. Chemical recycling technology licensing represents the priority capability acquisition against emerging pyrolysis-based entrants. For New Entrants and Emerging Players: Cosmetic packaging converters in Dubai and Riyadh present an underserved buyer archetype demanding optical-grade material with shorter certification cycles than beverage-grade specifications. Bottle-to-fiber chemical recycling pathways for contaminated post-consumer streams offer penetrable white-space before food-contact pyrolysis scale-up. Direct technical service partnerships with beauty product companies provide differentiated go-to-market positioning against commodity resin traders. For Investors and Strategic Acquirers: Re-rating potential sits with regional bottle-grade specialists possessing Ras Al Khaimah logistics access given MOCCAE rPET mandate acceleration across UAE beverage producers. Long-term viability over a five-to-ten year horizon favors assets with demonstrated SASO certification track records and multi-year offtake contract backlogs. The signal to watch is Qatar Petrochemical Company Ras Laffan expansion timeline announcements as inflection indicator for Gulf supply security sentiment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatics | SABIC's Jubail corridor expansion secures captive paraxylene supply against feedstock volatility. |
| Chemical Recycling Scale-Up | Pyrolysis-based depolymerization opens food-contact pathways for contaminated post-consumer PET streams. |
| Multi-Year Offtake Contracting | UAE beverage producers under MOCCAE mandates lock supply continuity through integrated producer agreements. |
| Lightweighting Technology Licensing | Sub-ten-gram preform advances combined with plasma-enhanced barrier coatings reduce per-unit resin consumption. |
| SASO Pre-Certification Investment | Early migration testing completion captures procurement preference across Riyadh and Jeddah manufacturing clusters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with PET plant managers, beverage procurement leads, downstream packaging converters, and technical R&D directors at Gulf resin producers. SASO certification databases, GCC customs harmonization frameworks, and MOCCAE circular economy policy documents provided secondary validation. Bottom-up resin consumption estimates across Saudi, UAE, and Qatar bottling clusters triangulated against top-down petrochemical capacity assessments.
Granularity-level modeling distinguished bottle-grade, packaging-grade, fiber-grade, and film-grade specifications with separate intrinsic viscosity and food-contact compliance assumptions. End-use segmentation captured beverage container, textile, electrical insulation, automotive component, and cosmetic packaging demand drivers. CAGRs derived from trend extrapolation of per-capita bottled water consumption, carbonated soft drink proliferation, and synthetic textile export momentum across the projection horizon. Feedstock cost scenarios incorporated naphtha-crude spread volatility and rPET incorporation target compliance costs.
Revisions become necessary when SASO tightens migration thresholds beyond current reformulation capabilities, when Qatar Petrochemical Company accelerates or delays Ras Laffan expansion timelines, or when MOCCAE mandates exceed certified rPET feedstock availability. Forecasts reflect documented assumptions regarding customs harmonization progress and circular economy policy convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Middle-East and Africa Fluoropolymers Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Water-Borne Epoxy Resins Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Ammonium Polyphosphate (Phase II) Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Global Polyethyleneimine Market