
 North America Super Absorbent Polymers (SAP) Market | 2026-2036
North America Super Absorbent Polymers (SAP) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Super Absorbent Polymers (SAP) Market Analytics
Market Context
EPA chemical safety standards around acrylamide residual limits is rebalancing the cost-of-entry calculus for new SAP entrants. BASF SE leverages its integrated acrylic acid supply chain to sustain margin resilience under tighter compliance thresholds. Evonik Industries AG anchors its North American position through specialized superabsorbent formulations for medical-grade applications. Nippon Shokubai Co., Ltd. competes by controlling captive production of key raw materials across its U.S. manufacturing footprint.
Technical Definition and Segment Structure
Super Absorbent Polymers are cross-linked polyacrylate networks capable of absorbing hundreds of times their dry weight in aqueous fluid, typically manufactured through inverse suspension or solution polymerization of acrylic acid neutralized with sodium hydroxide. These materials function primarily as fluid management agents in products requiring rapid uptake, gel strength, and retention under load. Disposable diapers occupies the largest volume share within product type segments, while agriculture applications represents the fastest-expanding margin pool as drought-resistant farming protocols spread across water-stressed growing regions. Granular form dominates industrial procurement channels, whereas powder formulations command premium positioning in medical and personal care applications where dissolution kinetics determine performance outcomes.
Regulatory Framework and Outlook
EPA chemical safety standards, FDA biocompatibility requirements for medical devices, and OSHA workplace exposure limits collectively shape product formulation standards and facility compliance costs across the North American SAP value chain. State-level water conservation mandates in California and Texas are accelerating agricultural sector trials of moisture-retention polymers. Stakeholders must monitor how biobased feedstock certification criteria evolve, as this will determine which producers qualify for preferential procurement contracts with sustainability-focused institutional buyers.
Market Dynamics
EPA tightening of acrylamide residual limits in SAP products is compressing margin structures and forcing producers to revalidate polymerization chemistries across their North American manufacturing footprints. This regulatory pressure is simultaneously accelerating R&D spend on alternative cross-linking agents while advantaging incumbents with captive analytical testing infrastructure.
Growth Catalysts
- Precision agriculture protocols:Moisture-retention SAP formulations are penetrating the U.S. Midwest agricultural belt as drought-resistant farming expands across water-stressed growing regions in California and Texas.
- OSHA workplace exposure limits:Stricter enforcement of monomer handling standards is driving facility upgrades that improve product consistency and reduce batch rejection rates.
- Biobased feedstock certification:USDA BioPreferred program criteria are opening preferential procurement channels with sustainability-focused institutional buyers in the personal care sector.
Market Restraints
- Acrylic acid supply concentration:Input cost volatility tracks crude oil derivatives and refinery output decisions concentrated along the U.S. Gulf Coast petrochemical corridor.
- Solution polymerization energy intensity:Thermal requirements for neutralization and drying stages expose producers to natural gas price swings and carbon accounting pressures.
- Medical-grade biocompatibility timelines:FDA device master file reviews for SAP-containing wound care products extend commercialization cycles by 18-36 months versus standard personal care applications.
Strategic Opportunities
- Texas state water conservation mandates:Agricultural trials of subsurface moisture-retention polymers are expanding beyond California into the Southern Plains cotton and grain sectors.
- Medical device convergence:Advanced wound care and ostomy applications are absorbing specialized SAP formulations with antimicrobial loading and controlled-release kinetics.
- Direct polymer procurement:Large-scale diaper manufacturers are bypassing distributors to negotiate long-term offtake agreements with integrated acrylic acid producers.
Industry Challenges
- Cross-link density optimization:Balancing absorption capacity against gel strength under load requires specialized polymer chemistry expertise that commands premium compensation in tight labor markets.
- Residual monomer testing capacity:EPA method validation for acrylamide detection at sub-ppm thresholds is creating bottlenecks at third-party analytical laboratories serving mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Super Absorbent Polymers (SAP) Market |
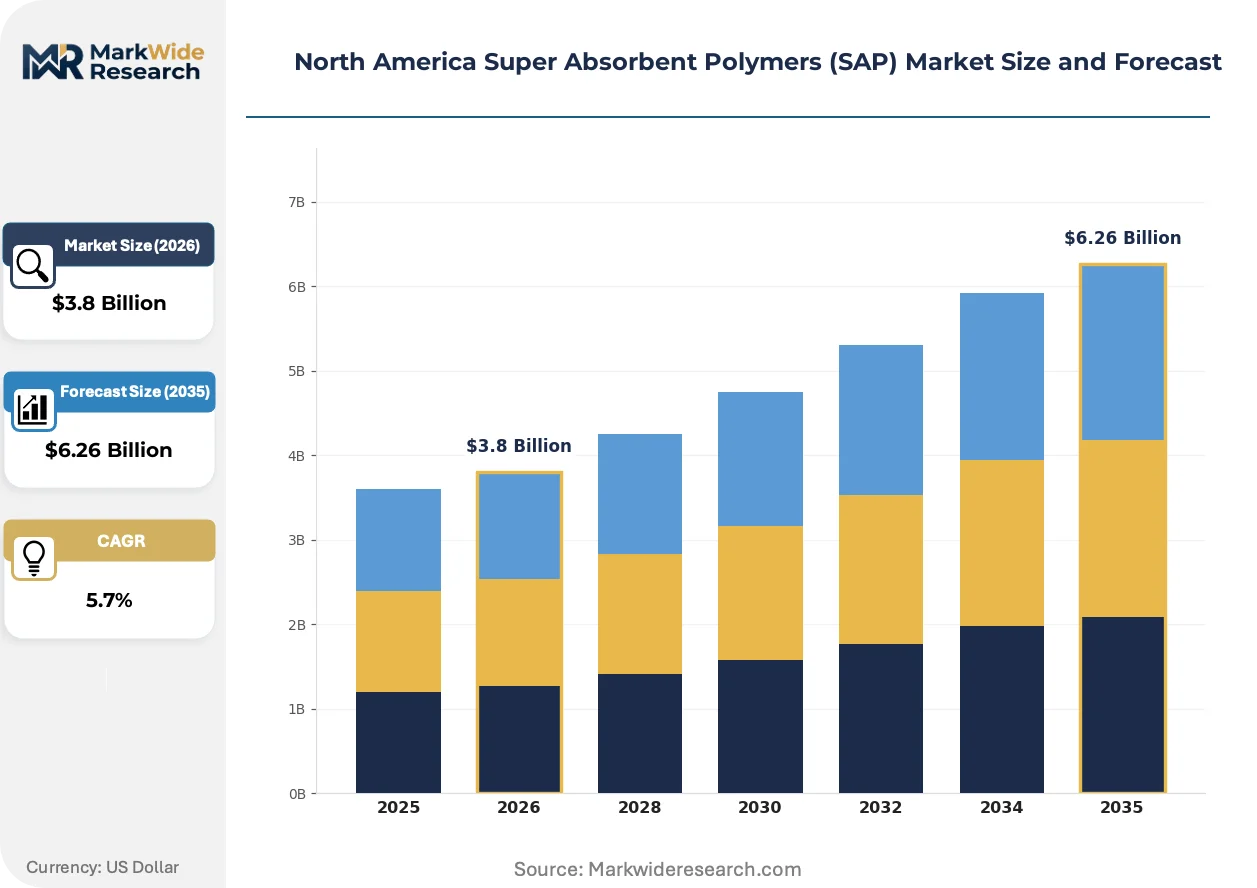
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Diapers, Adult Incontinence Products, Feminine Hygiene Products, Agriculture Applications End User: Households, Healthcare Institutions, Agricultural Sector, Manufacturers Application: Personal Care, Medical, Agriculture, Industrial Form: Granular, Powder, Beads, Sheets |
| Companies Covered | BASF SE, Evonik Industries AG, Kao Corporation, Nippon Shokubai Co., Ltd., Sumitomo Seika Chemicals Co., Ltd., LG Chem, Wanhua Chemical Group Co., Ltd., ADM, Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Super Absorbent Polymers (SAP) Market Evolving Landscape
Polymerization process intensification and feedstock diversification are converging to reshape competitive advantage in North American SAP manufacturing. Producers are racing to decouple performance specifications from petroleum-derived inputs while maintaining cost parity with established supply chains.
Surface-crosslinked granular SAP is absorbing fluid under mechanical pressure with improved retention characteristics compared to conventional homogeneous networks. Diaper manufacturers in the U.S. and Canada are adopting these structures for next-generation ultrathin core designs. The technology is absorbing market share from first-generation powder formulations in premium product tiers where leakage performance determines brand loyalty.
EPA chemical safety standards for acrylamide residuals are forcing reformulation of neutralization catalysts and post-treatment washing protocols. Facilities in Louisiana and Texas are retrofitting polymerization lines with closed-loop solvent recovery systems to meet tightened discharge limits. Agricultural-grade SAP producers face the steepest compliance cost escalation as their lower-margin product lines cannot absorb the same per-ton regulatory overhead as medical-grade specialties.
Contract manufacturing arrangements are fragmenting as large personal care brands internalize polymer specification development and quality auditing functions. Mid-sized producers in the U.S. Midwest are losing volume to integrated suppliers with dedicated technical service teams embedded at buyer R&D facilities. This shift is most visible in the disposable hygiene sector where Procter & Gamble and Kimberly-Clark have consolidated supplier panels to three preferred partners with regional manufacturing redundancy.
North America Super Absorbent Polymers (SAP) Market Segmentation
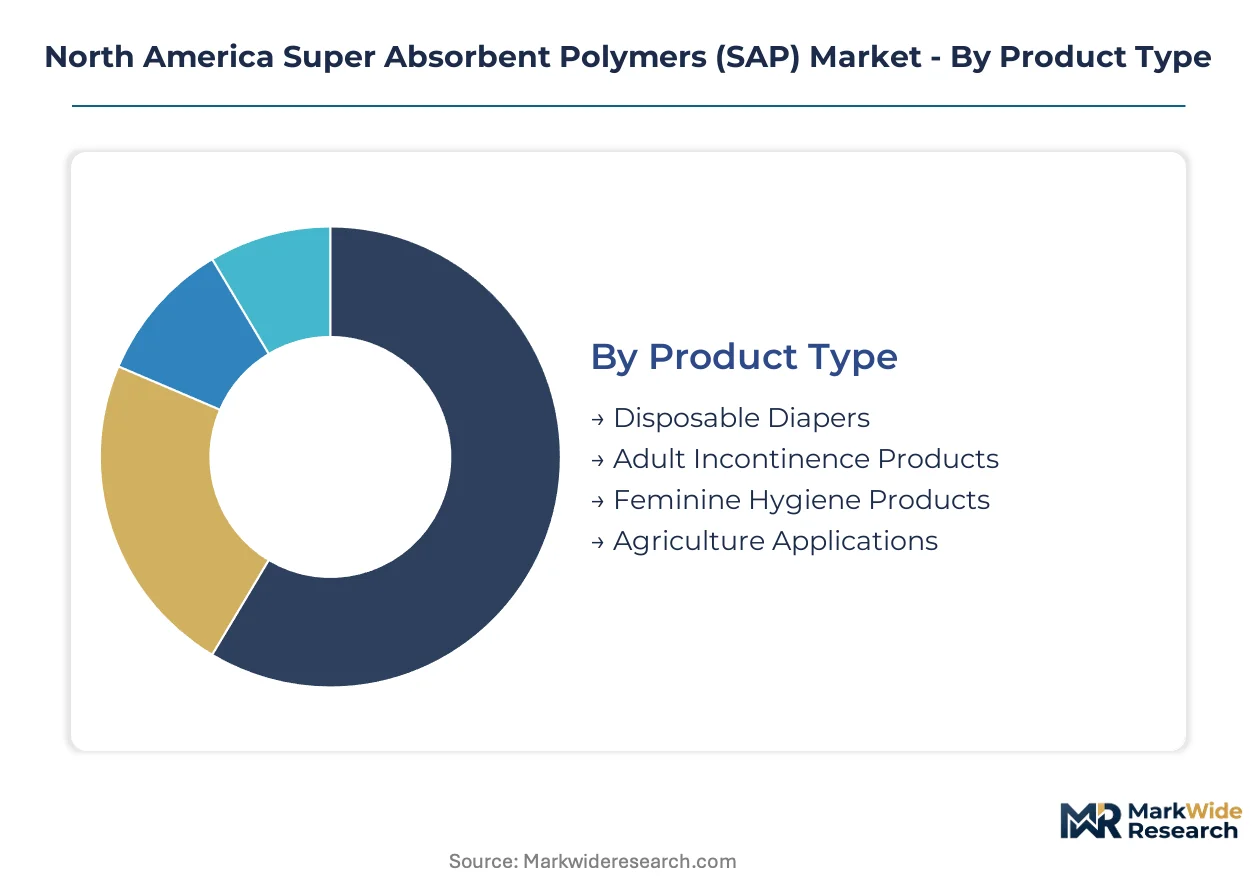
Super Absorbent Polymers function across radically different performance environments, from the controlled chemistry of medical devices to the variable field conditions of agricultural deployment. Each segment demands distinct polymerization protocols, purity standards, and supply chain configurations that reshape how producers allocate technical resources and capital.
Product Type:
Upgrade cycles in absorbent hygiene products are accelerating as EPA acrylamide limits force reformulation of legacy polymer architectures across North American manufacturing lines.
- Disposable Diapers:Surface-crosslinked granular structures dominate ultrathin core designs, with fluid retention under mechanical load determining brand switching behavior among U.S. and Canadian parents. Procter & Gamble and Kimberly-Clark procurement teams are consolidating supplier panels to three preferred partners with regional manufacturing redundancy.
- Agriculture Applications:Moisture-retention formulations penetrate the U.S. Midwest agricultural belt and California's Central Valley as drought-resistant farming protocols expand. State-level water conservation mandates in Texas are accelerating trials beyond traditional irrigation-intensive crops into Southern Plains cotton and grain sectors.
- Adult Incontinence Products:Higher absorbency requirements per unit drive specialized gel strength specifications for institutional procurement channels serving aging demographics.
- Feminine Hygiene Products:Premium tier formulations emphasize dissolution kinetics and skin-contact biocompatibility under FDA cosmetic safety guidelines.
Disposable Diapers sits at the top of the volume ranking, with Agriculture Applications climbing the fastest.
End User:
Procurement authority is shifting from distributors toward direct technical partnerships, fragmenting traditional volume-based contracting structures.
- Manufacturers:Large-scale diaper and hygiene product makers bypass distributors to negotiate long-term offtake agreements with integrated acrylic acid producers. BASF SE and Nippon Shokubai Co., Ltd. embed technical service teams at buyer R&D facilities to co-develop next-generation core specifications.
- Agricultural Sector:Precision farming adopters in the U.S. Midwest specify SAP loading rates and degradation profiles for subsurface moisture retention systems. USDA BioPreferred program criteria open preferential procurement channels for biobased-certified formulations.
- Healthcare Institutions:Hospital procurement committees demand FDA device master file documentation for wound care and ostomy applications, extending vendor qualification timelines.
- Households:Retail channel demand concentrates in mass-market diaper and feminine hygiene segments where price elasticity shapes brand loyalty.
Manufacturers commands the largest contract value concentration, while Agricultural Sector procurement expands most quickly.
Application:
Regulatory jurisdiction determines formulation complexity, with medical applications facing the steepest compliance cost escalation relative to commodity personal care volumes.
- Personal Care:Diaper and hygiene manufacturers drive granular SAP consumption through ultrathin core designs requiring surface-crosslinked architectures for improved fluid retention under load.
- Medical:Advanced wound care and ostomy applications absorb specialized formulations with antimicrobial loading and controlled-release kinetics. FDA biocompatibility requirements extend commercialization cycles substantially versus standard personal care approvals.
- Agriculture:Moisture-retention polymers penetrate water-stressed growing regions as California and Texas state mandates accelerate adoption.
- Industrial:Cable filling and construction applications utilize lower-purity grades where gel strength specifications relax relative to hygiene and medical tiers.
Personal Care generates the dominant volume share, with Medical applications carrying the steepest margin expansion trajectory.
Form:
Physical morphology dictates dissolution kinetics and mechanical handling properties, creating distinct procurement channels for industrial versus precision applications.
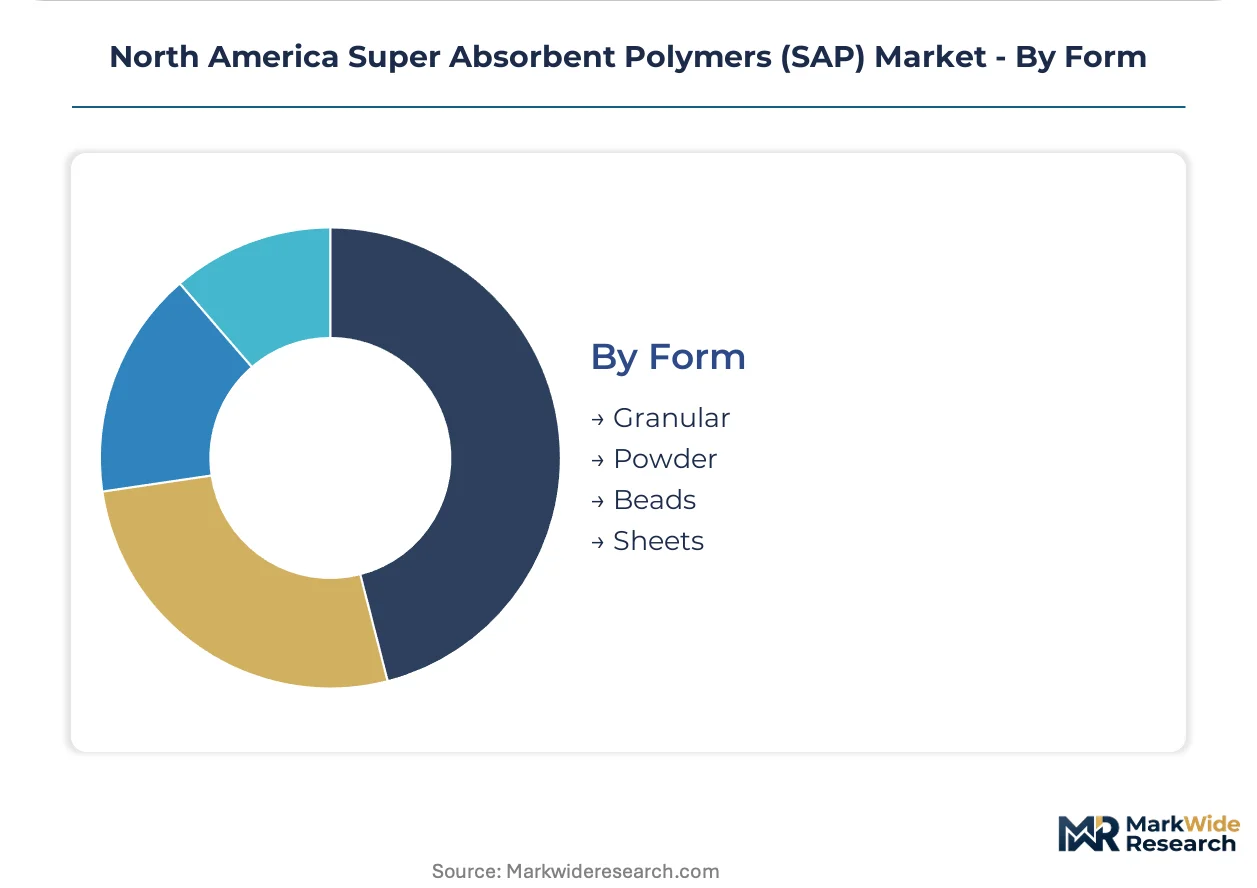
- Granular:Dominates industrial procurement channels for disposable diapers and agricultural moisture retention, with particle size distribution determining flow characteristics in automated manufacturing lines.
- Powder:Commands premium positioning in medical and personal care applications where rapid dissolution kinetics determine performance outcomes and FDA biocompatibility standards apply.
- Beads:Specialized controlled-release applications in agricultural and medical sectors where gradual fluid absorption profiles match specific use-case requirements.
- Sheets:Pre-formed configurations for wound dressing and ostomy appliance manufacturers seeking reduced handling complexity at point of assembly.
Granular form leads absolute volume, with Powder formulations gaining share fastest in premium medical and personal care tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemists and process engineers concentrate along the U.S. Gulf Coast petrochemical corridor and the Midwest manufacturing belt, anchoring North American SAP production capacity.
United States
Precision farming adoption in the Midwest agricultural belt drives specialty SAP formulations for moisture retention under variable irrigation conditions. EPA tightening of acrylamide residual limits forces Louisiana and Texas facilities to retrofit polymerization lines with closed-loop solvent recovery systems. The Gulf Coast petrochemical corridor hosts integrated acrylic acid production that supplies neutralization feedstock for regional SAP manufacturing.
Canada
Personal care manufacturers in Ontario and Quebec expand SAP procurement as Health Canada aligns chemical safety standards with EPA acrylamide thresholds. The country's national pharmaceutical regulator maintains biocompatibility requirements for medical-grade SAP applications that parallel FDA device master file protocols. Greater Toronto Area technical service teams embed with buyer R&D facilities to co-develop next-generation absorbent core specifications.
Mexico
Diaper assembly operations in Nuevo León and Jalisco pull granular SAP through cross-border supply chains serving U.S. consumer goods distributors. Mexico's federal environmental regulator enforces discharge limits that accelerate facility upgrades among contract manufacturers serving North American hygiene brands. The Bajío Region automotive corridor generates secondary demand for industrial-grade SAP in cable filling and sealing applications.
North America Super Absorbent Polymers (SAP) Market Competitive Landscape
The competitive structure tilts toward integrated petrochemical conglomerates with captive acrylic acid supply. Three to four multinational chemical groups control the majority of North American manufacturing capacity through wholly-owned subsidiaries and joint ventures. Strategic archetypes separate into upstream-integrated resin producers, specialized medical-grade formulators, and regional distribution-focused compounders. Dominant competitive moves include backward integration into acrylic acid production and long-term offtake agreements with absorbent hygiene manufacturers.
Within the integrated chemical conglomerate tier, BASF SE and Nippon Shokubai Co., Ltd. exemplify producers with in-house control over key raw material streams. Evonik Industries AG occupies a position among specialized formulators targeting medical-grade applications with differentiated biocompatibility profiles. These three entities represent the core competitive anchors shaping procurement dynamics across personal care, agricultural, and healthcare end-use segments.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Kao Corporation |
| Nippon Shokubai Co., Ltd. |
| Sumitomo Seika Chemicals Co., Ltd. |
| LG Chem |
| Wanhua Chemical Group Co., Ltd. |
| ADM |
| Formosa Plastics Corporation |
| Others |
Value Network & Pricing Analysis
Integrated petrochemical conglomerates with captive acrylic acid production anchor North American SAP manufacturing, translating upstream control into pricing discipline that mid-tier compounders cannot match. Their ownership of neutralization feedstock insulates margin structures from Gulf Coast refinery volatility while forcing price compression on distributors lacking equivalent backward integration.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between large diaper manufacturers and integrated resin producers, unbundling technical service from base polymer pricing. Price differentiation separates medical-grade FDA device master file tiers from agricultural commodity grades, with certification investment and volume scale as primary drivers. Cost compression in agricultural-grade tiers is intensifying because EPA acrylamide compliance overhead cannot absorb across lower-margin product lines. Mass-market diaper assemblers exhibit highest price sensitivity, while advanced wound care formulators prioritize biocompatibility over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Procter & Gamble and Kimberly-Clark procurement teams mandate multi-supplier qualification across at least three preferred partners with regional manufacturing redundancy. Acrylic acid feedstock concentrates in the United States along the Gulf Coast petrochemical corridor, with sodium hydroxide neutralization agents and cross-linking chemical additives as critical dependencies. Single-source vulnerability in analytical testing capacity for sub-ppm acrylamide detection creates bottlenecks at third-party laboratories. Distribution runs through direct technical partnerships that disintermediate traditional volume-based distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America SAP market functions as a stable compounder, with EPA regulatory tightening on acrylamide residuals driving steady replacement demand for reformulated polymer architectures.
For Market Incumbents: Deepen captive analytical testing infrastructure to accelerate batch validation cycles while competitors face third-party laboratory queues. Expand technical service team embedding at buyer R&D facilities to defend against direct polymer procurement bypassing traditional distribution channels. Cross-link density optimization expertise commands premium compensation in tight labor markets, creating defensive moats against emerging specialty formulators. For New Entrants and Emerging Players: Biobased feedstock certification under USDA BioPreferred criteria offers a technology-first wedge for sustainability-focused institutional procurement in personal care. Target agricultural moisture-retention trials in Texas Southern Plains cotton and grain sectors, where state water conservation mandates accelerate adoption faster than saturated Midwest markets. Lead with controlled-release kinetics expertise for antimicrobial-loaded wound care formulations to bypass FDA device master file timeline disadvantages in standard applications. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized U.S. Midwest producers losing volume to integrated suppliers with dedicated technical service teams. The five-to-ten-year viability window favors acquisition of regional compounders with established agricultural distribution relationships and retrofit-ready polymerization lines. Watch biobased feedstock certification criteria evolution as the inflection indicator determining which producers qualify for preferential procurement contracts with sustainability-focused buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | BASF SE and Nippon Shokubai Co., Ltd. neutralize Gulf Coast feedstock volatility through captive supply. |
| Closed-Loop Solvent Recovery Retrofit | Louisiana and Texas facilities meet EPA discharge limits while reducing batch rejection rates. |
| Medical-Grade Biocompatibility Certification | Evonik Industries AG extends FDA device master file documentation for wound care applications. |
| Precision Agriculture Technical Partnership | Midwest producers embed with USDA BioPreferred-certified buyers for drought-resistant farming protocols. |
| Supplier Panel Consolidation | Procter & Gamble and Kimberly-Clark reduce preferred partners to three with regional manufacturing redundancy. |
Research Methodology
Bottom-up absorbent hygiene and agricultural application modeling reconciled against top-down acrylic acid production tracking forms the analytical core of this study. Primary interviews with polymerization plant managers, procurement leads at diaper manufacturers, distribution channel partners, and technical R&D directors combined with secondary validation from EPA chemical safety filings, U.S. customs trade data, ACC industry reports, and SEC 10-K disclosures. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity across product type, end user, application, and physical form dimensions.
Historical trendline analysis of surface-crosslinked granular adoption rates and biobased certification penetration established baseline growth patterns across the projection horizon. The analytical framework models personal care grade tier, agricultural end-use industry, medical certification status, and regional production hub as primary segmentation dimensions. CAGRs derive from elasticity-adjusted demand curves incorporating precision farming adoption rates, EPA compliance cost pass-through assumptions, and medical device commercialization cycle timelines.
The model holds under stable EPA acrylamide enforcement intensity and continued acrylic acid supply from Gulf Coast petrochemical corridors; deviation in federal environmental regulatory stringency or refinery output decisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Green Polyols Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Global Ultra-High Molecular Weight Polyethylene Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Agar Resin Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market