
 Acrylonitrile Styrene Acrylate (ASA) Market | 2026-2036
Acrylonitrile Styrene Acrylate (ASA) Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylonitrile Styrene Acrylate (ASA) Market Outlook
Polycarbonate is pivoting toward ASA blends in automotive exterior applications where UV stability and cost efficiency outweigh pure PC performance. INEOS Styrolution leverages its European styrenics platform to supply color-stable grades for premium vehicle programs. Chi Mei Corporation anchors the Asia-Pacific supply base through its integrated acrylonitrile and rubber production in Taiwan. Kumho Petrochemical dominates Korean automotive OEM channels with specialized high-gloss formulations.
Acrylonitrile styrene acrylate is a terpolymer synthesized from acrylonitrile, styrene, and acrylic ester rubber, typically containing 15-30% acrylate content to confer exceptional weathering resistance and thermal stability up to 85°C continuous service temperature. The material serves primarily as a durable engineering thermoplastic for outdoor applications requiring long-term color retention and mechanical integrity without painting or coating. Injection molding occupies the largest volume share among product types due to its prevalence in complex automotive parts and consumer housings, while extrusion represents the fastest-expanding process segment driven by building profiles and sheet applications. Automotive parts command the dominant application position, though electrical components are gaining structural importance as outdoor enclosure standards tighten.
The US EPA and NHTSA coordinate material flammability and durability standards that ASA must satisfy for automotive interior and exterior deployment, while REACH and RoHS frameworks in Europe restrict hazardous additive packages and mandate recyclability disclosures for polymer compounds. China's SAMR enforces GB standards for plastic weathering performance that directly determine market access for imported and domestic ASA grades. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation fragmentation that would multiply compliance costs across supply chains.
Market Dynamics
Automotive OEMs are consolidating exterior material specifications around weather-resistant polymers that eliminate secondary painting operations, compressing supply chains and elevating certification barriers for compounders.
Growth Catalysts
- REACH and RoHS frameworks:European hazardous substance restrictions are accelerating substitution of PVC and painted ABS in outdoor applications, channeling volume toward ASA's additive-compliant formulations.
- Building-integrated photovoltaics:Solar module frame manufacturers are specifying ASA for junction box housings and mounting profiles requiring decades of UV exposure without degradation.
- Yangtze River Delta concentration:China's integrated petrochemical cluster enables just-in-time delivery to Asia-Pacific automotive assembly plants, reducing working capital requirements for Tier 1 suppliers.
Market Restraints
- Acrylonitrile feedstock volatility:Propylene-ammonia oxidation route exposure ties compounder margins to olefin cracking economics and regional refinery utilization rates.
- Taiwanese rubber supply concentration:Acrylic ester elastomer production clusters create single-source vulnerability for weatherable grade manufacturers outside integrated producers.
- Polycarbonate-ASA blend performance ceiling:Heat distortion temperature limitations below 95°C restrict under-hood applications where polyamide and PBT compounds dominate.
Strategic Opportunities
- India's BIS polymer certification expansion:Mandatory IS 15495 testing for outdoor electrical enclosures creates first-mover advantage for pre-certified compounders entering infrastructure projects.
- Recycled content mandates:EU Green Deal packaging regulations are forcing post-consumer ASA stream development for non-automotive durables.
- Laser direct structuring convergence:Antenna-integrated automotive mirror housings combine metallization-grade ASA with 5G frequency requirements, opening device-grade pricing tiers.
Industry Challenges
- Color matching across polymer batches:Pigment dispersion consistency for metallic and pearlescent automotive finishes demands spectrophotometric validation extending lead times.
- Multi-jurisdiction certification stacking:Simultaneous EPA, REACH, and GB standard compliance requires parallel testing protocols that fragment R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylonitrile Styrene Acrylate (ASA) Market |
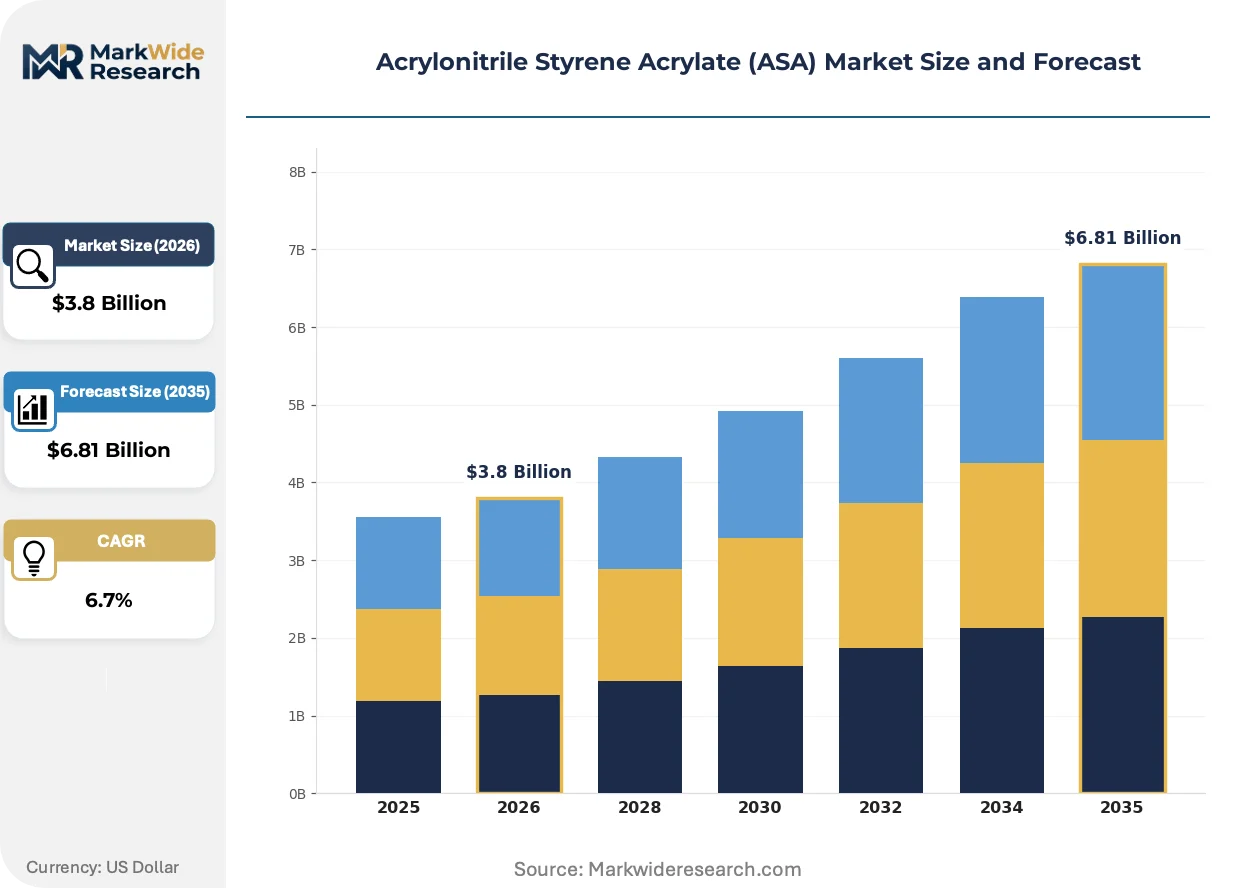
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Blow Molding, Extrusion, Thermoforming Application: Automotive Parts, Consumer Goods, Electrical Components, Industrial Equipment End User: Manufacturers, OEMs, Retailers, Construction Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | LG Chem, INEOS Styrolution, SABIC, Chi Mei Corporation, BASF SE, Formosa Plastics Corporation, Kumho Petrochemical, Mitsubishi Chemical Corporation, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylonitrile Styrene Acrylate (ASA) Market Strategic Shifts
Material science advances are collapsing the performance gap between commodity engineering plastics and specialized weatherable compounds, while regulatory pressure on lifecycle emissions is reshaping formulation priorities across automotive and construction verticals.
Multi-layer coextrusion technology is integrating ASA cap layers over ABS substrates in automotive body panels, delivering surface weatherability without full material substitution. Tier 1 suppliers in Germany and Japan are qualifying these hybrid structures for bumper fascias and mirror housings, reducing material costs while preserving Class A surface requirements. This architecture is compressing demand for solid ASA in non-critical cosmetic areas.
China's evolving GB standards for plastic weathering performance are mandating accelerated UV exposure testing protocols that exceed historical OEM specifications. SAMR enforcement of these protocols is disqualifying uncertified import grades and forcing reformulation of legacy products for the domestic market. Automotive exterior compounders are responding by establishing captive testing facilities in Shanghai and Tianjin.
Specification consolidation among European automotive OEMs is compressing approved material lists and elevating recyclability disclosures under CSRD supply chain requirements. Buyers are consolidating purchase volumes with compounders offering cradle-to-gate carbon accounting and mechanically recycled feedstock options. This preference shift is most visible in German premium vehicle programs where EPD certification now gates supplier qualification.
Acrylonitrile Styrene Acrylate (ASA) Market Segmentation
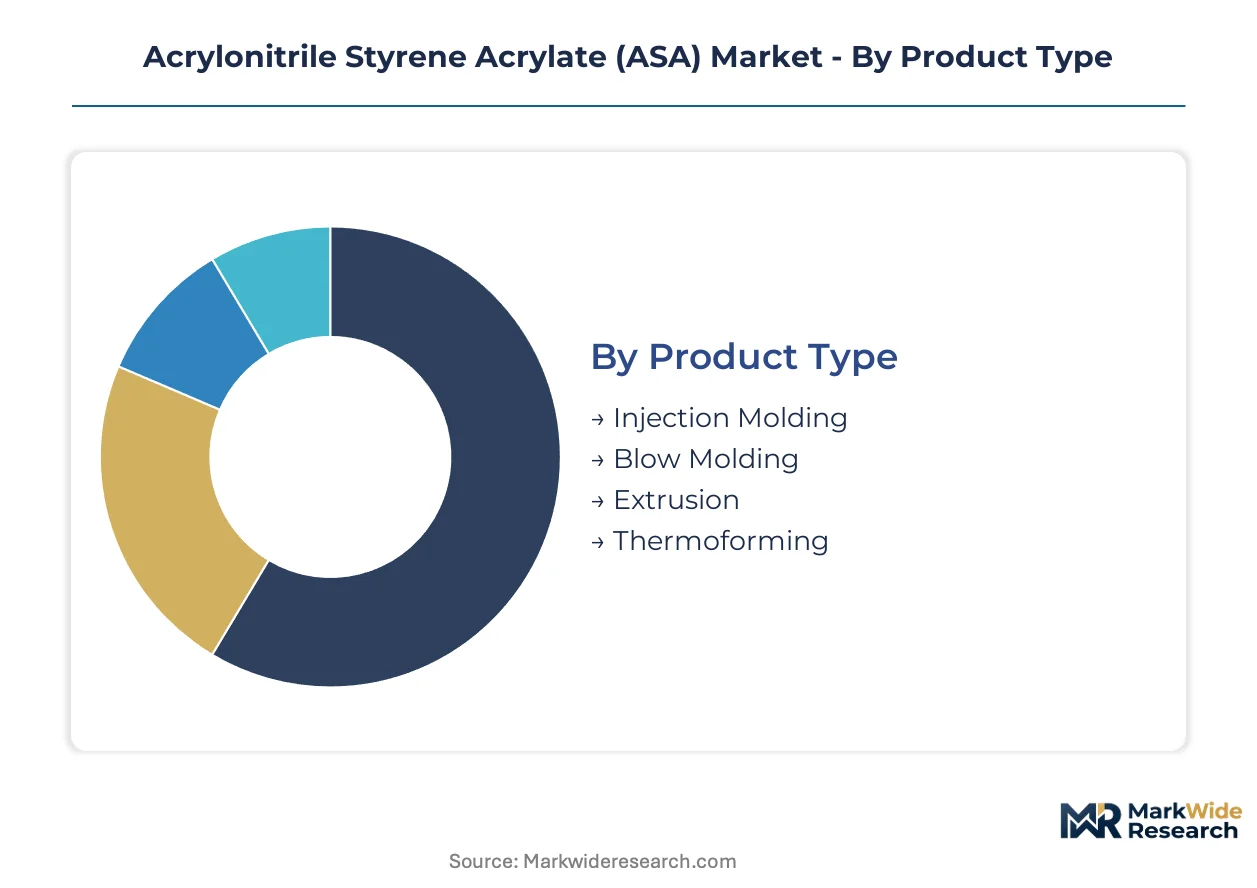
ASA market segmentation reveals how processing constraints and end-use durability requirements fragment demand across distinct technical specifications and supply chain configurations. Compounders must align formulation portfolios with the specific thermal, aesthetic, and regulatory demands of each segment to capture volume.
Product Type:
Customization intensity varies sharply across this category, with high-volume automotive programs demanding tailored melt flow indices while construction applications tolerate broader specification bands.
- Injection Molding:Dominant volume position serving complex automotive exterior components requiring tight dimensional tolerance and Class A surface finish. China's Yangtze River Delta automotive cluster concentrates demand for high-flow grades that reduce cycle times in bumper fascia production.
- Extrusion:Fastest-expanding process segment driven by building profile and solar module frame applications requiring continuous UV resistance without secondary coating. European building-integrated photovoltaics manufacturers are qualifying cap-layer formulations for decades of weather exposure.
- Blow Molding:Hollow part production for outdoor lighting enclosures and recreational vehicle components where impact resistance combines with hollow-wall structural efficiency.
- Thermoforming:Sheet-based processing for shallow-draw architectural panels and spa equipment housings where material thickness uniformity governs optical performance.
Leading the category by volume: Injection Molding. Expanding most quickly: Extrusion.
Application:
Margin structures across applications diverge based on certification burden and replacement cycle length, with automotive exterior parts commanding premium pricing against commoditized consumer durables.
- Automotive Parts:Weather-resistant body panels, mirror housings, and trim components that eliminate secondary painting through integral color stability. German premium OEMs are consolidating approved supplier lists around compounders offering cradle-to-gate carbon accounting under CSRD requirements.
- Electrical Components:Outdoor enclosure applications for junction boxes, meter housings, and solar mounting hardware where GB standard weathering certification gates market access in China. India's BIS IS 15495 testing mandate is creating qualification barriers for uncertified imports.
- Consumer Goods:Garden furniture, recreational equipment, and appliance housings where cost efficiency outweighs extended service life requirements.
- Industrial Equipment:Machinery guards and outdoor instrumentation housings requiring chemical resistance alongside UV stability.
Highest certification burden: Automotive Parts. Steepest expansion trajectory: Electrical Components.
End User:
Procurement sophistication separates this category, with integrated OEMs conducting resin qualification in-house while construction firms rely on distributor technical support.
- OEMs:Direct material specification authority in automotive and appliance manufacturing, conducting accelerated weathering testing that exceeds regulatory minimums. Tier 1 suppliers in Germany and Japan are establishing captive testing facilities to compress qualification timelines.
- Manufacturers:Compounders and converters serving multiple downstream sectors, balancing inventory flexibility against batch consistency requirements for metallic automotive finishes.
- Construction Firms:Project-based procurement of profiles and sheets through distributor networks with limited technical specification involvement.
- Retailers:Private-label garden furniture and recreational product sourcing where price positioning dominates material selection.
Deepest technical integration: OEMs. Fastest procurement digitization: Manufacturers.
Distribution Channel:
Channel selection tracks order scale and formulation complexity, with direct relationships governing automotive volume and digital platforms penetrating standard grades.
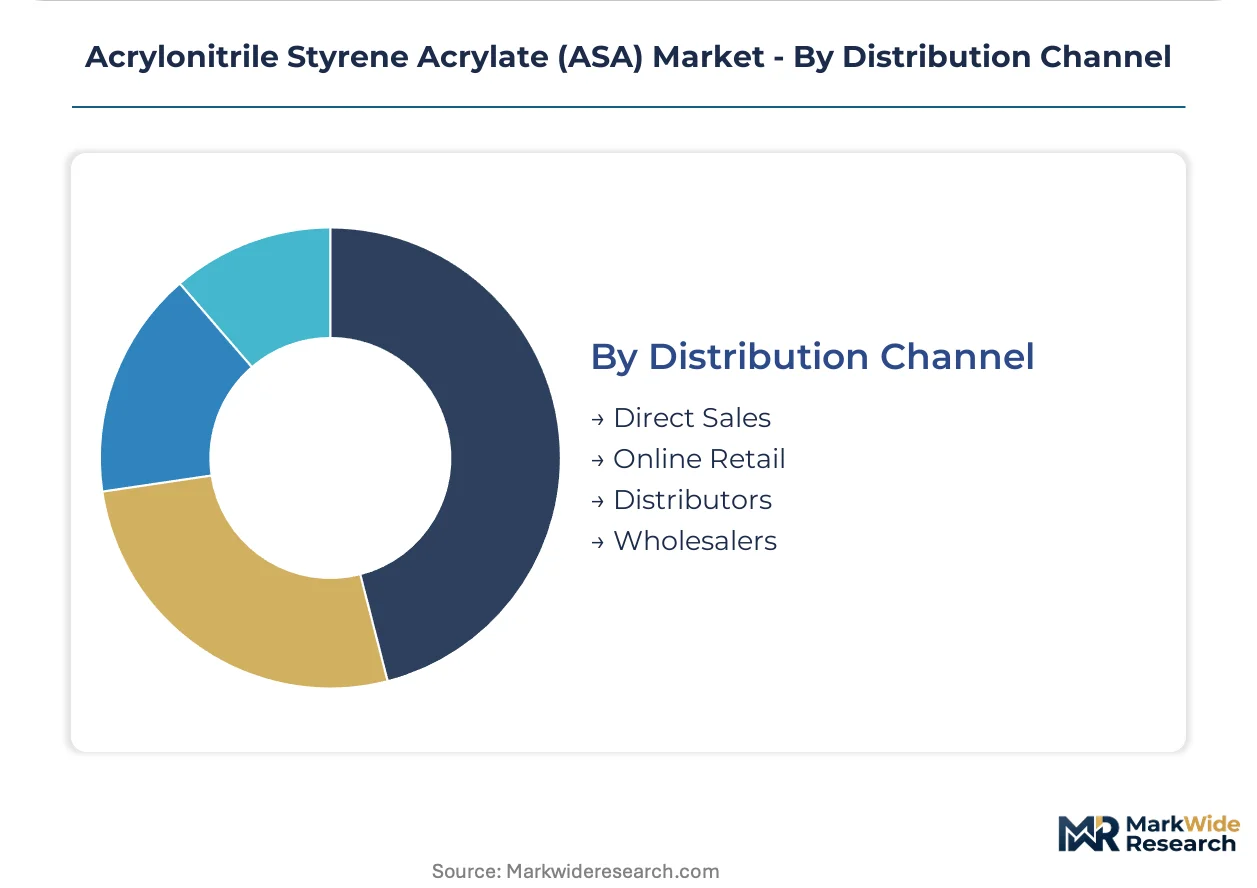
- Direct Sales:Dedicated account management for automotive OEMs and major appliance manufacturers requiring lot traceability and spectrophotometric color matching validation. INEOS Styrolution and Chi Mei Corporation maintain technical service teams at customer formulation labs.
- Distributors:Regional inventory positioning for construction and industrial customers requiring just-in-time delivery of standard grades. Yangtze River Delta concentration enables same-day fulfillment to Asia-Pacific automotive assembly plants.
- Online Retail:Emerging channel for small-batch custom colors and rapid prototyping materials serving product development teams.
- Wholesalers:Volume aggregation for commodity grades in consumer goods and general industrial applications with limited technical service requirements.
Dominant by volume: Direct Sales. Gaining share fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany and China are consolidating exterior material specifications around weather-resistant polymers, compressing supply chains and elevating certification barriers for compounders serving premium vehicle programs.
China
Yangtze River Delta petrochemical clusters anchor Asia-Pacific supply, with integrated ABS-ASA producers serving just-in-time automotive assembly plants. SAMR enforcement of evolving GB standards for plastic weathering performance is disqualifying uncertified import grades. Shanghai and Tianjin host captive testing facilities established by compounders to compress qualification timelines for domestic OEMs.
Germany
Premium automotive manufacturers specify color-stable ASA grades for mirror housings and bumper fascias requiring Class A surface finishes. ECHA REACH frameworks restrict hazardous additive packages and mandate recyclability disclosures for polymer compounds. Bavaria and Baden-Württemberg concentrate Tier 1 supplier technical service teams supporting cradle-to-gate carbon accounting under CSRD requirements.
United States
Building-integrated photovoltaics manufacturers specify ASA for solar module frames and junction box housings requiring decades of UV exposure. EPA and NHTSA coordinate material flammability and durability standards governing automotive interior and exterior deployment. Michigan and Ohio automotive corridors concentrate demand for high-flow injection molding grades reducing cycle times in bumper production.
South Korea
Domestic automotive OEM channels drive specialized high-gloss formulation requirements for exterior trim components. MFDS polymer safety protocols align with international standards while maintaining distinct testing protocols for electrical enclosure applications. Ulsan and Busan petrochemical complexes enable integrated acrylonitrile supply chains serving captive rubber production for weatherable grades.
India
Infrastructure project growth is creating demand for outdoor electrical enclosures requiring BIS IS 15495 certification. Maharashtra and Gujarat industrial corridors concentrate compounder facilities pre-qualifying materials for government tender participation. Mumbai and Ahmedabad host technical centers supporting spectrophotometric color matching for metallic automotive finishes.
Acrylonitrile Styrene Acrylate (ASA) Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical producers dominating high-volume automotive programs while independent compounders capture specialty electrical enclosure applications. The market structure tilts toward consolidation among acrylonitrile-integrated producers controlling feedstock costs, though regional formulation specialists maintain positions in color-matched automotive grades. Three archetypes define competitive positioning: integrated petrochemical conglomerates with captive rubber supply, European styrenics specialists leveraging color stability expertise, and Asia-Pacific producers exploiting Yangtze River Delta logistics concentration. Capacity expansion in acrylic ester elastomer production and strategic partnerships for recycled content development represent dominant competitive vectors.
Within the integrated petrochemical tier, LG Chem and SABIC exemplify producers with backward control over acrylonitrile and rubber supply chains. Chi Mei Corporation anchors the Taiwan-based specialist position through integrated production architecture. INEOS Styrolution occupies the European branded compounder position serving premium automotive programs with technical service capabilities.
| Leading Market Players |
|---|
| LG Chem |
| INEOS Styrolution |
| SABIC |
| Chi Mei Corporation |
| BASF SE |
| Formosa Plastics Corporation |
| Kumho Petrochemical |
| Mitsubishi Chemical Corporation |
| Toray Industries |
| Others |
Value Chain & Pricing Dynamics
Backward integration into acrylonitrile and acrylic ester rubber production anchors pricing power for compounders serving automotive OEMs, insulating integrated producers from propylene-ammonia oxidation route volatility while forcing non-integrated competitors to absorb margin compression during olefin cracking downturns. Chi Mei Corporation and LG Chem leverage captive feedstock supply to maintain cost position against spot-market-dependent compounders in color-matched automotive grades.
Pricing Analysis
High-volume injection molding grades for bumper fascias trade on thin margins against specialized electrical enclosure formulations commanding premium certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates automotive Class A surface specifications from construction profile commodity grades. Cost compression in standard grades is intensifying because Yangtze River Delta producers are expanding extrusion capacity for solar module frames. Construction firms exhibit highest price sensitivity, while German premium OEMs prioritize color stability over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for weatherable grades, forcing compounders to maintain redundant production certifications across Taiwan, South Korea, and China. Acrylic ester elastomer supply draws from concentrated Taiwanese rubber production clusters, creating single-source vulnerability for weatherable grade manufacturers outside integrated producers. Tariff exposure on acrylonitrile imports threatens European compounders without backward integration. Distribution runs through direct technical service relationships for automotive volume, with regional distributors handling construction and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH and RoHS frameworks construct a cost-of-compliance moat that rewards pre-certified compounders while disqualifying reformulation-lagged competitors from European automotive programs. SAMR enforcement of evolving GB standards for plastic weathering performance replicates this barrier architecture in China.
For Market Incumbents: Hedge acrylonitrile feedstock exposure through long-term offtake agreements with Yangtze River Delta petrochemical complexes. Defend automotive supplier position by establishing captive testing facilities in Shanghai and Tianjin to compress GB standard qualification timelines. Expand capacity in acrylic ester rubber production to eliminate Taiwanese supply concentration risk.
For New Entrants and Emerging Players: The 40-60% price-point gap between premium automotive grades and economy construction profiles opens white-space targeting for mid-tier electrical enclosure compounders. India's BIS IS 15495 certification mandate creates penetrable infrastructure demand with lower incumbent saturation than German automotive channels. Enter through pre-certification investment ahead of government tender cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in integrated petrochemical conglomerates seeking color-matching formulation capabilities. Long-term viability favors producers with backward acrylonitrile control and demonstrated SAMR testing compliance. Watch for MFDS polymer safety protocol alignment with international standards as signal for Korean market consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Captive propylene-ammonia oxidation supply eliminates feedstock margin volatility for automotive compounders. |
| GB Standard Testing Facility Establishment | Shanghai-based captive qualification compresses SAMR compliance timelines for China automotive programs. |
| Recycled Content Stream Development | EU Green Deal packaging regulations force post-consumer ASA feedstock investment for non-automotive durables. |
| Laser Direct Structuring Grade Qualification | Antenna-integrated mirror housings combine metallization-grade ASA with 5G frequency device pricing tiers. |
| Acrylic Ester Rubber Capacity Expansion | Taiwanese supply concentration vulnerability drives captive elastomer production for weatherable grade security. |
Study Parameters
Document review covered customs and trade flow databases, SEC 10-K filings from petrochemical conglomerates, and SAMR regulatory bulletins, complemented by interviews with plant managers at integrated ABS-ASA producers, procurement leads at German Tier 1 automotive suppliers, and technical R&D directors at electrical enclosure compounders. Bottom-up demand modeling from injection molding and extrusion process segments was cross-validated against top-down petrochemical capacity analysis.
Segment-level volume and value trajectories across the projection horizon reflect modeled interactions between automotive exterior specification consolidation and solar module frame demand expansion. The analytical framework incorporated grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from elasticity-adjusted demand curves calibrated to acrylonitrile feedstock cost pass-through rates and GB standard compliance adoption timelines.
Underlying measurement precision varies by segment; injection molding automotive grades carry tighter precision than emerging thermoforming architectural applications due to established OEM reporting channels. Forecasts reflect assumptions regarding SAMR enforcement intensity and REACH additive restriction evolution. Deviation in acrylic ester rubber supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Long-Chain Polyamide Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market