
 Aromatic Ketone Polymer Market | 2026-2036
Aromatic Ketone Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Aromatic Ketone Polymer Market Analysis
Aerospace procurement is consolidating as a dominant demand channel for aromatic ketone polymers, displacing slower-growing industrial machinery segments. Victrex plc anchors its position through captive supply of implantable-grade polyether ether ketone to medical device manufacturers. Solvay S.A. leverages its fluoropolymer heritage to extend compounding capabilities into sulfone-modified ketone formulations. SABIC competes on manufacturing scale, operating one of the largest continuous extrusion lines for high-temperature polymer sheets in the European market.
Aromatic ketone polymers are semi-crystalline thermoplastics containing aryl-ether-ketone linkages in their backbone, typically processed via injection molding or compression molding at temperatures exceeding 350°C to achieve melt flow without thermal degradation. Their primary commercial purpose centers on metal replacement in load-bearing components subjected to continuous service temperatures above 150°C and aggressive chemical environments. Polyether ether ketone dominates value generation due to its stiffness-to-weight ratio and established qualification in FAA-regulated aircraft interiors, while polyphenylene sulfide occupies the high-volume, lower-margin tier for automotive under-hood connectors. Film and sheet forms capture disproportionate margin pools in healthcare and semiconductor fabrication equipment, whereas rod and tube forms remain concentrated in oilfield and chemical processing applications.
FDA 21 CFR 177.2415 governs food-contact applications of polyether ketone resins, while EPA TSCA Section 5 premanufacture notifications constrain introduction of novel monomer chemistries. The EU MDR tightens biocompatibility documentation for implantable grades, directly affecting Victrex and Evonik product registration cycles. Stakeholders must monitor evolving FAA flame-smoke-toxicity standards for cabin interiors, as pending amendments could disqualify incumbent formulations or accelerate qualification of next-generation sulfone-ketone copolymers.
Market Dynamics
REACH compliance deadlines and EU Green Deal mandates are compressing formulation disclosure timelines, forcing compounders to requalify supply chains before 2030 regulatory cliffs.
Growth Catalysts
- Aerospace metal replacement:FAA flame-smoke-toxicity qualification pathways for cabin interiors are accelerating polyether ether ketone adoption in structural brackets and ducting. Boeing and Airbus tier-one suppliers now specify aromatic ketone polymers for weight-critical assemblies.
- EU MDR biocompatibility mandates:The tightened documentation regime for implantable grades is locking in specialized polymer suppliers with established regulatory files, creating defensive moats around medical device procurement channels.
- Fluoropolymer compounding convergence:Sulfone-modified ketone formulations are capturing semiconductor fabrication equipment demand where aggressive chemical resistance and dimensional stability intersect.
Market Restraints
- Monomer supply concentration:Difluorobenzophenone feedstock production clusters in Chinese chemical parks, exposing European compounders to tariff volatility and dual-use export licensing friction.
- Processing temperature barriers:Melt temperatures exceeding 350°C require specialized corrosion-resistant tooling and energy-intensive thermal management, constraining small-batch contract manufacturers.
- Polyphenylene sulfide substitution:Lower-cost sulfide polymers are capturing automotive under-hood connector volumes where continuous service temperatures remain below 150°C, compressing aromatic ketone polymer addressable market in high-volume segments.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with EU MDR standards is enabling import-substitution strategies for implantable-grade resin compounders targeting domestic joint replacement device production.
- Hydrogen infrastructure materials:Electrolyzer stack frames and high-pressure valve housings represent emerging load-bearing applications where chemical resistance and fatigue performance specifications favor ketone-based thermoplastics over incumbent metal designs.
- Film and sheet channel expansion:Direct-to-device-manufacturer distribution models are bypassing traditional distributor markups in semiconductor and healthcare verticals, capturing margin pools previously allocated to regional polymer distributors.
Industry Challenges
- Polymer characterization expertise scarcity:Semi-crystalline morphology control and crystallization kinetics modeling require specialized rheology and thermal analysis capabilities that outpace current technical training pipeline output.
- Multi-jurisdiction registration synchronization:FDA 510(k) clearance timelines, EU MDR technical documentation reviews, and PMDA foreign manufacturer registration cycles create overlapping compliance burdens that strain regulatory affairs staffing at mid-scale compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aromatic Ketone Polymer Market |
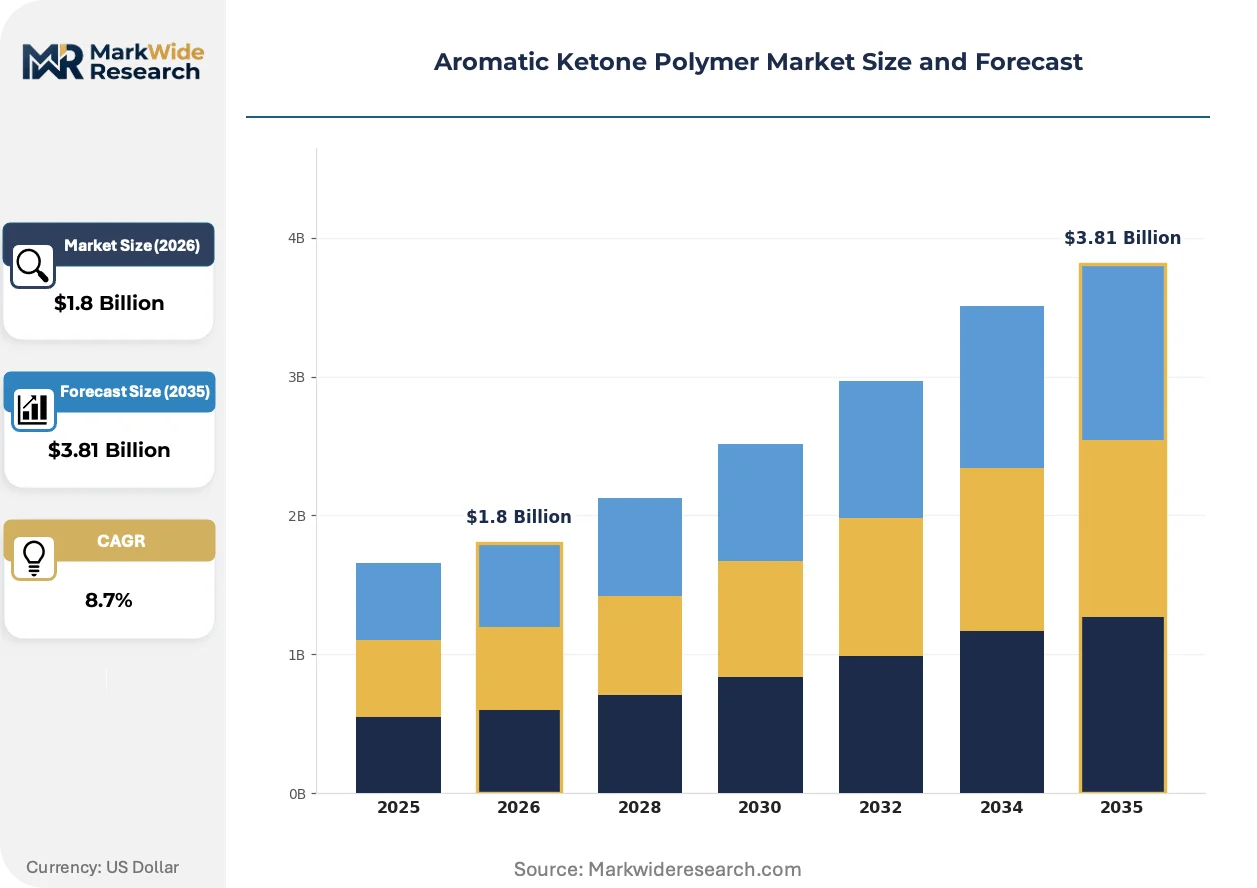
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether Ketone, Polyphenylene Ether, Polyphenylene Sulfide, Polyether Ether Ketone End Use Industry: Aerospace, Automotive, Electrical, Healthcare Form: Films, Sheets, Rods, Tubes Grade: Industrial Grade, Research Grade, Commercial Grade, High Purity |
| Companies Covered | SABIC, Arkema S.A., Evonik Industries AG, Sumitomo Chemical Company, Ltd., Toray Industries, Inc., Solvay S.A., Ensinger GmbH, LG Chem Ltd, Victrex plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aromatic Ketone Polymer Market Emerging Trajectories
Formulation science and regulatory science are converging to reshape competitive positioning, with qualification speed and disclosure transparency emerging as distinct sources of differentiation beyond base resin performance.
Carbon fiber-reinforced polyether ether ketone composites are consolidating as the default material for aerospace structural brackets and satellite bus components. Tier-one suppliers to Boeing and Airbus have shifted procurement specifications toward continuous fiber thermoplastic composites within eighteen-month qualification windows. This consolidation is compressing demand for unreinforced grades in structural applications while elevating compounders with prepreg manufacturing capabilities.
REACH Article 33 disclosure obligations and SCIP database requirements are forcing granular supply chain mapping for substances of very high concern in polymer formulations. Compounders must now document monomer provenance and additive packages across multi-tier supplier networks. Medical device manufacturers in Germany and France are responding by consolidating procurement around suppliers with captive backward integration into difluorobenzophenone production.
Buyer concentration among aerospace OEMs and medical device multinationals is compressing negotiation leverage for specialty compounders. Long-term offtake agreements with volume commitments and price adjustment mechanisms are displacing spot market transactions in implantable-grade resin procurement. This pattern is most pronounced in southern Germany, where automotive and medical device clusters overlap and shared compounders face divergent qualification timelines.
Aromatic Ketone Polymer Market Segmentation
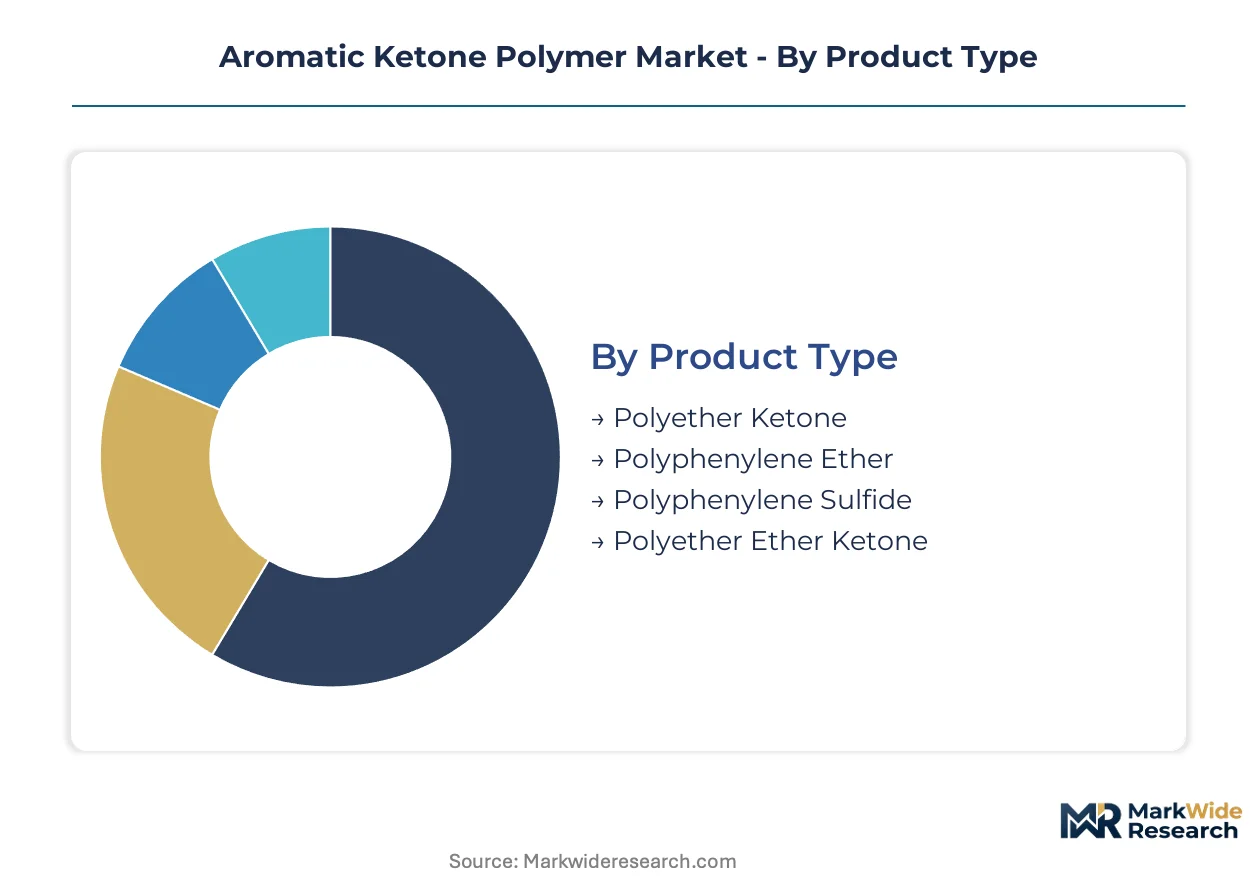
Aromatic ketone polymer procurement splits across performance tiers that map directly to qualification burdens and thermal specifications. Upgrade cycles in aerospace and medical device manufacturing are compressing demand toward certified grades while displacing commodity formulations.
Product Type:
Replacement cycles in metal-to-polymer substitution favor resins with established regulatory files and proven melt-processing windows.
- Polyether Ether Ketone:Semi-crystalline thermoplastic with aryl-ether-ketone backbone achieves melt flow above 350°C without thermal degradation. FAA-qualified grades dominate Boeing and Airbus structural bracket procurement, where stiffness-to-weight ratios displace aluminum in weight-critical ducting and clip assemblies.
- Polyphenylene Sulfide:Lower-cost sulfide chemistry captures automotive under-hood connector volumes where continuous service temperatures remain below 150°C, compressing aromatic ketone polymer penetration in high-volume segments sensitive to resin cost differentials.
- Polyether Ketone:Intermediate crystallinity grade bridges performance gaps in industrial machinery bearings and pump housings.
- Polyphenylene Ether:Amorphous variant serves electrical insulation applications requiring dimensional stability without full ketone backbone cost.
Volume placements concentrate in polyphenylene sulfide; the faster expansion belongs to polyether ether ketone.
End Use Industry:
Customer procurement patterns diverge sharply between qualification-heavy regulated sectors and cost-driven industrial applications.
- Aerospace:Tier-one suppliers to Boeing and Airbus now specify aromatic ketone polymers for structural brackets, ducting, and satellite bus components. Carbon fiber-reinforced formulations within eighteen-month qualification windows are consolidating as the default material, elevating compounders with prepreg manufacturing capabilities.
- Healthcare:EU MDR tightened biocompatibility documentation for implantable grades, locking in specialized polymer suppliers with established regulatory files. Implantable-grade resin procurement in Germany and France is consolidating around suppliers with captive backward integration into difluorobenzophenone production.
- Automotive:OEM specification activity clusters in Germany, where powertrain thermal management components drive specialized grade consumption.
- Electrical:Semiconductor fabrication equipment demand favors sulfone-modified ketone formulations where aggressive chemical resistance and dimensional stability intersect.
Procurement volume tilts toward automotive; healthcare claims the steepest expansion trajectory.
Form:
Margin capture varies dramatically by conversion complexity and direct-to-manufacturer distribution feasibility.
- Films:Thin-gauge extrusions serve semiconductor wafer handling and medical packaging applications. Direct-to-device-manufacturer distribution models are bypassing traditional distributor markups in these verticals.
- Sheets:Thick-plate forms capture disproportionate margin pools in healthcare sterilization trays and chemical processing tank linings. SABIC operates one of the largest continuous extrusion lines for high-temperature polymer sheets in the European market.
- Rods:Stock shapes concentrate in oilfield downhole tool components and chemical processing valve seats.
- Tubes:Hollow profiles serve pneumatic conveying systems and analytical instrumentation fluid handling.
Sheet formats dominate current revenue; film formats are climbing the fastest.
Grade:
Certification tier directly determines addressable application scope and pricing power in regulated end uses.
- Industrial Grade:Standard melt-flow formulations serve chemical processing equipment and general machinery bearings where thermal performance exceeds engineering plastics but full aerospace qualification remains unnecessary.
- High Purity:Reduced extractable content grades meet semiconductor fabrication equipment specifications and aggressive chemical resistance requirements in analytical instrumentation.
- Commercial Grade:Intermediate specification tier bridges prototyping volumes and production scale-up phases.
- Research Grade:Small-batch formulations support university polymer science programs and compounder R&D pipelines.
Industrial grade shipments hold the largest volume position; high purity grades are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Chinese chemical parks supplying difluorobenzophenone feedstock, while consumption clusters in Germany, the United States, and Japan where aerospace and medical device manufacturers drive specialized grade procurement.
Germany
Automotive OEMs and medical device manufacturers in Baden-Württemberg and Bavaria dominate specialized grade consumption. EU MDR biocompatibility mandates and REACH Article 33 disclosure obligations force granular supply chain mapping. The Stuttgart-Munich corridor anchors implantable-grade resin procurement, with compounders consolidating around suppliers possessing captive backward integration into monomer production.
United States
Boeing and Airbus tier-one suppliers specify aromatic ketone polymers for structural brackets and cabin interiors. FAA flame-smoke-toxicity qualification pathways accelerate adoption in weight-critical ducting assemblies. The Pacific Northwest aerospace cluster and Texas medical device corridor drive differentiated demand for carbon fiber-reinforced formulations and implantable grades respectively.
China
Difluorobenzophenone feedstock production clusters in eastern chemical parks, exposing European compounders to tariff volatility and dual-use export licensing friction. MIIT industrial policy prioritizes high-performance polymer self-sufficiency. The Yangtze River Delta hosts expanding compounding capacity serving domestic semiconductor fabrication equipment demand.
Japan
Semiconductor fabrication equipment manufacturers favor sulfone-modified ketone formulations where aggressive chemical resistance intersects with dimensional stability requirements. METI technology roadmaps support next-generation thermoplastic development. The Nagoya-Tokyo industrial corridor concentrates precision machinery demand for high-purity grades.
India
CDSCO regulatory harmonization with EU MDR standards enables import-substitution strategies for implantable-grade resin compounders. Domestic joint replacement device production expands in Maharashtra and Gujarat. The Pune-Ahmedabad medical device cluster attracts specialized polymer suppliers targeting orthopedic implant manufacturing.
Aromatic Ketone Polymer Market Vendor Landscape
Top-tier vendors anchor premium-grade supply, while mid-scale compounders compete on qualification speed and regional proximity. The vendor base stratifies across three tiers: integrated resin producers with captive monomer supply, specialized compounders with prepreg manufacturing capabilities, and regional distributors converting stock shapes. Two strategic archetypes dominate: aerospace-focused suppliers with FAA qualification expertise, and medical-grade specialists with EU MDR technical documentation capabilities. Competitive moves center on backward integration into difluorobenzophenone production and long-term offtake agreements with volume commitments.
Among European integrated producers, Victrex plc and Solvay S.A. occupy positions exemplifying the premium-tier archetype, with the former representing medical-grade specialization and the latter anchoring fluoropolymer compounding convergence. SABIC sits within the scale-driven segment, operating large-format continuous extrusion capabilities. These three entities collectively illustrate the competitive spectrum spanning specialized qualification expertise and manufacturing scale.
| Leading Market Players |
|---|
| SABIC |
| Arkema S.A. |
| Evonik Industries AG |
| Sumitomo Chemical Company, Ltd. |
| Toray Industries, Inc. |
| Solvay S.A. |
| Ensinger GmbH |
| LG Chem Ltd |
| Victrex plc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with Boeing and Airbus tier-one suppliers are compressing spot market liquidity and forcing compounders to absorb working capital burdens for eighteen-month qualification cycles. This procurement consolidation elevates pricing power for suppliers with captive difluorobenzophenone production while squeezing margins at distributors dependent on transactional volumes.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above contract baselines reward compounders maintaining safety stock of implantable-grade resin. Three-tier pricing structure across aerospace-qualified, medical-grade, and industrial formulations reflects certification burden differentials rather than raw material cost spreads. Cost compression in industrial-grade rod and tube formats stems from polyphenylene sulfide substitution in automotive connectors. Medical device manufacturers exhibit lowest price sensitivity due to locked-in regulatory files, while chemical processing equipment buyers negotiate aggressively on volume commitments.
Supply Chain Analysis
Container freight rate volatility between Shanghai and Rotterdam directly impacts landed costs for European compounders sourcing difluorobenzophenone from Yangtze River Delta chemical parks. Monomer production clusters in China, compounding capacity in Germany, and precision machining in Japan form a three-node supply architecture. Feedstock dependency on Chinese difluorobenzophenone exposes buyers to dual-use export licensing friction. Distribution runs through authorized distributors for stock shapes, with direct-to-manufacturer channels capturing film and sheet margin pools in semiconductor and healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR biocompatibility documentation requirements have erected a cost-of-compliance barrier that locks out speculative entrants lacking multi-year technical file investment capacity. This regulatory moat defends premium positioning for established implantable-grade suppliers.
For Market Incumbents: Lock in backward integration into difluorobenzophenone production to neutralize Chinese feedstock tariff exposure and secure supply continuity for long-term aerospace offtake agreements. Deepen prepreg manufacturing capabilities to capture carbon fiber-reinforced composite demand from Boeing and Airbus tier-one suppliers, displacing unreinforced grade competitors in structural bracket applications. For New Entrants and Emerging Players: Launch via direct-to-device-manufacturer distribution models in Indian orthopedic implant manufacturing clusters, bypassing entrenched distributor relationships in saturated European markets. Target CDSCO-harmonized regulatory pathways in Maharashtra and Gujarat medical device corridors where import-substitution strategies favor localized compounding partnerships over established multinational supply chains. For Investors and Strategic Acquirers: The window for entry favors compounders with captive monomer supply and established EU MDR technical documentation capabilities over pure-play distributors or speculative R&D ventures. Watch FAA flame-smoke-toxicity standard amendments as the critical inflection signal that could disqualify incumbent formulations or accelerate sulfone-ketone copolymer qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive difluorobenzophenone supply neutralizes Chinese tariff exposure for European compounders. |
| Prepreg Manufacturing Capability Expansion | Continuous fiber thermoplastic qualification locks in Boeing and Airbus structural bracket procurement. |
| EU MDR Technical Documentation Investment | Biocompatibility file depth creates defensive moats around implantable-grade resin pricing power. |
| Direct-to-Manufacturer Distribution Launch | Bypassing regional distributors captures semiconductor wafer handling film margin pools. |
| Hydrogen Infrastructure Materials Qualification | Electrolyzer stack frame specifications favor ketone thermoplastics over incumbent metal designs. |
Methodological Framework
Independent corroboration across compounder technical directors, aerospace procurement leads, and medical device regulatory affairs managers underwrites the qualitative findings in this study. Primary fieldwork with plant managers at German automotive OEMs and distribution channel partners in semiconductor fabrication equipment was validated against customs trade data, ECHA REACH registration databases, and SEC filings from listed polymer producers. Bottom-up resin shipment estimates were triangulated against top-down end-use consumption models across the projection horizon.
Comparable historical periods anchored the forecast window to post-REACH implementation demand shifts and FAA qualification cycle precedents. The analytical framework modeled grade tier, end-use industry, form factor, and regional production hub segmentation throughout the forecast period. CAGRs were derived from elasticity-adjusted volume projections incorporating aerospace build rate assumptions and medical device approval velocity. Crystallization kinetics modeling capabilities and regulatory file maturity served as industry-specific forecast inputs.
Feedstock tariff volatility, dual-use export licensing friction, and pending FAA flame-smoke-toxicity amendments are the dominant revision risks that could alter trajectory assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Polyamide 12 Market