
 Middle East Biodegradable Plastics Market | 2026-2036
Middle East Biodegradable Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Biodegradable Plastics Market Foresight
Subscription-based resin certification and compostability-as-a-service is decoupling material sales from standalone product transactions across the Middle East biodegradable plastics value chain. BASF SE leverages its global Ecovio portfolio to anchor technical support programs for Gulf-based converters seeking EN 13432 compliance. NatureWorks LLC specializes in polylactic acid supply partnerships with UAE food packaging distributors, while Novamont S.p.A. competes through localized starch blend compounding capabilities in the Saudi market.
Middle East biodegradable plastics comprise polymers engineered to mineralize through microbial action under industrial composting or soil burial conditions, typically exhibiting tensile strengths between 20 and 70 MPa depending on polylactic acid or polyhydroxyalkanoates base chemistry. These materials serve primarily as drop-in replacements for conventional polyethylene and polypropylene in applications where end-of-life organic recovery is mandated or brand-positioned. Polylactic acid currently leads product type value generation due to mature fermentation supply chains and Ingeo brand recognition, while polyhydroxyalkanoates represents the fastest-expanding chemistry segment as marine biodegradability claims attract premium pricing from coastal emirate buyers. Packaging dominates end user revenue capture, though agriculture applications in Saudi drip irrigation and mulch film trials are deepening volume commitments.
Saudi Arabia's SFDA governs food-contact safety approvals, the UAE's Ministry of Climate Change and Environment enforces extended producer responsibility frameworks for single-use items, and both jurisdictions reference ASTM D6400 and EN 13432 compostability standards in public procurement specifications. These overlapping requirements compel importers to maintain dual-certification portfolios and restrict market access for uncertified Asian resin suppliers. Stakeholders must monitor how Gulf standardization bodies harmonize biodegradability test methods with European REACH chemical safety registrations, as divergence would fragment compliance costs across the six-nation trade bloc.
Market Dynamics
Dual-certification mandates under Saudi SFDA food-contact guidelines and UAE Ministry of Climate Change extended producer responsibility frameworks are fragmenting resin sourcing strategies across the six-nation Gulf Cooperation Council trade bloc.
Growth Catalysts
- UAE single-use plastic restrictions:Hospitality procurement teams in Dubai and Abu Dhabi emirates are mandating compostable food service items for hotel and retail operations.
- Polylactic acid fermentation supply chains:Mature biotechnology infrastructure is lowering unit production costs for Ingeo-grade biopolymers serving Gulf packaging converters.
- Saudi agricultural modernization:Drip irrigation and mulch film trials under the Kingdom's food security initiatives are deepening volume commitments from agribusiness operators.
Market Restraints
- Petrochemical feedstock cost volatility:Conventional polyethylene and polypropylene pricing swings from Saudi Aramco supply fluctuations compress biopolymer margin premiums during crude oil downturns.
- Asian resin supplier concentration:Uncertified import volumes from non-EN 13432/ASTM D6400 compliant sources create price floor pressure and compliance verification burdens for Gulf distributors.
- Industrial composting infrastructure gaps:Limited aerobic digestion facility coverage across Qatar, Kuwait, and Oman forces reliance on soil burial validation with slower mineralization timelines.
Strategic Opportunities
- Oman and Bahrain underpenetration:Nascent hospitality sectors in Muscat and Manama present first-mover positioning for certified biopolymer distributors before regulatory mandates replicate UAE/Saudi frameworks.
- Marine biodegradability premium positioning:Polyhydroxyalkanoates chemistry with saltwater mineralization claims attracts coastal emirate buyers in Sharjah and Fujairah seeking differentiated end-of-life narratives.
- Subscription-based certification services:Compostability-as-a-service models decouple resin sales from standalone transactions, enabling recurring revenue streams for technical support providers.
Industry Challenges
- Dual-standard compliance timelines:Maintaining simultaneous EN 13432 and ASTM D6400 certification portfolios stretches Gulf importer quality assurance teams and extends product launch cycles.
- Composting facility operator training gaps:Limited regional expertise in aerobic digestion temperature management and contamination screening threatens end-of-life performance validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Biodegradable Plastics Market |
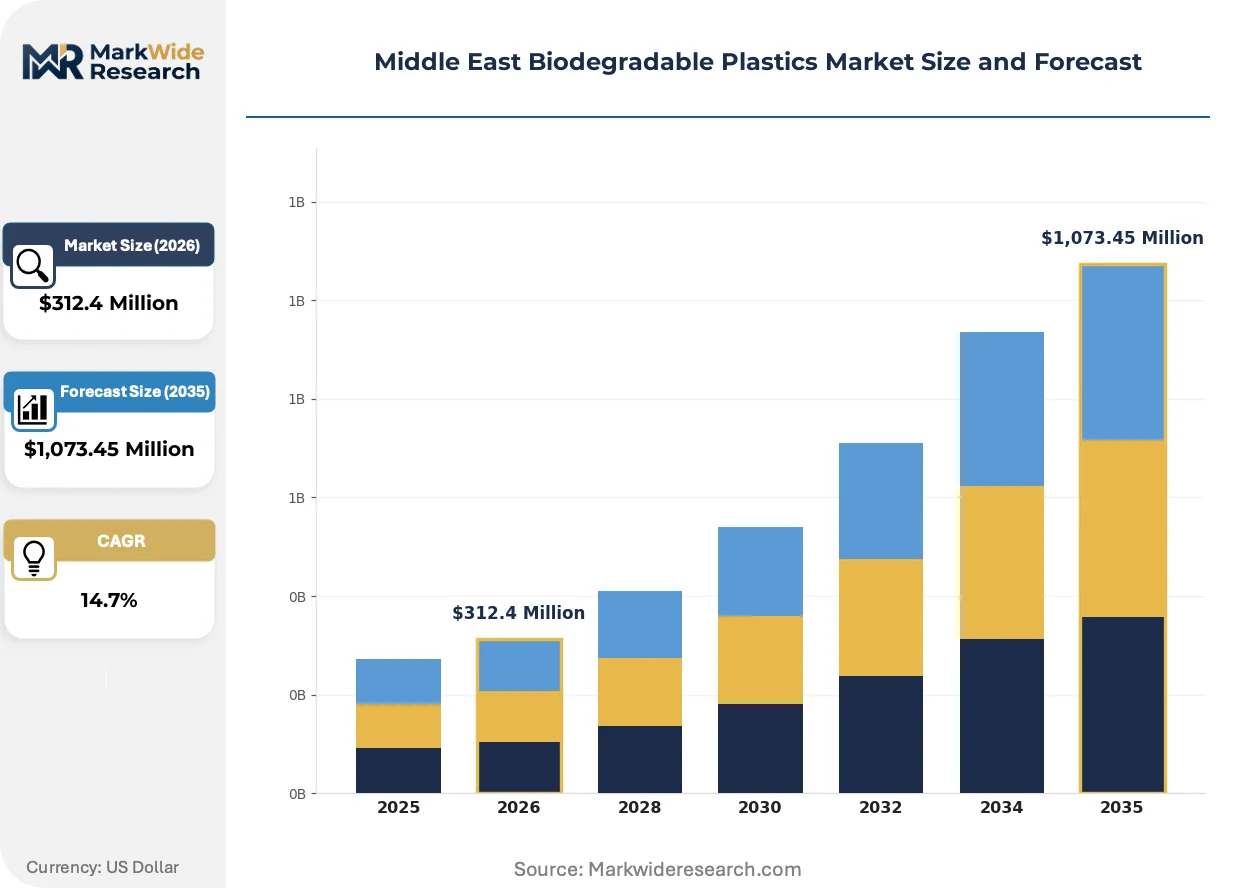
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polylactic Acid, Starch Blends, Polyhydroxyalkanoates, Cellulose End User: Packaging, Agriculture, Consumer Goods, Automotive Form: Films, Injection Molding, Foams, Coatings Application: Food Service, Mulch Films, Disposable Cutlery, Medical Devices |
| Companies Covered | BASF SE, Avani Eco Middle East, Al Bayader International, NatureWorks LLC, Novamont S.p.A., TotalEnergies Corbion, Cargill Incorporated, Eastman Chemical Company, Ecoway Biopolymers LLC, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Biodegradable Plastics Market Shifts & Advancements
Biodegradable plastics value chains across the Middle East are pivoting from commodity resin transactions toward integrated certification and technical service bundles that lock in converter loyalty.
Aliphatic-aromatic copolyester formulations with enhanced heat deflection temperatures are rewriting performance benchmarks for hot-fill food packaging applications. Saudi dairy and beverage processors are trialing these materials for yogurt cups and juice bottles previously reserved for fossil-based polypropylene. The technology is compressing the historical trade-off between biodegradation rates and thermal stability that constrained earlier polylactic acid generations.
UAE Ministry of Climate Change enforcement of extended producer responsibility frameworks for single-use items is mandating deposit-return schemes and post-consumer collection targets for hospitality distributors. Food service operators in Dubai must now document compostable item recovery rates to maintain operating licenses. Large-format retail chains are responding by pre-qualifying suppliers with dual EN 13432 and ASTM D6400 certification to preempt procurement disqualification.
Hospitality procurement teams are consolidating vendor relationships around full-service biopolymer partners who bundle resin supply with compostability certification and end-of-life logistics coordination. This behavior shift displaces spot-market resin purchasing that dominated early market development. The concentration is most visible in Abu Dhabi's hotel and catering supply chains, where procurement directors now prioritize single-accountability sourcing over lowest-unit-cost bidding.
Middle East Biodegradable Plastics Market Segmentation
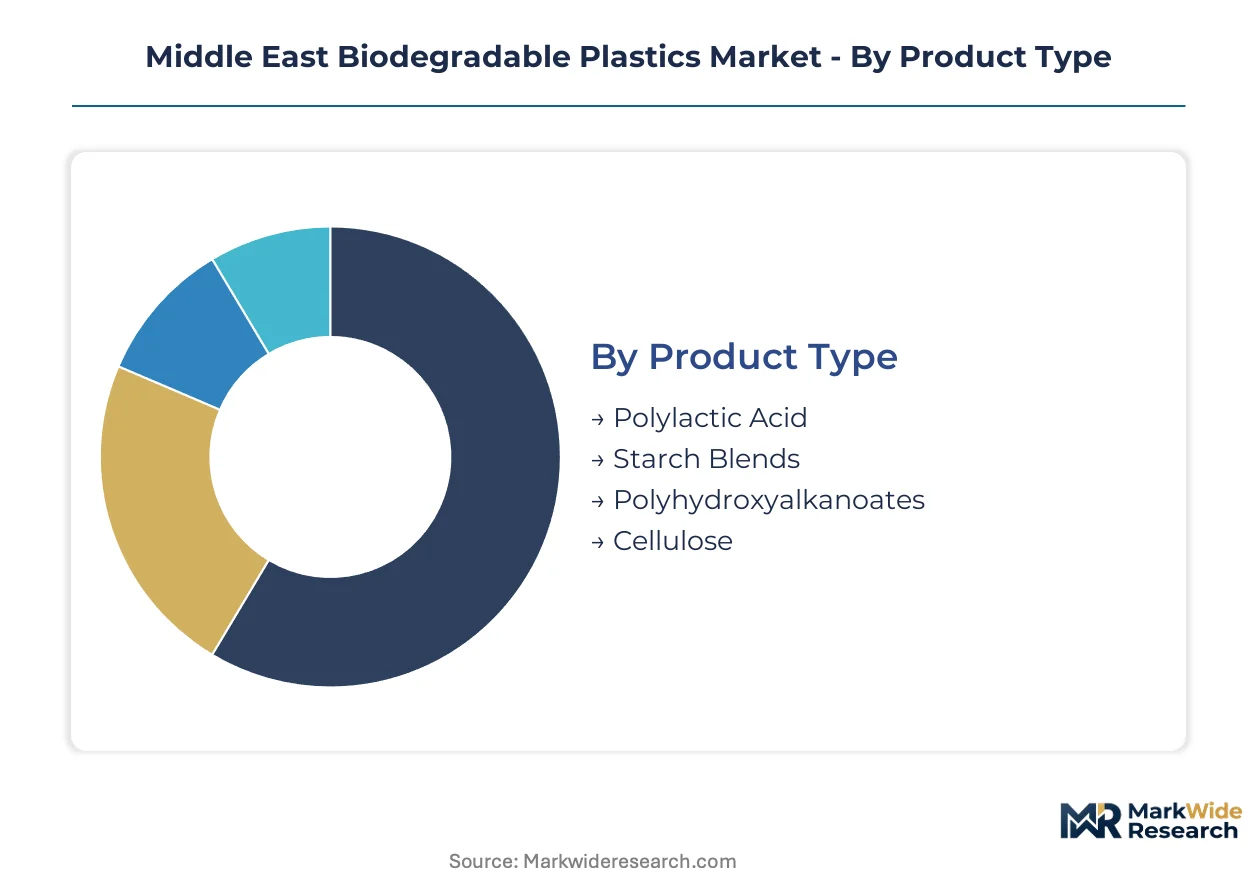
Biodegradable plastics procurement across the Middle East fragments sharply by technical specification and end-of-life pathway. Buyers in Dubai's hospitality corridors select differently than Saudi agribusiness operators or UAE healthcare procurement teams.
Product Type:
Cost tier separates commodity converters from premium-positioned buyers seeking marine biodegradability claims.
- Polylactic Acid:Fermentation-derived aliphatic polyester exhibiting tensile strengths of 20-70 MPa. Gulf packaging converters in Dubai and Abu Dhabi prioritize Ingeo-grade material for food-contact applications under SFDA guidelines.
- Starch Blends:Thermoplastic compounds combining native starches with synthetic aliphatic-aromatic copolyesters. Saudi distributors source localized compounding to meet price-sensitive food service procurement budgets.
- Polyhydroxyalkanoates:Bacterial fermentation polymers commanding premium pricing from Sharjah and Fujairah coastal buyers for saltwater mineralization claims.
- Cellulose:Regenerated plant fiber materials serving niche coating applications with limited thermal stability.
Volume sits with Polylactic Acid; growth tilts toward Polyhydroxyalkanoates.
End User:
Application maturity determines whether buyers accept certification-only procurement or demand full technical service bundles.
- Packaging:Drop-in replacements for polyethylene and polypropylene in food-contact articles. Dubai hotel chains mandate compostable items under UAE Ministry of Climate Change extended producer responsibility frameworks.
- Agriculture:Mulch films and drip irrigation tubing for Saudi food security initiatives. Riyadh-based agribusiness operators trial soil-burial validation with slower mineralization timelines.
- Consumer Goods:Disposable cutlery and personal care packaging serving retail chains in Abu Dhabi with dual EN 13432 and ASTM D6400 pre-qualification requirements.
- Automotive:Interior trim and insulation components with limited current penetration across Gulf manufacturing bases.
Revenue concentrates in Packaging; expansion accelerates most quickly in Agriculture.
Form:
Processing infrastructure availability constrains converter selection across the six-nation Gulf Cooperation Council trade bloc.
- Films:Blown and cast sheet formats for flexible food packaging. UAE converters dominate regional supply with established extrusion lines.
- Injection Molding:Rigid container production for dairy and beverage processors in Saudi Arabia trialing hot-fill applications.
- Foams:Expanded polylactic acid cushioning for protective packaging with nascent regional capacity.
- Coatings:Barrier layer applications on paper substrates serving limited specialty food service niches.
Installed capacity favors Films; investment flows toward Injection Molding.
Application:
Regulatory enforcement intensity shapes whether specifications demand industrial composting or accept soil burial validation.
- Food Service:Compostable plates, cups, and containers for Dubai hospitality procurement teams documenting recovery rates to maintain operating licenses.
- Mulch Films:Agricultural ground cover for Saudi drip irrigation trials requiring UV stability during growing seasons followed by biodegradation.
- Disposable Cutlery:Single-use utensils for UAE retail chains pre-qualifying suppliers with dual certification portfolios.
- Medical Devices:Sterile packaging and disposable instruments with stringent SFDA approval timelines limiting market entry.
Procurement volume clusters in Food Service; regulatory tailwinds strengthen fastest in Medical Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's hospitality corridor anchors biodegradable plastics procurement across the Gulf Cooperation Council, with hotel chains and retail operators in the emirate setting compliance benchmarks that cascade to neighboring markets.
Saudi Arabia
Riyadh-based agribusiness operators drive mulch film and drip irrigation tubing trials under the Kingdom's food security initiatives. The Saudi Food and Drug Authority governs food-contact safety approvals with strict SFDA guidelines. Jeddah's packaging converters are scaling Ingeo-grade polylactic acid extrusion to serve dairy processors seeking hot-fill alternatives.
United Arab Emirates
Dubai and Abu Dhabi emirates concentrate hospitality and retail procurement mandating compostable food service items. The Ministry of Climate Change and Environment enforces extended producer responsibility frameworks with documented recovery rate requirements. Sharjah's coastal buyers command premium pricing for marine-biodegradable polyhydroxyalkanoates with saltwater mineralization claims.
Qatar
Doha's hospitality sector imports certified biopolymers for hotel and catering operations ahead of anticipated regulatory alignment with UAE frameworks. The national environment ministry references ASTM D6400 and EN 13432 standards in public procurement specifications. Limited industrial composting infrastructure forces reliance on soil burial validation with extended mineralization timelines.
Kuwait
Kuwait City's retail chains are pre-qualifying suppliers with dual certification portfolios as extended producer responsibility discussions advance. The Environment Public Authority monitors single-use plastic reduction targets. Food service distributors in the capital are consolidating vendor relationships around full-service biopolymer partners bundling resin supply with technical support.
Oman
Muscat's nascent hospitality sector presents first-mover positioning for certified biopolymer distributors before regulatory mandates replicate Saudi and UAE frameworks. The Ministry of Environment and Climate Affairs evaluates compostability standards for future enforcement. Port infrastructure in Sohar is attracting import distributors seeking Gulf trade bloc access with reduced compliance fragmentation.
Middle East Biodegradable Plastics Market Competitive Landscape
Capital-heavy petrochemical producers compete with asset-light specialty compounders for converter relationships across the Middle East biodegradable plastics market. The vendor base clusters around three strategic tiers: global resin suppliers with certification portfolios, regional distributors with logistics integration, and local converters with formulation capabilities. Dominant competitive moves include backward integration into fermentation feedstock supply and technology licensing partnerships that transfer compostability testing expertise to Gulf-based partners.
Within the global resin supplier tier, BASF SE and NatureWorks LLC exemplify divergent archetypes for market engagement. BASF SE anchors technical support programs leveraging global portfolio scale, while NatureWorks LLC occupies a position centered on polylactic acid specialization with UAE distribution partnerships. Novamont S.p.A. sits within the European compounder archetype, representing localized starch blend capabilities adapted to Saudi price-sensitive procurement budgets. These three companies illustrate how geographic origin and chemistry focus determine competitive positioning without requiring identical go-to-market structures.
| Leading Market Players |
|---|
| BASF SE |
| Avani Eco Middle East |
| Al Bayader International |
| NatureWorks LLC |
| Novamont S.p.A. |
| TotalEnergies Corbion |
| Cargill Incorporated |
| Eastman Chemical Company |
| Ecoway Biopolymers LLC |
| Others |
Supply & Pricing Matrix
UAE Ministry of Climate Change extended producer responsibility frameworks gate qualified supply and premium-tier pricing access by mandating dual EN 13432 and ASTM D6400 certification for hospitality procurement contracts. Buyers without documented compostable item recovery rates face operating license suspension, forcing distributors to absorb certification costs or forfeit Dubai and Abu Dhabi market entry.
Pricing Analysis
Certification-as-a-service bundling anchors value-based pricing for Gulf converters seeking compliance without in-house testing infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates marine-biodegradable polyhydroxyalkanoates from commodity polylactic acid and uncertified starch blends. Cost compression in economy-tier imports intensifies because Asian resin suppliers without dual certification flood spot markets. Saudi agribusiness operators exhibit highest price sensitivity due to soil-burial validation acceptance, while Sharjah coastal buyers pay least attention to unit cost.
Supply Chain Analysis
Freight costs from European fermentation hubs and Asian compounding centers dominate landed price variability for Gulf distributors. Supply concentrates in Germany, Thailand, and the United States for polylactic acid resin, while Saudi Arabia and Italy feed starch blend formulations. Raw material dependencies span corn-derived dextrose, sugarcane sucrose, and tapioca starch feedstocks. Single-source vulnerability from NatureWorks LLC's Nebraska fermentation complex threatens Ingeo-grade supply continuity. Distribution runs through Dubai Jebel Ali port consolidation before last-mile delivery to Riyadh and Doha converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polylactic acid fermentation infrastructure is displacing petroleum-based polypropylene in hot-fill food packaging, marking a materials-transition phase for Gulf converters. Legacy fossil-polymer supply relationships are dissolving as SFDA guidelines and UAE extended producer responsibility frameworks mandate organic end-of-life pathways.
For Market Incumbents: Hedge certification portfolio concentration by securing secondary ASTM D6400 laboratory partnerships beyond primary EN 13432 facilities. Backward integration into regional composting facility operations defends margin position against subscription-based service providers decoupling resin sales from technical support. Threat of uncertified Asian resin price floors demands dual-standard quality assurance investment to maintain Dubai hospitality procurement access.
For New Entrants and Emerging Players: The mid-tier price gap between premium marine-biodegradable polyhydroxyalkanoates and economy starch blends creates entry space for aliphatic-aromatic copolyester specialists. Oman and Bahrain underpenetration offers most penetrable geography before regulatory mandates replicate UAE frameworks. Go-to-market angle should bundle resin supply with compostability certification and end-of-life logistics coordination to match Abu Dhabi procurement director preferences for single-accountability sourcing.
For Investors and Strategic Acquirers: First announced industrial composting facility construction in Qatar or Kuwait is the leading indicator that soil-burial validation acceptance is shifting toward mandatory aerobic digestion infrastructure. Long-term viability favors asset-light certification and technical service providers over capital-heavy fermentation capacity. Acquisition target archetype: regional distributors with logistics integration and dual-standard compliance portfolios. Signal to monitor: UAE Ministry of Climate Change deposit-return scheme enforcement thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive fermentation feedstock supply secures margin control against commodity dextrose volatility. |
| Dual Certification Investment | Simultaneous EN 13432 and ASTM D6400 portfolios unlock Saudi and UAE public procurement eligibility. |
| Compostability-as-a-Service Launch | Subscription revenue decouples from resin spot pricing and locks converter loyalty through technical support. |
| Geographic Expansion to Oman | First-mover positioning in Muscat hospitality before regulatory mandates replicate Dubai frameworks. |
| Joint Venture with Composting Operator | End-of-life logistics coordination completes full-service bundles demanded by Abu Dhabi procurement directors. |
Research Methodology
Multi-period observation of resin import volumes, certification issuance rates, and composting facility development anchored the trend analysis, supplemented by interviews with biopolymer plant managers, Gulf packaging converter procurement leads, hospitality distributor channel partners, and technical R&D directors at fermentation suppliers. Secondary validation drew from customs and trade data, Saudi Food and Drug Authority filings, UAE Ministry of Climate Change enforcement notices, and SEC disclosures by publicly traded petrochemical conglomerates. Bottom-up demand modeling and top-down supply capacity assessment were triangulated against cross-referenced stakeholder inputs.
Segment-weighting across product type, end user, form, and application dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from fitted growth curves against historical penetration rates and regulatory enforcement intensity assumptions. Industry-specific forecast inputs included SFDA guideline implementation timelines and UAE extended producer responsibility recovery rate thresholds.
Inputs from customs databases and regulatory filings were available through the study window; gaps in real-time composting facility utilization data introduce uncertainty bands around end-of-life performance validation assumptions. Forecasts reflect documented assumptions regarding certification harmonization and infrastructure buildout pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
North America Bioplastics Market
Bioplastics
Biopolymers Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Biocomposite Materials Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Starch-Based Plastics Market