
 Emulsion PVC Market | 2026-2036
Emulsion PVC Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsion PVC Market Analysis
Aftermarket coating reformulation services is reconfiguring margin pools away from commodity resin sales toward technical advisory and custom blend supply. Kem One leverages its European manufacturing footprint to sustain premium positioning in specialty water-based formulations. Formosa Plastics Corporation anchors volume supply across Asia through integrated VCM-to-emulsion resin operations. Vinnolit GmbH & Co. KG differentiates via high-purity medical-grade emulsion PVC lines that command superior pricing.
Emulsion PVC denotes a polyvinyl chloride resin produced via suspension polymerization in aqueous media, yielding particles with diameters between 0.1 and 2.0 micrometers that disperse readily into water-based systems for coating and adhesive applications. The material functions primarily as a film-forming binder in architectural paints, providing adhesion, durability, and weather resistance without solvent carriers. Coatings formulations occupy the dominant value share as construction maintenance cycles sustain steady offtake across mature economies. Water-based formulation types are gaining fastest as regulatory pressure on volatile organic compound emissions intensifies across industrialized markets. Specialty grades concentrate margin pools where custom rheology and adhesion profiles serve automotive interior and textile lamination niches.
EPA regulations on architectural coating VOC content and REACH restrictions on phthalate plasticizers are reshaping formulation chemistry and raw material sourcing across the value chain. ECHA classification of certain vinyl chloride monomer residuals as substances of very high concern is tightening purity standards for emulsion PVC destined for consumer-contact applications. China MEE enforcement of dual carbon goals is pressing domestic producers toward cleaner polymerization catalyst systems and energy-efficient drying operations. Stakeholders must monitor evolving chemical hazard designations in Europe and North America while calibrating capacity investments toward low-carbon process certifications that major construction and automotive buyers now require in supplier qualification protocols.
Market Dynamics
Water-based formulation chemistry is displacing solvent-borne systems across architectural coatings as EPA VOC limits and REACH phthalate restrictions tighten compliance requirements for resin suppliers and formulators alike.
Growth Catalysts
- Construction sector renovation cycles:Building maintenance schedules in mature economies sustain steady offtake for architectural coating binders. Property managers specify emulsion-grade resins for exterior durability.
- REACH SVHC designations:ECHA classification of vinyl chloride monomer residuals as substances of very high concern is elevating purity premiums for medical-grade and consumer-contact applications.
- China infrastructure spending:Domestic transportation and housing projects concentrate regional consumption of emulsion PVC for water-based adhesive and coating systems.
Market Restraints
- VCM feedstock volatility:Ethylene and chlorine input costs fluctuate with energy markets, compressing margin predictability for non-integrated resin producers.
- Specialty supply concentration:High-purity medical-grade lines concentrate among German and Japanese manufacturers, creating bottleneck risk for healthcare sector buyers.
- Acrylic latex substitution:Water-based acrylic systems compete for share in premium architectural coatings where weatherability specifications permit formulation flexibility.
Strategic Opportunities
- India construction chemicals:Urban housing and commercial real estate expansion in Mumbai and Delhi NCR create underpenetrated demand for water-based coating binders.
- Automotive interior lamination:Custom rheology grades serve textile backing and synthetic leather applications as OEMs phase out solvent-based adhesive systems.
- EU Green Deal procurement:Public construction tenders increasingly require Environmental Product Declarations and low-carbon process certifications from resin suppliers.
Industry Challenges
- Polymerization catalyst expertise:Formulation chemists with specialized knowledge of aqueous-phase kinetics remain scarce relative to solvent-based system experience.
- Legacy equipment retrofitting:Drying and classification assets designed for suspension-grade resins require capital-intensive modification to handle sub-micron emulsion particle distributions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsion PVC Market |
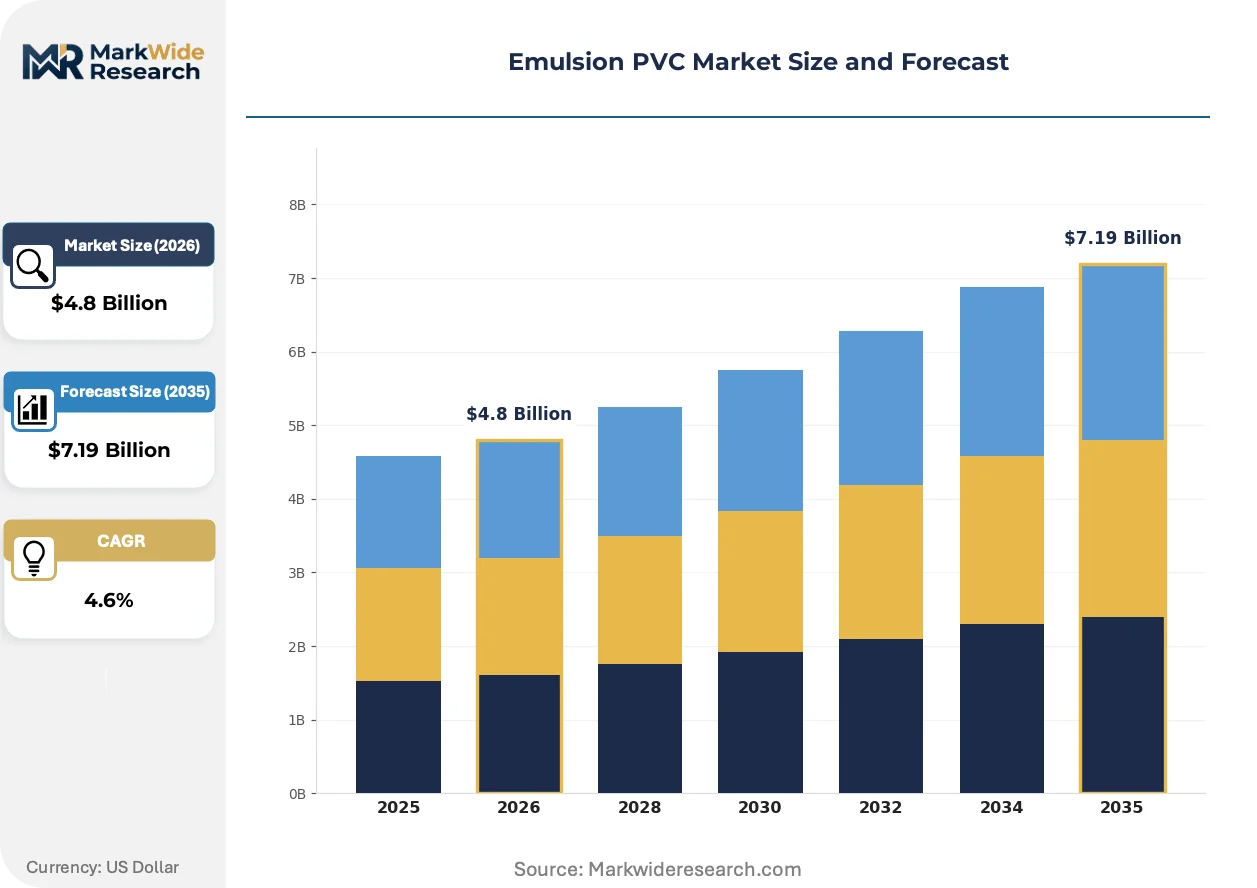
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Adhesives, Sealants, Inks End Use Industry: Construction, Automotive, Packaging, Textiles Formulation Type: Water-Based, High-Gloss, Low-VOC, Specialty Processing Technique: Extrusion, Injection Molding, Blow Molding, Calendarizing |
| Companies Covered | Chemplast Sanmar Limited, Kem One, SCG Chemicals Co., Ltd., Kaneka Corporation, Formosa Plastics Corporation, Vinnolit GmbH & Co. KG, RusVinyl LLC, Finolex Industries Limited, Mexichem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsion PVC Market Emerging Trajectories
Formulation science is pivoting toward bio-based plasticizers and hybrid polymer architectures that satisfy tightening chemical hazard designations without sacrificing film performance in exterior exposure conditions.
Micro-emulsion polymerization is collapsing the particle size distribution gap between conventional emulsion PVC and specialty colloidal dispersions. Automotive tier-one suppliers adopt these grades for sprayable interior coatings that achieve Class A surface finish without solvent carriers. The technology is collapsing the traditional segmentation between commodity construction binders and premium industrial coating resins.
EPA architectural coating VOC content regulations and ECHA restrictions on phthalate plasticizers are forcing reformulation across the value chain. Resin producers must qualify alternative plasticizer systems and validate long-term adhesion performance under accelerated weathering protocols. North American and European formulators face the steepest compliance timelines as enforcement windows narrow.
Specification authority is migrating from general contractors to asset owners and their sustainability consultants. Large commercial real estate operators in Germany and California now mandate cradle-to-gate carbon disclosures and third-party certified low-VOC content for maintenance coating programs. This procurement evolution favors resin suppliers with verified process certifications and transparent supply chain documentation over commodity volume players.
Emulsion PVC Market Segmentation
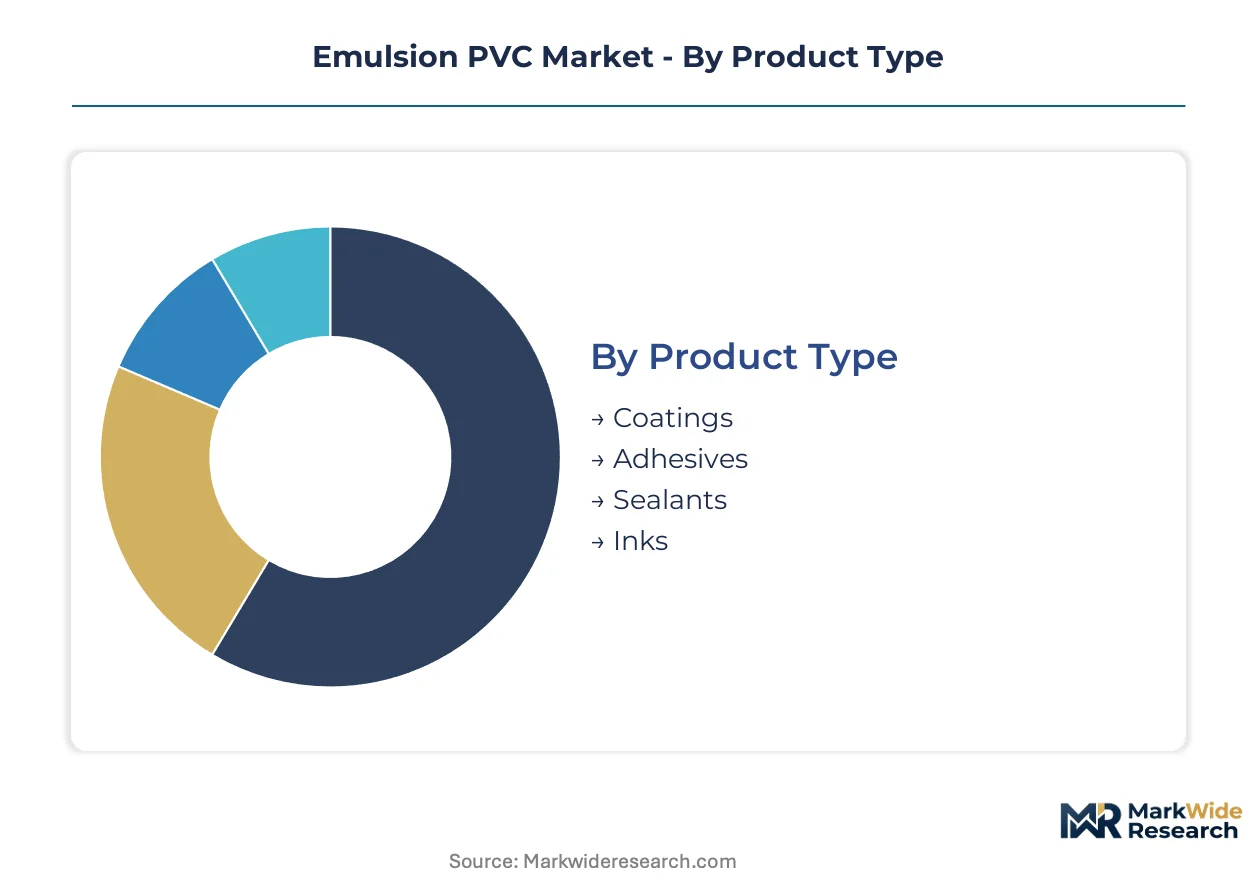
Segmentation in emulsion PVC markets reveals distinct margin pools and technical service requirements across formulation chemistries and end-use specifications. Each category carries different after-sales intensity, from commodity coating binders requiring minimal technical support to specialty automotive grades demanding ongoing rheology optimization.
Product Type:
After-sales service intensity varies sharply across product categories, with coatings and adhesives commanding dedicated formulation laboratories while sealants and inks operate through distributor technical support.
- Coatings:Film-forming binders for architectural and industrial applications dominate value capture. Exterior durability specifications in Germany and California drive demand for weather-resistant grades with verified low-VOC certification.
- Adhesives:Pressure-sensitive and structural bonding formulations serve textile lamination and automotive interior assembly. OEMs in Japan and South Korea specify custom tack profiles requiring ongoing technical partnership.
- Sealants:Joint-filling compounds for construction maintenance cycles. Building envelope specifications in France and Italy sustain steady offtake through distributor channels.
- Inks:Flexographic and gravure printing vehicles for packaging substrates. Narrow-web label applications in the UK concentrate specialty grade consumption.
Coatings holds the largest share; momentum sits with adhesives as automotive interior lamination specifications tighten.
End Use Industry:
Cost tier differentiation separates commodity construction applications from premium automotive and medical-contact segments where purity premiums apply.
- Construction:Architectural maintenance and new build applications consume volume share. Property managers in the US specify water-based systems for EPA compliance, while German commercial real estate operators mandate EPD certification.
- Automotive:Interior textile backing and synthetic leather coatings require Class A surface finish. Tier-one suppliers in Japan adopt micro-emulsion grades for sprayable solvent-free systems.
- Packaging:Flexible film lamination and label adhesives serve food-contact applications. REACH SVHC restrictions on vinyl chloride monomer residuals elevate purity requirements for European converters.
- Textiles:Fabric coating and artificial leather backing demand custom rheology profiles. Italian and Portuguese manufacturers drive specialty formulation development.
Construction commands volume leadership; automotive climbs fastest as OEMs phase out solvent carriers.
Formulation Type:
Volume concentration centers on water-based systems, while margin pools concentrate in specialty grades serving medical and automotive niches.
- Water-Based:Standard emulsion systems displace solvent-borne alternatives across architectural coatings. EPA VOC limits and China MEE enforcement accelerate conversion timelines.
- High-Gloss:Premium aesthetic finishes for consumer-facing applications. Appliance and furniture coatings in Germany and Japan specify optical clarity grades.
- Low-VOC:Compliance-grade formulations meeting tightening regulatory thresholds. California Air Resources Board and EU Green Deal procurement standards drive qualification requirements.
- Specialty:Medical-grade and consumer-contact applications with elevated purity standards. ECHA SVHC classification of VCM residuals concentrates supply among certified German and Japanese producers.
Water-based formulations dominate volume; specialty grades capture the steepest margin expansion.
Processing Technique:
Application method determines particle size distribution requirements and drying energy intensity across the value chain.
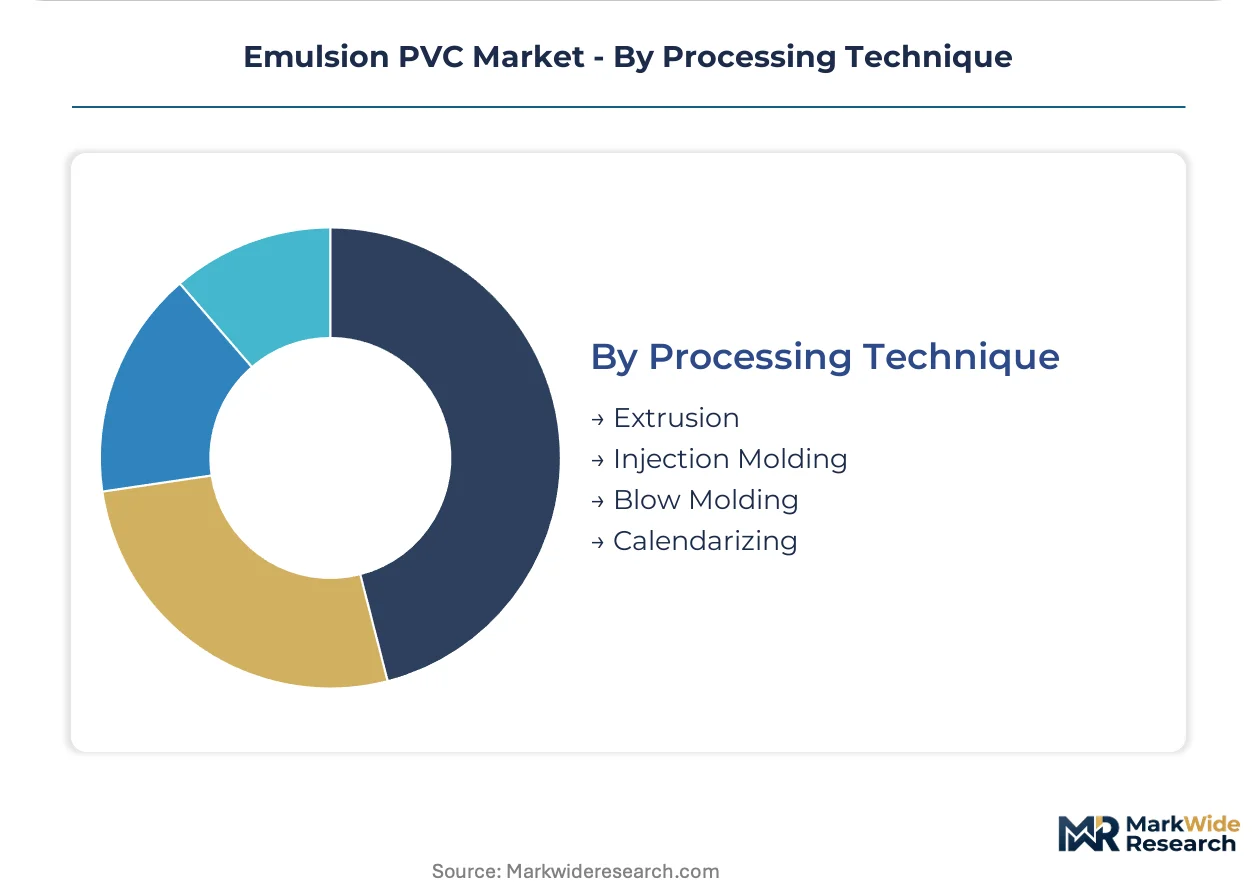
- Extrusion:Profile and sheet applications requiring controlled fusion behavior. Window and siding manufacturers in the US specify consistent gelation characteristics.
- Injection Molding:Complex geometry parts with tight dimensional tolerance. Automotive component suppliers in Germany favor grades with predictable flow properties.
- Blow Molding:Hollow articles including bottles and containers. Limited emulsion PVC penetration due to suspension-grade resin cost advantages.
- Calendarizing:Film and sheet production for flooring and wall covering. Italian flooring producers drive demand for consistent gauge control.
Extrusion anchors volume consumption; calendarizing maintains position in premium decorative applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan accept purity premiums for medical-grade specifications, while construction contractors in India and Brazil prioritize cost-efficient water-based binders for volume applications.
China
Domestic infrastructure spending on transportation and housing projects concentrates demand for emulsion-grade resins in water-based adhesive systems. MEE enforcement of dual carbon goals presses producers toward cleaner polymerization catalysts and energy-efficient drying operations. The Yangtze River Delta hosts the densest cluster of integrated VCM-to-resin facilities serving regional coating formulators.
Germany
Commercial real estate operators in Frankfurt and Munich mandate Environmental Product Declarations and cradle-to-gate carbon disclosures for maintenance coating programs. ECHA classification of vinyl chloride monomer residuals as substances of very high concern elevates purity premiums for consumer-contact applications. The Rhine-Ruhr industrial corridor anchors specialty production of high-grade medical and automotive formulations.
United States
Property managers specify water-based emulsion systems for exterior architectural durability as EPA VOC limits tighten compliance timelines. California Air Resources Board standards drive qualification requirements for low-VOC formulations in public and private construction tenders. The Gulf Coast petrochemical corridor supplies integrated feedstock advantages for domestic resin producers serving coating compounders.
India
Urban housing and commercial real estate expansion in Mumbai and Delhi NCR creates underpenetrated demand for water-based coating binders in construction chemicals. BIS standards for architectural coating quality and environmental safety are gradually aligning with international low-VOC benchmarks. Gujarat's chemical manufacturing belt hosts emerging domestic capacity targeting regional adhesive and sealant formulators.
Japan
Tier-one automotive suppliers adopt micro-emulsion grades for sprayable interior coatings achieving Class A surface finish without solvent carriers. METI guidelines on chemical substance management and carbon neutrality targets reshape supplier qualification protocols for domestic OEMs. The Nagoya industrial zone concentrates formulation expertise serving synthetic leather and textile lamination applications.
Emulsion PVC Market Vendor Landscape
Capability concentration sits with European and Japanese specialists commanding purity premiums; scale advantage sits with Asian integrated producers anchoring volume supply. The vendor base separates into three functional tiers: petrochemical conglomerates with captive VCM supply, regional specialists serving formulation technical service, and medical-grade pure-play producers. Strategic moves center on backward integration into vinyl chloride monomer production and portfolio diversification toward low-VOC certified product lines.
Among European specialists, Vinnolit GmbH & Co. KG and Kem One occupy positions defined by formulation chemistry expertise and REACH compliance leadership. Formosa Plastics Corporation exemplifies the integrated scale tier with captive raw material control across Asian markets. Kaneka Corporation represents the Japanese specialist archetype serving automotive and medical niches with custom rheology development.
| Leading Market Players |
|---|
| Chemplast Sanmar Limited |
| Kem One |
| SCG Chemicals Co., Ltd. |
| Kaneka Corporation |
| Formosa Plastics Corporation |
| Vinnolit GmbH & Co. KG |
| RusVinyl LLC |
| Finolex Industries Limited |
| Mexichem |
| Others |
Supply Flow & Price Mechanics
Integrated VCM-to-resin facilities along China's Yangtze River Delta concentrate upstream supply, anchoring margin pools in formulation technical service and REACH-compliant certification rather than commodity resin tonnage. European specialty producers capture purity premiums through medical-grade lines that command superior pricing over construction-grade volume supply.
Pricing Analysis
After-sales formulation advisory and custom blend technical service drives lifetime value capture for resin suppliers serving coating compounders. Three-tier pricing structure across specialty, compliance-grade, and commodity levels separates medical-contact applications from architectural binders. Cost compression in standard water-based grades is intensifying because acrylic latex substitution pressures specification flexibility. Volume construction contractors in India and Brazil exhibit highest price sensitivity; German automotive tier-one suppliers accept premium positioning for Class A surface finish grades.
Supply Chain Analysis
Extended payment terms from European formulators and supply-chain finance facilities at Chinese state-owned resin producers shape working capital dynamics across the value chain. Manufacturing concentrates in China, Germany, and Japan for distinct grade tiers. Feedstock draws from ethylene and chlorine derivatives tethered to energy market volatility. Single-source vulnerability concentrates in high-purity medical-grade lines among certified German and Japanese producers. Distribution runs through regional coating compounders and adhesive formulators serving construction and automotive assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based formulation chemistry is disrupting solvent-borne systems as EPA VOC limits and REACH phthalate restrictions tighten compliance windows across industrialized markets. This regulatory inflection compresses timelines for resin qualification and elevates technical service intensity.
For Market Incumbents: Harden formulation chemistry expertise in aqueous-phase polymerization kinetics to defend against acrylic latex substitution in premium architectural coatings. Deepen backward integration into captive VCM supply to buffer margin predictability against ethylene cost volatility. Invest in EPD certification and cradle-to-gate carbon disclosure capabilities to meet EU Green Deal procurement requirements from German commercial real estate operators. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated construction chemicals sector by targeting water-based coating binder demand from Mumbai and Delhi NCR urban housing expansion. Qualify low-VOC formulations aligned with BIS standards convergence to international benchmarks. Pursue technical partnership positioning with regional adhesive formulators rather than direct commodity resin supply. For Investors and Strategic Acquirers: Capital is best deployed toward European and Japanese specialty producers commanding medical-grade purity premiums and automotive custom rheology capabilities. Long-term viability favors certified producers with verified process documentation over volume players exposed to commodity margin compression. Monitor ECHA SVHC designation expansion for vinyl chloride monomer residuals as a signal for purity standard escalation and supply consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCM Production | Captive raw material control buffers margin predictability against ethylene and chlorine input volatility. |
| Green Manufacturing Transition | Low-carbon process certifications satisfy EU Green Deal procurement requirements from German asset owners. |
| Long-term Supply Agreement | Contractual offtake with automotive OEMs secures volume visibility for custom rheology grade investments. |
| Joint Venture | Regional partnerships in India leverage Gujarat's chemical manufacturing belt for construction chemicals distribution. |
| Capacity Expansion | Micro-emulsion polymerization scale-up serves Japanese tier-one suppliers adopting sprayable solvent-free systems. |
Methodological Framework
Cross-validation between primary interviews with resin plant managers, procurement leads at downstream coating compounders, distribution channel partners, and technical R&D directors anchors the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and EPA regulatory dockets. Bottom-up demand modeling across formulation types and end-use industries triangulates against top-down market sizing from production capacity and trade flow analysis.
Calibration against historical price realization data and capacity utilization rates informs the projection framework across the analysis window. Segmentation dimensions include product grade tier, end-use industry, formulation chemistry, and regional production hub. CAGRs derive from elasticity-adjusted demand curves and substitution rate assumptions. Forecast inputs incorporate regulatory enforcement timelines from EPA and ECHA, plus China MEE dual carbon goal implementation pace.
Stress conditions across VCM feedstock cost bands, acrylic substitution penetration rates, and REACH SVHC designation expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about construction renovation cycle intensity and automotive solvent-phase-out schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Thermoplastic Edge Bands Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
United States Geopolymer Market