
 Cold Cast Elastomers Market | 2026-2036
Cold Cast Elastomers Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Cast Elastomers Market Outlook
Multi-source procurement for prepolymer feedstocks is decoupling from traditional single-source petrochemical contracts across the cold cast elastomers value chain. Covestro AG leverages its European MDI production network to sustain formulation consistency for high-performance polyurethane grades. Wanhua Chemical Group anchors regional supply security through backward integration into isocyanate manufacturing in China. Huntsman Corporation differentiates via specialized aliphatic systems that compete in optical clarity and UV stability segments.
Cold cast elastomers are two-component systems cured at ambient temperatures, typically combining polyol resins with isocyanate or amine curatives to achieve Shore hardness ranges from 10A to 90D without thermal processing equipment. These materials serve critical functions in precision mold fabrication, flexible sealing interfaces, and protective coatings where heat-sensitive substrates prohibit conventional vulcanization. Polyurethane formulations dominate volume consumption due to their tunable mechanical properties and established processing infrastructure across industrial mold-making operations. Silicone cold cast systems command premium positioning in healthcare and aerospace sealing applications where biocompatibility and thermal stability requirements exceed standard elastomer performance envelopes.
EPA regulations on volatile organic compound emissions from polyurethane manufacturing constrain formulation chemistry choices and production site permitting across the United States. REACH restrictions on aromatic amine curatives and isocyanate exposure limits under ECHA guidelines reshape product development priorities and worker safety protocols for European compounders. ISO 10993 biocompatibility standards govern healthcare-grade silicone elastomer qualification pathways, creating segmented compliance burdens between medical and industrial applications. Stakeholders must monitor evolving chemical hazard classifications and regional carbon border adjustments that will determine feedstock cost structures and competitive manufacturing locations.
Market Dynamics
Multi-source procurement for prepolymer feedstocks is decoupling from traditional single-source petrochemical contracts across the cold cast elastomers value chain, forcing compounders to restructure supply security around regional isocyanate networks and backward-integrated producers rather than spot market arbitrage.
Growth Catalysts
- REACH chemical compliance:Tightening ECHA restrictions on aromatic amine curatives are accelerating formulation shifts toward aliphatic polyurethane systems in European precision manufacturing clusters.
- Vibration-damping component demand:Automotive OEMs in Germany and China are expanding cold cast elastomer procurement for NVH reduction in electric vehicle platforms where thermal management constraints favor ambient-cure processing.
- East Asian mold-making concentration:Industrial clusters in China and South Korea are consolidating precision mold fabrication capacity, concentrating demand for high-replication-surface cold cast systems.
Market Restraints
- MDI supply concentration:European and Chinese producers control isocyanate feedstock availability, exposing compounders to input cost volatility and allocation risk during petrochemical turnarounds.
- EPA VOC emissions constraints:United States manufacturing site permitting under federal air quality standards limits formulation chemistry choices and constrains greenfield capacity expansion.
- Conventional vulcanization substitution:Heat-stable substrates in high-volume automotive sealing applications continue to favor traditional rubber molding where thermal processing equipment is already sunk.
Strategic Opportunities
- Healthcare biocompatibility standards:ISO 10993 qualification pathways for silicone cold cast systems create premium positioning in medical device sealing where thermoset alternatives face sterilization compatibility limits.
- Optical clarity segments:Aliphatic polyurethane formulations are penetrating aerospace transparency interlayers and display lamination applications where UV stability requirements exceed standard elastomer performance.
- Carbon border adjustment preparation:European compounders investing in renewable polyol feedstocks are positioning for EU carbon border mechanisms that will restructure feedstock cost competitiveness against imports.
Industry Challenges
- Isocyanate handling certification:Worker exposure limit compliance under ECHA and OSHA protocols requires specialized training infrastructure that constrains workforce scalability.
- Multi-tier supplier qualification:Automotive and medical OEMs are extending audit requirements to tier-three prepolymer sources, compressing certification timelines for new formulation approvals.
- Legacy equipment retrofit costs:Ambient-cure processing lines require different metering and mixing hardware than conventional vulcanization, creating capital intensity barriers for rubber compounders pivoting into polyurethane systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Cast Elastomers Market |
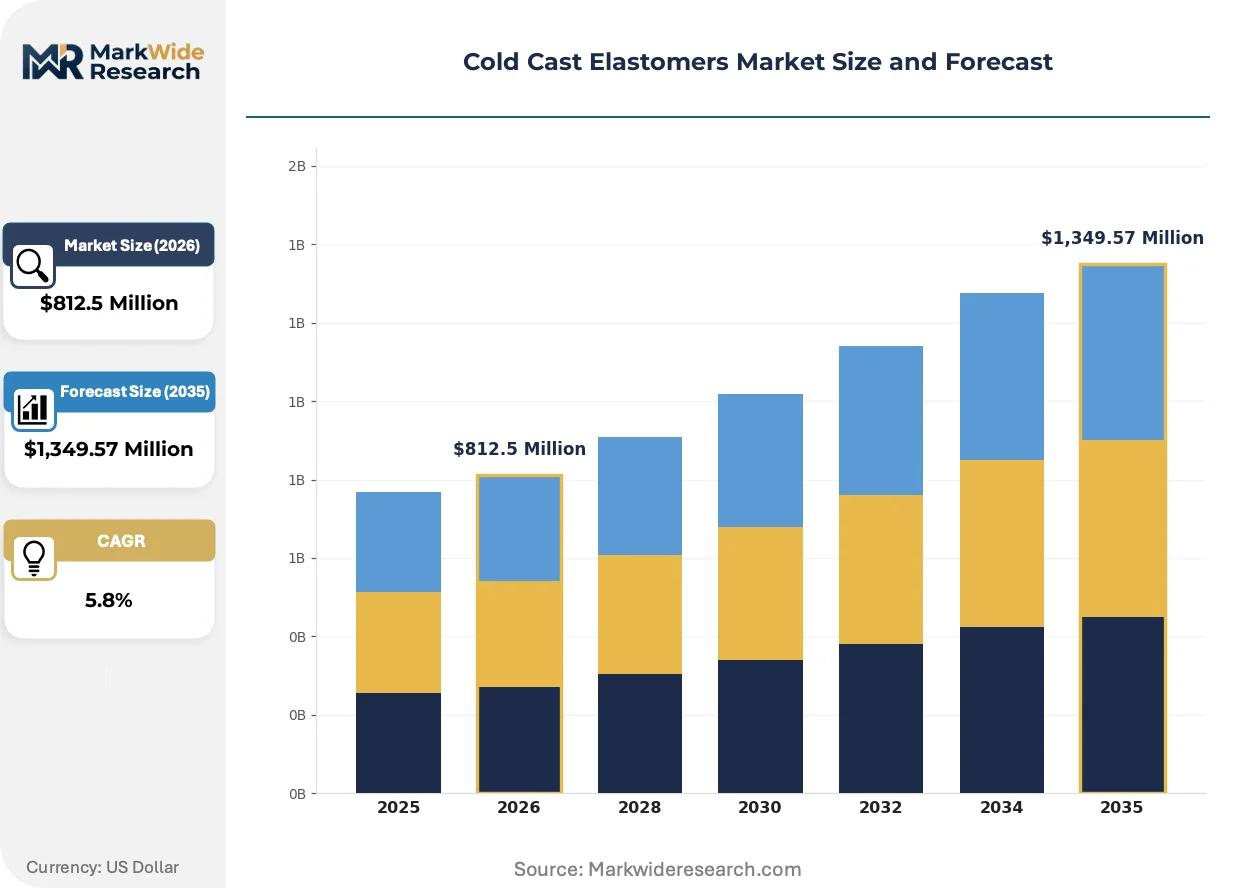
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,349.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Epoxy, Thermoplastic End User: Automotive, Aerospace, Healthcare, Consumer Goods Application: Mold Making, Sealing, Coating, Casting Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | BASF, Tosoh Corporation, Covestro AG, Wanhua Chemical Group, Mitsui Chemicals, Huntsman Corporation, Era Polymers, Coim Group, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Cast Elastomers Market Strategic Shifts
Digital formulation databases and predictive curing models are compressing development cycles for application-specific cold cast elastomers, enabling faster qualification against legacy thermoset benchmarks in precision manufacturing segments.
Aliphatic polyurethane cold cast systems are converging with optical lamination and display protection applications where UV stability and clarity specifications exceed conventional aromatic system capabilities. Aerospace transparency manufacturers and premium electronics assemblers are adopting these formulations at accelerated qualification paces. The technology is converging with established silicone cold cast infrastructure to create hybrid specification tiers that compress the premium positioning of legacy fluorosilicone alternatives.
REACH restrictions on aromatic amine curatives under ECHA guidelines are reshaping product development priorities and worker safety protocols for European compounders. Formulation chemistries are pivoting toward aliphatic isocyanate systems and blocked curative technologies that maintain processing windows while eliminating restricted substance classifications. Medical-grade silicone elastomer producers face segmented compliance burdens between industrial and healthcare applications, with ISO 10993 qualification creating divergent development pathways.
Buyer concentration among automotive tier-one suppliers is compressing procurement cycles and unbundling technical service from material supply contracts. Mold-making operations in China and Germany are consolidating vendor panels around compounders offering integrated design support and rapid prototyping capability. This pattern is most visible in East Asian industrial clusters where just-in-sequence manufacturing requirements favor suppliers with localized formulation laboratories and same-day compounding capacity.
Cold Cast Elastomers Market Segmentation
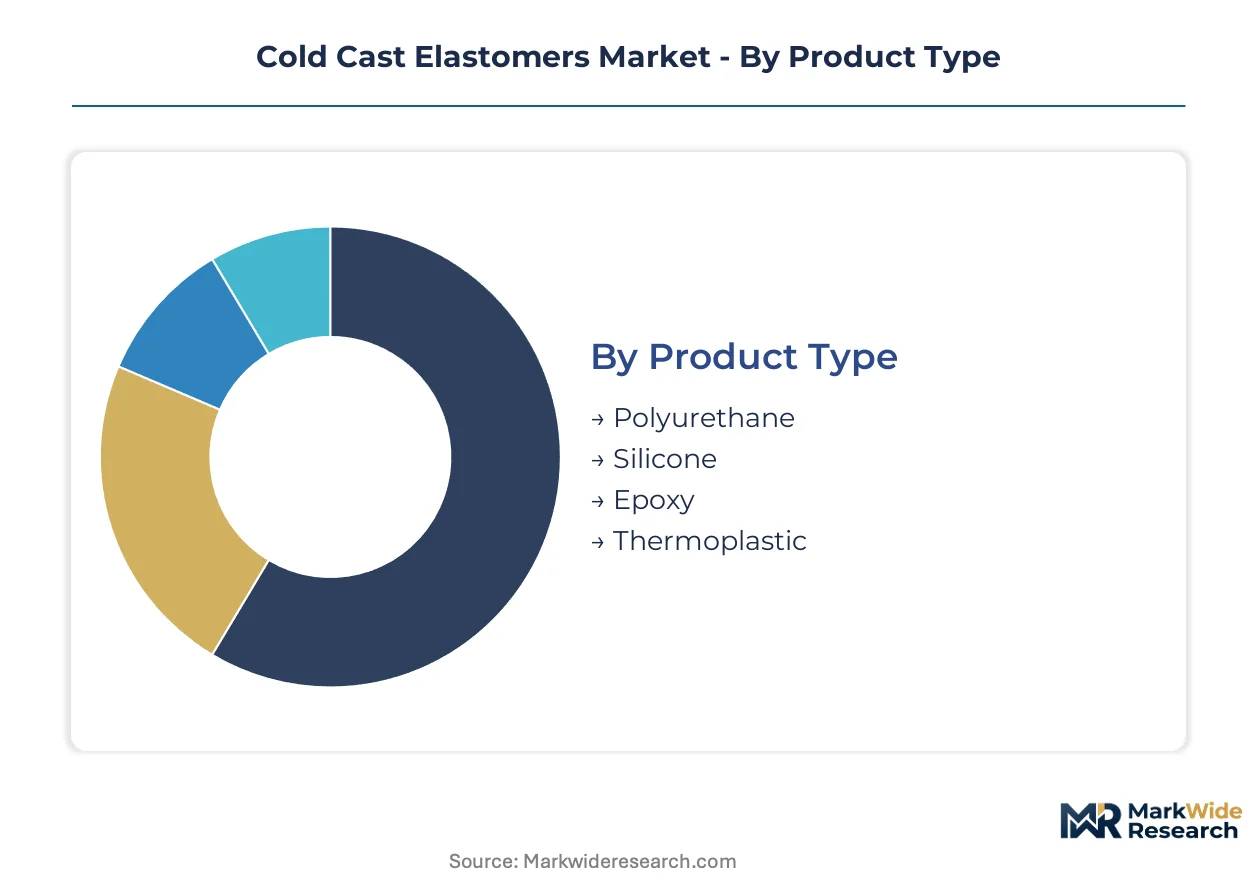
Cold cast elastomer procurement patterns diverge sharply across formulation chemistry and end-use compliance requirements. Specification-grade segmentation determines margin capture, with medical and aerospace applications commanding premium positioning against industrial mold-making volumes.
Product Type:
Formulation chemistry dictates processing infrastructure, cure kinetics, and regulatory compliance pathways across ambient-cure systems.
- Polyurethane:Two-component systems combining polyol resins with isocyanate curatives achieve Shore hardness from 10A to 90D without thermal equipment. Demand concentrates in German and Chinese automotive clusters where NVH-damping specifications favor tunable mechanical properties and established compounding infrastructure.
- Silicone:Platinum-catalyzed addition-cure formulations deliver biocompatibility and thermal stability from -60°C to 230°C. Healthcare device manufacturers in the United States and Europe specify these systems for sterilization-compatible sealing where ISO 10993 qualification creates segmented compliance burdens against industrial grades.
- Epoxy:Rigid ambient-cure systems serve electrical encapsulation and tooling applications requiring chemical resistance and dimensional stability.
- Thermoplastic:Reprocessable elastomer variants compete in prototyping and short-run manufacturing where material recovery reduces waste costs.
Mature deployment sits with polyurethane. Newer deployment is concentrated in silicone.
End User:
Customer verticals impose divergent qualification timelines, with automotive and medical OEMs extending audit requirements deep into prepolymer supply tiers.
- Automotive:Tier-one suppliers procure vibration-damping bushings, grommets, and flexible mounts for electric vehicle platforms. German and Chinese OEMs favor ambient-cure processing where thermal management constraints prohibit conventional vulcanization of heat-sensitive substrates.
- Aerospace:Transparency interlayers and sealing gaskets demand aliphatic polyurethane grades with UV stability and optical clarity specifications exceeding aromatic system capabilities.
- Healthcare:Medical-grade silicone systems face ISO 10993 biocompatibility qualification pathways that compress procurement to qualified compounders with dedicated cleanroom compounding.
- Consumer Goods:Molded grips, protective cases, and wearable interfaces prioritize cost-efficient processing over specification-grade certification.
Revenue concentration clusters in automotive. Steepest expansion trajectory appears in healthcare.
Application:
Functional use case determines surface replication fidelity, chemical exposure profiles, and thickness constraints across processing methods.
- Mold Making:High-replication-surface cold cast systems serve precision tooling for prototyping and short-run injection molding. East Asian industrial clusters in China and South Korea consolidate capacity here, concentrating demand for same-day compounding and localized formulation laboratories.
- Sealing:Gasket and O-ring applications span automotive fluid systems, aerospace pressure boundaries, and medical device interfaces. REACH restrictions on aromatic amine curatives under ECHA guidelines accelerate formulation shifts toward aliphatic systems in European precision manufacturing.
- Coating:Protective layers for abrasion resistance and chemical shielding deploy across industrial equipment and marine applications.
- Casting:Solid elastomer forms for rollers, wheels, and impact pads serve material handling and industrial automation.
Volume leadership belongs to mold making. Technology differentiation concentrates in sealing.
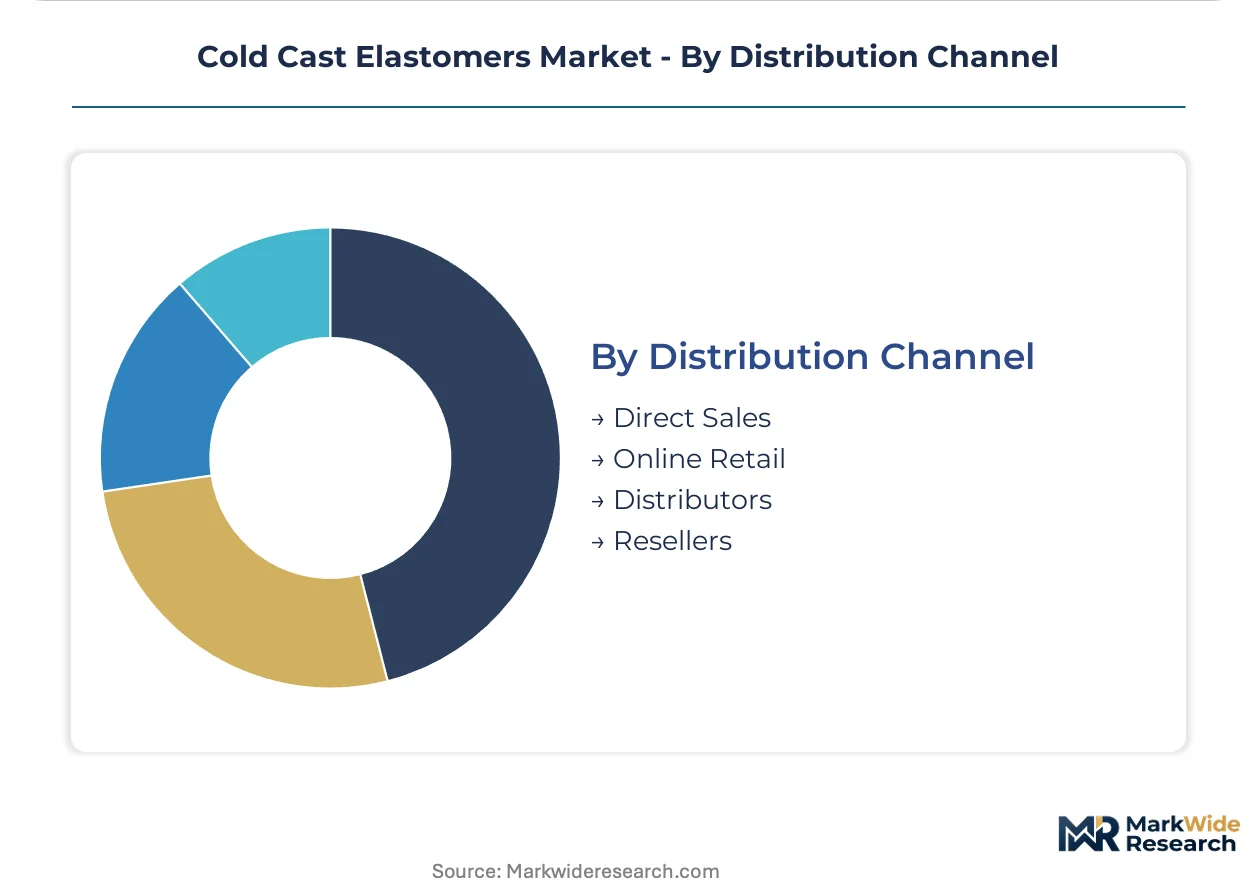
Distribution Channel:
Channel structure reflects technical service intensity, with specification-grade applications demanding integrated design support.
- Direct Sales:Compounders maintain technical service teams for automotive and medical OEMs requiring rapid prototyping and just-in-sequence delivery. German mold-making operations consolidate vendor panels around suppliers offering co-located formulation laboratories.
- Distributors:Regional stocking points serve industrial maintenance and repair operations with standardized grades and shorter lead times.
- Online Retail:Small-volume procurement for prototyping and hobbyist applications operates through specialty chemical platforms.
- Resellers:Value-added repackagers serve geographic markets lacking direct compounder presence.
Technical complexity favors direct sales. Geographic coverage expansion runs through distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isocyanate production networks in Germany and China anchor regional supply security for cold cast elastomer compounders, with MDI availability determining formulation economics across precision manufacturing clusters.
United States
Automotive tier-one suppliers in Michigan and Ohio procure vibration-damping bushings for electric vehicle platforms where thermal management constraints favor ambient-cure processing. EPA VOC emissions regulations under the Clean Air Act constrain formulation chemistry choices and manufacturing site permitting. Industrial mold-making operations in the Great Lakes region consolidate vendor panels around compounders offering rapid prototyping capability.
Germany
REACH restrictions on aromatic amine curatives under ECHA guidelines accelerate formulation shifts toward aliphatic polyurethane systems in precision manufacturing. Bavarian automotive OEMs expand cold cast elastomer procurement for NVH reduction components amid tightening chemical compliance requirements. The Stuttgart industrial cluster concentrates demand for high-replication-surface systems serving just-in-sequence manufacturing.
China
MIIT industrial standards and dual carbon goals reshape feedstock cost structures for polyurethane compounders in the Yangtze River Delta. Wanhua Chemical Group anchors regional supply security through backward integration into isocyanate manufacturing. East Asian mold-making capacity consolidates in Shanghai and Suzhou, concentrating demand for same-day compounding and localized formulation laboratories.
Japan
METI chemical handling protocols and JIS standards govern silicone cold cast system qualification for medical device sealing applications. Precision manufacturers in the Kanto region specify platinum-catalyzed formulations for sterilization-compatible interfaces. The Osaka-Kobe industrial corridor serves aerospace transparency interlayers demanding UV stability and optical clarity specifications.
South Korea
MFDS biocompatibility standards create segmented compliance pathways for healthcare-grade silicone elastomers against industrial grades. Automotive suppliers in the Busan-Ulsan corridor procure flexible mounts for electric vehicle thermal management systems. The Seoul Capital Area concentrates precision mold fabrication capacity, driving demand for high-replication-surface cold cast systems.
Cold Cast Elastomers Market Competitive Environment
Global majors compete with regional champions across isocyanate feedstock access and formulation specialization, creating a tiered structure where scale-driven producers coexist with application-specific compounders. Market concentration clusters around backward-integrated chemical conglomerates controlling MDI supply and independent formulators serving niche compliance segments. Three archetypes dominate: petrochemical-integrated producers, specialized aliphatic system developers, and medical-grade silicone qualification specialists. Competitive dynamics center on multi-source procurement restructuring and regional laboratory co-location for just-in-sequence delivery.
Within the petrochemical-integrated tier, BASF and Covestro AG represent European-scale producers anchoring formulation consistency through captive isocyanate networks. Wanhua Chemical Group exemplifies the Asia-Pacific archetype of regional supply security through upstream chemical manufacturing. Among specialty formulators, Huntsman Corporation occupies a position in aliphatic polyurethane segments where UV stability requirements exceed conventional system capabilities.
| Leading Market Players |
|---|
| BASF |
| Tosoh Corporation |
| Covestro AG |
| Wanhua Chemical Group |
| Mitsui Chemicals |
| Huntsman Corporation |
| Era Polymers |
| Coim Group |
| LANXESS |
| Others |
Value Chain & Pricing Dynamics
Backward integration into isocyanate manufacturing anchors both supply security and pricing leverage for compounders serving automotive and medical OEMs. Wanhua Chemical Group and Covestro AG leverage captive MDI networks to buffer formulation costs against petrochemical volatility, while independent compounders face compressed margins from feedstock spot market exposure.
Pricing Analysis
Technical service bundling separates premium compounders from commodity suppliers in cold cast elastomer procurement. Three-tier pricing structure across specification-grade, industrial-grade, and prototyping-grade levels reflects ISO 10993 certification investment and same-day compounding capability. Price differentiation hinges on REACH compliance documentation and localized laboratory co-location. Cost compression in industrial-grade polyurethane runs through MDI allocation constraints during petrochemical turnarounds. Automotive tier-one suppliers exhibit highest price sensitivity, while medical device manufacturers prioritize qualification speed over unit economics.
Supply Chain Analysis
Scrap prepolymer reclamation and off-grade material reprocessing flow through specialized compounders in Germany and China. MDI feedstock draws from concentrated production networks in China, Germany, and the United States. Key inputs include aromatic and aliphatic isocyanates, polyol resins, and platinum catalysts for silicone systems. Single-source vulnerability concentrates around European MDI producers during scheduled maintenance periods. Distribution runs through direct technical sales for specification-grade applications and regional distributors for industrial maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold cast elastomers are displacing conventional vulcanized rubber in heat-sensitive substrate applications, with aliphatic polyurethane systems capturing share from aromatic alternatives under tightening chemical compliance regimes.
For Market Incumbents: Deepen backward integration into specialty isocyanate grades to defend formulation consistency against emerging Chinese producers. Expand cleanroom compounding capacity for ISO 10993-qualified silicone systems before medical OEMs consolidate vendor panels. Anchor procurement relationships through co-located formulation laboratories in Stuttgart and Shanghai industrial clusters. For New Entrants and Emerging Players: REACH restrictions in Europe open a window for aliphatic system specialists to capture share from legacy aromatic compounders facing reformulation timelines. Target aerospace transparency interlayers and display lamination applications where UV stability specifications exceed incumbent capabilities. Enter through rapid prototyping partnerships with East Asian mold-making clusters lacking same-day compounding alternatives. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to petrochemical conglomerates seeking formulation expertise. Long-term viability favors compounders with dual capability across polyurethane and silicone chemistries. Watch ECHA hazard classification updates for aromatic amines as inflection indicators for aliphatic system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Manufacturing | Wanhua Chemical Group's captive MDI supply anchors cost competitiveness against import-dependent compounders. |
| ISO 10993 Qualification Investment | Medical-grade silicone certification creates segmented procurement pathways that compress vendor panels to qualified suppliers. |
| Regional Laboratory Co-location | Same-day formulation capability in Shanghai and Stuttgart secures just-in-sequence supply contracts with automotive OEMs. |
| Aliphatic System Development | REACH-compliant polyurethane grades capture aerospace transparency applications from legacy aromatic alternatives. |
| Scrap Prepolymer Reprocessing Network | Specialized reclaim operations in Germany reduce virgin material costs for industrial-grade mold-making compounds. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cold cast elastomers assessment. Primary interviews with polyurethane plant managers, automotive Tier 1 procurement leads, medical device regulatory affairs directors, and distribution channel partners validated formulation demand patterns. Bottom-up segmentation modeling triangulated against top-down petrochemical feedstock consumption data from ECHA chemical safety dossiers and MIIT industrial statistics.
Data-stream reconciliation across prepolymer production volumes, compounder shipment records, and end-use procurement databases established the analytical framework. Segmentation dimensions include formulation chemistry, Shore hardness grade, compliance tier, and regional manufacturing cluster. CAGRs derived from trend extrapolation of isocyanate consumption patterns and OEM contract award timelines. Forecast inputs incorporated REACH restriction implementation schedules and electric vehicle platform rollout assumptions.
The model assumes a particular technology adoption path; alternative pathways for platinum-catalyzed silicone systems would alter the outlook if medical device sterilization standards shift toward gamma-compatible alternatives. Forecasts reflect assumptions about ECHA enforcement intensity and MDI capacity expansion timelines. Practitioners should monitor aromatic amine hazard reclassification proceedings and carbon border adjustment implementation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Elastomeric Membrane
Silicone Elastomers Market
Elastomeric Membrane
Global Flexible Elastomeric Foam Market
Elastomeric Membrane
Modified Silicone Fluids Market
Elastomeric Membrane
Thermoplastic Polyester Elastomer Market
Elastomeric Membrane
Chlorinated Polyethylene Resins and Elastomers (CPE) Market
Elastomeric Membrane
Thermo Elastic Acrylic Market
Elastomeric Membrane
Asia-Pacific Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Global Elastomeric Sealants Market
Elastomeric Membrane
Vinyl Terminated Polydimethylsiloxane Market
Elastomeric Membrane
Styrene Ethylene Butylene Styrene (SEBS) Market
Elastomeric Membrane
Stretchable Conductive Material Market
Elastomeric Membrane
Elastomeric Polyolefins Market
Elastomeric Membrane
Polyolefin Elastomer Market
Elastomeric Membrane
Middle-East and Africa Thermoplastic Elastomer (TPE) Market
Elastomeric Membrane
Ethylene Propylene Diene Monomer(EPDM) Market
Elastomeric Membrane
Butyl Elastomers Market