
 Antimicrobial Plastics Market | 2026-2036
Antimicrobial Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Plastics Market Intelligence
The ISO 22196 standard for antibacterial activity measurement is reorganizing the competitive landscape by setting a verifiable performance benchmark. Clariant AG leverages its extensive masterbatch portfolio to serve a wide range of industrial applications. Microban International differentiates through its strong brand recognition and co-branding partnerships with consumer goods companies. BASF SE sustains its position through continuous R&D in advanced polymer additives and antimicrobial agents.
Antimicrobial plastics are polymers compounded with additives that inhibit the growth of bacteria, mold, and fungi on the material's surface. These agents, such as silver ions, are incorporated directly into the polymer matrix during manufacturing to ensure lasting efficacy. Commodity polymers like polypropylene and polyethylene constitute the largest volume due to their use in high-turnover applications. Silver ion technology commands a premium for its broad-spectrum efficacy and durability, particularly in food packaging and building materials.
Regulatory frameworks, including the US Environmental Protection Agency's registration process and Europe's REACH regulation under ECHA, govern the use of specific biocidal agents. China's NMPA also sets stringent requirements for materials used in medical devices, shaping market access. Material suppliers must navigate these divergent regional compliance pathways while innovating to meet demands for non-leaching and more sustainable antimicrobial solutions.
Market Dynamics
The proliferation of verifiable performance standards, led by the ISO 22196 testing protocol, is the central force shaping the antimicrobial plastics market. This move toward quantifiable efficacy is compelling material suppliers to invest in advanced testing and validation, separating premium, data-backed solutions from unverified claims.
Growth Catalysts
- Healthcare Infection Control:Heightened focus on mitigating healthcare-associated infections (HAIs) in hospitals and clinical settings drives adoption in medical devices, hospital furniture, and high-touch surfaces.
- Food Safety Regulations:Stringent food contact material regulations from bodies like the US FDA and the European Food Safety Authority (EFSA) encourage the use of antimicrobial plastics in packaging to extend shelf life and prevent microbial contamination.
- Consumer Goods Differentiation:Demand from manufacturing centers in China and Southeast Asia for value-added features in electronics, appliances, and children's products creates a significant pull for plastics with antimicrobial properties.
Market Restraints
- High Additive Costs:The premium price of high-efficacy antimicrobial agents, particularly silver-ion-based technologies, increases the final cost of plastic components, limiting adoption in price-sensitive commodity applications.
- Complex Regulatory Approvals:Navigating the divergent and stringent registration processes for biocidal additives, such as the US EPA's framework and Europe's REACH regulation under ECHA, creates significant compliance burdens and time-to-market delays.
- Potential for Biocidal Leaching:Concerns over the long-term environmental impact and potential health effects of biocidal agents leaching from plastic surfaces constrain material selection, particularly for food-contact and single-use items.
Strategic Opportunities
- Non-Leaching Technologies:Development of covalently-bonded or non-leaching antimicrobial surfaces that inhibit microbial growth without releasing active agents presents a significant opportunity to address environmental and health concerns.
- Automotive Interior Applications:Growing consumer interest in cabin hygiene and shared mobility models creates an opportunity for antimicrobial plastics in high-touch automotive components like steering wheels, dashboards, and upholstery.
- Sustainable and Bio-Based Agents:Formulating antimicrobial solutions derived from natural sources or integrating them into biodegradable polymers aligns with market-wide sustainability goals, opening new avenues in green-certified products.
Industry Challenges
- Harmonization of Testing Standards:Discrepancies between regional testing protocols and efficacy standards create confusion for buyers and add complexity for manufacturers seeking to validate and market their products on a global scale.
- End-of-Life Management:Developing effective recycling streams for antimicrobial plastics is a challenge, as the presence of biocidal additives can complicate reprocessing and limit the usability of recycled material.
- Consumer Education on Efficacy:Communicating the specific benefits and limitations of antimicrobial plastics to end-users, and managing expectations about their role in a broader hygiene strategy, remains a persistent market challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Plastics Market |
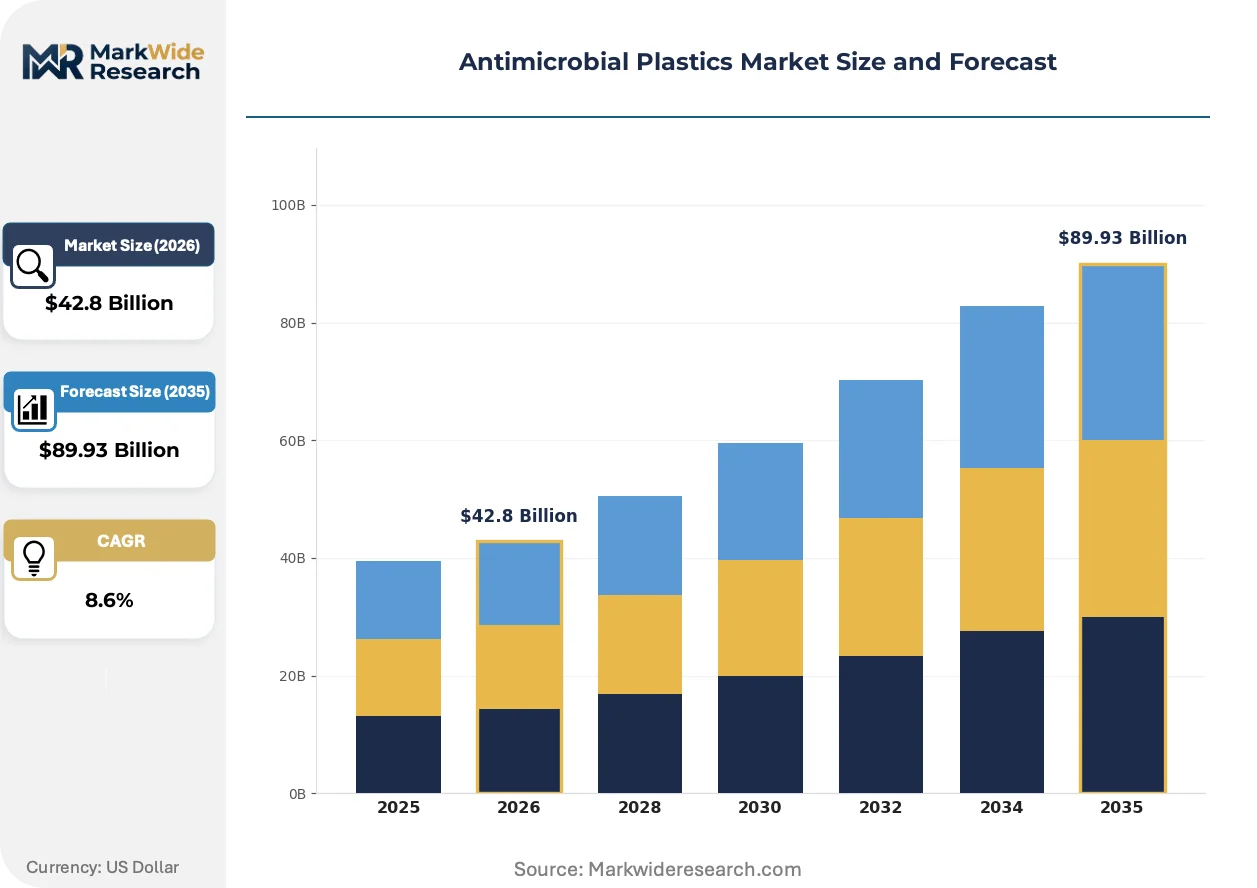
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $89.93 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene, Acrylonitrile Butadiene Styrene Technology: Silver Ion, Copper Ion, Zinc Oxide, Triclosan, Quaternary Ammonium Compounds Application: Food Packaging, Personal Protective Equipment, Electronics Components, Sports Goods, Building Materials End User Industry: Consumer Goods Manufacturers, Electronics Assemblers, Construction Firms, Sports Equipment Producers, Packaging Suppliers |
| Companies Covered | BioCote Limited, Clariant AG, Microban International, RTP Company, Covestro AG, Avient Corporation, Sanitized AG, Lonza Group AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Plastics Market Strategic Shifts & Innovations
The market is advancing toward integrated solutions where antimicrobial functionality is combined with other material properties like durability and sustainability. This evolution is driven by regulatory pressures for safer, non-toxic agents and end-user demand for products with verifiable, long-lasting performance claims.
Advanced organic antimicrobial additives are being developed for applications where metal-ion leaching is a concern. Medical device manufacturers and food packaging converters are increasingly adopting these polymer-based or nature-inspired agents for their favorable safety profiles. This technology is displacing traditional heavy-metal compounds in sensitive applications, providing a solution that offers efficacy without contributing to heavy metal accumulation in the environment.
Europe's Biocidal Products Regulation (BPR) is mandating a more rigorous approval process for both the active biocidal substances and the finished articles treated with them. This forces manufacturers to provide extensive data on safety and efficacy to gain market access within the European Union. The regulation most heavily impacts non-EU suppliers, who must now invest significantly in compliance to continue selling into the region's high-value markets.
A notable shift in buyer behavior is the selection of antimicrobial additives based on the supplier's ability to provide co-branding rights and marketing support. This partnership model disrupts the conventional sale of additives as simple chemical inputs, replacing it with a value-added service offering. This trend is most prominent in the consumer electronics and building materials sectors, where a recognized antimicrobial brand logo can serve as a key purchasing driver for the end customer.
Antimicrobial Plastics Market Segmentation
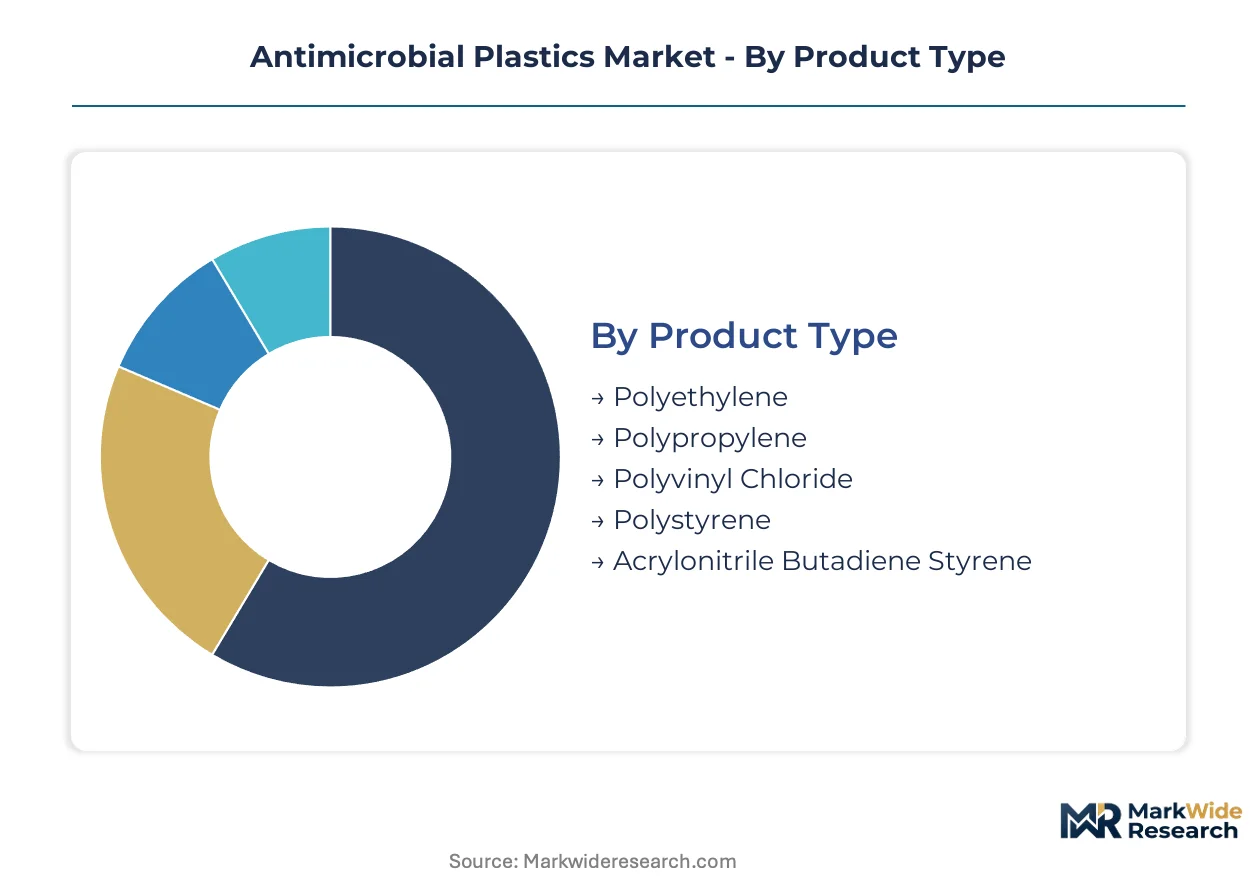
The antimicrobial plastics market is segmented by product type, technology, application, and end user industry, reflecting the diverse material requirements and functional demands across various sectors. Understanding these segments is crucial for identifying specific growth vectors and tailoring product development to meet specialized needs.
Product Type:
The distribution channels for antimicrobial plastics vary significantly by polymer type, influencing their market penetration across diverse applications.
- Polyethylene:Widely used in films, bags, and bottles, polyethylene benefits from antimicrobial integration to enhance food packaging safety and extend product shelf life. Regulatory approvals for food contact materials in the US and Europe are critical for market access.
- Polypropylene:This versatile commodity polymer is frequently compounded with antimicrobial agents for high-turnover consumer goods and automotive interiors. Its cost-effectiveness and mechanical properties drive its extensive use in packaging applications across China and Southeast Asia.
- Polyvinyl Chloride:PVC finds application in medical tubing, flooring, and wall coverings, where its durability is enhanced by antimicrobial properties for infection control.
- Polystyrene:Used in disposable food containers and consumer electronics casings, polystyrene benefits from antimicrobial additives for improved hygiene in high-contact items.
- Acrylonitrile Butadiene Styrene:ABS is valued for its strength and aesthetic appeal in electronics and automotive parts, where antimicrobial versions address surface hygiene.
Polypropylene dominates the installed base for antimicrobial plastics. Polyethylene is where expansion concentrates for food-contact applications.
Technology:
The choice of antimicrobial technology often dictates the target application and performance requirements, with varying efficacy and cost profiles.
- Silver Ion:Known for broad-spectrum antibacterial efficacy and durability, silver ions are incorporated into polymers for premium applications like medical devices and food packaging. Its high cost commands a premium, particularly in building materials in Germany and Japan.
- Copper Ion:Copper ions provide natural antimicrobial properties and are increasingly explored for high-touch surfaces in healthcare and public transport due to their biocidal activity. Research into non-leaching formulations is a priority for this technology.
- Zinc Oxide:Zinc oxide offers antimicrobial and UV-blocking properties, making it suitable for outdoor applications and specific medical textiles where broad-spectrum protection is required.
- Triclosan:Once widely used, triclosan faces increasing regulatory scrutiny and phase-outs in many regions, including parts of the US and EU, due to environmental and health concerns.
- Quaternary Ammonium Compounds:These organic agents offer effective antimicrobial properties and are increasingly adopted in high-touch surfaces and textiles due to their favorable safety profiles. Their utility spans consumer goods and healthcare settings across North America.
Silver ion technology maintains the highest average selling prices due to its broad efficacy. Quaternary ammonium compounds are gaining share fastest in cost-sensitive applications.
Application:
The volume of antimicrobial plastic consumption is directly tied to specific end-use applications, each with distinct performance and regulatory needs.
- Food Packaging:Antimicrobial plastics in food packaging extend shelf life and prevent microbial contamination, addressing stringent food safety regulations from the US FDA and EFSA. This application represents a significant demand driver in Europe and North America.
- Personal Protective Equipment:PPE such as masks, gloves, and gowns benefit from antimicrobial coatings or integrated additives to reduce microbial load and enhance user safety. The healthcare sector in India and Brazil drives this demand.
- Electronics Components:High-touch surfaces on smartphones, keyboards, and remote controls use antimicrobial plastics to improve user hygiene, especially in densely populated markets like China.
- Sports Goods:Equipment like helmets, grips, and protective gear utilize antimicrobial polymers to inhibit odor-causing bacteria and fungi, enhancing product longevity and user comfort.
- Building Materials:Used in high-traffic areas and public spaces, antimicrobial building materials enhance hygiene in hospitals, schools, and commercial properties. Demand for these materials is particularly strong in urban development projects in China and India.
Food packaging applications exhibit the deepest market penetration. Personal protective equipment shows the most significant potential for future market expansion.
End User Industry:
Different end-user industries procure antimicrobial plastics based on their specific product lines and consumer hygiene expectations.
- Consumer Goods Manufacturers:These firms integrate antimicrobial plastics into products like appliances, children's toys, and household items to offer enhanced hygiene and product differentiation. Manufacturing clusters in China and Southeast Asia are primary consumers.
- Electronics Assemblers:Companies producing consumer electronics and IT hardware incorporate antimicrobial materials into device casings and peripherals for improved user health and product appeal.
- Construction Firms:Building and construction companies use antimicrobial plastics in various components, including flooring, wall panels, and HVAC systems, to create healthier indoor environments.
- Sports Equipment Producers:Manufacturers of sporting goods and athletic wear employ antimicrobial plastics to address hygiene concerns related to sweat and frequent contact.
- Packaging Suppliers:Companies providing food and beverage packaging utilize antimicrobial polymers to meet regulatory requirements and consumer demand for extended freshness. This segment is driven by global food safety standards and supply chain efficiency.
Consumer goods manufacturers represent the largest customer base. Construction firms are strategically important for long-term infrastructure projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent regulatory frameworks globally are shaping the antimicrobial plastics market, compelling material suppliers to innovate. These regulations, from bodies like the US Environmental Protection Agency and Europe's ECHA, drive demand for compliant and effective solutions. Material suppliers must navigate diverse regional compliance pathways while developing new products.
United States
Healthcare infection control drives demand for antimicrobial plastics in the United States, particularly for medical devices and hospital surfaces. The US Food and Drug Administration's stringent food contact material regulations encourage adoption in packaging applications. Major medical device manufacturing clusters in California and Massachusetts integrate these materials for enhanced patient safety.
Germany
European Biocidal Products Regulation (BPR) mandates rigorous approval for antimicrobial substances and treated articles in Germany. Demand for silver ion technology is strong in building materials and medical devices, commanding a premium for its broad-spectrum efficacy. The chemical industry in North Rhine-Westphalia actively develops advanced polymer additives and sustainable solutions.
China
Manufacturing clusters in China exhibit significant consumption of antimicrobial plastics due to high electronics and consumer goods production. China's NMPA sets stringent requirements for medical device materials, influencing market access for foreign suppliers. Industrial hubs in the Yangtze River Delta integrate antimicrobial plastics into high-volume consumer products and electronics casings.
India
Heightened focus on mitigating healthcare-associated infections (HAIs) drives adoption in India's medical sector and personal protective equipment. India's Food Safety and Standards Authority (FSSAI) encourages antimicrobial plastics in food packaging to extend shelf life. Major urban development projects in Mumbai and Delhi use these materials for healthier public infrastructure components.
Japan
Consumer interest in hygiene and an aging population contribute to demand for antimicrobial plastics in Japan, especially in consumer electronics. METI supports research and development into advanced materials, including non-leaching formulations for sensitive applications. Industrial centers around Tokyo and Osaka lead in adopting silver ion technology for premium applications and high-touch surfaces.
Antimicrobial Plastics Market Key Industry Players
Player mix skews toward a blend of diversified chemical conglomerates and specialized additive producers. The market structure is characterized by both established players leveraging broad portfolios and niche innovators focusing on specific technologies. Key strategic archetypes include large-scale chemical producers, specialized additive manufacturers, and brand-focused co-branding partners. Competitive moves often involve continuous R&D in advanced polymer additives and strategic co-branding partnerships to differentiate offerings.
Specialized additive manufacturers, often exemplified by Microban International, differentiate through strong brand recognition and strategic co-branding partnerships, particularly with consumer goods companies seeking verifiable hygiene features. Diversified chemical giants, such as BASF SE, sustain their market position through continuous research and development in advanced polymer additives and antimicrobial agents, focusing on broad-spectrum efficacy and material integration. Companies like Clariant AG, recognized for their masterbatch production capabilities, leverage extensive portfolios to serve a wide range of industrial applications, providing tailored solutions for various polymer types and end-use sectors.
| Leading Market Players |
|---|
| BioCote Limited |
| Clariant AG |
| Microban International |
| RTP Company |
| Covestro AG |
| Avient Corporation |
| Sanitized AG |
| Lonza Group AG |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Thirty days of inventory for specialized antimicrobial additives significantly influence pricing power for advanced material suppliers, as supply concentration in key manufacturing regions can create upward pressure on costs for downstream users.
Pricing Analysis
Cost-plus contracts, often indexed to polymer resin and silver commodity prices, dominate transactions for antimicrobial plastics. Price differentiation stems from certified broad-spectrum efficacy, particularly for silver ion technology, and the ability to provide co-branding rights. Pricing pressure stems from stringent regulatory scrutiny of older biocidal agents, forcing investment into higher-cost, compliant alternatives. Commodity applications, like basic polyethylene films, exhibit the highest price sensitivity, while medical device manufacturers demonstrate lower sensitivity due to critical performance requirements.
Supply Chain Analysis
Logistics chokepoints in key Asian manufacturing hubs, particularly the Yangtze River Delta, underpin the supply chain for high-volume antimicrobial polypropylene. The market draws from raw material dependencies including specialized polymer resins and silver precursors, primarily sourced from China and Germany. Regulatory restriction on specific biocidal agents poses a structural risk, necessitating rapid reformulation or re-certification. Distribution runs through a hybrid model, with direct sales to large-scale compounders and specialized distributors serving smaller OEM and end-user markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antimicrobial plastics market stands at a platform-economics inflection, driven by the increasing interoperability between material science and verifiable performance standards like ISO 22196.
For Market Incumbents: Consolidate market share by acquiring niche additive producers specializing in non-leaching technologies. This move counters the threat of regulatory phase-outs for conventional agents and leverages R&D in sustainable solutions. Investing in advanced testing and certification capabilities, particularly for Europe's BPR compliance, enhances competitive positioning against emerging alternatives. Control over key distribution channels through co-branding partnerships reinforces market presence.
For New Entrants and Emerging Players: Differentiate on verifiable sustainability credentials, targeting the bio-based polymer segment. This strategy addresses environmental concerns and positions new players in green-certified products. The most penetrable segment lies in specialized medical textiles and cost-sensitive applications within Southeast Asian markets. A focused go-to-market angle involves direct partnerships with consumer goods companies prioritizing eco-friendly and health-conscious product lines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core polymer additive divisions. These assets often possess proprietary technologies or established regulatory approvals. Long-term viability rests on sustained demand for hygiene solutions across healthcare and consumer sectors. A key signal to watch is the rapid growth in green certifications for antimicrobial products, indicating market acceptance of sustainable formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Non-Leaching Additives | Increases supply of environmentally compliant materials, meeting stringent regulatory demands for food contact. |
| Joint Venture for Bio-Based Polymer Integration | Accelerates development of sustainable antimicrobial solutions, aligning with global environmental objectives. |
| Strategic Partnership with Medical Device OEMs | Ensures early adoption of advanced antimicrobial plastics, enhancing patient safety in critical applications. |
| Investment in ISO 22196 Testing Facilities | Provides verifiable performance data, differentiating products in a market driven by efficacy benchmarks. |
| Acquisition of Specialty Biocide Manufacturer | Secures proprietary technology and regulatory expertise, reducing time-to-market for innovative solutions. |
Research Approach
Initial hypotheses were tested against primary input from polymer compounders, food packaging converters, medical device manufacturers, and regulatory affairs specialists, then refined. Secondary validation drew from US EPA registrations, ECHA REACH dossiers, ISO standards documents, and national statistical agency reports. A rigorous bottom-up and top-down triangulation approach reconciled discrepancies between primary insights and published data.
Variance decomposition across the analysis window isolates the impact of technological advancements and regulatory shifts on market evolution. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user industry, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected market drivers, incorporating polymer resin price fluctuations and biocidal agent approval rates as key forecast inputs.
Material uncertainties — including unforeseen shifts in global trade policies or rapid biocidal agent bans — sit outside the modeled envelope. Forecasts reflect underlying assumptions regarding regulatory stability and technological adoption rates. Revision becomes warranted when regulatory frameworks or raw material supply dynamics cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Europe Engineering Plastics Market