
 North America Braze Alloys Market | 2026-2036
North America Braze Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
North America Braze Alloys Market Analytics
Aftermarket service revenue for braze alloy reclamation and reconditioning is tilting toward original equipment suppliers with captive metallurgical capabilities. Lucas-Milhaupt, Inc. leverages its Wisconsin-based wire and ribbon production to dominate North American HVAC supply channels. Johnson Matthey sustains premium positioning through specialized precious-metal brazing formulations for aerospace turbine applications. Harris Products Group anchors its competitive stance with extensive distributor relationships and broad copper-phosphorus alloy availability.
North America braze alloys are metal filler materials, typically with melting points above 450°C but below those of base metals, engineered to create metallurgical bonds through capillary flow during controlled thermal cycles. Silver-copper-zinc compositions remain prevalent for high-strength joints in pressure systems and electronic assemblies. Nickel-based alloys command structural importance in aerospace applications due to superior oxidation resistance and creep performance at elevated temperatures. Aluminum brazing alloys represent the fastest-growing product category as electric vehicle thermal management systems expand radiator and heat exchanger production. Wires and rods occupy the largest form share, though pastes gain traction in automated electronics assembly for precise deposition control.
FAA airworthiness directives and NHTSA safety standards govern alloy qualification pathways for transportation applications, creating multi-year certification barriers for new suppliers. EPA enforcement of the AIM Act refrigerant transition compels HVAC manufacturers to validate braze joint integrity with alternative working fluids. OSHA workplace exposure limits for cadmium and zinc oxide fumes influence shop-floor alloy selection and ventilation investment across fabrication facilities. Stakeholders must monitor how evolving Department of Energy appliance efficiency rules reshape heat exchanger designs and corresponding brazing specifications.
Market Dynamics
Heat pump deployment across the United States and Canada is forcing HVAC equipment manufacturers to expand braze alloy procurement, while EPA refrigerant phase-down rules under the AIM Act reshape brazing specifications for lower-global-warming-potential systems.
Growth Catalysts
- AIM Act refrigerant transition:EPA enforcement of hydrofluorocarbon phase-down rules compels HVAC manufacturers to validate braze joint integrity with alternative working fluids, expanding alloy testing protocols.
- Electric vehicle thermal management:Automotive OEMs are scaling aluminum brazing alloy consumption for radiator and heat exchanger production in battery cooling systems.
- Great Lakes industrial corridor concentration:Dense supplier networks in Michigan, Ohio, and Ontario sustain captive metallurgical capabilities for automotive and aerospace OEMs.
Market Restraints
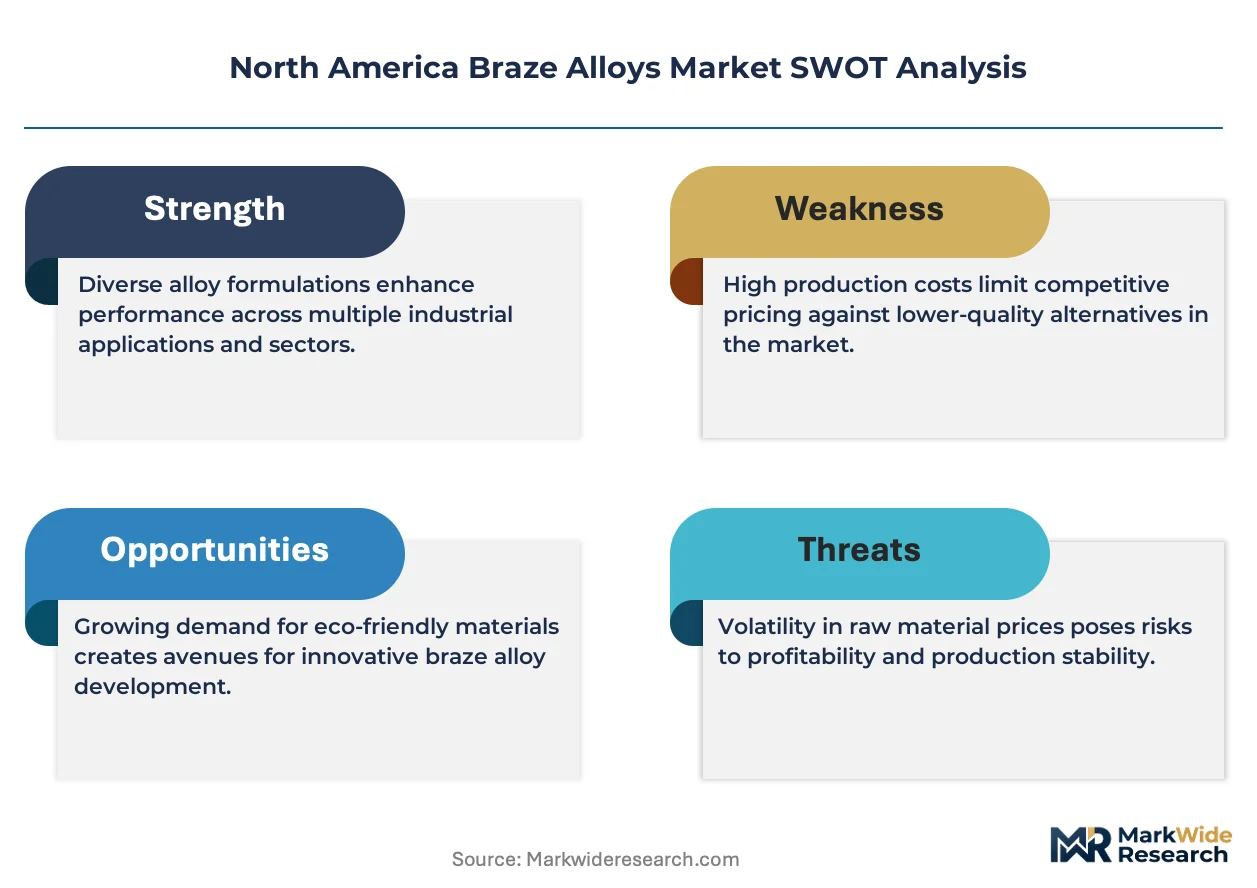
- Silver price volatility:Fluctuations in precious metal markets compress margins for silver-copper-zinc alloy producers serving pressure system applications.
- Supply concentration in Wisconsin wire production:Dominant wire and ribbon manufacturing in a single state creates geographic vulnerability for North American HVAC supply channels.
- Cadmium workplace exposure limits:OSHA fume restrictions force fabrication facilities to invest in ventilation upgrades or switch to alternative alloy formulations.
Strategic Opportunities
- Canadian heat pump acceleration:Federal and provincial decarbonization incentives in Ontario and Quebec are expanding residential and commercial HVAC retrofit markets.
- Precise deposition control in electronics:Automated assembly lines are adopting brazing pastes for microelectronics joints, displacing traditional wire-fed processes.
- Aerospace nickel alloy specialization:FAA airworthiness directives create multi-year certification barriers that reward suppliers with established turbine application portfolios.
Industry Challenges
- FAA certification timelines:New suppliers face multi-year alloy qualification pathways for transportation applications, locking out entrants without existing metallurgical validation records.
- Department of Energy efficiency rule uncertainty:Evolving appliance efficiency standards force heat exchanger redesign cycles that outpace brazing specification stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Braze Alloys Market |
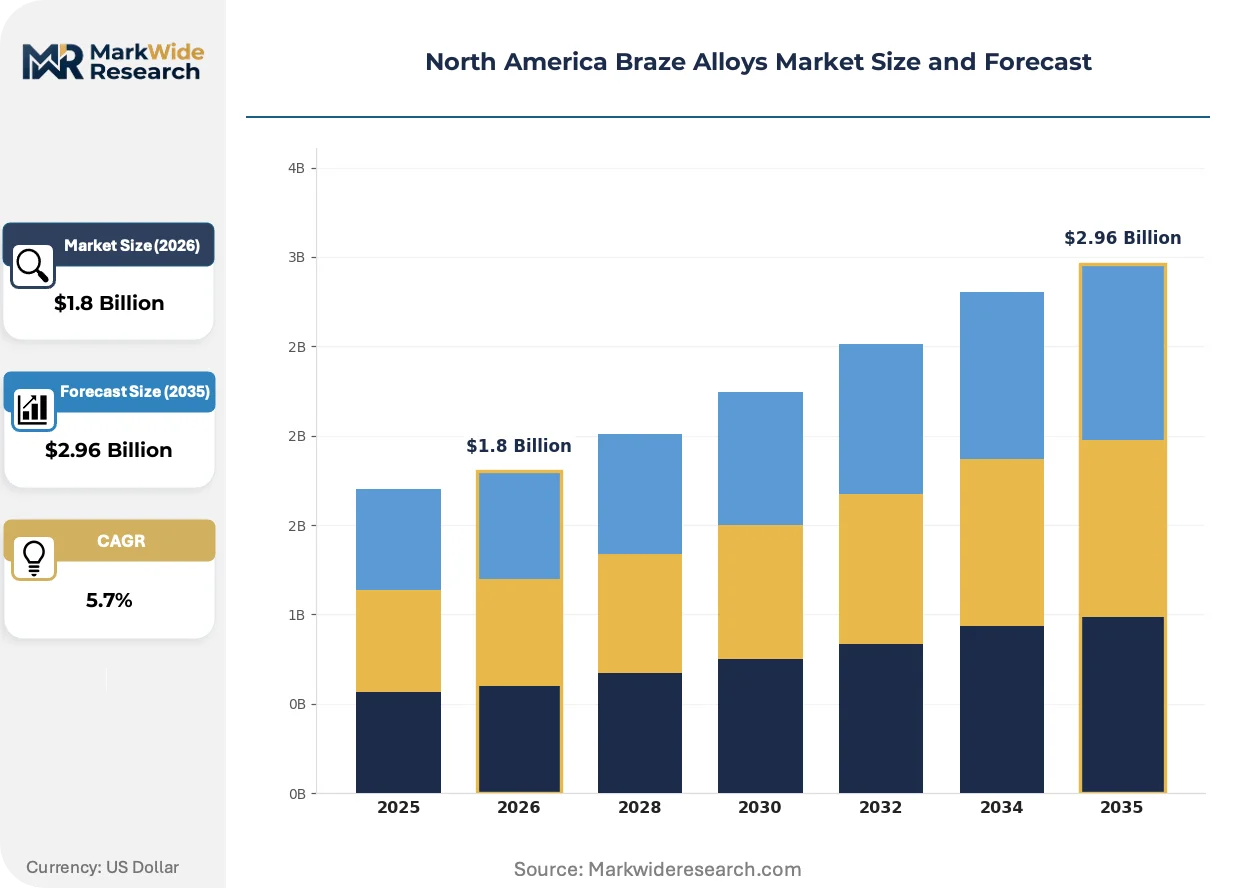
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Non-Ferrous, Copper, Nickel, Aluminum Application: Aerospace, Automotive, Electronics, HVAC End User: Manufacturers, Service Centers, Distributors, Contractors Form: Wires, Rods, Foils, Pastes |
| Companies Covered | Johnson Matthey, Lucas-Milhaupt, Inc., Harris Products Group, Aimtek, Inc., Morgan Advanced Materials, OC Oerlikon Management AG, Sulzer Ltd, Belmont Metals, Prince & Izant Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Braze Alloys Market Evolving Landscape
Controlled atmosphere brazing and active filler metal technologies are compressing thermal cycle times while expanding joint performance envelopes for next-generation heat exchangers and electronic assemblies.
Active brazing alloys containing titanium or zirconium wet ceramic and composite surfaces without metallization pretreatment. Aerospace turbine manufacturers in Connecticut and Arizona are adopting these formulations for ceramic matrix composite joining. The technology is rendering obsolete traditional nickel-based pre-placement methods that required surface preparation steps.
EPA enforcement of the AIM Act refrigerant phase-down is tightening hydrofluorocarbon allocation rules through 2036. HVAC manufacturers must requalify braze joint integrity with R-454B and R-32 working fluids. United States residential heat pump assemblers are accelerating corrosion-resistant alloy validation to meet 2027 compliance deadlines.
Aftermarket service revenue for braze alloy reclamation is consolidating toward original equipment suppliers with captive metallurgical capabilities. Independent distributors face margin compression as HVAC OEMs internalize wire and ribbon reconditioning. This pattern is most visible in the United States Great Lakes corridor, where Lucas-Milhaupt and Harris Products Group have vertically integrated reclamation services.
North America Braze Alloys Market Segmentation
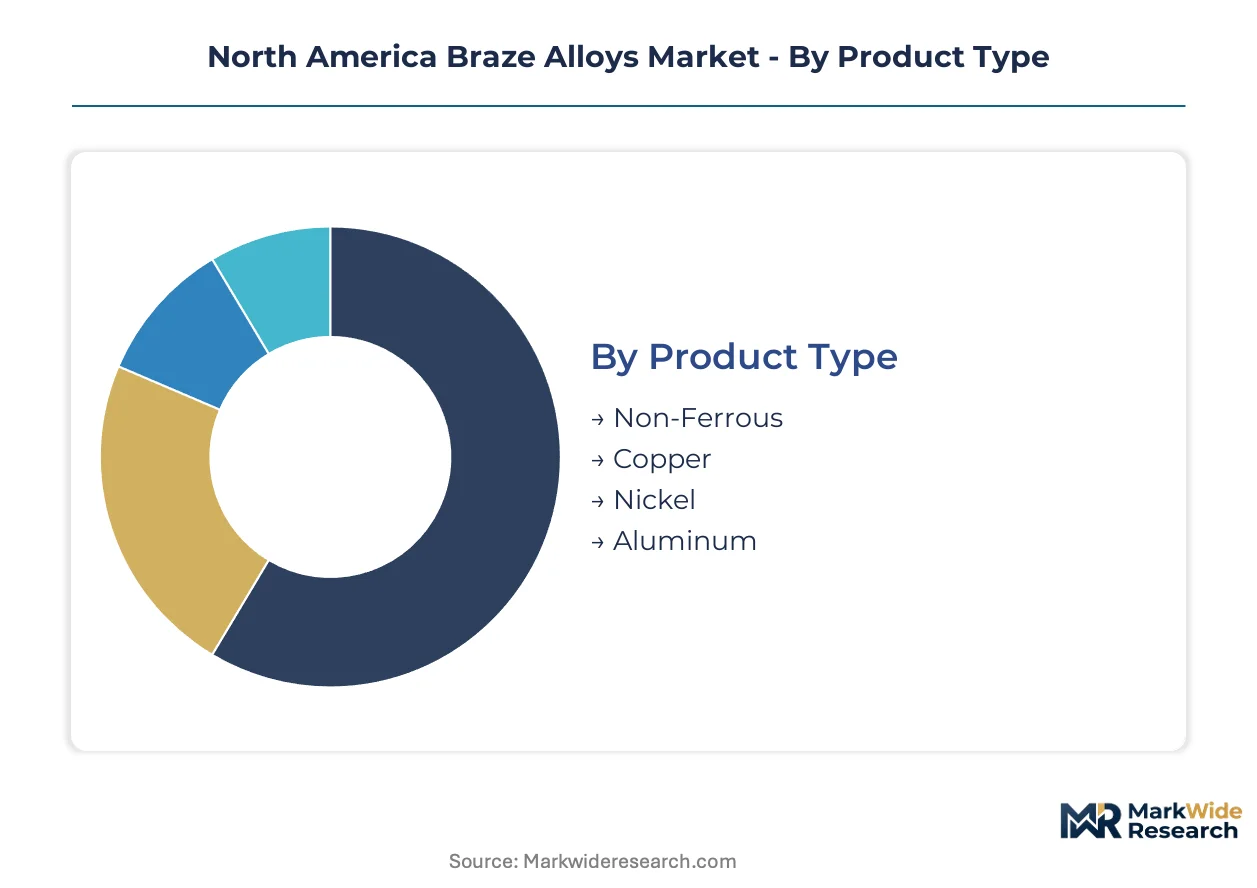
North American braze alloy procurement patterns diverge sharply across product chemistry, physical form, and end-use certification requirements. Each segmentation axis reveals distinct margin structures and supply chain configurations that shape supplier competitive positioning.
Product Type:
Alloy selection spans a use-case spectrum from high-volume HVAC joining to precision aerospace turbine applications, with base metal chemistry determining thermal performance envelopes and regulatory compliance pathways.
- Non-Ferrous:Silver-copper-zinc formulations dominate pressure system brazing with melting points optimized for capillary flow in refrigerant circuits. Demand concentrates in the U.S. Great Lakes corridor where HVAC OEMs validate joint integrity against EPA AIM Act refrigerant transition timelines.
- Aluminum:Silicon-modified aluminum alloys enable fluxless brazing of heat exchanger cores for electric vehicle battery thermal management. Automotive OEMs in Michigan and Ontario are scaling procurement as EV production lines expand radiator assembly capacity.
- Copper:Phosphorus-bearing copper alloys deliver self-fluxing characteristics for plumbing and HVAC tube joining without separate flux application.
- Nickel:Chromium-boron-silicon compositions withstand oxidation and creep at turbine operating temperatures, requiring FAA airworthiness directive compliance for aerospace applications.
The dominant share belongs to non-ferrous alloys, while aluminum is closing the gap fastest.
Application:
End-use verticals impose divergent certification burdens and volume economics, with transportation and building equipment representing contrasting procurement rhythms.
- HVAC:Heat pump deployment across the United States and Canada is accelerating alloy consumption for evaporator and condenser coil assembly. EPA refrigerant phase-down rules under the AIM Act compel manufacturers to requalify braze joint integrity with R-454B and R-32 working fluids.
- Automotive:Battery electric vehicle thermal management systems are displacing traditional internal combustion cooling architectures, redirecting alloy demand toward aluminum-intensive heat exchanger designs.
- Aerospace:Turbine blade and combustor component joining requires nickel-based alloys with FAA-mandated metallurgical validation records spanning multi-year qualification cycles.
- Electronics:Miniaturized power module and semiconductor packaging applications favor precise deposition control through paste formulations rather than wire-fed processes.
HVAC commands the largest volume position, though automotive applications are expanding most quickly.
End User:
Procurement authority sits at different supply chain nodes depending on alloy specification complexity and reclamation value.
- Manufacturers:OEMs with captive metallurgical capabilities internalize alloy selection for critical joints, particularly in aerospace and automotive verticals where FAA and NHTSA standards govern qualification.
- Service Centers:Regional metal distributors maintain inventory positions for standard copper-phosphorus and silver-bearing formulations serving job shop fabrication.
- Distributors:Independent channel partners face margin compression as HVAC OEMs vertically integrate wire and ribbon reconditioning services.
- Contractors:Field installation crews procure consumable alloys for aftermarket repair and retrofit, with OSHA cadmium exposure limits influencing shop-floor formulation choices.
Manufacturers retain pricing power on specification-driven alloys, while distributors compete on availability for commodity grades.
Form:
Physical configuration determines deposition method, automation compatibility, and inventory carrying cost structures across the value chain.
- Wires:Continuous feedstock dominates automated HVAC coil manufacturing and manual torch brazing operations, with Wisconsin-based production anchoring North American supply.
- Pastes:Controlled rheology formulations enable stencil printing and syringe dispensing for electronics assembly, gaining share in microelectronics joints requiring precise volume deposition.
- Rods:Hand-fed stick forms serve field repair and maintenance applications where portability outweighs automation efficiency.
- Foils:Preform geometries eliminate manual alloy measurement for high-volume heat exchanger core assembly, reducing joint variability in controlled atmosphere brazing furnaces.
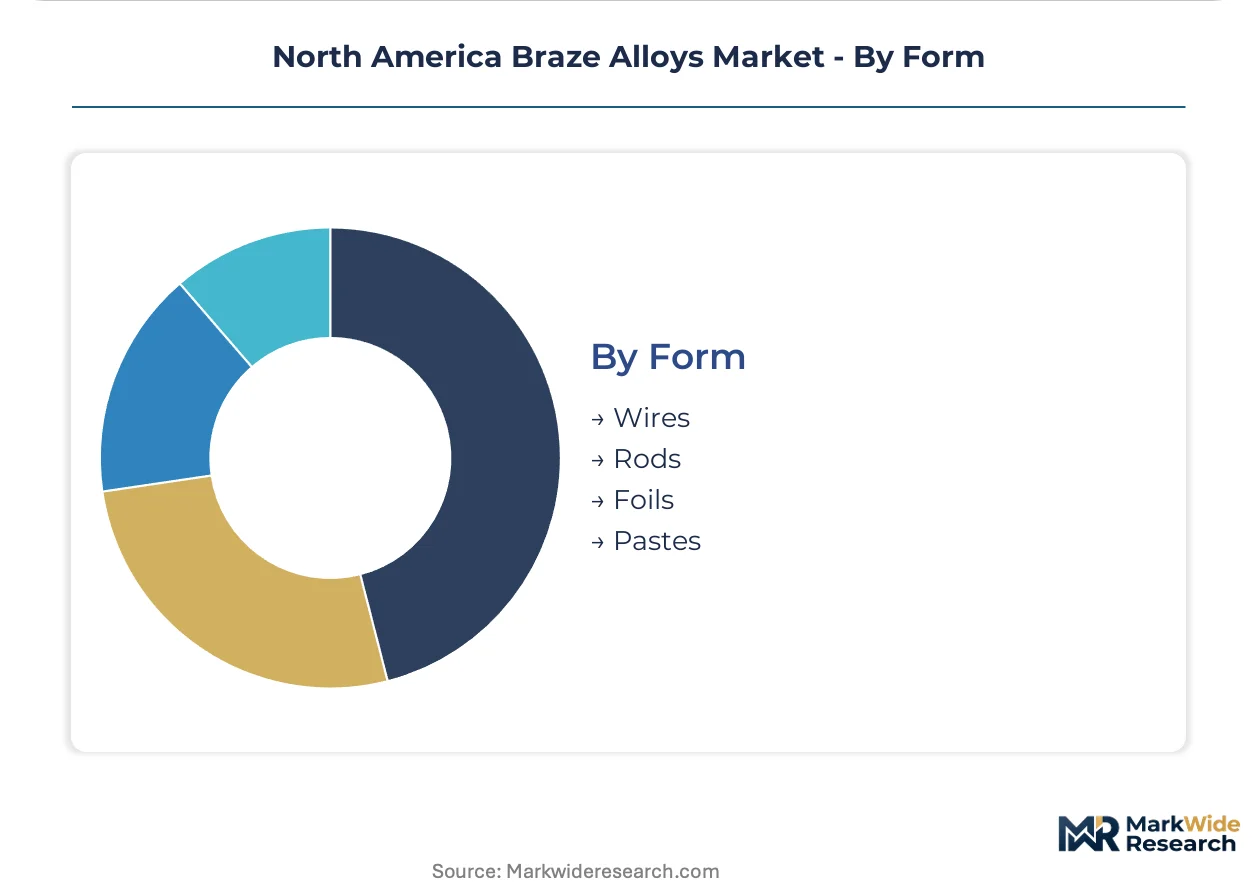
Wires maintain the volume leadership position, while pastes are gaining share fastest in automated electronics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply, with the United States driving HVAC and aerospace demand through federal energy policy, while Canada accelerates heat pump deployment through provincial decarbonization mandates.
United States
Heat pump manufacturing and aerospace turbine production dominate alloy consumption. EPA enforcement of AIM Act refrigerant phase-down rules compels HVAC manufacturers to revalidate braze joint integrity with R-454B and R-32 working fluids. The Great Lakes industrial corridor—spanning Michigan, Ohio, and Wisconsin—hosts dense supplier networks where automotive and aerospace OEMs maintain captive metallurgical capabilities.
Canada
Federal and provincial decarbonization incentives in Ontario and Quebec are expanding residential and commercial HVAC retrofit markets. Environment and Climate Change Canada aligns refrigerant transition timelines with EPA regulations, forcing manufacturers to synchronize cross-border product validation. The Ontario manufacturing belt around Toronto sustains alloy fabrication capacity serving both domestic demand and U.S. supply chain integration.
Mexico
Automotive thermal management component assembly is scaling in Nuevo León and Bajío Region facilities supplying U.S. electric vehicle production lines. Mexican environmental regulators are adopting refrigerant transition schedules compatible with U.S. AIM Act timelines. Querétaro and Guanajuato industrial parks attract HVAC component manufacturers seeking tariff-advantaged access to North American markets.
North America Braze Alloys Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The North American braze alloys market structures around three distinct player categories: precious-metal formulation specialists, high-volume non-ferrous producers, and regional distribution-focused fabricators. Competitive dynamics favor backward integration into captive metallurgical services and geographic consolidation near Great Lakes industrial demand clusters.
Among precious-metal and specialized alloy developers, Johnson Matthey and Lucas-Milhaupt, Inc. exemplify divergent strategic positions—Johnson Matthey occupying premium-tier aerospace certification pathways, while Lucas-Milhaupt anchors high-volume HVAC supply channels through Wisconsin-based wire production. Harris Products Group represents the distribution-integrated archetype, leveraging broad copper-phosphorus alloy availability and extensive distributor relationships to defend position in commodity-grade segments.
| Leading Market Players |
|---|
| Johnson Matthey |
| Lucas-Milhaupt, Inc. |
| Harris Products Group |
| Aimtek, Inc. |
| Morgan Advanced Materials |
| OC Oerlikon Management AG |
| Sulzer Ltd |
| Belmont Metals |
| Prince & Izant Company |
| Others |
Value Network & Pricing Analysis
Wisconsin-based wire and ribbon production anchors North American HVAC supply channels, concentrating margin capture with Lucas-Milhaupt and Harris Products Group while independent distributors face compression from OEM reclamation services. Silver price volatility in precious metal markets feeds directly into cost structures for silver-copper-zinc alloy producers, forcing contract renegotiation cycles that favor vertically integrated suppliers with captive metallurgical capabilities.
Pricing Analysis
Long-term offtake agreements dominate procurement between Great Lakes automotive OEMs and nickel-based alloy suppliers, insulating aerospace turbine manufacturers from silver spot market swings while locking in multi-year validation commitments. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified nickel formulations from commodity copper-phosphorus grades and reclamation-sourced wire products. Cost compression in silver-bearing alloys is intensifying because precious metal volatility compresses margins for pressure system applications. Job shop fabricators and field contractors exhibit highest price sensitivity, while aerospace OEMs prioritize certification continuity over unit cost.
Supply Chain Analysis
Extended payment terms from HVAC OEMs are squeezing working capital for regional distributors, accelerating consolidation toward suppliers with supply-chain finance facilities or captive banking relationships. Raw material sourcing draws from Mexican copper concentrate, Canadian nickel mining operations, and domestic silver refining capacity concentrated in the western United States. Single-source vulnerability concentrates in Wisconsin wire production, where geographic clustering creates disruption risk from regional weather or labor events. Distribution runs through authorized distributor networks for standard grades, while specification-driven alloys move through direct OEM procurement channels with metallurgical validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical joining and adhesive bonding technologies threaten brazed joint share in lightweight automotive assemblies, compelling alloy suppliers to defend metallurgical performance advantages through certification investment and thermal cycle optimization.
For Market Incumbents: Build certification moats around FAA airworthiness directives and EPA AIM Act refrigerant validation timelines, extending multi-year qualification barriers that lock out entrants without existing metallurgical records. Backward integration into captive reclamation services captures aftermarket revenue streams from HVAC OEMs internalizing wire reconditioning, while channel control over Great Lakes distributor networks defends commodity-grade market position against price-driven competitors.
For New Entrants and Emerging Players: Pursue aluminum brazing alloy specialization for electric vehicle thermal management systems, where automotive OEMs in Michigan and Ontario are scaling radiator assembly capacity with less entrenched supplier relationships. Target Canadian provincial decarbonization incentives in Quebec and Ontario, where federal heat pump acceleration creates white-space demand with synchronized EPA-Environment and Climate Change Canada regulatory timelines. Go-to-market through direct technical sales to Tier 2 HVAC component manufacturers bypasses incumbent distributor lock-in.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap alloy formulators with existing aerospace validation records and underutilized capacity in the Great Lakes corridor, where consolidation synergies overlap with EPA refrigerant transition-driven retooling cycles. Long-term viability hinges on positioning for sustained heat pump deployment and EV thermal management expansion rather than cyclical HVAC replacement demand. Monitor Environment and Climate Change Canada alignment with EPA AIM Act enforcement as inflection signal for cross-border supply chain integration intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reclamation Services | Captures aftermarket revenue from HVAC OEMs internalizing wire reconditioning in the Great Lakes corridor. |
| Aluminum Alloy Capacity Expansion | Addresses silicon-modified aluminum demand from Michigan and Ontario EV battery thermal management production. |
| FAA Certification Investment | Extends multi-year qualification barriers that protect nickel-based alloy margins in Connecticut and Arizona turbine manufacturing. |
| Long-term Supply Agreement | Locks in offtake commitments from automotive OEMs scaling heat exchanger assembly for refrigerant transition timelines. |
| Joint Venture | Combines Wisconsin wire production expertise with Canadian provincial incentive access for cross-border HVAC retrofit markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EPA enforcement documentation, FAA airworthiness directives, and HVAC OEM procurement disclosures, triangulating bottom-up alloy consumption estimates with top-down market sizing. Primary interviews engaged metallurgical engineering directors at aerospace turbine manufacturers, procurement leads at automotive thermal management divisions, HVAC OEM supply chain executives, and regional distributor principals across the Great Lakes corridor. Secondary validation incorporated customs and trade data, OSHA workplace exposure records, and Department of Energy appliance efficiency rulemaking dockets.
Forecast inputs include alloy chemistry segmentation, physical form factor adoption curves, end-use certification requirements, and regional production cluster concentration across the projection horizon. Modeled dimensions span product type, application vertical, procurement authority node, and deposition method compatibility. CAGRs were derived from regression analysis against heat pump deployment trajectories, EV production scaling, and refrigerant phase-down compliance deadlines. Industry-specific inputs incorporate EPA AIM Act enforcement intensity and FAA certification backlog duration.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese aluminum alloy producers or accelerated adhesive bonding adoption in automotive lightweighting would shift outcomes. Macroeconomic deviation in precious metal markets, regulatory acceleration in refrigerant transition timelines, or technological breakthrough in active filler metal deposition would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Polymer Blends Alloys Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Structural Power Composites Market
Advanced Alloys
Steel Fiber Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Nickel Superalloy Market
Advanced Alloys
Super Alloys Market
Advanced Alloys
Ultra High Strength Steel Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Tungsten Alloy Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Asia-Pacific Green Steel Market
Advanced Alloys
Nickel Alloy Market