
 Global Medical Superabsorbent Polymers Market | 2026-2036
Global Medical Superabsorbent Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Superabsorbent Polymers Market Foresight
Modular dressing formats with integrated superabsorbent layers is broadening procurement options for hospital systems seeking to reduce SKU complexity. BASF SE leverages its polymer science heritage to sustain leadership in crosslinked polyacrylate grades for exuding wounds. Evonik Industries AG anchors its position through high-purity resin platforms tailored to sterile medical applications. Nippon Shokubai Co., Ltd. competes on manufacturing scale in Asia-Pacific supply corridors.
Medical superabsorbent polymers are lightly crosslinked hydrophilic networks engineered to absorb and retain aqueous solutions at multiples of their dry mass, typically achieving fluid retention capacities exceeding 50 grams per gram in standard physiological saline tests. These materials function primarily to manage exudate in wound care, control moisture in surgical environments, and maintain skin integrity in incontinence products. Crosslinked Polyacrylate dominates current revenue pools due to its established clinical track record and manufacturing economies, while Surface Crosslinked SAP variants are gaining fastest in advanced wound care where directional absorption and reduced gel blocking improve patient outcomes. The Therapy Area dimension shows Wound Care commanding the largest addressable base, though Incontinence Management presents expanding volume opportunity as home-based elder care protocols proliferate.
The FDA governs these materials as device components or accessories under 21 CFR quality system regulations, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for polymer-containing products marketed in Europe. ISO 10993 biocompatibility testing series provides the harmonized framework manufacturers use to demonstrate cytotoxicity and sensitization safety across jurisdictions. Stakeholders must monitor evolving EPA and REACH chemical registration thresholds for residual monomer content, as tightening toxicological standards could reshape acceptable feedstock specifications and reformulation timelines.
Market Dynamics
EU Medical Device Regulation is tightening biocompatibility testing protocols, forcing reformulation cycles and clinical evidence upgrades for polymer-containing wound care products across European supply chains.
Growth Catalysts
- Chronic Disease Prevalence:Aging populations in Germany, Japan, and the United States are generating sustained demand for advanced wound care and incontinence management solutions requiring superabsorbent polymer cores.
- REACH Chemical Registration:Evolving toxicological standards for residual monomer content are accelerating R&D investment in ultra-purity resin platforms that command premium positioning in sterile medical applications.
- Modular Dressing Formats:Hospital systems are consolidating procurement around integrated superabsorbent layers that reduce SKU complexity and simplify inventory management across wound care protocols.
Market Restraints
- Acrylic Acid Feedstock Volatility:Crosslinked polyacrylate production depends on petrochemical-derived monomers exposed to crude oil price swings and refinery capacity constraints.
- Supply Concentration Risk:Asia-Pacific manufacturing corridors dominate base resin output, creating geographic single-point vulnerabilities for European and North American formulators.
- Gel Blocking Limitations:Conventional superabsorbent polymers suffer from surface gel formation that restricts fluid wicking in high-exudate wound scenarios, limiting clinical efficacy.
Strategic Opportunities
- Home-Based Elder Care Expansion:Brazil and Mexico present underpenetrated volume opportunity as informal caregiving transitions to structured home health protocols requiring disposable incontinence products.
- Surface Crosslinked SAP Convergence:Directional absorption technologies are converging with antimicrobial silver-ion integration to create next-generation dressings for infected wound management.
- ISO 10993 Harmonization:Streamlined biocompatibility testing frameworks are reducing regulatory friction for manufacturers seeking multi-jurisdictional product registrations.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with crosslinked hydrogel expertise are concentrated in German and Japanese research clusters, constraining expansion timelines for new market entrants.
- MDR Certification Timelines:Extended clinical evidence requirements under EU Medical Device Regulation are stretching product launch cycles and freezing development capital for 18-24 month periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Superabsorbent Polymers Market |
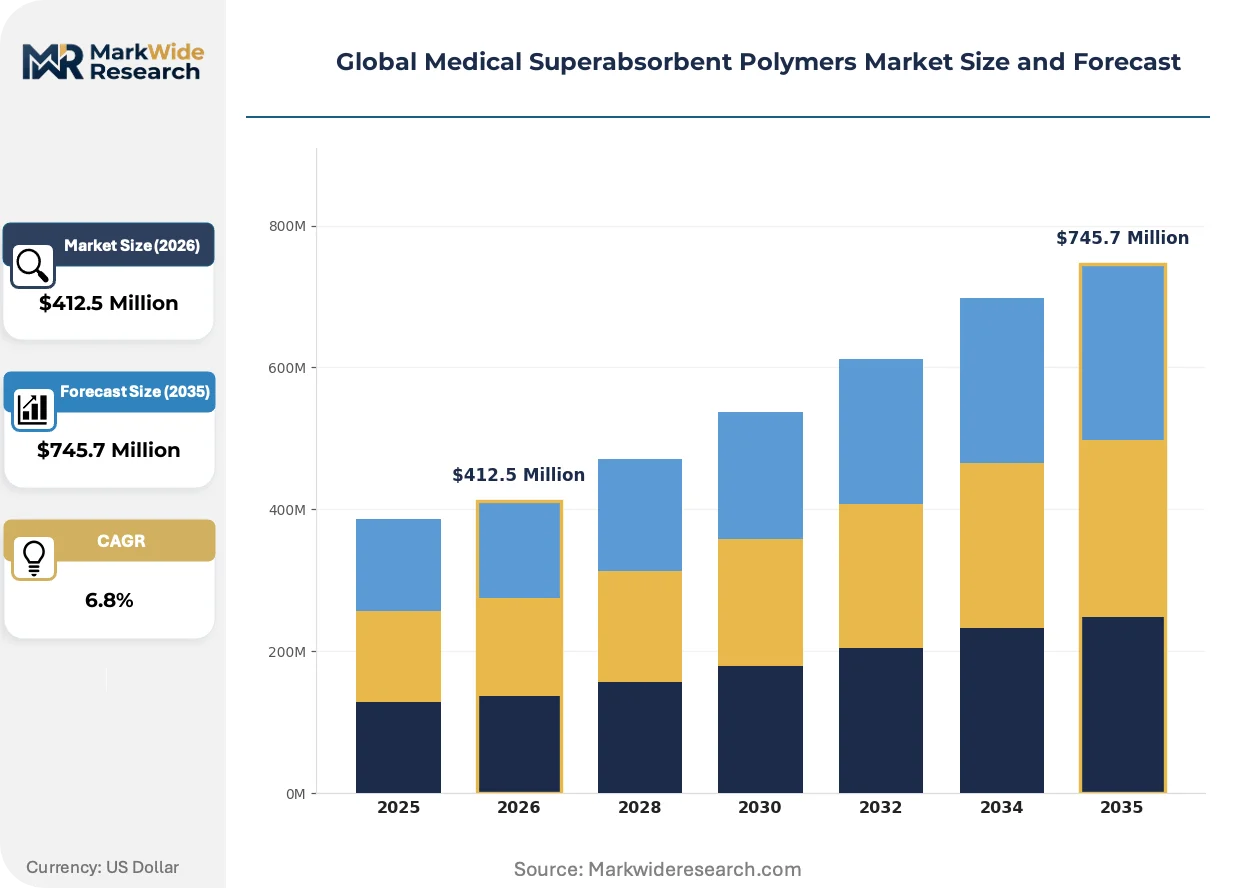
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crosslinked Polyacrylate, Polyvinyl Alcohol, Grafted Starch, Surface Crosslinked SAP Therapy Area: Wound Care, Surgical Drapes, Odor Control, Incontinence Management, Absorbent Dressings End User: Hospitals, Ambulatory Surgery Centers, Rehabilitation Clinics, Diagnostic Laboratories Deployment: Sterile Packaging, Bulk Formulation, Single-Use Systems, Reusable Applications |
| Companies Covered | BASF SE, Evonik Industries AG, Nippon Shokubai Co., Ltd., LG Chem, SDP Global Co., Ltd., Sumitomo Seika Chemicals Co., Ltd., Kao Corporation, Formosa Plastics Corporation, Yixing Danson Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Superabsorbent Polymers Market Shifts & Advancements
Surface-engineered superabsorbent architectures are displacing conventional bulk-crosslinked materials as wound care manufacturers prioritize directional fluid management and reduced maceration risk in chronic wound protocols.
Zwitterionic surface modifications are absorbing protein and cellular debris while maintaining hydration balance at the wound interface. Advanced wound care centers in the United States and Germany are piloting these materials for diabetic foot ulcer protocols. This absorption dynamic is compressing demand for traditional hydrocolloid dressings that lack active exudate modulation.
EU Medical Device Regulation Annex I general safety and performance requirements are mandating enhanced clinical evidence for polymer-containing devices marketed in Europe. Manufacturers must now submit biocompatibility data packages covering cytotoxicity, sensitization, and irritation endpoints. Implantable and long-wear topical applications face the steepest compliance burdens, with notified bodies extending review timelines.
Hospital purchasing consortia are consolidating supplier relationships around full-category vendors capable of delivering integrated dressing systems rather than component materials. Group purchasing organizations in the United States are favoring contracts with polymer suppliers who provide technical support for finished device validation. This concentration pattern is most visible in integrated delivery networks across Texas and California seeking to reduce qualification overhead.
Global Medical Superabsorbent Polymers Market Segmentation
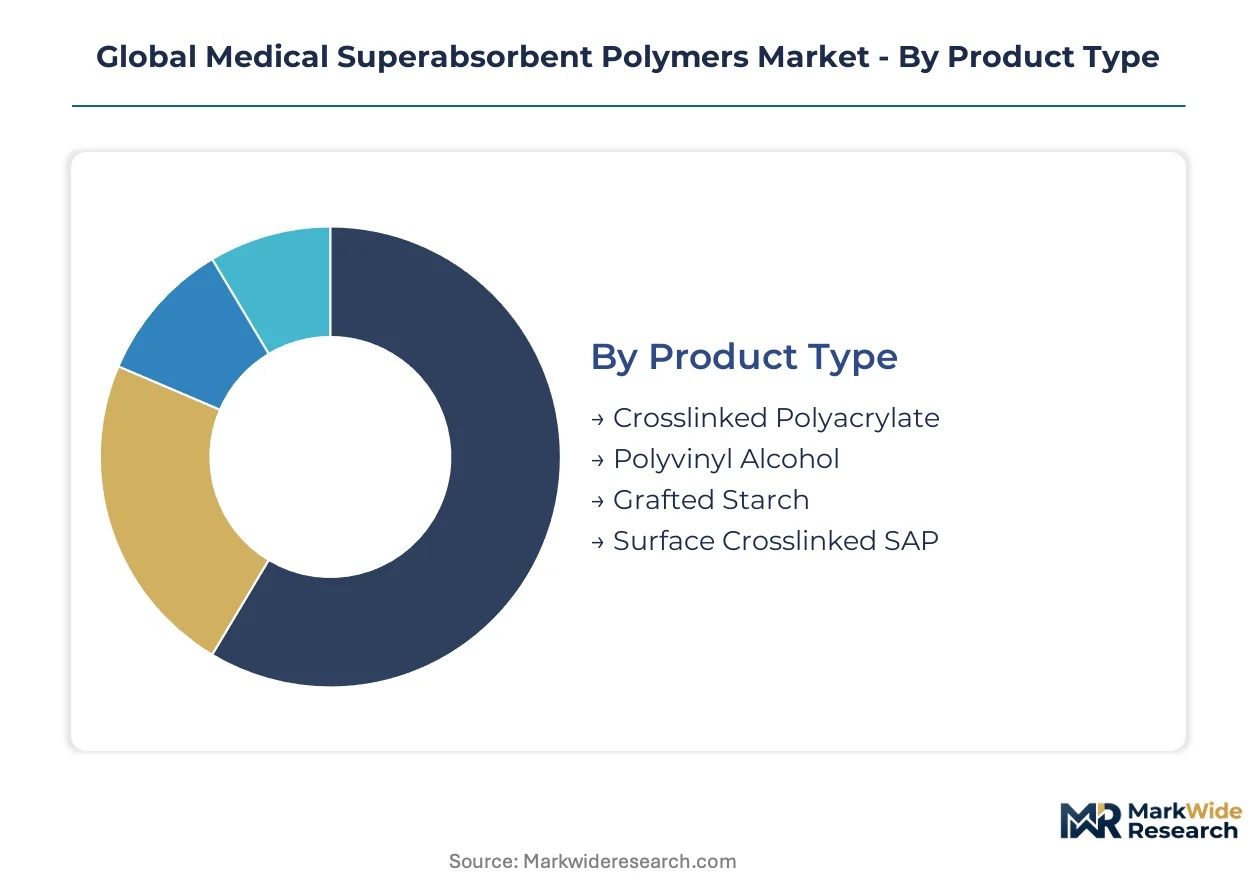
Procurement managers in wound care and surgical supply chains evaluate superabsorbent polymers across four critical dimensions. Each segmentation axis reveals distinct margin structures, regulatory burdens, and technical qualification pathways that determine vendor selection and contract longevity.
Product Type:
Material selection hinges on fluid retention capacity against gel blocking risk and sterilization compatibility.
- Crosslinked Polyacrylate:These lightly crosslinked networks achieve retention exceeding 50 grams per gram in physiological saline. German wound care manufacturers specify this grade for high-exudate diabetic ulcers where manufacturing economies and clinical track records outweigh premium alternatives.
- Surface Crosslinked SAP:Directional absorption architectures reduce maceration through controlled wicking rather than bulk gel formation. Demand concentrates in United States advanced wound care centers piloting diabetic foot protocols where reduced dressing change frequency offsets material cost premiums.
- Polyvinyl Alcohol:Biodegradable hydrogel platforms serve Japanese surgical drape manufacturers seeking aqueous solubility for controlled dissolution.
- Grafted Starch:Natural-polymer hybrids address sustainability procurement criteria in Nordic hospital systems prioritizing renewable feedstock content.
Volume sits with Crosslinked Polyacrylate; growth tilts toward Surface Crosslinked SAP.
Therapy Area:
Clinical application dictates absorption kinetics, antimicrobial integration requirements, and reimbursement coding complexity.
- Wound Care:Chronic ulcer management consumes the largest polymer tonnage as aging populations in Germany, Japan, and the United States drive sustained demand for exudate-controlling dressings. EU MDR biocompatibility testing upgrades are stretching qualification timelines for new product introductions.
- Incontinence Management:Home-based elder care expansion in Brazil and Mexico is generating volume opportunity as informal caregiving transitions to structured health protocols requiring disposable products with odor-neutralizing polymer cores.
- Surgical Drapes:Sterile barrier applications prioritize low-linting grades that maintain integrity under irrigation.
- Odor Control:Activated carbon-polymer composites serve ostomy and incontinence segments where ammonia binding determines patient compliance.
- Absorbent Dressings:Post-operative and trauma applications balance fluid capacity against conformability for anatomically challenging wound sites.
Wound Care commands installed base; Incontinence Management shows steepest expansion trajectory.
End User:
Facility type determines order consolidation patterns, technical service expectations, and sterilization validation requirements.
- Hospitals:Integrated delivery networks in Texas and California are consolidating procurement around full-category vendors capable of delivering integrated dressing systems with embedded technical support for device validation.
- Ambulatory Surgery Centers:These facilities prioritize single-use sterile systems that minimize reprocessing overhead and infection control liability.
- Rehabilitation Clinics:Long-term wound care protocols in German rehabilitation clusters demand consistent polymer specification across extended treatment courses.
- Diagnostic Laboratories:Specimen collection and transport applications require controlled-release absorption for biological sample integrity.
Contract concentration favors Hospitals; Ambulatory Surgery Centers are gaining share fastest in polymer consumption per procedure.
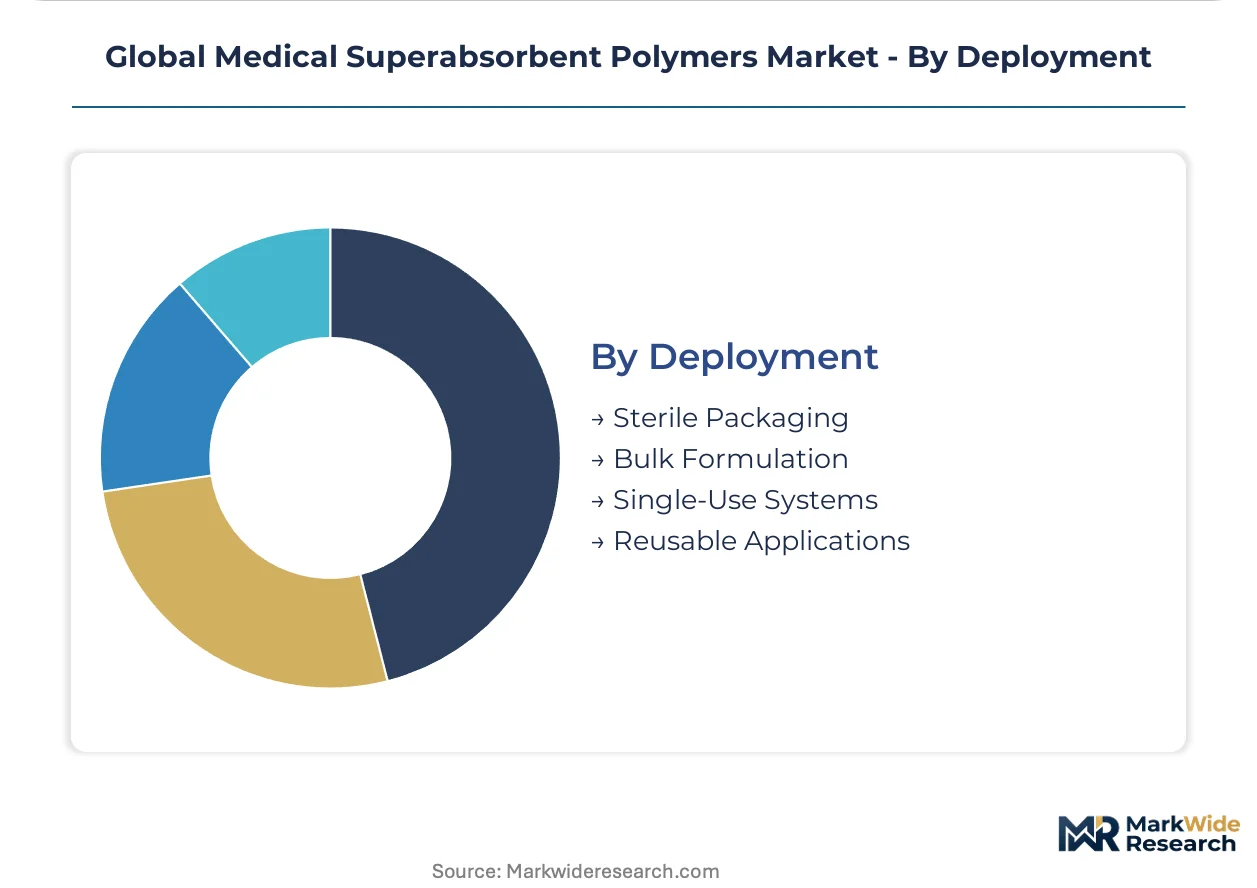
Deployment:
Packaging and use-configuration determines sterilization method, shelf-life economics, and environmental disposal pathways.
- Sterile Packaging:Pre-validated gamma-irradiated or ethylene-oxide-treated formats command premium positioning in implantable and long-wear topical applications facing EU MDR Annex I clinical evidence requirements.
- Single-Use Systems:Disposable configurations dominate infection-sensitive protocols where reprocessing validation costs exceed material premiums.
- Bulk Formulation:Raw resin supply serves contract manufacturers with in-house sterilization and conversion capabilities.
- Reusable Applications:Launderable polymer-impregnated textiles address sustainability mandates in select European institutional laundry networks.
Sterile Packaging captures value concentration; Single-Use Systems expand most quickly in ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific manufacturing corridors dominate base resin output for medical superabsorbent polymers, while European and North American markets absorb finished materials for wound care and incontinence applications. Germany, the United States, and Japan concentrate advanced formulation capabilities alongside clinical validation infrastructure.
United States
Advanced wound care centers in Texas and California pilot surface-crosslinked SAP technologies for diabetic foot ulcer protocols. FDA quality system regulations under 21 CFR govern device component classifications, requiring sterilization validation for implantable polymer applications. Integrated delivery networks across the Southwest consolidate procurement around full-category vendors with embedded technical support teams.
Germany
Chronic disease prevalence in aging demographics sustains demand for high-exudate wound management solutions. EU Medical Device Regulation Annex I imposes enhanced biocompatibility testing for polymer-containing devices, extending notified body review timelines. The Rhine-Ruhr and Bavarian polymer research clusters host formulation chemists with crosslinked hydrogel expertise concentrated in industrial R&D facilities.
Japan
Surgical drape manufacturers specify polyvinyl alcohol grades for controlled dissolution in aqueous environments. METI industrial standards and PMDA device regulations coordinate safety requirements for sterile medical applications. The Kansai region around Osaka anchors manufacturing scale for high-purity resin platforms serving domestic and export markets.
China
Base resin production capacity concentrates in coastal manufacturing zones supplying global formulators. NMPA medical device regulations and GB standards establish biocompatibility testing protocols for polymer-containing products. Yangtze River Delta chemical clusters integrate acrylic acid feedstock processing with superabsorbent polymer synthesis at manufacturing scale.
Brazil
Home-based elder care expansion generates volume opportunity for incontinence management products with odor-neutralizing polymer cores. ANVISA medical device regulations govern import and registration requirements for disposable healthcare products. São Paulo state distribution networks channel finished goods into structured home health protocols replacing informal caregiving arrangements.
Global Medical Superabsorbent Polymers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material grades and application segments. The market structure shows tiered concentration, with integrated chemical majors commanding crosslinked polyacrylate supply while specialty resin platforms occupy premium sterile applications. Three archetypes dominate: polymer science heritage conglomerates, high-purity medical specialists, and Asia-Pacific manufacturing scale players. Competitive moves center on backward integration into acrylic acid feedstocks and clinical evidence upgrades for EU MDR compliance.
Among German chemical conglomerates, BASF SE and Evonik Industries AG exemplify divergent strategic positioning within medical-grade superabsorbent supply. BASF SE leverages its Ludwigshafen polymer science heritage across industrial and medical applications, while Evonik Industries AG occupies a position emphasizing high-purity resin platforms for sterile device markets. Nippon Shokubai Co., Ltd. represents the Asia-Pacific manufacturing scale archetype, anchoring supply corridor efficiency for base resin output.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Nippon Shokubai Co., Ltd. |
| LG Chem |
| SDP Global Co., Ltd. |
| Sumitomo Seika Chemicals Co., Ltd. |
| Kao Corporation |
| Formosa Plastics Corporation |
| Yixing Danson Technology |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EU MDR-validated sterile platforms and commodity crosslinked polyacrylate resins manifests in divergent margin structures and procurement channel configurations across wound care supply chains. Premium sterile grades command contract-based offtake arrangements with hospital systems while commodity volumes trade through distributor-mediated spot markets.
Pricing Analysis
Margin tightening in surface-crosslinked SAP tiers reflects REACH-driven R&D overhead for residual monomer reduction and extended EU MDR clinical evidence timelines. Three-tier pricing structure across premium sterile, validated medical-grade, and industrial-conversion resin levels segments buyers by certification burden and end-use risk. Cost-down pressure on commodity crosslinked polyacrylate accelerates because acrylic acid feedstock volatility compresses converter margins. Ambulatory surgery centers exhibit highest price sensitivity per procedure volume; implantable device manufacturers show lowest sensitivity given qualification lock-in effects.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale wound care manufacturer demand for validated resin platforms with embedded technical support. Manufacturing gravity centers on China, Japan, and Germany for base resin synthesis, formulation, and sterile conversion respectively. Feedstock supply draws from petrochemical-derived acrylic acid monomers, crosslinking agents, and initiator chemicals. Single-source vulnerability concentrates in Asia-Pacific base resin output for European and North American formulators. Distribution runs through regional chemical distributors, GPO-integrated direct contracts, and contract manufacturing organization partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surface-crosslinked SAP architectures are displacing conventional bulk-crosslinked materials as wound care protocols prioritize directional fluid management and reduced maceration risk in chronic ulcer treatment.
For Market Incumbents: Anticipate formulation chemist scarcity in German and Japanese research clusters constraining rapid product line expansion. Prioritize backward integration into high-purity acrylic acid feedstocks to defend margin position against commodity resin imports. Accelerate EU MDR Annex I biocompatibility data package preparation to preempt notified body review timeline extensions freezing competitor launch cycles. For New Entrants and Emerging Players: Zwitterionic surface modification platforms offer technology-first wedge positioning against established hydrocolloid and alginate dressing incumbents. Target Brazilian and Mexican home-based elder care markets for incontinence management polymer cores where structured health protocol transition outpaces domestic supply capacity. Pursue toll manufacturing partnerships with Yangtze River Delta chemical clusters to bypass capital-intensive resin synthesis scale requirements. For Investors and Strategic Acquirers: Re-rating potential sits with high-purity medical resin specialists given EU MDR compliance burden acceleration and hospital system consolidation around full-category vendor relationships. Long-term viability frames around 5-10 year sterilization validation asset life cycles and recurring revenue from contract-based resin supply agreements. Monitor notified body capacity constraints and MDR certification backlog duration as inflection indicator for premium-grade pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid Feedstocks | Captive monomer supply secures margin stability against crude oil price volatility and refinery capacity constraints. |
| EU MDR Clinical Evidence Package Investment | Pre-validated biocompatibility data accelerates notified body review timelines for polymer-containing device registrations. |
| Surface Crosslinked SAP Manufacturing Scale-Up | Directional absorption capacity expansion serves United States advanced wound care center pilot programs for diabetic foot protocols. |
| Hospital System Technical Partnership | Embedded formulation support reduces qualification overhead for integrated delivery networks consolidating procurement contracts. |
| Brazil Distribution Network Development | São Paulo state channel infrastructure captures home-based elder care transition from informal caregiving to structured health protocols. |
Research Methodology
Independent corroboration across hospital procurement database analysis, GPO contract documentation, and chemical trade flow records underwrites the qualitative findings. Primary interviews with wound care product development executives, biomedical engineers at integrated delivery networks, sterile conversion plant managers, and regulatory affairs specialists at notified bodies combined with secondary validation from FDA 510(k) filings, EUDAMED device registrations, customs export data, and SEC chemical company disclosures. Bottom-up resin volume modeling and top-down wound care market sizing triangulate demand estimates.
Rate-of-change decomposition across therapy area adoption curves, product type substitution dynamics, and end-user procurement consolidation patterns structures the analytical framework. Segmentation dimensions modeled include material grade tier, clinical application, facility type, and deployment configuration across the projection horizon. CAGRs derive from regression-based trend extrapolation adjusted for regulatory timeline impacts and feedstock cost pass-through assumptions. Forecast inputs incorporate EU MDR implementation pace, chronic disease prevalence trajectories, and home-based care protocol expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH monomer restriction scenarios or sustained acrylic acid supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
C5 Resin Market