
 Middle-East and Africa Epoxy Resins Market | 2026-2036
Middle-East and Africa Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Epoxy Resins Market Foresight
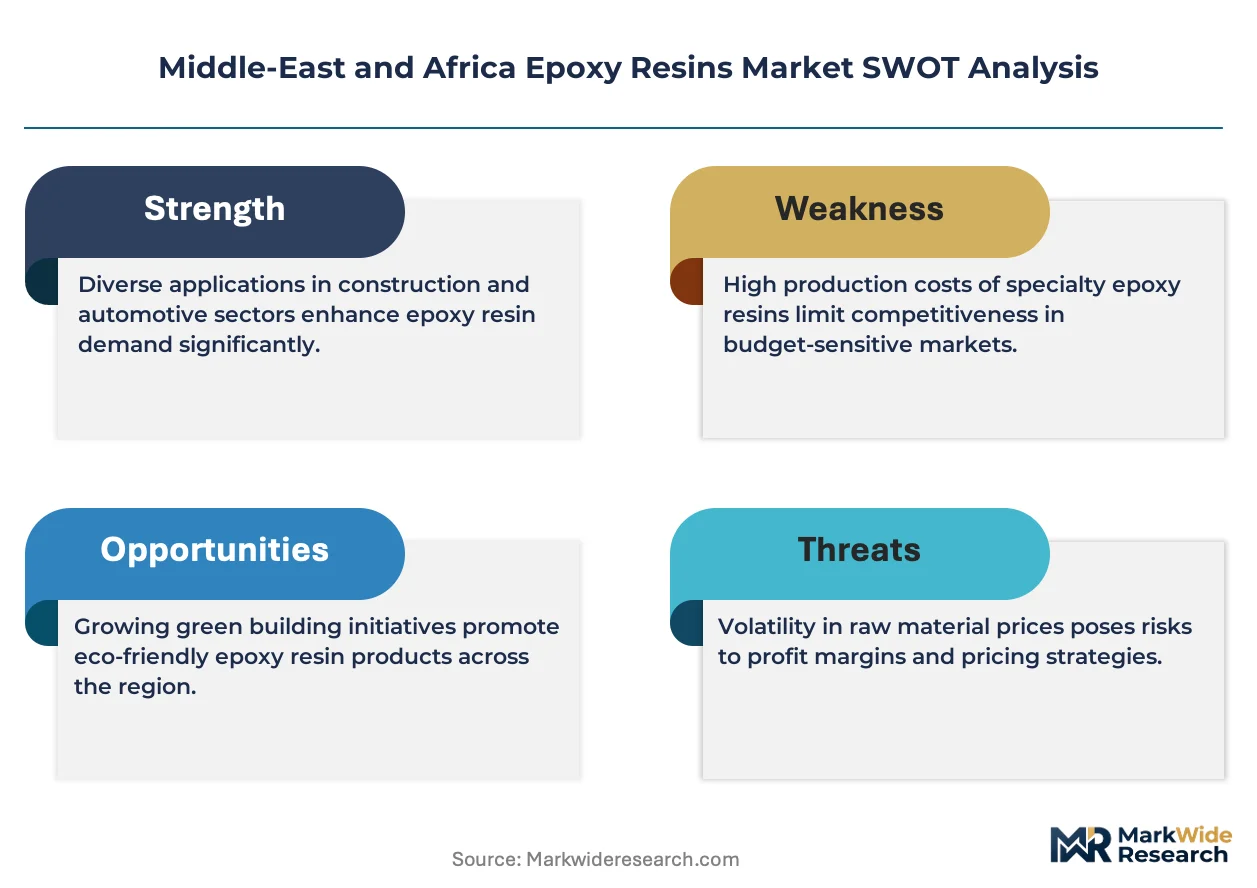
Specialized polymer chemist availability across the Middle-East and Africa epoxy resins industry is bifurcating into two distinct labor pools: Gulf-based technical specialists concentrated around Jubail and Yanbu industrial cities, and North African formulation technicians serving Mediterranean export channels. Huntsman Corporation LLC leverages its Jubail manufacturing complex to sustain regional supply continuity for high-purity liquid grades. Hexion anchors its competitive stance through backward integration into bisphenol-A feedstock streams. BASF SE differentiates via technical service teams embedded with major Saudi Arabian and Emirati construction conglomerates.
Epoxy resins constitute thermosetting polymers formed through the reaction of epichlorohydrin with bisphenol-A or novolac precursors, yielding materials with exceptional adhesive strength, chemical resistance, and dimensional stability under thermal stress above 150°C. The construction application commands the dominant volume position across the Middle-East and Africa region, driven by infrastructure spending in Saudi Arabia's giga-projects and Egypt's new administrative capital development. Liquid epoxy formulations represent the fastest-expanding product category, reflecting their processing advantages in automated coating systems and wind blade fabrication. Thermosetting grades retain the deepest margin pools due to their irreplaceable performance in protective coatings for oilfield equipment and marine structures exposed to corrosive Gulf environments.
Saudi Arabia's SFDA enforces chemical substance registration requirements that constrain market access for unregistered epoxy hardener imports, while the UAE's MOHAP maintains aligned industrial chemical safety protocols across Abu Dhabi and Dubai free zones. Egypt's environmental regulator applies discharge standards affecting solvent-based epoxy formulation facilities in Alexandria and Suez Canal Economic Zone. Stakeholders must monitor evolving Gulf standardization harmonization between GSO technical regulations and EU REACH-aligned requirements, as this convergence will determine qualification costs for European and Asian suppliers seeking long-term regional positioning.
Market Dynamics
Construction megaprojects across the Gulf Cooperation Council are pulling thermosetting epoxy grades into specifications that prioritize chemical resistance and dimensional stability under thermal stress above 150°C.
Growth Catalysts
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea Development Authority infrastructure tenders specify high-performance protective coatings for marine and desert exposure conditions.
- SFDA chemical substance registration:The Saudi Food and Drug Authority's mandatory hardener registration creates qualified supplier status for compliant importers, filtering competition.
- Wind blade fabrication scale-up:Egypt's Suez Canal Economic Zone and Morocco's Atlantic coastline are attracting composite manufacturers using automated liquid epoxy infusion systems.
Market Restraints
- Bisphenol-A feedstock volatility:Regional dependence on Asian petrochemical imports exposes formulators to freight cost swings and currency fluctuation.
- Jubail-Yanbu supply concentration:Over 60% of regional liquid epoxy capacity sits within a 200-kilometer corridor on Saudi Arabia's Eastern Province, creating single-point vulnerability.
- Solvent-based formulation discharge limits:Egypt's environmental regulator applies effluent standards that force Alexandria coating facilities into capital-intensive waterborne system conversions.
Strategic Opportunities
- Ethiopia and East African construction:Underpenetrated infrastructure markets lack qualified epoxy applicators, creating first-mover technical service advantages for trained distributors.
- MOHAP industrial chemical safety alignment:The UAE's Ministry of Health and Prevention is harmonizing Abu Dhabi and Dubai free zone protocols, reducing multi-jurisdiction compliance costs for registered suppliers.
- UV-curable epoxy hybrid systems:Convergence of photoinitiator chemistry with conventional thermosetting platforms enables rapid-cure repair applications for offshore oilfield maintenance windows.
Industry Challenges
- Specialized polymer chemist scarcity:Gulf-based technical specialists cluster around Jubail and Yanbu industrial cities, leaving North African formulation facilities dependent on expatriate talent with 18-24 month rotation cycles.
- SFDA-MOHAP registration timeline compression:Dual jurisdiction qualification for Saudi and UAE markets requires 14-22 month documentation cycles, delaying revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Epoxy Resins Market |
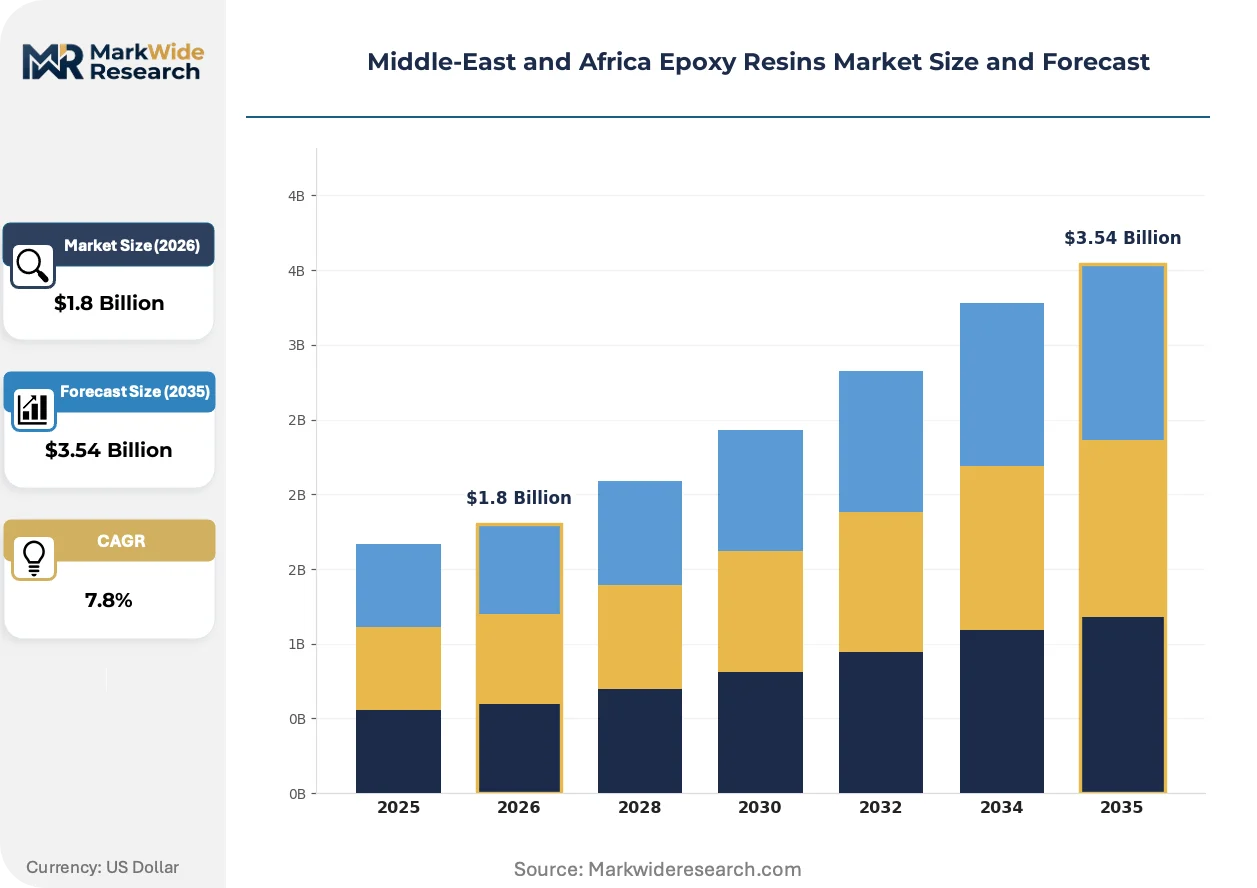
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermosetting, Liquid, Solid, Epoxy Novolac Application: Aerospace, Automotive, Electronics, Construction End User: Manufacturers, Contractors, OEMs, Suppliers Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | NAMA Chemicals, Huntsman Corporation LLC, Hexion, Olin Corporation, BASF SE, 3M, Dow, Sika AG, Nan Ya Plastics Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Epoxy Resins Market Shifts & Advancements
Formulation chemistry is pivoting toward systems that cure faster, emit less, and survive harsher chemical environments than legacy solvent-borne standards permitted.
Bio-based epoxy precursors derived from lignin and plant-based epichlorohydrin substitutes are supplanting petroleum-derived bisphenol-A formulations in European-export-oriented coating operations. Moroccan and Tunisian formulators serving Mediterranean marine customers have adopted these grades to preempt EU REACH-aligned border adjustments. The shift is compressing margin structures for conventional liquid epoxy suppliers while creating qualification premiums for certified bio-content tiers.
SFDA chemical safety protocols are tightening substance-by-substance registration requirements for epoxy hardener imports, extending documentation timelines and forcing reformulation of legacy amine curing agents. Saudi construction conglomerates now demand pre-registered hardener certificates in tender prequalification documents. European and Asian suppliers are responding by embedding regulatory affairs specialists within Riyadh and Jeddah commercial offices.
Specification-driven procurement is consolidating buying power among Saudi Aramco-approved construction contractors and Emirates-based EPC firms, compressing supplier rosters to pre-qualified resin formulators with embedded technical service teams. Long-term framework agreements with volume commitments are replacing spot purchasing for giga-project coating packages. This concentration is most visible in Saudi Arabia's Eastern Province petrochemical corridor, where downstream manufacturing clusters absorb bulk liquid epoxy volumes through direct pipeline supply arrangements.
Middle-East and Africa Epoxy Resins Market Segmentation
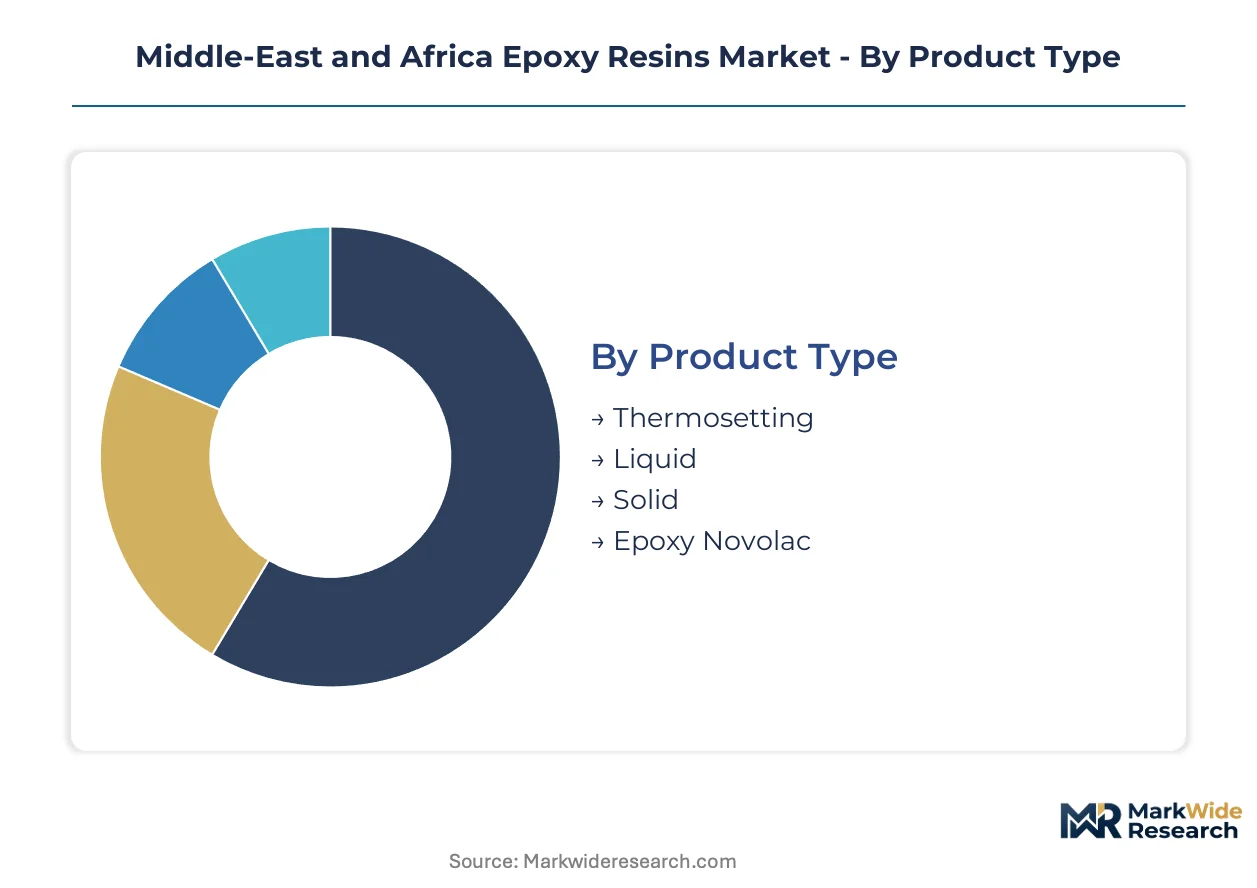
Epoxy resin procurement patterns across the Middle-East and Africa diverge sharply by segment, with construction contractors favoring bulk direct supply while electronics manufacturers fragment orders across specialized distributors. Channel economics and regulatory compliance burdens reshape how each segment reaches end-users.
Product Type:
Liquid grades flow through pipeline supply arrangements to Jubail corridor manufacturing clusters, while solid and novolac variants concentrate in distributor networks serving smaller formulation facilities.
- Thermosetting:Cross-linked polymers cured through heat-activated hardener reactions deliver dimensional stability above 150°C. Saudi Aramco-approved construction contractors specify these grades for offshore platform protective coatings, with procurement consolidating under long-term framework agreements that bypass spot markets.
- Liquid:Low-viscosity formulations enable automated infusion systems in wind blade fabrication and high-solids coating application. Egypt's Suez Canal Economic Zone composite manufacturers absorb expanding volumes through direct technical service relationships rather than traditional distribution.
- Solid:Powder or flake forms serve powder coating operations and adhesive compounding where solvent-free processing is mandated.
- Epoxy Novolac:Higher functionality precursors deliver superior chemical resistance for tank linings and secondary containment in corrosive Gulf environments.
Thermosetting grades dominate installed base across oilfield and marine specifications. Liquid formulations are where expansion concentrates, climbing fastest on wind energy and automated coating adoption.
Application:
Cost tier stratification separates specification-driven aerospace and electronics procurement from price-sensitive construction bulk purchasing.
- Construction:Protective coatings, flooring systems, and structural adhesives for infrastructure megaprojects constitute the deepest volume pool. NEOM and Red Sea Development Authority tenders pre-qualify only suppliers with embedded Saudi-based technical service teams, filtering channel access.
- Electronics:Printed circuit board laminates and semiconductor encapsulation demand ultra-high-purity grades with tight ionic contamination specifications. UAE free zone electronics assemblers import primarily through specialized chemical distributors with MOHAP registration certificates.
- Automotive:Structural composites and corrosion-resistant coatings for commercial vehicle manufacturing in Morocco and South Africa.
- Aerospace:Certified prepregs and adhesives for MRO operations and emerging indigenous manufacturing in the Gulf.
Construction commands the broadest channel footprint across direct sales and distributor networks. Electronics procurement is where margin concentration sits, rewarding qualified suppliers with technical specification influence.
End User:
Customer type determines whether procurement centralizes through direct mill supply or fragments across layered distribution.
- Contractors:Saudi and Emirati construction conglomerates with Aramco or ADNOC approval status negotiate direct pipeline supply from Jubail manufacturing complexes, eliminating distributor margins on high-volume coating packages.
- Manufacturers:Composite fabricators and formulation facilities in Egypt and Morocco purchase through regional distributors with local inventory and technical support capabilities.
- OEMs:Original equipment manufacturers in automotive and electronics sectors specify approved resin systems through qualified supplier programs.
- Suppliers:Trading companies and local agents serve fragmented small-scale users without volume leverage for direct mill relationships.
Contractors dominate direct channel volume through giga-project procurement scale. Manufacturers represent the most contested segment, with distributors competing on technical service proximity and SFDA registration support.
Distribution Channel:
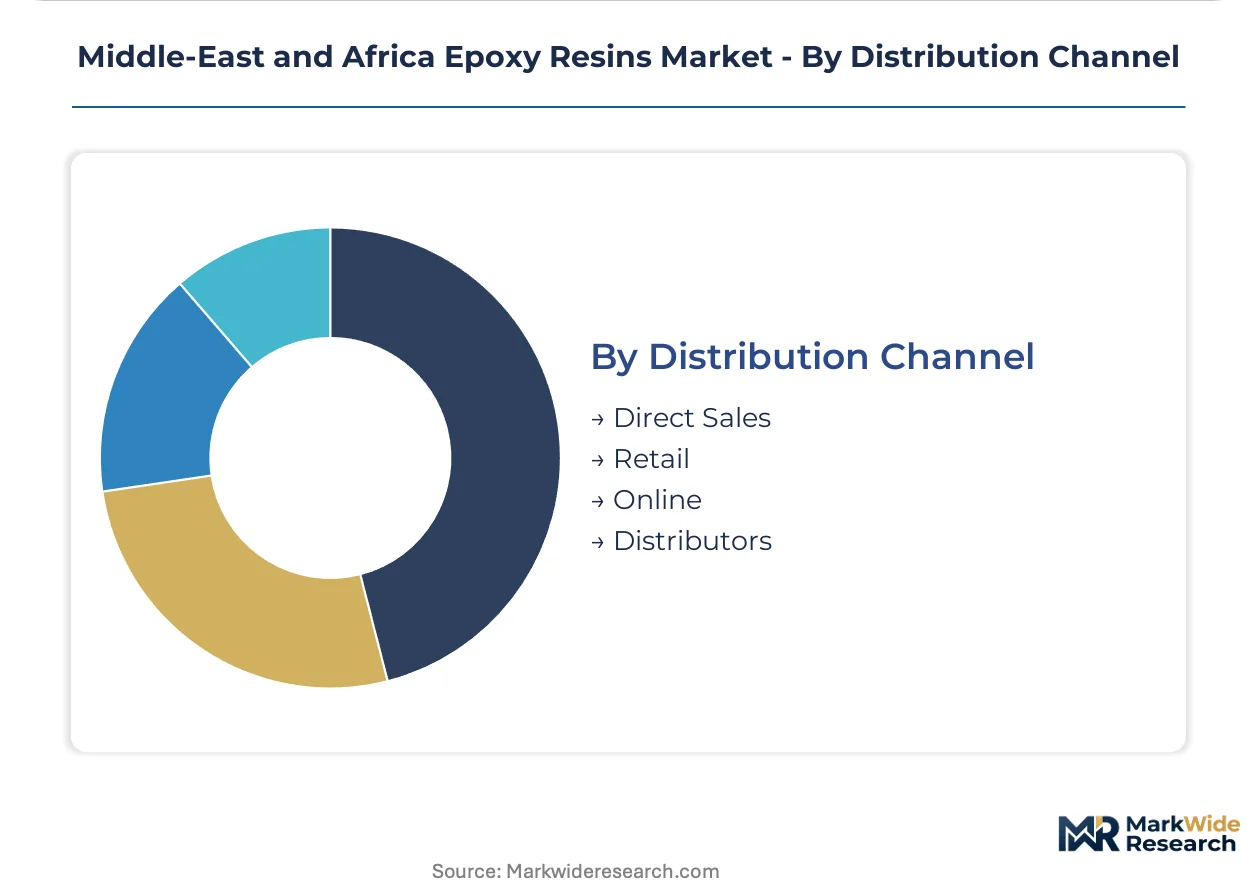
Geographic supply concentration in the Eastern Province dictates channel viability, with direct sales economical only within pipeline radius.
- Direct Sales:Producer-to-customer relationships capture bulk liquid epoxy movements to Jubail and Yanbu industrial city clusters. Huntsman and Hexion maintain dedicated account teams for Saudi construction conglomerates, with supply continuity guaranteed through on-site storage terminals.
- Distributors:Regional chemical distributors with Riyadh, Jeddah, and Cairo warehousing serve formulation facilities outside pipeline reach. SFDA hardener registration capabilities differentiate competitive positioning, as unregistered imports face customs detention.
- Retail:Limited to small-package adhesives and repair kits for maintenance applications in fragmented construction and consumer markets.
- Online:Emerging channel for technical documentation access and reordering of standardized grades among established accounts, not primary sourcing.
Direct sales dominate value capture in thermosetting grades. Distributor networks are where geographic coverage expansion concentrates, particularly for Egyptian and North African market development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA chemical safety protocols in Saudi Arabia anchor regulatory compliance requirements across the Middle-East and Africa epoxy resins market, with construction megaprojects in the Gulf Cooperation Council states driving thermosetting grade procurement.
Saudi Arabia
NEOM and Red Sea Development Authority infrastructure tenders specify high-performance protective coatings for marine and desert exposure conditions. The Saudi Food and Drug Authority enforces mandatory hardener registration that filters competition and creates qualified supplier status for compliant importers. Manufacturing clusters in Jubail and Yanbu industrial cities absorb bulk liquid epoxy volumes through direct pipeline supply arrangements.
United Arab Emirates
Emirates-based EPC firms consolidate buying power through pre-qualified resin formulator rosters with embedded technical service teams. The Ministry of Health and Prevention harmonizes Abu Dhabi and Dubai free zone protocols, reducing multi-jurisdiction compliance costs for registered suppliers. Construction conglomerates in Dubai negotiate direct mill relationships for giga-project coating packages.
Egypt
Composite manufacturers in the Suez Canal Economic Zone deploy automated liquid epoxy infusion systems for wind blade fabrication scale-up. The country's environmental regulator applies discharge standards affecting solvent-based formulation facilities in Alexandria, forcing capital-intensive waterborne system conversions. Downstream coating facilities cluster around Cairo and Alexandria port zones.
Morocco
Mediterranean marine customers drive adoption of bio-based epoxy precursors derived from lignin to preempt EU REACH-aligned border adjustments. Formulators serving European export channels have pivoted toward certified bio-content tiers, compressing margin structures for conventional liquid epoxy suppliers. Atlantic coastline manufacturing zones attract composite producers seeking automated processing advantages.
South Africa
Automotive structural composites and corrosion-resistant coatings for commercial vehicle manufacturing anchor industrial demand. The country's environmental and chemical safety frameworks apply discharge limits affecting formulation facilities in Gauteng and Eastern Cape industrial zones. Durban and Cape Town port corridors serve as distribution nodes for regional chemical supply chains.
Middle-East and Africa Epoxy Resins Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Middle-East and Africa epoxy resins market, with backward integration into bisphenol-A feedstock streams distinguishing the upper tier from formulation-dependent competitors. Gulf-based manufacturing complexes concentrate around Jubail and Yanbu industrial cities, creating geographic supply advantages for Eastern Province producers. Three archetypes dominate: petrochemical-integrated resin manufacturers, technical service-embedded formulators, and specialty hardener specialists. Competitive moves concentrate on long-term framework agreements with volume commitments and SFDA-MOHAP dual jurisdiction registration capabilities.
Among petrochemical-integrated manufacturers, Huntsman Corporation LLC and Hexion exemplify the backward-integrated archetype with captive feedstock control, while BASF SE represents the technical service-embedded formulator model. These three companies anchor competitive positioning through differentiated supply chain configurations rather than undifferentiated commodity supply.
| Leading Market Players |
|---|
| NAMA Chemicals |
| Huntsman Corporation LLC |
| Hexion |
| Olin Corporation |
| BASF SE |
| 3M |
| Dow |
| Sika AG |
| Nan Ya Plastics Corporation |
| Others |
Supply & Pricing Matrix
SFDA hardener registration requirements gate both supply qualification and price differentiation simultaneously, filtering unregistered imports into detention while rewarding compliant suppliers with premium positioning in Saudi construction tenders. The resulting bifurcation concentrates pricing power among dual-registered suppliers serving both Saudi Arabia and UAE markets.
Pricing Analysis
Jubail corridor producers command 15-20% premia over Mediterranean-sourced alternatives due to pipeline delivery economics and SFDA registration bundling. Three-tier pricing structure across premium certified, standard registered, and unregistered economy grades separates Aramco-approved contractors from secondary formulators. Cost compression in bio-based novolac tiers is intensifying because Moroccan formulators are absorbing EU REACH compliance premiums. Construction contractors in Egypt's Suez Canal Economic Zone exhibit highest price sensitivity, while aerospace MRO operators in the UAE demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Strait of Hormuz transit underwrites feedstock security for Saudi Arabia's Eastern Province manufacturing clusters, though alternative routing through Red Sea ports adds 12-15 days for European suppliers. Production concentrates in Saudi Arabia, UAE, and Egypt, with bisphenol-A, epichlorohydrin, and amine hardeners drawing primarily from Asian petrochemical complexes. Single-source vulnerability pervades the Jubail-Yanbu corridor where over 60% of regional liquid epoxy capacity sits within 200 kilometers. Distribution runs through direct pipeline supply to Eastern Province clusters, with distributor networks covering North African and East African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as infrastructure spending in Gulf Cooperation Council states accelerates, with NEOM and Red Sea Development Authority tenders creating qualified-supplier scarcity that favors prepared incumbents.
For Market Incumbents: Fortify registration moats by securing dual SFDA-MOHAP hardener certifications before documentation timelines extend further. Backward integration into bisphenol-A feedstock streams defends margin position against Asian import volatility. Embedded technical service teams in Riyadh and Dubai commercial offices represent the critical lever for specification influence in giga-project tenders. For New Entrants and Emerging Players: Anchor in Ethiopia and East African construction markets where qualified epoxy applicator scarcity creates first-mover technical service advantages. Wind blade fabrication in Egypt's Suez Canal Economic Zone offers the most penetrable segment given automated liquid epoxy infusion demand expansion. Partner with regional distributors possessing SFDA registration capabilities rather than attempting direct qualification independently. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based epoxy precursor segments as Moroccan and Tunisian formulators invest in lignin-derived certification infrastructure. Over a 5-10 year horizon, acquisition targets should display dual jurisdiction registration capabilities and embedded technical service relationships with Saudi construction conglomerates. The signal to watch is harmonization between GSO technical regulations and EU REACH-aligned requirements, which will determine qualification cost trajectories for European and Asian suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA-MOHAP Dual Registration | Filters competition and creates qualified supplier status for compliant importers in Saudi and UAE markets. |
| Backward Integration into Bisphenol-A | Hexion and Huntsman anchor competitive positioning through captive feedstock control against Asian import volatility. |
| Bio-Based Precursor Certification | Moroccan formulators serving Mediterranean marine customers preempt EU REACH-aligned border adjustments. |
| Technical Service Team Embedding | BASF SE differentiates via specialists embedded with Saudi Arabian and Emirati construction conglomerates. |
| Long-Term Framework Agreements | Saudi Aramco-approved contractors consolidate buying power through pre-qualified resin formulator rosters. |
Research Methodology
A spread of perspectives from epoxy resin plant managers, downstream coating procurement leads at Saudi construction conglomerates, distribution channel partners in Cairo and Casablanca, and technical R&D directors at hardener specialists converged on the working assumptions. These primary insights were cross-referenced with customs and trade data, Gulf Petrochemicals and Chemicals Association reports, SEC 10-K filings of listed producers, and SFDA registration databases. Bottom-up volume builds by product grade and application were triangulated against top-down market sizing derived from petrochemical capacity announcements.
Segmentation dimensions modeled include thermosetting versus thermoplastic curing chemistry, liquid versus solid versus novolac physical forms, construction versus electronics versus automotive end-use industries, and direct sales versus distributor channel economics. CAGRs were derived from regression analysis of historical volume movements against infrastructure spending indices and wind energy installation forecasts. Key inputs encompassed SFDA registration timeline data, Jubail corridor production capacity utilization rates, and Suez Canal Economic Zone composite manufacturing announcements.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf infrastructure spending and stable Asian petrochemical feedstock availability; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as GSO-EU REACH harmonization negotiations and Red Sea shipping security conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Styrenics Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Europe Polyols Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Water-Borne Epoxy Resins Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Nylon Resins Market