
 Global Grease Cartridges Market | 2026-2036
Global Grease Cartridges Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grease Cartridges Market Analysis
Subscription-based lubricant replenishment programs is rebalancing how industrial buyers procure grease cartridges, shifting volume commitments from spot purchases to contracted fulfillment tiers. Shell plc leverages its integrated supply chain to secure bulk cartridge contracts with mining operators across Australia and Canada. Fuchs Petrolub SE anchors its position through specialized high-temperature formulations that command premium placement in steel mill maintenance schedules. SKF competes by bundling cartridge supply with bearing condition monitoring services, tightening customer switching costs.
Grease cartridges are cylindrical sealed containers, typically holding 400 grams of lubricating grease, engineered from high-density polyethylene or fiber-composite materials to resist deformation under mechanical loading and prevent moisture ingress during storage. Their primary commercial purpose centers on enabling clean, metered dispensing of lubricants in field maintenance environments where bulk pumping systems prove impractical. Plastic material segments dominate unit economics due to blow-molding scalability, though composite cartridges are capturing fastest growth in aerospace end-use applications where weight reduction commands design priority. Standard cartridges still occupy the largest volume share across automotive maintenance channels, while specialty cartridges concentrate margin pools through custom aperture designs for automated grease gun systems.
EPA regulations in the United States restrict volatile organic compound emissions from lubricant packaging materials, compelling manufacturers to reformulate cartridge sealants and surface coatings. REACH compliance through ECHA mandates full material disclosure for chemical substances in cartridge construction sold across European Union member states, elevating documentation costs for non-EU suppliers. China's GB standards through SAMR enforce dimensional tolerances for interchangeability with domestic grease gun equipment, creating a technical barrier for imported cartridge formats. Stakeholders must monitor how evolving extended producer responsibility frameworks in multiple jurisdictions reshape packaging recovery economics and supplier qualification requirements.
Market Dynamics
Subscription-based lubricant replenishment programs are rebalancing procurement patterns across industrial buyers, shifting volume commitments from spot purchases to contracted fulfillment tiers with embedded technical support services.
Growth Catalysts
- REACH compliance mandates:ECHA disclosure requirements for chemical substances in cartridge construction elevate documentation costs for non-EU suppliers, advantaging incumbent European manufacturers with established compliance infrastructure.
- Fleet operator maintenance programs:Automotive service networks across Germany, China, and the United States are standardizing cartridge-based lubrication protocols, creating pull-through demand for standardized 400-gram formats.
- High-temperature steel mill applications:Specialized formulations command premium placement in maintenance schedules where equipment failure costs exceed lubricant expenditures by orders of magnitude.
Market Restraints
- HDPE resin price volatility:Blow-molding feedstock costs fluctuate with petrochemical cycles, compressing margins for plastic cartridge producers during upstream price spikes.
- Import substitution in China:GB standards through SAMR enforce dimensional tolerances for interchangeability with domestic grease gun equipment, creating technical barriers for foreign cartridge formats.
- Bulk pumping system competition:Centralized lubrication infrastructure in greenfield industrial facilities displaces cartridge consumption in high-volume continuous operations.
Strategic Opportunities
- Aerospace weight reduction mandates:Fiber-composite cartridges are capturing fastest growth in aviation maintenance where every gram commands design priority and regulatory certification unlocks fleet placement.
- Extended producer responsibility frameworks:Packaging recovery economics in multiple jurisdictions reshape supplier qualification requirements, rewarding early movers with closed-loop collection infrastructure.
- Bearing condition monitoring convergence:Bundled cartridge supply with predictive maintenance services tightens customer switching costs and expands addressable spend per account.
Industry Challenges
- Multi-jurisdiction certification timelines:EPA sealant reformulation, REACH material disclosure, and GB dimensional compliance must synchronize for global product launches, extending time-to-revenue.
- Legacy grease gun interoperability:Automated dispensing systems require custom aperture designs that fragment manufacturing runs and complicate inventory planning across regional specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grease Cartridges Market |
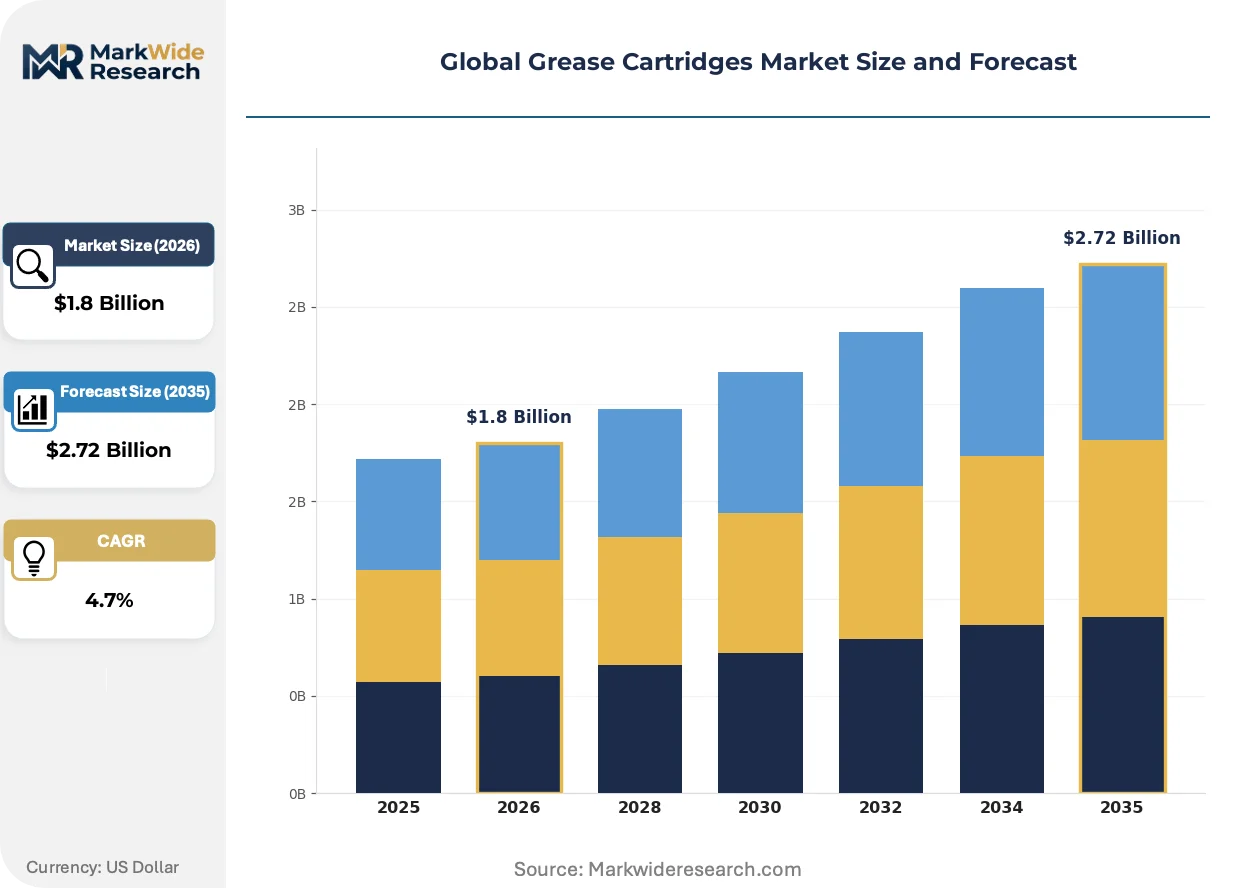
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cartridges, Bulk Cartridges, Mini Cartridges, Specialty Cartridges Material: Plastic, Metal, Composite, Paper End User: Automotive, Industrial, Marine, Aerospace Application: Machinery Lubrication, Automotive Maintenance, Equipment Repair, Heavy-Duty Applications |
| Companies Covered | Shell plc, ExxonMobil Corporation, Fuchs Petrolub SE, TotalEnergies SE, Chevron Corporation, SKF, Parker Hannifin, Kluber Lubrication, Castrol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grease Cartridges Market Emerging Trajectories
Material science advances and regulatory stringency are compressing product development cycles while elevating performance specifications across cartridge construction, sealant chemistry, and dispensing interface design.
Smart cartridge technologies embedding RFID tags and pressure sensors are converging with industrial IoT platforms to enable real-time lubricant level monitoring and automated replenishment triggering. Mining operators in Australia and Canada are piloting these connected formats to eliminate manual inspection rounds. This convergence is compressing maintenance labor intensity while generating usage data that locks buyers into integrated supplier ecosystems.
EPA regulations restricting volatile organic compound emissions from lubricant packaging materials are compelling manufacturers to reformulate cartridge sealants and surface coatings. The industrial consequence extends beyond compliance costs to qualification delays for new chemical formulations. Steel mill and mining maintenance channels face the tightest reformulation timelines given their exposure to outdoor storage conditions requiring robust moisture barriers.
Buyer consolidation among fleet operators and industrial maintenance contractors is compressing supplier rosters and elevating technical service requirements alongside product supply. Spot purchasing through distribution intermediaries is yielding to direct contracting with volume-tier pricing and embedded engineering support. This pattern concentrates most visibly in German automotive service networks and North American mining maintenance operations where procurement centralization has advanced furthest.
Global Grease Cartridges Market Segmentation
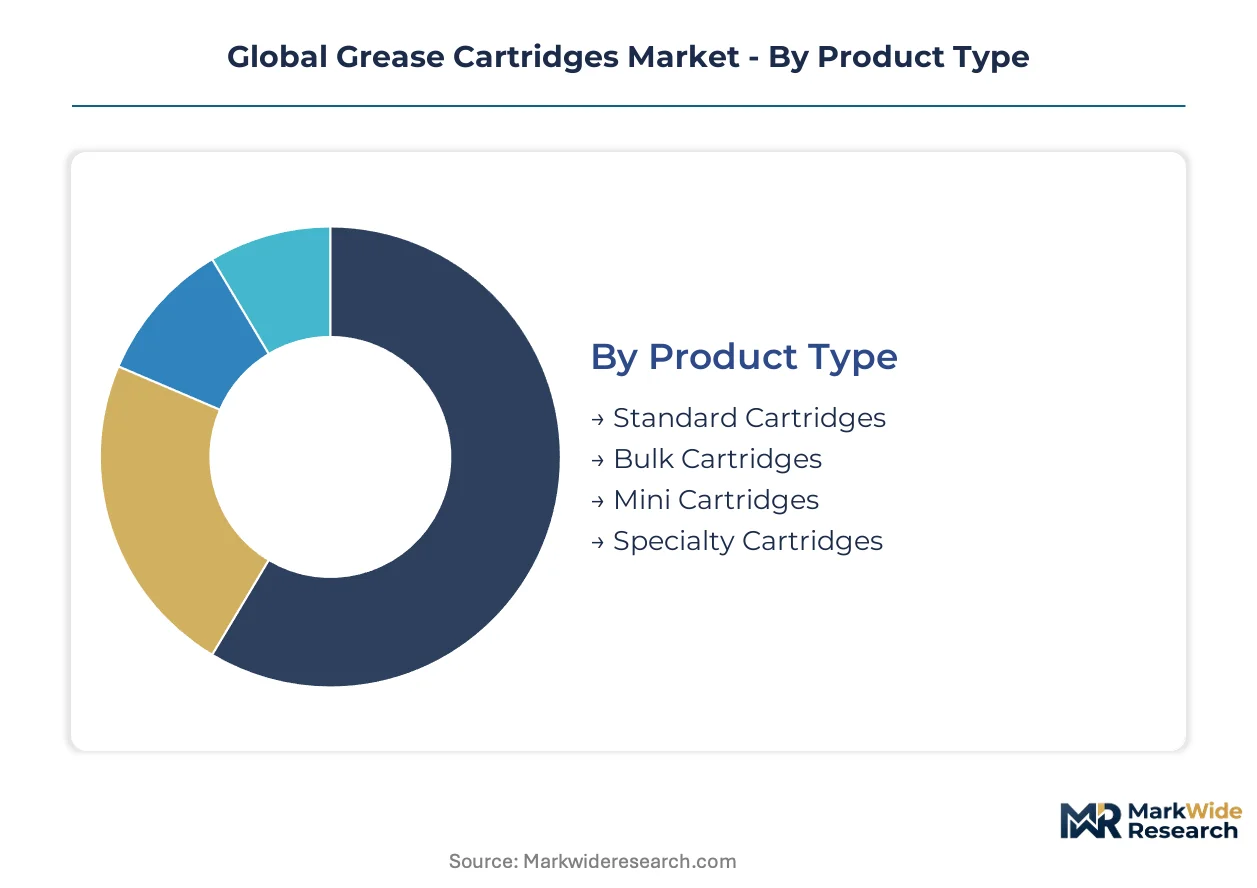
Grease cartridge procurement patterns diverge sharply across industrial verticals, with material specifications and dimensional formats determining interchangeability with legacy grease gun infrastructure. Fleet operators and maintenance contractors prioritize standardization to reduce inventory complexity, while specialized applications drive premium segmentation through custom aperture designs.
Product Type:
Buyers select cartridge formats based on equipment compatibility and lubricant volume requirements, with fleet standardization programs favoring interoperable dimensions over performance differentiation.
- Standard Cartridges:These 400-gram cylindrical formats dominate automotive maintenance channels due to universal grease gun compatibility. Demand concentrates in Germany and the United States where fleet operators enforce procurement standardization across service networks.
- Specialty Cartridges:Custom aperture configurations serve automated dispensing systems in steel mill and mining operations. These formats command premium placement where equipment failure costs dwarf lubricant expenditures, particularly across Australian and Canadian mining corridors.
- Bulk Cartridges:High-volume formats reduce per-unit packaging costs for centralized industrial lubrication systems.
- Mini Cartridges:Compact 100-gram variants address precision lubrication in confined machinery spaces.
Volume sits with Standard Cartridges; growth tilts toward Specialty Cartridges.
Material:
Material selection trades blow-molding scalability against performance specifications, with regulatory compliance costs reshaping supplier economics across jurisdictions.
- Plastic:High-density polyethylene dominates unit economics through blow-molding scalability and moisture resistance. EPA volatile organic compound regulations are compelling sealant reformulation for US-bound production, extending qualification timelines.
- Composite:Fiber-reinforced constructions address aerospace weight reduction mandates where every gram commands design priority. ECHA REACH disclosure requirements elevate documentation burdens for non-EU suppliers seeking European aviation placement.
- Metal:Steel and aluminum cartridges persist in high-pressure industrial environments requiring structural rigidity.
- Paper:Biodegradable formats gain traction in extended producer responsibility frameworks with mandatory packaging recovery.
Plastic captures current volume leadership; composite materials are climbing the fastest.
End User:
End-use concentration determines margin structure, with industrial maintenance programs generating contracted volume tiers distinct from spot-purchased automotive consumption.
- Automotive:Service networks across Germany, China, and the United States standardize cartridge-based lubrication protocols. SAMR GB standards enforce dimensional tolerances for interchangeability with domestic grease gun equipment.
- Industrial:Steel mills and mining operations generate the steepest expansion trajectory through predictive maintenance convergence. SKF bundles cartridge supply with bearing condition monitoring services, tightening customer switching costs.
- Marine:Salt-resistant sealant specifications address offshore platform maintenance in corrosive environments.
- Aerospace:Regulatory certification requirements unlock fleet placement for qualified suppliers.
Industrial buyers concentrate procurement volume; aerospace represents the highest margin capture.
Application:
Application context determines dispensing interface requirements, with heavy-duty cycles demanding robust construction distinct from precision machinery lubrication.
- Heavy-Duty Applications:Mining and construction equipment subject cartridges to mechanical loading and outdoor storage extremes. Shell plc secures bulk contracts with Australian and Canadian operators through integrated supply chain coverage.
- Machinery Lubrication:Manufacturing plant maintenance favors standardized formats compatible with manual grease guns. Fuchs Petrolub SE anchors position through specialized high-temperature formulations.
- Automotive Maintenance:Quick-lube service bays prioritize rapid cartridge exchange and minimal waste generation.
- Equipment Repair:Field service operations require portable formats for on-site lubrication without bulk pumping infrastructure.
Heavy-Duty Applications drive premium pricing; Machinery Lubrication holds the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor maintenance depots in Germany generate concentrated cartridge procurement volume through integrated fleet lubrication programs serving steel mill and automotive service networks.
United States
EPA volatile organic compound regulations compel sealant reformulation for domestic cartridge production. Houston petrochemical corridors supply blow-molding feedstock to regional manufacturers. Midwest automotive service networks standardize 400-gram formats across quick-lube franchise operations.
Germany
ECHA REACH disclosure requirements elevate documentation burdens for imported cartridge construction materials. Bavarian automotive OEMs enforce procurement standardization across supplier tiers. Ruhr steel mills command premium placement for high-temperature specialty formulations.
China
SAMR GB dimensional standards create technical barriers for foreign cartridge formats seeking domestic grease gun interoperability. Yangtze River Delta manufacturing clusters consolidate lubricant packaging procurement. Shandong Peninsula petrochemical complexes expand blow-molding capacity for plastic cartridge production.
Australia
Mining maintenance corridors across Western Australia and Queensland drive bulk cartridge contracting through predictive maintenance convergence. TGA-equivalent industrial safety frameworks govern lubricant storage specifications. Pilbara iron ore operators pilot RFID-enabled smart cartridges for automated replenishment triggering.
Canada
Alberta oil sands and Ontario automotive manufacturing generate divergent cartridge specifications across heavy-duty and precision lubrication channels. Health Canada environmental guidelines influence packaging recovery economics. Toronto-Windsor industrial corridor maintenance contractors consolidate supplier rosters under volume-tier contracting.
Global Grease Cartridges Market Vendor Landscape
Capital-heavy petrochemical integrators compete with asset-light lubricant specialists across the grease cartridge value chain. Market structure tilts toward consolidated supply through integrated oil majors with captive polymer feedstock access, while specialized formulators carve defensible positions in temperature-extreme applications. Three archetypes dominate: vertically integrated energy conglomerates controlling resin-to-dispensing supply chains; independent lubricant houses commanding formulation chemistry premiums; and industrial equipment bundlers tightening switching costs through predictive maintenance convergence. Dominant competitive moves include backward integration into blow-molding capacity and strategic partnerships with fleet operators for contracted fulfillment tiers.
Within the integrated energy tier, Shell plc and ExxonMobil Corporation occupy positions anchored by petrochemical infrastructure scale and global distribution density. Fuchs Petrolub SE exemplifies the independent formulation specialist archetype, sitting within a tier where chemistry expertise commands premium placement in steel mill and aerospace maintenance schedules. SKF represents the equipment-bundling vector, exemplifying how bearing manufacturers tighten customer relationships through converged hardware and consumable supply.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| Fuchs Petrolub SE |
| TotalEnergies SE |
| Chevron Corporation |
| SKF |
| Parker Hannifin |
| Kluber Lubrication |
| Castrol |
| Others |
Supply Flow & Price Mechanics
Fleet operator consolidation across Germany, China, and the United States is compressing supplier rosters and forcing cartridge manufacturers to absorb certification costs or surrender margin to retain contracted volume tiers. This procurement centralization rewards suppliers with captive blow-molding capacity and integrated formulation chemistry, while marginalizing intermediaries lacking upstream resin access or downstream technical service capabilities.
Pricing Analysis
Margin tightening in standard plastic cartridges reflects HDPE resin price volatility tied to petrochemical cycles, compressing producer economics during upstream spikes. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and after-sales engineering support, with specialty high-temperature formulations commanding placement premiums in steel mill maintenance. Cost-down pressure on economy tiers accelerates because Chinese domestic manufacturers exploit GB standard dimensional tolerances to displace imports. Automotive service networks exhibit highest price sensitivity due to standardized procurement protocols, while mining operators prioritize equipment failure avoidance over lubricant unit economics.
Supply Chain Analysis
REACH certification and EPA sealant reformulation requirements are gating supplier qualification timelines, extending time-to-revenue for new market entrants. Manufacturing concentrates in Germany, China, and the United States, with Shandong Peninsula petrochemical complexes expanding blow-molding capacity and Houston corridors supplying regional HDPE feedstock. Raw material dependencies center on high-density polyethylene resin, fiber-composite reinforcements, and moisture-barrier sealant chemistry. Single-source vulnerability persists in aerospace-grade composite formulations where ECHA documentation burdens limit qualified European suppliers. Distribution runs through direct contracting with fleet operators and industrial maintenance contractors, displacing spot purchasing through distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grease cartridge market is becoming a vertical-integration race where control over blow-molding capacity and formulation chemistry determines margin capture. Players lacking captive resin supply or certified specialty formulations face systematic exclusion from contracted procurement tiers.
For Market Incumbents: Anchor market position through backward integration into regional blow-molding capacity across the Ruhr corridor and Yangtze River Delta manufacturing clusters. Deepen technical service embedding with mining operators in Australia and Canada through predictive maintenance convergence, tightening customer switching costs against independent lubricant houses. Defend against fiber-composite entrants in aerospace by accelerating ECHA REACH documentation infrastructure. For New Entrants and Emerging Players: The price-point gap between premium specialty formulations and economy standard cartridges creates entry space for mid-tier composite suppliers serving weight-sensitive industrial applications. Target mini cartridge formats for precision lubrication in confined machinery spaces, where incumbent scale advantages weaken and customization requirements fragment manufacturing runs. Pursue direct contracting with mid-sized fleet operators in Canada and Australia bypassing consolidated supplier rosters of multinational oil majors. For Investors and Strategic Acquirers: The window for entry favors independent lubricant houses with specialized high-temperature formulation expertise and established steel mill maintenance channel relationships. Long-term viability hinges on convergence with predictive maintenance platforms and bearing condition monitoring services. Watch for inflection signals in extended producer responsibility framework implementation across European Union member states, which will reshape packaging recovery economics and reward early movers with closed-loop collection infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blow-Molding Capacity | Captive HDPE resin conversion secures margin control against petrochemical price cycles. |
| REACH Certification Infrastructure Investment | ECHA documentation capabilities unlock European aerospace and automotive procurement tiers. |
| Predictive Maintenance Platform Convergence | Bearing condition monitoring bundling tightens switching costs with industrial maintenance contractors. |
| Closed-Loop Collection Infrastructure Buildout | Extended producer responsibility compliance rewards early movers in packaging recovery economics. |
| Smart Cartridge Technology Development | RFID-enabled lubricant level monitoring locks buyers into integrated supplier ecosystems. |
Methodological Framework
Trade association publications, customs and import-export databases, and SEC regulatory filings formed the secondary backbone of this analysis. Primary fieldwork incorporated structured interviews with maintenance directors at mining operations across Western Australia and Queensland, procurement leads at German automotive OEMs, plant managers at Shandong Peninsula petrochemical facilities, and aftermarket service heads at bearing manufacturers. Technical R&D directors at independent lubricant houses provided formulation chemistry perspectives. Bottom-up and top-down triangulation validated volume estimates across material segments and end-use applications.
Bottom-up modeling aggregated segment-level consumption patterns across automotive service networks, steel mill maintenance schedules, and mining operator procurement protocols. Top-down verification cross-referenced against regional manufacturing cluster outputs and lubricant packaging trade flows. Segmentation dimensions included cartridge format, material construction, end-use vertical, and application intensity. CAGRs derived from historical consumption trajectories adjusted for regulatory compliance cost absorption and fleet operator consolidation trends. Forecast inputs incorporated EPA sealant reformulation timelines, SAMR GB standard enforcement patterns, and aerospace weight reduction mandate progression.
Underlying measurement precision varies by segment; standard plastic cartridge volumes carry tighter precision than emerging composite formats where certification data remains sparse. Forecasts reflect assumptions regarding procurement centralization continuity and regulatory harmonization timelines across jurisdictions. A model refresh is warranted upon material change in extended producer responsibility framework implementation or breakthrough in biodegradable cartridge material performance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Aerospace Lubricant Market
Lubricants
Marine Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
Europe Marine Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Global Grease Market
Lubricants
Neat Cutting Oil Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Global Finished Lubricant Market
Lubricants
Indonesia Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Israel Lubricants Market