
 High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market | 2026-2036
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market Insights
European specialty chemical producers is expanding high-solids acrylic polyol capacity to serve automotive and industrial maintenance formulators migrating from conventional solvent-borne systems. BASF leverages integrated precursor supply from its Ludwigshafen Verbund complex to sustain cost-advantaged resin output. Covestro anchors its position through polyurethane crosslinking expertise that extends into low-VOC topcoat formulations. allnex competes on radiation-curable and waterborne adjacencies while maintaining high-solids acrylic polyol production for protective coating specialists.
High-solids acrylic polyol resins are hydroxyl-functional acrylic polymers synthesized via solution polymerization at solids contents exceeding 80 weight percent, designed to react with isocyanate or melamine crosslinkers while emitting minimal volatile organic compounds during cure. Aliphatic acrylics dominate architectural and automotive clearcoat segments where exterior durability and UV resistance command premium positioning. Protective coatings application leads volume consumption as infrastructure maintenance cycles and corrosion prevention standards tighten across industrial facilities. Modified polyols represent the fastest-growing product category as formulators blend acrylic backbones with polyester or silicone segments to achieve hybrid performance profiles.
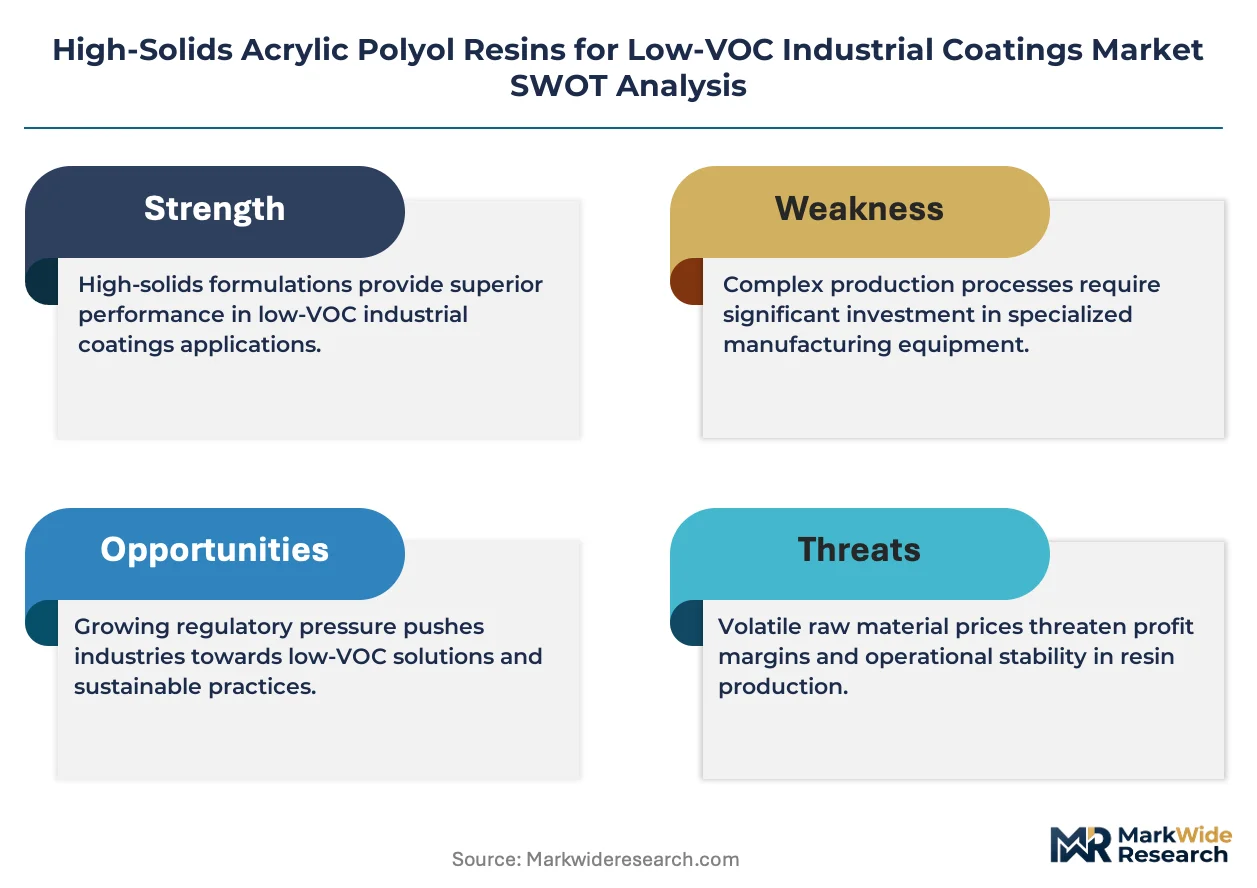
EPA National Emission Standards for Hazardous Air Pollutants and REACH Annex XVII restrictions on solvent content are reshaping formulation chemistry across North American and European coating operations. ECHA substance evaluations and state-level California Air Resources Board rules are forcing incremental VOC reductions that favor high-solids systems over conventional alternatives. Stakeholders must monitor regulatory harmonization between EU Green Deal industrial emissions targets and evolving US OSHA workplace exposure limits to anticipate specification shifts in cross-border coating procurement.
Market Dynamics
REACH Annex XVII solvent restrictions and EPA NESHAP compliance deadlines are compressing formulation timelines across industrial coating operations, forcing resin suppliers to accelerate high-solids validation cycles while automotive OEMs rewrite procurement specifications.
Growth Catalysts
- Automotive OEM Specification Migration:Tier-1 suppliers in Germany and the US are mandating 80+ weight percent solids content for clearcoat and basecoat systems to meet fleet emissions targets.
- REACH VOC Phase-Down:The EU regulatory framework is eliminating solvent-borne alternatives in industrial maintenance and protective coatings through progressive solvent-content ceilings.
- Polyester-Acrylic Hybrid Synthesis:Modified polyol technology is enabling single-coat systems that match two-coat durability, reducing application labor and material waste in field maintenance.
Market Restraints
- Isocyanate Feedstock Concentration:Aliphatic diisocyanate supply concentrates among three global producers, creating vulnerability to force majeure events and price volatility.
- High-Viscosity Handling Limits:Resins above 85 weight percent solids require heated storage and specialized pumping infrastructure unavailable at smaller job-shop applicators.
- Waterborne Acrylic Substitution:Formulators in architectural segments are bypassing high-solids systems entirely, opting for waterborne polyurethanes where humidity-controlled application is feasible.
Strategic Opportunities
- India Industrial Corridor Expansion:The PLI scheme for manufacturing and infrastructure buildout under the National Infrastructure Pipeline is creating specification windows for low-VOC protective coatings at new steel and chemical facilities.
- Radiation-Curable Convergence:UV-acrylic hybrid systems are opening wood and plastic substrate applications where thermal cure constraints previously blocked polyol-isocyanate chemistry.
- CSRD Supply Chain Disclosure:The EU Corporate Sustainability Reporting Directive is compelling coating buyers to document Scope 3 emissions, advantaging suppliers with verified low-VOC resin portfolios.
Industry Challenges
- Formulation Chemist Shortage:The specialized knowledge required to balance hydroxyl functionality, viscosity, and pot-life in high-solids systems is retiring faster than training programs replace it.
- Crosslinker Compatibility Validation:Each new blocked isocyanate or melamine resin requires 12-18 month qualification cycles with major automotive and aerospace OEMs, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market |
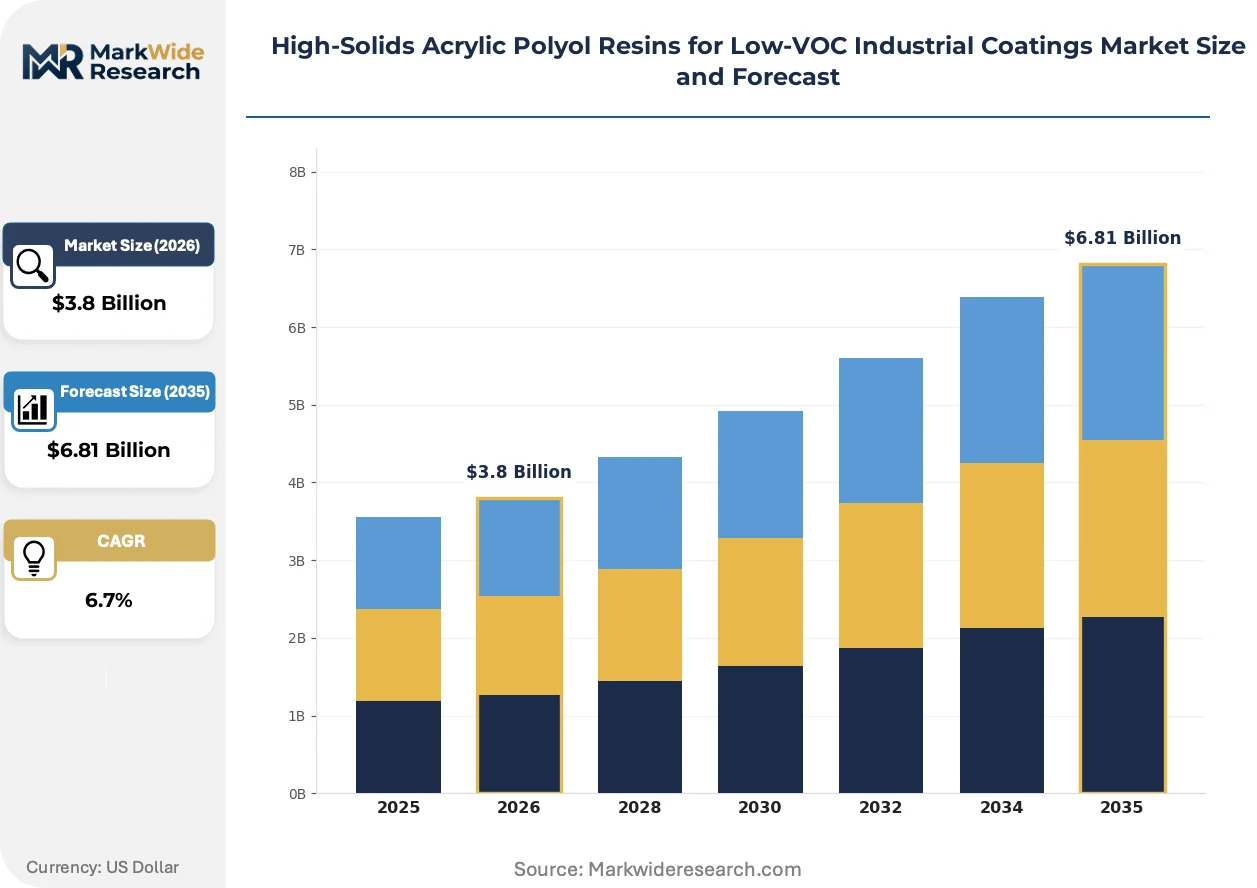
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic Acrylics, Aromatic Acrylics, Modified Polyols, Polyester Polyols Application: Protective Coatings, Wood Finishes, Automotive Paints, Marine Coatings, Metal Packaging End User: OEMs, Aftermarket Suppliers, Industrial Manufacturers, Specialty Contractors Packaging Type: Drums, Pails, Bulk Containers, Intermediate Bulk Containers |
| Companies Covered | BASF, Covestro, allnex, Arkema, Dow, Evonik, Eastman Chemical Company, DIC Corporation, Wanhua Chemical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market Trends and Innovations
Acrylic polyol chemistry is converging with adjacent resin technologies to create hybrid systems that satisfy multiple performance vectors previously requiring separate coating layers.
Silicone-modified acrylic polyol synthesis is unifying weatherability and chemical resistance in single-resin architectures. Wind turbine OEMs in Denmark and Spain are specifying these hybrids for leading-edge protection where erosion and UV degradation intersect. The technology is compressing the traditional two-coat system into one high-build application, reducing field labor hours and material waste.
EPA NESHAP Subpart HHHHHH is tightening hazardous air pollutant limits for miscellaneous coating manufacturing. Facility operators in Ohio and Texas are retrofitting solvent recovery systems or converting entirely to high-solids feedstocks to avoid Title V permitting triggers. The rule is accelerating most visibly in custom coating shops serving agricultural and construction equipment.
Specification-driven procurement now dominates automotive refinish and aerospace MRO channels. Tier-1 distributors in Germany and France are consolidating supplier relationships to three approved resin houses per coating category, displacing spot-buying from regional traders. This concentration is most advanced in Bavaria's automotive supplier cluster, where BASF and allnex have secured multi-year sole-source positions.
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market Segmentation
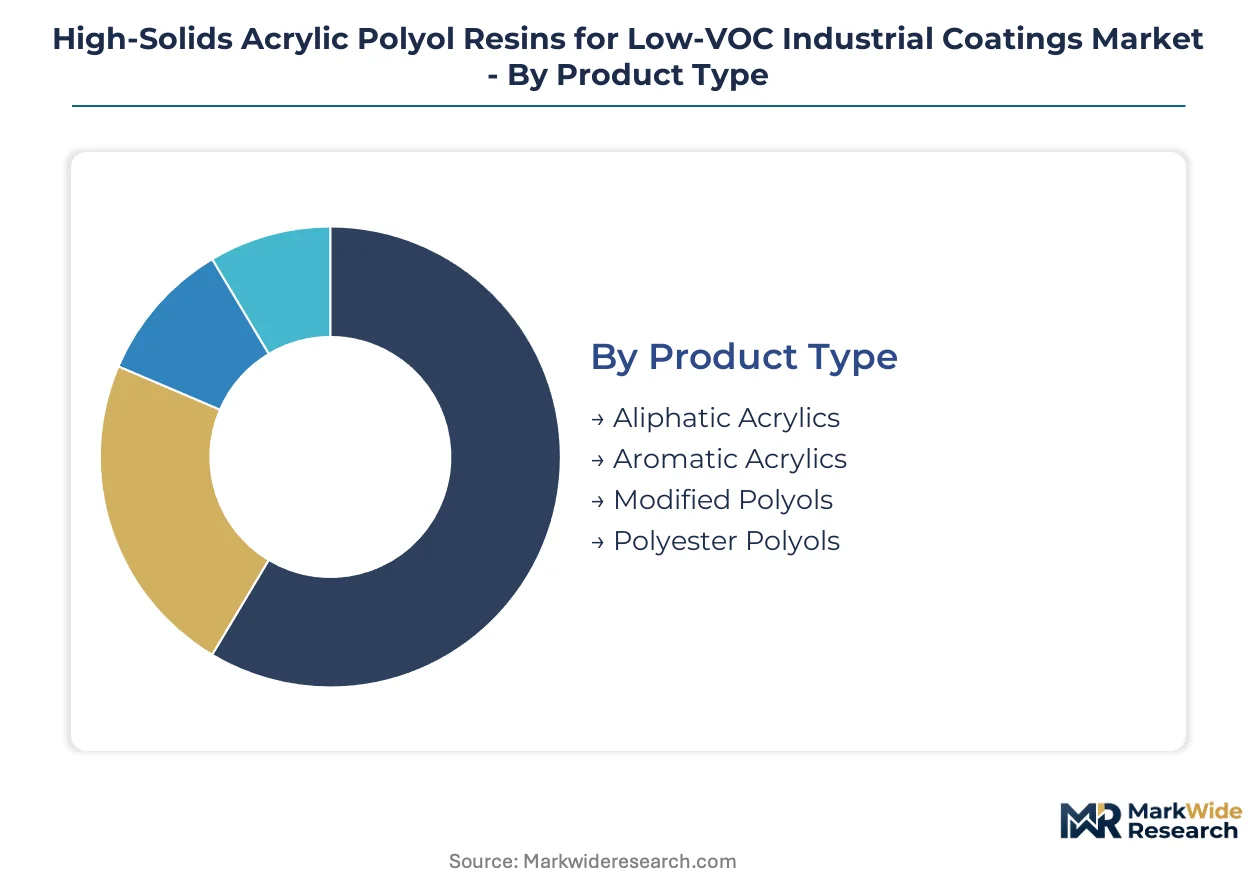
Segmentation in high-solids acrylic polyol resins reveals how formulation chemistry, application environment, and procurement scale intersect to determine pricing power and technical specification intensity. Understanding these divides exposes where resin suppliers can defend margin versus where volume throughput dominates commercial strategy.
Product Type:
Volume production concentrates in commodity aliphatic grades, while premium positioning attaches to modified and specialty hybrid architectures that command specification loyalty from automotive and aerospace formulators.
- Aliphatic Acrylics:These resins deliver exterior durability and UV resistance through hydrocarbon backbone structures that resist yellowing under photoxidative stress. Demand clusters in Germany's automotive clearcoat supply chain, where BASF and Covestro enforce 80+ weight percent solids mandates for fleet compliance with EU Green Deal industrial emissions targets.
- Modified Polyols:Hybrid architectures blend acrylic backbones with polyester or silicone segments to achieve single-coat performance equivalent to traditional two-layer systems. Wind turbine OEMs in Denmark and Spain specify silicone-modified variants for leading-edge protection where erosion and UV degradation intersect, compressing field labor hours and material waste.
- Aromatic Acrylics:Cost-optimized resins for interior industrial maintenance where UV exposure remains minimal and solvent reduction still satisfies EPA NESHAP thresholds.
- Polyester Polyols:Adjacent chemistry increasingly hybridized with acrylic functionality for flexible packaging and coil coating applications requiring enhanced adhesion to metal substrates.
Mature deployment sits with Aliphatic Acrylics. Newer deployment is concentrated in Modified Polyols.
Application:
Protective coatings generate the highest tonnage offtake, though automotive and marine segments extract superior margin through qualification barriers and specification lock-in.
- Protective Coatings:Infrastructure maintenance and corrosion prevention drive bulk consumption across industrial facilities, petrochemical plants, and offshore platforms. The segment expands most quickly in India's National Infrastructure Pipeline corridors, where PLI scheme incentives for domestic manufacturing create specification windows for low-VOC systems at new steel and chemical complexes.
- Automotive Paints:Clearcoat and basecoat systems demand precise hydroxyl functionality control to balance pot-life with cure speed under isocyanate crosslinking. Tier-1 suppliers in Bavaria's automotive cluster have consolidated procurement to sole-source relationships with validated resin houses, displacing spot-buying from regional traders.
- Marine Coatings:Ballast tank and topside applications requiring IMO-compliant corrosion protection with reduced solvent emissions during shipyard application.
- Wood Finishes:Furniture and flooring segments where UV-curable acrylic hybrids are displacing conventional thermal-cure systems in high-throughput manufacturing lines.
- Metal Packaging:Interior and exterior can coatings where FDA compliance for food contact limits crosslinker selection and favors specific acrylic polyol architectures.
Specification intensity peaks in Automotive Paints. Volume scaling dominates in Protective Coatings.
End User:
OEM procurement operates through multi-year framework agreements with technical validation cycles, while aftermarket and contractor channels reward logistics flexibility and smaller batch availability.
- OEMs:Automotive, aerospace, and appliance manufacturers mandate 12-18 month qualification cycles for each new resin-crosslinker combination, creating sticky supplier relationships and high switching costs. CSRD supply chain disclosure requirements are compelling documented Scope 3 emissions tracking that advantages resin suppliers with verified low-VOC portfolios.
- Industrial Manufacturers:In-house coating operations at machinery and equipment producers balancing cost control with progressive VOC reduction mandates under tightening state-level regulations.
- Aftermarket Suppliers:Refinish distributors serving collision repair and maintenance channels where color-matching speed and local inventory availability determine procurement decisions.
- Specialty Contractors:Protective coating applicators for infrastructure and marine assets where project-based purchasing and technical field support influence supplier selection.
Long-term contract security concentrates with OEMs. Spot market responsiveness defines Specialty Contractors.
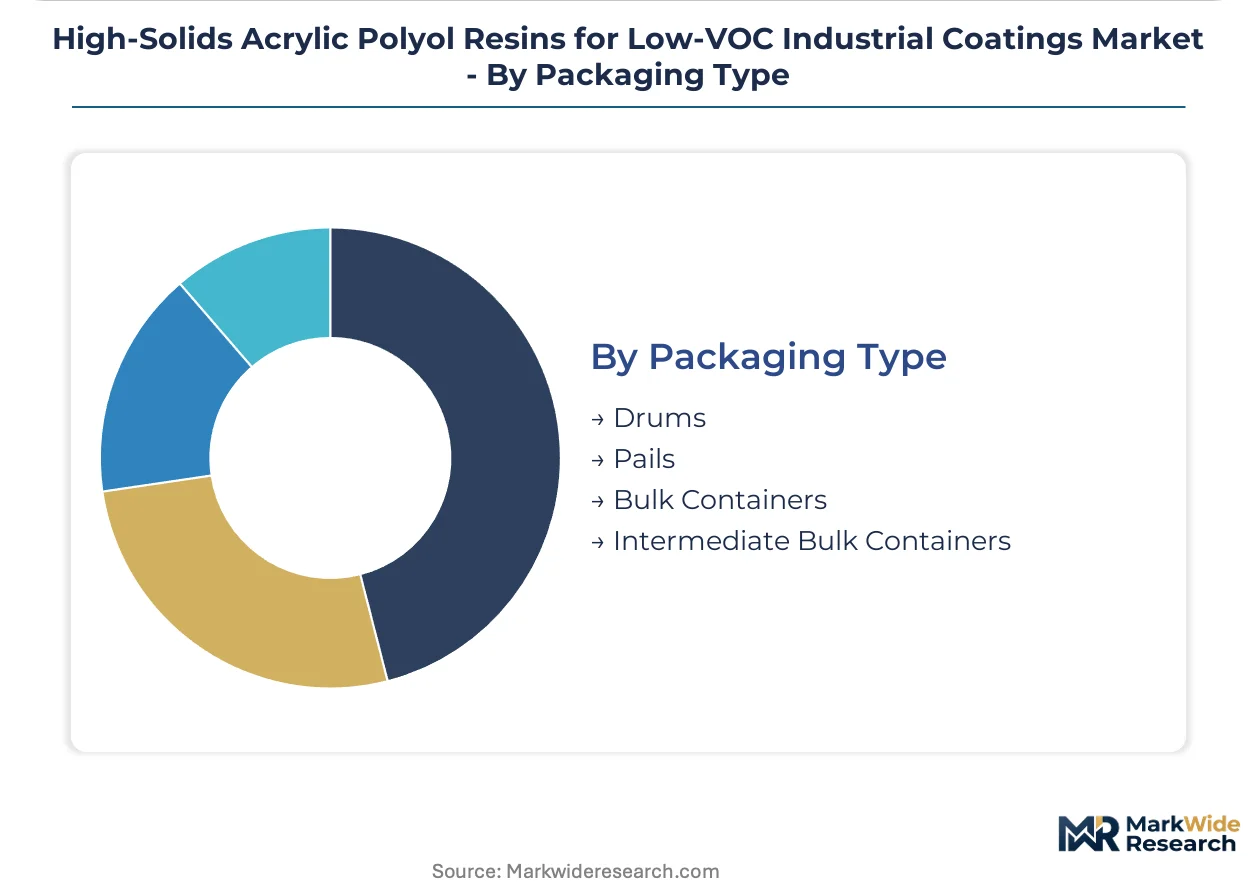
Packaging Type:
Packaging economics track application scale and supply chain proximity, with bulk formats capturing logistics efficiency for integrated formulators and smaller units serving distributed job-shop networks.
- Bulk Containers:Tank truck and railcar deliveries to large coating manufacturing facilities with dedicated unloading infrastructure and high-volume throughput. These formats minimize per-unit logistics cost but require capital investment in heated storage systems for resins above 85 weight percent solids.
- Intermediate Bulk Containers:Flexible intermediate bulk containers and rigid totes serving mid-tier formulators seeking to balance inventory flexibility with unit economics.
- Drums:Standard 55-gallon steel and polyethylene drums for regional distributors and smaller coating operations without bulk handling capability.
- Pails:Five-gallon and smaller containers for specialty contractors, R&D laboratories, and custom color-matching operations requiring frequent product changes.
Capital-intensive infrastructure anchors Bulk Container adoption. Pail flexibility supports fragmented contractor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock corridors in Germany's Rhine-Neckar region anchor European resin production, while automotive OEM mandates in Bavaria and industrial maintenance clusters in North Rhine-Westphalia concentrate demand for low-VOC formulations.
Germany
Automotive clearcoat procurement from BMW, Mercedes-Benz, and Volkswagen enforces 80+ weight percent solids specifications across Tier-1 suppliers. REACH Annex XVII solvent-content ceilings eliminate conventional solvent-borne alternatives in industrial maintenance. The Ludwigshafen chemical corridor hosts integrated precursor production that sustains cost-advantaged resin output for protective coating formulators.
United States
EPA NESHAP Subpart HHHHHH compliance deadlines compress formulation timelines at custom coating shops serving agricultural and construction equipment manufacturers. Ohio and Texas facility operators retrofit solvent recovery systems or convert entirely to high-solids feedstocks to avoid Title V permitting triggers. The Ohio River Valley petrochemical belt supplies aliphatic diisocyanate crosslinkers to regional resin blenders.
China
Wind turbine OEM procurement for leading-edge protection drives silicone-modified acrylic polyol specification at domestic blade manufacturers. MEE enforcement of dual carbon goals tightens VOC emission thresholds at industrial coating facilities in coastal provinces. The Yangtze River Delta concentration of automotive and marine coating plants absorbs expanding high-solids capacity from domestic polyol producers.
India
PLI scheme incentives for domestic manufacturing under the National Infrastructure Pipeline create specification windows for low-VOC protective coatings at new steel and chemical complexes. BIS standards for industrial coating emissions are tightening in parallel with state-level pollution control mandates. The Gujarat chemical corridor attracts resin capacity expansion to serve refinery and petrochemical maintenance demand.
Japan
Automotive OEMs Toyota and Honda extend low-VOC procurement mandates to their Southeast Asian supplier networks, pulling Japanese resin exports. METI industrial emissions guidelines accelerate solvent-phase reductions at domestic appliance and machinery coating operations. The Chubu region around Nagoya concentrates automotive supplier coating facilities with validated high-solids resin supply chains.
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue radiation-curable and waterborne adjacencies rather than direct high-solids competition. The market structure concentrates among integrated petrochemical majors with captive precursor supply and specialty resin houses with qualification-locked automotive relationships. Three archetypes dominate: integrated chemical conglomerates leveraging Verbund economics, polyurethane crosslinking specialists extending into topcoat formulations, and radiation-curable adjacency players maintaining high-solids production for protective coating specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with suppliers retrofitting existing solution polymerization lines rather than greenfield investment.
Within the integrated chemical tier, BASF anchors European supply through its Ludwigshafen complex, while Covestro exemplifies polyurethane crosslinking expertise extension into low-VOC topcoat formulations. Among specialty resin houses, allnex occupies a position spanning radiation-curable adjacencies with maintained high-solids acrylic polyol production for protective coating specialists.
| Leading Market Players |
|---|
| BASF |
| Covestro |
| allnex |
| Arkema |
| Dow |
| Evonik |
| Eastman Chemical Company |
| DIC Corporation |
| Wanhua Chemical Group |
| Others |
Pricing and Supply Chain Analysis
Backward integration into aliphatic diisocyanate and acrylic precursor production anchors supply position and pricing power for resin producers serving automotive OEMs under REACH Annex XVII compliance mandates. Ludwigshafen-based producers leverage captive feedstock streams to defend margin against spot-market volatility while smaller blenders absorb cost pass-through from concentrated crosslinker suppliers.
Pricing Analysis
Technical service bundling separates premium resin tiers from unbundled commodity grades where formulation support carries separate charges. Three-tier pricing structure across premium, standard, and economy levels tracks hydroxyl functionality precision and qualification status with automotive OEMs. Pricing pressure stems from waterborne acrylic substitution in architectural segments where humidity-controlled application is feasible. Aftermarket refinish distributors exhibit highest price sensitivity due to fragmented purchasing and inventory turnover pressures, while OEM procurement teams prioritize specification lock-in over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired or off-specification resins remain minimal given thermal cure constraints and pot-life limitations that prevent refurbishment. Supply concentrates in Germany, the United States, and China where petrochemical corridors feed integrated polyol production. Raw material dependencies center on methyl methacrylate, butyl acrylate, and aliphatic diisocyanate crosslinkers sourced from three global producers. Single-source vulnerability in hexamethylene diisocyanate supply creates force majeure exposure for formulators lacking dual-qualified resin houses. Distribution runs through tank truck and railcar bulk formats to large coating manufacturers, with drums and pails serving fragmented job-shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII solvent-content ceilings and EPA NESHAP compliance deadlines construct a cost-of-compliance moat that advantages incumbents with validated low-VOC portfolios while raising capital barriers for unqualified entrants.
For Market Incumbents: Acquire blocked isocyanate formulation expertise to accelerate crosslinker compatibility validation cycles that currently delay revenue recognition by 12-18 months. Secure sole-source positions with Tier-1 automotive distributors in Bavaria's supplier cluster before specification consolidation displaces regional traders. Waterborne acrylic substitution in architectural segments threatens volume erosion in commodity grades, demanding R&D investment in silicone-modified hybrid architectures for wind turbine and marine applications. For New Entrants and Emerging Players: Capture specification windows in India's National Infrastructure Pipeline corridors where PLI scheme incentives for domestic manufacturing create demand for low-VOC protective coatings at new steel and chemical complexes. Target protective coating applicators for infrastructure assets where project-based purchasing rewards technical field support over brand heritage. Partner with Gujarat-based resin distributors to establish local inventory positioning before BIS emission standards tighten procurement requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking polyurethane crosslinking expertise extension into low-VOC topcoat formulations. Long-term viability hinges on qualification-locked relationships with automotive OEMs extending through multi-year framework agreements. Monitor CSRD supply chain disclosure adoption rates among European coating buyers as the signal indicating accelerated specification consolidation toward verified low-VOC resin portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aliphatic Diisocyanate | Captive crosslinker supply insulates margin from three-producer concentration risk. |
| Silicone-Modified Hybrid Capacity Expansion | Single-coat wind turbine protection commands premium positioning in Denmark and Spain. |
| REACH Compliance Certification Investment | Validated portfolios secure sole-source positions with Tier-1 automotive distributors. |
| Long-Term Supply Agreement with OEMs | Multi-year frameworks lock out spot competitors in Bavaria's automotive cluster. |
| Joint Venture in Gujarat Chemical Corridor | Local production captures PLI scheme benefits for India's infrastructure buildout. |
Research Methodology
Trade data from Eurostat, customs filings from India's DGFT, and SEC 10-K disclosures from coating raw material suppliers formed the secondary backbone for demand quantification. Primary interviews with plant managers at European resin production facilities, procurement leads at German automotive Tier-1 suppliers, technical R&D directors at protective coating formulators, and distribution channel partners in the Ohio River Valley petrochemical belt validated secondary estimates. Bottom-up and top-down triangulation reconciled facility-level capacity assessments against end-use consumption models.
Bottom-up modeling built from individual resin production lines, crosslinker supply contracts, and formulation validation cycles across the projection horizon. Segmentation dimensions included product architecture, application environment, end-user procurement scale, and regional regulatory cluster. CAGRs derived from fitted growth curves anchored to named capacity expansions and OEM specification migration timelines. Forecast inputs incorporated REACH Annex XVII phase-down schedules and EPA NESHAP Subpart HHHHHH compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to isocyanate feedstock concentration events and waterborne acrylic substitution rates in architectural segments. Practitioners should monitor BIS emission standard adoption in Indian states and MEE dual carbon goal enforcement in China's coastal provinces for early signals of specification acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Global Nylon Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market