
 PA66 Market | 2026-2036
PA66 Market Size, Share, and Industry Trends Forecast 2026-2036
PA66 Market Outlook
China's Zhejiang and Jiangsu provinces is tilting global PA66 supply balances as integrated chemical parks expand adiponitrile and hexamethylenediamine capacity. DuPont leverages its upstream control over key intermediates to sustain margin resilience across specialty resin grades. BASF SE anchors European automotive qualification pipelines with certified materials meeting OEM thermal performance benchmarks. Ascend Performance Materials operates one of North America's largest fully integrated PA66 chains, from petrochemical feedstock to engineered compounds.
Polyamide 66 is a semi-crystalline thermoplastic synthesized from adipic acid and hexamethylenediamine, distinguished by a melting point near 265°C and tensile strength exceeding 80 MPa in glass-filled grades. Its primary industrial purpose centers on replacing metal in high-temperature, load-bearing applications across powertrain, electrical connector, and industrial machinery systems. The resin segment dominates value capture due to compounder customization requirements and OEM qualification barriers, while recycled-grade PA66 represents the fastest-expanding grade category as automakers enforce post-consumer content mandates. Injection molding applications command the largest volume share, though 3D printing filament formulations are gaining traction for prototyping and spare-part digital inventories.
EPA emissions rules and REACH substance restrictions are forcing reformulation of flame-retardant PA66 compounds away from legacy halogenated systems. China's MEE enforces stricter wastewater discharge limits on adipic acid plants, raising capital requirements for new PA66 monomer investments. Germany's KBA type-approval process embeds material traceability standards that favor suppliers with certified quality management systems. Stakeholders must monitor adiponitrile technology licensing decisions, as bio-based and propylene-derived routes threaten to disrupt conventional benzene-feedstock economics.
Market Dynamics
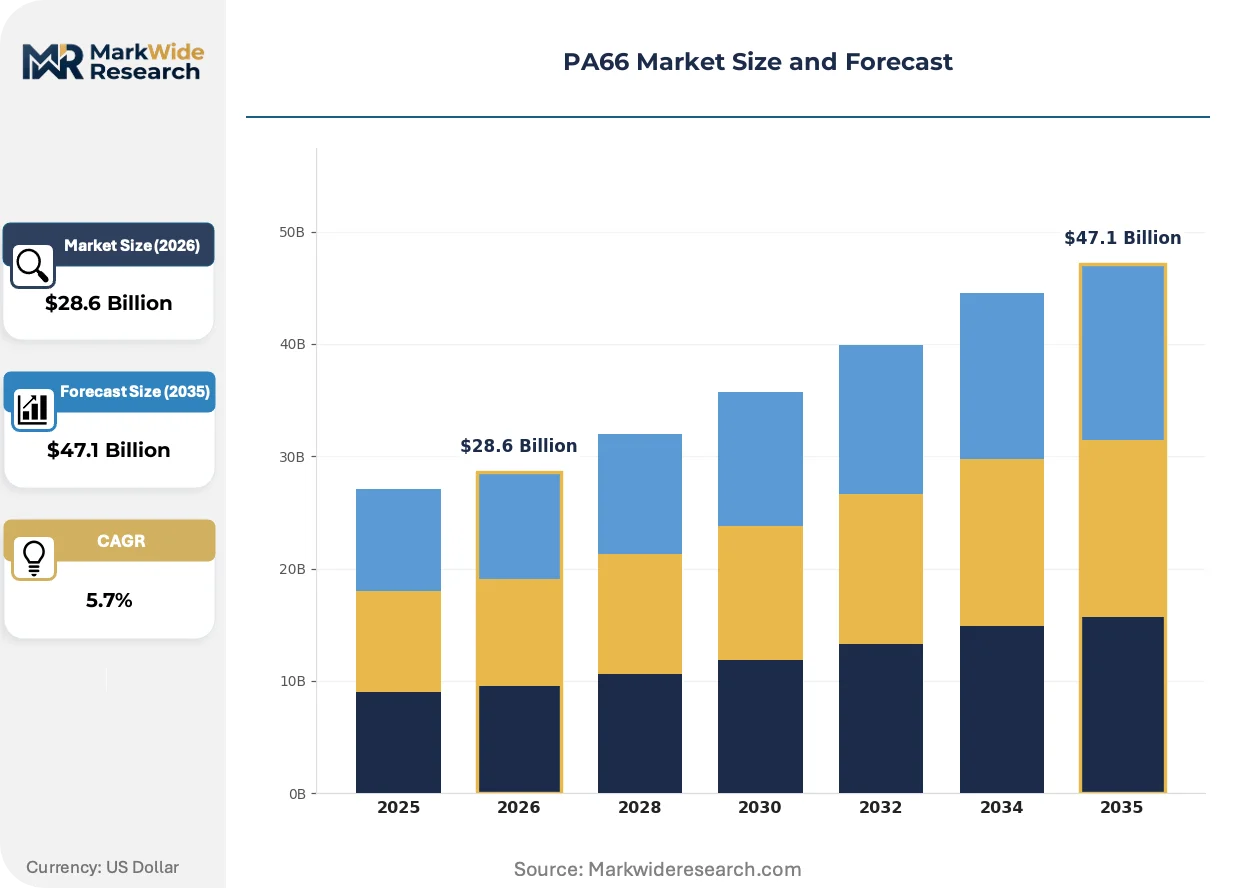
Automotive lightweighting mandates and REACH chemical compliance are restructuring PA66 supply chains, forcing compounders to certify recycled-grade materials while adiponitrile producers face capital-intensive wastewater upgrades under China's MEE discharge limits.
Growth Catalysts
- Automotive lightweighting programs:Germany's KBA type-approval process and China's GB standards for engineering plastics are accelerating metal-to-polymer substitution in powertrain components. OEM thermal performance benchmarks now favor certified PA66 grades.
- REACH substance restrictions:ECHA's tightening flame-retardant compound rules are redirecting formulation R&D toward halogen-free systems. Compounders with pre-certified sustainable portfolios capture qualification pipelines faster.
- East China chemical cluster expansion:Integrated adipic acid-to-polymer operations in Zhejiang and Jiangsu provinces are consolidating regional supply advantages. Captive hexamethylenediamine capacity reduces feedstock exposure for tier-one automotive suppliers.
Market Restraints
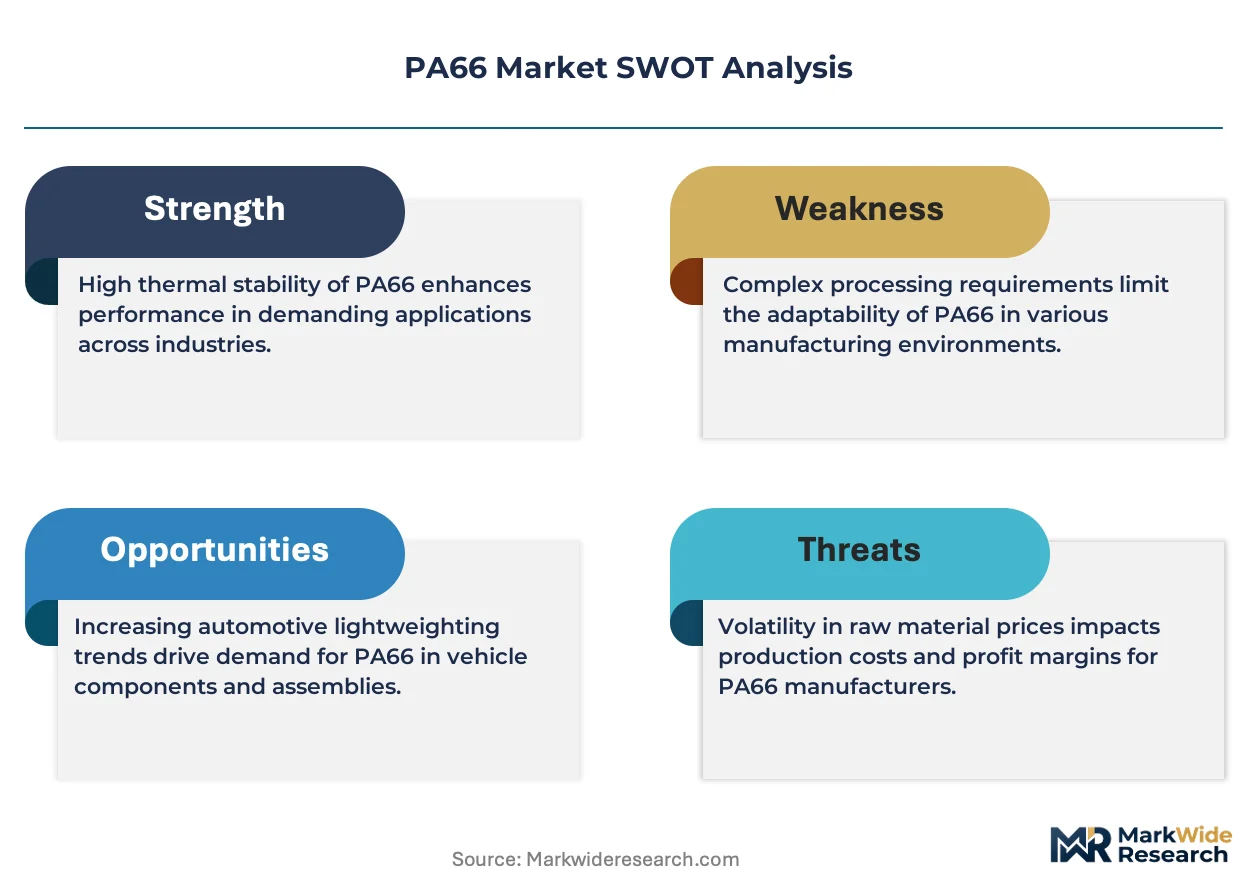
- Benzene-feedstock cost volatility:Conventional adiponitrile routes remain tethered to cyclohexane derivatives, exposing margins to naphtha-cracker economics. Bio-based and propylene-derived alternative technologies threaten incumbent cost structures.
- Upstream concentration risk:A handful of adiponitrile technology licensors control capacity expansion licensing decisions. New entrants face barriers securing process rights for integrated PA66 monomer investments.
- High-temperature performance ceiling:PA66's 265°C melting point limits under-the-hood applications as engine bay temperatures rise. Polyphthalamide and polyphenylene sulfide substitutes encroach on thermal-critical connector segments.
Strategic Opportunities
- Post-consumer content mandates:Automaker recycled-grade procurement quotas are creating certified-material premiums. Compounders with validated mechanical recycling streams capture OEM sustainability scorecard advantages.
- 3D printing filament formulations:Spare-part digital inventory programs in industrial machinery are opening prototyping-to-production pathways. Material extrusion systems favor glass-reinforced PA66 for functional end-use components.
- India's PLI scheme for engineering plastics:Domestic compounding capacity investments are accelerating as BIS standards align with automotive supplier qualification requirements. Localized resin production reduces landed cost disadvantages.
Industry Challenges
- OEM qualification timeline compression:Thermal performance benchmarking and material traceability documentation now require 18-24 month approval cycles. Compounders must maintain parallel certification tracks across multiple automaker platforms.
- Adipic acid plant wastewater compliance:China's MEE discharge limit enforcement is raising capital requirements for hexamethylenediamine expansion projects. Existing producers face retrofit obligations that strain project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PA66 Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.1 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibers, Resins, Compounds, Films End Use Industry: Automotive, Electrical & Electronics, Consumer Goods, Industrial Grade: Virgin, Recycled, Modified, Filled Application: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | DuPont, Radici Group, BASF SE, Evonik Industries, Toray Advanced Composite, Invista, Lanxess, Honeywell International Inc, Ascend Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PA66 Market Strategic Shifts
Advanced recycling technologies and regulatory chemical restrictions are restructuring how PA66 compounders source feedstocks and certify material grades for automotive and electrical applications.
Bio-based adipic acid production from renewable feedstocks is rendering obsolete conventional benzene-derived monomer economics for sustainability-focused OEM procurement programs. European automakers with science-based emissions targets are fast-tracking qualification of certified bio-attributed resin grades. This technology shift compresses the cost premium between conventional and sustainable PA66 over the analysis window.
REACH substance restrictions on halogenated flame retardants are forcing compound reformulation across electrical connector applications. ECHA's persistent organic pollutant screening criteria now exclude legacy brominated systems from new platform designs. Electrical infrastructure suppliers in Germany and France are accelerating phosphorous-nitrogen synergist compound approvals.
Automaker post-consumer content mandates are restructuring procurement specifications toward mass-balance certified and chemically recycled grades. Sustainability scorecard weighting now favors suppliers with verified circular material flows over virgin-resin pricing advantages. This behavioral shift concentrates demand in East China's integrated chemical parks with mechanical recycling capabilities.
PA66 Market Segmentation
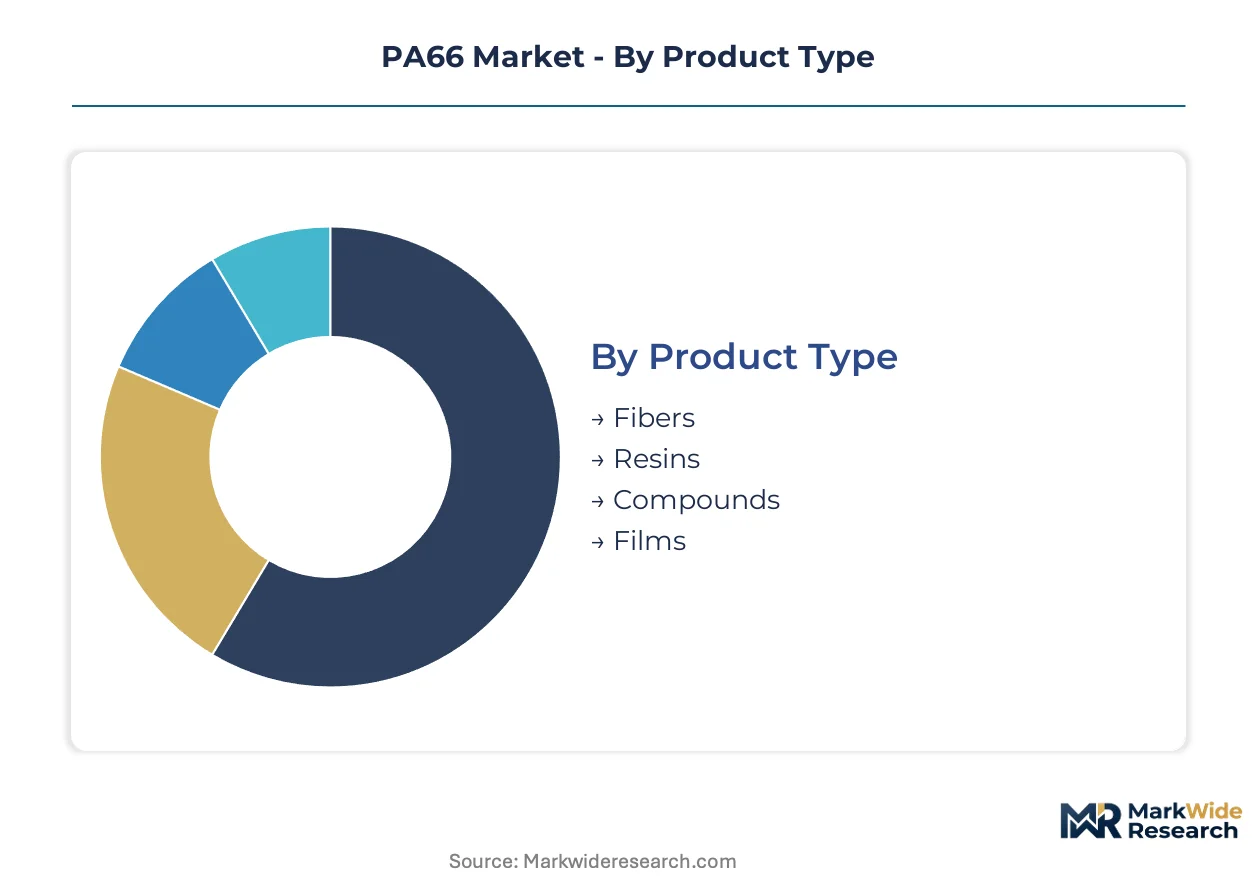
PA66 market segmentation reflects divergent technical requirements across automotive qualification pipelines and electrical connector specifications. Compounders configure resin grades, processing methods, and performance tiers to match OEM thermal benchmarks and sustainability procurement mandates.
Product Type:
After-sales service intensity varies sharply across product types, with compounds demanding formulation troubleshooting and resin grades requiring lot-to-lot certification support.
- Resins:Base polymer pellets synthesized from adipic acid and hexamethylenediamine serve compounders and direct molders with standard viscosity grades. Automotive suppliers in Germany's KBA approval system specify certified resin lots for powertrain component traceability.
- Compounds:Glass-filled and flame-retardant formulations incorporate additives during twin-screw extrusion to meet OEM thermal performance benchmarks. Electrical infrastructure suppliers in France accelerate phosphorous-nitrogen synergist approvals under ECHA screening criteria.
- Fibers:Industrial yarn and staple fiber for technical textiles and carpet applications.
- Films:Biaxially oriented and cast film structures for flexible packaging and industrial laminates.
Resins hold the largest share; momentum sits with compounds as OEMs tighten material certification requirements.
End Use Industry:
Cost tier stratification separates premium-qualified automotive grades from standard industrial applications.
- Automotive:Under-the-hood components including air intake manifolds, radiator end tanks, and engine covers substitute metal for polymer weight reduction. China's GB standards for engineering plastics accelerate metal-to-polymer substitution in powertrain systems.
- Electrical & Electronics:Connectors, circuit breakers, and housings leverage PA66's dielectric strength and UL94 flame-retardant ratings. REACH substance restrictions on halogenated systems force reformulation toward phosphorous-nitrogen synergist compounds.
- Industrial:Gears, bearings, and conveyor components utilize wear-resistant grades.
- Consumer Goods:Appliance housings and sporting equipment applications.
Automotive commands premium pricing; electrical and electronics is expanding most quickly as infrastructure electrification accelerates connector demand.
Grade:
Volume concentration favors virgin material, though sustainability procurement quotas restructure demand toward circular alternatives.
- Virgin:Petroleum-derived adipic acid and hexamethylenediamine polymerization yields standard-performance resin with consistent lot properties. East China's Yangtze River Delta chemical cluster anchors integrated adipic acid-to-polymer operations for tier-one automotive suppliers.
- Recycled:Post-industrial and post-consumer mechanical recycling streams produce certified circular grades. Automaker sustainability scorecards now weight verified material flows above virgin-resin pricing advantages.
- Modified:Heat-stabilized and hydrolysis-resistant grades for extended service temperature ranges.
- Filled:Mineral and glass fiber reinforcement for dimensional stability and creep resistance.
Virgin grades dominate current volume; recycled grades are gaining share fastest as post-consumer content mandates harden.
Application:
Customer type segmentation separates high-volume automotive molders from prototyping service bureaus and industrial extrusion houses.
- Injection Molding:High-pressure molding of complex geometries for automotive and electrical components dominates processing volume. OEM qualification timelines now require 18-24 month approval cycles with parallel certification tracks across multiple automaker platforms.
- 3D Printing:Filament formulations for fused deposition modeling enable spare-part digital inventory programs in industrial machinery. Glass-reinforced PA66 filaments bridge prototyping to functional end-use production.
- Extrusion:Profile, sheet, and monofilament production for industrial and textile applications.
- Blow Molding:Hollow part production for fluid handling and packaging applications.
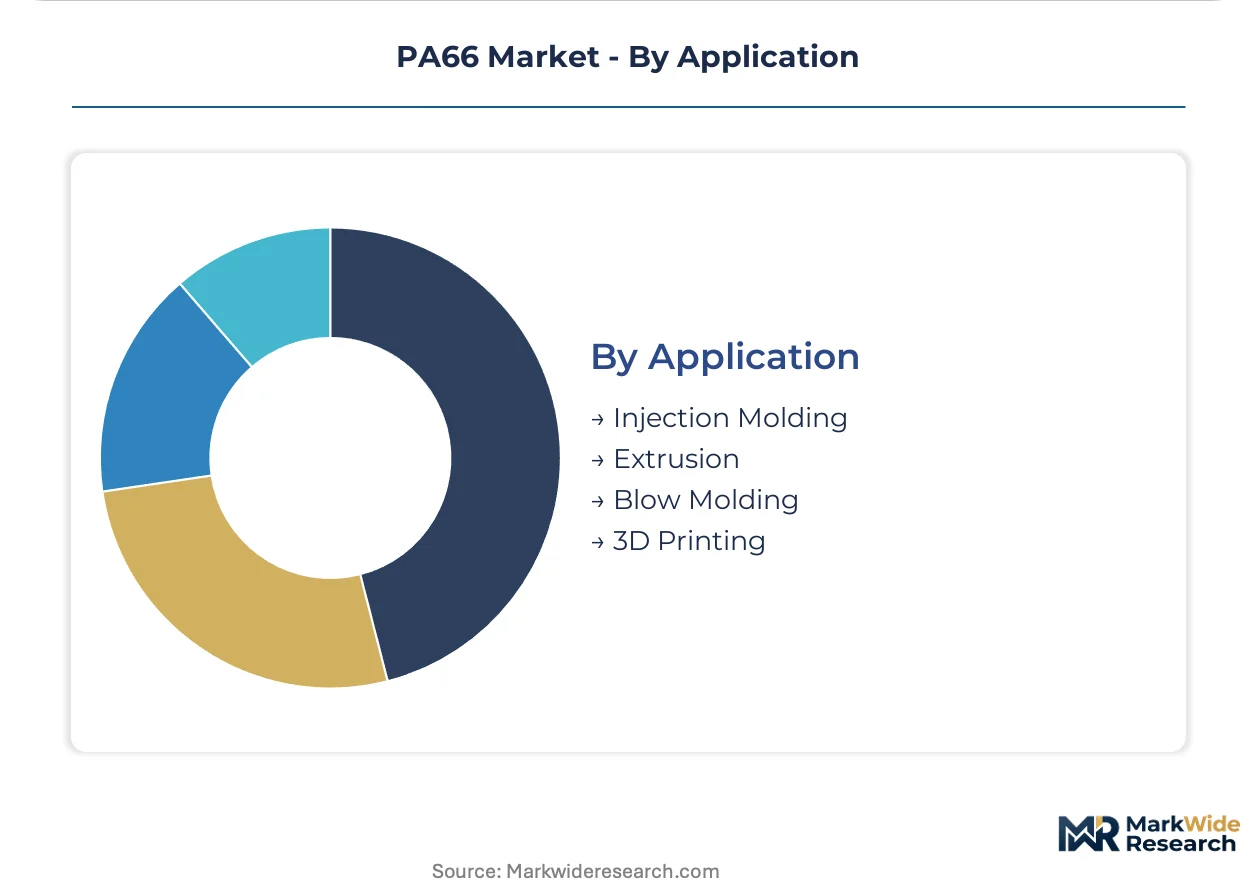
Injection molding retains the largest volume position; 3D printing shows the steepest expansion trajectory as digital inventory programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive lightweighting intensity varies sharply by geography, with Germany and China prioritizing under-the-hood metal substitution while the United States emphasizes electrical connector applications for infrastructure electrification.
China
Zhejiang and Jiangsu provinces host integrated adipic acid-to-polymer operations serving tier-one automotive suppliers. MEE wastewater discharge limits on adipic acid plants are raising capital requirements for hexamethylenediamine expansion projects. The Yangtze River Delta chemical cluster consolidates regional supply advantages through captive feedstock integration.
Germany
KBA type-approval processes embed material traceability standards that favor suppliers with certified quality management systems. REACH substance restrictions on halogenated flame retardants redirect formulation R&D toward phosphorous-nitrogen synergist compounds. Bavaria and Baden-Württemberg anchor European automotive qualification pipelines with OEM thermal performance benchmarking facilities.
United States
EPA emissions rules force reformulation of flame-retardant PA66 compounds away from legacy halogenated systems. Infrastructure electrification accelerates demand for high-temperature electrical connectors in grid modernization projects. The Gulf Coast petrochemical corridor sustains integrated adiponitrile production economics despite naphtha-cracker feedstock volatility.
India
PLI scheme incentives for engineering plastics accelerate domestic compounding capacity investments as BIS standards align with automotive supplier qualification requirements. Maharashtra and Gujarat concentrate polymer processing infrastructure for powertrain component localization. Tier-one suppliers reduce landed cost disadvantages through regional resin production partnerships.
Japan
METI industrial standards enforce rigorous material certification for automotive and electrical applications. Kansai and Chubu regions maintain precision compounding capabilities for high-performance connector grades. Domestic automakers source certified resin lots with consistent lot-to-lot properties for hybrid powertrain thermal management systems.
PA66 Market Competitive Environment
Capability concentration sits with integrated monomer producers; scale advantage sits with compounders with validated OEM qualification pipelines. The market structures around three tiers: upstream adiponitrile technology licensors, midstream resin producers with captive feedstock, and downstream compounders serving automotive and electrical specification markets. Strategic moves concentrate on securing bio-based feedstock certifications and expanding mechanical recycling capabilities for post-consumer content mandates.
Among North American integrated producers, Ascend Performance Materials exemplifies upstream-to-compound vertical control, while DuPont anchors specialty resin grade development through intermediate supply security. BASF SE represents European qualification pipeline dominance with certified materials meeting OEM thermal benchmarks. These three occupy positions across the capability-scale spectrum, with integrated feedstock control separating upstream specialists from formulation-dependent compounders.
| Leading Market Players |
|---|
| DuPont |
| Radici Group |
| BASF SE |
| Evonik Industries |
| Toray Advanced Composite |
| Invista |
| Lanxess |
| Honeywell International Inc |
| Ascend Performance Materials |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Jiangsu provinces in East China concentrate integrated adipic acid-to-polymer capacity, granting regional producers pricing leverage over downstream compounders dependent on captive hexamethylenediamine supply. This feedstock integration shapes contract negotiations with tier-one automotive suppliers seeking certified resin lots.
Pricing Analysis
Long-term offtake contracts dominate automotive qualification pipelines, insulating qualified suppliers from spot-market volatility while locking in volume commitments. Price differentiation separates certified recycled-grade compounds from virgin resin, with sustainability scorecard weighting commanding premiums. Pricing pressure stems from bio-based adipic acid routes compressing cost premiums between conventional and sustainable grades. Tier-two molders exhibit highest price sensitivity, whereas OEMs with KBA type-approval requirements prioritize certified material security over unit economics.
Supply Chain Analysis
Benzene-derived cyclohexane feedstock anchors conventional adiponitrile economics, drawing from naphtha-cracker output concentrated in China, Germany, and the United States Gulf Coast. Raw material dependencies span adipic acid, hexamethylenediamine, and glass fiber reinforcement. Single-source vulnerability concentrates in adiponitrile technology licensing, where a handful of licensors control capacity expansion rights. Distribution runs through compounder networks serving qualified automotive and electrical specification markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PA66 demand tracks automotive production cycles, with lightweighting mandates in Germany and China signaling recovery-phase inventory restocking by tier-one suppliers.
For Market Incumbents: Entrench qualification pipeline advantages by expanding mechanical recycling capabilities ahead of hardening post-consumer content mandates. Secure backward integration into adiponitrile intermediates to defend margin position against bio-based route disruption. Prioritize parallel certification tracks across multiple OEM platforms to compress 18-24 month approval timelines. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme-supported compounding capacity, where BIS standard alignment creates qualification pathways without incumbent certification backlogs. Target 3D printing filament formulations for industrial machinery spare-part digital inventories. Leverage phosphorous-nitrogen flame-retardant compound expertise to capture electrical infrastructure substitution demand under ECHA screening criteria. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with validated OEM pipelines over upstream monomer capacity exposed to feedstock volatility. Five-to-ten-year viability rests on circular material flow verification capabilities. Monitor adiponitrile technology licensing decisions as inflection signal for conventional route obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adiponitrile | Captive hexamethylenediamine supply reduces feedstock exposure for compounders serving KBA-qualified automotive programs. |
| Mechanical Recycling Capacity Expansion | Validated post-consumer streams capture OEM sustainability scorecard premiums under tightening procurement quotas. |
| Halogen-Free Flame-Retardant Certification | ECHA persistent organic pollutant screening redirects electrical connector formulation toward phosphorous-nitrogen synergist compounds. |
| Long-Term Automotive Supply Agreement | Offtake commitments with tier-one suppliers lock in volume through cyclical downturns and raw material volatility. |
| Bio-Based Adipic Acid Partnership | Renewable feedstock certification aligns with European automaker science-based emissions targets and compresses sustainable grade premiums. |
Study Parameters
A spread of perspectives from adipic acid plant managers, automotive procurement leads at tier-one suppliers, distribution channel partners, and technical R&D directors converged on the working assumptions for capacity expansion and qualification timelines. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE wastewater discharge enforcement records. Bottom-up resin consumption estimates triangulated against top-down polymer production capacity assessments.
Demand-supply-balance framing anchored the analytical approach across the analysis window, modeling segmentation dimensions including grade tier, end-use industry, processing method, and regional production hub. CAGRs derived from production capacity buildout schedules weighted against automotive lightweighting program commitments and electrical infrastructure electrification capex. Industry-specific forecast inputs incorporated adiponitrile technology licensing timelines and REACH substance restriction implementation phases.
Macroeconomic conditions sit as an overlay; deviation in naphtha-cracker economics, automotive production volumes, or MEE enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about bio-based route cost convergence and OEM post-consumer content mandate timing. Cross-checking against IHS Markit vehicle production databases and Cefic polymer trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Plastic Calendering Resins Market