
 North America Polyurethane Market | 2026-2036
North America Polyurethane Market Size, Share, and Industry Trends Forecast 2026-2036
North America Polyurethane Market Analytics
Direct distribution from resin producers to large construction and automotive OEMs is narrowing as specialty distributors consolidate their positions in the coatings and adhesives tier. Covestro AG leverages its backward integration into isocyanate precursors to sustain cost advantages across rigid foam supply chains. BASF SE anchors its North American position through technology leadership in spray polyurethane systems for commercial insulation. Huntsman International LLC differentiates via specialized formulations serving automotive seating producers in the Midwest manufacturing belt.
Polyurethane denotes a class of polymers formed through the exothermic reaction between diisocyanates and polyols, yielding materials with tunable density, elasticity, and thermal resistance ranging from flexible foams at 15-30 kg/m³ to rigid insulation boards exceeding 30 kg/m³. These materials serve as essential components across thermal barriers, cushioning systems, protective coatings, and structural adhesives. Flexible foam applications in furniture and automotive interiors represent mature volume pools with stable margins, while rigid foam for insulation commands premium positioning driven by escalating building energy efficiency mandates. Coatings and adhesives segments are attracting formulation investment as manufacturers pursue higher-value specialty grades resistant to abrasion and chemical exposure.
EPA regulations under the Significant New Alternatives Policy constrain blowing agent chemistries in foam production, compelling reformulation toward lower-global-warming-potential options. OSHA workplace exposure limits for isocyanates shape manufacturing site requirements and personal protective equipment protocols across US production facilities. California's Title 24 building energy standards and comparable codes in Ontario and British Columbia directly elevate demand for high-R-value rigid foam insulation in residential and commercial envelopes. Stakeholders must monitor evolving state-level amendments to energy codes and EPA enforcement timelines to align capital deployment with compliant product platforms.
Market Dynamics
EPA's Significant New Alternatives Policy is forcing a wholesale transition in blowing agent chemistry across North American foam production, compressing reformulation timelines while elevating capital requirements for compliant manufacturing platforms.
Growth Catalysts
- California Title 24 standards:Building energy codes in California and comparable regulations in Ontario mandate high-R-value rigid foam insulation, directly elevating specification rates for spray polyurethane systems in commercial envelope construction.
- Automotive lightweighting:Seating and interior component producers across Michigan and Ohio are expanding polyurethane consumption to meet corporate average fuel economy targets through density-reduced foam formulations.
- US Gulf Coast feedstock access:Concentrated petrochemical infrastructure along the Texas-Louisiana corridor provides isocyanate and polyol producers with integrated supply economics unavailable to inland competitors.
Market Restraints
- Isocyanate price volatility:MDI and TDI feedstock costs fluctuate with benzene and toluene spot markets, compressing margin stability for non-integrated foam compounders serving construction and automotive tiers.
- Canadian supply concentration:Ontario and Quebec host limited domestic isocyanate production, creating import dependency and currency exposure for Canadian insulation manufacturers serving residential markets.
- Technical limitations in bio-based polyols:Renewable feedstock-derived polyols exhibit inconsistent hydroxyl values and moisture sensitivity, constraining their adoption in high-performance rigid foam applications requiring precise reaction kinetics.
Strategic Opportunities
- Mexico automotive expansion:OEM assembly capacity growth in Aguascalientes and Guanajuato creates demand for just-in-time foam seating and interior component supply from cross-border US producers.
- Canadian federal green building incentives:The Canada Greener Homes Initiative subsidizes deep energy retrofits, expanding addressable market for high-performance spray foam contractors in British Columbia and Alberta.
- Waterborne polyurethane dispersion technology:Convergence of low-VOC coating chemistry with UV-curable systems enables furniture and flooring manufacturers to eliminate solvent-based formulations while maintaining abrasion resistance.
Industry Challenges
- Isocyanate handling certification:OSHA respiratory protection and medical surveillance requirements for diisocyanate exposure create workforce qualification bottlenecks, extending hiring timelines for production facilities in Texas and Ohio.
- Legacy equipment retrofit costs:Transitioning existing slabstock foam lines to low-global-warming-potential blowing agents requires pressurized storage and metering system upgrades, straining capital allocation for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Polyurethane Market |
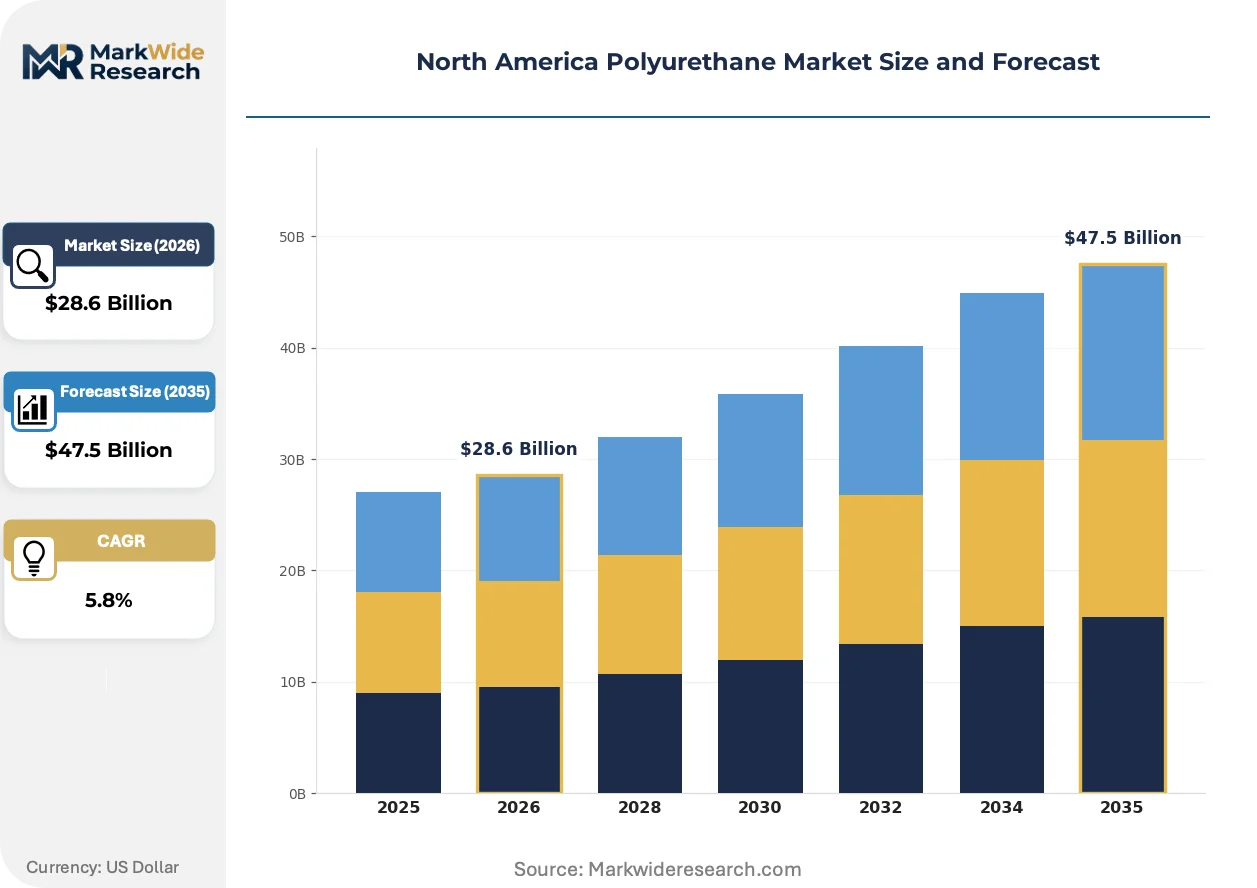
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives Application: Furniture, Automotive Interiors, Insulation, Footwear End User: Construction, Automotive, Consumer Goods, Electronics Form: Solid, Liquid, Gel, Spray |
| Companies Covered | Covestro AG, BASF SE, Huntsman International LLC, Dow, LANXESS, Mitsubishi Chemical Group Corporation, The Lubrizol Corporation, Eastman Chemical Company, RAMPF Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Polyurethane Market Evolving Landscape
Formulation chemistry and manufacturing process control are converging to enable precise density grading within single foam components, collapsing traditional trade-offs between cushioning comfort and structural support.
Hydrofluoroolefin blowing agents are collapsing the performance gap between legacy HFC systems and next-generation insulation requirements. Commercial roofing contractors across the US Sun Belt are specifying HFO-blown spray foam at accelerating rates to meet utility rebate thresholds. This transition is compressing the viable product portfolio for compounders unable to secure supply agreements with HFO licensors.
EPA enforcement timelines under the Significant New Alternatives Policy are accelerating facility-level compliance investments. The agency's phased restrictions on high-global-warming-potential blowing agents are compelling rigid foam producers to validate alternative chemistries through third-party certification. California's Air Resources Board maintains parallel enforcement authority, creating dual-jurisdiction complexity for multi-state manufacturers.
Specification authority is migrating from general contractors to building envelope consultants and energy modelers. These technical intermediaries now control insulation material selection through whole-building performance simulations, displacing traditional distributor relationships in commercial construction procurement. This shift is most visible in Pacific Northwest markets where municipal benchmarking ordinances mandate disclosed energy performance.
North America Polyurethane Market Segmentation
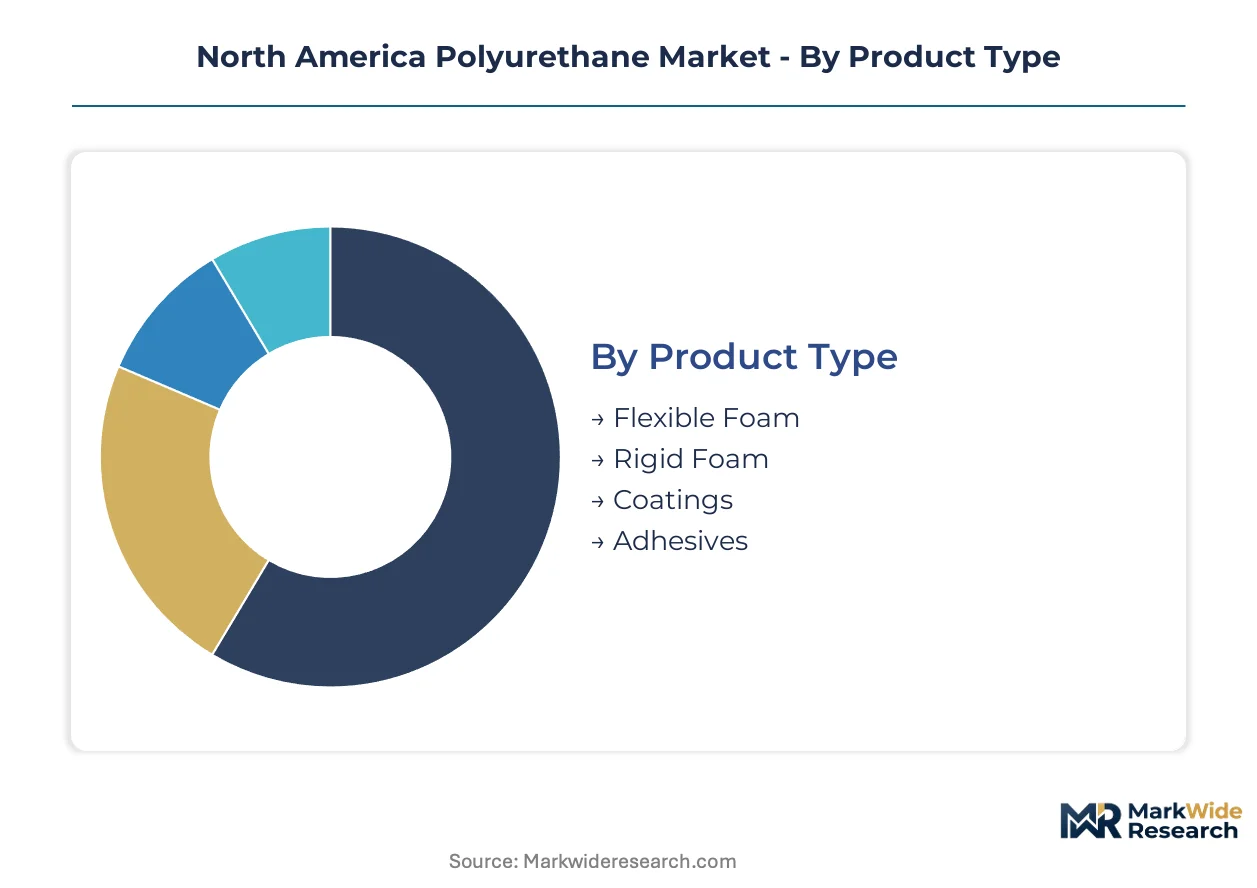
Polyurethane's tunable chemistry enables precise matching of density, elasticity, and thermal properties to end-use requirements. Segmentation reveals how formulation choices align with regulatory pressures and specification authority shifts across North American construction and manufacturing tiers.
Product Type:
Application requirements dictate density ranges from 15 kg/m³ cushioning systems to structural boards exceeding 30 kg/m³, with each product type commanding distinct margin profiles and reformulation timelines.
- Flexible Foam:Open-cell structures at 15-30 kg/m³ deliver compression set resistance for seating and bedding applications. Automotive seating producers in Michigan and Ohio specify density-graded formulations to meet corporate average fuel economy targets through component lightweighting. Furniture manufacturers concentrate procurement among compounders with slabstock continuous production capability.
- Rigid Foam:Closed-cell insulation boards and spray systems achieve thermal resistance values mandated by California Title 24 and comparable Ontario energy codes. Commercial envelope consultants in Pacific Northwest markets specify these systems through whole-building performance simulations, bypassing traditional distributor channels. EPA Significant New Alternatives Policy enforcement is compressing reformulation timelines for blowing agent chemistry transitions.
- Coatings:Abrasion-resistant formulations serve industrial flooring and protective applications with solventborne and waterborne chemistry options.
- Adhesives:Structural bonding systems integrate with composite manufacturing across transportation and construction assembly operations.
Flexible foam holds installed capacity across mature furniture and automotive supply chains. Rigid foam is rotating up the share rankings as building energy codes tighten across US states and Canadian provinces.
Application:
End-use performance requirements vary dramatically across comfort, thermal barrier, and structural functions, with specification authority migrating toward technical intermediaries in commercial construction.
- Furniture:Mattress and upholstery producers specify indentation force deflection ratings to match comfort profiles with durability standards. Residential bedding manufacturers concentrate procurement in Southeast US production clusters where foam fabrication integrates with textile finishing operations.
- Automotive Interiors:Seating, headliner, and instrument panel applications demand flame-retardant formulations meeting FMVSS 302 standards. Tier-1 suppliers across the Midwest manufacturing belt coordinate just-in-time delivery to OEM assembly plants, with cross-border supply extending to Mexican facilities in Aguascalientes and Guanajuato.
- Insulation:Residential and commercial building envelopes specify spray polyurethane systems and rigid board stock to achieve code-compliant R-values. Energy modelers and envelope consultants now control material selection through performance simulation workflows, displacing general contractor authority in procurement decisions.
- Footwear:Midsole and insole applications combine cushioning response with abrasion resistance for athletic and safety footwear categories.
Furniture maintains volume concentration across established supply relationships. Insulation is gaining share fastest as federal and provincial retrofit incentives expand addressable markets.
End User:
Customer scale and procurement sophistication separate specification-driven segments from price-sensitive commodity procurement.
- Construction:General contractors, specialty envelope subcontractors, and deep energy retrofit contractors purchase rigid foam systems through distributor and direct channels. Canada Greener Homes Initiative subsidies in British Columbia and Alberta are expanding demand for high-performance spray foam installation services.
- Automotive:OEM seating divisions and Tier-1 interior component suppliers specify density-reduced formulations to achieve lightweighting targets. Just-in-time delivery requirements favor compounders with production proximity to assembly plants across Michigan, Ohio, and northern Mexico.
- Consumer Goods:Furniture and bedding manufacturers procure flexible foam through long-term supply agreements with slabstock producers.
- Electronics:Encapsulation and potting applications demand precise viscosity control and thermal management properties.
Construction commands premium positioning through code-driven specification. Automotive maintains stable volume pools with integrated supply chain coordination requirements.
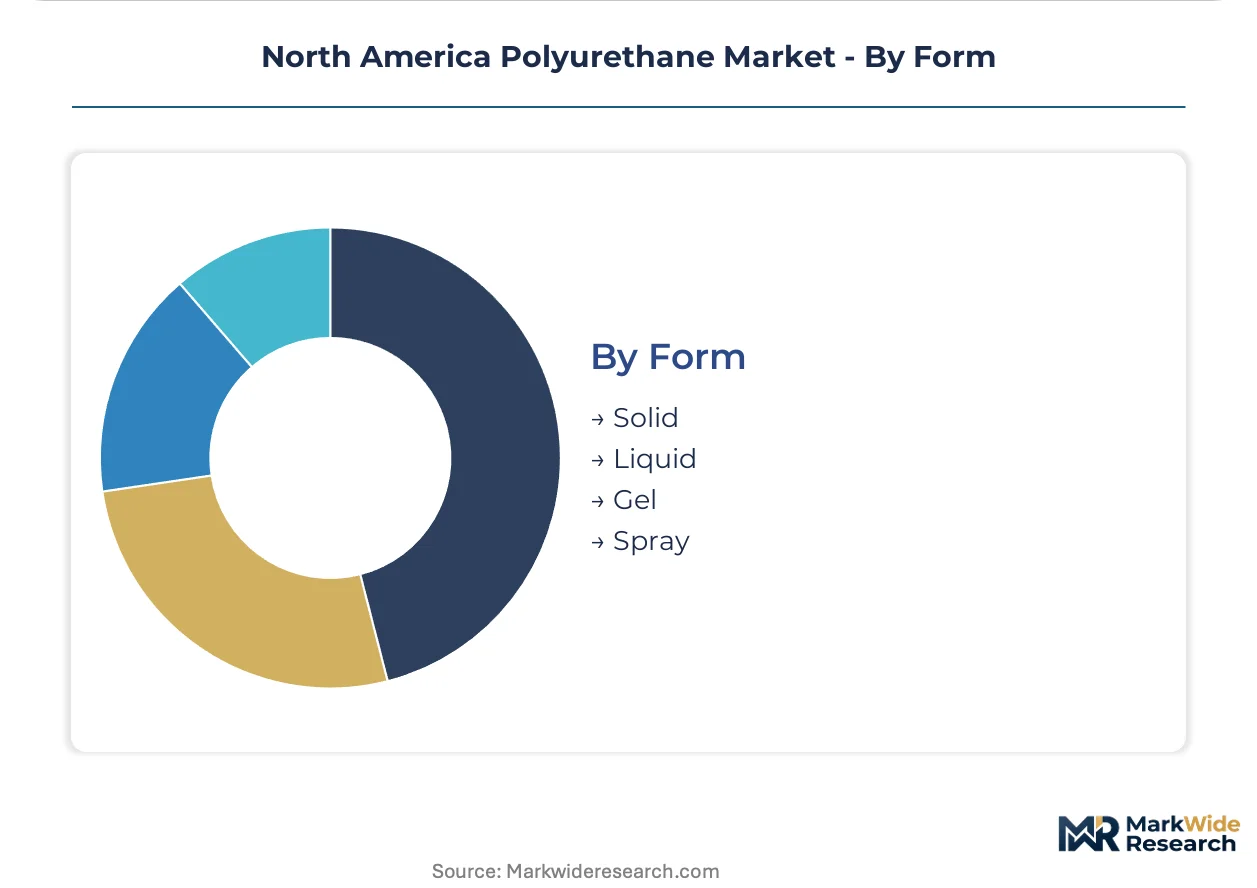
Form:
Physical state determines application methodology, equipment requirements, and field-level workforce certification needs.
- Solid:Molded and fabricated components serve furniture cushioning, automotive interior trim, and industrial gasket applications with precise dimensional tolerances.
- Liquid:Two-component systems for pour-in-place insulation, adhesive bonding, and coating applications require precise metering and mixing equipment. Isocyanate handling certification under OSHA respiratory protection standards creates workforce qualification bottlenecks for production facilities.
- Gel:Viscoelastic formulations provide pressure distribution for medical and comfort applications with slow recovery characteristics.
- Spray:On-site applied insulation systems enable complex envelope geometries and air sealing integration. Commercial roofing contractors across the US Sun Belt are specifying hydrofluoroolefin-blown formulations at accelerating rates to meet utility rebate thresholds and EPA compliance timelines.
Solid forms maintain manufacturing efficiency across high-volume fabrication. Spray systems are climbing the fastest as building retrofit activity intensifies and envelope performance standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedstock-advantaged producers along the US Gulf Coast command pricing leverage over Canadian compounders facing import dependency on isocyanates. Mexican automotive expansion is redrawing cross-border supply corridors.
United States
California Title 24 energy codes and utility rebate programs in the Sun Belt drive specification of high-R-value spray foam systems. EPA Significant New Alternatives Policy enforcement compels reformulation toward hydrofluoroolefin blowing agents. The Texas-Louisiana petrochemical corridor anchors integrated isocyanate and polyol production serving downstream foam fabricators.
Canada
The Canada Greener Homes Initiative subsidizes deep energy retrofits in British Columbia and Alberta, expanding demand for spray foam installation services. Ontario and Quebec rely on US isocyanate imports, exposing compounders to currency fluctuation and cross-border logistics costs. Toronto-area insulation contractors face compressed margins from feedstock price volatility.
Mexico
OEM assembly capacity growth in Aguascalientes and Guanajuato creates demand for just-in-time foam seating and interior components. Mexican automotive producers coordinate cross-border supply from US compounders in Texas and the Midwest. Nuevo León's manufacturing belt attracts tier-1 interior suppliers seeking proximity to assembly plants.
North America Polyurethane Market Competitive Landscape
Backward-integrated resin producers and specialty formulation houses split the market into distinct competitive spheres. Concentration is moderate at the precursor level, with isocyanate production clustering around Gulf Coast feedstock infrastructure, while downstream foam compounding remains fragmented across regional service territories. Two archetypes dominate: integrated chemical conglomerates controlling precursor supply, and specialized compounders serving niche automotive and construction applications. Competitive moves center on capacity expansion for low-global-warming-potential blowing agent platforms and strategic partnerships with building envelope consultants who now control specification authority.
Within the integrated chemical tier, Covestro AG and BASF SE exemplify producers leveraging captive isocyanate supply to sustain cost positions across rigid foam value chains. Huntsman International LLC occupies a position as a formulation specialist serving automotive seating producers with density-graded systems. These three anchors demonstrate how strategic positioning around feedstock access, technical service capability, and end-use specialization defines competitive differentiation in a market where regulatory compliance timelines compress reformulation windows.
| Leading Market Players |
|---|
| Covestro AG |
| BASF SE |
| Huntsman International LLC |
| Dow |
| LANXESS |
| Mitsubishi Chemical Group Corporation |
| The Lubrizol Corporation |
| Eastman Chemical Company |
| RAMPF Group |
| Others |
Value Network & Pricing Analysis
US Gulf Coast isocyanate concentration feeds margin capture downstream, with benzene-tethered MDI and TDI producers commanding pricing leverage over inland compounders lacking backward integration into petrochemical precursors.
Pricing Analysis
Configured-to-order pricing for spray polyurethane systems commands 15-25% premiums over standard rigid board stock, reflecting formulation complexity and on-site application certification requirements. Price differentiation hinges on blowing agent chemistry tier—HFO-blown systems trade at premiums to legacy HFC formulations—and volume scale, with national roofing contractors securing indexed contracts unavailable to regional installers. Cost compression in commodity flexible foam is intensifying because furniture manufacturers are consolidating procurement among slabstock producers with continuous line efficiency. Tier-1 automotive seating suppliers exhibit lowest price sensitivity, prioritizing density-graded formulations and just-in-time reliability over per-kilogram costs.
Supply Chain Analysis
Export-control regimes on specialty catalysts and HFO blowing agent technology constrain technology transfer, limiting domestic production scale-up for compliant foam systems outside licensed jurisdictions. Geographic supply concentration centers on the United States, Germany, and Japan for isocyanate precursors, with Chinese polyol capacity expanding but facing tariff exposure on aromatic inputs. Raw material dependencies rest on benzene-toluene-xylene streams, adipic acid for nylon-linked polyols, and propylene oxide for polyether polyol backbone construction. Single-source vulnerability concentrates around HFO-1234ze and HFO-1336mzz blowing agent supply, where two licensors control North American access. Distribution runs through petrochemical majors to large construction OEMs, with specialty distributors consolidating positions in coatings and adhesives tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray foam installation services and ongoing envelope performance monitoring represent expanding recurring-revenue layers outpacing commodity foam sales, as building owners face escalating energy benchmarking disclosure requirements.
For Market Incumbents: Build certification moats around OSHA isocyanate handling credentials and EPA SNAP compliance validation. Expand captive HFO blowing agent storage capacity in Texas and Louisiana to secure supply continuity as reformulation deadlines compress. Acquire regional spray foam contractors in Pacific Northwest markets where envelope consultants control specification authority, displacing traditional distributor relationships. For New Entrants and Emerging Players: Pursue white-space positioning in Canadian deep energy retrofit markets subsidized by federal Greener Homes Initiative funding, where incumbent coverage remains thin in British Columbia and Alberta. Target waterborne polyurethane dispersion technology for furniture and flooring manufacturers eliminating solvent-based coatings under California air quality regulations. Establish technical service partnerships with building envelope consultants rather than competing through distributor channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional foam compounders lacking HFO transition capital, presenting consolidation candidates for integrated resin producers seeking downstream service capabilities. Five-to-ten year viability hinges on successful navigation of EPA enforcement timelines and state-level energy code adoption velocity. Watch for inflection signals in municipal benchmarking ordinance expansion beyond Pacific Northwest markets into Midwest and Sun Belt jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| HFO Blowing Agent Capacity Expansion | Secures EPA SNAP compliance ahead of phased HFC restrictions affecting rigid foam producers. |
| Backward Integration into Propylene Oxide | Captures polyol precursor margins and insulates against feedstock volatility from Gulf Coast crackers. |
| Spray Foam Contractor Acquisition | Locks in specification access as envelope consultants displace general contractor procurement authority. |
| Waterborne Polyurethane Dispersion R&D | Enables furniture manufacturers to meet California CARB VOC limits without sacrificing abrasion resistance. |
| Cross-Border Mexican Automotive Supply | Positions just-in-time delivery networks for OEM seating plants in Aguascalientes and Guanajuato. |
Research Methodology
A standing panel of plant managers at Gulf Coast petrochemical facilities, procurement leads at Midwest automotive Tier-1 suppliers, spray foam installation contractors across California and Texas, and technical directors at building envelope consulting firms provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with customs and trade data from the American Chemistry Council, EPA enforcement disclosure records, SEC 10-K filings from integrated chemical producers, and state-level energy code adoption tracking. Bottom-up volume modeling triangulated against top-down value estimates derived from petrochemical feedstock consumption patterns.
Scenario bracketing around EPA SNAP enforcement velocity, California Title 24 amendment adoption, and Canadian federal retrofit subsidy renewal framed projection ranges across the analysis window. Segmentation modeling incorporated product type tier, end-use industry vertical, formulation chemistry class, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves calibrated to historical code adoption patterns and automotive production forecasts. Industry-specific inputs included HFO blowing agent licensing timelines, isocyanate plant turnaround schedules, and municipal benchmarking ordinance expansion trajectories.
Sensitivities concentrate around EPA enforcement acceleration, state-level energy code stringency revisions, and feedstock price volatility from benzene-toluene spot market disruption. Forecasts reflect documented assumptions on HFO supply scale-up, contractor workforce expansion rates, and cross-border automotive production coordination. Material shifts in federal green building incentive structures or OSHA isocyanate exposure threshold reductions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Global Hydroxypropyl Cellulose Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Foamed Plastics Market