
 South America Polyvinyl Chloride (PVC) Market | 2026-2036
South America Polyvinyl Chloride (PVC) Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polyvinyl Chloride (PVC) Market Analytics
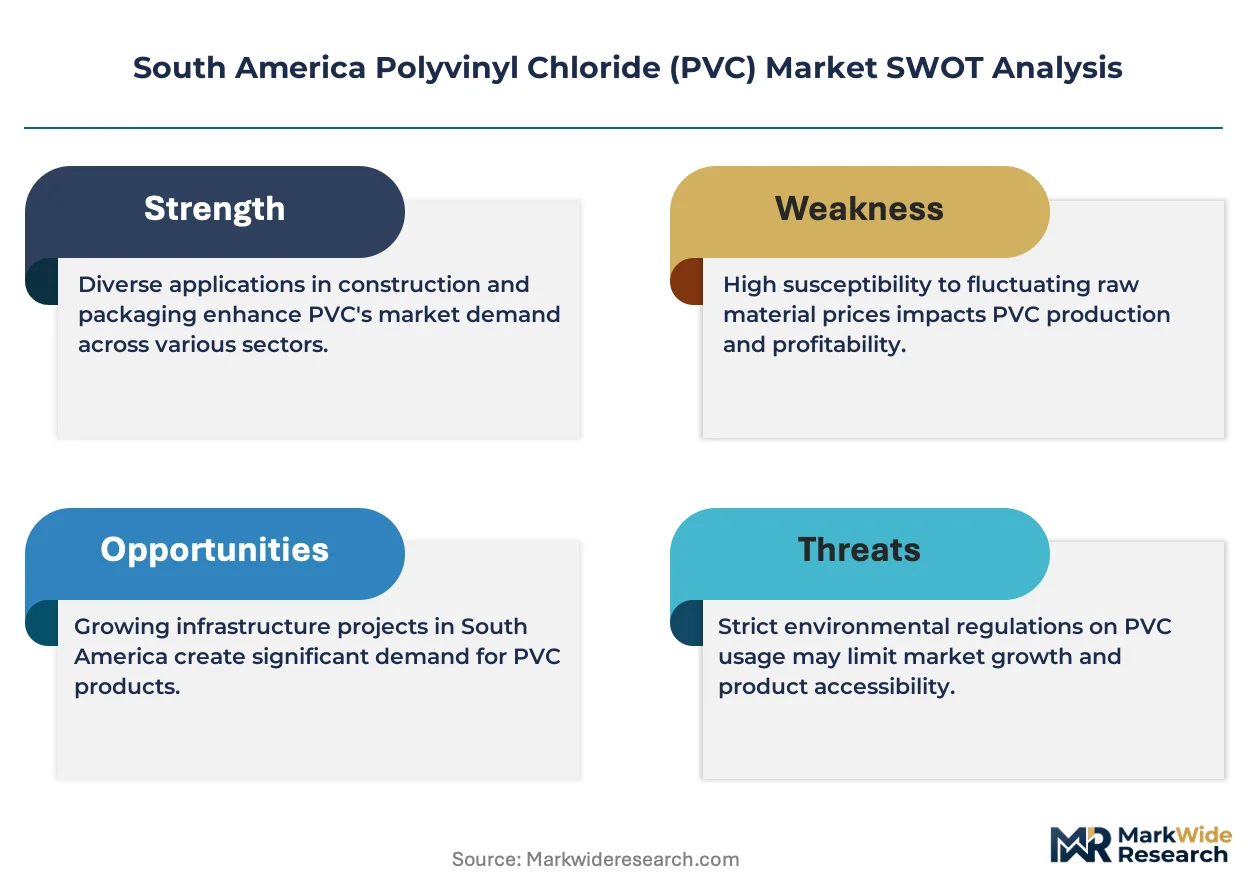
High-purity suspension-grade PVC resin is rotating toward dominance as infrastructure specifications tighten across South America. Braskem leverages its integrated petrochemical complexes in Brazil to control feedstock costs and secure supply continuity for regional construction markets. Orbia anchors its position through specialized chlor-alkali and PVC operations that sustain captive chlorine supply chains. Unipar Carbocloro differentiates by concentrating production scale on domestic Brazilian demand while navigating import substitution pressures.
Polyvinyl chloride is a thermoplastic polymer synthesized from vinyl chloride monomer through suspension, emulsion, or bulk polymerization processes, with suspension polymerization yielding the dominant general-purpose grades characterized by controlled particle size and porosity for plasticizer absorption. Its primary industrial purpose centers on replacing metal, wood, and concrete in piping, siding, wire insulation, and profile extrusions where corrosion resistance and cost efficiency prove decisive. Rigid PVC commands the largest volume share across the region's construction pipeline and electrical conduit applications, while flexible PVC expands fastest in automotive wire harnesses and medical tubing segments where plasticizer compatibility drives specification. PVC pipe maintains mature, stable demand tied to municipal water infrastructure cycles, though margin pools concentrate in specialized foam board formulations for signage and display applications.
ANVISA governs chemical substance registration and migration limits for PVC in food-contact and medical applications, while Brazil's environmental regulator enforces emissions controls on vinyl chloride monomer production facilities that elevate capital requirements for new chlor-alkali investments. REACH-equivalent chemical management frameworks under Mercosur harmonization discussions are reshaping cross-border product standards and testing protocols for Argentine and Brazilian manufacturers. Stakeholders must monitor regulatory divergence between national chemical registries and the pace of infrastructure project approvals that ultimately determine regional resin offtake volumes.
Market Dynamics
ANVISA's tightening chemical safety protocols for plastic additives are compressing formulation flexibility while elevating compliance costs across Brazilian PVC compounders, forcing resin specifications toward higher-purity suspension grades that squeeze smaller blenders from municipal tender pools.
Growth Catalysts
- Chlor-alkali capacity expansion:Captive chlorine supply from integrated petrochemical corridors in São Paulo state secures monomer availability for regional pipe extruders facing import volatility.
- Mercosur REACH-equivalent harmonization:Cross-border testing protocol alignment reduces duplicate certification burdens for Argentine-Brazilian manufacturers serving integrated construction supply chains.
- Flexible PVC formulation advances:Plasticizer compatibility improvements in automotive wire harness specifications open specification wins against thermoplastic elastomer substitutes.
Market Restraints
- Ethylene feedstock cost volatility:Naphtha-linked cracker economics expose margin compression during oil price spikes, disproportionately affecting non-integrated compounders.
- Vinyl chloride monomer emissions controls:Brazil's environmental regulator mandates scrubber upgrades and continuous monitoring systems that extend new chlor-alkali project timelines by 18-24 months.
- Concrete piping substitution in rural water infrastructure:Lower upfront material costs and established contractor familiarity preserve cement-based systems in Argentina's northern provinces.
Strategic Opportunities
- Medical tubing grade specialization:ANVISA migration limit compliance for food-contact and clinical applications commands 15-20% formulation premiums over general-purpose compounds.
- Foam board display applications:Signage and retail fixture sectors in Colombia and Chile represent underpenetrated demand outside Brazil's construction-heavy consumption base.
- Recycled PVC feedstock integration:Post-industrial scrap recovery from window profile extruders enables circular content claims for sustainability-specified municipal tenders.
Industry Challenges
- Plasticizer chemist talent scarcity:Formulation expertise for medical-grade flexible compounds concentrates among retiring specialists at legacy Argentine compounders.
- Chlor-alkali asset retooling timelines:Mercury cell phase-out deadlines force accelerated membrane technology conversion capex before depreciation recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polyvinyl Chloride (PVC) Market |
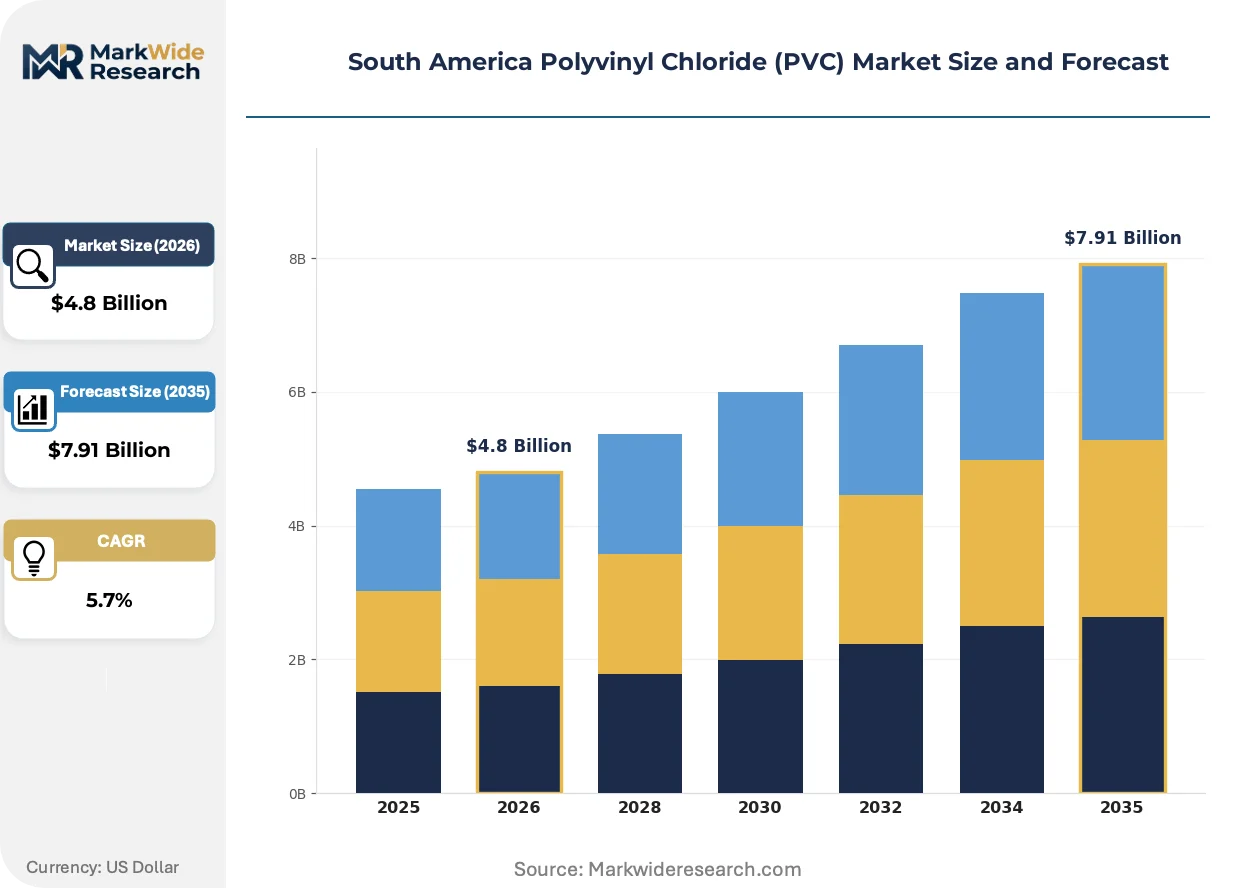
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, Foam Board, PVC Pipe Application: Construction, Electrical, Packaging, Automotive End User: Building Contractors, Manufacturers, Retailers, Wholesalers Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Braskem, Orbia, Unipar Carbocloro, Formosa Plastics Corporation, INEOS, Westlake Vinnolit GmbH & Co. KG, Occidental Petroleum Corporation, Shin-Etsu Chemical Co., Ltd., Solvay, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polyvinyl Chloride (PVC) Market Evolving Landscape
Formulation chemistry and polymerization control systems are compressing specification windows while enabling premium grade segmentation that separates integrated producers from commodity blenders.
High-purity suspension-grade PVC resin with controlled particle porosity is miniaturizing the addressable market for emulsion-grade specialty producers in medical and micro-irrigation applications. São Paulo-based pipe extruders specify these grades for potable water pressure ratings that disqualify lower-porosity alternatives. The technology is miniaturizing formulation flexibility requirements, forcing compounders to source from integrated chlor-alkali complexes rather than merchant resin markets.
ANVISA's chemical substance registration framework now mandates migration testing for all food-contact PVC applications, elevating documentation burdens that favor compounders with in-house analytical laboratories. The regulation compresses tender participation to pre-qualified suppliers with established testing protocols. Medical tubing and potable water pipe segments absorb the highest compliance costs, driving consolidation among Brazilian compounders unable to sustain dedicated regulatory affairs functions.
Building contractors across Brazil's southeastern corridor now consolidate procurement through integrated distributors offering technical specification support alongside resin supply. This channel compression displaces direct mill relationships for mid-volume extruders lacking formulation expertise. The shift concentrates buying power among São Paulo-state distributors with captive logistics networks serving the industrial ABC region.
South America Polyvinyl Chloride (PVC) Market Segmentation
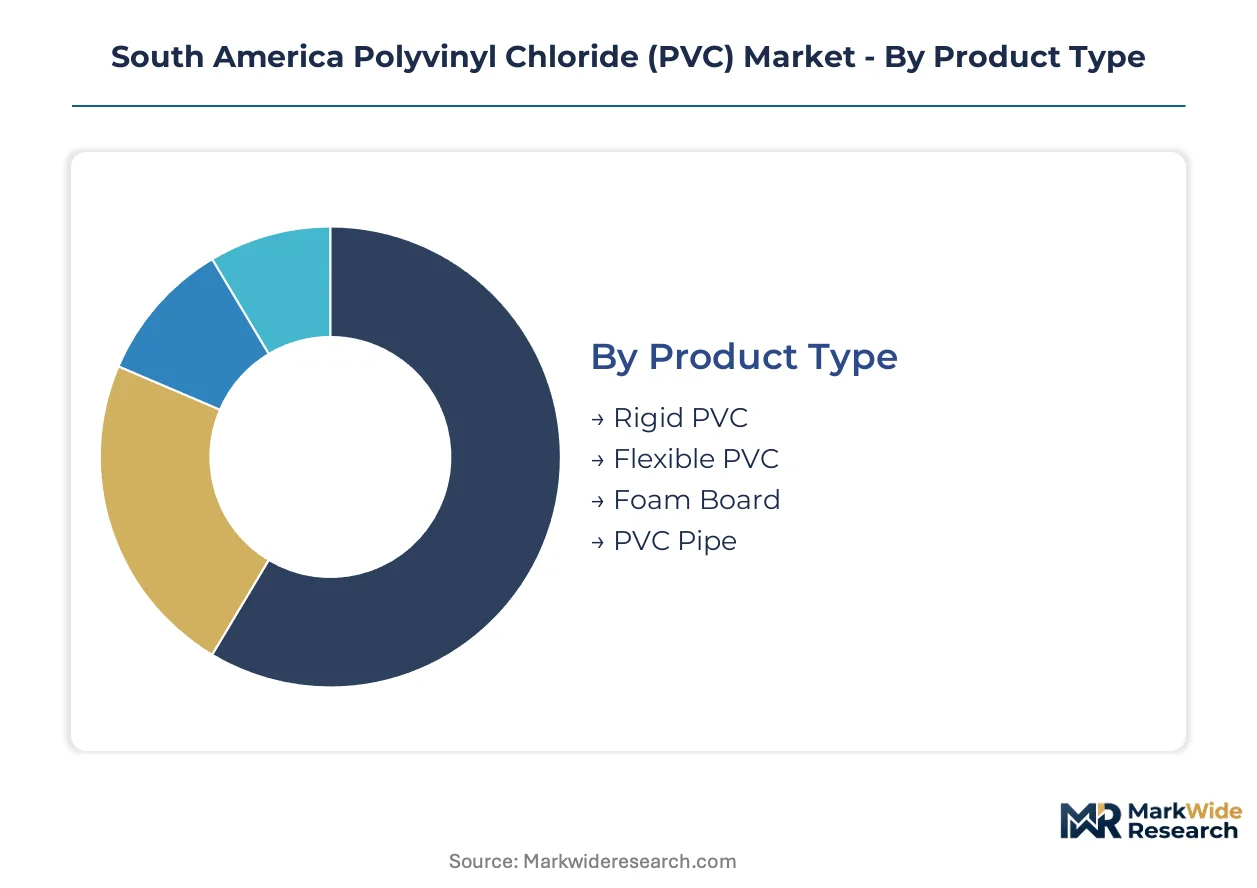
PVC segmentation across South America reflects the construction sector's dominance and the regulatory pressures that separate commodity grades from premium specifications. Category boundaries increasingly blur as ANVISA compliance requirements force compounders toward higher-purity resin streams regardless of end-use application.
Product Type:
Domestic Brazilian production concentrates on suspension-grade rigid and flexible formulations, while foam board and specialized pipe grades draw heavier import dependency from Argentine and Colombian suppliers.
- Rigid PVC:Suspension-polymerized resin with controlled particle porosity for plasticizer absorption resistance. São Paulo-state pipe extruders specify these grades for potable water pressure ratings that disqualify lower-porosity alternatives. Municipal infrastructure tenders in Brazil's southeastern corridor absorb the majority of regional offtake.
- Flexible PVC:Plasticizer-loaded formulations ranging from 20-60 phr flexible content for wire insulation and medical tubing. Automotive wire harness specifications in Brazil's ABC industrial region are expanding fastest as OEMs substitute against thermoplastic elastomers.
- Foam Board:Cellular PVC extrusions for signage and retail display applications with density grades from 0.35-0.7 g/cm³. Colombian and Chilean demand runs through specialized distributors rather than construction channels.
- PVC Pipe:Pressure-rated formulations for municipal water infrastructure with chlorinated variants for hot-water service. Argentina's northern provinces retain concrete piping substitution risk due to contractor familiarity gaps.
Rigid PVC holds the largest share; momentum sits with flexible PVC as automotive and medical specifications tighten.
Application:
Cost tier stratification separates specification-grade applications commanding formulation premiums from commodity construction volumes where price sensitivity dominates procurement decisions.
- Construction:Siding, window profiles, and roofing membranes consuming bulk suspension-grade resin. Brazil's Minha Casa Minha Vida housing program cycles drive volume volatility tied to federal budget approvals.
- Electrical:Conduit and wire insulation grades with flame-retardant additive packages. ANATEL certification requirements for telecommunications cable sheathing elevate testing burdens for compounders serving this segment.
- Packaging:Blister packs and food-contact films with migration-tested stabilizer systems. ANVISA registration compliance compresses supplier pools to pre-qualified compounders with in-house analytical laboratories.
- Automotive:Underhood wire harnesses and interior trim with low-VOC plasticizer specifications. Argentina's automotive OEM supply chain sources through integrated distributors with captive logistics networks.
Construction absorbs the dominant volume; packaging and automotive are climbing the fastest as specification premiums widen.
End User:
Customer type concentration shapes channel strategy, with building contractors consolidating procurement through technical distributors while manufacturers retain direct mill relationships for formulation control.
- Building Contractors:Municipal and residential construction procurement consolidating through São Paulo-state distributors. Tender participation now requires pre-qualification documentation that favors established suppliers with regulatory affairs capacity.
- Manufacturers:Pipe extruders, profile producers, and film processors with captive compounding operations or tolling arrangements. These entities specify resin porosity and molecular weight distribution parameters directly with chlor-alkali producers.
- Retailers:Hardware chains and construction material outlets serving small-scale renovation demand. Inventory turns concentrate on standard pipe dimensions and siding profiles with minimal technical support requirements.
- Wholesalers:Regional distributors bridging mill production to remote construction sites in Brazil's northeast and Amazon regions. Logistics cost absorption limits their penetration of specification-grade segments.
Building contractors command the largest volume share; manufacturers represent the steepest expansion trajectory as backward integration pressures intensify.
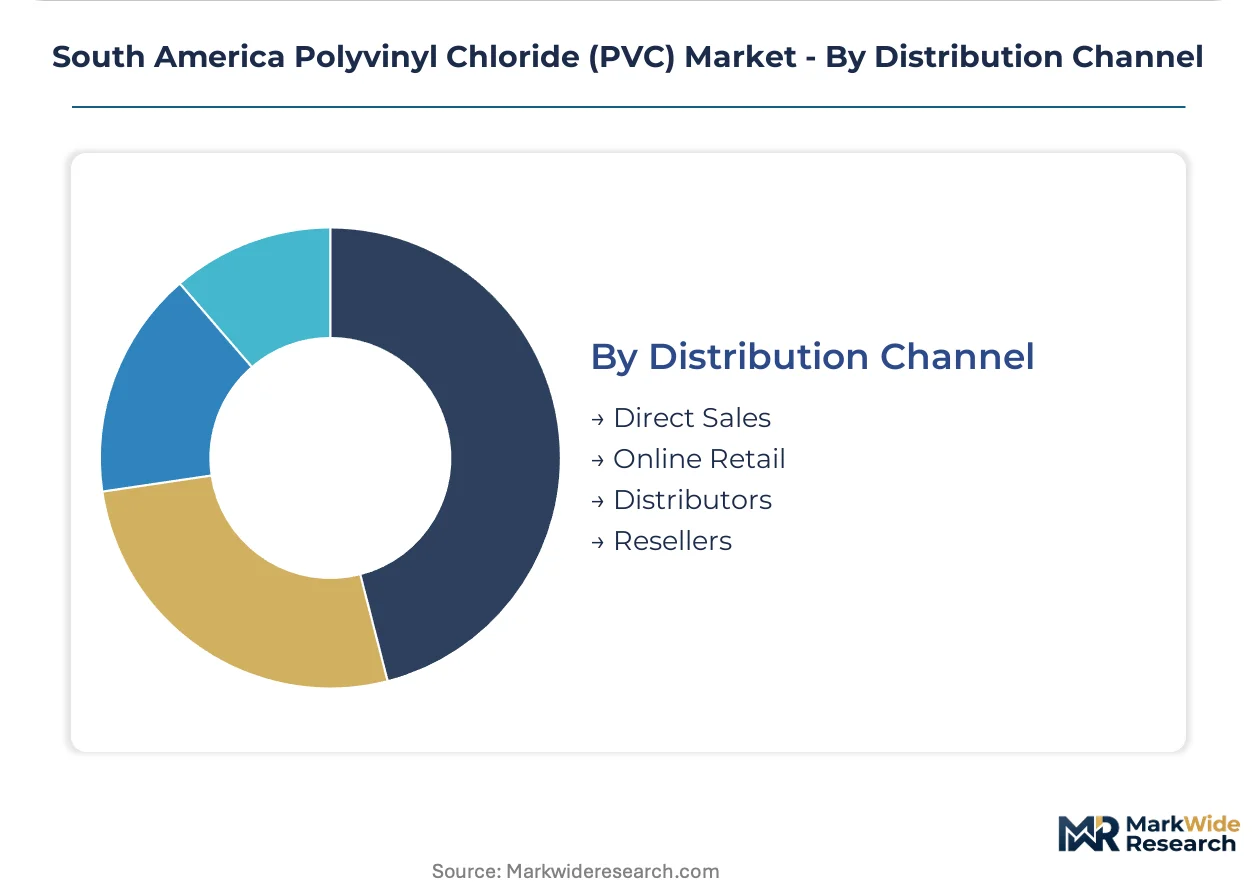
Distribution Channel:
Channel configuration varies by customer scale and technical complexity, with direct sales concentrating among integrated producers and distributor networks capturing fragmented mid-volume demand.
- Direct Sales:Mill-direct relationships for high-volume extruders with formulation expertise and specification development capability. Braskem and Unipar Carbocloro maintain dedicated technical service teams for these accounts.
- Online Retail:E-procurement platforms for standard pipe dimensions and accessory products. Penetration remains limited by contractor preference for physical inspection of resin batch certifications.
- Distributors:Integrated logistics networks with warehousing in São Paulo's ABC industrial region. These entities now consolidate procurement for mid-volume extruders lacking in-house formulation laboratories.
- Resellers:Independent traders serving remote geographies outside integrated distributor coverage. Margin compression and working capital constraints limit their participation in premium grade segments.
Distributors hold the largest share; direct sales are gaining share fastest as large extruders consolidate procurement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South America's PVC trade flows reflect a structural deficit in high-purity suspension grades, with Brazil importing specialized formulations while exporting commodity resin to Mercosur partners. Argentina and Colombia source chlor-alkali intermediates through cross-border arrangements that concentrate value-added production in São Paulo's industrial corridor.
Brazil
Federal housing program cycles drive volume volatility for pipe extruders serving Minha Casa Minha Vida infrastructure tenders. ANVISA mandates migration testing for all food-contact applications, compressing supplier pools to compounders with in-house analytical capacity. São Paulo state's ABC industrial region anchors integrated chlor-alkali production feeding southeastern construction markets.
Argentina
Automotive wire harness demand from Córdoba-based OEM suppliers expands fastest as plasticizer compatibility specifications tighten against thermoplastic elastomer substitutes. The national chemical registry under Mercosur harmonization discussions forces duplicate testing protocol alignment with Brazilian standards. Buenos Aires province compounders concentrate medical-grade formulation expertise now scarce across the region.
Chile
Copper mining infrastructure investment sustains rigid PVC conduit demand for electromechanical installations in northern extraction zones. The environmental regulator enforces emissions controls on vinyl chloride monomer storage facilities that elevate capital requirements for distribution infrastructure. Santiago metropolitan distributors serve retail signage and display sectors with foam board grades imported through Valparaíso port logistics.
Colombia
Municipal water infrastructure rehabilitation programs in Bogotá and Medellín absorb pressure-rated pipe formulations with chlorinated variants for hot-water service. The national standards body implements REACH-equivalent chemical management frameworks that reshape import documentation for Brazilian resin suppliers. Antioquia department extruders specialize in window profile production for Andean climate specifications.
Peru
Mining sector electromechanical installations drive conduit demand through Lima-based distributors serving northern copper and southern gold extraction corridors. The Ministry of Health governs chemical substance registration for medical tubing applications with migration limits mirroring ANVISA protocols. Callao port logistics concentrate import flows for construction-grade compounds lacking domestic chlor-alkali production.
South America Polyvinyl Chloride (PVC) Market Competitive Landscape
Concentration sits with integrated petrochemical producers controlling captive chlorine supply chains through São Paulo-state chlor-alkali corridors. Three archetypes define competitive positioning: integrated resin producers with backward control over vinyl chloride monomer, specialized compounders with formulation expertise for medical and automotive specifications, and regional distributors consolidating procurement leverage for mid-volume extruders. Capacity expansion and regulatory compliance investments constitute the dominant competitive moves, with membrane technology conversion capex separating sustainable operators from legacy asset holders.
Among Brazilian integrated producers, Braskem anchors the petrochemical complex tier with captive feedstock economics, while Unipar Carbocloro occupies a position concentrated on domestic demand absorption. Orbia represents the specialized operator archetype through chlor-alkali and PVC operations sustaining regional chlorine supply continuity. These three entities exemplify the structural division between scale-driven resin production and specification-grade formulation capability now widening under ANVISA compliance pressures.
| Leading Market Players |
|---|
| Braskem |
| Orbia |
| Unipar Carbocloro |
| Formosa Plastics Corporation |
| INEOS |
| Westlake Vinnolit GmbH & Co. KG |
| Occidental Petroleum Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| Solvay |
| Others |
Value Network & Pricing Analysis
Chlor-alkali capacity utilization rates above 85% in São Paulo's ABC industrial region cement pricing power for integrated producers while squeezing merchant resin compounders into thinner margin bands. Scale economics at Braskem's petrochemical complexes translate directly into price floors that non-integrated Brazilian blenders struggle to match during naphtha cost spikes.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Brazilian automotive wire harness and medical tubing specifications. Price differentiation rests on ANVISA certification grade and volume scale, with migration-tested compounds commanding substantial premiums over general-purpose grades. Cost compression in standard pipe formulations is intensifying because Argentine concrete substitution preserves cement-based alternatives in northern provinces. Municipal tender participants show highest price sensitivity, while medical device OEMs absorb premiums for regulatory pre-qualification.
Supply Chain Analysis
Strategic stockpile preferences dominate among São Paulo-state pipe extruders facing vinyl chloride monomer delivery volatility from chlor-alkali corridors. Supply concentrates in Brazil, Argentina, and Colombia, with Brazilian integrated producers drawing from captive ethylene feedstock at Camacari and Triunfo complexes. Raw material dependencies center on naphtha-derived ethylene, chlorine gas, and specialized plasticizer chemistries. Single-source vulnerability from mercury cell phase-out timelines threatens regional chlorine availability. Distribution runs through integrated São Paulo distributors with captive logistics networks serving the southeastern construction corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's Minha Casa Minha Vida housing program cycles position this market for cyclical recovery as federal infrastructure appropriations accelerate pipe extrusion demand across the southeastern industrial corridor.
For Market Incumbents: Secure membrane technology conversion capex at chlor-alkali assets ahead of depreciation recovery deadlines. Consolidate formulation expertise through technical service team expansion targeting medical-grade compounders facing ANVISA migration testing burdens. Threat from thermoplastic elastomer substitution in automotive wire harnesses demands plasticizer compatibility R&D investment. Channel control through distributor pre-qualification partnerships locks out smaller blenders from municipal tender pools. For New Entrants and Emerging Players: Technical specification support gaps among mid-volume extruders lacking in-house analytical laboratories present service-layer white space. Target foam board display applications in Colombian and Chilean retail signage sectors where Brazilian construction-heavy incumbents under-penetrate. Post-industrial scrap recovery tolling arrangements enable circular content claims without chlor-alkali asset ownership. Go-to-market leverage rests on sustainability-specified municipal tender participation rather than commodity resin price competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized compounders with ANVISA-compliant formulation libraries over commodity resin producers facing naphtha margin volatility. Long-term viability across a 5-10 year window hinges on regulatory compliance infrastructure rather than scale economics alone. Acquisition targets should demonstrate established testing protocols and migration limit documentation capacity. Signal to watch: Mercosur REACH-equivalent harmonization implementation pace as cross-border certification burden reduction catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Conversion | Mercury cell phase-out compliance at Brazilian chlor-alkali assets secures chlorine supply continuity for regional PVC production. |
| ANVISA Pre-Qualification Investment | In-house analytical laboratory capacity compresses supplier pools to established compounders for food-contact and medical applications. |
| Backward Integration into Ethylene | Captive naphtha cracker economics at São Paulo petrochemical corridors insulates margin position from oil price volatility. |
| Foam Board Geographic Expansion | Colombian and Chilean retail signage demand diversifies revenue beyond Brazil's construction-heavy consumption base. |
| Recycled Feedstock Integration | Post-industrial scrap recovery from window profile extruders enables circular content claims for sustainability-specified tenders. |
Research Methodology
Cross-validation between primary interviews with Brazilian pipe extruder procurement leads and secondary customs trade data anchors the qualitative findings on regional resin flow patterns. Plant managers at São Paulo-state chlor-alkali complexes, distribution channel partners in the ABC industrial region, and technical R&D directors at Argentine compounders provided operational perspectives. Secondary validation drew from ANVISA regulatory filings, Brazilian chemical industry association reports, and SEC disclosures from listed petrochemical producers. Bottom-up volume estimates from end-use application consumption patterns triangulate against top-down chlor-alkali capacity assessments.
Sensitivity analysis on naphtha-ethylene spread volatility and housing program budget appropriation timing frames the forecast uncertainty range across the projection horizon. Segmentation dimensions modeled include suspension versus emulsion polymerization grades, rigid versus flexible formulation content, and construction versus automotive end-use splits. CAGRs derive from historical volume trend extrapolation adjusted for regulatory compliance cost step-changes and infrastructure tender cycle phasing. Industry-specific inputs encompass vinyl chloride monomer emissions control implementation timelines and Mercosur chemical registry harmonization progress.
Underlying assumptions cover stable ANVISA migration limit enforcement, with deviation risk concentrated in federal housing program budget volatility and chlor-alkali asset retooling delays. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when naphtha-ethylene spreads or infrastructure appropriation levels cross thresholds that alter integrated producer margin sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Polyamide Precursors Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market