
 Resorcinol Formaldehyde Resin Market | 2026-2036
Resorcinol Formaldehyde Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Resorcinol Formaldehyde Resin Market Outlook
Asset-light leasing arrangements for phenol derivative processing capacity are reshaping competitive entry in resorcinol formaldehyde resin production. SI Group leverages captive phenol supply chains to sustain margin stability across adhesive-grade output. Hexion anchors North American wood-bonding demand through specialized liquid formulations. BASF competes on REACH-compliant product portfolios that navigate tightening European formaldehyde emission standards.
Resorcinol formaldehyde resin is a thermosetting polymer synthesized from resorcinol and formaldehyde under alkaline conditions, typically achieving gel times between 60 and 120 seconds at 25°C depending on catalyst loading. The material functions primarily as a cold-setting adhesive binder in structural wood laminates and as a reinforcing resin in rubber-to-metal bonding for tire manufacturing. Adhesive-grade formulations dominate current volume flows due to sustained plywood and engineered-wood demand from construction end users. Powder formulations are gaining share in automated mixing environments where precise dosing and extended shelf stability reduce batch variability. Automotive OEM applications for tire cord dip systems represent the fastest-expanding demand pool as high-performance tire specifications proliferate.
EPA formaldehyde emission standards under the Toxic Substances Control Act and REACH Annex XVII restrictions in Europe are compelling reformulation toward lower free-formaldehyde content. China's MEE enforces GB standards on resin emissions that condition market access for domestic and imported supply. Stakeholders must monitor regulatory divergence across these jurisdictions to calibrate product registration strategies and avoid compliance-driven supply disruptions.
Market Dynamics
REACH Annex XVII formaldehyde emission limits and EPA Toxic Substances Control Act standards are forcing simultaneous reformulation across European and North American supply chains, compressing acceptable free-formaldehyde thresholds and raising technical barriers to market entry.
Growth Catalysts
- GB Standards Enforcement:China's MEE emission mandates are conditioning domestic tire and plywood manufacturing scale, pulling resin demand toward certified low-emission formulations.
- Structural Wood Laminates:Cold-setting adhesive specifications in engineered-wood construction are sustaining volume flows for resorcinol formaldehyde binders.
- Automotive Tire Cord Dip Systems:High-performance tire OEM specifications are expanding rubber-to-metal bonding resin consumption.
Market Restraints
- Phenol Derivative Volatility:Feedstock cost swings in phenol supply chains compress margin stability for non-integrated producers.
- Substitution Pressure from Phenol-Formaldehyde:Lower-cost thermosetting alternatives displace resorcinol formaldehyde in non-structural wood bonding applications.
- REACH Registration Burden:ECHA compliance timelines and data requirements create asymmetric cost structures favoring incumbent formulators.
Strategic Opportunities
- India Plywood Cluster Expansion:BIS certification requirements and domestic construction material demand create formulation registration whitespace.
- Automated Mixing Powder Formulations:Precise dosing and extended shelf stability are displacing liquid resins in high-throughput manufacturing environments.
- EU Green Deal Procurement Incentives:Public construction tender preferences for low-emission adhesives reward early REACH-compliant portfolio investment.
Industry Challenges
- Cross-Jurisdictional Formulation Reconciliation:Divergent EPA, REACH, and GB standard thresholds force parallel product line maintenance and inventory segmentation.
- Alkaline Catalyst Handling Expertise:Gel time control and batch consistency require specialized technical labor pools that concentrate in established manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resorcinol Formaldehyde Resin Market |
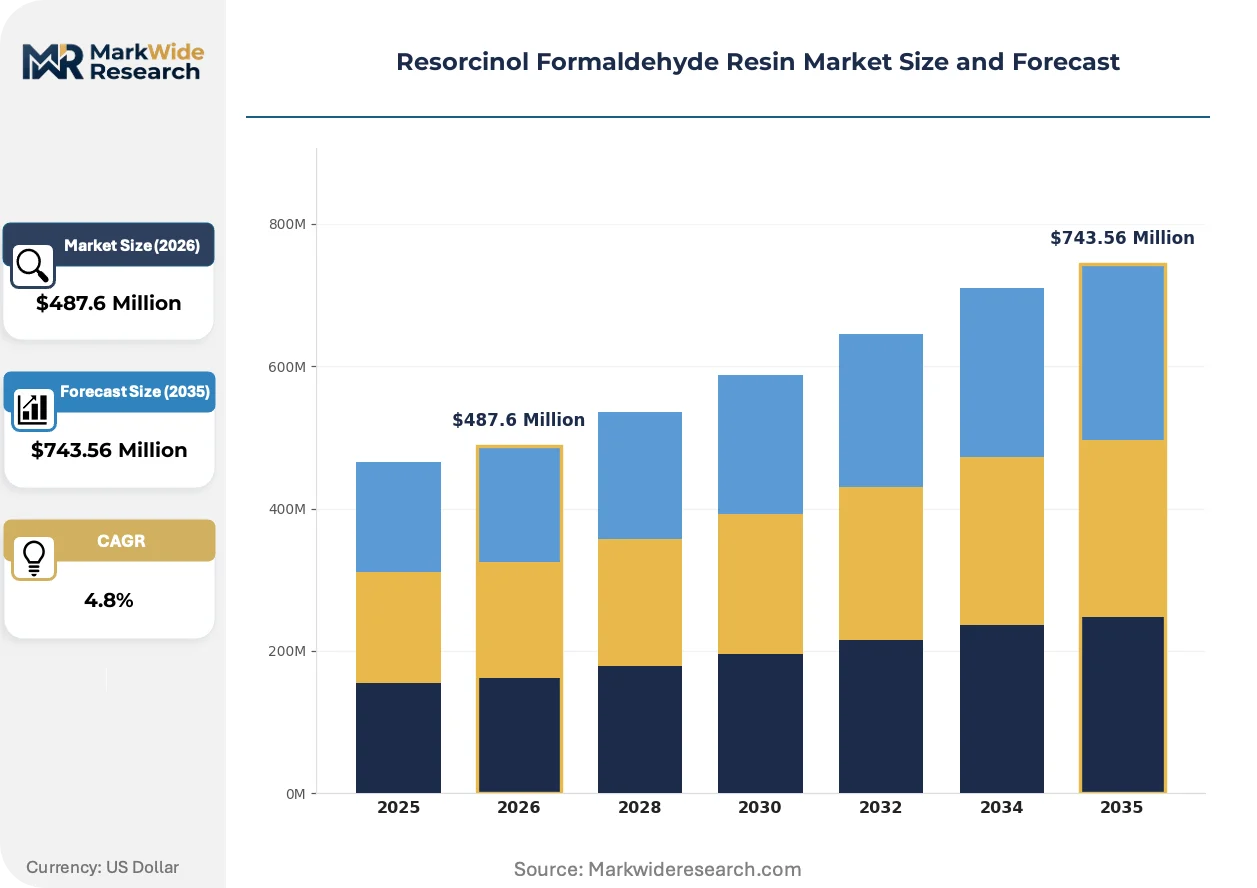
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Cosmetic Grade, Adhesive Grade, Pharmaceutical Grade Application: Wood Bonding, Automotive, Coatings, Textiles Formulation: Liquid, Powder, Paste, Granular End User: Manufacturers, Construction, Automotive OEMs, Laboratories |
| Companies Covered | Sumitomo Chemical, Jiangsu Zhongdan Group, SI Group, Georgia Pacific Chemicals, BASF, Hexion, Atul Ltd, AICA, ASK Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resorcinol Formaldehyde Resin Market Strategic Shifts
Reformulation chemistry and emission testing protocols are the primary arenas of competitive differentiation, with powder processing automation and regulatory pre-certification emerging as parallel capability investments.
Low-emission resorcinol formaldehyde pre-polymers with encapsulated formaldehyde release profiles are rendering obsolete conventional high-free-formaldehyde liquid formulations in European wood-bonding applications. German engineered-wood manufacturers have accelerated adoption of these pre-polymers since REACH Annex XVII threshold reductions. The technology is rendering obsolete legacy batch processes that cannot achieve sub-0.1 ppm emission targets without extended curing cycles.
EPA formaldehyde emission standards under the Toxic Substances Control Act are compelling North American adhesive formulators to redesign cure kinetics and catalyst loading. The industrial consequence is extended R&D timelines and third-party certification costs that favor larger producers with dedicated compliance infrastructure. Structural plywood mills in the US Southeast are responding by consolidating supplier relationships around pre-certified resin portfolios.
Specification-driven procurement is compressing supplier qualification timelines as tire OEMs and construction material distributors consolidate approved vendor lists. Long-term offtake agreements with volume commitments are displacing spot market purchasing in high-volume adhesive applications. This pattern is most visible in China's tire manufacturing belt, where domestic cord dip system specifications now mandate supplier pre-approval through MEE-registered facilities.
Resorcinol Formaldehyde Resin Market Segmentation
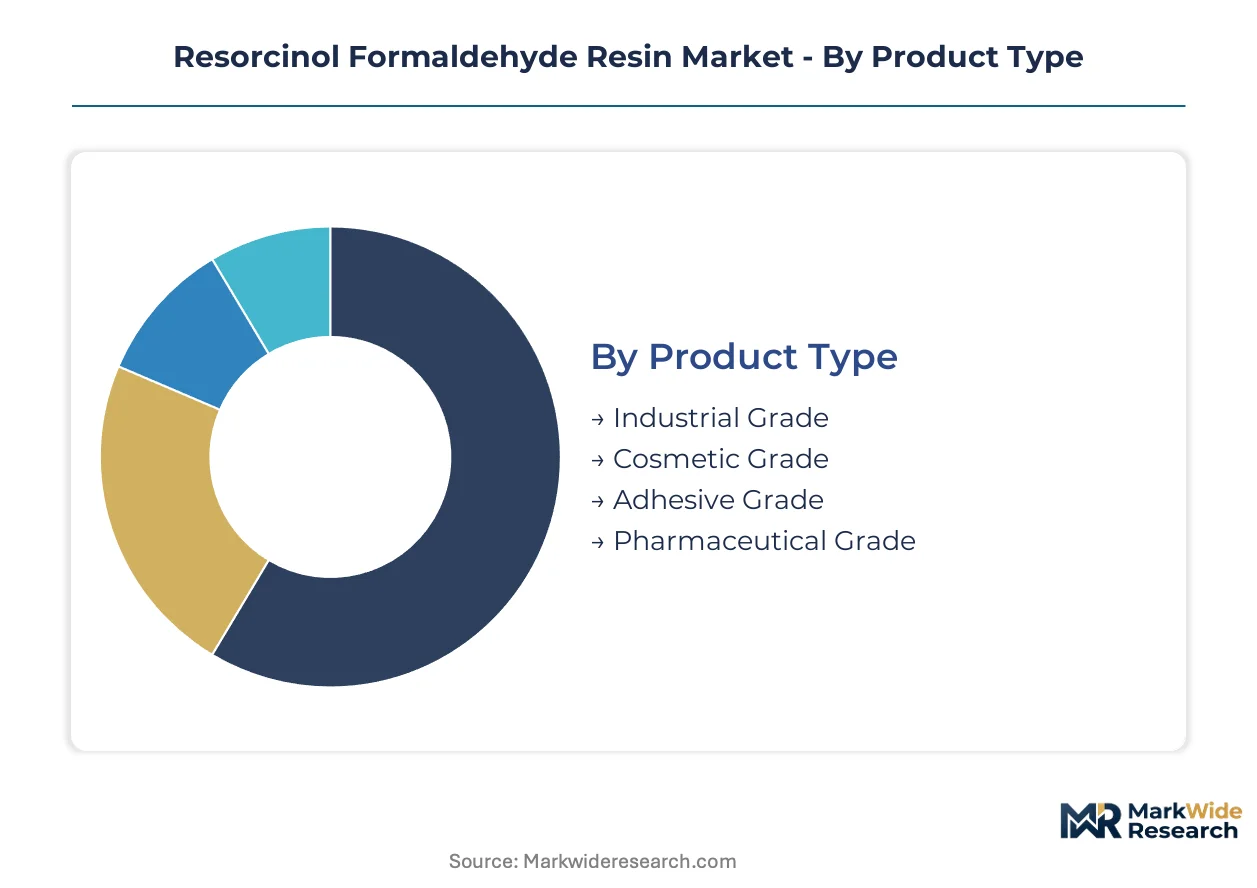
Resorcinol formaldehyde resin segmentation reflects divergent technical specifications across adhesive performance tiers and regulatory compliance thresholds. Each category captures distinct value chain positions from raw material sourcing through end-use certification requirements.
Product Type:
The use-case spectrum spans industrial commodity volumes to specialized pharmaceutical purity grades with radically different margin structures and technical barriers.
- Adhesive Grade:Thermosetting formulations engineered for cold-setting wood laminate bonding with 60-120 second gel times at 25°C. Demand concentrates in China's plywood manufacturing belt as GB standards enforcement tightens emission certification requirements for structural engineered-wood exports.
- Industrial Grade:General-purpose resin for rubber-to-metal tire cord dip systems and non-structural bonding. Automotive OEM specifications in Germany and Japan are pulling consumption toward pre-certified low-emission variants with encapsulated formaldehyde release profiles.
- Cosmetic Grade:Ultra-purified formulations meeting dermatological safety thresholds for hair dye and skincare applications.
- Pharmaceutical Grade:cGMP-compliant resin for excipient and active pharmaceutical ingredient synthesis.
The dominant share belongs to Adhesive Grade, while Industrial Grade is closing the gap fastest.
Application:
Volume concentration tracks construction material demand and automotive specification evolution across major manufacturing economies.
- Wood Bonding:Structural laminate adhesives for plywood, oriented strand board, and engineered timber. REACH Annex XVII threshold reductions in Germany have accelerated pre-polymer adoption, rendering obsolete legacy high-free-formaldehyde liquid formulations that cannot achieve sub-0.1 ppm emission targets.
- Automotive:Rubber-to-metal bonding resins for tire cord dip systems and brake pad formulations. China's tire manufacturing belt now mandates MEE-registered supplier pre-approval, consolidating procurement around certified domestic facilities.
- Coatings:Cross-linking agents for corrosion-resistant industrial finishes and marine protective systems.
- Textiles:Dye fixatives and fabric finishing resins for wrinkle-resistant apparel applications.
Wood Bonding retains volume leadership, though Automotive exhibits the steepest expansion trajectory as high-performance tire specifications proliferate.
Formulation:
Physical state selection hinges on manufacturing automation level, shelf stability requirements, and mixing precision demands.
- Liquid:Conventional solution resins with immediate reactivity and established handling protocols. US Southeast structural plywood mills are consolidating supplier relationships around pre-certified liquid portfolios as EPA Toxic Substances Control Act standards compel reformulation of cure kinetics and catalyst loading.
- Powder:Spray-dried formulations with extended shelf stability and precise dosing control. Automated mixing environments in high-throughput tire and wood-panel manufacturing are displacing liquid resins where batch variability reduction justifies capital investment.
- Paste:High-viscosity formulations for gap-filling and vertical surface applications.
- Granular:Free-flowing solid resin for controlled dissolution and custom formulation blending.
Liquid formulations command current volume share, yet Powder is gaining ground fastest in automated production environments.
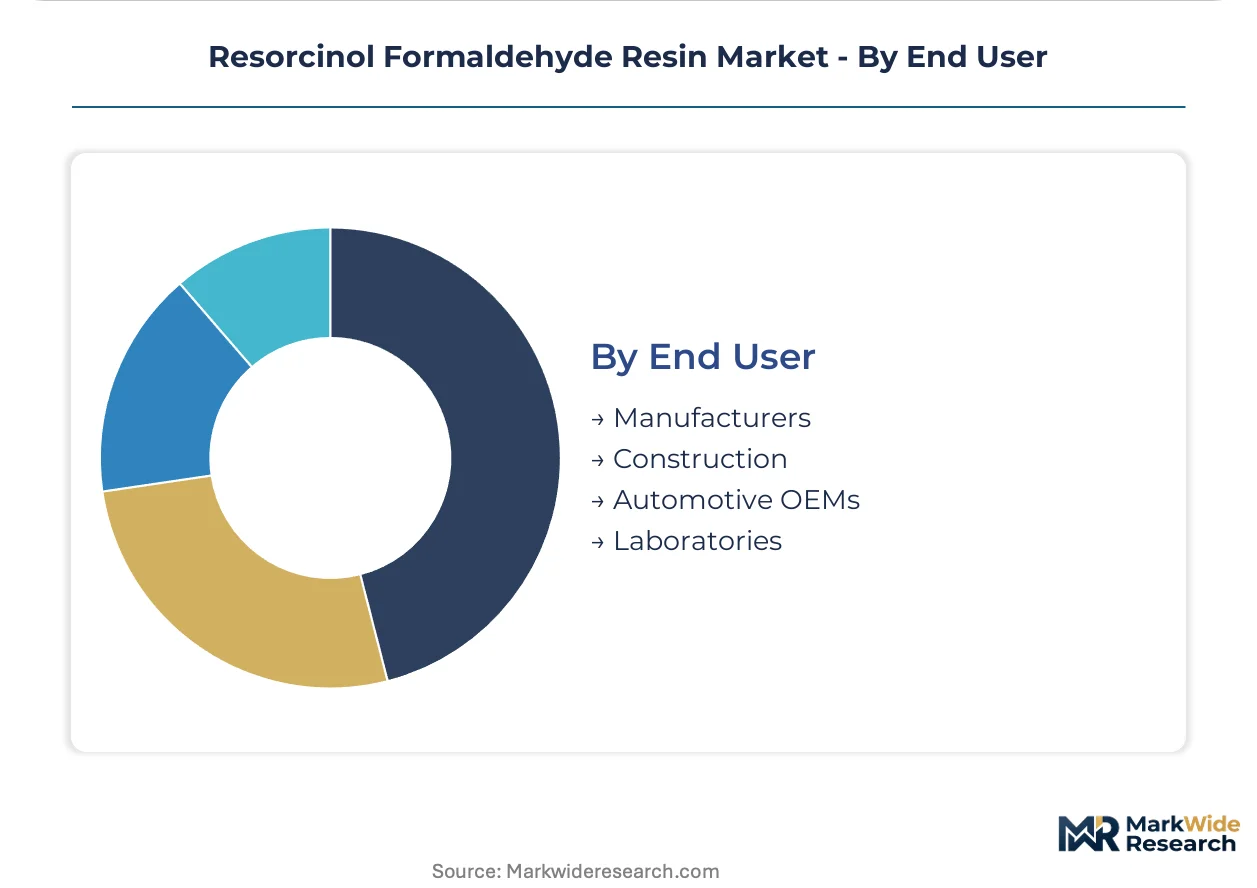
End User:
Customer segmentation reveals divergent procurement sophistication from commodity spot purchasing to long-term offtake agreements with embedded compliance certification.
- Construction:Plywood mills, engineered-wood manufacturers, and structural laminate fabricators. EU Green Deal procurement incentives for public construction tenders are rewarding early REACH-compliant adhesive portfolio investment among European formulators.
- Automotive OEMs:Tire manufacturers and component suppliers with specification-driven vendor qualification. China's domestic cord dip system mandates now require MEE-registered facility pre-approval, compressing supplier consolidation timelines.
- Manufacturers:Diversified industrial adhesive compounders and private-label resin blenders.
- Laboratories:R&D facilities and analytical testing organizations requiring small-batch specialty grades.
Construction holds the dominant procurement volume, while Automotive OEMs are driving the fastest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA formaldehyde emission standards under the Toxic Substances Control Act and REACH Annex XVII threshold reductions are conditioning manufacturing location decisions across major resin-consuming economies. The analysis examines five countries where regulatory enforcement and industrial clustering are reshaping competitive positioning.
United States
Structural plywood mills in the US Southeast are consolidating supplier relationships around pre-certified liquid resin portfolios. EPA Toxic Substances Control Act standards compel reformulation of cure kinetics and catalyst loading, extending R&D timelines for domestic formulators. Georgia and Alabama host concentrated engineered-wood manufacturing capacity where emission-compliant adhesive specifications now dominate procurement.
Germany
German engineered-wood manufacturers have accelerated adoption of low-emission resorcinol formaldehyde pre-polymers since REACH Annex XVII threshold reductions. The country's national chemical regulator enforces sub-0.1 ppm emission targets that render obsolete legacy high-free-formaldehyde liquid formulations. Bavaria and Baden-Württemberg contain specialized adhesive compounders serving automotive and construction OEMs with REACH-compliant portfolios.
China
China's tire manufacturing belt now mandates MEE-registered supplier pre-approval for cord dip system specifications. GB standards enforcement by the Ministry of Ecology and Environment conditions market access for domestic and imported resin supply. Shandong and Jiangsu provinces concentrate plywood and tire production where certified low-emission formulations pull volume demand.
India
BIS certification requirements and domestic construction material demand are creating formulation registration whitespace for adhesive-grade resins. The Bureau of Indian Standards regulates chemical product safety thresholds that foreign suppliers must navigate for market entry. Maharashtra and Gujarat host expanding plywood clusters where local formulators compete on import-substitution strategies.
Japan
Automotive OEM specifications in Japan are pulling industrial-grade consumption toward pre-certified low-emission variants with encapsulated formaldehyde release profiles. METI oversees industrial chemical standards that align with export market requirements in Europe and North America. Kansai region tire manufacturers and Aichi prefecture automotive suppliers represent specification-escalating demand nodes.
Resorcinol Formaldehyde Resin Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply relationships. The market exhibits moderate consolidation around integrated phenol derivative producers and specialized adhesive formulators with regulatory certification infrastructure. Three archetypes dominate: captive feedstock integrators, REACH-compliant European specialists, and Asia-Pacific construction-focused volume suppliers. Capacity expansion in low-emission powder formulations and strategic partnerships for automated mixing technology represent the primary competitive moves.
Within the integrated feedstock tier, SI Group exemplifies captive phenol supply chain positioning. Among Asia-Pacific volume suppliers, Jiangsu Zhongdan Group occupies a construction-demand anchoring role. At the specialty formulation end, Sumitomo Chemical represents automotive specification expertise. These three companies illustrate divergent strategic postures across regulatory compliance, feedstock security, and end-use concentration.
| Leading Market Players |
|---|
| Sumitomo Chemical |
| Jiangsu Zhongdan Group |
| SI Group |
| Georgia Pacific Chemicals |
| BASF |
| Hexion |
| Atul Ltd |
| AICA |
| ASK Chemicals |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European phenol derivative processing is tightening feedstock availability for non-integrated resorcinol formaldehyde resin producers, compressing margin buffers and forcing selective customer prioritization among adhesive-grade suppliers.
Pricing Analysis
Certification level creates the primary spread across adhesive-grade, industrial-grade, and pharmaceutical-grade tiers. Contract-based long-term offtake agreements dominate high-volume construction and automotive procurement, insulating integrated producers from phenol cost swings while exposing spot-market buyers to volatility. Price differentiation hinges on REACH pre-certification status and volume scale, with MEE-registered Chinese suppliers commanding premiums over uncertified imports. Cost compression in standard-grade liquid formulations is intensifying because phenol-formaldehyde substitution pressure constrains pricing power. Construction plywood mills exhibit highest price sensitivity due to commoditized end-product margins, whereas automotive tire OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Phenol feedstock concentration in China, the United States, and Germany anchors upstream supply security for resin manufacturers. Resorcinol production draws from benzene derivatives and formaldehyde, with caustic soda catalyst systems completing the input stack. Single-source vulnerability in Shandong province phenol capacity creates exposure for Asia-Pacific formulators dependent on coastal Chinese chemical clusters. Distribution runs through specialized chemical distributors serving plywood belts and tire manufacturing corridors, with direct mill supply relationships consolidating around pre-certified portfolio suppliers in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-driven procurement platforms are consolidating vendor qualification around MEE-registered and REACH-compliant portfolios, creating interoperability barriers for uncertified suppliers seeking access to tier-one construction and automotive supply chains.
For Market Incumbents: Harden REACH-compliant formulation portfolios against Annex XVII threshold compression by investing in encapsulated formaldehyde pre-polymer R&D. Deepen backward integration into captive phenol supply through asset-light leasing arrangements that preserve capital flexibility. Consolidate supplier relationships with Southeast US plywood mills and Shandong tire manufacturers before MEE registration deadlines eliminate second-tier competitors from approved vendor lists. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certification whitespace by targeting Maharashtra and Gujarat plywood clusters with adhesive-grade powder formulations that exploit import-substitution tailwinds. Pursue automated mixing technology partnerships with domestic tire manufacturers seeking dosing precision improvements. Position around EU Green Deal procurement incentives by pre-certifying low-emission portfolios before public construction tender preferences fully mature. For Investors and Strategic Acquirers: Capital is best deployed toward integrated phenol-resin producers with MEE-registered Chinese facilities and REACH-compliant European distribution infrastructure. Long-term viability over the next decade hinges on regulatory certification moats rather than volume scale alone. Watch for inflection signals in EPA Toxic Substances Control Act enforcement intensity that would accelerate consolidation among non-compliant North American formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Supply | Captive feedstock security insulates margin stability against derivative volatility in Shandong and Texas chemical corridors. |
| MEE Registration Investment | Pre-approval status unlocks access to China's tire manufacturing belt where cord dip specifications mandate certified facility sourcing. |
| Powder Formulation Capacity Expansion | Automated dosing compatibility addresses batch variability reduction priorities in high-throughput plywood and tire production environments. |
| REACH Pre-Certification Portfolio | Annex XVII compliance enables participation in EU Green Deal procurement incentives for public construction adhesive tenders. |
| Long-Term Offtake Agreements | Volume commitments with Southeast US engineered-wood mills secure capacity utilization amid EPA-driven supplier consolidation. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with resin plant managers, procurement leads at tire OEMs, plywood mill technical directors, and chemical distribution channel partners; and secondary validation through customs trade data, ACC and Cefic industry reports, EPA regulatory filings, and SEC 10-K disclosures from integrated phenol producers. Bottom-up capacity and demand modeling was triangulated against top-down macroeconomic indicators across the projection horizon.
Forecast inputs considered grade tier segmentation, end-use industry concentration, formulation state, and regional regulatory cluster alignment. CAGRs were derived from elasticity-adjusted demand projections across adhesive, automotive, and industrial application nodes. Phenol price trajectory assumptions and emission standard enforcement intensity were modeled as scenario-dependent variables.
Stress conditions across feedstock cost bands, regulatory timeline acceleration, and substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions that may require revision upon shifts in EPA, REACH, or MEE enforcement posture. Cross-checking against ECHA registration database updates and MEE facility certification rosters is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Polyolefin Wax Market