
 Bisphenol a Market | 2026-2036
Bisphenol a Market Size, Share, and Industry Trends Forecast 2026-2036
Bisphenol a Market Intelligence
High-purity grade bisphenol A, essential for food-contact polycarbonates, is unwinding traditional supply chains focused on standard industrial grades. Covestro AG leverages its integrated polycarbonate production to serve high-specification end markets. SABIC dominates with its vast manufacturing scale and global distribution network. Mitsui Chemicals Inc. competes by specializing in advanced polymer formulations derived from BPA.
Bisphenol A is an organic synthetic compound produced from the condensation of phenol and acetone. Its primary industrial purpose is to serve as a monomer for synthesizing polymers. The polycarbonate product segment represents the largest volume application, driven by its use in durable, transparent plastics. Epoxy resins, another major segment, are crucial for protective coatings and adhesives in the electronics and construction end-user markets.
Regulatory actions from bodies like the European Food Safety Authority (EFSA) and the U.S. Food and Drug Administration (FDA) heavily influence market dynamics. These agencies set stringent limits on BPA migration in food-contact materials, shaping product development and market access. Navigating the complex and often divergent international regulations on chemical safety remains a central strategic challenge for producers and downstream users.
Market Dynamics
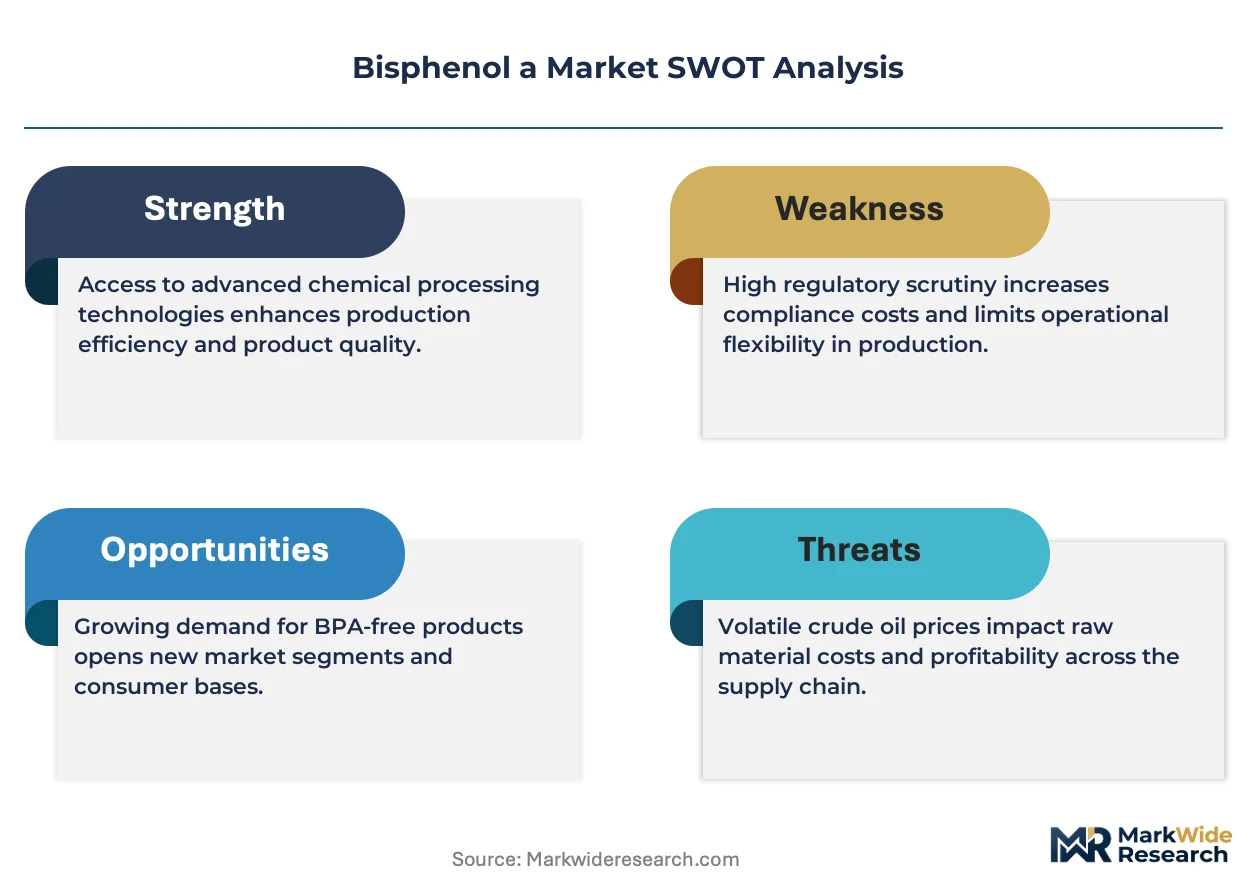
The Bisphenol A market is defined by a structural divergence between the commoditized, high-volume industrial grade sector and a rapidly expanding, high-purity specialty segment driven by stringent regulatory requirements for food-contact and medical applications.
Growth Catalysts
- Automotive Lightweighting:Demand for polycarbonate in vehicles to reduce weight and meet fuel efficiency standards, particularly in electric vehicles, serves as a primary catalyst for BPA consumption.
- Chinese Industrial Expansion:China's continued dominance in chemical production and manufacturing, especially in electronics and construction, anchors global volume demand for both polycarbonate and epoxy resins.
- Advanced Electronics:The proliferation of data centers and 5G infrastructure requires high-performance epoxy resins for printed circuit boards and encapsulants, driving consumption of specific BPA grades.
Market Restraints
- Feedstock Volatility:The market is exposed to price fluctuations in petrochemical feedstocks, primarily phenol and acetone, which can compress producer margins and create price instability for downstream users.
- Regulatory Scrutiny:Intensifying health and safety regulations from bodies like the European Food Safety Authority (EFSA) impose significant compliance costs and can lead to market access restrictions.
- Material Substitution:The threat from BPA-free alternatives, such as co-polyesters like Tritan, is significant in consumer-facing applications like food containers and reusable water bottles due to public perception.
Strategic Opportunities
- High-Performance Composites:Untapped demand exists for BPA-derived epoxy resins in advanced composites for wind turbine blades and aerospace components, offering higher-margin opportunities beyond traditional applications.
- Premium Purity Grades:Stringent regulations, including Japan's Food Sanitation Act, create a distinct market for high-purity, low-migration BPA, enabling producers to capture value through certification and quality assurance.
- Infrastructure Development in India:India's national infrastructure pipeline and production-linked incentive (PLI) schemes for electronics manufacturing create new, concentrated demand centers for polycarbonates and epoxy resins.
Industry Challenges
- Capital-Intensive Upgrades:Transitioning production from standard to high-purity BPA grades requires substantial capital investment in advanced purification technologies and segregated manufacturing lines.
- Divergent Global Standards:Manufacturers face significant operational complexity in managing product portfolios to comply with differing and evolving chemical safety regulations across the EU, US, and China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bisphenol a Market |
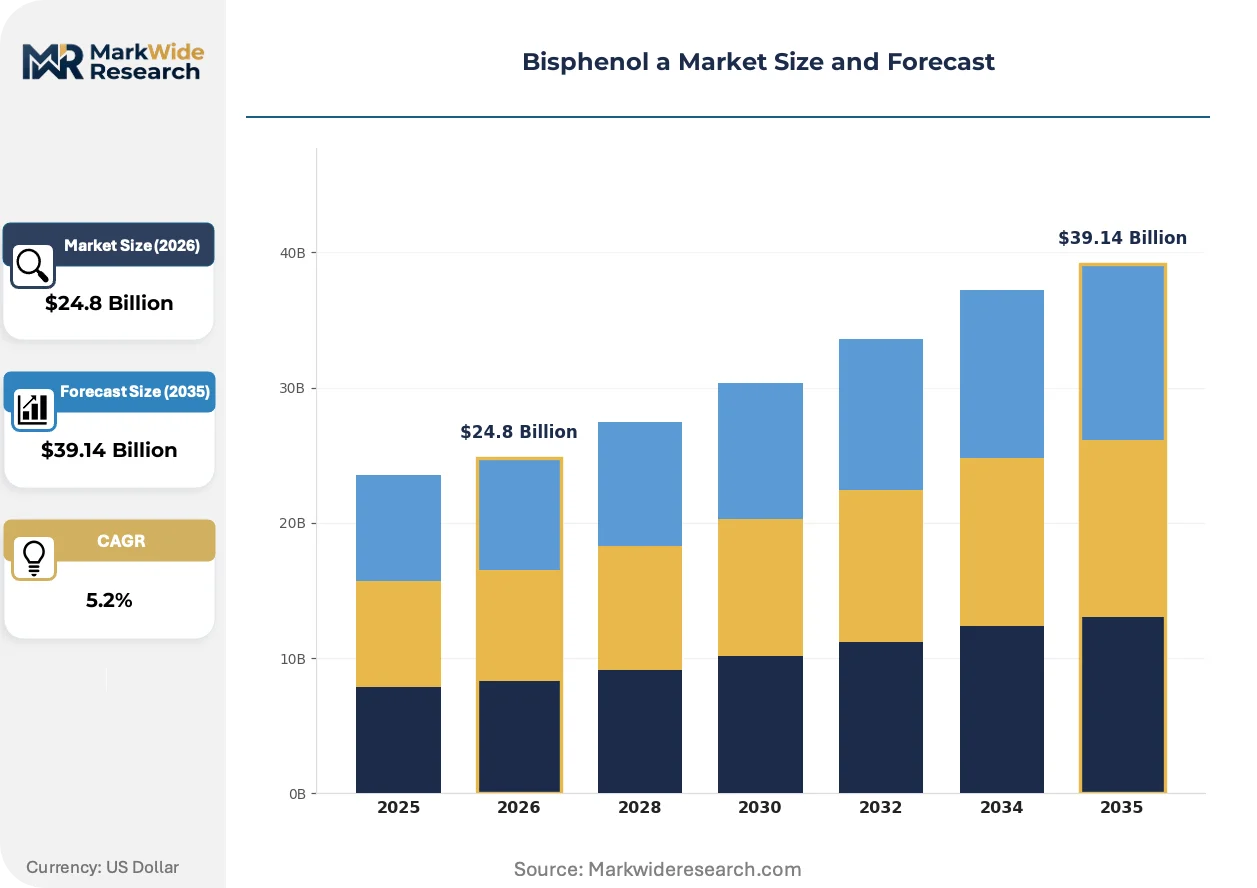
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.14 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Epoxy Resins, Phenolic Resins, Other End User: Automotive, Electronics, Packaging, Construction Application: Aerospace, Consumer Goods, Healthcare, Electrical Form: Solid, Liquid, Granules, Powder |
| Companies Covered | Covestro AG, Mitsui Chemicals Inc., Chang Chun Group, SABIC, Nan Ya Plastics Corporation, LG Chem, Mitsubishi Chemical Corporation, Kumho P&B Chemicals Inc., Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bisphenol a Market Strategic Shifts & Innovations
Material science advancements and regulatory pressures are forcing a bifurcation of the market. A high-value, specification-driven segment is separating from the traditional, volume-focused industrial grade, reshaping supply chains and competitive strategies for producers.
Chemical recycling technologies for polycarbonate are gaining traction. These processes break down post-consumer plastic waste into its constituent monomers, including a recovered form of BPA. The automotive and electronics sectors are early adopters, driven by circular economy mandates like the EU Green Deal. This circularity is decomposing the linear produce-use-dispose model, creating value from waste streams and reducing dependence on virgin petrochemical feedstocks.
Regulatory frameworks are becoming significantly more stringent, led by actions from agencies like the European Food Safety Authority. The EFSA's recent opinion drastically lowering the tolerable daily intake for BPA directly impacts all food-contact materials. Consequently, the food and beverage packaging segment is most affected, accelerating a forced evolution toward either certified low-migration materials or complete substitution.
A notable shift in procurement is underway for sensitive end-uses. Buyers in the medical device and infant product sectors now mandate extensive material traceability and compliance documentation beyond basic technical data sheets. This disrupts traditional, price-led purchasing from bulk distributors, favoring suppliers with robust quality management systems. The trend is most pronounced in North America and Europe, where litigation risk is a primary consideration.
Bisphenol a Market Segmentation
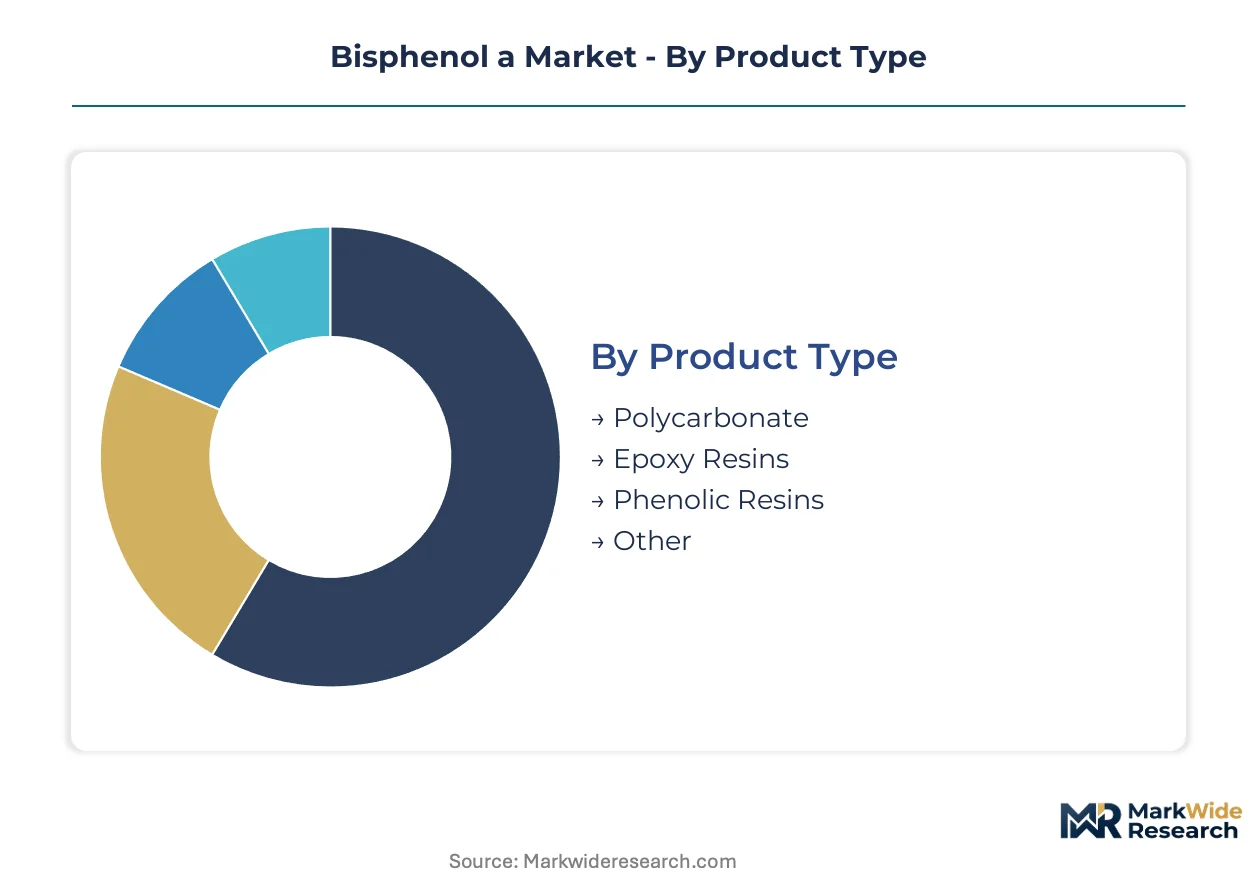
The Bisphenol A market segmentation highlights the diverse applications and purity requirements driving distinct value streams across the industry. Understanding these segments is critical for producers to navigate the structural divergence between commoditized industrial grades and specialized, high-margin materials.
Product Type:
Margin pools within the product type category are increasingly concentrated in specialty grades that meet stringent performance or regulatory standards. These high-specification products command premium pricing due to their unique properties and compliance requirements.
- Polycarbonate:This segment comprises transparent, durable thermoplastics produced from BPA, widely valued for their impact resistance and optical clarity. Demand is concentrating in the automotive sector, where lightweighting initiatives in electric vehicles drive consumption for components like headlamp lenses and panoramic roofs.
- Epoxy Resins:These thermosetting polymers are formed by reacting BPA with epichlorohydrin, providing exceptional adhesion and chemical resistance for protective coatings and advanced composites. Demand is concentrating in the electronics industry for printed circuit boards and encapsulants, fueled by the expansion of 5G infrastructure.
- Phenolic Resins:Derived from BPA and formaldehyde, these resins offer high heat resistance and mechanical strength, finding use in laminates and molding compounds.
- Other:This category includes various minor BPA derivatives and specialty chemicals used in niche industrial processes.
The dominant share belongs to Polycarbonate, while Epoxy Resins are expanding most quickly.
End User:
Volume demand across end-user sectors is heavily influenced by large-scale industrial activities and consumer product trends, with distinct requirements shaping material specifications. Each sector presents unique challenges and opportunities for BPA suppliers.
- Automotive:This sector utilizes Bisphenol A primarily in polycarbonate for vehicle components, contributing to reduced weight and improved fuel efficiency. Demand is concentrated in major manufacturing hubs such as China and Germany, driven by stringent emissions regulations and the growth of electric vehicle production.
- Electronics:The electronics industry relies on BPA-derived epoxy resins for printed circuit boards, encapsulants, and other high-performance materials. Demand is concentrated in Asia, particularly China, due to its extensive manufacturing capabilities for consumer electronics and data center infrastructure.
- Packaging:This end-use segment incorporates BPA in food and beverage containers and protective coatings, though it faces significant regulatory pressure regarding migration limits.
- Construction:Bisphenol A-based epoxy resins serve as binders in flooring, protective coatings, and structural adhesives for various building applications.
The Automotive sector commands the largest volume, with Electronics demonstrating the steepest expansion trajectory.
Application:
The application landscape for Bisphenol A showcases its versatility, ranging from high-performance engineering materials to everyday consumer items. Each application segment has distinct performance criteria and regulatory considerations.
- Aerospace:This application leverages high-performance epoxy resins for advanced composites, offering exceptional strength-to-weight ratios in aircraft structures and interior components. Demand is concentrating in North America and Europe, driven by the increasing use of lightweight materials to enhance fuel efficiency.
- Healthcare:The healthcare sector utilizes high-purity polycarbonates for medical devices, surgical instruments, and laboratory equipment due to their sterilization compatibility and transparency. Demand is concentrating in regions with advanced medical infrastructure and stringent material traceability requirements, such as Europe and the United States.
- Consumer Goods:This segment includes a broad range of products such as sports equipment, eyewear, and household appliances, where BPA-derived materials offer durability and aesthetic appeal.
- Electrical:Electrical applications incorporate BPA in insulation materials, connectors, and casings, benefiting from its dielectric properties and heat resistance.
Aerospace applications represent the largest value segment, while Healthcare is gaining share fastest.
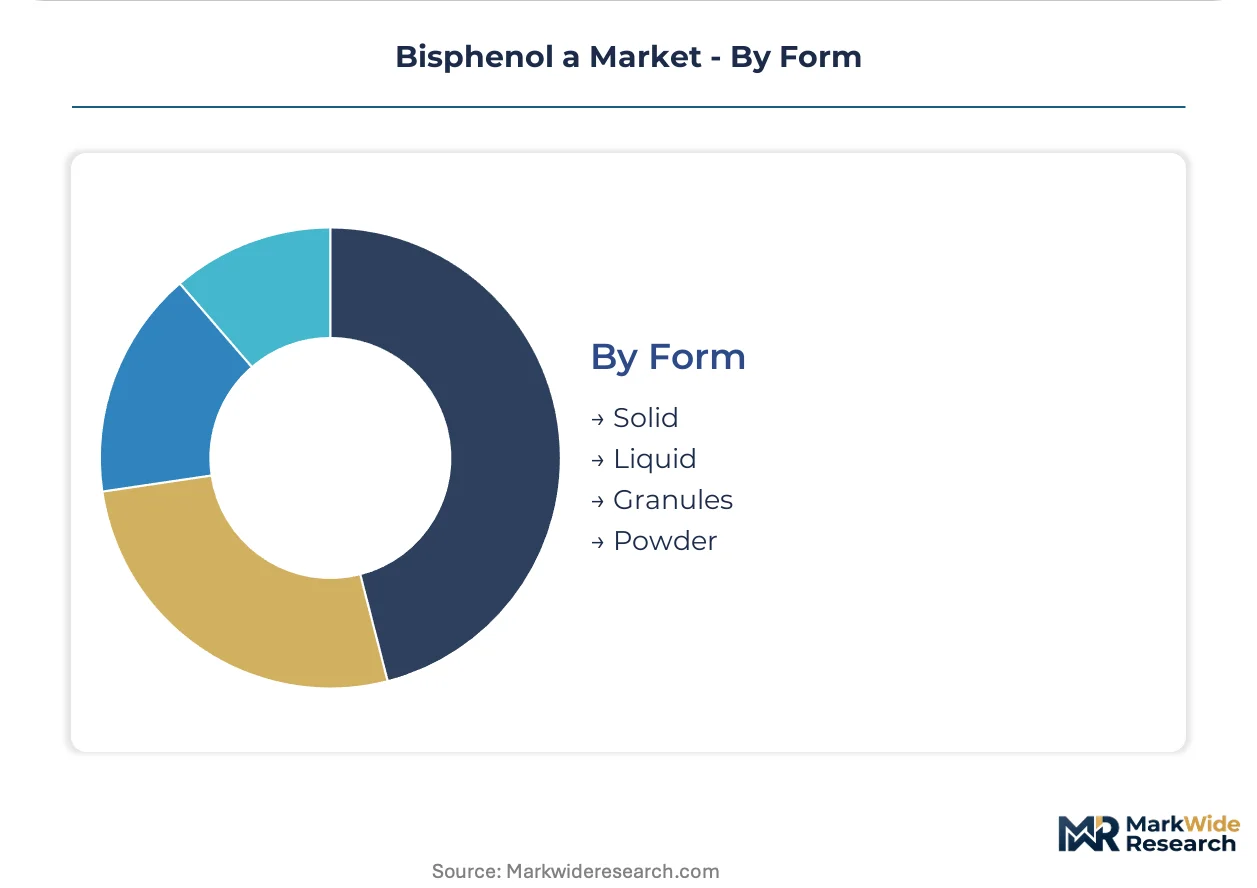
Form:
The physical form of Bisphenol A dictates its handling, storage, and processing requirements for downstream manufacturers. Each form caters to specific industrial needs and production scales.
- Solid:Bisphenol A in solid form, typically flakes or pastilles, offers ease of handling and precise dosing for batch processing in polymer synthesis. Demand is concentrating among large-scale polycarbonate and epoxy resin producers in Asia, where bulk material efficiency is paramount.
- Liquid:Liquid BPA is often used in specific resin formulations where direct incorporation or continuous mixing is required, facilitating easier dispersion in certain chemical reactions. Demand is concentrating in specialty adhesive and coating formulations that require rapid curing or specific rheological properties.
- Granules:Granular BPA provides a dust-reduced alternative to powder forms, improving material flow and reducing airborne particulate matter during manufacturing.
- Powder:Powdered Bisphenol A offers a high surface area for rapid reaction kinetics, suitable for certain chemical processes and smaller-scale applications.
Solid Bisphenol A maintains the largest market presence, with liquid forms experiencing significant growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the Bisphenol A market. Buyers of commoditized industrial grades exhibit high price sensitivity, while high-purity specialty grades for regulated applications demonstrate lower elasticity. This divergence influences regional investment priorities and supply chain configurations for producers.
China
China's electronics manufacturing and construction sectors drive substantial demand for BPA-derived polymers. Strict GB standards govern chemical safety, influencing material selection in consumer products. The Yangtze River Delta region, including Shanghai, acts as a major hub for both chemical production and downstream electronics assembly.
United States
United States automotive lightweighting initiatives and medical device manufacturing consume significant high-purity polycarbonate. FDA guidelines for food contact materials shape product development for sensitive applications. The Gulf Coast region concentrates petrochemical production, while California leads advanced materials research.
Germany
Germany's advanced automotive industry and specialized engineering plastics demand high-performance BPA derivatives. Stringent REACH regulations and EU Green Deal objectives push for sustainable production practices. North Rhine-Westphalia remains a core chemical industry cluster, supporting automotive innovation in Bavaria.
India
India's rapid infrastructure development and expanding electronics manufacturing are creating new demand centers for BPA. The PLI scheme for electronics manufacturing stimulates local production and material consumption. Gujarat's petrochemical complexes and Maharashtra's industrial zones are critical for supply and consumption.
Japan
Japanese electronics and optical applications require high-purity polycarbonates with specific performance characteristics. Japan's Food Sanitation Act sets strict requirements for BPA in packaging materials. The Kanto region, encompassing Tokyo, remains a center for advanced electronics and materials R&D.
Bisphenol a Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Bisphenol A market. The industry exhibits a tiered structure, encompassing large integrated producers, specialized formulators, and regional commodity suppliers. Integrated producers leverage economies of scale for volume production, while specialty players focus on high-purity grades. Dominant competitive moves include strategic capacity expansion to meet regional demand and portfolio diversification into higher-margin specialty grades.
Within the integrated producer archetype, Covestro AG and SABIC exemplify global scale and extensive distribution networks for both standard and high-purity BPA derivatives. Covestro leverages its integrated polycarbonate production to serve high-specification end markets, while SABIC dominates with its vast manufacturing scale. Mitsui Chemicals Inc. represents a specialized formulator, focusing on advanced polymer formulations that cater to specific performance requirements. These companies anchor different segments of the value chain, from monomer production to specialized end-use applications, navigating complex regulatory environments.
| Leading Market Players |
|---|
| Covestro AG |
| Mitsui Chemicals Inc. |
| Chang Chun Group |
| SABIC |
| Nan Ya Plastics Corporation |
| LG Chem |
| Mitsubishi Chemical Corporation |
| Kumho P&B Chemicals Inc. |
| Dow Chemical Company |
| Others |
Cost & Logistics Intelligence
Three-month inventory buffers for high-purity Bisphenol A underscore a supply chain optimized for stringent regulatory compliance and specialized end-use, influencing premium pricing for certified materials. This structure contrasts sharply with the commodity segment, where price sensitivity remains high for bulk industrial grades.
Pricing Analysis
High-purity grade certification drives significant pricing differentiation in the Bisphenol A market, allowing for premium pricing in regulated applications like food-contact polycarbonates. The dominant pricing model incorporates contract-based long-term offtake agreements for industrial grades and value-based pricing for specialty materials. Pricing pressure stems from volatile petrochemical feedstock costs, especially phenol and acetone, compressing producer margins. Buyers of commoditized industrial grades exhibit high price sensitivity, while the high-purity specialty segment demonstrates lower elasticity due to critical performance and regulatory requirements.
Supply Chain Analysis
Global petrochemical refining capacity underwrites the Bisphenol A supply chain, with significant production concentrated in China, the United States, and Germany. The industry draws from key raw materials like phenol and acetone, exposing the market to price fluctuations in these petrochemical inputs. A structural supply chain risk involves divergent international regulations, which necessitate segregated production lines and complex logistics for producers serving multiple regions. Distribution runs through a tiered structure of large integrated producers, specialized formulators, and regional commodity suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bisphenol A market is at a platform-economics inflection, driven by the emergence of circular economy mandates that integrate chemical recycling into the material ecosystem.
For Market Incumbents:Fortify market position by investing in advanced purification technologies for high-purity BPA grades, addressing the threat from stringent regulatory shifts like EFSA's revised TDI. Secure long-term feedstock contracts for phenol and acetone to mitigate price volatility and ensure supply stability. Leverage existing scale to drive cost efficiencies in standard industrial grades, maintaining competitiveness against regional commodity suppliers. Invest in R&D for chemical recycling processes to meet circular economy mandates and reduce reliance on virgin petrochemicals.
For New Entrants and Emerging Players:FDA certification fast-track for novel low-migration BPA derivatives offers a strategic entry point into the healthcare and food-contact segments. Target high-performance advanced composites for aerospace and wind energy applications, where demand for specialized epoxy resins is growing. Focus on niche, high-value applications requiring specific regulatory compliance and material traceability in North America and Europe. A go-to-market angle emphasizing sustainable sourcing and closed-loop recycling solutions can differentiate offerings.
For Investors and Strategic Acquirers:Long-term, this sits as a specialty chemical transformation play because demand is shifting towards high-value, specification-driven materials. Identify acquisition targets with proprietary purification technologies or strong intellectual property in chemical recycling processes. Companies possessing established distribution networks for high-purity grades in regulated markets represent attractive opportunities. The signal to watch is increased M&A activity among specialty chemical producers focusing on sustainable polymer solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity BPA | This meets growing demand for regulated applications in healthcare and food contact. |
| Green Manufacturing Transition | Investment in chemical recycling enhances sustainability and reduces reliance on virgin feedstocks. |
| Long-term Feedstock Supply Agreements | These agreements mitigate price volatility and ensure stable production for downstream polymers. |
| Joint Ventures in Advanced Composites | Collaboration accelerates material development for high-growth sectors like aerospace and wind energy. |
| Portfolio Diversification into Specialty Grades | This strategy captures higher margins and reduces exposure to commoditized industrial segments. |
Research Approach
A spread of perspectives from plant managers, procurement leads at downstream OEMs, technical R&D directors, and regulatory affairs specialists converged on the working assumptions for the Bisphenol A market. This primary intelligence was cross-referenced with secondary validation from customs/trade data, chemical industry association reports, and regulatory body publications from EFSA and FDA. The analysis employed both bottom-up and top-down triangulation to ensure data consistency and accuracy.
The segmentation dimensions modeled included product type (polycarbonate, epoxy resins), end user (automotive, electronics), application (aerospace, healthcare), form (solid, liquid), and grade tier (commodity, high-purity) over the projection horizon. Compound Annual Growth Rates were derived from historical trends, market growth drivers, and expert projections. Key industry-specific forecast inputs included petrochemical feedstock prices and evolving regulatory compliance costs.
Decision-makers should treat outputs as directional under current macroeconomic conditions and regulatory frameworks; material deviation would warrant model refresh to reflect new market realities. Forecasts reflect assumptions regarding feedstock stability and sustained demand from key end-use sectors. Practitioners should keep alternative scenarios live as unforeseen regulatory bans or rapid adoption of BPA-free alternatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polymer Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Propylene Terpolymer Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market