
 Stealth Coating Material Market | 2026-2036
Stealth Coating Material Market Size, Share, and Industry Trends Forecast 2026-2036
Stealth Coating Material Market Insights
Defense procurement channels is rewriting how stealth coating suppliers reach end-users across NATO member states. PPG Industries leverages its aerospace coatings infrastructure to sustain long-term supply relationships with prime contractors. Northrop Grumman anchors its position through captive R&D programs that internalize proprietary formulation work. BAE Systems competes by controlling classified testing protocols that lock in specification authority with European ministries of defence.
Stealth coating material denotes engineered surface treatments formulated with ferrite-loaded polymers, carbon nanotube dispersions, or multi-layer dielectric stacks designed to attenuate radar cross-section, infrared signature, or acoustic detection thresholds in military platforms. These coatings undergo precision spray deposition or chemical vapor deposition to achieve thickness tolerances measured in micrometres while maintaining operational durability across thermal cycling and salt-fog environments. Radar absorbent material dominates current volume flows due to platform retrofit cycles on legacy fighter fleets, while nanocomposite coatings represent the fastest-expanding technology segment as defence agencies mandate weight reduction on unmanned systems. Polymer-based coatings occupy the broadest application base across tactical ground vehicles where cost-per-square-metre constraints limit exotic ceramic alternatives.
The US Department of Defense imposes MIL-STD-461 and MIL-STD-810 qualification gates that filter supplier entry and perpetuate incumbent advantages through testing cost barriers. The EU AI Act and CSRD disclosure requirements are extending compliance burdens to coating supply chains serving European defence contractors, forcing raw material traceability upgrades. Stakeholders must monitor how export control harmonisation between the US State Department and EU dual-use regulations reshapes cross-border formulation licensing before committing to regional production footprints.
Market Dynamics
Defense procurement centralization and electromagnetic compatibility standard tightening are compressing supplier qualification windows while concentrating contract awards among incumbent primes with captive testing infrastructure.
Growth Catalysts
- Next-Generation Combat Aircraft Programs:Radar absorbent material retrofit cycles on legacy fighter fleets sustain baseline demand across NATO air forces. Platform modernization mandates in the United States and Germany accelerate specification updates.
- REACH and RoHS Compliance Upgrades:European raw material traceability requirements are forcing formulation refresh cycles. Suppliers with pre-certified polymer bases capture accelerated qualification pathways.
- Nanocomposite Weight Reduction:Carbon nanotube dispersions address unmanned systems payload constraints. Defense agencies specify gram-level signature reduction thresholds for drone swarms.
Market Restraints
- Ferrite Feedstock Volatility:Rare earth processing concentration in China creates input cost instability. Alternative magnetite sourcing from Australian deposits remains undeveloped at scale.
- Dual-Use Export Control Friction:Harmonization gaps between US State Department ITAR and EU dual-use regulations delay cross-border formulation licensing. Multi-national primes face project timeline uncertainty.
- Thickness-Durability Trade-off:Micrometre-precision deposition layers degrade under thermal cycling and salt-fog exposure. Field maintenance protocols require complete stripping and reapplication.
Strategic Opportunities
- Hypersonic Thermal Protection Convergence:Multi-layer dielectric stacks developed for radar absorption are migrating into infrared signature management for Mach 5+ platforms. Material suppliers with high-temperature polymer expertise capture adjacent specification authority.
- Ground Vehicle Cost-Down Segments:Polymer-based coatings on tactical vehicles operate below ceramic price floors. India's armored vehicle modernization creates volume absorption for mid-tier formulation houses.
- CSRD Supply Chain Disclosure:EU corporate sustainability reporting mandates require coating provenance documentation. First-mover suppliers with blockchain-tracked raw material chains lock in preferred supplier status with Airbus Defence and Space.
Industry Challenges
- Classified Testing Protocol Access:BAE Systems and Northrop Grumman internalize proprietary validation procedures. Independent coating houses face exclusion from specification-setting forums.
- Chemical Vapor Deposition Capex Burden:Vacuum chamber infrastructure for dielectric stack fabrication requires facility investments exceeding mid-cap balance sheet capacity. Equipment lead times extend 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stealth Coating Material Market |
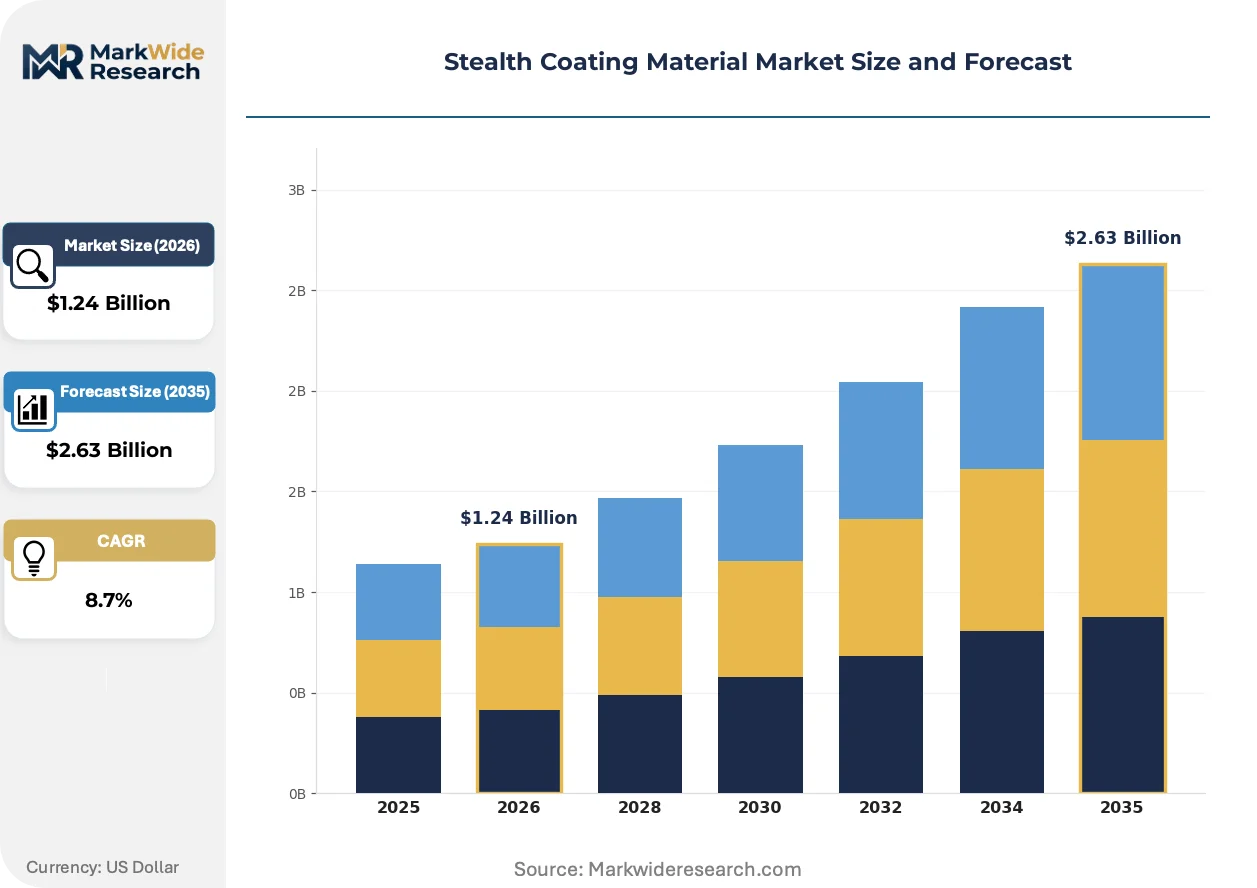
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.63 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Absorbent Material, Infrared Suppressive Coating, Acoustic Dampening Paint, Electromagnetic Shielding Layer Application: Military Aircraft, Naval Vessels, Tactical Ground Vehicles, Unmanned Systems Technology: Nanocomposite Coatings, Polymer-based Coatings, Ceramic-based Coatings, Metallic Thin Films End User: Defense Contractors, Aerospace Manufacturers, Naval Shipbuilders, Security Agencies |
| Companies Covered | PPG Industries, AkzoNobel, Northrop Grumman, BAE Systems, Lockheed Martin, BASF, Axalta Coating Systems, Intermat Defense, Stealth Veils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stealth Coating Material Market Trends and Innovations
Formulation science is pivoting toward multi-spectral signature management as single-band radar absorption loses platform specification priority. Material architectures now integrate thermal, acoustic, and electromagnetic attenuation in unified deposition sequences.
Metamaterial surface engineering is migrating from laboratory demonstration to production-relevant scale. These engineered electromagnetic structures achieve anomalous absorption through sub-wavelength geometric arrays rather than bulk ferrite loading. DARPA and the UK's Defence Science and Technology Laboratory are accelerating transition timelines for unmanned combat air vehicle prototypes. The technology is migrating from aerospace primes toward tier-two subsystem suppliers as deposition patterning tools commoditize.
EU AI Act risk classification rules are extending algorithmic audit requirements to coating process control systems. Automated spray deposition platforms using machine vision for thickness verification now face conformity assessment procedures. German aerospace manufacturers around Munich are pre-emptively restructuring quality management systems to absorb documentation burdens before mandatory enforcement dates.
Platform primes are consolidating specification authority through captive R&D rather than external sourcing. Northrop Grumman and BAE Systems internalize proprietary formulation iterations, compressing the addressable market for independent material houses. This pattern concentrates most acutely in the United Kingdom and United States, where classified program access gates filter supplier participation.
Stealth Coating Material Market Segmentation
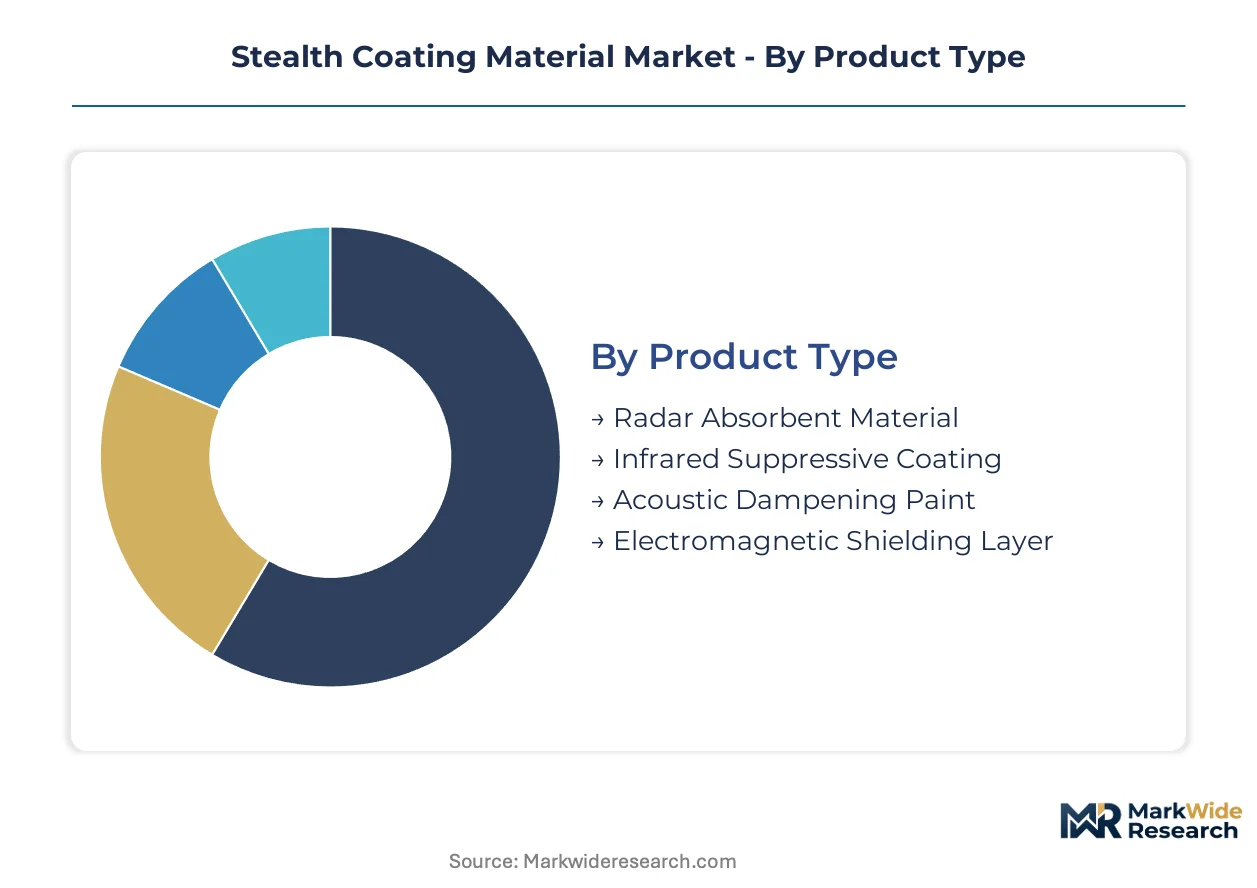
Stealth coating procurement channels fragment across signature bands and platform types, each with distinct qualification protocols and price floors. Understanding how demand concentrates across these dimensions reveals where formulation houses can bypass prime contractor lock-in.
Product Type:
Mature radar absorption competes against emerging multi-spectral formulations as defense agencies retire single-band specifications.
- Radar Absorbent Material:Ferrite-loaded polymers and dielectric composites attenuate microwave returns through magnetic and dielectric loss mechanisms. Retrofit cycles on legacy fighter fleets in the United States and Germany sustain volume flows, though specification updates are slowing as platforms age out.
- Infrared Suppressive Coating:Multi-layer stacks with tailored emissivity profiles manage thermal signatures against heat-seeking threats. Demand concentrates on hypersonic prototypes where Mach 5+ skin temperatures defeat conventional absorbers, with DARPA and the UK's Defence Science and Technology Laboratory accelerating transition timelines.
- Acoustic Dampening Paint:Viscoelastic polymers reduce hull resonance for submarine and torpedo defense. Naval shipbuilders in France and Sweden specify these for next-generation undersea platforms.
- Electromagnetic Shielding Layer:Conductive meshes and sprayed metals protect avionics from high-altitude electromagnetic pulse events. Integration into unmanned systems wiring bays is climbing fastest as drone swarms expand.
Radar absorbent material handles the majority of throughput; infrared suppressive coating is the fastest mover on share.
Application:
Volume tiers separate high-unit-cost aerial platforms from cost-constrained ground systems.
- Military Aircraft:Fighters and bombers require micrometre-precision deposition with thermal cycling durability. MIL-STD-810 qualification gates in the United States filter supplier entry and perpetuate incumbent advantages through testing cost barriers.
- Naval Vessels:Superstructure coatings must survive salt-fog corrosion and biofouling while maintaining radar cross-section reduction. European shipyards around Hamburg and Brest are consolidating specification authority through captive R&D programs.
- Tactical Ground Vehicles:Polymer-based formulations dominate where cost-per-square-metre constraints limit exotic ceramic alternatives. India's armored vehicle modernization creates volume absorption for mid-tier houses.
- Unmanned Systems:Gram-level signature reduction thresholds and payload constraints favor carbon nanotube dispersions. Defense agencies in the United States and United Kingdom are mandating weight reduction as drone swarm tactics proliferate.
Military aircraft commands the premium tier on unit value; unmanned systems is expanding most quickly as procurement volumes scale.
Technology:
Process complexity and capital intensity stratify the supplier base from spray-applied polymers to vacuum-deposited ceramics.
- Nanocomposite Coatings:Carbon nanotube and graphene dispersions achieve anomalous absorption at reduced mass. These formulations are displacing legacy ferrite systems on unmanned platforms where every gram determines mission radius.
- Polymer-based Coatings:Spray-deposited elastomers and thermosets offer the broadest application base across tactical vehicles. REACH and RoHS compliance upgrades in Europe are forcing formulation refresh cycles, advantaging suppliers with pre-certified polymer bases.
- Ceramic-based Coatings:High-temperature oxides and carbides protect hypersonic leading edges. Chemical vapor deposition capex burdens exceeding mid-cap balance sheet capacity concentrate supply among aerospace primes.
- Metallic Thin Films:Sputtered and evaporated metal layers provide precise electromagnetic impedance matching. Lead times for vacuum chamber infrastructure extend 18-24 months, constraining capacity expansion.
Polymer-based coatings dominate current volume; nanocomposite coatings are gaining share fastest as unmanned procurement accelerates.
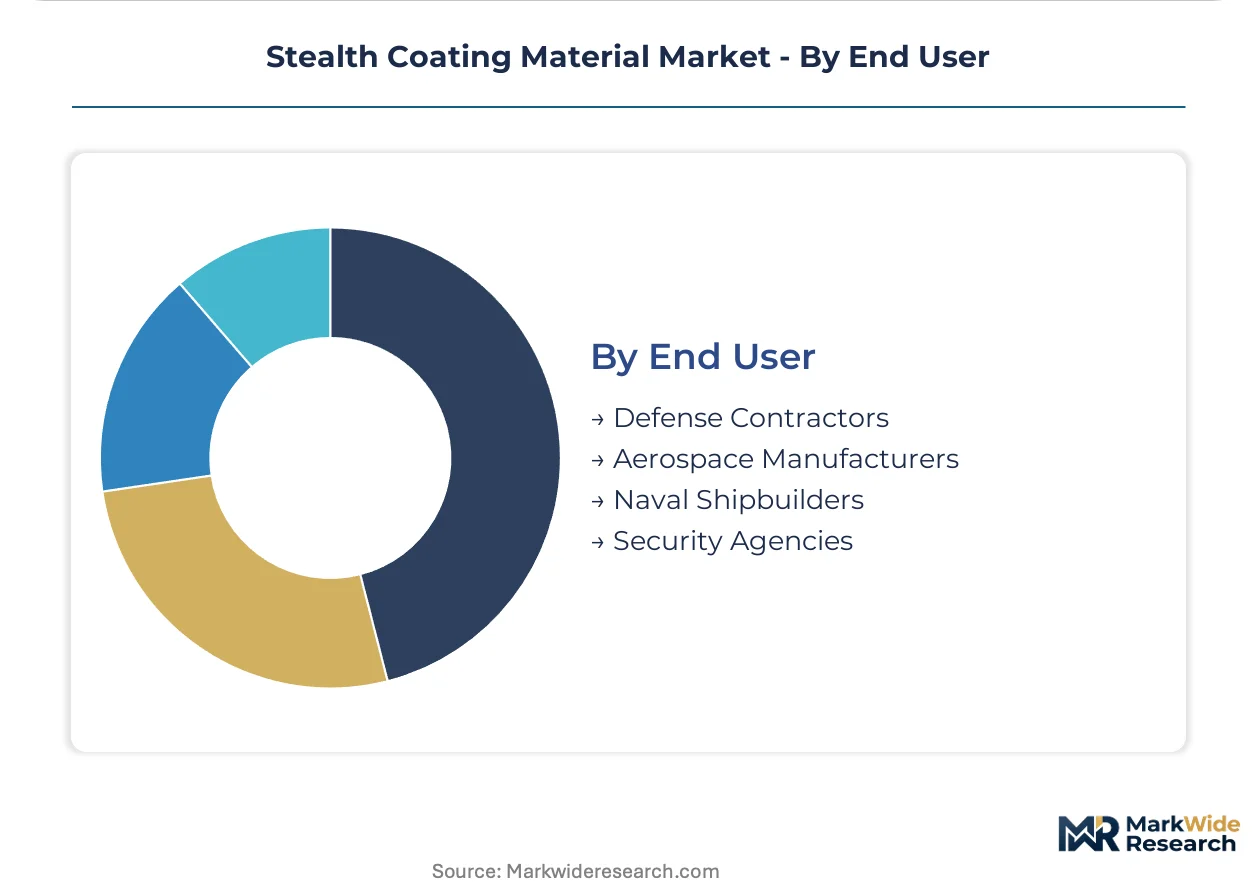
End User:
Customer concentration and classification barriers determine whether independent coating houses can access specification-setting forums.
- Defense Contractors:Northrop Grumman and BAE Systems internalize proprietary formulation work, compressing the addressable market for external material suppliers. Classified testing protocol access gates filter participation in the United States and United Kingdom.
- Aerospace Manufacturers:Airbus Defence and Space and tier-one subsystem integrators are consolidating supplier lists under EU AI Act and CSRD disclosure requirements. Blockchain-tracked raw material chains are becoming a preferred supplier differentiator.
- Naval Shipbuilders:European yards are tightening electromagnetic compatibility standards under EU defense procurement directives, reshaping supplier qualification windows.
- Security Agencies:Intelligence community procurement for surveillance and counter-surveillance platforms operates through classified channels with limited vendor visibility.
Defense contractors concentrate the highest-value contracts; aerospace manufacturers are opening fastest to external qualification as compliance burdens mount.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Transatlantic defense procurement corridor linking United States and European aerospace clusters underwrites regional demand distribution for stealth coating materials.
United States
Next-generation combat aircraft programs and legacy fighter fleet retrofits drive procurement volumes. MIL-STD-461 and MIL-STD-810 qualification gates filter supplier entry and perpetuate incumbent advantages. Defense contractors in California and Texas anchor specification authority through captive R&D infrastructure.
Germany
Tightening electromagnetic compatibility standards under EU defense procurement directives reshape supplier qualification windows. REACH and RoHS compliance upgrades force formulation refresh cycles. Aerospace manufacturing corridors around Munich and Hamburg concentrate demand for radar absorbent materials.
United Kingdom
Classified testing protocols and proprietary validation procedures lock in specification authority with the Ministry of Defence. The Defence Science and Technology Laboratory accelerates transition timelines for unmanned combat air vehicle prototypes. BAE Systems internalizes formulation work, compressing the addressable market for external suppliers.
France
Naval shipbuilders specify acoustic dampening paints for next-generation undersea platforms. EU AI Act risk classification rules extend algorithmic audit requirements to coating process control systems. Shipyards around Brest consolidate specification authority through captive R&D programs.
India
Armored vehicle modernization creates volume absorption for mid-tier formulation houses. Cost-per-square-metre constraints on tactical ground vehicles favor polymer-based coatings over ceramic alternatives. Domestic defense procurement centralization is compressing supplier qualification windows.
Stealth Coating Material Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying raw formulations and deposition equipment. The market exhibits tiered concentration with aerospace primes internalizing proprietary work while independent coating houses compete for residual specification openings. Three archetypes dominate: defense contractors with captive R&D, diversified chemical conglomerates leveraging pre-certified polymer bases, and specialized coating houses targeting cost-constrained ground vehicle segments. Competitive moves center on backward integration into raw material supply and strategic partnerships to access classified testing protocols.
Within the defense contractor archetype, Northrop Grumman and BAE Systems exemplify platform integrators that internalize formulation iterations and control specification-setting forums. Among diversified chemical suppliers, BASF and PPG Industries occupy positions anchored by pre-certified polymer infrastructure and long-term aerospace relationships. These entities represent contrasting strategic postures: captive R&D lock-in versus external qualification pathways.
| Leading Market Players |
|---|
| PPG Industries |
| AkzoNobel |
| Northrop Grumman |
| BAE Systems |
| Lockheed Martin |
| BASF |
| Axalta Coating Systems |
| Intermat Defense |
| Stealth Veils |
| Others |
Pricing and Supply Chain Analysis
Rare earth processing concentration in China creates input cost instability that determines both pricing tier spreads and supply chain shape across stealth coating procurement channels. Ferrite feedstock volatility compresses margins at the polymer-based coating tier while amplifying premium capture for nanocomposite formulations with alternative sourcing pathways.
Pricing Analysis
Volume-discount tiering structures stratify procurement across defense contractor, aerospace manufacturer, and naval shipbuilder archetypes. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810 certified formulations for next-generation combat aircraft from REACH-compliant polymer bases for tactical ground vehicles and uncertified commodity coatings for training platforms. Price differentiation rests on certification level and vertical integration depth, with captive R&D primes commanding premium capture while independent houses face cost compression from raw material volatility. Price erosion runs through the standard tier as mid-cap formulation houses compete for residual specification openings.
Supply Chain Analysis
Extended payment terms from prime contractors to tier-two suppliers strain working capital across the coating value chain. Geographic supply concentrates in China for rare earth ferrite precursors, Germany for specialized polymer resin synthesis, and the United States for deposition equipment fabrication. Raw material dependencies span magnetite ores, carbon nanotube dispersions, and high-temperature ceramic precursors. Single-source vulnerability around Chinese rare earth processing creates tariff exposure and input cost instability. Distribution runs through defense procurement centralization channels with prime contractor specification authority gating downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
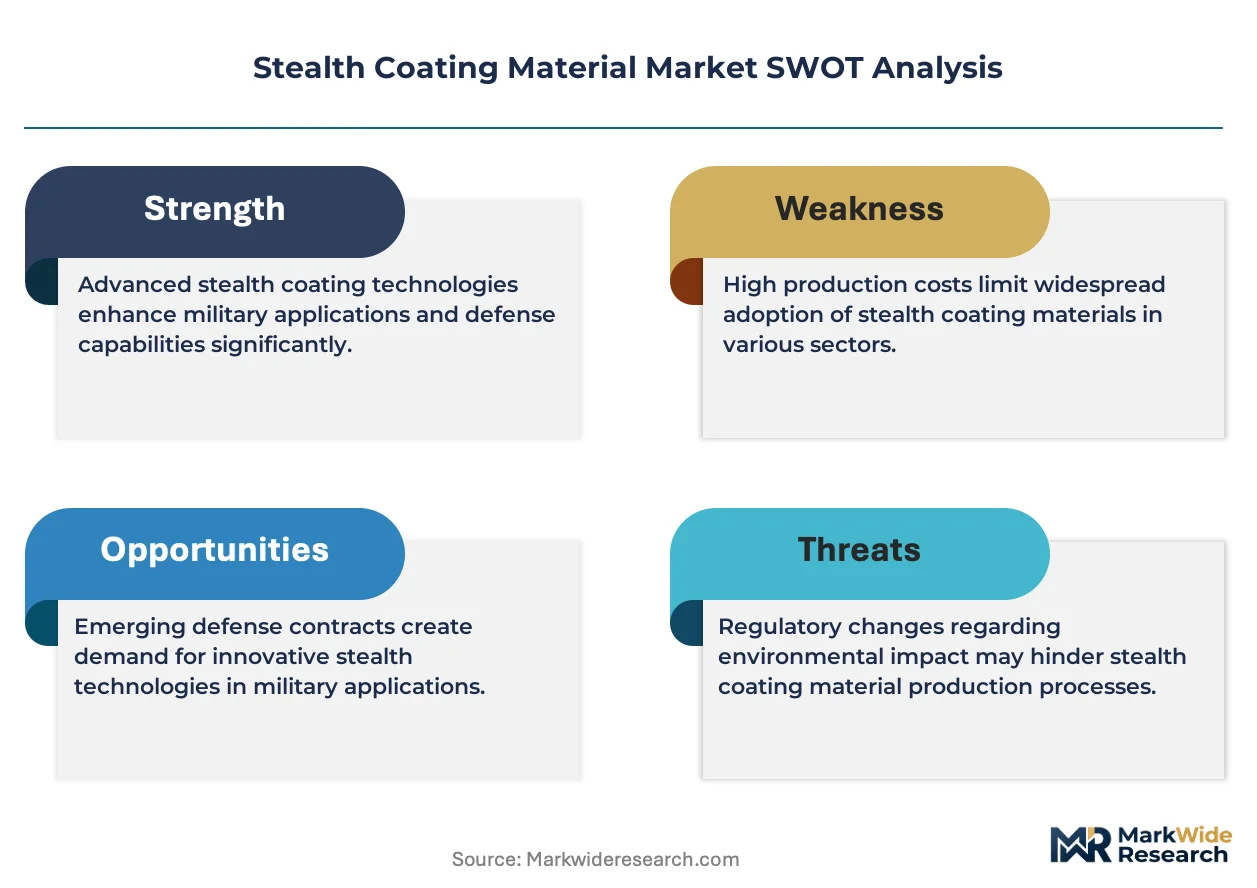
Incumbents face a substitution defense against metamaterial surface engineering migrating from laboratory demonstration to production-relevant scale, threatening ferrite-loaded polymer dominance across unmanned systems procurement.
For Market Incumbents: Entrench specification authority through captive control of classified testing protocols at BAE Systems and Northrop Grumman internalization models. Deepen backward integration into carbon nanotube dispersion supply to offset rare earth ferrite volatility. Lock in preferred supplier status with blockchain-tracked raw material chains ahead of CSRD enforcement dates.
For New Entrants and Emerging Players: Establish a beachhead in India's armored vehicle modernization segment where cost-per-square-metre constraints favor polymer-based coatings over ceramic alternatives. Target acoustic dampening paint specifications for French and Swedish naval shipbuilders with viscoelastic polymer formulations. Pursue qualification partnerships with tier-one subsystem integrators rather than direct prime contractor engagement.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors specialized coating houses with high-temperature polymer expertise adjacent to hypersonic thermal protection convergence. Long-term viability hinges on multi-spectral signature management capability spanning radar, infrared, and acoustic bands. Acquisition targets should demonstrate pre-certified polymer bases under REACH and RoHS frameworks. The signal to watch is DARPA and UK Defence Science and Technology Laboratory funding velocity for metamaterial deposition patterning tools.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive ferrite sourcing from Australian deposits mitigates Chinese rare earth concentration risk. |
| CSRD-Compliant Supply Chain Documentation | Blockchain-tracked provenance secures preferred supplier status with Airbus Defence and Space. |
| Metamaterial Deposition Scale-Up | Sub-wavelength geometric arrays achieve anomalous absorption without bulk ferrite loading. |
| Hypersonic Thermal Protection Convergence | Multi-layer dielectric stacks migrate specification authority into Mach 5+ platform procurement. |
| Ground Vehicle Cost-Down Formulation | Polymer-based coatings capture volume absorption in India's armored vehicle modernization. |
Research Methodology
A standing panel of defense procurement officers, aerospace coatings engineers, raw material procurement leads, and regulatory compliance directors provided ongoing calibration throughout the study. Primary interviews with platform integrators and tier-two formulation houses combined with secondary validation from MIL-STD qualification databases, EU defense procurement directive filings, REACH registration dossiers, and customs trade data for ferrite and carbon nanotube feedstocks. Bottom-up segment sizing across radar absorbent material, infrared suppressive coating, and acoustic dampening paint categories triangulated against top-down defense budget allocation analysis.
Scenario-bracketing framed low, base, and high cases across the projection horizon using defense procurement cycle timing and technology transition velocity assumptions. Segmentation dimensions modeled include signature band, platform type, deposition technology, and end-user archetype. CAGRs derived from platform retrofit cycle analysis and unmanned systems procurement scaling trajectories. Industry-specific forecast inputs encompassed DARPA funding disclosures and EU AI Act implementation timelines affecting automated spray deposition platforms.
Stress conditions across rare earth supply disruption, REACH compliance cost escalation, and metamaterial technology transition acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense procurement centralization continuity and electromagnetic compatibility standard harmonization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Anti-Graffiti Coatings Market
Coatings
Gelcoat Market
Coatings
PACVD-Based Coatings Market
Coatings
Coatings and Fillings Market
Coatings
Italy Protective Coatings Market
Coatings
UV Coatings Market
Coatings
Marine Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Asia-Pacific Superhydrophobic Coating Market
Coatings
Physical Vapor Deposition (PVD) Coatings Market
Coatings
Global Surface Protection Films Market
Coatings
Polyester Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Global Optical Coating Market
Coatings
Radiation Curable Coatings Market