
 UV Cure Resins Market | 2026-2036
UV Cure Resins Market Size, Share, and Industry Trends Forecast 2026-2036
UV Cure Resins Market Analytics
The EU Green Deal's industrial emissions benchmarks is rebalancing procurement priorities across European coating supply chains. Allnex Netherlands B.V. leverages its integrated monomer-to-oligomer platform to secure feedstock reliability for acrylate resin output. Covestro AG anchors its position through high-performance polyurethane dispersions tailored to automotive refinish specifications. IGM Resins competes on photoinitiator compatibility breadth, sustaining formulation flexibility for regional inkjet developers.
UV cure resins are oligomeric and monomeric formulations that polymerize upon exposure to ultraviolet radiation in the 200–400 nanometer wavelength range, typically incorporating photoinitiators such as alpha-cleavage or hydrogen-abstraction types to trigger radical or cationic crosslinking. These materials cure within seconds at ambient temperature, eliminating thermal energy input and enabling high-speed processing of coatings, inks, and adhesive layers on heat-sensitive substrates. Acrylate oligomers command the largest formulation share due to their tunable viscosity and rapid reactivity, while epoxy-based UV resins capture premium margin pools in semiconductor encapsulation where low shrinkage and dielectric stability are critical. The 3D printing application segment is expanding fastest as vat photopolymerization systems adopt customized urethane acrylates to improve build-part toughness and reduce post-cure warpage.
EPA regulations on volatile organic compound emissions from coating operations constrain solvent-based alternatives in US manufacturing facilities, directly expanding addressable demand for UV-curable systems. ECHA's REACH authorization requirements for traditional photoinitiators such as benzophenone derivatives are forcing reformulation investments toward safer cleavage-type alternatives. China's MEE enforcement of dual carbon goals is tightening emissions permits for thermal-cure coating lines, accelerating domestic resin producer migration to UV platforms. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets and misaligned capacity commitments.
Market Dynamics
REACH authorization requirements for benzophenone photoinitiators are forcing European formulators to rebuild resin portfolios around safer cleavage-type alternatives, compressing reformulation timelines and redirecting R&D budgets toward photoinitiator compatibility testing.
Growth Catalysts
- EPA VOC emissions rules:US coating facilities face escalating penalties for solvent-based operations, accelerating line conversions to UV-curable systems in automotive refinish and wood furniture manufacturing.
- China's dual carbon enforcement:MEE emissions permit tightening for thermal-cure lines is pushing domestic coating producers toward UV platforms in the Pearl River Delta automotive cluster.
- Semiconductor encapsulation demand:Epoxy-based UV resins with low shrinkage properties are capturing premium positioning in dielectric stability applications for advanced packaging.
Market Restraints
- Acrylate monomer supply concentration:Feedstock reliability hinges on a narrow base of integrated monomer-to-oligomer producers in the Netherlands and Germany.
- Photoinitiator reformulation costs:ECHA's substance authorization timeline is imposing 18-24 month validation cycles on European inkjet developers.
- Heat-sensitive substrate limitations:UV cure depth constraints restrict application on thick-section composites in aerospace interior panels.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic PCB manufacturing incentives are creating first-mover openings for UV-curable solder mask suppliers in Gujarat and Tamil Nadu.
- 3D printing vat photopolymerization:Customized urethane acrylates addressing post-cure warpage represent unclaimed white space in dental and industrial prototyping.
- EU Green Deal industrial benchmarks:Carbon accounting requirements are tilting procurement toward radiation-curable chemistries with verified lifecycle footprints.
Industry Challenges
- Photoinitiator toxicology expertise:Formulation teams lack sufficient toxicologists to navigate ECHA substance evaluation dossiers.
- Legacy thermal-cure asset stranding:Coating producers face write-down risks on convection oven investments as UV line conversions accelerate.
- Cross-jurisdictional formulation drift:Divergent EPA, REACH, and China GB standards are fragmenting product portfolios and inflating SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Cure Resins Market |
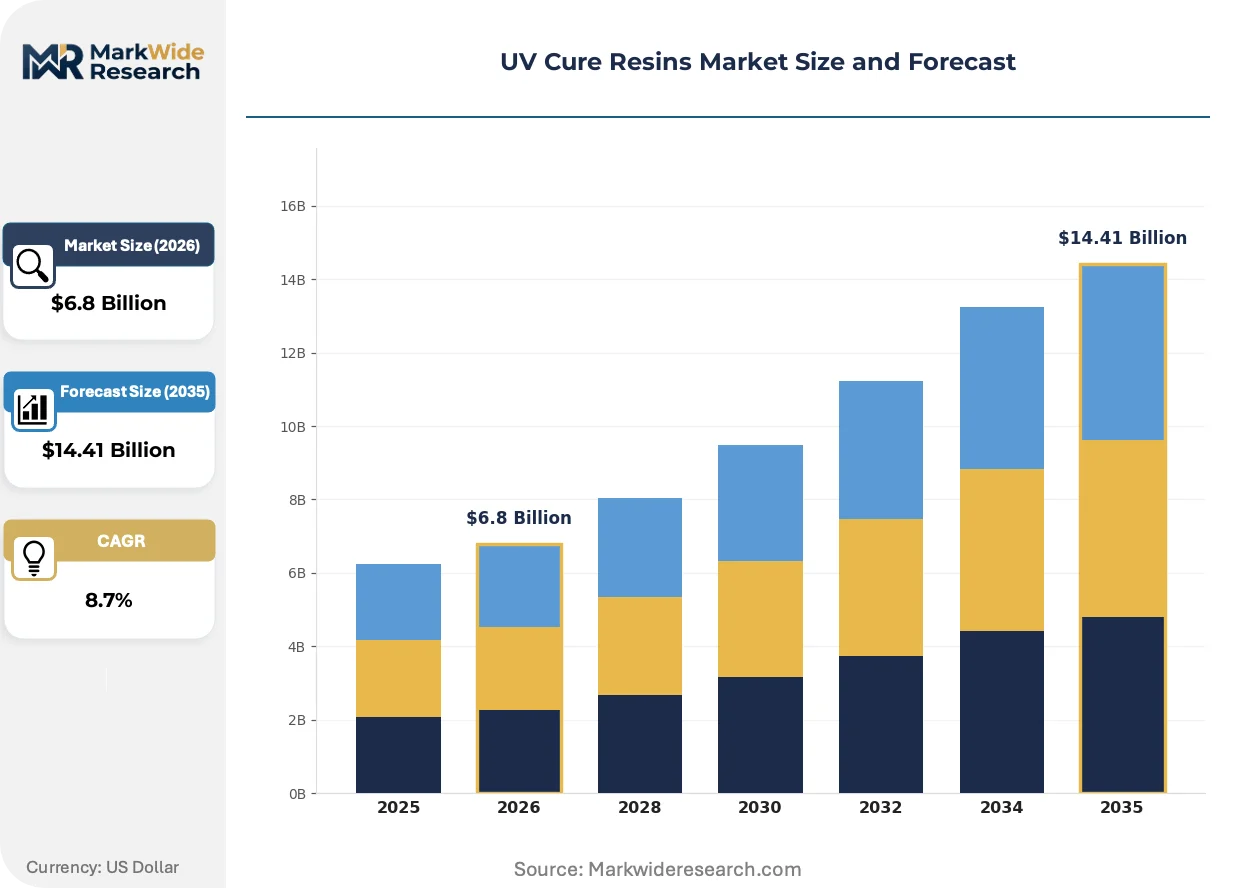
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylate, Polyester Application: Coatings, Inks, Adhesives, 3D Printing End User: Automotive, Electronics, Packaging, Furniture Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Allnex Netherlands B.V., BASF SE, Covestro AG, Arkema Group, IGM Resins, DIC Corporation, Resonac Holdings Corporation, Alberdingk Boley GmbH, Miwon Specialty Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Cure Resins Market Evolving Landscape
Formulation architectures are fragmenting across regulatory jurisdictions while converging on photoinitiator safety, creating parallel development tracks for North American, European, and Asian resin specifications.
LED-optimized photoinitiator packages are decentralizing cure equipment ownership across smaller coating operations. Job shops and mid-tier furniture finishers in Vietnam and Mexico are adopting 395-nm LED arrays without mercury arc lamp infrastructure. This hardware shift is compressing the minimum viable scale for UV coating adoption from factory lines to cell-level workstations.
ECHA's restriction proposal for TPO (2,4,6-trimethylbenzoyl-diphenyl-phosphine oxide) is triggering portfolio rebalancing across European ink and coating formulators. The anticipated 2025-2026 authorization timeline is accelerating substitution toward BAPO (bisacylphosphine oxide) alternatives despite higher raw material costs. German automotive refinish suppliers are front-loading validation trials to secure OEM approvals before regulatory deadlines.
Buyers in China's Yangtze River Delta are consolidating resin procurement through integrated coating service platforms rather than direct oligomer purchases. These platforms bundle formulation, application equipment, and technical service into annual contracts. Furniture exporters in Zhejiang province are migrating fastest, driven by downstream brand audits for VOC compliance in EU and US retail channels.
UV Cure Resins Market Segmentation
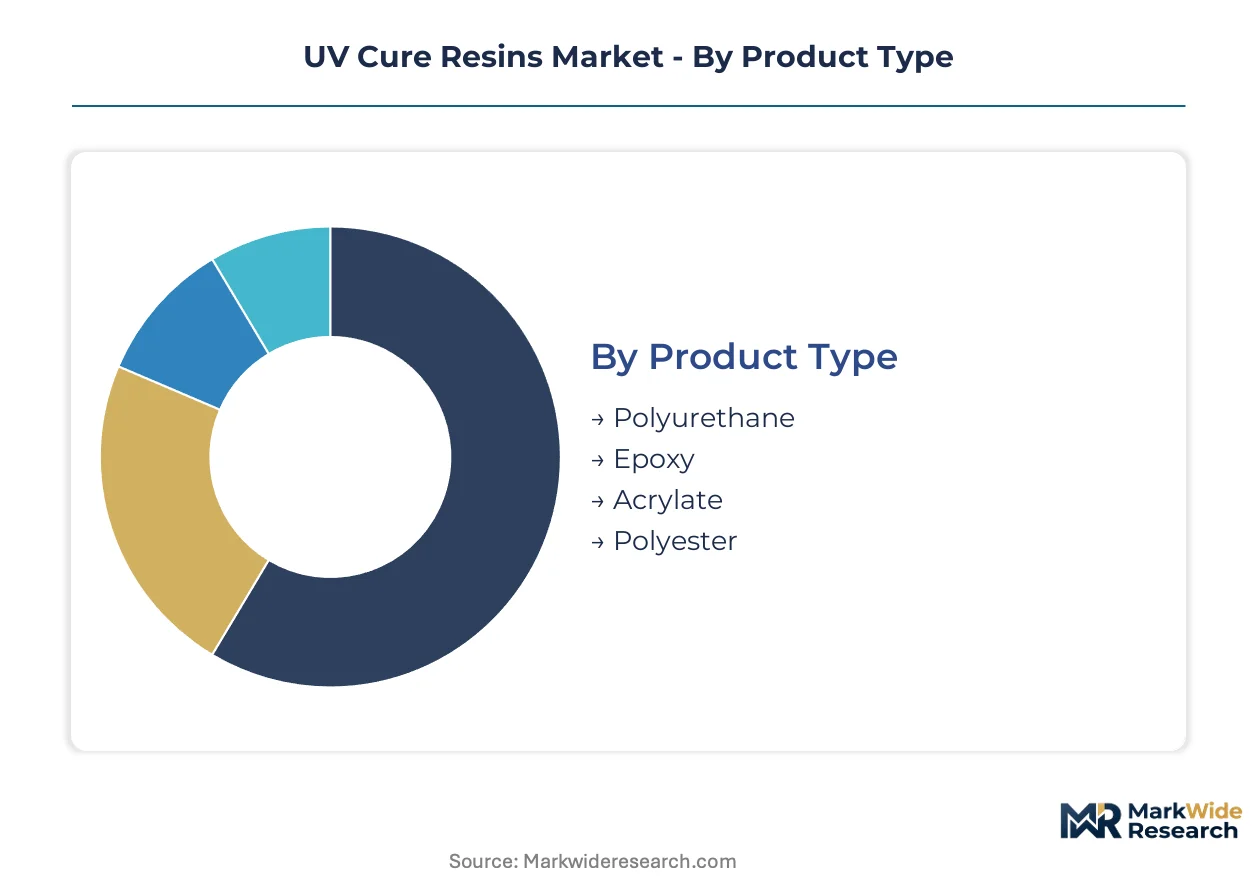
UV cure resin buyers select formulations based on substrate compatibility, cure speed requirements, and regulatory compliance profiles. Segmentation reveals how technical specifications diverge across end-use verticals and procurement channels.
Product Type:
Buyers differentiate primarily by viscosity control needs and shrinkage tolerance in their specific coating or encapsulation processes.
- Acrylate:These oligomers dominate formulation portfolios due to tunable viscosity and rapid radical polymerization kinetics. Demand concentrates in China's Pearl River Delta furniture clusters, where MEE emissions enforcement is accelerating line conversions from thermal-cure alternatives.
- Polyurethane:Urethane acrylate hybrids deliver superior toughness and flexibility for flexible packaging laminates and automotive refinish topcoats. German automotive OEMs specify these grades for scratch-resistant clearcoat systems.
- Epoxy:Cationic cure systems with minimal shrinkage serve semiconductor encapsulation and dielectric stability applications in advanced packaging.
- Polyester:Lower-cost options target wood furniture primers and general industrial coatings where flexibility requirements are moderate.
Volume sits with acrylate formulations; growth tilts toward polyurethane hybrids in automotive and 3D printing.
Application:
Application selection tracks substrate heat sensitivity and line speed requirements across manufacturing operations.
- Coatings:Wood furniture and automotive refinish lines adopt UV-curable clearcoats and primers for instant handling and stackability. EPA VOC penalties in US manufacturing facilities are redirecting capital toward UV line conversions.
- 3D Printing:Vat photopolymerization systems deploy customized urethane acrylates to reduce post-cure warpage in dental and industrial prototyping. This segment is expanding most quickly as hardware costs decline.
- Inks:Narrow-web label and packaging printers favor LED-optimized formulations for energy efficiency and substrate compatibility.
- Adhesives:Electronics assembly and medical device bonding leverage rapid cure for heat-sensitive components.
Coatings command the largest installed base; 3D printing exhibits the steepest expansion trajectory.
End User:
End-user procurement patterns reflect divergent regulatory exposure and performance certification requirements.
- Electronics:PCB manufacturers and semiconductor packagers specify low-shrinkage epoxy resins for solder mask and encapsulation. India's PLI scheme for electronics manufacturing is creating first-mover demand in Gujarat and Tamil Nadu.
- Automotive:Refinish shops and tier suppliers prioritize polyurethane acrylates for OEM color matching and durability specifications. German suppliers are front-loading validation trials ahead of ECHA photoinitiator deadlines.
- Furniture:Exporters in Zhejiang province bundle resin procurement through integrated coating service platforms to satisfy EU and US retail VOC audits.
- Packaging:Food-contact compliance drives selection of low-migration photoinitiator packages in flexible laminate applications.
Electronics generates premium pricing; furniture drives volume through consolidated platform procurement.
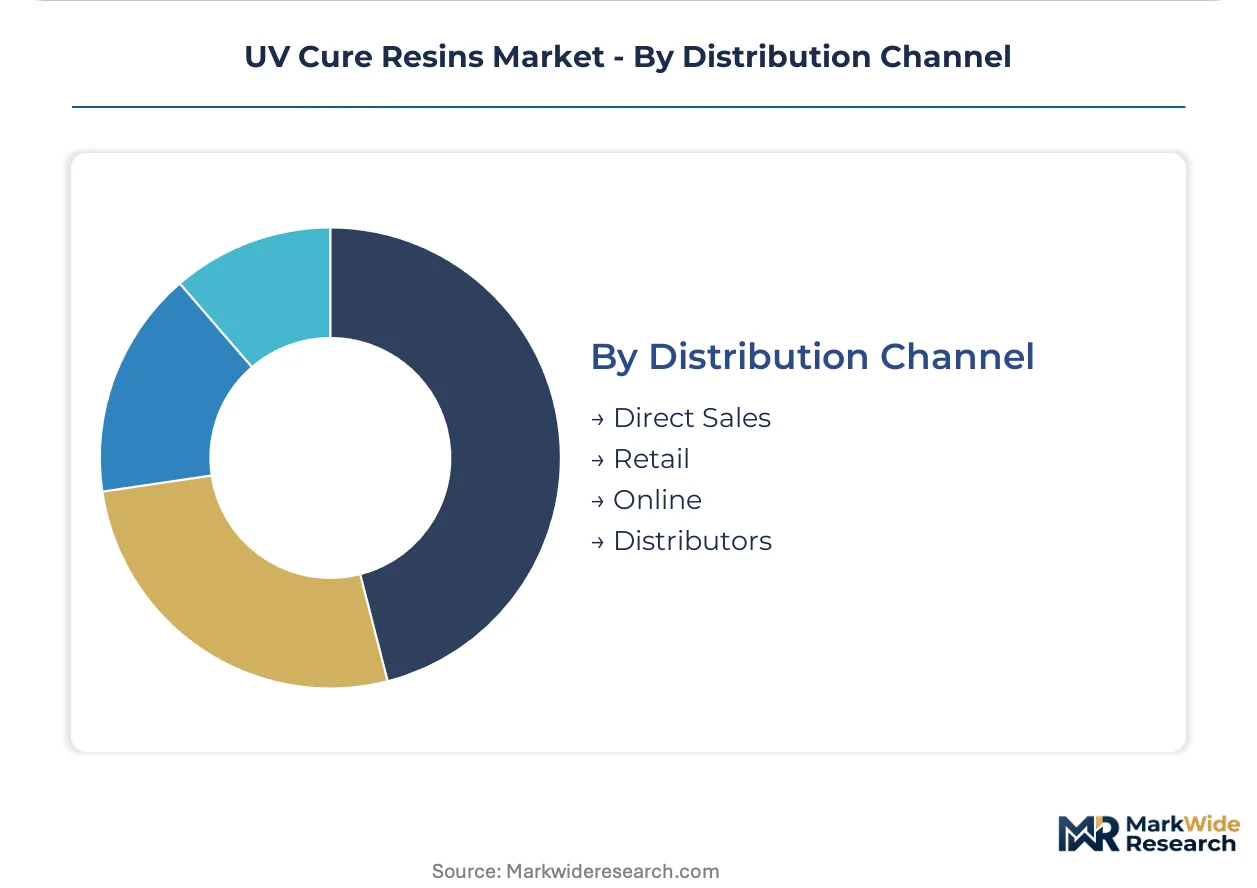
Distribution Channel:
Channel selection correlates with formulation complexity and technical service requirements.
- Distributors:Regional chemical distributors dominate mid-tier coating producer supply, bundling oligomers with photoinitiators and technical support.
- Direct Sales:Large automotive and electronics manufacturers negotiate annual contracts with integrated monomer-to-oligomer producers for feedstock security.
- Online:Small job shops and 3D printing service bureaus procure LED-optimized resin packages through specialty chemical marketplaces.
- Retail:Limited to consumer-grade 3D printing resins and small-volume repair coatings.
Distributors capture the broadest reach; direct sales secure the largest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta's furniture manufacturing corridor generates the densest concentration of UV cure resin consumption outside petrochemical hubs. Guangdong province's coating lines convert thermal-cure assets at accelerating rates as MEE emissions enforcement tightens permit allocations for solvent-based operations.
China
Zhejiang province exporters are consolidating procurement through integrated coating service platforms to satisfy EU and US retail VOC audits. MEE dual carbon enforcement is redirecting capital toward UV line conversions in automotive clusters across the Yangtze River Delta. Domestic resin producers are scaling acrylate oligomer capacity to serve regional demand from PCB manufacturers in Jiangsu and semiconductor packagers in Shanghai.
United States
EPA VOC penalties are accelerating line conversions in automotive refinish shops and wood furniture manufacturing across the Midwest and Southeast. Michigan and Ohio-based tier suppliers specify polyurethane acrylates for OEM color matching requirements. The agency's escalating enforcement in coating operations is compressing payback periods for UV capital investments in industrial facilities.
Germany
Automotive refinish suppliers in Baden-Württemberg and Bavaria are front-loading validation trials ahead of ECHA's anticipated TPO authorization timeline. REACH restrictions on benzophenone photoinitiators are forcing 18-24 month reformulation cycles on inkjet developers. Covestro AG anchors supply security through integrated polyurethane dispersion production for premium clearcoat specifications.
India
Gujarat and Tamil Nadu electronics manufacturing zones are emerging as first-mover markets under the PLI scheme for domestic PCB production. BIS standards alignment with RoHS directives is redirecting formulation sourcing toward UV-curable solder mask suppliers. Coating producers in these states are building technical service capabilities to support line conversions from thermal-cure alternatives.
Netherlands
Allnex Netherlands B.V. leverages its integrated monomer-to-oligomer platform to secure feedstock reliability for acrylate resin output serving European coating formulators. ECHA substance evaluation dossiers are concentrating toxicology expertise in Rotterdam-Antwerp chemical corridor operations. The country's position as a regulatory compliance hub is attracting reformulation investment from ink and coating developers facing REACH deadlines.
UV Cure Resins Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive monomer supply and specialized photoinitiator formulators. Three archetypes dominate: integrated resin-oligomer producers controlling upstream feedstock, photoinitiator specialists competing on compatibility breadth, and regional coating service platforms bundling formulation with application equipment. Capacity expansion and strategic partnerships represent the primary competitive vectors as formulators rebuild portfolios around safer cleavage-type photoinitiators.
Among European integrated producers, Allnex Netherlands B.V., Covestro AG, and Arkema Group occupy positions spanning oligomer production through formulated resin supply. These entities exemplify the feedstock-integrated archetype that dominates acrylate and polyurethane resin output. IGM Resins represents the photoinitiator-specialist tier, competing on formulation flexibility for regional inkjet developers navigating ECHA authorization timelines. BASF SE and DIC Corporation anchor diversified chemical portfolios that span multiple resin chemistries and geographic markets.
| Leading Market Players |
|---|
| Allnex Netherlands B.V. |
| BASF SE |
| Covestro AG |
| Arkema Group |
| IGM Resins |
| DIC Corporation |
| Resonac Holdings Corporation |
| Alberdingk Boley GmbH |
| Miwon Specialty Chemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EU Green Deal industrial emissions benchmarks gate qualified supply and premium-tier pricing access for UV cure resin producers serving European coating formulators. REACH authorization timelines for legacy photoinitiators compress reformulation windows, forcing buyers toward validated alternative chemistries at higher price points while integrated monomer-to-oligomer platforms capture margin premiums.
Pricing Analysis
Throughput-based pricing anchors value capture for UV cure resin suppliers, with formulators paying premiums tied to line speed guarantees and defect rate reductions in high-volume coating operations. Three-tier pricing structure across photoinitiator-optimized, standard acrylate, and economy polyester grades differentiates by certification tier and technical service bundling. Cost compression in standard acrylate tiers intensifies because Chinese domestic producers are scaling capacity in the Yangtze River Delta. Small furniture finishers in Vietnam and Mexico exhibit highest price sensitivity, while German automotive refinish suppliers prioritize photoinitiator compatibility over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive tier suppliers and electronics manufacturers, while regional chemical distributors serve mid-tier coating producers with bundled oligomer-photoinitiator packages. Feedstock reliability draws from integrated production platforms concentrated in the Netherlands, Germany, and China. Acrylate monomer supply rests on a narrow base of upstream producers, with photoinitiator sourcing tethered to specialized chemical manufacturers in Belgium and Japan. Single-source vulnerability in benzophenone alternative development creates bottleneck risk as ECHA authorization deadlines approach. Distribution runs through formulation service platforms in China's Pearl River Delta that bundle resin supply with application equipment and technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylate monomer supply concentration props pricing power for integrated producers, constraining downstream formulators and creating acquisition premiums for captive feedstock assets.
For Market Incumbents: To counter ECHA photoinitiator authorization disruptions, secure backward integration into cleavage-type photoinitiator production or exclusive supply partnerships with validated alternative suppliers. Expand technical service capabilities in China's Yangtze River Delta to capture platform procurement consolidation among furniture exporters facing EU and US retail VOC audits.
For New Entrants and Emerging Players: Enter via customized urethane acrylate development for 3D printing vat photopolymerization systems, where post-cure warpage reduction commands premium positioning. Target India's Gujarat and Tamil Nadu electronics manufacturing zones under PLI scheme incentives, offering UV-curable solder mask formulations with BIS-RoHS alignment as the go-to-market anchor.
For Investors and Strategic Acquirers: German automotive refinish suppliers front-loading validation trials is the leading indicator that photoinitiator-compatible resin portfolios will command scarcity premiums. Over the medium-term horizon, prioritize acquisition targets with integrated monomer-to-oligomer production and established ECHA dossier expertise. Watch for MEE emissions permit tightening announcements in China's automotive clusters as the signal for accelerated UV line conversion demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Production | Secures supply continuity for European formulators navigating ECHA authorization timelines. |
| Capacity Expansion in Yangtze River Delta | Captures MEE-driven UV line conversions among domestic automotive coating producers. |
| Joint Venture with LED Equipment Manufacturers | Accelerates 395-nm optimized formulation adoption among Vietnam and Mexico job shops. |
| Long-term Supply Agreement with PCB Manufacturers | Locks in volume commitments from India's PLI-scheme electronics zones in Gujarat and Tamil Nadu. |
| Green Manufacturing Transition Certification | Qualifies premium pricing access under EU Green Deal industrial emissions benchmarks. |
Research Methodology
Multi-period observation of photoinitiator authorization timelines, line conversion rates, and regional emissions enforcement anchored the trend analysis, supplemented by interviews with coating plant managers, resin procurement leads at automotive tier suppliers, distribution channel partners, and technical R&D directors. Secondary validation drew from ECHA substance evaluation dossiers, EPA enforcement records, Chinese MEE emissions permit databases, and customs trade data. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the analysis window.
Segment-weighting applied product type, application vertical, end-user industry, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Industry-specific inputs included photoinitiator substitution rates, LED cure equipment adoption curves, and dual carbon policy enforcement intensity in Chinese manufacturing corridors.
Revisions become necessary when ECHA accelerates or delays TPO authorization timelines, when Chinese MEE enforcement intensity shifts, or when semiconductor packaging demand for low-shrinkage epoxy resins diverges from base case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Polyether Block Amide Market