
 Fluid Bed and Coating System Market | 2026-2036
Fluid Bed and Coating System Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Bed and Coating System Market Analysis
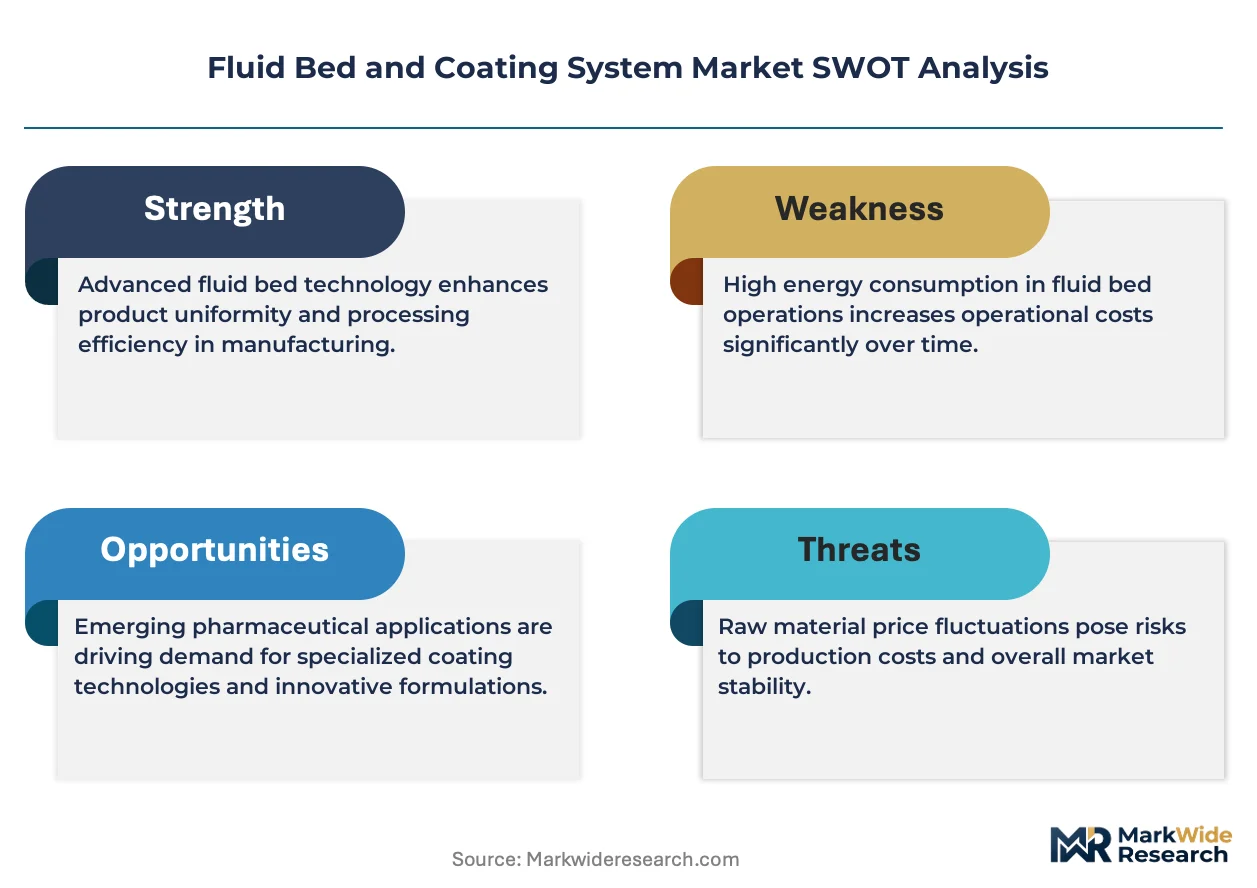
Preventive maintenance contracts and software-defined process control is hardening as the primary revenue layer beyond hardware sales. GEA Group AG leverages its aftermarket service infrastructure across European pharmaceutical clusters. Freund-Vector Corporation anchors its North American position through specialized batch system support programs. Glatt GmbH dominates German-speaking markets with integrated process analytical technology services.
Fluid bed and coating systems suspend particulate solids in upward-flowing process air while applying atomized liquid coatings or achieving thermal drying, typically operating between 40°C and 120°C with air velocities of 0.4–2.5 m/s depending on particle density and target moisture content. Batch systems command the largest installed base among pharmaceutical end users due to validated cleaning protocols and regulatory familiarity. Continuous systems attract new investment from food and beverage processors seeking throughput gains without scale-up validation cycles. Coating technology generates premium margins compared to drying or mixing functions because film uniformity directly determines bioavailability and shelf stability in oral dosage forms.
FDA process validation guidance and EU GMP Annex 15 shape equipment qualification requirements across all major supply markets. EPA air emission standards for volatile organic compounds from coating solvents influence system design in US chemical and food processing installations. Stakeholders must monitor how evolving EMA guidelines on continuous manufacturing validation reshape customer preferences between batch and continuous architectures.
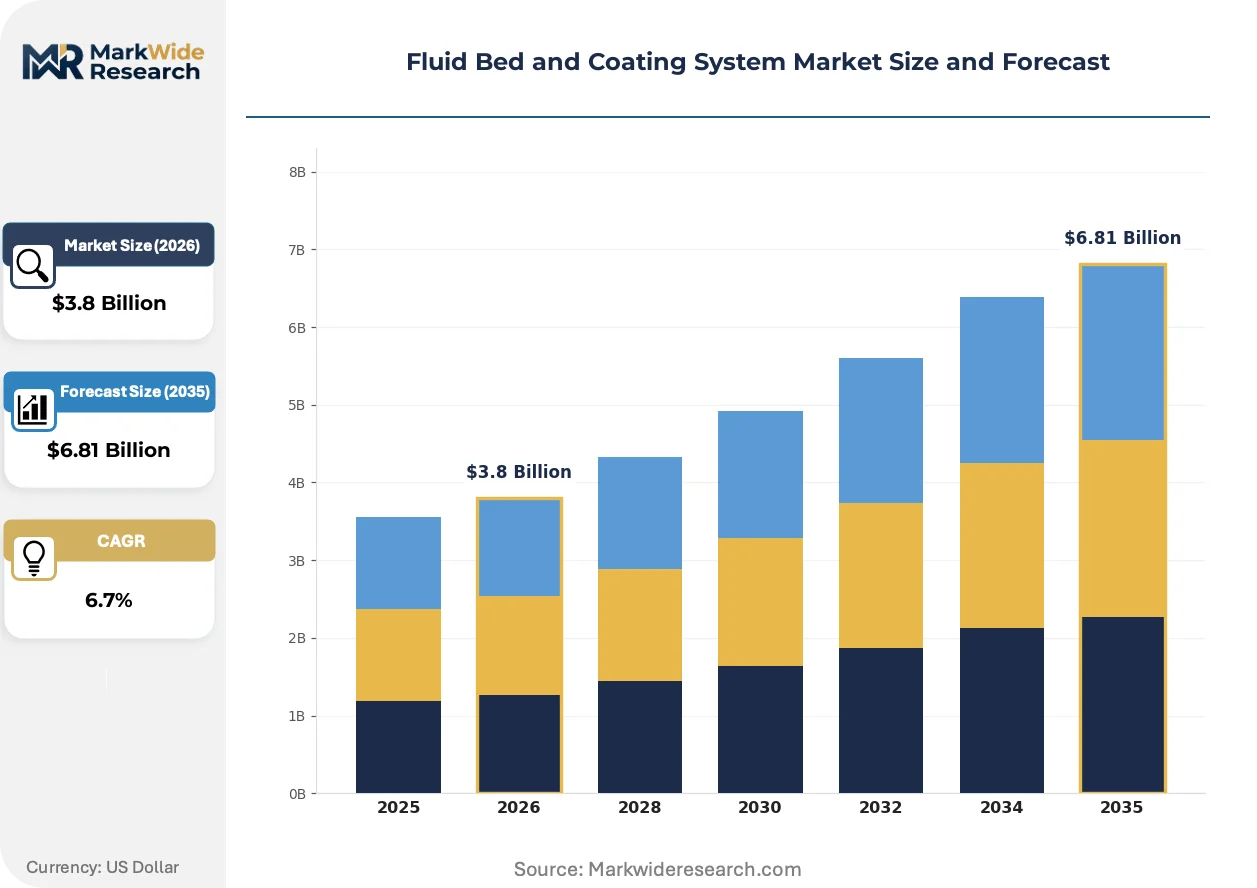
Market Dynamics
Continuous manufacturing validation requirements from FDA and EMA are forcing pharmaceutical processors to reevaluate capital deployment between batch and continuous fluid bed architectures, compressing equipment replacement cycles and expanding qualification service contracts.
Growth Catalysts
- EU GMP Annex 15 alignment:European pharmaceutical manufacturers are accelerating equipment qualification investments to meet revised process validation guidelines, expanding demand for integrated analytical technology services.
- Specialty oral dosage expansion:Controlled-release tablet and pellet formulations require precision coating uniformity, driving specification upgrades in film application systems across contract manufacturing organizations.
- India:Domestic pharmaceutical equipment demand is strengthening under PLI scheme incentives for active pharmaceutical ingredient and formulation manufacturing, with local producers expanding batch system capacity.
Market Restraints
- Stainless steel alloy volatility:Equipment fabrication costs fluctuate with nickel and chromium input prices, compressing margin stability for mid-scale system builders.
- Specialized technician scarcity:Process analytical technology integration requires hybrid mechanical-electrical-software competencies that outpace vocational training pipeline output.
- EPA VOC emission thresholds:Coating solvent recovery system mandates add capital intensity to US chemical and food processing installations, extending payback periods.
Strategic Opportunities
- Brazil:ANVISA harmonization with ICH Q12 lifecycle management guidelines creates first-mover advantage for suppliers offering continuous manufacturing validation packages.
- Cell therapy support media:Bioprocessing applications for fluid bed granulation of serum-free media powders represent untapped equipment utilization outside traditional pharmaceutical solid dosage.
- Remote diagnostic convergence:Integration of vibration analysis sensors with cloud-based process historians enables predictive maintenance subscription models that decouple revenue from unit shipments.
Industry Challenges
- IQ/OQ/PQ documentation burden:Equipment qualification protocol execution consumes 12-18 months for complex coating systems, straining customer engineering resources and delaying revenue recognition.
- Legacy control system incompatibility:Brownfield pharmaceutical facilities operate Siemens S7 or Allen-Bradley PLC architectures that resist seamless integration with modern process analytical technology platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Bed and Coating System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Systems, Pilot Systems, Laboratory Systems End User: Pharmaceuticals, Food & Beverage, Chemicals, Nutraceuticals Technology: Granulation, Coating, Drying, Mixing Capacity: Small Scale, Medium Scale, Large Scale, Custom-Built |
| Companies Covered | Glatt GmbH, Freund-Vector Corporation, GEA Group AG, Bühler Holding AG, Romaco Group, L.B. Bohle, Robert Bosch GmbH, Spraying Systems Co., Andritz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Bed and Coating System Market Emerging Trajectories
Equipment architecture is fragmenting between standardized skid-mounted units for commodity applications and highly customized continuous processing trains for complex oral dosage forms, with software-defined control layers emerging as the primary differentiation vector.
Process analytical technology is modularizing around plug-and-play near-infrared and Raman spectroscopy modules that retrofit existing fluid bed vessels without mechanical modification. Large-scale generic pharmaceutical manufacturers in India and China are adopting these retrofit packages aggressively to avoid capital-intensive system replacement. The technology is modularizing quality assurance from offline laboratory testing into real-time release verification, compressing batch release timelines from days to hours.
FDA draft guidance on continuous manufacturing quality considerations is tightening equipment qualification expectations for integrated powder feeding and discharge systems. The regulation requires demonstrated process robustness across defined design spaces rather than fixed setpoints, compelling equipment suppliers to expand validation service portfolios. Oral solid dosage manufacturers in the United States are responding by consolidating supplier relationships toward vendors with demonstrated continuous manufacturing regulatory filing support.
Service contract unbundling is separating preventive maintenance, spare parts logistics, and process optimization consulting into discrete purchase decisions rather than bundled annual agreements. Contract development and manufacturing organizations are driving this fragmentation, preferring to self-execute routine maintenance while purchasing specialist consulting on-demand. The pattern is most pronounced in Germany and Switzerland, where pharmaceutical engineering capabilities concentrate and in-house technical depth supports selective outsourcing.
Fluid Bed and Coating System Market Segmentation
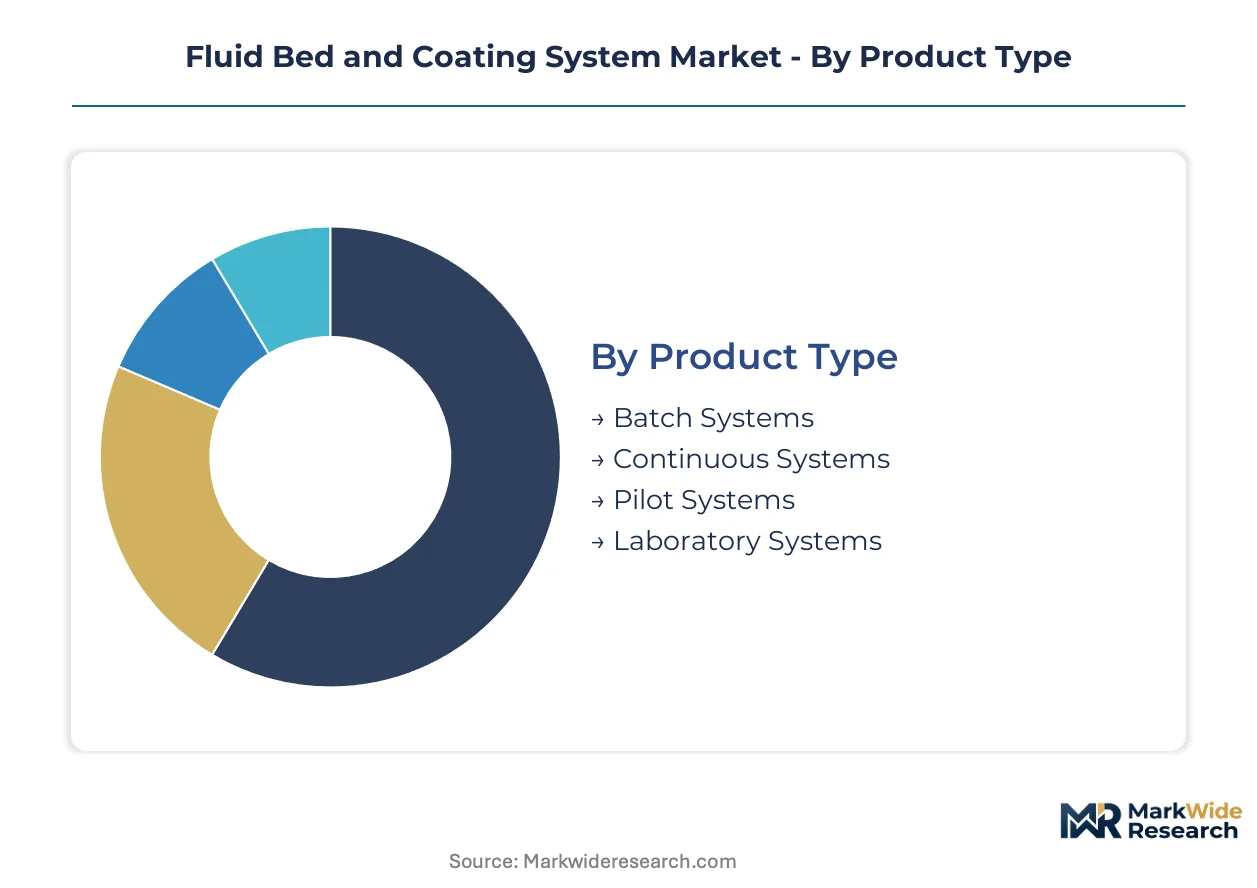
Fluid bed and coating system procurement decisions split sharply between validated pharmaceutical batch architectures and throughput-driven continuous designs. Equipment specification cascades from end-use regulatory burden through capacity scaling economics to technology functional requirements.
Product Type:
Volume concentration favors standardized batch units, while premium margins attach to continuous processing trains with integrated analytical packages.
- Batch Systems:These units process discrete material loads with validated cleaning protocols between cycles, dominating pharmaceutical installations where FDA and EMA qualification requirements demand extensive documentation. North American and German pharmaceutical manufacturers maintain the densest installed base, driven by regulatory familiarity and established cleaning validation procedures that compress requalification timelines for new product introductions.
- Continuous Systems:Material flows uninterrupted through integrated powder feeding, fluidization, and discharge stages, attracting food and beverage processors in the United States seeking throughput gains without scale-up validation cycles. The technology eliminates batch-to-batch variability but requires demonstrated process robustness across defined design spaces rather than fixed setpoints, expanding validation service portfolios for suppliers with regulatory filing experience.
- Pilot Systems:Intermediate-scale units bridge laboratory development and commercial manufacturing, serving contract manufacturing organizations in India that require flexible capacity for multiple client products under PLI scheme incentives.
- Laboratory Systems:Bench-scale configurations support formulation development and process parameter mapping, concentrating in Swiss and German pharmaceutical research clusters with strong in-house engineering capabilities.
Mature deployment sits with batch systems. Newer deployment is concentrated in continuous systems.
End User:
Regulatory stringency determines equipment specification tiers, with pharmaceutical buyers absorbing premium pricing for qualification support while chemical processors prioritize capital efficiency.
- Pharmaceuticals:Oral solid dosage manufacturers command the largest equipment investment per installation, driven by coating uniformity requirements for controlled-release tablet and pellet formulations that directly determine bioavailability and shelf stability.
- Food & Beverage:Processors in the United States deploy fluid bed drying for ingredient moisture control, with EPA VOC emission thresholds from coating operations adding capital intensity through mandated solvent recovery systems.
- Chemicals:Specialty chemical producers in Germany utilize granulation technology for catalyst and additive production, balancing throughput requirements against stainless steel alloy price volatility in fabrication cost structures.
- Nutraceuticals:Dietary supplement manufacturers in India represent emerging demand concentration, with domestic equipment makers competing against multinational suppliers for batch system contracts under expanding formulation manufacturing capacity.
Pharmaceutical end users absorb the highest service contract attachment rates. Nutraceutical buyers are gaining share fastest among new equipment shipments.
Technology:
Functional application separates premium-margin coating operations from commodity drying and mixing configurations.
- Coating:Film application systems achieve precision uniformity through atomized liquid deposition onto fluidized particulate beds, generating superior margins compared to other functions due to direct impact on oral dosage form performance characteristics. Contract manufacturing organizations drive specification upgrades as controlled-release formulations expand across specialty pharmaceutical portfolios.
- Granulation:Particle size enlargement through binder liquid addition and subsequent drying serves oral solid dosage preparation, with cell therapy support media applications representing untapped utilization outside traditional pharmaceutical solid dosage for serum-free media powder processing.
- Drying:Thermal moisture removal operates across temperature ranges between 40°C and 120°C with air velocities of 0.4–2.5 m/s depending on particle density and target moisture content, serving as foundational capability across all end-use segments.
- Mixing:Homogeneous powder blending functions as auxiliary capability integrated within multi-purpose fluid bed units rather than standalone system justification.
Coating technology commands premium positioning. Drying functions as baseline capability with compressed differentiation potential.
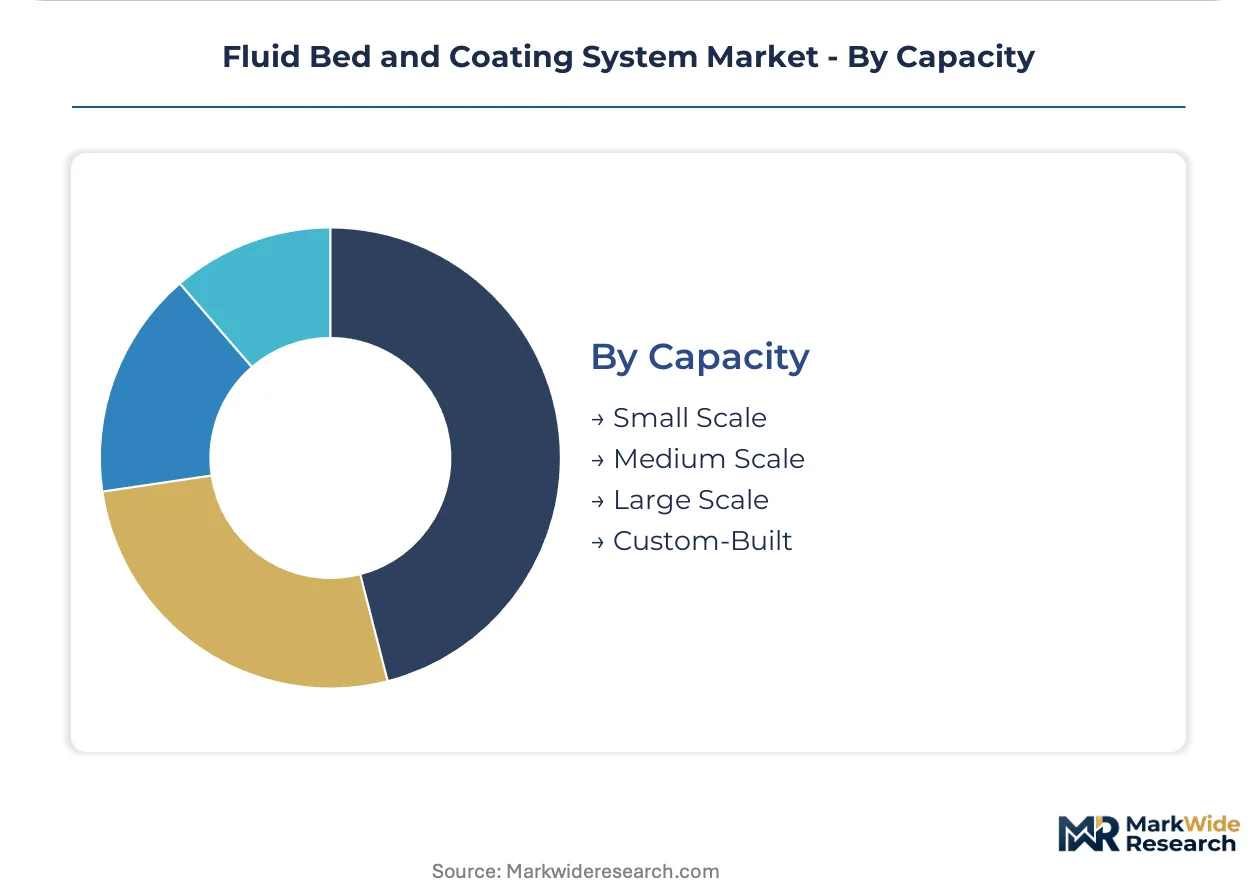
Capacity:
Scale economics fragment procurement between standardized skid-mounted units and customized processing trains.
- Large Scale:Production trains exceeding 500 kg batch capacity serve high-volume generic pharmaceutical manufacturers in India and China, where retrofit process analytical technology packages avoid capital-intensive system replacement while enabling real-time release verification.
- Medium Scale:Mid-range configurations balance throughput flexibility with capital efficiency, dominating contract development and manufacturing organization installations where product mix variability requires adaptable capacity.
- Small Scale:Limited-capacity units support niche product manufacturing and clinical trial material production, concentrating in Swiss and German pharmaceutical engineering clusters with selective outsourcing preferences.
- Custom-Built:Engineered-to-order systems address unique process constraints or facility integration requirements, extending equipment qualification protocol execution to 12-18 months for complex coating installations.
Large scale units anchor volume concentration. Custom-built configurations are expanding most quickly as continuous manufacturing validation requirements reshape equipment architecture preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the densest concentration of fluid bed and coating system manufacturing capacity, while the United States and India absorb the largest equipment import volumes for pharmaceutical processing installations.
United States
Oral solid dosage manufacturers in New Jersey and North Carolina are retrofitting legacy batch systems with process analytical technology modules to compress batch release timelines. FDA draft guidance on continuous manufacturing quality considerations tightens equipment qualification expectations for integrated powder feeding systems. The Boston-Cambridge pharmaceutical engineering cluster concentrates pilot-scale system demand for cell therapy support media applications.
Germany
Specialty chemical producers in North Rhine-Westphalia utilize granulation technology for catalyst production, balancing throughput against stainless steel alloy price volatility. EMA guidelines on continuous manufacturing validation reshape customer preferences between batch and continuous architectures in Baden-Württemberg pharmaceutical facilities. The Frankfurt-Rhine-Main region anchors aftermarket service contract concentration for validated equipment.
India
Domestic pharmaceutical equipment demand strengthens under PLI scheme incentives for active pharmaceutical ingredient manufacturing, with Maharashtra-based producers expanding batch system capacity. CDSCO alignment with ICH Q12 lifecycle management guidelines accelerates equipment qualification investments. The Hyderabad-Pune corridor concentrates contract manufacturing organization installations requiring flexible pilot-scale configurations.
Switzerland
Pharmaceutical research clusters in Basel and Zurich drive bench-scale laboratory system demand for formulation development and process parameter mapping. Swissmedic requirements for process validation documentation support premium pricing for integrated analytical technology services. The Swiss-German border region concentrates engineering capabilities that enable selective outsourcing of maintenance functions.
China
Large-scale generic pharmaceutical manufacturers in Jiangsu and Zhejiang provinces adopt retrofit process analytical technology packages to avoid capital-intensive system replacement. NMPA process validation guidance shapes equipment qualification requirements for oral solid dosage producers. The Yangtze River Delta concentrates domestic equipment fabrication capacity serving regional pharmaceutical and nutraceutical processors.
Fluid Bed and Coating System Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across equipment specification tiers, with integrated system builders maintaining fabrication capabilities while specialized engineering consultancies supply validation documentation and process optimization services. The vendor base organizes around three strategic archetypes: multinational conglomerates with aftermarket service infrastructure, mid-scale domestic fabricators serving regional pharmaceutical clusters, and niche specialists in continuous manufacturing validation packages. Consolidation pressure operates through strategic partnerships between equipment makers and process analytical technology suppliers, plus geographic expansion into PLI scheme beneficiary markets.
Among German-based integrated equipment builders, Glatt GmbH, GEA Group AG, and L.B. Bohle occupy positions spanning batch and continuous system architectures. Freund-Vector Corporation represents the North American specialist archetype with concentrated service program deployment. Bühler Holding AG exemplifies the diversified industrial conglomerate model with cross-sector equipment fabrication capabilities. These named entities anchor competitive positioning without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Glatt GmbH |
| Freund-Vector Corporation |
| GEA Group AG |
| Bühler Holding AG |
| Romaco Group |
| L.B. Bohle |
| Robert Bosch GmbH |
| Spraying Systems Co. |
| Andritz |
| Others |
Supply Flow & Price Mechanics
Family-owned German equipment fabricators anchor supply-side concentration, enabling disciplined pricing power through captive stainless steel processing capabilities and long-term service contract anchoring against multinational aftermarket competitors.
Pricing Analysis
Cost-down pressure on mid-scale system builders accelerates because nickel and chromium alloy volatility compresses fabrication margin stability. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical installations from food-grade commodity configurations and basic chemical processing units. Price differentiation traces to certification grade and after-sales service bundling. Contract manufacturing organizations exhibit highest price sensitivity; oral solid dosage manufacturers absorb premium positioning for qualification support.
Supply Chain Analysis
Stainless steel alloy supply rests on German and Chinese specialty metal producers serving equipment fabrication hubs. Control system components draw from Japanese and German automation specialists. Single-source vulnerability concentrates in process analytical technology sensor modules. Distribution runs through direct OEM channels for validated pharmaceutical systems and regional distributor networks for commodity chemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum intensifies as equipment suppliers pursue captive process analytical technology module production to defend margin structure against component cost volatility.
For Market Incumbents: Lock in aftermarket service contract renewal through predictive maintenance platform deployment. Expand validation documentation capabilities to compress IQ/OQ/PQ timelines for customers facing FDA continuous manufacturing guidance pressure. Backward integration into stainless steel processing mitigates alloy price volatility exposure. For New Entrants and Emerging Players: Cloud-based remote diagnostic subscriptions offer low-capital entry into pharmaceutical service contract fragmentation. Target nutraceutical equipment demand in India under PLI scheme expansion. Position pilot-scale flexible configurations for contract manufacturing organizations seeking multi-client capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale domestic fabricators in India with established CDSCO regulatory relationships. Five-to-ten-year viability hinges on continuous manufacturing validation service portfolio depth. Watch FDA draft guidance finalization timing as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Process Analytical Technology Module Integration | Enables real-time release verification for FDA continuous manufacturing compliance. |
| Predictive Maintenance Platform Launch | Decouples recurring revenue from unit shipment cyclicality for service providers. |
| Backward Integration into Stainless Steel Processing | Reduces fabrication cost volatility exposure for German equipment builders. |
| Continuous Manufacturing Validation Package Development | Captures premium service margins from EMA guideline alignment investments. |
| PLI Scheme Geographic Expansion | Positions batch system capacity for Maharashtra and Hyderabad-Pune corridor demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs. Primary interviews with pharmaceutical plant engineers, aftermarket service directors, OEM procurement teams, and regulatory affairs specialists combined with FDA guidance documents, EMA submission databases, and equipment import statistics. Bottom-up installation base modeling and top-down market sizing triangulated value outputs.
Segmentation granularity modeled product type, end user, technology function, and capacity tier across the analysis window. CAGRs derived from equipment shipment trajectory analysis and service contract attachment rate evolution. Forecast inputs incorporated PLI scheme incentive disbursement patterns and stainless steel price index volatility assumptions.
The model holds under stable regulatory guidance implementation timelines; deviation in FDA continuous manufacturing finalization pace or EMA Annex 15 enforcement intensity would shift equipment replacement cycle assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Solar Reflective Film Market
Coatings
PU Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Glass Coatings Market
Coatings
Europe Powder Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
UV Coatings Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Carpet Back Coatings Market
Coatings
Anti-Microbial Nano Coatings Market
Coatings
OEM Coatings Market
Coatings
Canada Floor Coatings Market
Coatings
Shipping Container Coatings Market