
 Global High-Performance Anti-Corrosion Coatings Market | 2026-2036
Global High-Performance Anti-Corrosion Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global High-Performance Anti-Corrosion Coatings Market Foresight
Market Context
Project finance structures for large infrastructure coatings programs are reshaping competitive access, allowing mid-tier applicators to bid on billion-dollar energy contracts without carrying full material inventory risk. PPG Industries leverages its marine certification network to dominate specification-driven procurement in offshore environments. Akzo Nobel N.V. sustains R&D intensity in zinc-rich primer technology across European shipyards. Hempel A/S anchors its position through backward integration into epoxy resin supply for North Sea wind installations.
Technical Definition and Segment Structure
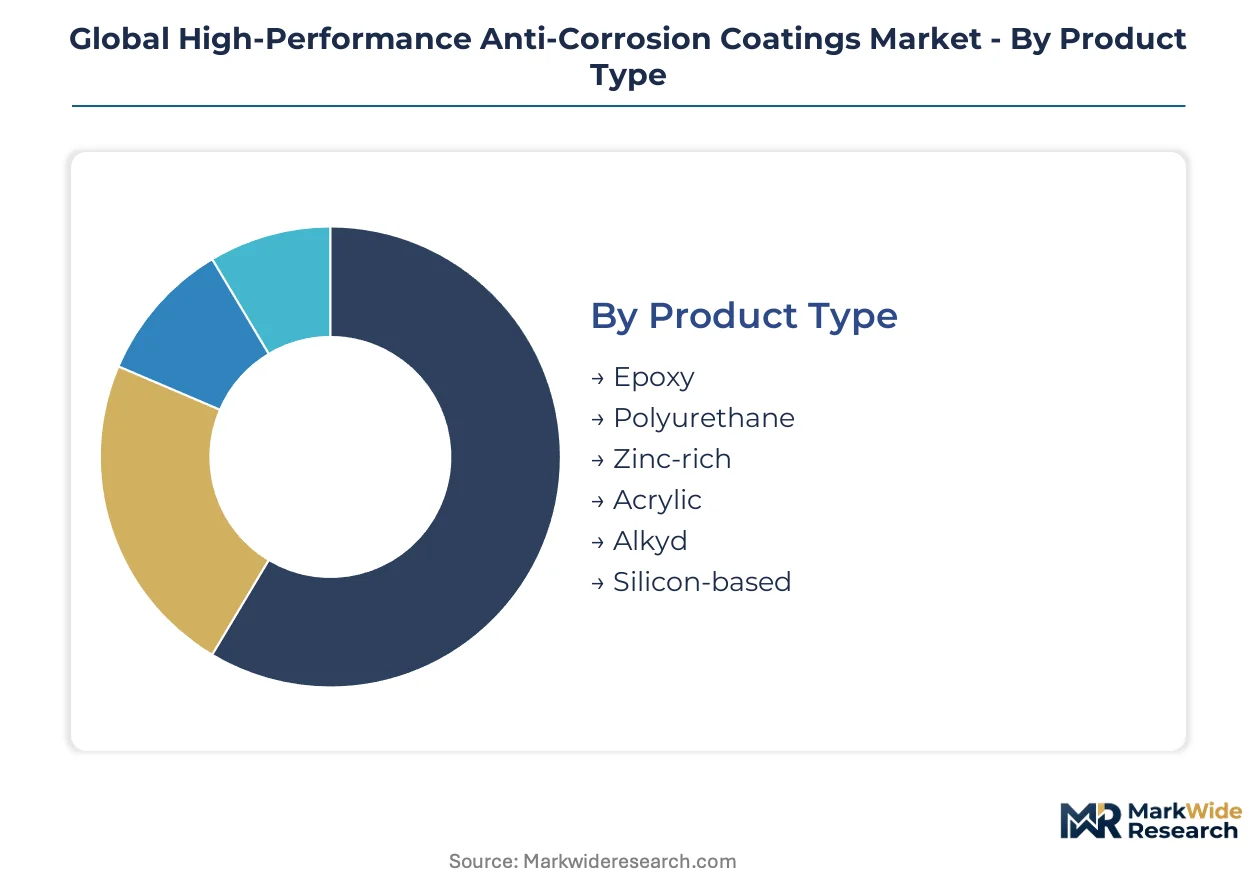
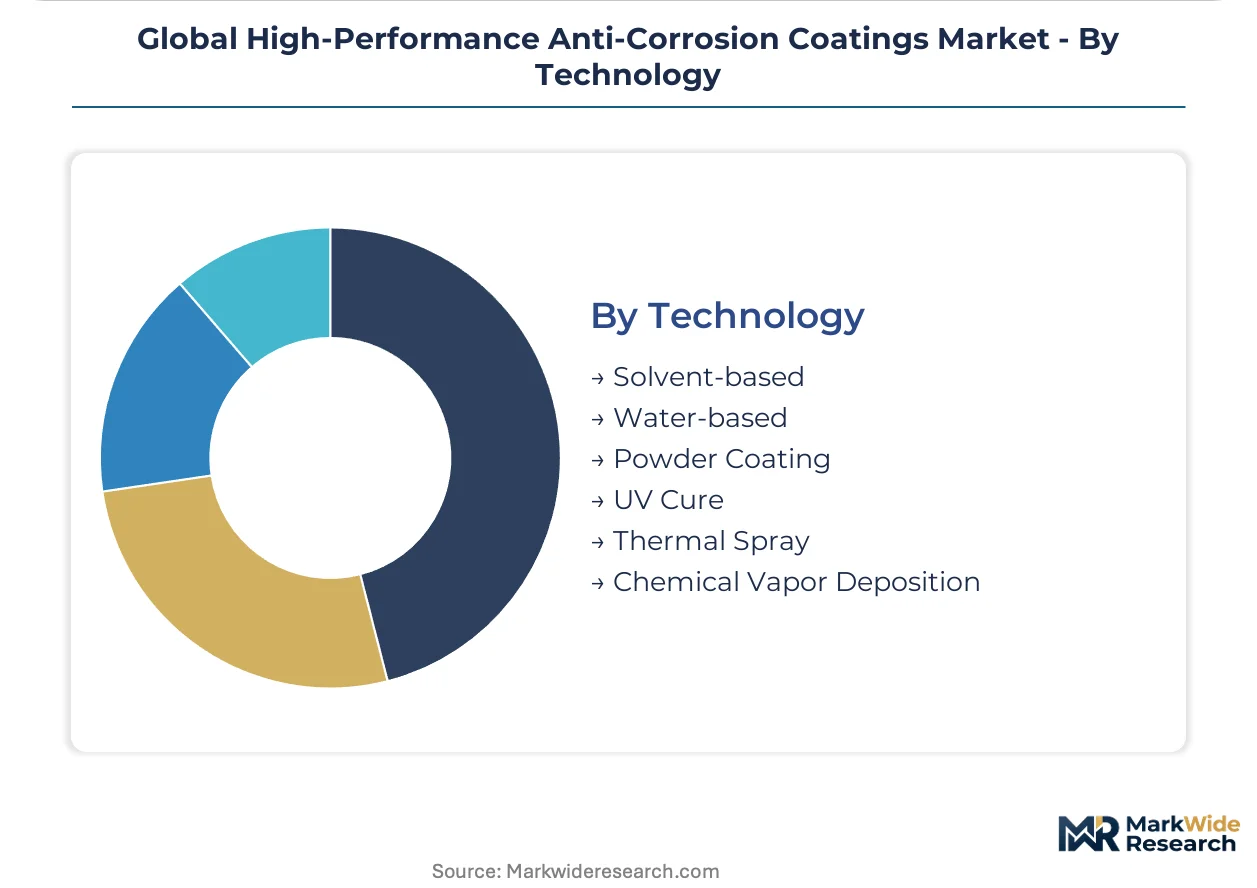
High-performance anti-corrosion coatings are engineered protective films, typically 75–500 micrometers dry-film thickness, formulated with barrier pigments, sacrificial metal particles, or chemically resistant polymers to prevent substrate degradation from electrochemical reaction, chemical attack, or atmospheric exposure in aggressive industrial settings. Epoxy systems occupy the largest value share due to their adhesion strength and chemical resistance in oil and gas infrastructure, while water-based technologies represent the fastest-growing technology category as environmental compliance tightens across coastal manufacturing zones. Powder coating applications in transportation equipment are maturing in Europe and East Asia, with margin pools concentrating in custom-formulated solvent-free systems for chemical processing vessels.
Regulatory Framework and Outlook
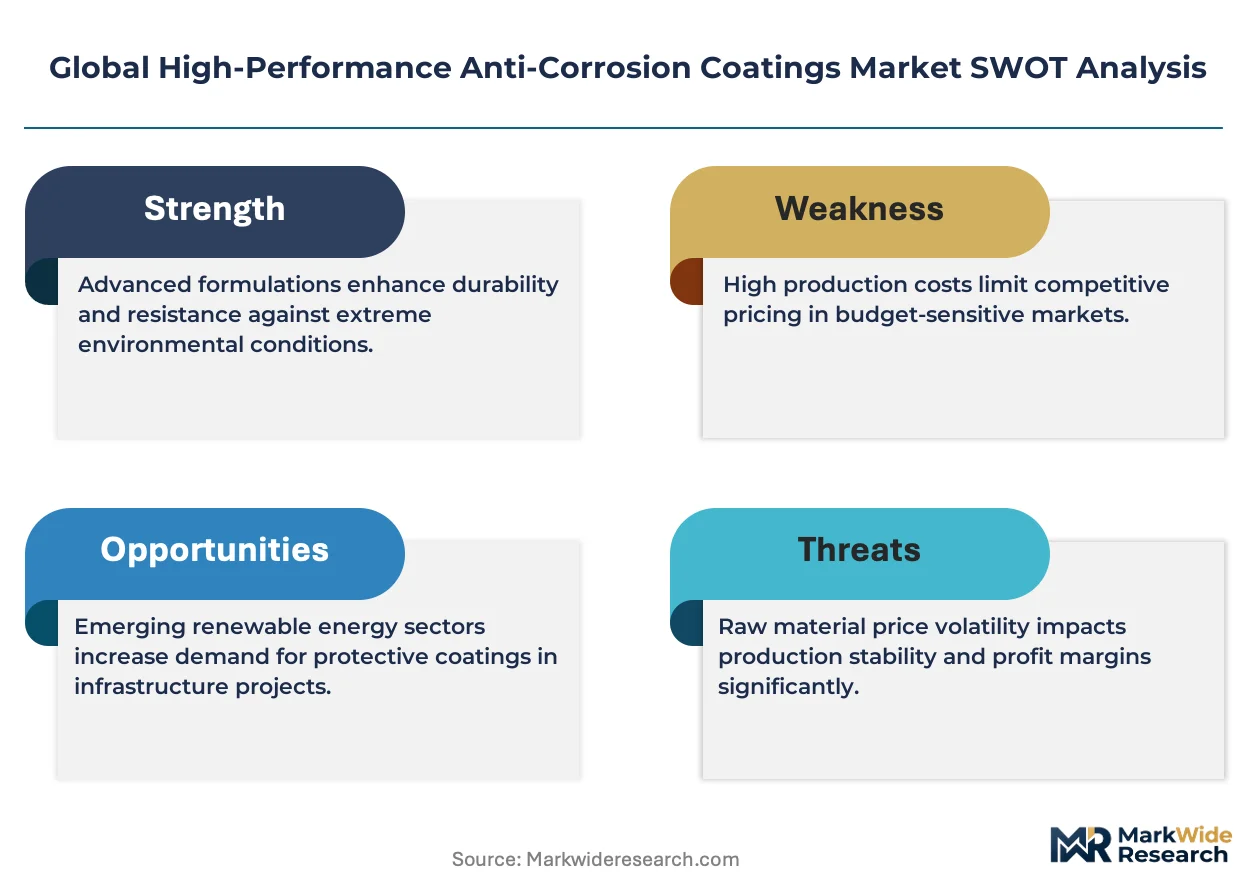
REACH restrictions on chromate and isocyanate content, EPA NESHAP standards for hazardous air pollutants in coating operations, and China's MEE enforcement of VOC emission limits collectively elevate formulation costs while creating specification barriers for uncertified suppliers. The EU F-Gas Regulation and evolving IMO antifouling conventions further constrain product portfolios, pushing manufacturers toward bio-based resin development. Stakeholders must monitor how diverging national chemical registries affect cross-border product registration costs and local manufacturing requirements.
Market Dynamics
Water-based formulation development is collapsing the traditional solvent-borne supply base as REACH and EU Green Deal VOC restrictions force capital reallocation across European manufacturing footprints.
Growth Catalysts
- Offshore wind installation surge:North Sea and East Asian governments are mandating gigawatt-scale renewable capacity additions, driving specification demand for immersion-grade epoxy systems on turbine foundations and transition pieces.
- MEE enforcement in China:China's Ministry of Ecology and Environment has tightened VOC emission limits for coastal manufacturing zones, accelerating domestic water-based coating substitution in shipyard and petrochemical applications.
- Subsea pipeline replacement cycles:North Sea and Gulf of Mexico operators are executing decade-overdue maintenance on corrosion-damaged infrastructure, creating pull-through demand for thermally sprayed aluminum and fusion-bonded epoxy.
Market Restraints
- Bisphenol A epoxy feedstock volatility:Petrochemical supply concentration in the US Gulf Coast and Northeast Asia creates margin compression risk for formulated coating producers during crude price spikes.
- Chromate primer phase-out friction:REACH Annex XVII restrictions on hexavalent chromium compounds force aerospace and defense applicators to qualify slower-curing titanate and silicate alternatives, extending job timelines.
- Zinc dust supply geography:Electrolytic zinc production concentrates in Australia and Kazakhstan, exposing marine coating formulators to concentrate transport cost inflation and smelter capacity constraints.
Strategic Opportunities
- Hydrogen infrastructure white space:Germany and the Netherlands are deploying high-pressure hydrogen pipeline networks requiring novel coating systems resistant to hydrogen embrittlement and permeation.
- Carbon capture vessel coatings:Amine-based solvent absorption units for post-combustion carbon capture require chemically resistant linings that incumbent epoxy suppliers are only beginning to qualify.
- EU Green Deal public procurement:The European Commission's sustainable product criteria for infrastructure tenders create preferential access for bio-based resin formulators meeting ISO 14040 lifecycle standards.
Industry Challenges
- NACE coating inspector certification scarcity:The pipeline of qualified inspectors for offshore asset condition assessment trails project award velocity in Brazil and West Africa, delaying contract commencement.
- Application equipment capex intensity:Plural-component spray systems for high-solids epoxy require six-figure capital outlays that exclude smaller marine maintenance contractors from specification-grade work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High-Performance Anti-Corrosion Coatings Market |
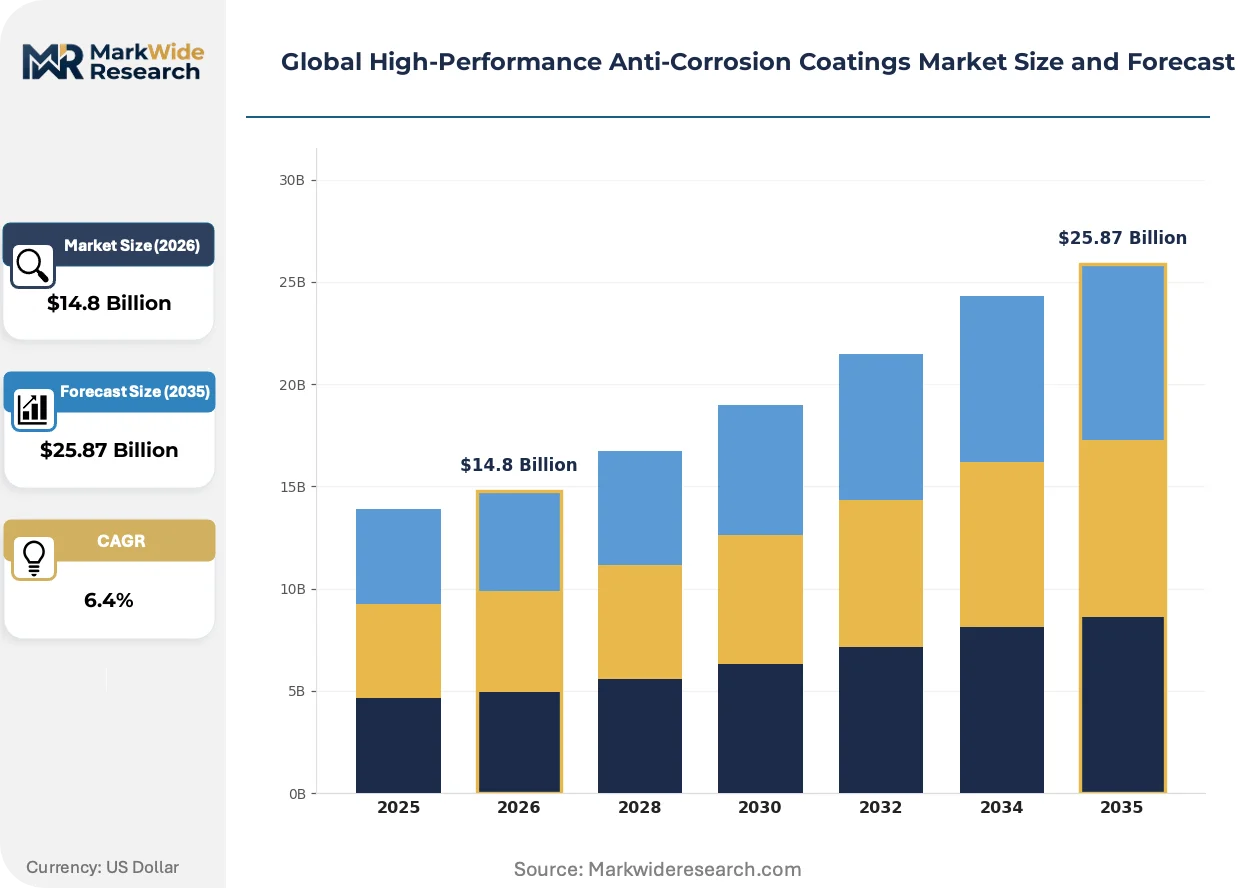
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Zinc-rich, Acrylic, Alkyd, Silicon-based Application: Marine Equipment, Oil & Gas Infrastructure, Power Generation, Transportation Equipment, Chemical Processing, Water Treatment End User Industry: Manufacturing Plants, Construction Firms, Energy Facilities, Heavy Machinery Operators, Metal Fabrication Units, Infrastructure Projects Technology: Solvent-based, Water-based, Powder Coating, UV Cure, Thermal Spray, Chemical Vapor Deposition |
| Companies Covered | Jotun Group, Axalta Coating Systems, Akzo Nobel N.V., RPM International Inc., BASF SE, PPG Industries, Inc., Hempel A/S, Kansai Paint Co., Ltd., Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High-Performance Anti-Corrosion Coatings Market Shifts & Advancements
Bio-based resin chemistry and digital application monitoring are converging to redefine performance benchmarks and warranty structures across industrial protective coatings.
Self-healing microcapsule technology is collapsing the maintenance cycle economics for subsea risers and splash zone assets. Norwegian offshore operators are piloting these systems on platform structural members, compressing the interval between drydock inspections from five years to eight while shifting liability toward coating suppliers.
REACH authorization requirements for isocyanate-containing hardeners are forcing polyurethane coating reformulation across European shipyards. The restriction triggers accelerated polyaspartic and polysiloxane development, with classification societies in Hamburg and Rotterdam updating type approval protocols to accommodate reduced-cure-temperature alternatives.
Asset owner engineering teams are consolidating coating specification authority away from maintenance contractors and into centralized procurement functions. This concentration favors formulators with direct technical service presence in Aberdeen, Singapore, and Houston, compressing distributor margins and rewarding vertically integrated suppliers with captive specification influence.
Global High-Performance Anti-Corrosion Coatings Market Segmentation
Coating selection in this market hinges on service lifecycle intensity, where specification-grade systems demand continuous technical support from formulation through warranty expiration. Segment boundaries increasingly blur as applicators bundle inspection, maintenance, and recoating services into multi-year contracts.
Product Type:
After-sales-service intensity varies sharply across chemistries, with immersion-grade systems requiring dedicated field engineering support throughout asset life.
- Epoxy:Two-component amine-cured formulations deliver the highest adhesion strength and chemical resistance for subsea pipelines and offshore platforms. Demand concentrates in the North Sea and Gulf of Mexico, where operators specify fusion-bonded epoxy for new pipeline construction and rehabilitation of corrosion-damaged infrastructure.
- Polyurethane:Aliphatic topcoats provide UV stability and gloss retention for exterior structural steel in marine atmospheres. Japanese shipyards and Korean offshore fabricators drive procurement of moisture-cured variants for high-humidity application windows.
- Zinc-rich:Inorganic silicate binders with metallic zinc loading above 85% by weight provide sacrificial protection for steel substrates in salt-laden environments.
- Acrylic:Thermoplastic emulsions and solvent-borne resins offer rapid dry-to-recoat intervals for maintenance painting in operational facilities.
- Alkyd:Modified drying-oil vehicles remain economical for atmospheric exposure in light industrial settings with moderate corrosivity.
- Silicon-based:Inorganic polysiloxane and silicone-modified polymers withstand continuous temperatures exceeding 400°C in exhaust stacks and fired heaters.
Epoxy holds the largest share; momentum sits with polyurethane as classification societies in Hamburg and Rotterdam update type approval protocols for reduced-cure-temperature alternatives.
Application:
Cost tier stratification separates specification-driven procurement in capital projects from maintenance budgets constrained by operational expenditure limits.
- Marine Equipment:Immersion-grade and atmospheric-zone coatings for vessels, offshore platforms, and port infrastructure subject to IMO antifouling conventions and classification society rules. Norwegian operators pilot self-healing microcapsule systems on platform structural members to extend drydock intervals.
- Oil & Gas Infrastructure:Internal linings for sour service, external coatings for buried and subsea pipelines, and fireproofing for topside facilities. Brazil and West Africa exhibit the steepest expansion trajectory as pre-salt development and marginal field revitalization accelerate coating procurement.
- Power Generation:Protective systems for boilers, turbines, cooling water systems, and transmission structures in fossil and renewable installations.
- Transportation Equipment:Railcar interiors and exteriors, commercial vehicle bodies, and aerospace structural primers facing chromate phase-out pressures.
- Chemical Processing:Tank linings and vessel coatings resistant to acids, caustics, and solvent exposure in continuous process operations.
- Water Treatment:Potable water contact approvals and wastewater corrosion protection for municipal and industrial treatment infrastructure.
Marine Equipment commands premium pricing; Oil & Gas Infrastructure is climbing the fastest on subsea pipeline replacement cycles and pre-salt development.
End User Industry:
Volume concentration tracks capital expenditure cycles, with large project awards consolidating procurement authority away from maintenance contractors.
- Energy Facilities:Refineries, petrochemical complexes, LNG terminals, and renewable energy installations requiring comprehensive corrosion management programs. China's state-owned energy majors drive infrastructure coating procurement at scale for coastal refining expansions.
- Manufacturing Plants:Process equipment, structural steel, and storage assets in continuous production environments with scheduled turnaround windows.
- Construction Firms:Structural steel fireproofing and corrosion protection for commercial and industrial building frameworks.
- Heavy Machinery Operators:Mining equipment, material handling systems, and agricultural machinery exposed to abrasive and corrosive operating conditions.
- Metal Fabrication Units:Shop-applied primers and pre-construction coatings for steel components prior to field erection.
- Infrastructure Projects:Bridges, tunnels, and public works requiring long-duration performance warranties and certified application.
Energy Facilities dominate current procurement value; Manufacturing Plants represent the steadiest replacement demand through turnaround-driven maintenance.
Technology:
Maturity gradients separate established application methods from emerging systems still navigating qualification protocols and equipment investment barriers.
- Water-based:Acrylic and epoxy emulsions with VOC content below regulatory thresholds for coastal manufacturing zones. REACH and EU Green Deal restrictions are accelerating substitution in European shipyards, while China's MEE enforcement drives domestic formulation development.
- Solvent-based:Conventional high-solids and conventional-solids systems retaining performance advantages in immersion service and low-temperature application. Regulatory pressure is concentrating remaining demand in jurisdictions with delayed VOC implementation timelines.
- Powder Coating:Thermoset epoxy and polyester powders applied electrostatically to transportation equipment and pipeline fittings.
- UV Cure:Rapid-curing acrylate formulations for small-diameter pipe interiors and complex geometries where thermal curing is impractical.
- Thermal Spray:Metallized aluminum and zinc coatings applied by flame or arc spray for subsea and splash-zone protection.
- Chemical Vapor Deposition:Thin-film ceramic and metallic coatings for precision components in aggressive chemical environments.
Solvent-based retains the largest installed base; Water-based is gaining share fastest on regulatory compliance and equipment cost reductions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal VOC restrictions and China's MEE enforcement are accelerating formulation shifts across coastal manufacturing zones, while offshore wind procurement in the North Sea and East Asia reshapes specification demand.
China
State-owned energy majors drive infrastructure coating procurement at scale for coastal refining expansions. MEE enforcement of VOC emission limits accelerates domestic water-based formulation substitution in shipyard and petrochemical applications. Concentrated demand clusters in the Yangtze River Delta, where marine fabrication yards execute specification-grade contracts.
Germany
High-pressure hydrogen pipeline deployment creates novel coating demand resistant to hydrogen embrittlement. REACH authorization requirements for isocyanate-containing hardeners force polyurethane reformulation across Hamburg and Rotterdam-linked shipyards. Industrial coating specification authority concentrates in centralized procurement functions serving North Sea offshore wind installations.
United States
Gulf of Mexico operators execute decade-overdue subsea pipeline maintenance, pulling demand for thermally sprayed aluminum and fusion-bonded epoxy. EPA NESHAP standards for hazardous air pollutants elevate formulation costs while creating barriers for uncertified suppliers. Houston anchors technical service presence for specification influence over billion-dollar energy contracts.
Norway
Offshore operators pilot self-healing microcapsule systems on platform structural members to extend drydock intervals. EU F-Gas Regulation constrains product portfolios, pushing manufacturers toward bio-based resin development. Aberdeen and Stavanger clusters concentrate specification-grade procurement authority for North Sea asset integrity programs.
Brazil
Pre-salt development and marginal field revitalization accelerate coating procurement for subsea infrastructure. NACE coating inspector certification scarcity trails project award velocity, delaying contract commencement. Rio de Janeiro and Espírito Santo fabrication yards drive demand for immersion-grade epoxy systems on floating production units.
Global High-Performance Anti-Corrosion Coatings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification-driven procurement segments. The market structure consolidates around vertically integrated formulators with captive resin supply and technical service networks, alongside regional applicators bundling inspection and maintenance services. Three archetypes dominate: marine-certified specification holders, water-based formulation specialists, and integrated coating-applicator hybrids. Competitive moves concentrate on backward integration into epoxy resin supply and direct technical service placement in Aberdeen, Singapore, and Houston.
Among diversified chemical conglomerates, BASF SE and RPM International Inc. occupy positions spanning multiple industrial coating chemistries. PPG Industries exemplifies the marine certification archetype through specification-driven procurement dominance in offshore environments. Akzo Nobel N.V. anchors the European R&D-intensive tier, while Hempel A/S represents backward integration into resin supply for wind installation markets. Kansai Paint Co., Ltd. and Jotun Group sit within the Asia-Pacific specialist tier serving regional shipyard demand.
| Leading Market Players |
|---|
| Jotun Group |
| Axalta Coating Systems |
| Akzo Nobel N.V. |
| RPM International Inc. |
| BASF SE |
| PPG Industries, Inc. |
| Hempel A/S |
| Kansai Paint Co., Ltd. |
| Sherwin-Williams Company |
| Others |
Supply & Pricing Matrix
Electrolytic zinc production concentrates in Australia and Kazakhstan, concentrating margin pools with marine coating formulators who secure long-term concentrate offtake agreements. REACH and EU Green Deal compliance costs cascade downstream, compressing distributor margins while rewarding vertically integrated suppliers with captive specification influence.
Pricing Analysis
Certification level (IMO marine-grade, NORSOK M-501, and ISO 12944 compliance) creates the primary spread between specification-grade systems and commodity alternatives. Project-based long-term contracting dominates, with price differentiation driven by technical service bundling and volume scale for billion-dollar energy contracts. Cost compression in water-based formulations is intensifying because MEE enforcement in China accelerates domestic substitution. Maintenance contractors in Brazil and West Africa exhibit highest price sensitivity due to NACE inspector scarcity, while North Sea offshore operators show lowest sensitivity given warranty-critical applications.
Supply Chain Analysis
Contract manufacturing for epoxy resin synthesis concentrates with European and Northeast Asian petrochemical complexes serving formulation plants. Geographic supply concentrates in Germany, China, and the United States for bisphenol A epoxy feedstock. Raw material dependencies rest on electrolytic zinc dust, amine curing agents, and barrier pigment concentrates. Single-source vulnerability runs through Kazakhstan smelter capacity for zinc dust supply. Distribution feeds from formulator technical service hubs in Aberdeen, Singapore, and Houston directly to asset owner procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based formulation substitution threatens solvent-borne incumbents as REACH and MEE enforcement collapses the traditional supply base. Incumbents must navigate this technology transition while defending specification-grade positions.
For Market Incumbents: Harden specification influence through captive NACE inspector training programs in Brazil and West Africa, addressing certification scarcity that delays contract commencement. Deepen backward integration into epoxy resin supply to offset bisphenol A feedstock volatility from US Gulf Coast concentration. Defend against water-based specialists by accelerating bio-based resin qualification for EU Green Deal procurement preference.
For New Entrants and Emerging Players: Build out hydrogen infrastructure coating capabilities in Germany and the Netherlands, where high-pressure pipeline deployment creates novel demand resistant to hydrogen embrittlement. Target carbon capture vessel linings as the most penetrable white space, where amine-based solvent absorption units require chemically resistant systems that incumbent epoxy suppliers are only beginning to qualify. Establish direct technical service presence in Aberdeen or Houston to bypass compressed distributor margins.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-based formulation manufacturing as REACH compliance requires dedicated emulsion production lines. Long-term viability favors vertically integrated formulators with captive resin supply and marine certification networks. Acquisition target archetype: regional applicators bundling inspection and maintenance services in Brazil or West Africa. Monitor NACE certification velocity as the inflection indicator for contract commencement delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Supply | Hempel A/S anchors North Sea wind positions through captive resin production. |
| NACE Inspector Training Program Expansion | Addresses certification scarcity delaying Brazil and West Africa contract awards. |
| Bio-Based Resin Qualification Investment | Unlocks EU Green Deal public procurement preference under ISO 14040 standards. |
| Hydrogen Infrastructure Coating Development | Germany and Netherlands pipeline deployment requires novel embrittlement-resistant systems. |
| Technical Service Hub Establishment | Direct presence in Aberdeen, Singapore, or Houston bypasses distributor margin compression. |
Research Methodology
The analysis maps epoxy, polyurethane, zinc-rich, and water-based formulation sub-sectors, each validated through plant managers at coating manufacturing facilities, procurement leads at offshore operators, technical R&D directors, and aftermarket service heads. Primary interviews with these stakeholders combined with secondary validation from customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and IMO antifouling convention documentation. Bottom-up volume builds and top-down market sizing triangulated across segmentation dimensions.
Assumptions around regulatory enforcement timelines, crude price corridors for petrochemical feedstock costs, and offshore wind capacity deployment schedules were held fixed versus varied across sensitivity scenarios. The analytical framework models chemistry type, application environment, end-use industry, and technology format across the analysis window. CAGRs derived from segment-level demand drivers and substitution elasticity parameters, with inputs from subsea pipeline replacement cycle data and hydrogen infrastructure project announcements.
Stress conditions across MEE enforcement intensity, REACH authorization scope expansion, and zinc smelter capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that diverging national chemical registries could revise cross-border product registration cost trajectories. Quarterly review of NACE certification pipeline velocity and EU Green Deal procurement criteria updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Powder Coating Booth Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Coatings Raw Materials Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
North America Thermal Spray Market
Coatings
Bio-Based Coatings Market
Coatings
Fire Retardant Coatings Market
Coatings
Stealth Coating Material Market
Coatings
High Performance Epoxy Coating Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Marking Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Global Waterborne Coatings Market