
 Russia Protective Coatings Market | 2026-2036
Russia Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Protective Coatings Market Analytics
Modular service bundling is rebalancing buyer choice in the Russia Protective Coatings Market, as suppliers combine coating application with substrate preparation and inspection services into single-contract offerings. PPG Industries, Inc. leverages its technical service network to anchor long-term industrial maintenance contracts across Russian manufacturing corridors. Huntsman International LLC competes through specialized epoxy formulations engineered for extreme Arctic operating conditions. The Sherwin-Williams Company extends its position by controlling distribution channels in the Central Federal District.
Russia protective coatings are formulated systems comprising resin binders, pigments, solvents, and functional additives that cure to form adherent films providing corrosion resistance, chemical protection, or thermal stability to metal, concrete, and composite substrates. Epoxy systems dominate heavy industrial applications due to superior adhesion and chemical resistance against aggressive process fluids. Polyurethane segments command premium positioning in automotive and transportation end uses where flexibility and UV durability determine replacement cycles. Waterborne technology lines are gaining structural share as regulatory pressure on solvent emissions intensifies reformulation investments across domestic production facilities.
Russian technical regulation TR EAEU 042/2017 establishes mandatory safety requirements for chemical products including protective coatings, while the Federal Service for Environmental, Technological and Atomic Supervision enforces industrial safety standards at oil and gas installations that dictate coating performance specifications. Compliance with GOST standards and EAEU harmonized technical regulations shapes product registration requirements and market access conditions for both domestic manufacturers and imported formulations. Stakeholders must monitor evolving customs union technical regulations and localization incentives to calibrate supply chain and formulation strategies.
Market Dynamics
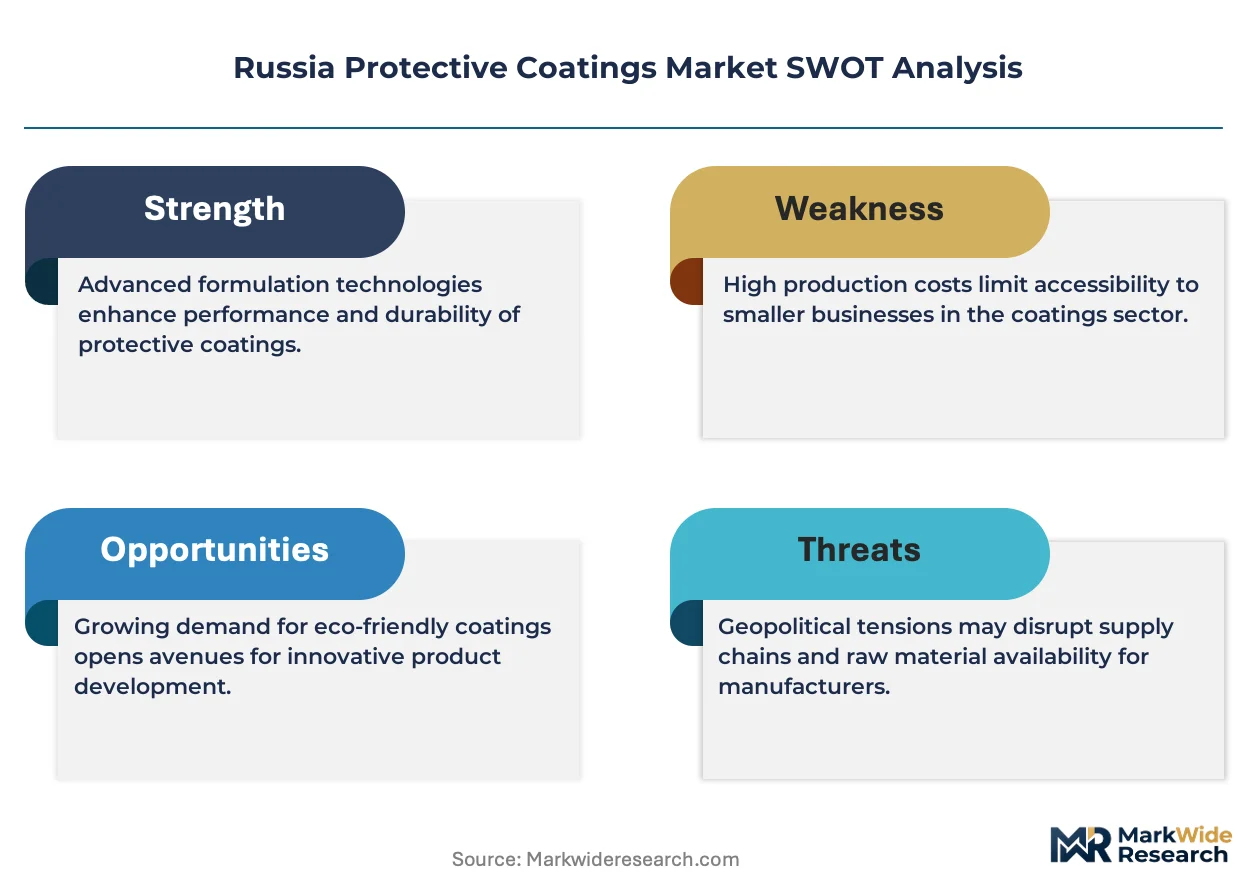
Reformulation pressure under TR EAEU 042/2017 is compressing solventborne coating margins while redirecting capital toward waterborne and high-solids development across Russian manufacturing corridors.
Growth Catalysts
- Arctic infrastructure mandates:Oil and gas operators in the Yamal-Nenets Autonomous Okrug require cold-cure epoxy systems that maintain adhesion at minus 50 degrees Celsius, expanding specification volumes for extreme-climate formulations.
- TR EAEU 042/2017 VOC limits:The technical regulation's tightening volatile organic compound thresholds is forcing domestic producers to retool coating lines, creating replacement demand for compliant waterborne alternatives in industrial maintenance.
- Shipbuilding cluster concentration:Zvezda Shipbuilding Complex in Primorsky Krai and Admiralty Shipyards in Saint Petersburg sustain heavy marine coating procurement for ice-class vessel construction and repair cycles.
Market Restraints
- Specialty resin import dependency:Epoxy hardeners and isocyanate curing agents concentrate supply from German and Chinese chemical producers, exposing formulators to currency volatility and customs clearance friction.
- Arctic logistics cost structure:Northern delivery routes to Norilsk and Vorkuta industrial sites multiply applied coating costs through temperature-controlled transport and seasonal access windows.
- Polyaspartic substitution threat:Fast-cure polyurea spray systems are displacing conventional epoxy tank linings in secondary containment applications where return-to-service speed governs contractor selection.
Strategic Opportunities
- Far East underpenetration:Sakhalin Oblast and Kamchatka Krai maintain limited local coating production, creating white space for toll manufacturing partnerships serving seafood processing and geothermal energy installations.
- Modular service bundling:Contractors are consolidating surface preparation, coating application, and NDT inspection into single-source contracts, shifting supplier relationships from product transactions to performance-based agreements.
- Import substitution incentives:The Russian government's localization requirements for state procurement are redirecting specification authority toward domestic formulators with verified supply chain documentation.
Industry Challenges
- Skilled applicator scarcity:NACE and FROSIO-certified coating inspectors remain concentrated in Moscow and Saint Petersburg, constraining quality assurance for remote pipeline and storage tank projects.
- Reformulation capex intensity:Waterborne alkyd and acrylic system development requires dedicated dispersion equipment and controlled humidity curing facilities that strain mid-tier producer balance sheets.
- EAEU harmonization lag:Divergent interpretation of technical regulations between Russian and Kazakh customs authorities creates product registration delays for formulations seeking cross-border market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Protective Coatings Market |
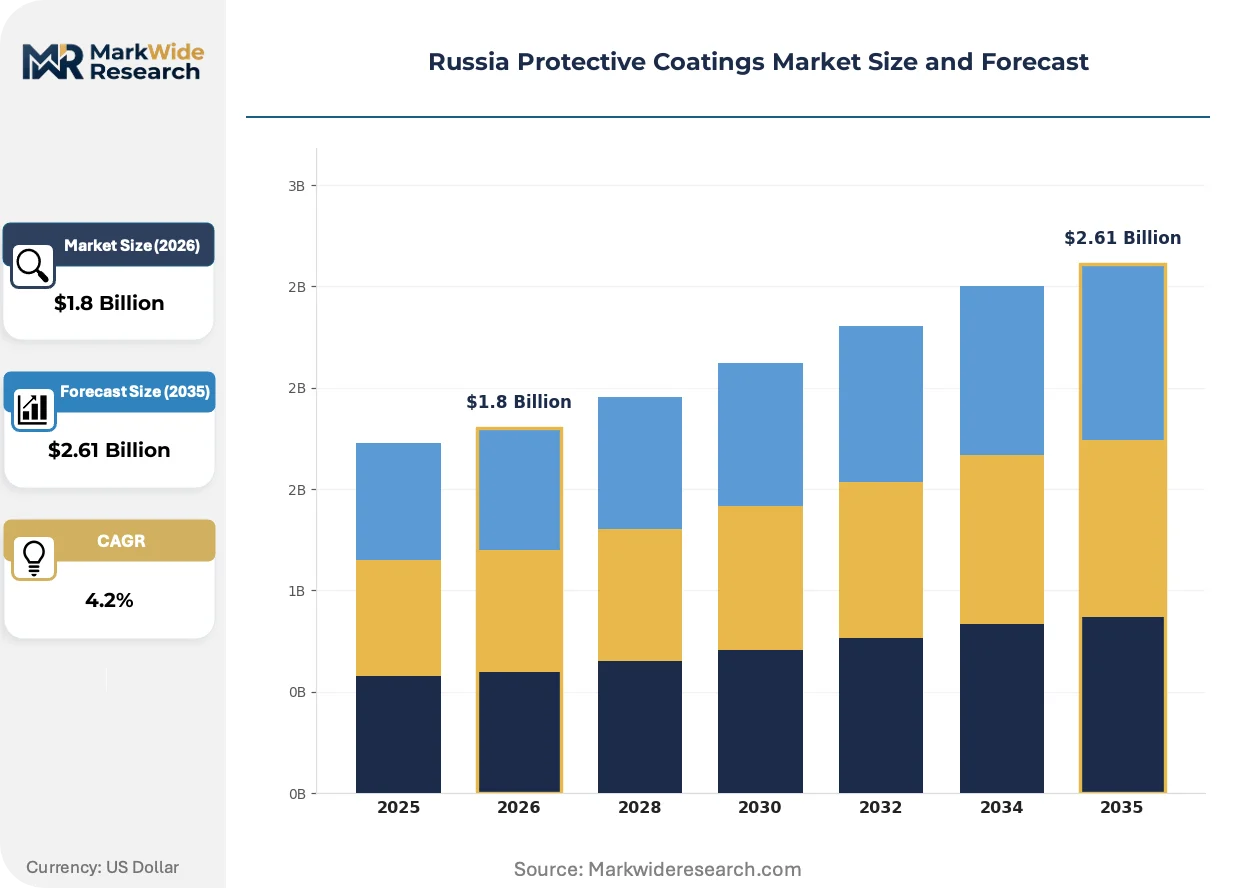
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd Application: Industrial, Marine, Automotive, Construction End User: Manufacturing, Oil & Gas, Transportation, Aerospace Technology: Waterborne, Solventborne, Powder Coating, UV-Cured |
| Companies Covered | Axalta Coating Systems, Huntsman International LLC, PPG Industries, Inc., RPM International Inc., The Sherwin-Williams Company, Russian Paints Company, Henkel AG & Co. KGaA, Sika AG, Tikkurila, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Protective Coatings Market Evolving Landscape
Active reformulation programs and procurement restructuring are compressing technology replacement cycles while elevating service integration as a competitive differentiator across Russian industrial corridors.
High-solids epoxy technology is rewriting specification standards for buried pipeline corrosion protection. Gazprom and Transneft maintenance divisions are accelerating adoption of solvent-free systems that achieve dry film thickness in single applications. This shift is compressing contractor labor hours and reducing volatile organic compound exposure liabilities at remote pumping stations.
TR EAEU 042/2017 enforcement is tightening product registration requirements for imported formulations. The Federal Service for Environmental, Technological and Atomic Supervision is expanding inspection protocols at oil and gas installations, forcing coating suppliers to maintain detailed technical documentation for batch traceability. Domestic producers with established GOST certification pathways are capturing specification share from import-dependent competitors.
Asset owner procurement departments are consolidating coating, insulation, and fireproofing contracts under integrated facility maintenance agreements. Saint Petersburg petrochemical complexes and Nizhny Novgorod automotive plants are leading this transition, replacing transactional material purchases with multi-year performance contracts. This restructuring favors suppliers with captive application crews and digital inspection reporting capabilities.
Russia Protective Coatings Market Segmentation
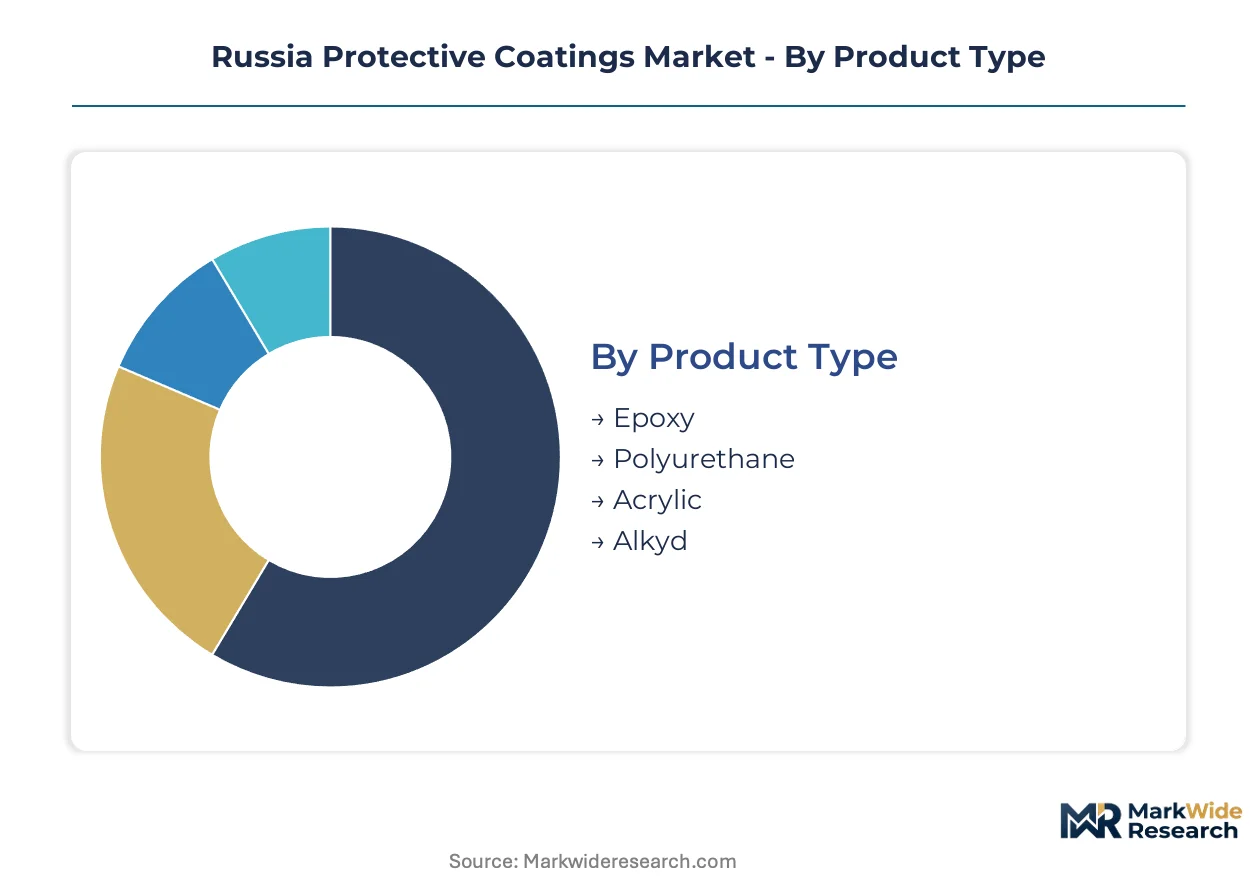
Protective coating specifications in Russia diverge sharply between standardized commodity formulations for volume construction and customized systems engineered for extreme Arctic operating conditions. Procurement patterns across federal districts reflect this bifurcation, with standardized alkyd and acrylic lines dominating housing rehabilitation while specialty epoxies command premium positioning in oil and gas infrastructure.
Product Type:
Customization intensity spans from commodity alkyds with minimal formulation variance to highly engineered epoxies requiring substrate-specific hardener selection and cure profile optimization.
- Epoxy:Two-part thermoset systems combining bisphenol-A or bisphenol-F resins with amine or polyamide hardeners deliver superior chemical resistance and adhesion to steel substrates. Demand concentrates in the Yamal-Nenets Autonomous Okrug, where Gazprom and Novatek specifications mandate cold-cure variants maintaining film integrity at minus 50 degrees Celsius under TR EAEU 042/2017 environmental compliance protocols.
- Polyurethane:Aliphatic and aromatic isocyanate-cured systems provide UV stability and flexibility for dynamic substrates. Automotive assembly plants in Tolyatti and Kaliningrad specify high-solids polyurethane topcoats for chassis and exterior components, driven by OEM warranty requirements extending corrosion protection to 12-year cycles.
- Acrylic:Thermoplastic resin systems offering rapid dry-to-touch properties and exterior durability for architectural metalwork.
- Alkyd:Oil-modified polyester resins dominating decorative and light industrial maintenance applications through cost-efficient single-pack convenience.
Leading the category by volume: Alkyd. Growing fastest: Epoxy, climbing the fastest on Arctic infrastructure mandates and pipeline rehabilitation cycles.
Application:
Application-specific formulation requirements range from immersion-grade marine systems to atmospheric exposure coatings for vertical infrastructure, with specification authority residing in distinct procurement channels across each sector.
- Industrial:Heavy-duty systems protecting processing equipment, storage tanks, and structural steel in chemical plants and power generation facilities. Petrochemical clusters in Nizhny Novgorod and Kazan drive specification volumes, with procurement departments consolidating coating contracts under integrated facility maintenance agreements that bundle surface preparation, application, and inspection services.
- Marine:Immersion and atmospheric zone coatings for hulls, decks, and ballast tanks subject to saltwater exposure and mechanical abrasion. Zvezda Shipbuilding Complex in Primorsky Krai and Admiralty Shipyards in Saint Petersburg sustain demand for ice-class vessel specifications requiring elastomeric anti-icing topcoats and cathodic protection compatibility.
- Automotive:OEM and refinish coatings for body-in-white, chassis, and component protection across passenger and commercial vehicle production.
- Construction:Architectural metal coatings for roofing, cladding, and structural elements in residential and commercial building envelopes.
Industrial commands the largest procurement volumes. Marine exhibits the steepest expansion trajectory on shipbuilding cluster development and Arctic fleet modernization.
End User:
End-user concentration determines specification complexity, with state-controlled oil and gas operators imposing rigorous qualification protocols compared to decentralized manufacturing procurement.
- Oil & Gas:Upstream, midstream, and downstream operations requiring corrosion protection for pipelines, storage tanks, and processing equipment. Transneft and Gazprom Neft maintenance divisions in the Volga Federal District specify solvent-free epoxy systems achieving dry film thickness in single applications, compressing contractor labor hours at remote pumping stations while reducing VOC exposure liabilities.
- Manufacturing:Diverse industrial facilities spanning automotive, electronics, and consumer goods production with coating needs for equipment, flooring, and structural steel. Nizhny Novgorod automotive plants and Saint Petersburg electronics manufacturers are transitioning from transactional material purchases to multi-year performance contracts favoring suppliers with captive application crews.
- Transportation:Rail, commercial vehicle, and infrastructure assets requiring protective and aesthetic coating systems.
- Aerospace:Military and civilian aircraft manufacturing with specialized primers and topcoats meeting weight, temperature, and aerodynamic specifications.
Oil and Gas dominates specification authority and contract value. Manufacturing is gaining share fastest on import substitution incentives and localization requirements for state procurement.
Technology:
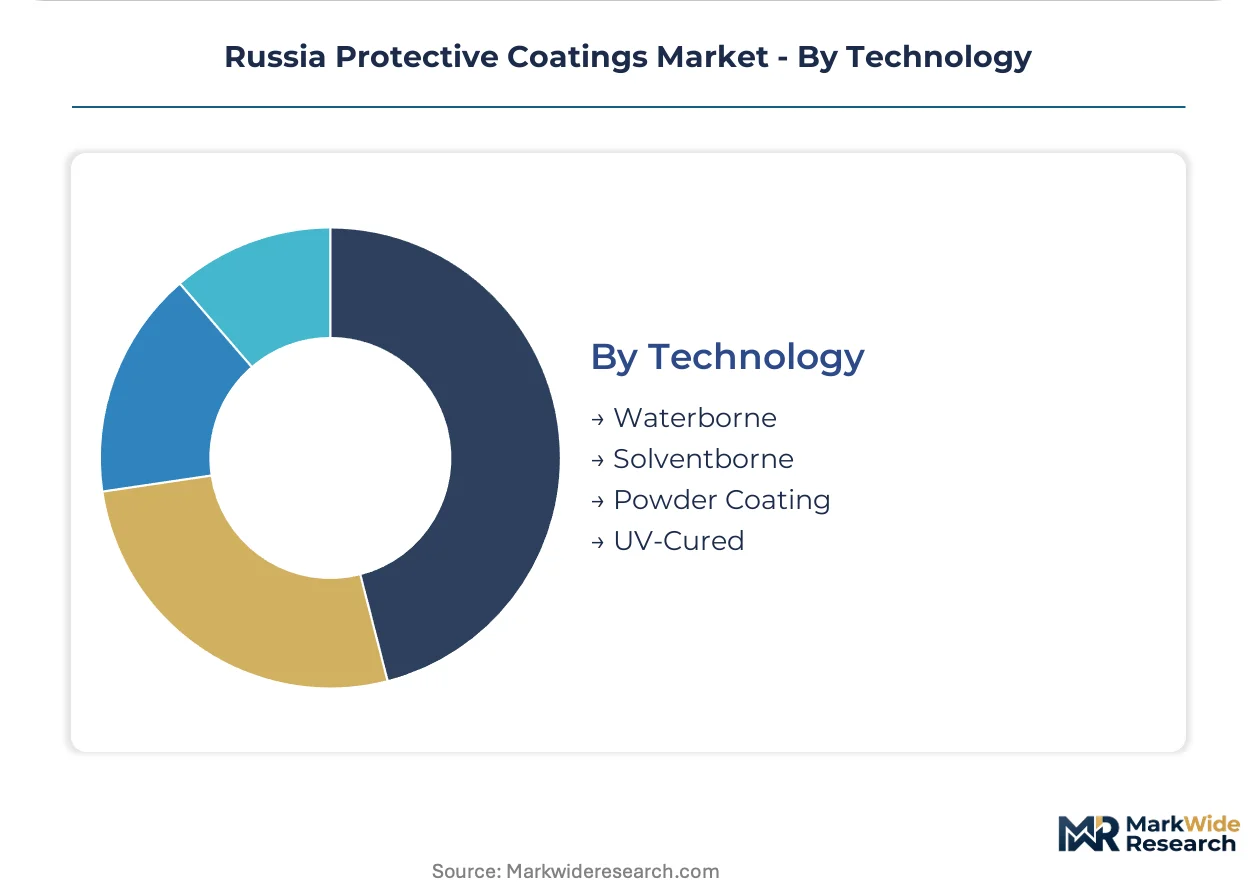
Technology selection reflects regulatory pressure gradient, with waterborne systems gaining structural share as TR EAEU 042/2017 VOC thresholds tighten while powder and UV-cured alternatives address specific substrate and throughput requirements.
- Solventborne:Conventional systems utilizing organic solvents for viscosity control and film formation, still prevalent in heavy industrial and marine applications where cure speed and substrate tolerance outweigh environmental considerations. Domestic producers are reformulating lines to meet tightened volatile organic compound limits, redirecting capital toward high-solids variants that reduce solvent content while maintaining application characteristics.
- Waterborne:Emulsion and dispersion-based systems using water as primary carrier, gaining specification share in industrial maintenance and architectural applications. Reformulation investments strain mid-tier producer balance sheets due to requirements for dedicated dispersion equipment and controlled humidity curing facilities.
- Powder Coating:Thermoset and thermoplastic dry powders applied electrostatically and cured through heat, dominating mass-production metal finishing with zero VOC emissions.
- UV-Cured:Photoinitiator-containing formulations polymerizing under ultraviolet radiation, enabling instant cure for high-throughput manufacturing lines with minimal thermal exposure to sensitive substrates.
Solventborne retains the largest installed base. Waterborne is expanding most quickly on regulatory compliance mandates and procurement department sustainability criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's protective coatings production clusters concentrate in the Central and Volga Federal Districts, while consumption gravity shifts toward Arctic oil and gas provinces and Far East shipbuilding corridors. This geographic mismatch elevates logistics costs and shapes regional procurement strategies.
Volga Federal District
Petrochemical processing complexes in Nizhny Novgorod and Kazan drive solvent-free epoxy specification volumes for pipeline rehabilitation. TR EAEU 042/2017 enforcement at Transneft maintenance facilities is accelerating compliant coating procurement. Togliatti automotive plants specify high-solids polyurethane systems for chassis protection under extended OEM warranty terms.
Northwestern Federal District
Saint Petersburg shipbuilding and Admiralty Shipyards sustain marine coating demand for ice-class vessel construction. The Federal Service for Environmental, Technological and Atomic Supervision inspects coating documentation at port facilities. Ust-Luga oil terminal expansion projects require immersion-grade systems with cathodic protection compatibility.
Siberian Federal District
Norilsk Nickel smelting operations and Krasnoyarsk hydroelectric infrastructure generate heavy industrial maintenance coating procurement. Seasonal access constraints along the Yenisei River multiply applied coating costs through temperature-controlled barge transport. Novatek's LNG train construction at the Cryogas-Vysotsk complex drives cold-cure epoxy specification.
Far Eastern Federal District
Zvezda Shipbuilding Complex in Primorsky Krai anchors marine coating consumption for Arctic tanker and icebreaker construction. Limited local production capacity creates toll manufacturing opportunities for seafood processing and geothermal energy installations. Sakhalin Oblast offshore platform maintenance generates specification demand for splash-zone resistant systems.
Ural Federal District
Chelyabinsk and Yekaterinburg metallurgical facilities require high-temperature resistant coatings for steel mill equipment. The region's machine-building sector sources standard alkyd and acrylic lines for equipment refurbishment. Magnitogorsk Iron and Steel Works maintenance cycles sustain steady procurement of anti-corrosion primers.
Russia Protective Coatings Market Competitive Landscape
The competitive structure tilts toward diversified multinational chemical conglomerates with established technical service networks. Domestic producers occupy mid-tier positions through import substitution incentives and localized GOST certification pathways. Three archetypes dominate: global coating specialists with captive application crews, regional formulators leveraging customs union regulatory familiarity, and integrated oilfield service providers bundling coating into maintenance contracts. Consolidation pressure is elevating through state procurement localization mandates and multi-year performance contract aggregation.
Among global coating specialists, PPG Industries, Inc., Huntsman International LLC, and The Sherwin-Williams Company occupy positions defined by technical service infrastructure and distribution channel control. These companies exemplify the premium-tier archetype through specification authority at Gazprom and Transneft facilities. Domestic players such as Russian Paints Company represent the localization-responsive tier, capturing share through verified supply chain documentation and reformulation agility under tightening VOC thresholds. The competitive dynamic centers on converting transactional material sales into integrated facility maintenance agreements bundling surface preparation, application, and inspection services.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Huntsman International LLC |
| PPG Industries, Inc. |
| RPM International Inc. |
| The Sherwin-Williams Company |
| Russian Paints Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Tikkurila |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers and family-owned mid-caps anchor Russia's protective coatings supply base, concentrating formulation expertise in the Central and Volga Federal Districts while pricing discipline erodes under import substitution mandates and raw material cost volatility.
Pricing Analysis
Margin tightening in mid-tier alkyd and acrylic lines reflects reformulation capex burdens under TR EAEU 042/2017 VOC thresholds. Three-tier pricing structure across premium, standard, and economy levels separates solvent-free epoxy systems for Gazprom specifications from commodity maintenance coatings and generic architectural lines. Price differentiation hinges on GOST certification grade and captive application service bundling. State procurement localization requirements intensify cost-down pressure on imported formulations, while small-scale industrial buyers in the Urals exhibit highest price sensitivity due to fragmented purchasing power.
Supply Chain Analysis
Dual-sourcing requirements for epoxy hardeners and isocyanate curing agents force Russian formulators to qualify both German and Chinese chemical producers, exposing supply chains to customs clearance friction and currency volatility. Raw material dependencies center on bisphenol-A resins, polyamide hardeners, and titanium dioxide pigments. Distribution runs through Transneft and Gazprom maintenance contractor networks for industrial volumes, with specialized marine coatings flowing through Saint Petersburg port logistics hubs. Single-source vulnerability concentrates in Arctic-grade cold-cure additives where qualified suppliers remain limited.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive resin production and application service crews defines competitive positioning in Russia's protective coatings sector, with TR EAEU 042/2017 compliance investments separating viable long-term players from margin-compressed formulators.
For Market Incumbents: Lock in specification authority at Gazprom and Transneft facilities through multi-year performance contracts bundling surface preparation, coating application, and NDT inspection services. Defend against polyaspartic substitution threats by accelerating high-solids epoxy development for tank lining applications. Prioritize backward integration into amine hardener production to reduce import dependency exposure. For New Entrants and Emerging Players: Far East seafood processing plants and Kamchatka geothermal installations represent underserved buyer archetypes with limited local coating production. Toll manufacturing partnerships in Sakhalin Oblast bypass capital-intensive dispersion equipment requirements. Position through TR EAEU 042/2017 pre-certified waterborne formulations targeting state procurement localization criteria. For Investors and Strategic Acquirers: Consolidation of coating contracts under integrated facility maintenance agreements is the leading indicator that asset owner procurement departments are shifting from transactional to performance-based supplier relationships. Mid-tier domestic formulators with verified GOST certification pathways and established Transneft contractor relationships represent prime acquisition targets. Watch for NACE-certified inspector network expansion as signal of quality assurance scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Reduces exposure to German and Chinese epoxy hardener supply volatility under customs friction. |
| Integrated Facility Maintenance Agreements | Captures multi-year revenue streams at Nizhny Novgorod petrochemical complexes and Togliatti automotive plants. |
| TR EAEU 042/2017 Pre-Certification | Accelerates product registration timelines versus import-dependent competitors facing inspection protocol expansion. |
| Arctic Cold-Cure Formulation Development | Secures specification volumes for Yamal-Nenets gas infrastructure operating at minus 50 degrees Celsius. |
| Toll Manufacturing Partnerships in Far East | Addresses white space in Sakhalin and Kamchatka without dedicated humidity-controlled curing facility investment. |
Research Methodology
Document review covered customs union technical regulations, GOST certification databases, and EAEU harmonization protocols, complemented by interviews with plant managers at Nizhny Novgorod petrochemical facilities, procurement leads at Transneft maintenance divisions, distribution channel partners in the Central Federal District, and technical R&D directors at domestic formulation plants. Secondary validation drew from Russian Federal Service for Environmental, Technological and Atomic Supervision inspection reports, customs import data for specialty resins, and SEC filings of multinational coating suppliers. Bottom-up coating consumption estimates by federal district and application were triangulated against top-down petrochemical infrastructure investment forecasts.
Volume and value projections across the analysis window employed a segmented analytical framework modeling product type, application sector, end-user industry concentration, and technology compliance tier against regulatory enforcement intensity. CAGRs were derived from regression analysis of historical procurement patterns at Gazprom and Transneft facilities, overlaid with TR EAEU 042/2017 implementation timelines and Arctic infrastructure construction schedules. Industry-specific inputs included pipeline rehabilitation cycle frequencies, shipbuilding order backlogs at Zvezda and Admiralty yards, and automotive OEM warranty term extensions driving specification upgrades.
Revisions become necessary when TR EAEU technical regulation interpretation diverges between Russian and Kazakh customs authorities, when Arctic logistics cost structures shift due to Northern Sea Route seasonal access changes, or when polyaspartic spray system adoption accelerates beyond current displacement rates for conventional epoxy tank linings. A model refresh is warranted upon material change in state procurement localization requirements or import substitution incentive thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Vacuum Coating Machine Market
Coatings
North America Powder Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Yacht Coatings Market
Coatings
US Protective Coatings Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Hydrophilic Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Global High-Performance Anti-Corrosion Coatings Market
Coatings
Global Laser Cladding Service Market
Coatings
Global Waterborne Coatings Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Anti Fog Coatings Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
North America Superhydrophobic Coating Market