
 Industrial Coatings Market | 2026-2036
Industrial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Coatings Market Intelligence
Demand from end-users requiring high-performance functionalities like advanced corrosion and chemical resistance is reorganizing the competitive landscape. This shift favors suppliers with deep R&D capabilities in specialized formulations. Sherwin-Williams leverages its extensive global distribution network to serve diverse industrial clients. AkzoNobel specializes in sustainable coatings for the marine and protective sectors, while PPG Industries dominates the aerospace and automotive OEM coatings segments with its technology-led portfolio.
Industrial coatings are liquid, liquifiable, or mastic compositions that convert to a solid protective or decorative film after application to a substrate. These formulations typically consist of binders, solvents, pigments, and additives to achieve specific properties like adhesion and durability. Waterborne and powder coating technologies are displacing traditional solventborne systems due to lower environmental impact. Within applications, anti-corrosion and protective coatings for infrastructure and heavy machinery constitute the largest segments, while chemical-resistant coatings represent a high-margin niche.
Regulatory frameworks are a primary influence on product development and market access. The US EPA's regulations on volatile organic compounds (VOCs) and Europe's REACH directive for chemical safety steer innovation toward compliant formulations. These standards, along with China's GB standards, create a preference for powder and waterborne coatings. Future market leadership will hinge on a company's ability to innovate in sustainable chemistries and efficient application processes.
Market Dynamics
The industrial coatings market is defined by a structural shift toward environmentally compliant formulations. This movement is driven by tightening regulations on volatile organic compounds (VOCs) from bodies like the US EPA and Europe's ECHA, forcing a pivot to waterborne and powder-based systems.
Growth Catalysts
- Aerospace Sector Demand:Requirements for lightweight, durable, and thermally resistant coatings for commercial and military aircraft are creating a high-value demand stream for advanced polymer and ceramic-based formulations.
- Infrastructure Modernization:Large-scale infrastructure projects, particularly within China's designated economic zones and India's National Infrastructure Pipeline, require vast quantities of anti-corrosion and protective coatings for steel and concrete structures.
- Regulatory Mandates:The European Union's REACH framework is accelerating the phase-out of hazardous substances in coatings, compelling manufacturers to innovate with safer, sustainable chemistries to maintain market access.
Market Restraints
- Raw Material Volatility:The cost and availability of key inputs like titanium dioxide, epoxy resins, and acrylic polymers are subject to price fluctuations in global petrochemical and mineral markets, impacting formulation costs.
- Regulatory Compliance Costs:Reformulating products to comply with disparate regional standards, such as Europe's REACH and China's GB standards, requires significant R&D investment and lengthy testing cycles.
- Performance Trade-offs:While more environmentally friendly, some waterborne coatings have historically faced challenges in matching the durability and application speed of traditional solventborne systems in demanding industrial environments.
Strategic Opportunities
- Coatings for New Energy:The expansion of renewable energy infrastructure presents an opportunity for specialized coatings for wind turbine blades, solar panel components, and protective linings for battery energy storage systems.
- Bio-based Formulations:Developing coatings from renewable raw materials like plant oils and bio-derived solvents offers a path to reduce carbon footprint and appeal to end-users with corporate sustainability goals.
- Smart and Functional Coatings:Integrating functionalities like self-healing properties, thermal insulation, or anti-fouling capabilities creates high-margin niche products for specialized applications in marine, aerospace, and construction sectors.
Industry Challenges
- Formulation Expertise Scarcity:A shortage of chemists and technicians skilled in developing and applying advanced powder and waterborne coating systems creates a bottleneck for innovation and production scale-up.
- Application Equipment Transition:End-users face significant capital expenditure and operational downtime to retrofit or replace application lines designed for solventborne coatings with equipment compatible with powder or waterborne technologies.
- Performance Validation Cycles:Gaining acceptance for new coating technologies in conservative sectors like infrastructure and oil and gas requires extensive, multi-year field testing to prove long-term durability and corrosion resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Coatings Market |
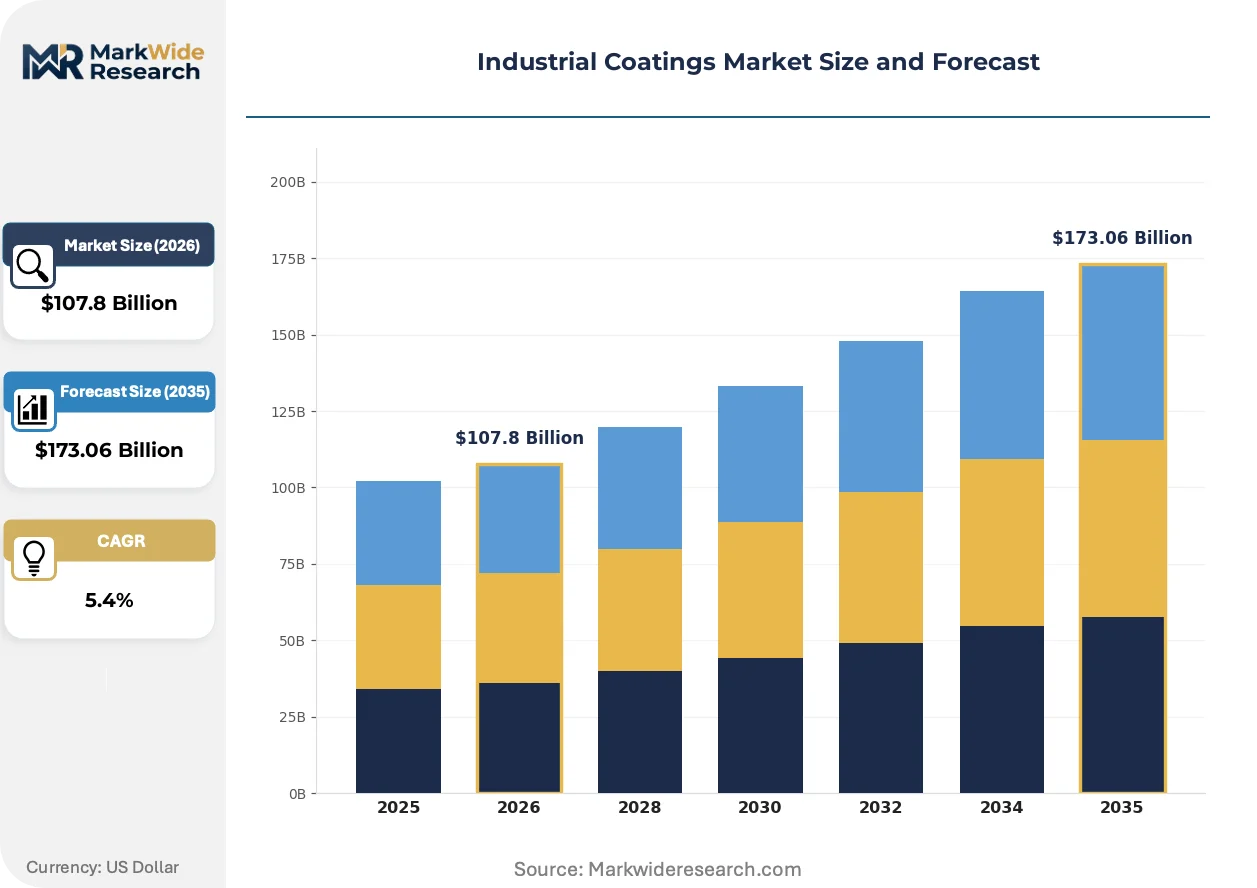
| Market Size in 2026 | $107.8 Billion |
| Market Size in 2035 | $173.06 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd, Silicone, Fluoropolymer Technology: Powder Coating, Waterborne, Solventborne, UV Curable, Electrodeposition, Thermal Spray Application: Protective Coating, Decorative Coating, Anti-Corrosion, Fire-Resistant, Chemical-Resistant, Wear-Resistant End User Industry: Manufacturing Plants, Infrastructure, Marine Vessels, Aerospace, Heavy Machinery, Energy Facilities |
| Companies Covered | Nippon Paint Holdings, Axalta Coating Systems, Sherwin-Williams, Jotun, BASF, PPG Industries, RPM International, Kansai Paint, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Coatings Market Strategic Shifts & Innovations
Innovation in the industrial coatings sector is driven by the need to reconcile demands for higher performance with stricter global environmental standards. This is pushing material science toward developing multifunctional coatings that offer protection while minimizing ecological impact through advanced chemistry and application methods.
Nano-additives such as graphene oxides and ceramic nanoparticles are being incorporated into formulations to enhance mechanical and thermal properties. Adoption is accelerating in the electronics and aerospace sectors, where superior scratch resistance and heat dissipation are critical. This development is miniaturizing the required film thickness for effective protection, enabling the design of lighter and more resource-efficient end-products.
Europe’s Corporate Sustainability Reporting Directive (CSRD) is compelling manufacturers to provide transparent, verifiable data on the lifecycle environmental impact of their products. This forces coating producers to scrutinize their entire value chain, from raw material sourcing to manufacturing emissions and end-of-life disposal. The directive most directly affects suppliers to the EU market, creating a competitive advantage for those who can document a lower carbon footprint.
A shift from transactional product sales to long-term service agreements is altering commercial models. Instead of simply selling paint, suppliers are offering full-service contracts that guarantee corrosion protection for a fixed period, covering application, inspection, and maintenance. This model is gaining traction in the marine and heavy infrastructure segments in North America and Europe, where asset owners prioritize predictable maintenance costs and long-term asset integrity.
Industrial Coatings Market Segmentation
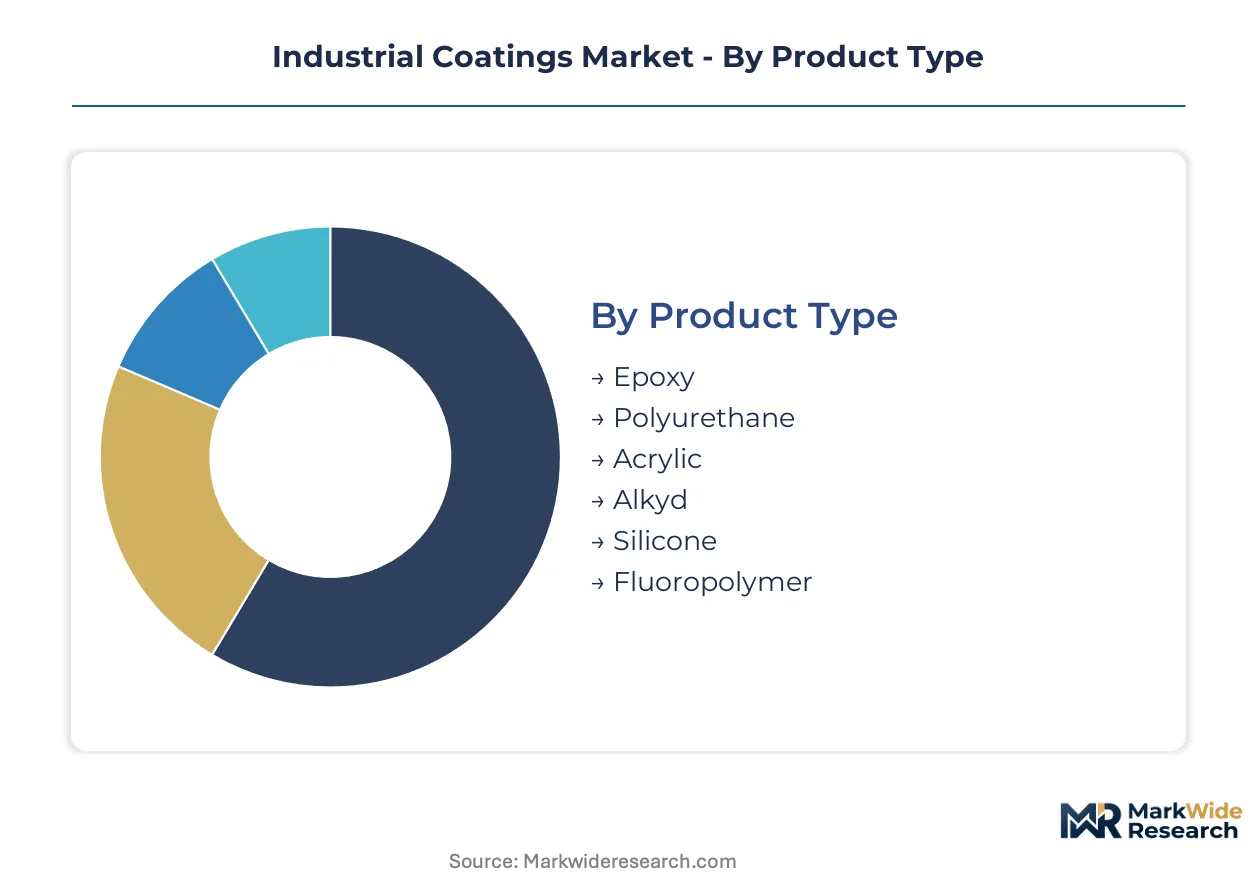
The industrial coatings market segments along several critical dimensions, reflecting the diverse material science requirements and application environments. Understanding these distinctions is crucial for suppliers to tailor product portfolios and for end-users to select optimal solutions for specific operational demands.
Product Type:
The geographic spread of manufacturing capabilities heavily influences the adoption patterns of various product types, with some formulations seeing higher domestic demand in specific industrial hubs.
- Epoxy:These are two-component systems providing excellent adhesion, chemical resistance, and mechanical strength. Infrastructure projects in China and India drive significant consumption for anti-corrosion applications on steel and concrete.
- Polyurethane:Known for their flexibility, abrasion resistance, and UV stability, these coatings offer durable finishes. Automotive OEMs in Germany and Japan increasingly specify these for exterior finishes due to superior performance characteristics.
- Acrylic:These polymers, available in water-based or solvent-based forms, offer good weatherability and color retention for general industrial use.
- Alkyd:Traditional oil-based resins used for general industrial maintenance and decorative purposes, valued for their cost-effectiveness.
- Silicone:Characterized by high-temperature resistance and flexibility, silicone coatings are critical for specialized thermal protection.
- Fluoropolymer:These offer exceptional non-stick properties, chemical inertness, and weather resistance, suitable for extreme environments.
Epoxy holds the largest share; momentum sits with Fluoropolymer.
Technology:
Application complexity and capital investment requirements significantly differentiate coating technologies, influencing adoption rates across various industrial settings.
- Waterborne:This technology utilizes water as the primary solvent, significantly reducing volatile organic compound (VOC) emissions. European manufacturers, driven by the EU's ECHA regulations, prioritize waterborne systems for environmental compliance.
- Powder Coating:Applied as a dry powder and cured with heat, this technology forms a hard, durable, and environmentally friendly finish. Automotive and appliance industries in North America favor powder coating for its efficiency and robust finish.
- Solventborne:These traditional systems use organic solvents, valued for fast drying times and high-performance properties in demanding applications.
- UV Curable:Cured rapidly by ultraviolet light, these systems enable high-speed production lines and offer excellent hardness and chemical resistance.
- Electrodeposition:This process applies an even coating to complex metal parts through an electrical current, ensuring uniform film thickness and corrosion protection.
- Thermal Spray:High-temperature application processes create thick, dense, and wear-resistant layers for specialized surface protection.
Solventborne technologies still command significant volume, but UV Curable systems are expanding most quickly.
Application:
The criticality of the end-use environment dictates the performance requirements and specialized nature of coating applications, ranging from basic protection to extreme resistance.
- Anti-Corrosion:These formulations are designed to prevent the degradation of metal substrates from environmental exposure, crucial for asset longevity. Infrastructure projects in India and Brazil heavily rely on anti-corrosion coatings for steel structures.
- Protective Coating:This broad category encompasses films that shield surfaces from wear, weather, and minor damage, extending the lifespan of industrial assets. Manufacturing plants globally apply protective coatings to equipment and facility surfaces for longevity.
- Decorative Coating:Primarily focused on aesthetic appeal and surface finish, these coatings also provide basic protection against environmental factors.
- Fire-Resistant:Designed to inhibit flame spread or provide thermal insulation during fires, these coatings are vital for safety in industrial and construction settings.
- Chemical-Resistant:Formulated to withstand exposure to aggressive chemicals and solvents, these coatings are essential for process equipment and storage tanks.
- Wear-Resistant:These coatings provide enhanced durability against abrasion, erosion, and impact in high-stress industrial applications.
Anti-Corrosion applications represent a foundational segment, while Chemical-Resistant coatings offer high-margin niche opportunities.
End User Industry:
The volume and value of industrial coatings vary significantly across end-user industries, reflecting differing operational scales, regulatory pressures, and performance demands.
- Infrastructure:This segment covers coatings for bridges, roads, buildings, and public utilities, requiring vast quantities of durable and protective formulations. China's extensive infrastructure development programs drive massive demand for protective and anti-corrosion coatings.
- Aerospace:This industry requires high-performance, lightweight coatings for aircraft bodies, engines, and interiors, prioritizing advanced thermal and erosion resistance. OEMs like Boeing and Airbus drive innovation for advanced coatings in the US and Europe.
- Manufacturing Plants:This sector utilizes coatings for factory floors, equipment, and structural components, focusing on durability and chemical resistance.
- Marine Vessels:Specialized coatings for ships and offshore platforms, including anti-fouling systems, protect against harsh saltwater environments.
- Heavy Machinery:This segment requires durable coatings for construction equipment, agricultural machinery, and mining vehicles that withstand extreme operating conditions.
- Energy Facilities:Protective and insulating coatings are critical for power plants, oil & gas installations, and renewable energy assets, ensuring operational safety and longevity.
Infrastructure provides the largest volume base, with Energy Facilities showing significant growth due to new project investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The expansion of global shipping lanes and interconnected rail networks underwrites the diverse regional demand for industrial coatings. These critical infrastructure assets require advanced protective and anti-corrosion formulations to ensure longevity and operational safety. Regional manufacturing hubs and regulatory frameworks further shape market dynamics.
China
China's ambitious Belt and Road Initiative drives substantial demand for anti-corrosion and protective coatings across new infrastructure. The nation's GB standards for environmental protection steer product innovation towards waterborne and powder coatings. Major industrial zones like the Yangtze River Delta concentrate manufacturing, requiring durable coatings for heavy machinery and structural components.
United States
The United States' aging infrastructure, including bridges and pipelines, necessitates extensive refurbishment with high-performance industrial coatings. US EPA regulations on volatile organic compounds (VOCs) compel manufacturers to develop compliant, low-emission formulations. Industrial clusters in the Gulf Coast region focus on chemical-resistant coatings for petrochemical facilities.
Germany
Germany's advanced manufacturing sector, particularly automotive and industrial machinery, creates consistent demand for high-quality polyurethane and UV-curable coatings. The EU's REACH directive mandates the phase-out of hazardous substances, accelerating the adoption of sustainable chemistries. The Rhine-Ruhr area, a major industrial hub, relies on specialized coatings for its diverse industrial base.
India
India's National Infrastructure Pipeline fuels massive consumption of anti-corrosion coatings for steel and concrete structures. The country's push for "Make in India" initiatives encourages domestic production of industrial coatings, aligning with local standards. Major manufacturing corridors, such as the Delhi-Mumbai Industrial Corridor, require protective coatings for new factories and equipment.
Brazil
Brazil's extensive energy infrastructure, including oil and gas platforms, drives demand for robust anti-corrosion and marine coatings. Environmental regulations from IBAMA influence the selection of eco-friendly coating solutions for industrial projects. The São Paulo state, a key industrial center, utilizes specialized coatings for its automotive and heavy machinery sectors.
Industrial Coatings Market Key Industry Players
Listed leaders compete with private specialists across a spectrum of product types and application technologies. The industrial coatings market exhibits a tiered structure, with global giants offering broad portfolios alongside niche players focused on specialized formulations. Strategic archetypes include diversified chemical conglomerates, dedicated coatings manufacturers, and regional specialists. Dominant competitive moves center on strategic partnerships for technology development and geographic expansion into emerging industrial markets.
On the premium-tier vector, Sherwin-Williams exemplifies extensive global distribution capabilities, serving diverse industrial clients with a wide product range, particularly in North America. AkzoNobel, a Netherlands-based Co., Ltd., occupies a position focused on sustainable coatings for marine and protective sectors, aligning with European environmental standards. PPG Industries, an Inc. in the US, anchors the aerospace and automotive OEM coatings segments with its technology-led portfolio, showcasing advanced material science. These entities represent the industry's drive towards high-performance and environmentally compliant solutions across critical end-user industries.
| Leading Market Players |
|---|
| Nippon Paint Holdings |
| Axalta Coating Systems |
| Sherwin-Williams |
| Jotun |
| BASF |
| PPG Industries |
| RPM International |
| Kansai Paint |
| AkzoNobel |
| Others |
Cost & Logistics Intelligence
Economies of scale in industrial coatings manufacturing shape both supply concentration and competitive price floors. This dynamic influences procurement strategies across diverse end-user industries, from infrastructure to aerospace.
Pricing Analysis
Volume-based tiered pricing structures characterize industrial coatings sales, reflecting customization levels and order size. Price differentiation stems from the specific performance requirements, such as chemical resistance or UV stability, and the level of technical support provided. Pricing pressure stems from raw material volatility and intense competition within the standard-grade segments. Infrastructure projects, requiring vast quantities, exhibit the highest price sensitivity, while aerospace OEMs prioritize performance over cost.
Supply Chain Analysis
Long lead times for specialized industrial coating formulations necessitate strategic inventory management by end-users. Supply for key inputs like titanium dioxide, epoxy resins, and acrylic polymers concentrates in China, the United States, and Germany. Raw material volatility represents a significant structural risk, impacting production costs and product availability. Downstream distribution runs through a mix of direct sales channels to large industrial clients and specialized distributors serving smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial coatings market presents a significant service-attach opportunity, with long-term maintenance contracts expanding faster than initial product sales.
For Market Incumbents:
Consolidate market share by acquiring niche specialists in advanced waterborne and powder coating technologies. This strategy counters margin pressure from regulatory compliance costs and raw material volatility. Invest heavily in R&D for sustainable chemistries to maintain a competitive edge. Strengthen global distribution networks to serve diverse industrial clients effectively.
For New Entrants and Emerging Players:
Anchor in specialized high-margin niches like bio-based or smart coatings for renewable energy infrastructure. Target underpenetrated segments adopting new technologies, such as smaller regional manufacturers seeking eco-friendly solutions. A go-to-market angle focusing on tailored application support and performance guarantees can build early traction. Focus on developing strong intellectual property in functional additives.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors agile mid-cap specialists with proven sustainable chemistry platforms. Long-term viability hinges on companies demonstrating strong R&D pipelines for compliant and high-performance formulations. Acquisition targets should possess strong intellectual property in functional coatings or efficient application technologies. A signal to watch is the accelerated adoption of UV-curable systems in new industrial applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling production for waterborne systems supports regulatory compliance in Europe and the US. |
| Green Manufacturing Transition | Adopting bio-based formulations reduces carbon footprint, appealing to sustainability-focused end-users. |
| Long-term Supply Agreement | Securing key raw materials like epoxy resins mitigates price volatility and ensures production stability. |
| Joint Venture | Partnering for specialized application equipment accelerates adoption of powder coating technologies. |
| Product Launch | Introducing advanced anti-corrosion coatings addresses demand from China's infrastructure projects. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade publications, and corporate reports. Primary interviews engaged R&D directors, procurement leads, plant managers, and distribution channel partners across key regions. This approach ensured a robust understanding of market dynamics through both top-down and bottom-up triangulation of data points.
Market segmentation dimensions modeled include product type, technology, application, end-user industry, and regional adoption patterns. Compound annual growth rates were derived from historical trends, future projections of industrial output, and regulatory impact assessments across the analysis window. Key forecast inputs included global infrastructure spending and timelines for environmental compliance mandates.
Material uncertainties — raw material price volatility and geopolitical shifts — sit outside the modeled envelope, influencing future market trajectories. Forecasts reflect current assumptions about regulatory enforcement and technological adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Electrocoat Market
Coatings
Polyurethane Powder Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Self-Healing Microcapsule Systems for Protective Coatings Market
Coatings
Epoxy Coating Market
Coatings
Shipping Container Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Paper Coating Binders Market
Coatings
Electrically Conductive Coating Market
Coatings
High Temperature Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Silicate Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Biopolymer Coatings Market