
 Thailand Architectural Coatings Market | 2026-2036
Thailand Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Architectural Coatings Market Analytics
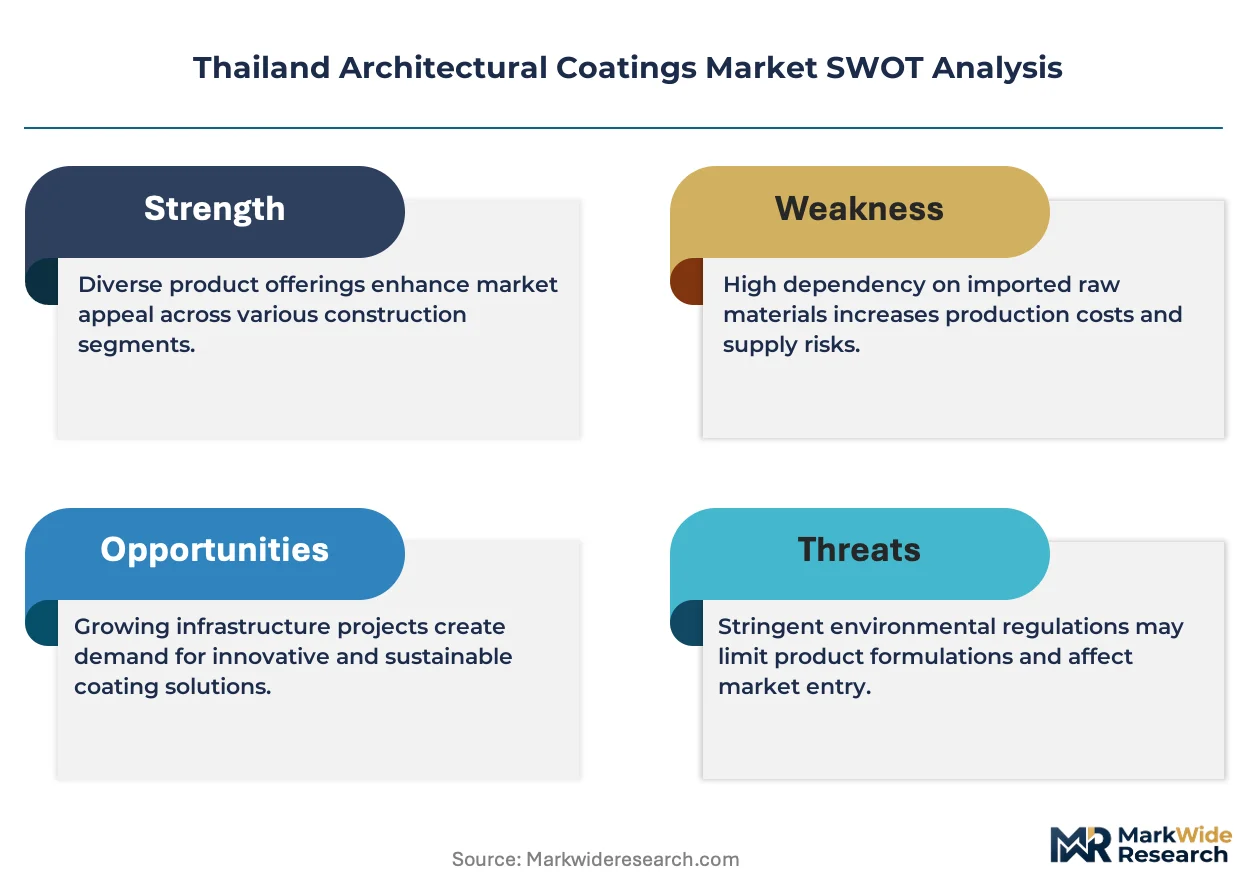
Multi-source resin procurement is recalibrating how Thai formulators manage input costs and quality consistency. TOA Paint Public Company Limited leverages its domestic manufacturing footprint to anchor supply security across the kingdom's northern and central provinces. AkzoNobel N.V. competes through technology leadership in low-VOC decorative platforms suited to Thailand's tropical humidity conditions. Jotun specializes in high-performance exterior coatings for coastal commercial developments exposed to monsoon salt corrosion.
Architectural coatings encompass liquid-applied protective and decorative films formulated with binders, pigments, solvents or water carriers, and functional additives, typically applied at dry-film thicknesses of 25–100 microns to shield substrates from UV degradation, moisture ingress, and biological attack. Water-based acrylic emulsions dominate the residential repaint segment due to faster dry times and compliance with tightening indoor air quality protocols. Solvent-based alkyds and urethanes retain structural share in industrial infrastructure applications where chemical resistance and adhesion to metal substrates remain non-negotiable performance parameters.
Thailand's Department of Industrial Works enforces Hazardous Substance Act amendments that mandate VOC content thresholds in decorative paints, compelling manufacturers toward water-based technology platforms. The Thai Industrial Standards Institute (TISI) certification requirements for lead-free formulations and antimicrobial performance claims shape product development pipelines and import clearance protocols. Stakeholders must monitor pending amendments to building energy codes that could mandate solar-reflective exterior coatings for commercial structures, a shift that would reorder technology investment priorities across domestic and multinational suppliers operating in the kingdom.
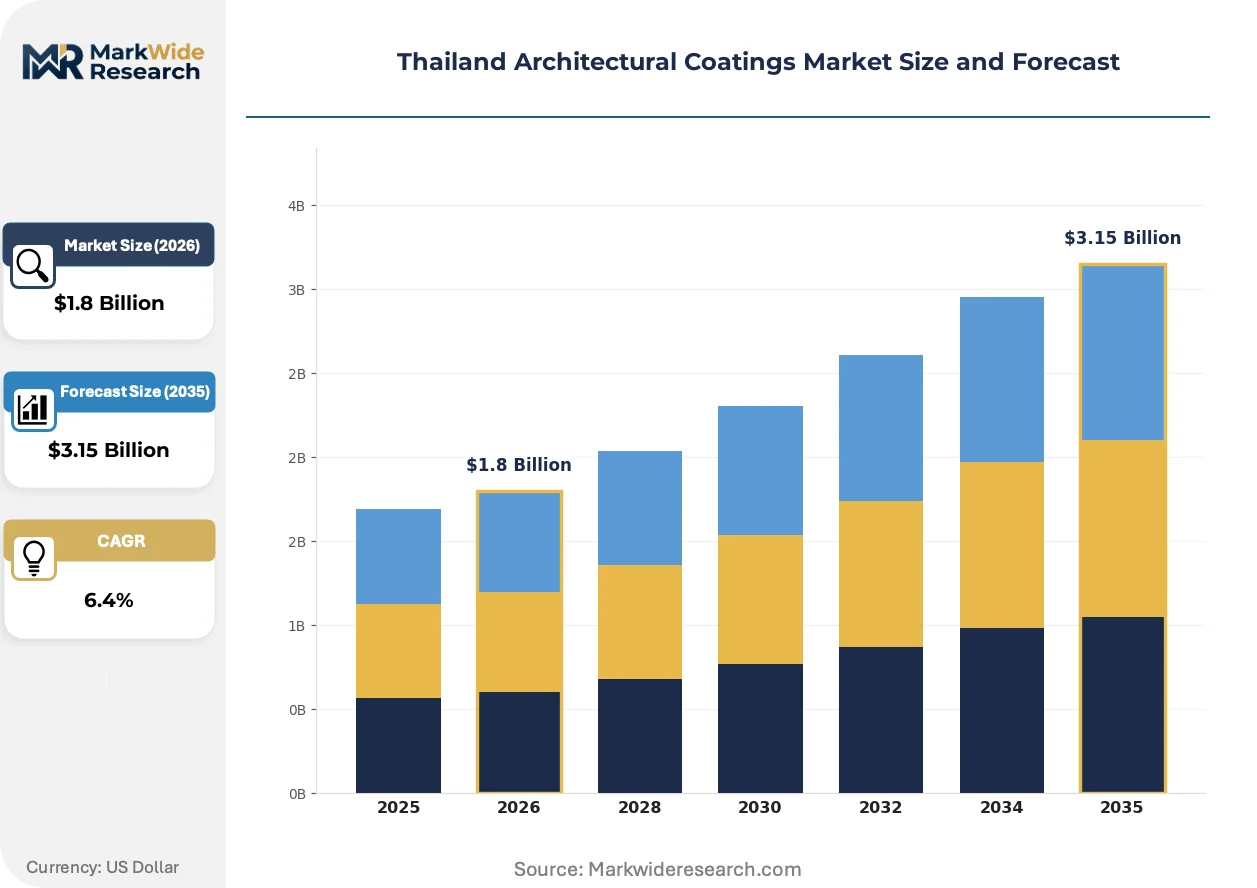
Market Dynamics
Thailand's Hazardous Substance Act amendments are compressing formulation timelines as manufacturers accelerate water-based system transitions to meet tightening VOC thresholds ahead of enforcement deadlines.
Growth Catalysts
- Regulatory Compliance Mandates:The Department of Industrial Works enforces progressively stricter VOC content ceilings in decorative paints, compelling nationwide reformulation investments and creating first-mover advantages for compliant suppliers.
- Urban Residential Clustering:Bangkok and surrounding provinces concentrate high-rise residential development, concentrating premium decorative coatings demand within the Greater Bangkok metropolitan corridor.
- Monsoon-Driven Performance Specifications:Coastal commercial developments exposed to salt-laden humidity cycles require specialized exterior protection systems, expanding the addressable market for high-durability formulations.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic emulsion binders and solvent precursors track regional naphtha and propylene pricing swings, compressing margin predictability for domestic formulators lacking long-term supply contracts.
- Import Dependency for Specialty Additives:Antimicrobial agents, rheology modifiers, and advanced pigments concentrate among Northeast Asian chemical suppliers, exposing Thai manufacturers to currency fluctuation and shipping disruption risks.
- Alkyd Performance Floor in Metal Substrates:Water-based acrylics face adhesion and chemical resistance limitations on industrial metal surfaces where solvent-based urethanes retain non-substitutable protective performance.
Strategic Opportunities
- Secondary City Penetration:Chiang Mai, Phuket, and Khon Kaen exhibit underdeveloped distribution infrastructure for premium decorative finishes, offering whitespace for localized stocking and technical service deployment.
- Solar-Reflective Coating Pre-Positioning:Pending amendments to Thailand's building energy codes could mandate cool roof specifications for commercial structures, enabling early technology certification investments to capture specification influence.
- E-Commerce Direct-to-Contractor Channels:Digital procurement platforms are bypassing traditional distributor layers for standard interior emulsions, rewarding logistics investments and SKU rationalization for online fulfillment.
Industry Challenges
- Formulation Chemist Scarcity:Thai universities produce limited graduates with hybrid polymer chemistry and tropical climatology expertise, constraining R&D throughput for humidity-optimized water-based systems.
- TISI Certification Timeline Compression:Lead-free and antimicrobial performance claims require extended Thai Industrial Standards Institute testing protocols, delaying product launches and freezing working capital in pre-approval inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Architectural Coatings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paints, Primers, Varnishes, Sealants Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Builders, Architects, Homeowners Technology: Water-Based, Solvent-Based, Powder Coatings, UV-Cured |
| Companies Covered | TOA Paint Public Company Limited, Guangdong Maydos Building Materials Limited Company, AkzoNobel N.V., Dai Nippon Toryo Co., Ltd., SKK(S) Pte Ltd., Jotun, Kansai Paint Co., Ltd., Hato Paint (J K R) Co., Ltd., Nippon Paint Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Architectural Coatings Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing simultaneous recalibration as regulatory pressure and procurement digitization converge on Thai coatings suppliers.
Nano-engineered photocatalytic additives are integrating self-cleaning functionality into exterior emulsion systems, enabling building facades to degrade organic pollutants under UV exposure. High-rise residential developers in Bangkok's Sukhumvit and Silom corridors specify these finishes to reduce maintenance cycle frequency. The technology is integrating specification influence into premium project bids, compressing competitive differentiation around functional performance rather than color range alone.
The Thai Industrial Standards Institute is expanding mandatory testing protocols for antimicrobial performance claims in interior coatings, requiring documented efficacy against specific fungal and bacterial strains. Manufacturers must revalidate existing product portfolios under revised TISI methodologies, extending approval timelines and freezing formulation flexibility. Interior residential repaint segments face the steepest compliance burden as health-conscious consumers drive verified antimicrobial demand.
Contractor procurement patterns are fragmenting across project-scale boundaries, with large Bangkok-based developers consolidating volume through direct manufacturer negotiations while smaller provincial contractors retain distributor relationships. Digital quotation platforms and mobile application tools are displacing traditional branch-based ordering for standard interior emulsions. This bifurcation concentrates price transparency pressure in metropolitan markets while preserving margin layers in upcountry regions with weaker logistics infrastructure.
Thailand Architectural Coatings Market Segmentation
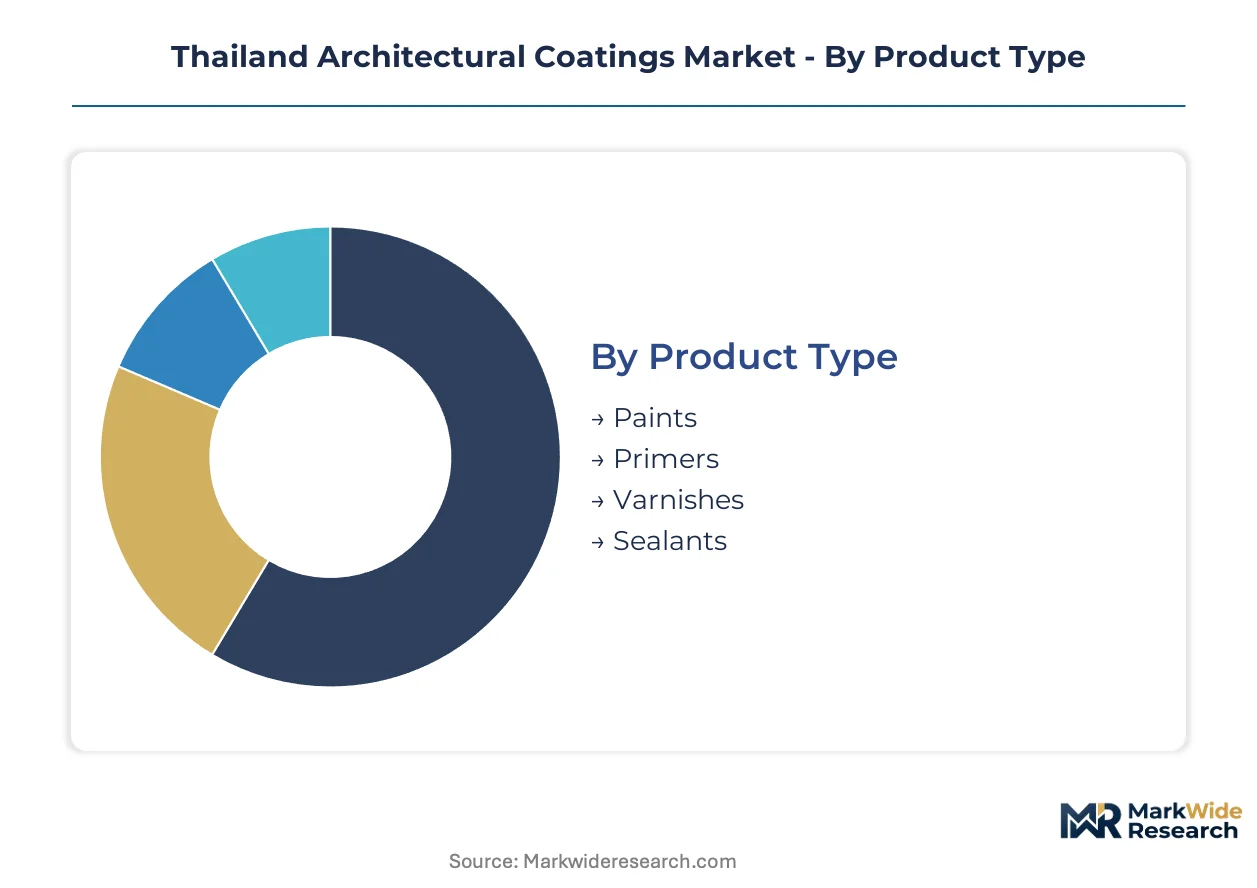
Architectural coatings in Thailand fragment across four intersecting dimensions that determine formulation priorities, channel strategy, and margin capture. Each segmentation axis reveals distinct competitive dynamics between multinational suppliers with technology leadership and domestic formulators with distribution density.
Product Type:
Paints dominate volume throughput while premium finishes command specification influence in Bangkok's high-rise residential towers.
- Paints:Acrylic emulsions and alkyd formulations constitute the volume core, with water-based systems capturing residential repaint demand in Greater Bangkok's condominium clusters. The Department of Industrial Works' VOC enforcement is accelerating solvent-to-water transitions ahead of compliance deadlines.
- Primers:Surface preparation films engineered for tropical humidity adhesion on concrete and masonry substrates. Demand concentrates in commercial developments across Sukhumvit and Silom corridors where specification-grade performance commands premium positioning.
- Varnishes:Protective clear coats for wood and decorative metal surfaces, predominantly solvent-based urethanes retaining share in heritage restoration and premium residential applications.
- Sealants:Elastomeric joint fillers and waterproofing membranes specified for monsoon-exposed building envelopes, with silicone and polyurethane chemistries serving coastal commercial projects in Phuket and Pattaya.
Today's leader: Paints. Tomorrow's challenger: Sealants.
Application:
Geographic clustering in the Greater Bangkok metropolitan corridor concentrates demand across all application segments, with coastal exposure creating specialized performance requirements.
- Residential:Interior emulsions and exterior masonry finishes for high-rise condominiums and landed housing estates. Water-based acrylics dominate due to faster dry times and indoor air quality compliance in Bangkok's dense urban core.
- Commercial:Durable exterior coatings for office towers, retail complexes, and hospitality structures requiring monsoon resistance and solar-reflective functionality. Specifications increasingly mandate photocatalytic self-cleaning additives in premium developments.
- Industrial:Chemical-resistant solvent-based urethanes for manufacturing facilities and warehouse metal substrates where water-based systems face adhesion limitations.
- Infrastructure:Heavy-duty protective coatings for bridges, ports, and utilities exposed to salt-laden humidity cycles. Thai Industrial Standards Institute certification requirements extend approval timelines for antimicrobial and lead-free claims in public sector procurement.
Commercial applications are gaining share fastest as Bangkok's skyline expansion outpaces residential construction velocity.
End User:
Procurement authority is bifurcating between consolidated developer-direct negotiations and fragmented contractor-distributor relationships.
- Contractors:Volume purchasers of standard interior emulsions through digital procurement platforms, with large Bangkok-based operators consolidating manufacturer-direct agreements while provincial contractors retain traditional distributor channels.
- Builders:Project-scale specifiers balancing cost efficiency with TISI compliance requirements, particularly for antimicrobial performance claims in health-conscious residential developments.
- Architects:Design-phase influencers driving premium finish specifications through performance-based selection criteria including solar reflectance and self-cleaning functionality.
- Homeowners:Fragmented retail purchasers of repaint materials, increasingly accessing product information through mobile applications while relying on contractor execution for application quality.
Builders currently anchor volume commitments. Architects are ascending as specification gatekeepers for premium technology adoption.
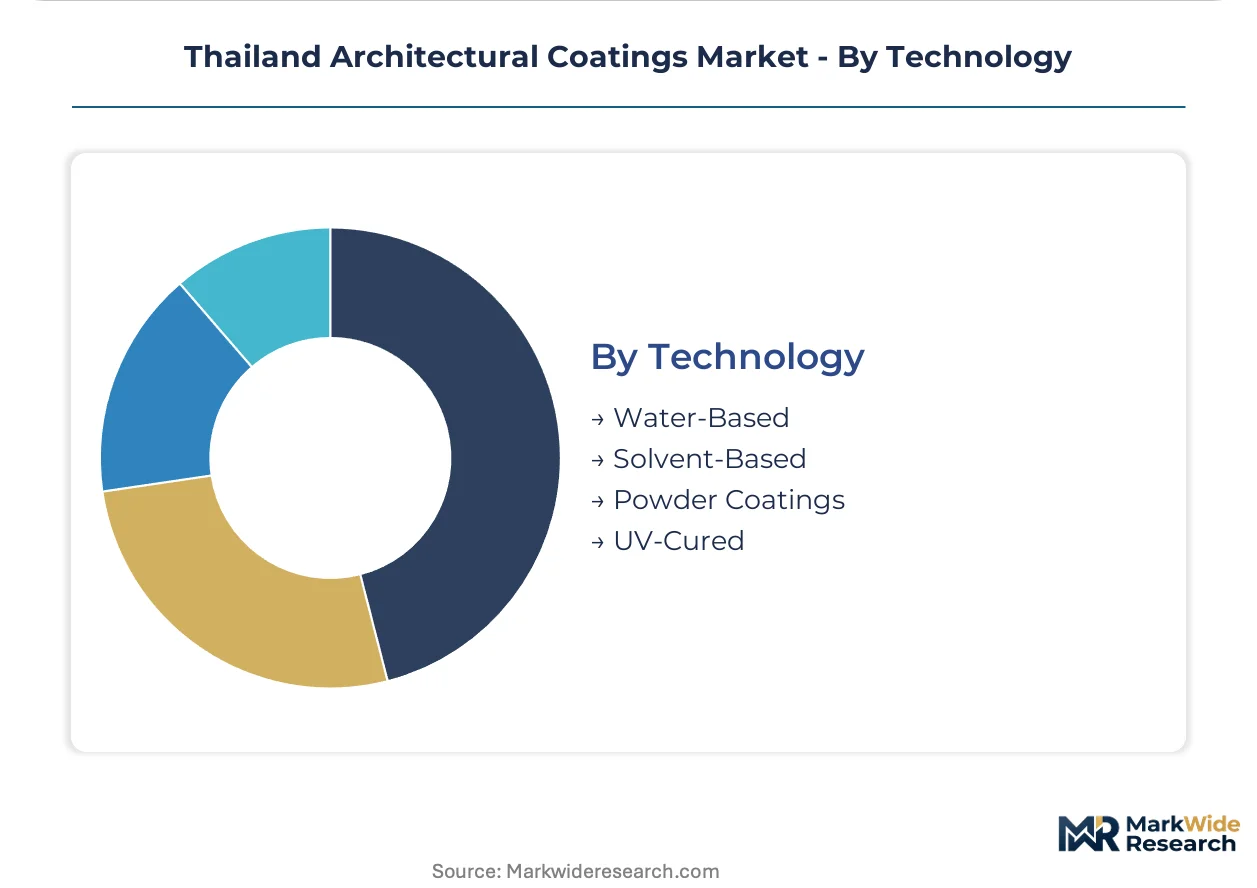
Technology:
Regulatory pressure from Hazardous Substance Act amendments is compressing formulation timelines and reordering competitive positioning across technology platforms.
- Water-Based:Acrylic emulsion systems capturing residential and commercial interior demand through compliance with tightening VOC thresholds and faster dry times suited to tropical humidity conditions. TOA Paint and domestic formulators leverage manufacturing proximity for supply security.
- Solvent-Based:Alkyd and urethane formulations retaining structural share in industrial metal applications and exterior wood protection where chemical resistance and adhesion performance remain non-negotiable.
- Powder Coatings:Zero-VOC dry film technologies specified for metal architectural elements in commercial and infrastructure applications, with limited penetration in field-applied construction due to application equipment requirements.
- UV-Cured:Rapid-cure liquid systems for factory-applied wood and metal finishing, with minimal on-site construction presence due to capital equipment constraints and substrate size limitations.
Water-Based technology holds dominant share. Powder Coatings present the steepest expansion trajectory as industrial manufacturing scales and environmental enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between Thailand and neighboring jurisdictions are redirecting production investment toward markets with lighter VOC enforcement timelines. Manufacturers evaluate reformulation capacity, feedstock access, and distribution density when positioning regional supply networks.
Bangkok Metropolitan Region
High-rise residential towers and commercial complexes in Sukhumvit and Silom corridors concentrate premium decorative coatings demand. The Department of Industrial Works enforces Hazardous Substance Act amendments that compress VOC compliance deadlines for suppliers serving this cluster. Central Bangkok and surrounding provinces anchor specification-grade project volume for water-based acrylic systems.
Eastern Economic Corridor
Industrial estate expansion in Chonburi and Rayong provinces drives protective coatings demand for manufacturing facilities and warehouse infrastructure. Thailand's Board of Investment incentives attract automotive and electronics manufacturing that requires chemical-resistant metal coatings. Coastal exposure in Laem Chabang port zone necessitates salt-corrosion-resistant exterior systems for commercial structures.
Northern Region
Chiang Mai's tourism-driven hospitality construction creates demand for decorative finishes in boutique hotels and residential developments. Thai Industrial Standards Institute certification requirements extend product approval timelines for antimicrobial claims in health-conscious hospitality specifications. Local distribution infrastructure remains underdeveloped relative to Bangkok, preserving margin layers for established suppliers.
Southern Coastal Provinces
Phuket and Pattaya resort developments require high-durability exterior coatings resistant to monsoon humidity cycles and salt-laden air. The Tourism Authority of Thailand's infrastructure investment programs stimulate commercial construction in these markets. Marine exposure conditions favor specialized sealant and waterproofing specifications for building envelope protection.
Thailand Architectural Coatings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital procurement channels and secondary city penetration. The vendor base stratifies across three tiers: domestic formulators with manufacturing proximity, multinational technology leaders with low-VOC platforms, and regional specialists with coastal protection expertise. Consolidation pressure concentrates among mid-scale distributors as direct-to-contractor platforms displace traditional branch networks. Capacity expansion and TISI certification pre-positioning represent dominant competitive moves.
Among Thailand-based producers, TOA Paint Public Company Limited anchors domestic manufacturing coverage across northern and central provinces. AkzoNobel N.V. and Jotun occupy positions exemplifying technology leadership in humidity-optimized and coastal-protection formulations respectively. These three entities represent the archetype spectrum from supply-security-focused domestic players to performance-specialized multinationals competing on specification influence rather than volume throughput.
| Leading Market Players |
|---|
| TOA Paint Public Company Limited |
| Guangdong Maydos Building Materials Limited Company |
| AkzoNobel N.V. |
| Dai Nippon Toryo Co., Ltd. |
| SKK(S) Pte Ltd. |
| Jotun |
| Kansai Paint Co., Ltd. |
| Hato Paint (J K R) Co., Ltd. |
| Nippon Paint Holdings Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Water-based premium certification tiers diverge sharply from solvent-based commodity grades, compressing margin structures at the mid-market level while rewarding TISI-compliant suppliers with specification-grade pricing power. This bifurcation channels procurement decisions through distinct supply chain configurations: Bangkok-based developers negotiate direct manufacturer contracts for certified volumes, while provincial contractors absorb distributor markups for standard alkyd formulations.
Pricing Analysis
Distributor margin layers absorb 15-25 point markups in upcountry channels serving Chiang Mai and Khon Kaen contractors, whereas direct-to-developer negotiations in Greater Bangkok strip these intermediaries for volume commitments. Three-tier pricing structure across premium, standard, and economy levels tracks TISI certification status and antimicrobial performance claims. Cost compression in the economy tier intensifies as naphtha-linked solvent feedstock volatility squeezes domestic formulators lacking long-term propylene contracts. Small provincial contractors exhibit acute price sensitivity, while Bangkok high-rise developers prioritize specification compliance over unit cost.
Supply Chain Analysis
Direct-to-developer channels handle hyperscale demand from Bangkok's condominium clusters, with TOA Paint leveraging northern and central manufacturing proximity to compress delivery lead times. Acrylic emulsion binders draw from Northeast Asian petrochemical complexes in South Korea, Japan, and Singapore, while specialty rheology modifiers and antimicrobial additives concentrate among Chinese and Taiwanese chemical suppliers. Single-source vulnerability for photocatalytic nano-additives exposes formulators to shipping disruption risks through the Strait of Malacca. Distribution runs through layered networks: manufacturer-direct for metropolitan developers, regional distributors for provincial contractors, and emerging e-commerce platforms for standard interior emulsions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion hinges on water-based technology transitions that capture premium positioning ahead of Hazardous Substance Act enforcement deadlines, while feedstock volatility creates downstream consolidation incentives for suppliers with captive resin capacity.
For Market Incumbents: Deepen backward integration into acrylic emulsion production to anchor margin stability against naphtha price swings, while accelerating TISI certification pipelines for antimicrobial claims to freeze out reformulation-lagged competitors. TOA Paint's northern manufacturing footprint exemplifies supply-security positioning that multinationals must replicate through regional blending capacity. Channel control through direct contractor platforms displaces vulnerable distributor relationships in Greater Bangkok. For New Entrants and Emerging Players: The premium-economy price-point gap in secondary cities creates whitespace for mid-tier positioning with localized technical service. Phuket and Pattaya coastal developments offer penetrable segments where salt-corrosion specialization commands specification influence unavailable to commodity suppliers. A digital-first go-to-market angle bypasses entrenched distributor layers for standard interior emulsions, rewarding logistics investment and SKU rationalization for contractor procurement platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale distributors face margin compression from direct-to-contractor digitization and manufacturer bypass strategies. Five-to-ten year viability favors suppliers with water-based R&D throughput and TISI certification pre-positioning. Acquisition target archetype: domestic formulators with underutilized northern manufacturing assets and stranded distributor relationships in secondary cities. The signal to watch is pending building energy code amendments mandating solar-reflective specifications, which would reorder technology investment priorities across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Technology Transition | Hazardous Substance Act compliance creates first-mover advantage for reformulation-complete suppliers ahead of enforcement deadlines. |
| TISI Certification Pre-Positioning | Antimicrobial and lead-free claim validation extends product approval timelines, freezing working capital and raising competitive barriers. |
| Secondary City Distribution Buildout | Localized stocking in Chiang Mai, Phuket, and Khon Kaen captures margin layers preserved by underdeveloped logistics infrastructure. |
| Direct-to-Contractor Platform Investment | Digital procurement channels displace traditional distributor markups for standard interior emulsions in metropolitan markets. |
| Solar-Reflective Coating Development | Pending building energy code amendments could mandate cool roof specifications, enabling specification influence capture in commercial segments. |
Research Methodology
Direct dialogue with plant managers at domestic formulators, procurement leads at Bangkok-based developers, distribution channel partners in secondary cities, and technical R&D directors at multinational suppliers grounded qualitative assessments in operational reality. Secondary validation drew from Thai Industrial Standards Institute certification records, Department of Industrial Works enforcement announcements, customs and trade data on resin imports, and SEC filings from listed coatings manufacturers. Bottom-up volume estimates triangulated against top-down market sizing derived from construction activity indices and coatings consumption intensity metrics.
Bottom-up modeling aggregated segment-level demand across residential, commercial, industrial, and infrastructure applications, while top-down approaches cross-referenced GDP-construction multipliers and regional coatings penetration rates. Segmentation dimensions included product type, application, end-user procurement authority, and technology platform. CAGRs were derived from regression analysis of historical consumption patterns against regulatory enforcement timelines and feedstock price trajectories. Key inputs encompassed monsoon-driven re-coating cycle frequencies and high-rise residential completion rates in Greater Bangkok.
Caveats apply where petrochemical feedstock volatility, currency fluctuation against Northeast Asian suppliers, or accelerated VOC enforcement timelines could materially shift the outlook. Forecasts reflect assumptions regarding regulatory implementation pacing and water-based technology substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Russia Protective Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
Carbon Fiber Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Europe Waterborne Polyurethane Coatings Market
Coatings
Global Performance Coating Market
Coatings
Epoxy Coating Market
Coatings
Saudi Arabia Floor Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Cladding Coatings Market
Coatings
United States Industrial Wood Coatings Market
Coatings
Fillers and Coating Market
Coatings
Coating Pre-Treatment Market
Coatings
Color-Shifting Coating Market
Coatings
Waterborne Automobile Coating Market
Coatings
Polyvinylidene Fluoride (PVDF) Coatings Market