
 Polyol Esters Market | 2026-2036
Polyol Esters Market Size, Share, and Industry Trends Forecast 2026-2036
Polyol Esters Market Analysis
Aviation lubricant formulators is bifurcating demand away from general industrial buyers as turbine OEMs specify higher thermal stability base stocks. BASF leverages its integrated petrochemical network to secure adipic acid and polyol feedstock advantages across European production sites. Dow anchors its position through proprietary catalytic esterification technology that reduces color bodies in refrigeration lubricant grades. Evonik Industries differentiates via specialized neopentyl polyol esters designed for extreme-pressure aviation turbine oil applications.
Polyol esters are synthetic compounds formed by the esterification of polyhydric alcohols such as neopentyl glycol, trimethylolpropane, or pentaerythritol with monocarboxylic acids, yielding molecular structures with exceptional thermal oxidative stability and low pour points for high-performance lubrication. These esters function primarily as base stocks and functional additives where mineral oils fail under extreme temperature or biodegradability requirements. Vegetable oil-based polyol esters command premium positioning in environmentally sensitive applications such as marine and hydraulic systems, while synthetic grades dominate aviation and automotive sectors where thermal stability thresholds exceed 200°C. The lubricants end-use industry concentrates margin pools among aerospace-qualified producers, whereas cosmetics applications in emulsifier form represent faster volume expansion but thinner returns.
EPA regulations under the Significant New Alternatives Policy constrain fluorinated lubricant options, indirectly channeling demand toward compliant polyol ester formulations in industrial refrigeration. REACH registration requirements and EU Green Deal decarbonization targets impose biodegradability and carbon footprint disclosure obligations on ester producers selling into European lubricant and cosmetic value chains. ASTM D02 lubricant standards and OEM specifications from engine manufacturers further tighten the qualification barrier for new market entrants. Stakeholders must monitor evolving aviation sustainability certification schemes and feedstock traceability mandates to anticipate which polyol ester chemistries will retain formulation approval across regulated end-use sectors.
Market Dynamics
Turbine engine OEM thermal stability specifications are compressing qualification timelines and concentrating demand among ester producers with aviation-certified manufacturing infrastructure.
Growth Catalysts
- REACH biodegradability mandates:EU Green Deal decarbonization targets channel lubricant formulators away from mineral oil toward compliant synthetic ester base stocks in hydraulic and marine applications.
- Aviation turbine thermal thresholds:Engine manufacturers now specify base stocks rated above 200°C, disqualifying conventional mineral oils and pulling specialized polyol esters into narrow-body and wide-body fleet lubricant specifications.
- Adipic acid supply clustering:Integrated petrochemical corridors in Germany and Belgium secure backward feedstock control for neopentyl glycol production, lowering input cost volatility for regional ester manufacturers.
Market Restraints
- Neopentyl glycol feedstock concentration:Three European chemical producers control over 70% of specialized polyol supply, creating bottleneck risk for aviation-grade ester manufacturers without long-term offtake agreements.
- ASTM D02 certification timelines:New ester chemistries require 18-36 months of OEM turbine testing before formulation approval, freezing out smaller producers lacking capital to sustain pre-revenue qualification periods.
- Vegetable oil price volatility:Rapeseed and palm kernel oil feedstocks for biodegradable grades swing with agricultural commodity cycles, compressing margins on environmentally positioned product lines.
Strategic Opportunities
- Indian aerospace MRO expansion:Maintenance, repair, and overhaul facilities in Bengaluru and Hyderabad are qualifying imported polyol ester stocks for narrow-body engine servicing, creating demand pull outside traditional Western aviation hubs.
- Refrigeration lubricant convergence:EPA SNAP restrictions on hydrofluorocarbon lubricants intersect with natural refrigerant adoption, opening formulation slots for compatible polyol esters in industrial cold chain equipment.
- Cosmetic emulsifier channel innovation:Direct-to-manufacturer digital procurement platforms are compressing distributor layers for specialty ester grades serving skin-care formulators in South Korea and Japan.
Industry Challenges
- Aviation chemist talent scarcity:Formulation expertise combining high-temperature tribology with regulatory compliance is concentrating at a handful of European and US producers, constraining expansion for mid-cap competitors.
- Feedstock traceability system integration:EU CSRD supply chain disclosure rules require ester producers to deploy blockchain or equivalent tracking infrastructure for bio-based raw materials, demanding capital outlays without immediate revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyol Esters Market |
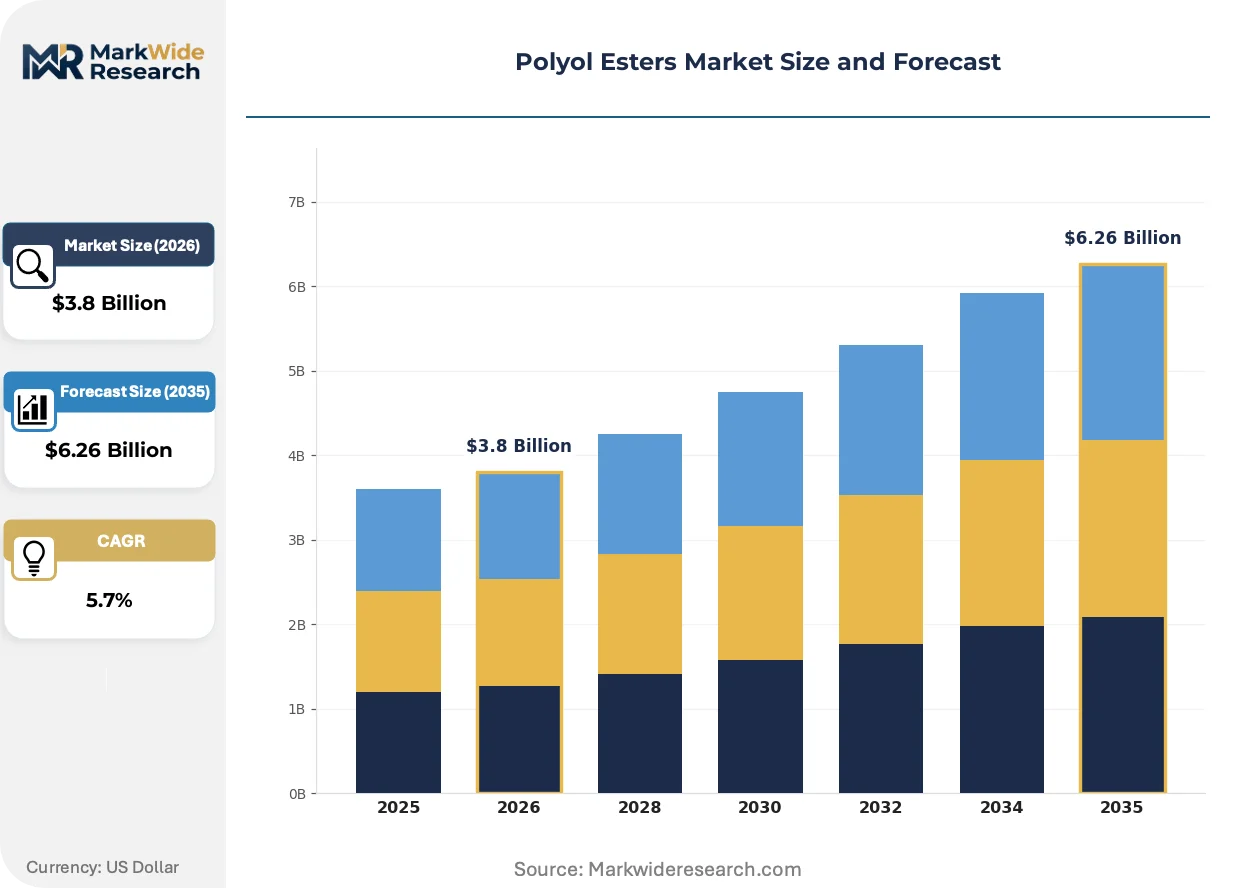
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Oil-Based, Synthetic, Glycerol Esters, Sorbitan Esters End Use Industry: Cosmetics, Food & Beverage, Pharmaceuticals, Lubricants Application: Emulsifiers, Foam Stabilizers, Skin Conditioning Agents, Flavoring Agents Form: Liquid, Powder, Gel, Granule |
| Companies Covered | Dow, Huntsman, BASF, Evonik Industries, Lanxess, Ultrachem, Chemtura Corporation, Cargill, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyol Esters Market Emerging Trajectories
Formulation science is pivoting toward molecular architectures that satisfy simultaneous thermal, biodegradability, and traceability requirements without trade-off compromises.
Neopentyl polyol ester blends with tailored viscosity indices are miniaturizing the performance gap between synthetic aviation grades and general industrial lubricants. Railway and wind turbine gearbox maintainers in Northern Europe are adopting these intermediate-tier formulations to reduce SKU complexity. The technology is miniaturizing the distinction between aerospace-certified and industrial-grade supply chains, forcing producers to unify quality systems across previously separate product lines.
ECHA REACH authorization procedures are tightening scrutiny on persistent, bioaccumulative, and toxic substances in lubricant additives. This regulatory pressure is displacing certain sulfur-phosphorus extreme-pressure packages that previously paired with polyol ester base stocks. Aviation formulators in Germany and France are accelerating testing of ashless additive alternatives to secure continued market access under evolving substance restriction schedules.
Long-term offtake contracting is displacing spot purchasing for specialized ester base stocks among major aviation lubricant blenders. Procurement teams at turbine service subsidiaries now negotiate 3-5 year supply agreements with fixed volume tiers and indexed pricing, transferring inventory risk upstream to ester producers. This pattern is most pronounced in North American and Western European aviation maintenance networks, where OEM warranty requirements demand batch-to-batch consistency documentation.
Polyol Esters Market Segmentation
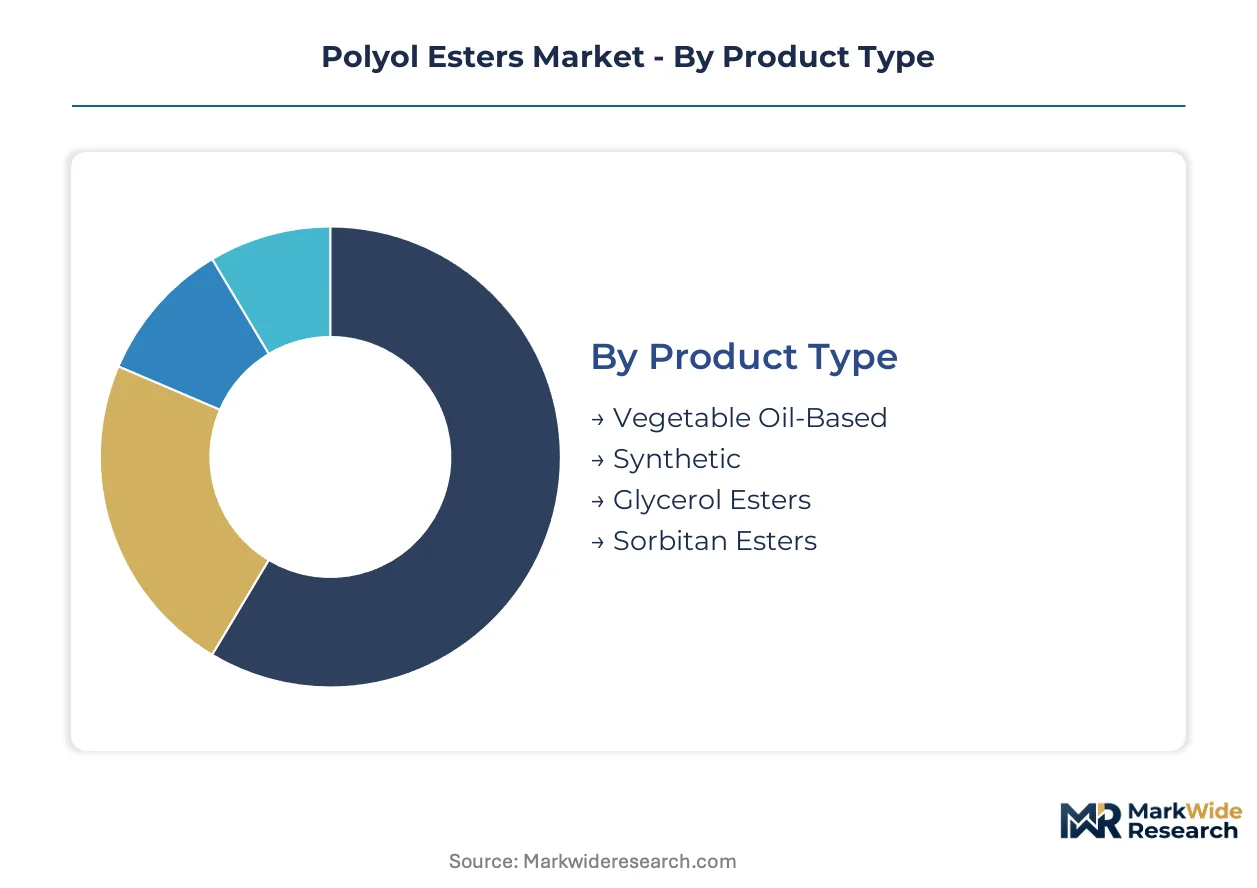
Polyol ester producers face divergent substitution threats across product categories. Synthetic aviation grades defend against mineral oil displacement through thermal performance, while vegetable oil variants compete with other biodegradable chemistries in cosmetics and marine applications.
Product Type:
Vegetable oil-based grades confront the most acute substitution pressure from synthetic alternatives as formulators weigh biodegradability premiums against performance reliability.
- Synthetic:Neopentyl glycol and trimethylolpropane esters deliver thermal oxidative stability exceeding 200°C. Aviation turbine OEMs in Germany and the United States specify these chemistries for narrow-body and wide-body engine lubricants, locking out mineral oil competitors through ASTM D02 qualification requirements.
- Vegetable Oil-Based:Rapeseed and palm kernel oil feedstocks yield biodegradable esters for marine hydraulic systems and environmentally sensitive applications. REACH mandates in Europe accelerate displacement of mineral oil in these segments, though agricultural commodity volatility compresses margins.
- Glycerol Esters:Mono- and di-glyceride structures function as food-grade emulsifiers and cosmetic stabilizers.
- Sorbitan Esters:Span and Tween derivatives serve surfactant roles across personal care and pharmaceutical formulations.
Synthetic grades retain volume leadership; vegetable oil-based alternatives hold the steepest expansion curve as EU Green Deal compliance deadlines tighten.
End Use Industry:
Cost tier stratification separates premium-margin aerospace applications from high-volume, thinner-return cosmetics channels.
- Lubricants:Base stock demand concentrates in aviation turbine oils and industrial refrigeration systems. EPA SNAP restrictions on hydrofluorocarbon lubricants open formulation slots for compatible polyol esters in cold chain equipment across the United States.
- Cosmetics:Emulsifier applications in skin-care and color cosmetics expand volume fastest. Direct-to-manufacturer digital procurement platforms in South Korea and Japan compress distributor layers for specialty ester grades.
- Food & Beverage:Glycerol and sorbitan esters function as emulsifiers and stabilizers in processed food systems.
- Pharmaceuticals:Excipient-grade esters support drug delivery and solubilization applications.
Lubricants command the highest value per kilogram; cosmetics applications are expanding most quickly through Asian personal care markets.
Application:
Application maturity determines whether segments compete on specification compliance or formulation innovation.
- Emulsifiers:Polyol esters stabilize oil-water interfaces in cosmetics, food, and pharmaceutical matrices. South Korean and Japanese skin-care formulators drive specification refinement through direct digital procurement relationships with specialty chemical producers.
- Skin Conditioning Agents:Neopentyl glycol esters deliver emollient properties in premium personal care lines. European cosmetics manufacturers prioritize bio-based feedstock traceability under CSRD disclosure rules.
- Foam Stabilizers:Sorbitan ester derivatives control aeration in food and personal care products.
- Flavoring Agents:Food-grade glycerol esters carry and release volatile compounds in processed formulations.
Emulsifiers anchor current volume; skin conditioning agents gain share fastest through premium personal care positioning.
Form:
Supply chain handling requirements differentiate liquid bulk shipments from powder processing investments.
- Liquid:Pumpable ester grades dominate lubricant base stock and cosmetic emulsifier supply chains. German and Belgian integrated petrochemical corridors optimize liquid bulk logistics for aviation-qualified producers serving aerospace formulators.
- Powder:Solid sorbitan and glycerol esters suit food and pharmaceutical powder blending operations. Powder processing adds capital intensity for producers targeting these segments.
- Gel:Semi-solid concentrates serve niche cosmetic and topical pharmaceutical applications.
- Granule:Free-flowing solid forms support automated dosing in food manufacturing lines.
Liquid forms retain logistics dominance; powder grades climb the fastest as food and pharmaceutical automation spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German polyol ester producers export specialized aviation base stocks to maintenance facilities in India and Southeast Asia, establishing a west-to-east trade corridor that reshapes regional demand patterns.
Germany
Aviation turbine OEMs in Munich and Hamburg specify neopentyl glycol esters rated above 200°C for narrow-body engine lubricants. REACH authorization procedures under ECHA tighten scrutiny on persistent additives, forcing formulators toward ashless alternatives. The Rhine-Ruhr petrochemical corridor secures backward integration into adipic acid feedstocks for regional ester manufacturers.
United States
EPA SNAP restrictions on hydrofluorocarbon lubricants channel industrial refrigeration demand toward compatible polyol ester formulations. ASTM D02 certification timelines extend 18-36 months for new aviation chemistries, freezing out smaller producers. Gulf Coast petrochemical clusters in Texas and Louisiana optimize liquid bulk logistics for domestic aviation-qualified producers.
India
Maintenance, repair, and overhaul facilities in Bengaluru and Hyderabad qualify imported polyol ester stocks for narrow-body engine servicing. BIS standards for industrial lubricants gradually align with ASTM specifications, easing technical barriers for foreign suppliers. The Maharashtra chemical belt attracts specialty ester distributors serving western Indian aerospace subcontractors.
China
Dual carbon goals under MEE accelerate displacement of mineral oil lubricants in marine and hydraulic applications. GB standards for biodegradable industrial fluids create compliance pathways for vegetable oil-based ester imports. The Yangtze River Delta concentrates domestic neopentyl glycol production for captive aviation ester manufacturing.
Japan
METI industrial decarbonization targets push automotive and machinery lubricant formulators toward synthetic ester base stocks. JIS standards for high-temperature hydraulic fluids specify polyol ester performance thresholds exceeding conventional mineral grades. The Osaka-Kobe chemical corridor hosts formulation R&D for Asian aviation maintenance networks.
Polyol Esters Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates with captive polyol feedstock positions. Three European chemical producers control over 70% of specialized neopentyl glycol supply, creating tiered access for aviation-grade ester manufacturers. Strategic archetypes separate backward-integrated feedstock controllers, catalytic technology licensors, and application-focused formulation specialists. Competitive moves concentrate on long-term offtake contracting and unified quality system deployment across previously separate aerospace and industrial product lines.
Among German-based integrated producers, BASF and Evonik Industries exemplify the feedstock-control archetype, securing adipic acid and specialized polyol positions across European production sites. Dow anchors the technology-licensor tier through proprietary catalytic esterification capabilities. These three companies represent the concentration of aviation-qualified manufacturing infrastructure that turbine OEM specifications increasingly require.
| Leading Market Players |
|---|
| Dow |
| Huntsman |
| BASF |
| Evonik Industries |
| Lanxess |
| Ultrachem |
| Chemtura Corporation |
| Cargill |
| Stepan Company |
| Others |
Supply Flow & Price Mechanics
Integrated adipic acid capacity at Rhine-Ruhr petrochemical sites in Germany compresses input cost volatility for regional ester manufacturers while simultaneously anchoring price floors through scale-driven efficiency thresholds that smaller producers cannot match.
Pricing Analysis
Current-generation neopentyl glycol esters command substantial premiums over prior-generation mineral oil alternatives, while next-generation vegetable oil-based biodegradable grades occupy a narrowing mid-tier position. Three-tier pricing structure across aviation-certified premium, industrial-standard, and economy mineral-replacement levels separates formulation tiers by ASTM D02 qualification status and thermal stability thresholds. Cost compression in industrial-grade segments is intensifying because railway and wind turbine gearbox maintainers in Northern Europe are adopting intermediate-tier formulations that miniaturize performance gaps. Aviation lubricant blenders exhibit the lowest price sensitivity due to OEM warranty requirements demanding batch-to-batch consistency documentation, whereas cosmetics emulsifier buyers in South Korea and Japan drive hardest volume negotiations through direct digital procurement platforms.
Supply Chain Analysis
Strategic stockpiling of neopentyl glycol feedstock dominates inventory strategy among aviation-qualified ester producers facing 18-36 month ASTM D02 certification timelines that preclude just-in-time raw material sourcing. Manufacturing concentrates in Germany, Belgium, and the United States where integrated petrochemical corridors secure backward integration into adipic acid and specialized polyol inputs. The supply chain draws from rapeseed and palm kernel oil agricultural commodities for biodegradable grades, creating margin exposure to commodity price cycles. Single-source vulnerability concentrates in the three European chemical producers controlling over 70% of specialized neopentyl glycol supply. Distribution runs through long-term offtake contracting with 3-5 year supply agreements transferring inventory risk upstream to ester producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation formulation expertise combining high-temperature tribology with REACH compliance represents a scarce capability set concentrating at a handful of European and US producers, constraining competitive entry and sustaining margin pools among qualified incumbents.
For Market Incumbents: Consolidate backward integration into adipic acid feedstocks across Rhine-Ruhr and Gulf Coast petrochemical corridors to neutralize input cost volatility from concentrated neopentyl glycol suppliers. Lock in 3-5 year offtake agreements with turbine service subsidiaries to transfer inventory risk downstream and freeze out smaller competitors lacking capital to sustain pre-revenue qualification periods. Prioritize unified quality system deployment across aerospace-certified and industrial-grade product lines as railway and wind turbine maintainers adopt intermediate-tier formulations. For New Entrants and Emerging Players: Aftermarket technical service gaps in Indian aerospace MRO facilities present the most penetrable entry point, where Bengaluru and Hyderabad maintenance shops qualify imported stocks but lack localized formulation support. Target digital procurement platform relationships with South Korean and Japanese cosmetics formulators seeking direct manufacturer connections for specialty emulsifier grades. Pursue toll manufacturing arrangements with established European producers to bypass 18-36 month ASTM D02 certification barriers while building qualification track records. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aviation-qualified ester producers with long-term offtake contracts indexed to raw material costs, offering visibility through multi-year OEM warranty cycles. Mid-cap specialists with captive neopentyl glycol positions or proprietary catalytic esterification technology represent the most defensible acquisition profiles over the medium-term horizon. Monitor EU CSRD supply chain disclosure implementation timelines as an inflection indicator for capital requirements that may force consolidation among smaller bio-based feedstock producers lacking blockchain traceability infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adipic Acid | Rhine-Ruhr petrochemical corridors secure feedstock cost advantages for aviation-grade ester manufacturers. |
| Long-term Supply Agreement | 3-5 year offtake contracts with turbine service subsidiaries transfer inventory risk upstream to producers. |
| Green Manufacturing Transition | EU Green Deal biodegradability mandates channel formulators toward compliant synthetic ester base stocks. |
| Joint Venture | Indian MRO partnerships in Bengaluru and Hyderabad create demand pull outside traditional Western aviation hubs. |
| Capacity Expansion | Yangtze River Delta neopentyl glycol production supports captive aviation ester manufacturing for domestic turbine OEMs. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at European and US ester production facilities, procurement leads at aviation lubricant blenders, and technical R&D directors at turbine OEMs; and secondary validation through customs and trade data, Cefic chemical industry reports, SEC 10-K filings, and ECHA REACH registration databases. Bottom-up triangulation across product-grade volume estimates and top-down reconciliation against end-use industry consumption patterns anchored market sizing.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type tier, end-use industry concentration, and regional production hub clustering. CAGRs were derived from segment-level growth coefficients applied to baseline estimates, with aviation turbine thermal stability specifications and EU Green Deal compliance deadlines serving as primary demand drivers in the projection algorithm.
Underlying assumptions cover sustained aviation fleet expansion, REACH authorization timelines, and adipic acid feedstock availability, with deviation risk concentrated in vegetable oil commodity volatility and neopentyl glycol supply concentration. Forecasts reflect these baseline conditions with acknowledged sensitivity to regulatory acceleration or feedstock disruption scenarios. Revision becomes warranted when EU CSRD traceability mandates or ASTM D02 specification changes cross implementation thresholds that alter qualification economics for new market entrants.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Polycide Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Conductive Polymers Market