
 France Protective Coatings Market | 2026-2036
France Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
France Protective Coatings Market Insights
REACH compliance is decoupling small-formulator economics from viable market participation in France. Akzo Nobel N.V. leverages its integrated resin supply chain to absorb regulatory testing costs that fragment smaller competitors. PPG Industries, Inc. anchors its position through dedicated marine R&D facilities in Brittany serving Atlantic offshore projects. Hempel A/S specializes in high-performance epoxy systems for French nuclear maintenance programs.
France protective coatings are engineered film-forming systems comprising binders, pigments, solvents or water carriers, and functional additives, applied at dry-film thicknesses typically ranging from 50 to 1,500 microns to shield substrates from corrosion, chemical attack, and environmental degradation. The primary purpose spans infrastructure longevity, asset protection in aggressive industrial environments, and compliance with safety-critical performance standards. Epoxy formulations dominate heavy industrial and marine maintenance cycles due to their adhesion and chemical resistance profile. Water-based technology is gaining formulation share as French environmental agencies tighten volatile organic compound emission thresholds for industrial painting operations. Powder coating occupies a specialized niche in automotive component finishing where zero-VOC output aligns with OEM sustainability mandates.
ANSM and ECHA frameworks govern biocidal claims and substance authorization for coatings deployed in French healthcare and food-contact environments. The EU Green Deal's industrial emissions directives are pushing Grand Est chemical manufacturers toward lower-carbon curing processes. France's national building code, aligned with RE2020 environmental performance standards, specifies coating durability metrics that extend specification lifecycles. Stakeholders must monitor how the EU AI Act's quality management requirements will influence automated coating inspection systems deployed across French shipyards and automotive plants.
Market Dynamics
France's protective coatings sector is compressing around REACH-aligned chemical registration requirements that systematically raise formulation compliance costs and filter smaller participants from viable commercial participation.
Growth Catalysts
- Offshore wind infrastructure:Marine-grade coating systems are experiencing accelerated specification as Atlantic wind farm construction expands along Brittany and Normandy coastlines. Foundation steel and turbine towers require specialized corrosion protection cycles.
- RE2020 building code alignment:France's national construction standards now mandate extended coating durability metrics for commercial and residential structures. Specification lifecycles are lengthening across Grand Est and Île-de-France building markets.
- Nuclear maintenance cycles:High-performance epoxy systems command sustained demand from EDF's reactor refurbishment schedules. Radiation-resistant formulations face limited substitution options in containment vessel applications.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate precursor costs fluctuate with European naphtha pricing. Formulators absorb margin compression or pass through to price-sensitive industrial maintenance buyers.
- Grand Est supply concentration:Specialty chemical manufacturing clusters near Strasbourg and Mulhouse create geographic dependency for technical coating intermediates. Logistics disruptions propagate quickly through regional formulation networks.
- Biocidal authorization friction:ECHA's active substance approval timelines extend product registration cycles for antifouling marine coatings. Market-ready formulations await regulatory clearance before commercial deployment.
Strategic Opportunities
- Auvergne-Rhône-Alpes industrial corridor:Underpenetrated aerospace component finishing demand around Lyon and Saint-Étienne offers expansion terrain for high-temperature resistant coating systems. OEM qualification programs are accelerating.
- EU Green Deal industrial emissions directives:Lower-carbon curing process mandates are creating specification windows for UV-curable and waterborne technologies. Grand Est manufacturers are retrofitting production lines to capture incentive-aligned contracts.
- Digital inspection integration:Automated coating thickness verification and defect detection systems are converging with shipyard and automotive plant quality protocols. The EU AI Act's quality management requirements will standardize deployment frameworks.
Industry Challenges
- Specialized applicator certification:Marine and nuclear coating specifications require qualified technician credentials that face limited training pipeline capacity. Workforce development lags behind project commissioning schedules.
- Legacy solvent-based inventory transition:Formulators must manage stranded stock while scaling waterborne and high-solids production. Capital allocation between compliance and capacity creates operational tension.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Protective Coatings Market |
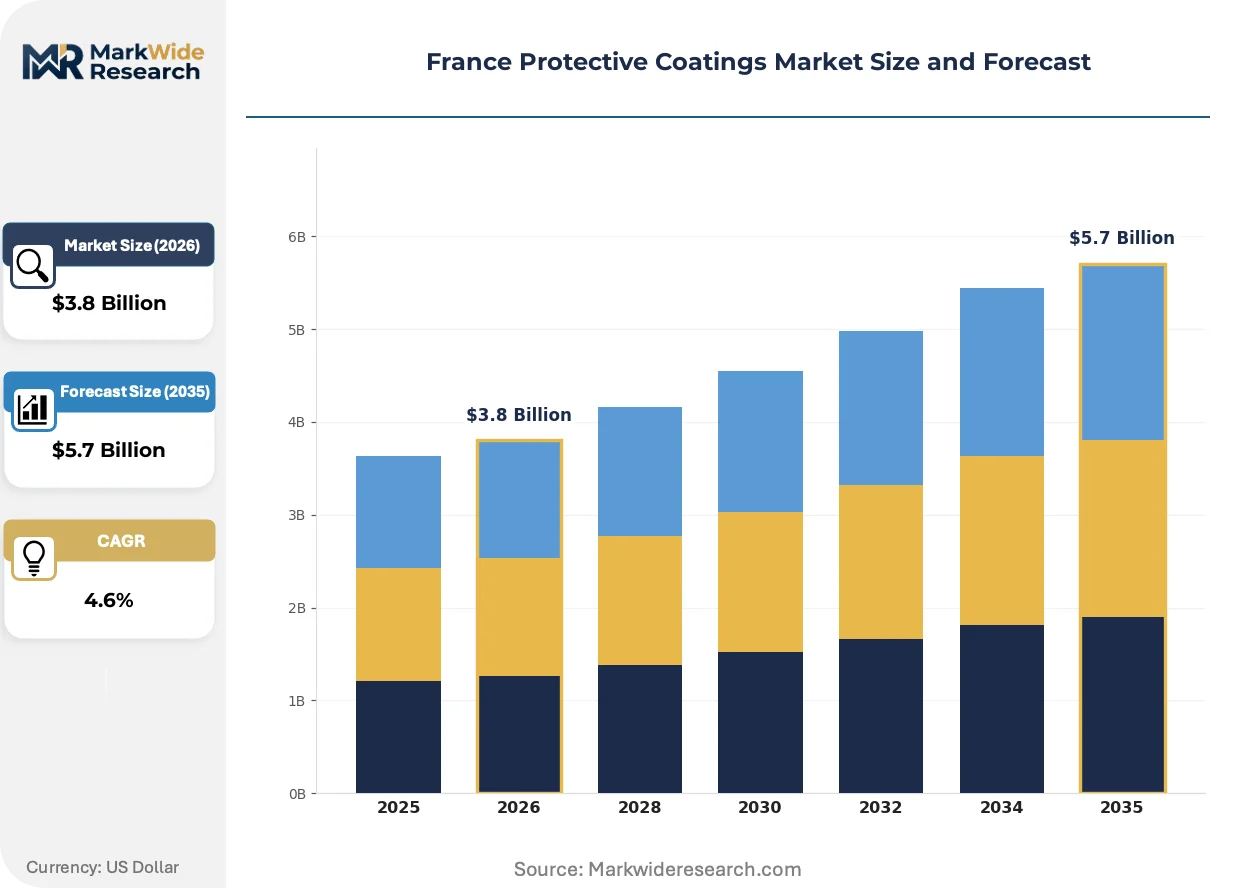
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Acrylic, Polyurethane, Alkyd Application: Marine, Automotive, Industrial, Building & Construction Technology: Water-based, Solvent-based, Powder Coating, UV-cured End User: Manufacturers, Contractors, Distributors, Retailers |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Hempel A/S, Nippon Paint Holdings Co., Ltd., Arkema, Axalta Coating Systems, Jotun, RPM International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Protective Coatings Market Trends and Innovations
Coating system architecture is fragmenting into application-specific modules that trade universal performance claims for targeted substrate-environment matching. This specialization is redrawing competitive boundaries between integrated suppliers and focused technology developers.
Self-healing polymer networks are modularizing maintenance protocols across French offshore wind installations. These materials autonomously repair microcracks from mechanical fatigue and thermal cycling. EDF and wind farm operators are piloting specifications that reduce touch-up frequency during harsh Atlantic weather windows. The technology is compressing total cost-of-ownership calculations that previously favored conventional epoxy rebuild cycles.
EU Green Deal industrial emissions directives are mandating solvent recovery and thermal oxidizer upgrades across Grand Est coating manufacturing facilities. ANSM and ECHA frameworks are tightening in parallel for biocidal product claims. Marine antifouling and healthcare facility coatings face the steepest compliance trajectories. Formulators with integrated resin production are absorbing capital requirements that fragment smaller competitors' economics.
Buyers in French shipyards and automotive assembly plants are unbundling coating supply from application service contracts. Previously integrated procurement packages are separating into material specification and contractor qualification components. This disintermediation is visible across Brittany naval repair facilities and Hauts-de-France automotive supplier parks. Technical specification authority is concentrating with end-user engineering teams rather than distributor sales organizations.
France Protective Coatings Market Segmentation
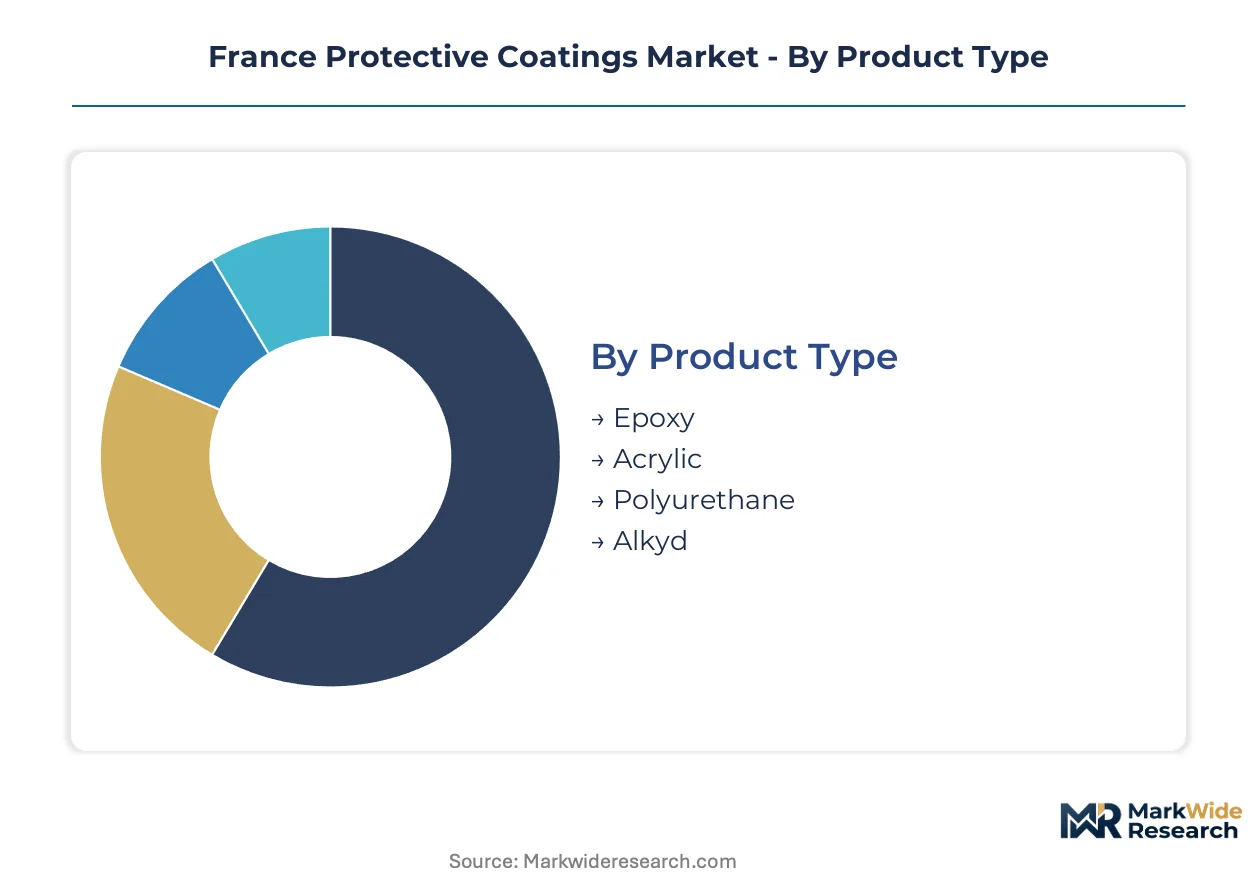
France's protective coatings market fragments along technical performance hierarchies that separate commodity maintenance formulations from specification-critical systems. Segmentation discipline reveals where formulation investment concentrates and which technology platforms face displacement pressure.
Product Type:
Customization intensity spans from rigid industrial specifications to adjustable architectural finishes across this chemistry spectrum.
- Epoxy:Two-part thermosetting systems built from bisphenol-A or bisphenol-F resin backbones deliver exceptional substrate adhesion and chemical resistance. EDF's reactor containment programs and Atlantic offshore wind foundations in Brittany specify these systems almost exclusively. REACH registration costs for epoxy hardeners filter smaller formulators from nuclear and marine certification tracks.
- Polyurethane:Aliphatic and aromatic isocyanate-cured films provide UV stability and abrasion resistance for exterior architectural and transportation applications. Grand Est automotive suppliers specify polyurethane clearcoats for component durability. Isocyanate precursor volatility compresses margin structures for non-integrated producers.
- Acrylic:Thermoplastic or thermosetting resin systems offering rapid dry times and color retention for decorative and light industrial protection.
- Alkyd:Oil-modified polyester formulations serving cost-sensitive maintenance recoating cycles with moderate durability requirements.
Leading the category by volume: Epoxy systems. Expanding most quickly: Polyurethane formulations capturing automotive and architectural specification share.
Application:
Performance requirements escalate with environmental severity from controlled interior environments to Atlantic marine exposure.
- Marine:Immersion-grade and atmospheric-zone coating systems protect hull structures, offshore platforms, and wind turbine foundations from saltwater corrosion and biofouling. Foundation steel for Brittany and Normandy wind farms drives specification of cathodic-protection-compatible epoxies and silyl-acrylate antifouling technologies. ECHA biocidal authorization timelines delay new product commercialization.
- Industrial:Chemical-resistant formulations protect processing equipment, storage tanks, and pipeline infrastructure across Grand Est petrochemical corridors and Auvergne-Rhône-Alpes manufacturing clusters. High-solids and solvent-free systems dominate new specification as EU Green Deal emissions directives tighten.
- Automotive:OEM-qualified coatings for body-in-white, component finishing, and refinishing applications with exacting appearance and durability standards.
- Building & Construction:Architectural coatings for structural steel, concrete protection, and decorative finishes across commercial and residential construction.
Marine applications command the highest specification barriers. Industrial maintenance offers the broadest volume base.
Technology:
Regulatory pressure and curing economics are redistributing share across liquid and solid film-formation methods.
- Water-based:Acrylic and polyurethane dispersions with volatile organic compound profiles below regulatory thresholds. French environmental agencies have tightened emission limits for industrial painting operations, accelerating specification in Grand Est manufacturing facilities. Drying time and humidity sensitivity constrain deployment in marine maintenance windows.
- Solvent-based:Conventional high-performance systems with established application characteristics and broad substrate compatibility. Stranded inventory management challenges formulators transitioning capacity to compliant alternatives.
- Powder Coating:Thermosetting resin systems applied electrostatically and cured without solvent emission. Zero-VOC output aligns with OEM sustainability mandates in automotive component finishing.
- UV-cured:Rapid polymerization systems activated by ultraviolet radiation for specialized industrial and wood coating applications with throughput-critical processing requirements.
Solvent-based technology retains the largest installed base. Water-based systems are climbing the fastest on regulatory tailwinds.
End User:
Technical authority and procurement leverage concentrate differently across direct applicators and intermediated distribution channels.
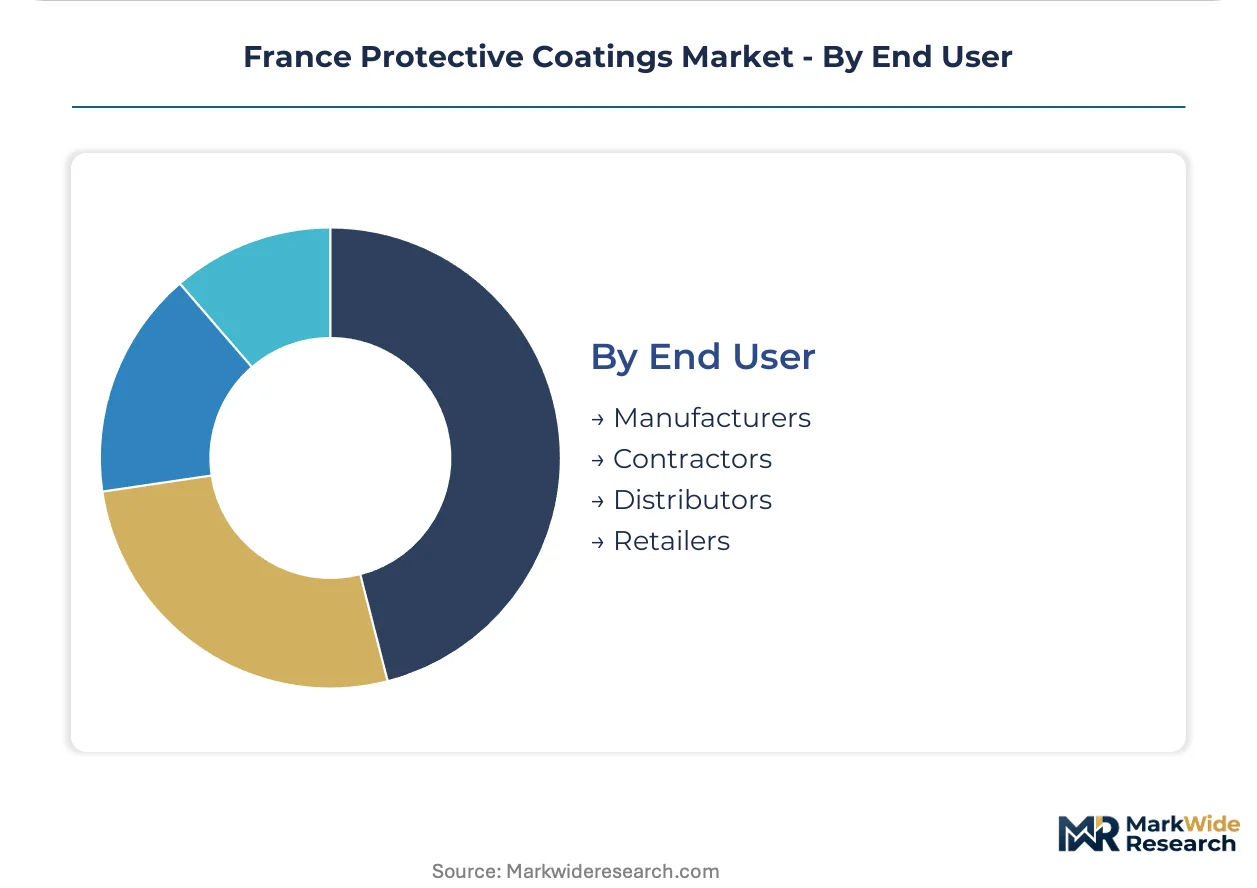
- Contractors:Specialized application firms execute marine, industrial, and infrastructure coating projects with certified technician crews. Brittany shipyards and EDF maintenance programs require qualified contractor credentials that face constrained training pipeline capacity. Disintermediation trends are separating material specification from application procurement.
- Manufacturers:OEM and industrial producers with in-house finishing operations for component and assembly protection. Automotive suppliers in Hauts-de-France and aerospace manufacturers around Lyon maintain captive coating lines with direct formulation relationships.
- Distributors:Regional stocking intermediaries serving maintenance contractors and smaller industrial accounts with product range and logistics support.
- Retailers:Consumer-facing channels for architectural and light maintenance coating products in smaller volume formats.
Contractor channels absorb the highest technical specification complexity. Manufacturer direct relationships offer the steepest expansion trajectory in aerospace and automotive qualification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's protective coatings demand concentrates in industrial corridors where nuclear maintenance, offshore wind construction, and automotive manufacturing intersect. Regional specialization creates distinct specification environments across metropolitan and peripheral zones.
Île-de-France
EDF's headquarters and nuclear engineering centers drive specification authority for radiation-resistant containment coatings. ANSM oversight of healthcare facility coatings tightens biocidal claims for hospital and pharmaceutical plant applications. La Défense commercial construction mandates RE2020-aligned durability standards for structural steel protection.
Auvergne-Rhône-Alpes
Aerospace component finishing demand accelerates around Lyon and Saint-Étienne manufacturing clusters. OEM qualification programs for high-temperature resistant systems are expanding. Saint-Étienne's precision engineering suppliers specify coating systems for turbine blade and landing gear components.
Grand Est
Petrochemical processing infrastructure near Strasbourg and Mulhouse absorbs chemical-resistant epoxy formulations for tank linings and pipeline protection. EU Green Deal emissions directives push manufacturers toward lower-carbon curing processes. Regional specialty chemical concentration creates supply dependency for coating intermediates.
Brittany and Normandy
Atlantic offshore wind farm construction specifies marine-grade cathodic-protection-compatible systems for foundation steel. Brittany shipyards and naval repair facilities drive antifouling coating demand. ECHA biocidal authorization timelines delay new product deployment for hull protection applications.
Hauts-de-France
Automotive supplier parks around Lille and Valenciennes specify OEM-qualified coatings for body-in-white and component finishing. Powder coating lines serving zero-VOC mandates dominate captive finishing operations. Disintermediation trends separate material specification from contractor procurement.
France Protective Coatings Market Competitive Landscape
Dutch and Danish producers anchor one tier; American specialists hold scale positions in automotive and industrial segments. The vendor base stratifies between integrated resin manufacturers absorbing REACH compliance costs and focused application-technology developers. Three archetypes dominate: captive resin producers, marine-specialized formulators, and diversified industrial coating suppliers. Competitive moves concentrate on geographic expansion into underpenetrated aerospace corridors and portfolio diversification toward waterborne technologies.
Among Netherlands-based integrated suppliers, Akzo Nobel N.V. occupies a position representing captive resin production advantages. PPG Industries, Inc. exemplifies the diversified industrial and automotive archetype with American manufacturing scale. Hempel A/S anchors the marine-specialized tier with Danish heritage in offshore and protective systems. These three entities collectively represent the competitive structure filtering smaller participants from REACH-intensive specification tracks.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Hempel A/S |
| Nippon Paint Holdings Co., Ltd. |
| Arkema |
| Axalta Coating Systems |
| Jotun |
| RPM International |
| Others |
Pricing and Supply Chain Analysis
Captive resin production anchors competitive economics across French protective coatings, with integrated manufacturers absorbing REACH registration costs that fragment smaller formulators. This backward integration into epoxy and polyurethane intermediates concentrates pricing power among Dutch and Danish suppliers while pressuring non-integrated competitors in Grand Est and Brittany.
Pricing Analysis
Volume-margin splits diverge sharply across specification tiers. Three-tier pricing structure across premium, standard, and economy levels separates nuclear-certified epoxies from industrial maintenance formulations and commodity architectural coatings. Certification grade and volume scale drive price differentiation, with EDF reactor containment specifications commanding substantial premiums over Grand Est tank lining contracts. Cost compression in standard industrial tiers is intensifying because petrochemical feedstock volatility propagates through European naphtha pricing. Maintenance contractors in Brittany shipyards exhibit highest price sensitivity, while nuclear program managers prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Dutch epoxy resin suppliers feeding Grand Est formulation networks. Specialty chemical manufacturing draws from bisphenol-A precursors, isocyanate intermediates, and titanium dioxide pigments sourced predominantly from Germany, Belgium, and China. Tariff exposure on Chinese pigment imports compounds margin pressure for non-integrated formulators. Distribution runs through regional stocking intermediaries serving certified contractor channels, with direct manufacturer relationships dominating automotive and aerospace captive finishing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's protective coatings sector is navigating a technology-transition phase as waterborne and UV-curable systems displace legacy solvent-based formulations under EU Green Deal mandates.
For Market Incumbents: Deploy captive resin capacity as a defensive moat against REACH compliance cost escalation. Absorb regulatory testing expenditures that would fragment smaller competitors, while redirecting R&D investment toward self-healing polymer networks for offshore wind applications. Marine-grade specification authority represents the most defensible position against waterborne technology substitution.
For New Entrants and Emerging Players: Launch via aerospace component qualification programs in Auvergne-Rhône-Alpes, where OEM certification barriers filter established suppliers less completely than nuclear or marine tracks. Underpenetrated demand around Lyon and Saint-Étienne for high-temperature resistant systems offers the most penetrable entry point. Target direct manufacturer relationships over distributor channels to capture specification authority.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated Dutch or American coating groups seeking French nuclear and marine certification assets. Five-to-ten year viability hinges on waterborne technology transition execution rather than solvent-based legacy retention. Watch ECHA biocidal authorization timelines for antifouling formulations as the inflection signal for marine segment profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resins | Captive supply of bisphenol-A intermediates absorbs REACH testing costs that fragment competitors. |
| Waterborne Technology Transition | Grand Est manufacturing retrofits align with EU Green Deal emissions directives for industrial painting operations. |
| Marine R&D Facility Expansion | Brittany-based development centers capture Atlantic offshore wind foundation steel specifications. |
| Self-Healing Polymer Commercialization | Autonomous crack-repair systems reduce EDF and wind operator touch-up frequency during harsh weather windows. |
| Aerospace OEM Qualification Program | Saint-Étienne turbine blade and landing gear coating approvals open underpenetrated Auvergne-Rhône-Alpes demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at Grand Est petrochemical facilities, procurement leads at EDF maintenance divisions, distribution channel partners serving Brittany shipyards, and technical R&D directors at integrated suppliers combined with ECHA substance authorization databases, French customs export records, and SEC 10-K disclosures from listed coating manufacturers. Bottom-up volume builds across application segments triangulated against top-down industry value estimates from Cefic and Fédération des Peintures.
Segment-level granularity modeled chemistry type, end-use industry, and technology platform across the projection horizon. CAGRs derived from regression analysis of historical specification trends, regulatory phase-in schedules, and capital expenditure pipelines for Atlantic offshore wind and nuclear refurbishment programs. Nuclear maintenance cycle timing, ECHA biocidal authorization progress, and RE2020 building code adoption curves served as industry-specific forecast inputs.
Petrochemical feedstock volatility, ECHA regulatory delays, and offshore wind construction pace are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about technology transition rates and certification timeline continuity that may shift with policy or macroeconomic developments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Marking Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Asia-Pacific Automotive Refinish Coatings Market
Coatings
North America Epoxy Powder Coatings Market
Coatings
Egyptian Protective Coatings Market
Coatings
Wire Enamels Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Transparent Conductive Coatings Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Global Metal Coatings Market
Coatings
Japan Architectural Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Global Graphite Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
Coating Auxiliaries Market