
 Yacht Coatings Market | 2026-2036
Yacht Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Coatings Market Intelligence
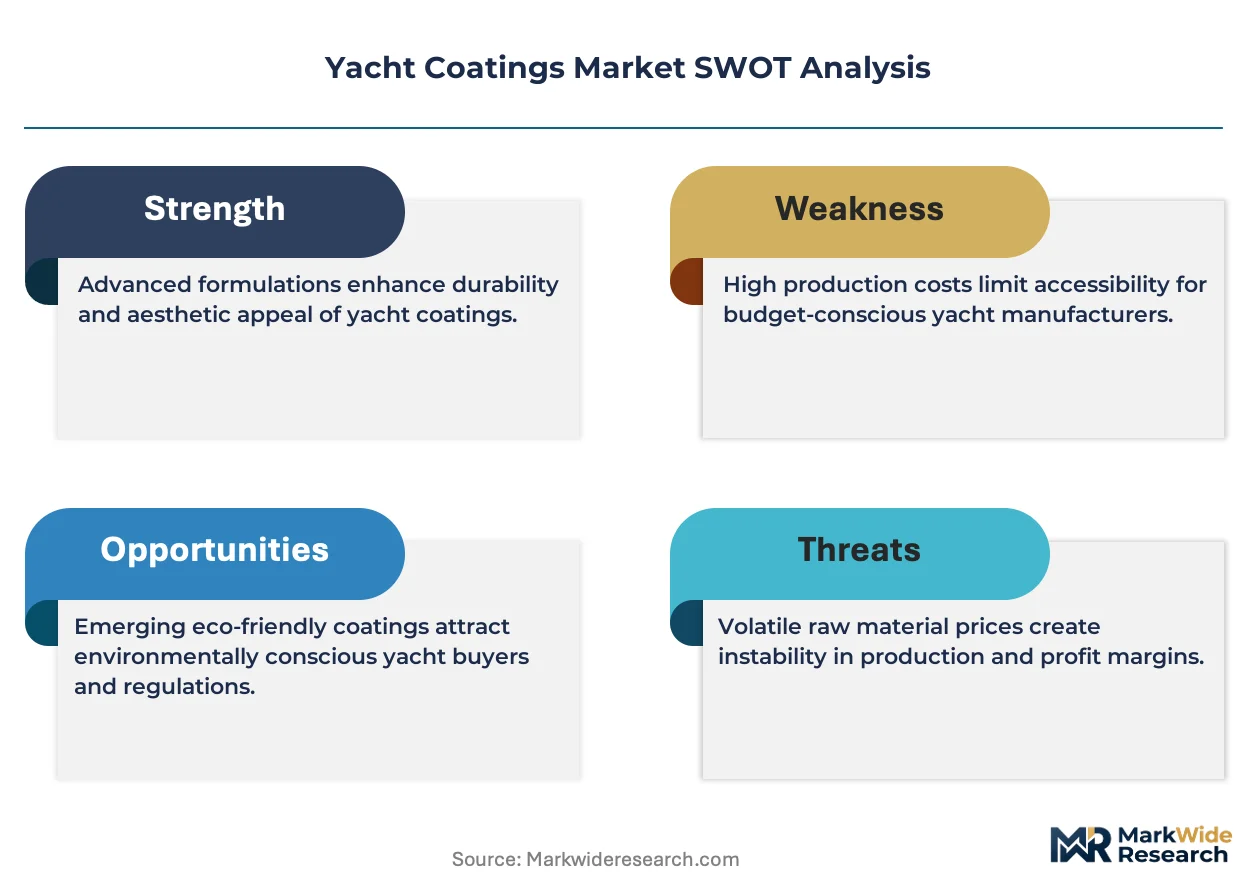
Silicone-hybrid foul-release chemistry is reconfiguring how hull protection systems are engineered for high-performance vessels. PPG Inc. leverages its marine R&D infrastructure to advance low-friction coating platforms, while Jotun A/S anchors its position through geographic dominance in Scandinavian and Mediterranean refit networks. Akzo Nobel N.V. differentiates via specialty primer systems designed for composite hull substrates.
Yacht coatings comprise multi-layer protective systems formulated from polyurethane, epoxy, vinyl, or silicone resin bases, applied sequentially to hulls, superstructures, and underwater surfaces to prevent biofouling, corrosion, and UV degradation while maintaining hydrodynamic efficiency and aesthetic finish. Antifouling formulations face structural pressure from biocide regulation, shifting margin pools toward silicone-based foul-release alternatives and specialty coatings engineered for superyacht application cycles. Epoxy primers retain volume leadership in new-build marine application segments, while polyurethane topcoats command premium positioning in recreational end-user refurbishment programs.
The European Chemicals Agency (ECHA) enforces REACH authorization requirements that restrict copper-based biocide content in antifouling products sold across EU member states, directly altering formulation R&D priorities and product registration costs for suppliers. The International Maritime Organization (IMO) antifouling systems convention extends these constraints to vessels over 400 gross tonnage, compressing market access for non-compliant coating portfolios. Stakeholders must monitor regulatory divergence between EU biocide frameworks and emerging standards in Asia-Pacific manufacturing jurisdictions to anticipate reformulation investment cycles and regional supply rebalancing.
Market Dynamics
The EU REACH biocide restrictions on copper-based antifouling systems are forcing a wholesale chemistry transition across the yacht coatings value chain, redirecting R&D investment toward silicone-hybrid foul-release platforms and compressing margins for legacy biocide-dependent portfolios.
Growth Catalysts
- Silicone-hybrid foul-release chemistry:Superyacht fleet operators in the Mediterranean are accelerating adoption of low-friction hull coatings to meet ECHA authorization timelines while maintaining hydrodynamic performance.
- EU Green Deal maritime decarbonization targets:The framework incentivizes hull efficiency improvements through advanced coating systems, creating pull-through demand for premium primer and topcoat combinations in new-build and refit yards.
- Composite hull substrate proliferation:Epoxy primer systems engineered for carbon fiber and fiberglass hulls are capturing volume as yacht builders shift from aluminum and steel construction methods.
Market Restraints
- Copper-based biocide input cost volatility:Remaining copper oxide supply chains face price instability as ECHA authorization restrictions tighten, squeezing margins for suppliers maintaining legacy antifouling portfolios.
- Specialty silicone resin supply concentration:Production of foul-release coating precursors clusters among a limited set of chemical manufacturers, creating vulnerability for formulators dependent on consistent silicone-hybrid feedstock.
- IMO antifouling systems convention compliance friction:The treaty's extension to vessels over 400 gross tonnage creates registration cost barriers and technical documentation burdens that compress market access for smaller coating portfolios.
Strategic Opportunities
- Scandinavian refit network expansion:Norway and Sweden's superyacht maintenance clusters present underpenetrated demand for silicone-based foul-release systems as owners extend vessel operating lives in Baltic and North Sea conditions.
- Performance-based coating service contracts:Hull efficiency guarantees bundled with application services are emerging as a channel innovation, displacing traditional transactional product sales in high-value yacht management programs.
- CE marking harmonization with MDR technical documentation standards:The convergence creates regulatory tailwinds for coating suppliers able to leverage existing quality management systems across marine and medical device compliance frameworks.
Industry Challenges
- Specialized applicator certification timelines:Silicone-hybrid foul-release systems require trained application crews, and yard certification bottlenecks are extending project lead times for premium coating programs.
- Legacy antifouling removal and substrate preparation:Biocide-containing hull coatings demand hazardous material handling protocols that complicate refit scheduling and inflate project costs for Mediterranean shipyards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Coatings Market |
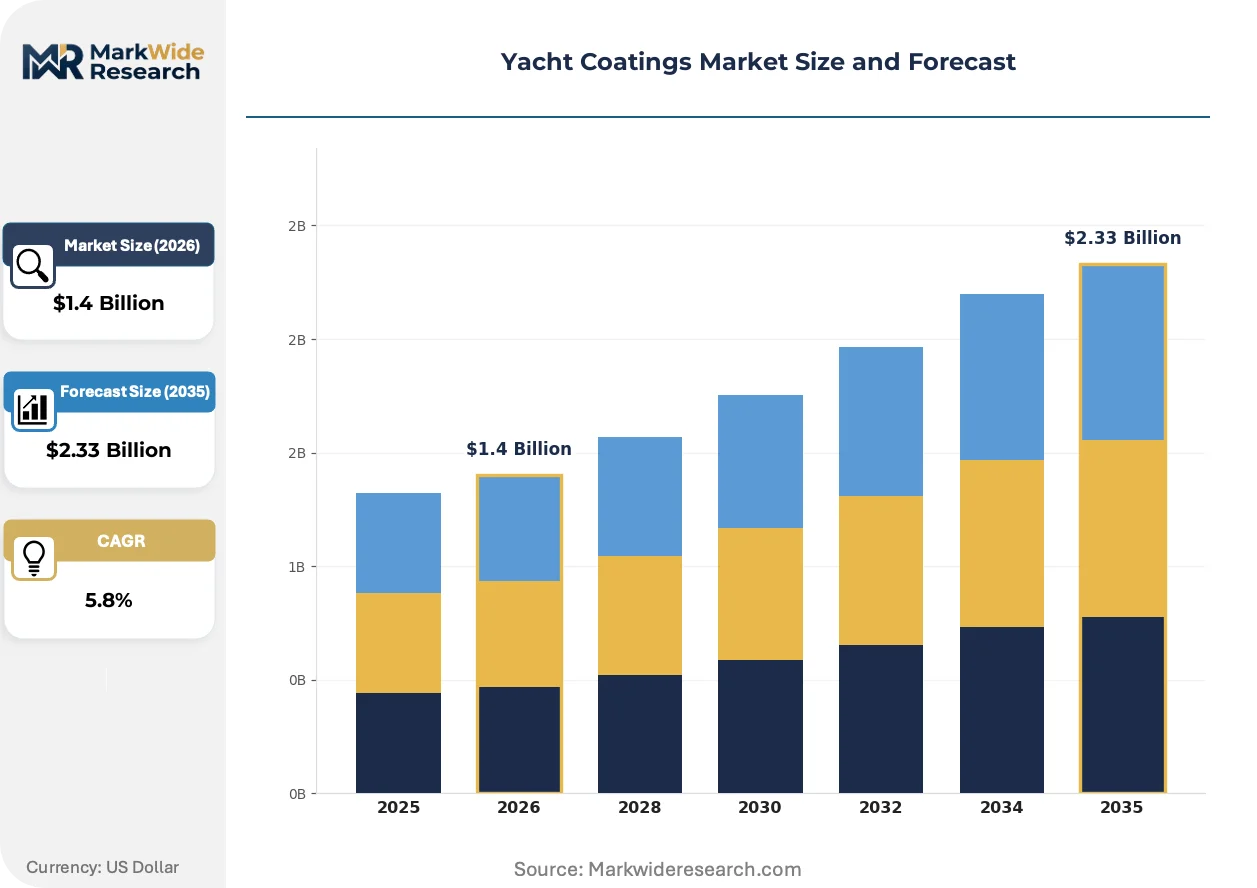
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifouling, Topcoat, Primer, Specialty Coatings Material: Polyurethane, Epoxy, Vinyl, Silicone Application: Marine, Commercial, Recreational, Industrial End User: Yacht Manufacturers, Boat Owners, Shipyards, Maintenance Services |
| Companies Covered | Hempel A/S, BASF SE, Akzo Nobel N.V., RPM International Inc., Nippon Paint Marine Coatings Co. Ltd., PPG Inc., Sherwin-Williams Company, Axalta Coating Systems, LLC, Jotun A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Coatings Market Strategic Shifts & Innovations
Formulation chemistry is bifurcating between biocide-dependent legacy systems and silicone-hybrid platforms, while regulatory pressure accelerates product registration costs and procurement models shift toward performance guarantees.
Silicone-hybrid foul-release coatings are collapsing the traditional antifouling application cycle by eliminating the need for annual hull cleaning and repainting. Superyacht operators with vessels above 60 meters are adopting these systems at accelerating rates despite 40-60% first-cost premiums. The technology is collapsing maintenance revenue pools for shipyards dependent on recurring antifouling contracts while enabling fuel savings claims that justify upfront investment.
REACH authorization requirements for copper-based biocides are compressing the addressable market for conventional antifouling products across EU member states. The European Chemicals Agency's cumulative cost burden for product registration and data submission is filtering out smaller formulators unable to sustain compliance investments. Specialty coating divisions at major chemical suppliers are responding by consolidating biocide-dependent portfolios and accelerating silicone platform commercialization.
Refit procurement is consolidating around integrated hull performance contracts that bundle coating supply, application, and efficiency monitoring. Yacht management companies are displacing traditional yard-direct purchasing by centralizing specification authority and demanding outcome-based guarantees. This pattern is most visible in Monaco and Palma de Mallorca, where fleet operators with multiple vessel holdings leverage scale to extract service-level commitments from coating applicators.
Yacht Coatings Market Segmentation
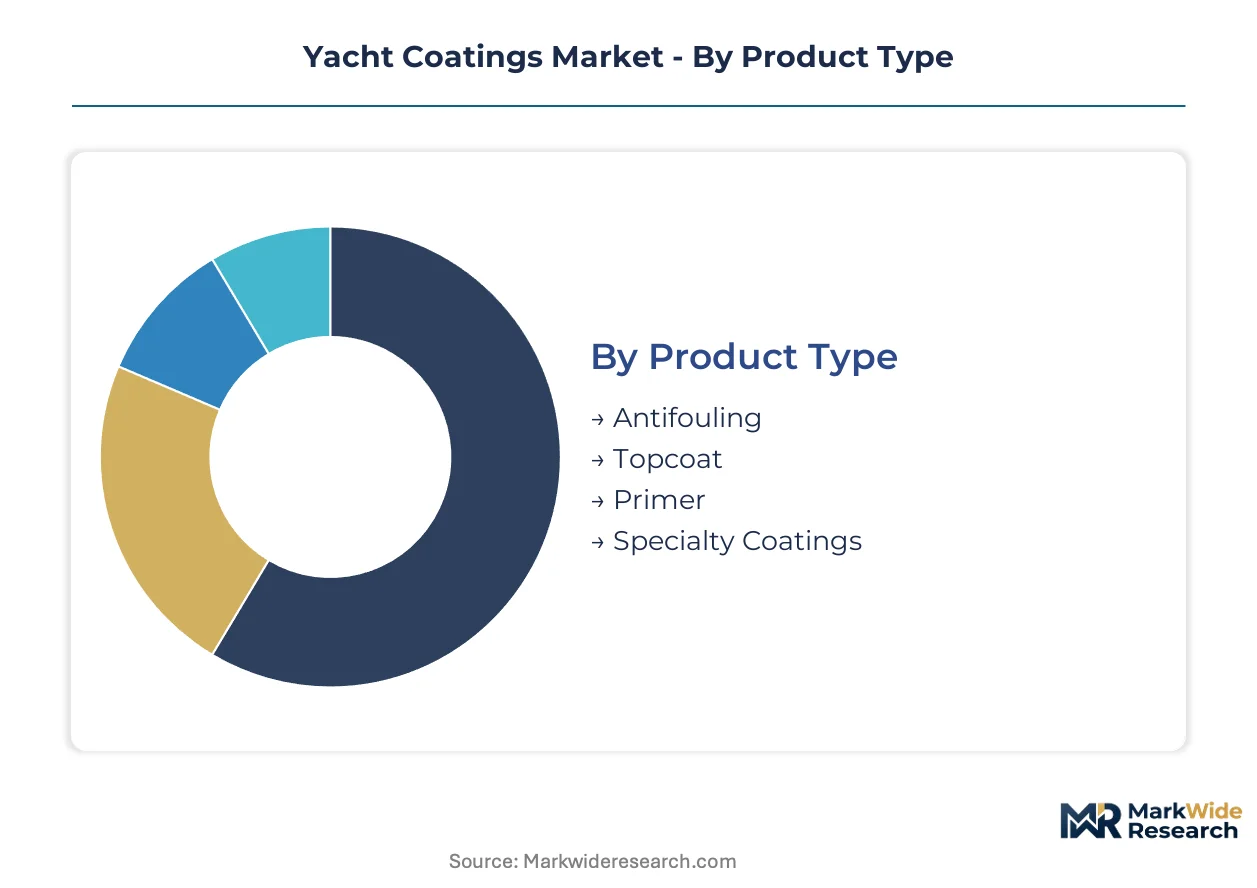
Yacht coatings segment along four distinct dimensions that shape procurement patterns and margin structures. Product type determines the regulatory exposure and replacement cycle frequency. Material chemistry governs the R&D investment intensity and supply chain configuration for each supplier portfolio.
Product Type:
Cost tier differentiation separates commodity hull protection from premium aesthetic and performance systems, with regulatory pressure reshuffling the value capture across each layer.
- Antifouling:Copper-oxide and silicone-hybrid formulations prevent biofouling on submerged hull surfaces. ECHA REACH authorization restrictions are compressing biocide-dependent volumes while accelerating foul-release chemistry adoption in Mediterranean superyacht refit yards.
- Topcoat:Polyurethane and acrylic systems deliver UV resistance and aesthetic finish for superstructures. Premium topcoat demand concentrates in Italian and French shipyard clusters handling new-build superyacht completion programs.
- Primer:Epoxy-based adhesion and corrosion barriers anchor multi-layer coating systems. Composite hull proliferation in Northern European yacht manufacturing is expanding specialty primer specifications for carbon fiber substrates.
- Specialty Coatings:Niche formulations include deck non-skid, interior wood finishes, and tank linings. These command formulation premiums in custom superyacht builds where specification flexibility outweighs volume scale.
Antifouling holds installed capacity. Specialty coatings are rotating up the share rankings.
Material:
Application requirements and regulatory compliance timelines are driving material substitution patterns across hull protection systems.
- Polyurethane:Dominates topcoat applications with superior gloss retention and UV stability. Recreational yacht refurbishment programs in the Netherlands and Germany specify high-solids polyurethane for extended service intervals.
- Epoxy:Primer systems engineered for steel, aluminum, and composite substrates provide chemical resistance and mechanical adhesion. New-build marine applications in Scandinavian yards sustain volume leadership for epoxy formulations.
- Vinyl:Legacy antifouling binder systems face declining registration viability under EU biocide frameworks. Remaining demand concentrates in commercial vessel segments outside REACH jurisdiction.
- Silicone:Foul-release chemistry eliminates biocide content while reducing hull friction coefficients. Mediterranean fleet operators are absorbing 40-60% first-cost premiums to access fuel efficiency gains and extended maintenance cycles.
Epoxy retains formulation volume leadership. Silicone is climbing the fastest among resin categories.
Application:
End-use environment dictates performance specifications, with regulatory scope varying sharply across operational contexts.
- Marine:Seagoing yachts and superyachts face IMO antifouling convention compliance requirements for vessels above 400 gross tonnage. This segment concentrates premium coating procurement in EU-registered fleets.
- Commercial:Charter operations and yacht fleet management drive performance-based service contracts with efficiency guarantees. Procurement authority is consolidating around Monaco and Palma de Mallorca-based yacht management companies.
- Recreational:Private ownership patterns sustain transactional product sales through distributor and direct retail channels. Maintenance cycles align with seasonal haul-out schedules in Mediterranean and Baltic marinas.
- Industrial:Limited yacht-specific demand; overlaps with broader marine protective coatings for shore infrastructure and manufacturing equipment.
Marine application holds specification authority. Commercial is gaining share fastest through contract restructuring.
End User:
Customer type determines procurement sophistication, with fleet scale and technical capability shaping supplier relationship structures.
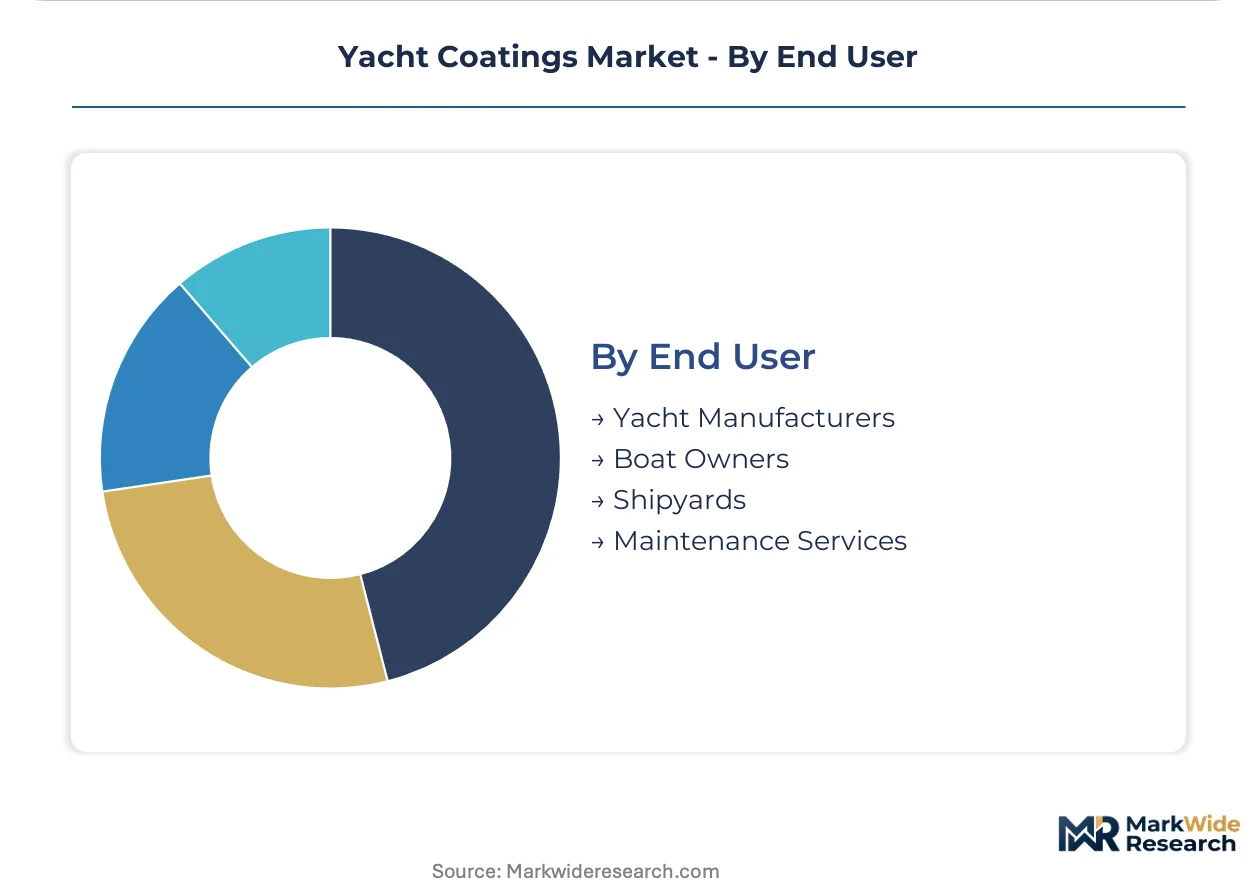
- Yacht Manufacturers:New-build yards in Italy, the Netherlands, and Germany specify coating systems during hull construction. These customers demand integrated technical support and warranty alignment across primer, antifouling, and topcoat layers.
- Boat Owners:Individual recreational users drive seasonal maintenance demand through retail and service network channels. Price sensitivity increases as vessel length decreases below 24 meters.
- Shipyards:Refit and repair facilities in Antibes, Barcelona, and Palma de Mallorca handle application labor and project management. Certification requirements for silicone-hybrid systems are extending lead times for premium coating programs.
- Maintenance Services:Specialized applicators and yacht management companies are displacing traditional yard-direct purchasing. These intermediaries centralize specification authority across multi-vessel fleets.
Shipyards hold application capacity. Maintenance services are expanding share through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian shipyards export premium topcoat systems to superyacht fleets operating across the Mediterranean, while Dutch coating formulators supply epoxy primer technologies to Northern European new-build yards. This trade-flow pattern concentrates formulation expertise in established maritime manufacturing clusters while distributing finished systems through refit networks in Monaco, Palma de Mallorca, and Antibes.
Italy
Superyacht new-build completion programs drive demand for polyurethane topcoat and specialty primer combinations. ECHA REACH biocide authorization timelines are compressing copper-based antifouling registrations while accelerating silicone-hybrid foul-release adoption in Viareggio and La Spezia shipyard clusters.
Netherlands
Amsterdam and Rotterdam harbor infrastructure supports coating raw material import flows serving Feadship and Oceanco new-build specifications. The EU Green Deal maritime decarbonization framework incentivizes hull efficiency investments through premium coating procurement in Dutch yacht manufacturing facilities.
Germany
Bavaria Yachts and Northern German superyacht builders specify epoxy primer systems for composite hull substrates. The country's national chemical regulator enforces stringent VOC emission standards that favor high-solids polyurethane formulations in recreational yacht refurbishment channels.
France
Antibes and La Ciotat refit yards handle silicone-hybrid foul-release application programs for Mediterranean fleet operators. ANSM technical documentation requirements align with CE marking standards for marine protective coatings distributed through Côte d'Azur maintenance networks.
United States
Florida and Pacific Northwest recreational boating clusters sustain seasonal maintenance demand through distributor and retail service channels. EPA antifouling pesticide registration requirements diverge from EU biocide frameworks, creating formulation portfolio segmentation between Atlantic and Mediterranean supply chains.
Yacht Coatings Market Key Industry Players
On the supply side, the industry is consolidating around integrated coating portfolios that span primer, antifouling, and topcoat layers. Three strategic archetypes dominate competitive positioning: diversified chemical conglomerates with marine divisions, specialty coating pure-plays with regional refit network penetration, and industrial paint manufacturers extending into yacht-specific formulations. Capacity expansion in silicone-hybrid resin production and strategic partnerships with superyacht shipyards represent the dominant competitive moves reshaping supplier relationships.
Within the diversified chemical conglomerate tier, BASF SE and Akzo Nobel N.V. exemplify integrated formulation capabilities spanning multiple resin chemistries. PPG Inc. anchors the specialty marine coating segment with established R&D infrastructure. Jotun A/S occupies a position in the Nordic-Mediterranean refit corridor, representing geographic concentration strategies among mid-scale coating specialists. These three companies illustrate how supplier positioning varies by portfolio breadth, geographic coverage, and technical service intensity across new-build and maintenance application cycles.
| Leading Market Players |
|---|
| Hempel A/S |
| BASF SE |
| Akzo Nobel N.V. |
| RPM International Inc. |
| Nippon Paint Marine Coatings Co. Ltd. |
| PPG Inc. |
| Sherwin-Williams Company |
| Axalta Coating Systems, LLC |
| Jotun A/S |
| Others |
Cost & Logistics Intelligence
Specialty silicone resin production clusters in Germany and Japan feed directly into margin capture by foul-release coating formulators serving Mediterranean superyacht fleets. The upstream concentration of hybrid polymer precursors allows incumbent suppliers to extract premium positioning while constraining pricing flexibility for mid-tier competitors dependent on spot market resin procurement.
Pricing Analysis
Silicone-hybrid foul-release coatings command 40-60% first-cost premiums over copper-based biocide systems, while legacy vinyl antifouling prices erode under ECHA registration cost pressure. Three-tier pricing structure across premium silicone foul-release, standard epoxy primer systems, and economy-grade maintenance coatings reflects certification grade and volume scale differentiation. Pricing pressure stems from REACH compliance cost absorption squeezing biocide-dependent portfolios. Recreational boat owners below 24 meters exhibit highest price sensitivity, whereas superyacht fleet operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between EU member states and post-Brexit UK regulatory divergence dominates supply chain risk assessment for coating distributors. Raw material sourcing draws from German silicone resin manufacturers, Dutch epoxy compounders, and Italian pigment specialists. Single-source vulnerability concentrates in silicone-hybrid precursor supply where three chemical conglomerates control global capacity. Distribution runs through Antibes, Palma de Mallorca, and Monaco-based yacht management intermediaries consolidating procurement authority across multi-vessel fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based hull efficiency contracts represent a service-attach opportunity expanding faster than standalone coating product sales, as yacht management companies centralize specification authority and demand outcome guarantees bundled with application services.
For Market Incumbents: Entrench silicone-hybrid foul-release technology leadership through captive supply of specialty resin precursors and exclusive certification partnerships with Viareggio and La Spezia shipyard clusters. ECHA biocide authorization timelines threaten legacy antifouling revenue streams, requiring accelerated portfolio consolidation toward low-friction chemistry platforms. Backward integration into silicone resin production secures margin defense against feedstock cost volatility. For New Entrants and Emerging Players: Establish a beachhead in Scandinavian refit networks serving Baltic and North Sea superyacht operators where silicone-based foul-release penetration remains underdeveloped compared to Mediterranean clusters. White-space opportunity concentrates in Norway and Sweden maintenance facilities lacking certified applicator capacity for premium coating programs. Partner with regional yacht management companies to bypass entrenched shipyard-direct procurement channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty coating divisions spun from diversified chemical conglomerates seeking portfolio rationalization. Long-term viability hinges on regulatory compliance infrastructure transferable across EU Green Deal maritime decarbonization frameworks. Monitor ECHA authorization withdrawal announcements for copper-based biocides as inflection indicator for foul-release chemistry adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Resin Capacity Expansion | German and Japanese chemical manufacturers anchor foul-release coating supply security for Mediterranean fleets. |
| Shipyard Certification Partnership | Exclusive applicator training agreements with Italian and Dutch new-build yards lock in specification authority. |
| Performance Contract Development | Hull efficiency guarantees bundled with coating supply displace transactional sales in Monaco fleet management. |
| REACH Compliance Consolidation | Biocide product registration cost sharing across coating portfolios filters out smaller formulators. |
| Composite Primer Specialization | Carbon fiber substrate expertise captures volume as Northern European builders shift from aluminum construction. |
Research Approach
A spread of perspectives from coating formulator R&D directors, superyacht fleet technical managers, shipyard procurement leads, and ECHA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings of listed chemical suppliers, European Chemicals Agency registration databases, and yacht industry association fleet statistics. Bottom-up vessel coating consumption estimates triangulated against top-down marine coatings market allocations.
Demand-supply-balance framing anchored the forecast framework across the analysis window, modeling volume and value outputs through product type, material chemistry, application environment, and end-user procurement sophistication dimensions. CAGRs derived from segment-level growth rate synthesis incorporating ECHA authorization timeline impacts, EU Green Deal maritime efficiency incentives, and composite hull substrate proliferation patterns. Silicone-hybrid adoption curves and refit cycle compression effects served as industry-specific forecast inputs.
Sensitivities concentrate around ECHA biocide authorization withdrawal timing, silicone resin supply disruption scenarios, and shipyard certification bottleneck duration. Forecasts reflect assumptions about regulatory enforcement consistency and fleet operator technology transition willingness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Trim Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
Global Coated Steel Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Fillers and Coating Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Electrical Insulation Coatings Market
Coatings
Sol Gel Nanocoating Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
ASEAN Protective Coatings Market
Coatings
US Concrete Floor Coatings Market
Coatings
Electron Beam Curable Coating Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Fluoropolymer Coating Market
Coatings
Global Polyaspartic Coatings Market