
 Russia Architectural Coatings Market | 2026-2036
Russia Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Architectural Coatings Market Analytics
Residential renovation is shifting toward premium exterior and interior finishes as Russian homeowners prioritize weather resistance and aesthetic longevity in harsh climates. DAW SE leverages its Central European manufacturing heritage to supply high-durability facade systems. Lakra Sintez anchors its position through deep distribution across Siberian and Far Eastern construction markets. VGT Enterprise LLC differentiates via specialized industrial coating lines adapted to Russian oil and gas infrastructure needs.
Russia architectural coatings encompass liquid-applied protective and decorative films formulated with acrylic, alkyd, water-based, or solvent-based binders, typically applied at dry film thicknesses of 50–150 microns to shield substrates from moisture, UV degradation, and thermal cycling. Their primary purpose spans both new construction finishing and maintenance of existing building envelopes across residential, commercial, and infrastructure assets. Water-based acrylic formulations lead volume due to regulatory pressure on solvent emissions and contractor preference for lower odor during application. Solvent-based alkyd segments retain share in industrial and heavy infrastructure where substrate adhesion and chemical resistance command priority over environmental profiles.
Russia's national standardization body, Rosstandart, administers GOST certification requirements that govern coating performance benchmarks, while the Eurasian Economic Commission harmonizes technical regulations across member states. These frameworks shape product registration costs, import compliance burdens, and domestic formulation strategies for multinational suppliers. Stakeholders must monitor pending amendments to EAEU technical regulations on construction material safety and anticipate how Rosstandert conformity assessment procedures will interact with evolving EU REACH-aligned chemical restrictions.
Market Dynamics
The Eurasian Economic Union's tightening volatile organic compound limits are forcing domestic reformulators to rebuild binder systems while import-dependent contractors face extended compliance timelines. This regulatory compression is reshaping procurement priorities across Moscow's high-volume construction corridor.
Growth Catalysts
- EAEU Technical Regulation 041/2017:Harmonized VOC ceilings across Russia, Belarus, and Kazakhstan are accelerating water-based acrylic adoption in residential renovation.
- Siberian infrastructure expansion:Oil and gas field development in Tyumen and Krasnoyarsk Krai is generating specialized industrial coating demand for pipeline and storage assets.
- Facade system durability:Extended freeze-thaw cycling in Central Russia is pulling specification toward high-build elastomeric finishes.
Market Restraints
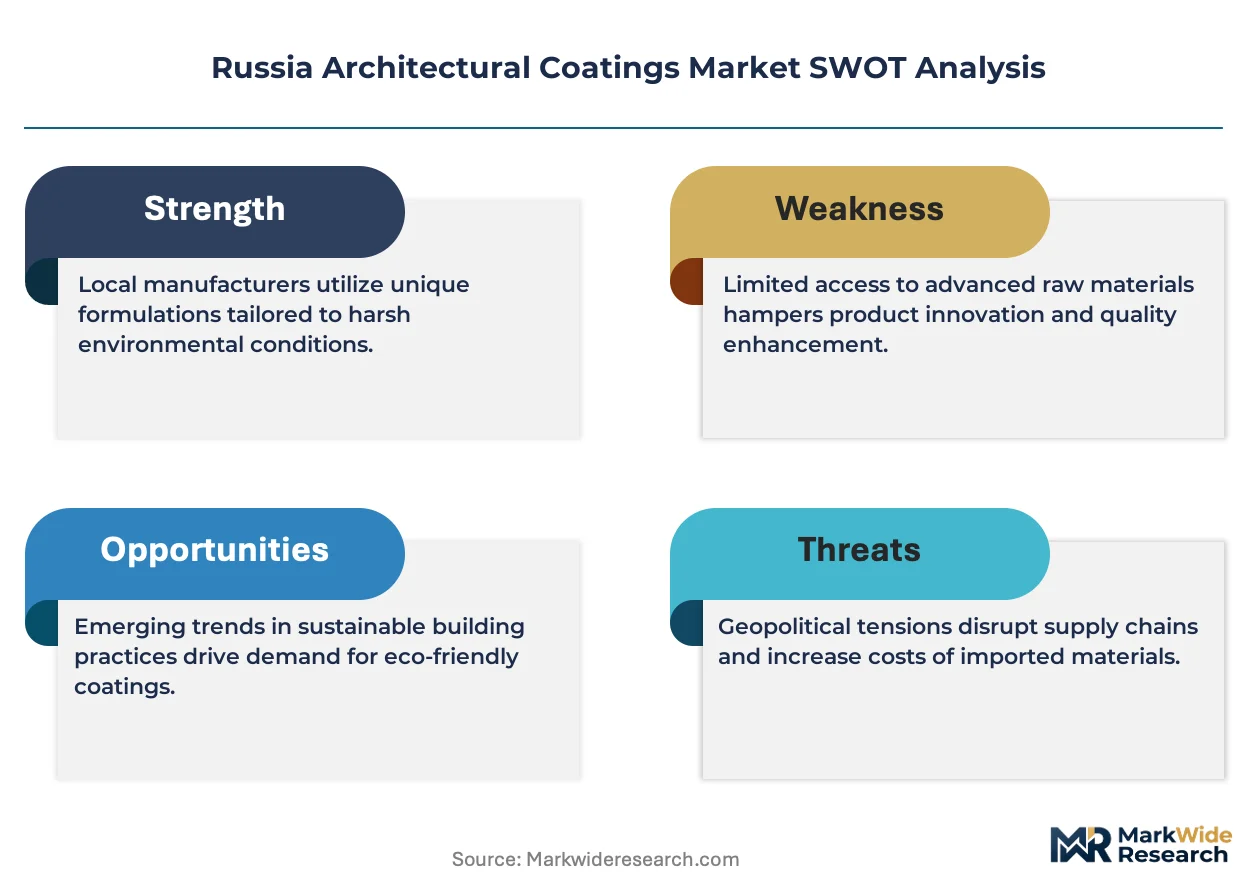
- Titanium dioxide supply concentration:Pigment sourcing dependence on Chinese sulfate-process output creates input cost volatility for domestic producers.
- Rosstandart certification timelines:GOST-R conformity assessment procedures extend product registration cycles by four to eight months versus pre-2022 baselines.
- Alkyd substitution ceiling:Solvent-based systems retain irreplaceable adhesion performance on weathered galvanized steel in Far Eastern marine environments.
Strategic Opportunities
- Far Eastern construction corridor:Vladivostok and Khabarovsk new-build volumes are outpacing local coating supply capacity.
- Digital color-matching kiosks:Retail channel innovation is compressing specification cycles in Moscow's DIY renovation segment.
- EAEU mutual recognition expansion:Pending Belarus and Armenia laboratory accreditation agreements will streamline multi-territory product launches.
Industry Challenges
- Formulation chemist scarcity:Russian technical universities have reduced polymer science enrollment, constraining domestic R&D pipeline replenishment.
- Import equipment servicing:Dispersion and grinding machinery from EU suppliers faces spare parts lead time extension, complicating capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Architectural Coatings Market |
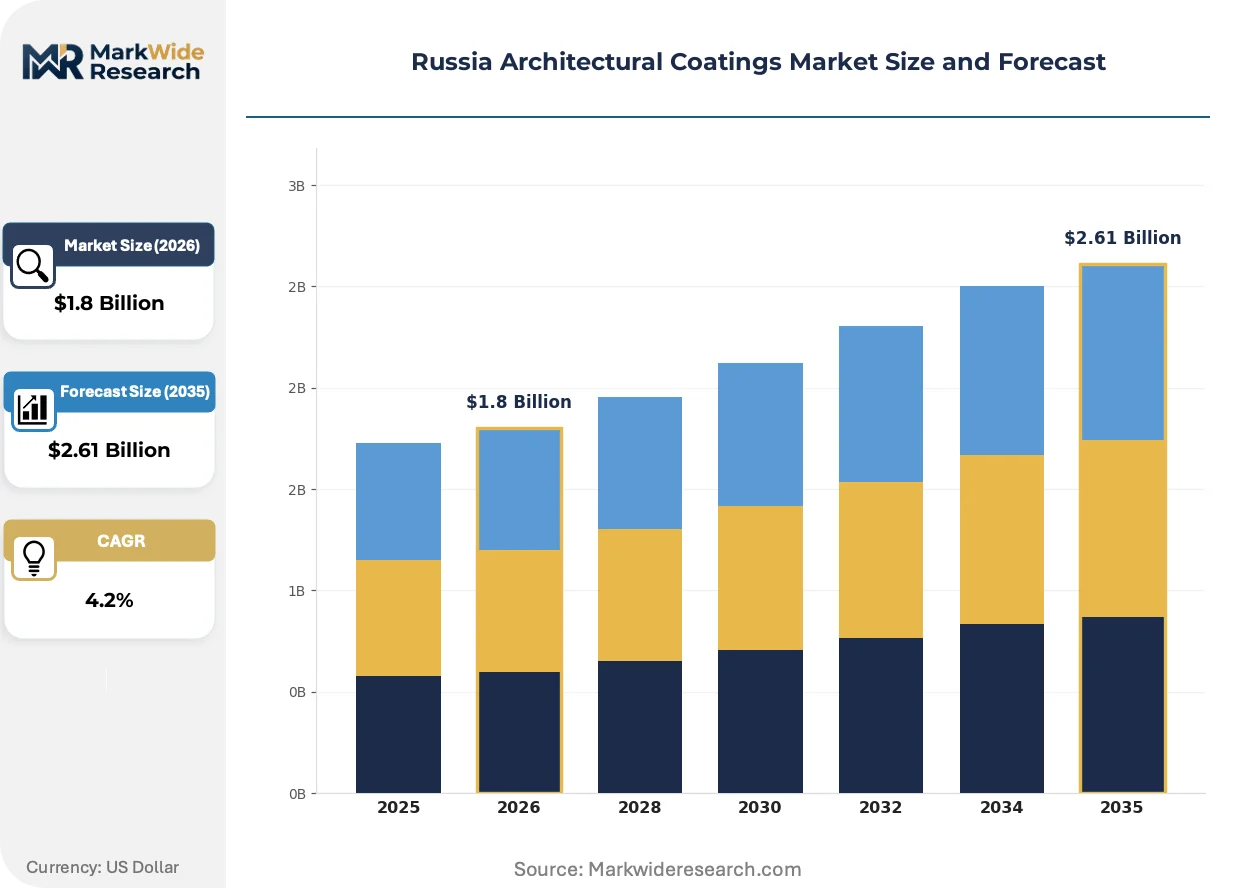
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paints, Primers, Stains, Sealers Application: Residential, Commercial, Industrial, Infrastructure Formulation Type: Acrylic, Alkyd, Water-Based, Solvent-Based End User: Contractors, Architects, Homeowners, Property Developers |
| Companies Covered | DAW SE, Flügger group A/S, AkzoNobel N.V., VGT Enterprise LLC, Lakra Sintez, PPG Industries, Inc., Компания «Русские Краски», Beckers Group, ABC Farben, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Architectural Coatings Market Evolving Landscape
Digital specification tools and automated tinting infrastructure are compressing color-matching cycles while regulatory pressure on solvent emissions accelerates water-borne system development. These forces are converging to reshape how coatings are formulated, sold, and applied across Russian construction markets.
Self-tinting dispensing technology is automating the final color adjustment step that previously required manual pigment addition. Large-format retail chains in Moscow and St. Petersburg are deploying these systems to reduce in-store inventory SKUs by eighty percent. The technology is automating the shift from pre-matched gallon stocks to base-plus-tinter models, compressing working capital requirements for distributors.
Rosstandart's pending amendments to GOST R 51691 will tighten exterior coating chalking resistance benchmarks effective upon publication in the national standards registry. Industrial consequence includes mandatory reformulation of mid-tier acrylic binders to incorporate higher-grade rutile titanium dioxide. Far Eastern contractors applying coatings in high-UV marine exposure zones face the steepest compliance cost increases.
Specification authority is migrating from general contractors to facade system integrators who bundle insulation, substrate preparation, and finish into single-source packages. This procurement consolidation is displacing independent coating distributors from new-build project capture. The pattern is most visible in Moscow's high-rise residential tower segment where envelope performance warranties now bundle substrate and finish liability.
Russia Architectural Coatings Market Segmentation
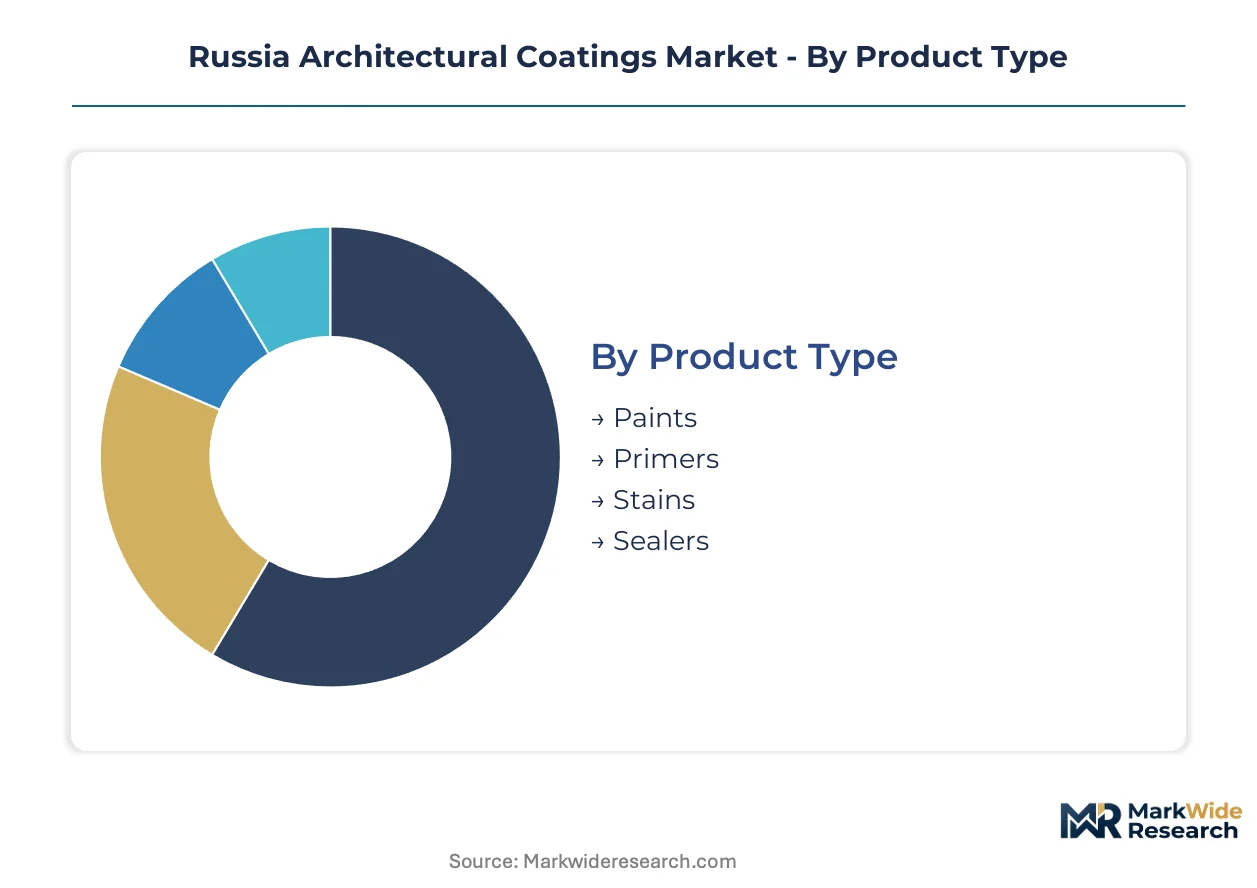
Architectural coatings in Russia fragment across formulation chemistry, end-use application, and procurement channel. Each axis carries distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Surface protection requirements differ sharply between new construction finishing and maintenance cycles across Russia's climatic zones.
- Paints:Acrylic and alkyd binders dominate decorative and protective films, with water-borne systems gaining share in Moscow residential renovation under EAEU VOC ceilings. Demand concentrates in the Central Federal District where high-rise envelope refurbishment cycles compress specification timelines.
- Primers:Substrate adhesion promoters formulated with penetrating alkyd or blocking acrylic chemistry anchor multi-coat systems on weathered concrete and galvanized steel. Siberian contractors specify heavy-build variants for thermal cycling resistance in Tyumen oilfield infrastructure.
- Stains:Semi-transparent penetrating finishes protect timber facades and decking in Far Eastern coastal construction.
- Sealers:Clear film-forming or penetrating treatments guard decorative concrete and masonry against freeze-thaw degradation.
Paints lead on scale; primers lead on momentum as substrate preparation gains specification authority.
Application:
Project type determines performance grade requirements and procurement channel access across Russian construction markets.
- Residential:Interior and exterior finishing of single-family homes and multi-unit buildings drives volume, with Moscow and St. Petersburg renovation activity pulling specification toward premium durability grades. Facade system integrators now bundle insulation and finish in high-rise tower envelopes, consolidating procurement away from independent distributors.
- Commercial:Office, retail, and hospitality assets require high-traffic interior durability and exterior weather resistance. Digital color-matching kiosks in Moscow DIY channels are compressing specification cycles for mid-market commercial refresh projects.
- Industrial:Manufacturing facility maintenance demands chemical-resistant alkyd and epoxy- modified systems. Procurement runs through specialized distributors with technical service capabilities.
- Infrastructure:Bridge, tunnel, and transportation asset protection requires certified high- performance coatings under GOST R conformance protocols.
Residential commands volume concentration; infrastructure shows steepest expansion trajectory as federal investment targets Siberian and Far Eastern corridors.
Formulation Type:
Binder chemistry determines regulatory compliance trajectory and application labor economics across Russian territory.
- Acrylic:Water-borne emulsion polymers dominate interior and exterior architectural finishes, offering low odor and cleanup advantages. Reformulation pressure from pending GOST R 51691 chalking resistance amendments is forcing titanium dioxide grade upgrades in mid-tier products.
- Alkyd:Solvent-borne ester resins retain irreplaceable adhesion on weathered metal substrates in marine and industrial exposure. EAEU VOC limits are compressing share in residential applications but protecting volume in Far Eastern infrastructure where substrate conditions demand solvent penetration.
- Water-Based:Low-VOC emulsion systems are accelerating adoption in Moscow and Central Federal District residential renovation under contractor health preferences.
- Solvent-Based:Higher-solids alkyd and urethane-modified systems persist where chemical resistance and substrate adhesion override environmental profiles.
Water-based formulations gain share fastest; alkyd systems defend position in irreplaceable industrial niches.
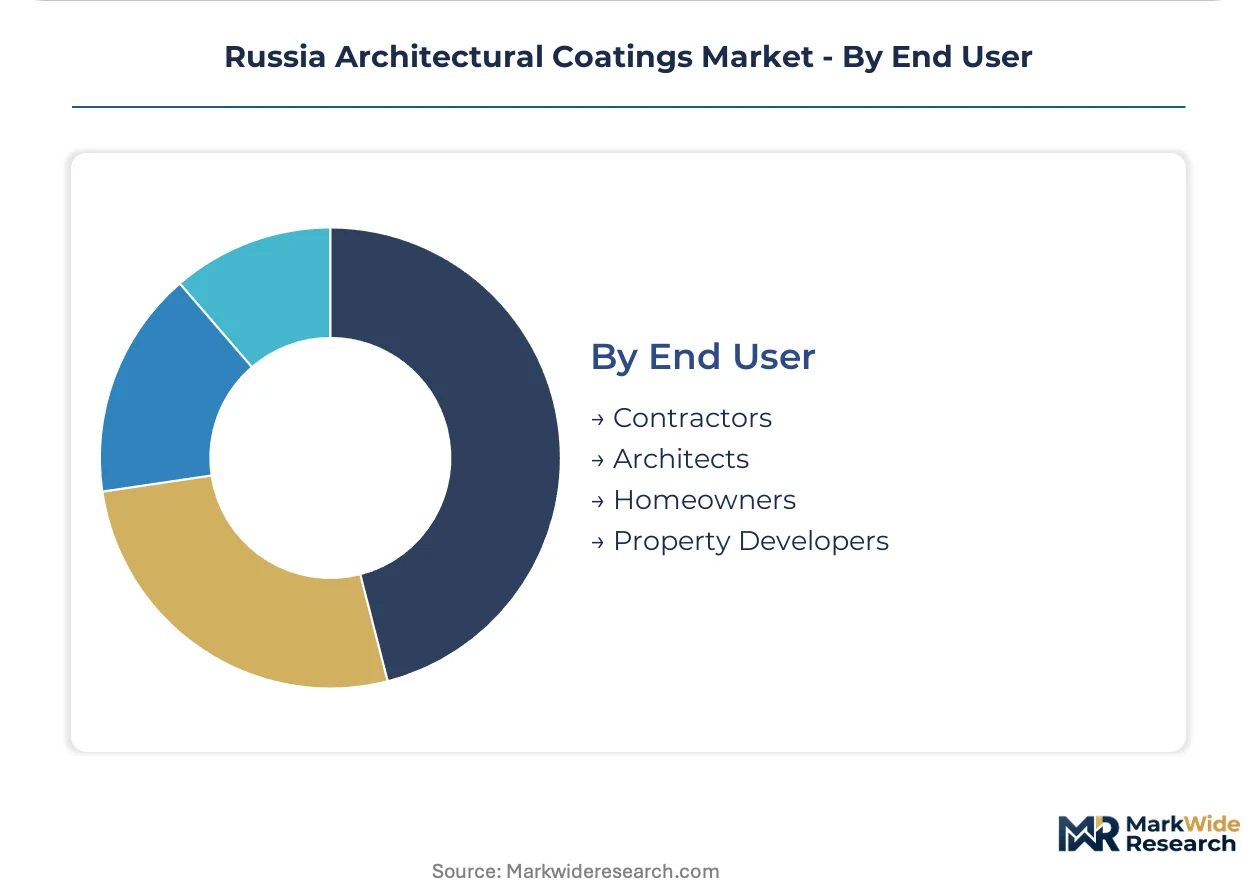
End User:
Procurement authority shapes product access, technical support requirements, and price realization across the Russian market.
- Contractors:Professional applicators specify coatings based on coverage rates, dry-time economics, and distributor availability. Moscow's high-volume construction corridor concentrates demand for standardized, readily available formulations.
- Architects:Design professionals influence specification through facade system integration and warranty bundling. Their authority is expanding in high-rise residential towers where envelope performance liability consolidates.
- Homeowners:DIY renovation participants in urban retail channels drive demand for pre-matched colors and simplified application systems.
- Property Developers:Volume purchasers of new construction finishes prioritize cost certainty and supply security across multi-phase projects.
Contractors anchor volume flows; architects are gaining specification authority fastest as envelope systems integrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers migrate capacity toward jurisdictions with lower compliance burdens. EAEU harmonization has compressed cross-border cost differentials, yet sub-regional enforcement variance still shapes facility siting decisions across Russian territory.
Central Federal District
Moscow's high-rise residential tower construction drives specification toward facade-integrated coating systems. Rosstandart's GOST-R certification protocols govern product registration timelines for suppliers targeting this corridor. The Moscow Oblast industrial ring hosts reformulation facilities adapting to pending chalking resistance amendments.
Siberian Federal District
Tyumen and Krasnoyarsk Krai oilfield infrastructure generates specialized industrial coating demand for pipeline protection. The Eurasian Economic Union's technical regulations on construction material safety apply here with regional enforcement variance. Novosibirsk serves as the distribution hub for heavy-build alkyd systems specified in sub-zero application windows.
Far Eastern Federal District
Vladivostok and Khabarovsk new-build volumes outpace local coating supply capacity, creating import dependency. Marine exposure conditions preserve solvent-based alkyd share where substrate adhesion overrides VOC compliance preferences. The Primorsky Krai construction corridor concentrates demand for weather-resistant elastomeric finishes.
Volga Federal District
Nizhny Novgorod and Kazan manufacturing bases anchor domestic production for water-borne acrylic volume segments. Regional technical universities supply formulation chemists to local producers despite national enrollment declines. The Tatarstan petrochemical cluster provides captive binder inputs for integrated coating manufacturers.
Northwestern Federal District
St. Petersburg's renovation market pulls specification toward premium interior finishes with digital color-matching infrastructure. The Baltic Sea port facilitates import logistics for EU-origin raw materials and equipment. Leningrad Oblast distribution centers serve the Nordic-influenced architectural aesthetic preferences of this corridor.
Russia Architectural Coatings Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise commanding premium positioning in industrial niches while volume players compete on distribution density. The vendor base organizes around three strategic archetypes: integrated petrochemical-coating hybrids, European heritage brands with localized production, and regional distributors with technical service capabilities. M&A activity concentrates on distribution network consolidation in the Central Federal District, while capacity expansion targets Far Eastern supply gaps.
Within the European heritage tier, DAW SE and AkzoNobel N.V. exemplify manufacturers leveraging Central and Western European technical bases to serve Russian specification requirements. Lakra Sintez occupies a position among Siberian-focused distributors with deep regional construction market access. VGT Enterprise LLC represents the specialized industrial coating archetype, with formulation lines adapted to oil and gas infrastructure exposure conditions.
| Leading Market Players |
|---|
| DAW SE |
| Flügger group A/S |
| AkzoNobel N.V. |
| VGT Enterprise LLC |
| Lakra Sintez |
| PPG Industries, Inc. |
| Компания «Русские Краски» |
| Beckers Group |
| ABC Farben |
| Others |
Value Network & Pricing Analysis
Facade system integrators in Moscow's high-rise residential tower segment command consolidated procurement authority, compressing channel margins and shifting pricing power toward volume-contract structures with multi-year supply security clauses. This buyer concentration forces independent distributors toward service-based differentiation while reinforcing tiered pricing separation across GOST-certified premium grades, reformulated mid-tier acrylics, and economy alkyd lines.
Pricing Analysis
Distributor margins in the Central Federal District compress under specification consolidation by facade system integrators. Three-tier pricing structure across premium, standard, and economy levels tracks GOST R certification tier and titanium dioxide grade. Cost compression in mid-tier water-borne acrylics is intensifying because pending chalking resistance amendments force rutile pigment upgrades. DIY homeowners in Moscow retail channels show highest price sensitivity; oil and gas infrastructure contractors in Tyumen exhibit lowest sensitivity due to performance warranty requirements.
Supply Chain Analysis
Formulation chemist scarcity in Russian technical universities constrains domestic R&D pipeline replenishment, forcing manufacturers toward imported expertise. Raw material sourcing draws from Chinese sulfate-process titanium dioxide, German dispersion equipment, and domestic petrochemical binders from Tatarstan. Single-source vulnerability in EU-origin grinding machinery spare parts complicates capacity expansion timelines. Distribution runs through regional technical-service distributors in Siberia and Far Eastern construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia architectural coatings function as a stable compounder anchored by mandatory renovation cycles in Moscow's aging high-rise stock and federal infrastructure investment targeting Siberian and Far Eastern corridors.
For Market Incumbents: Deploy digital color-matching infrastructure to defend Moscow DIY channel position against retail consolidation. Deepen backward integration into captive titanium dioxide sourcing to offset Chinese supply volatility. Counter specification authority migration by bundling substrate preparation warranties with finish systems in high-rise envelope contracts. For New Entrants and Emerging Players: Capture Far Eastern Federal District supply gaps in Vladivostok and Khabarovsk where local production capacity lags new-build volumes. Target specialized industrial coating lines for Tyumen oilfield infrastructure where solvent-based alkyd adhesion performance commands premium positioning. Pursue EAEU mutual recognition pathways through Belarus laboratory accreditation to streamline multi-territory product registration. For Investors and Strategic Acquirers: European heritage coating manufacturers are the most active acquirer in this space, seeking distribution density in the Central Federal District. The five-to-ten-year viability thesis rests on regulatory harmonization completion across EAEU member states. Monitor Rosstandart GOST amendment publication timelines as inflection indicators for reformulation cost spikes and margin compression windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide | Captive pigment supply from Tatarstan petrochemical clusters reduces Chinese import dependency and cost volatility. |
| Digital Color-Matching Kiosk Deployment | Moscow retail chains compress SKU inventory by eighty percent while accelerating specification cycles in DIY renovation. |
| EAEU Mutual Recognition Expansion | Belarus and Armenia laboratory accreditations streamline multi-territory product launches across Russian, Kazakh, and Kyrgyz construction markets. |
| Facade System Integration Partnerships | Envelope performance warranty bundling consolidates procurement authority and displaces independent coating distributors from new-build capture. |
| Specialized Industrial Line Development | Tyumen oilfield pipeline coatings command premium positioning where substrate adhesion overrides VOC compliance preferences. |
Research Methodology
Multiple input streams — formulation chemist interviews, distributor procurement lead discussions, regulatory affairs consultations, and facade system integrator specification reviews — were reconciled against customs trade records, Rosstandart certification databases, EAEU technical regulation filings, and petrochemical industry association reports. Bottom-up volume estimates from regional construction permit data were triangulated with top-down market sizing derived from producer capacity disclosures and channel inventory audits.
Historical volume trajectories were cross-referenced against panel input from plant managers and technical R&D directors to establish baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, end-use application vertical, procurement channel type, and federal district regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating EAEU VOC limit implementation schedules and GOST amendment compliance cost assumptions.
Underlying measurement precision varies by segment; water-borne acrylic residential volumes carry tighter precision than specialized industrial alkyd estimates due to distributor reporting granularity differences. Forecasts reflect documented assumptions regarding EAEU regulatory harmonization pace and Rosstandart certification timeline normalization. Material deviation in federal infrastructure appropriation levels or titanium dioxide export restriction announcements warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Rail Coatings Market
Coatings
Insulation Coating Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Global Sputter Coatings Market
Coatings
South Korea Protective Coatings Market
Coatings
United States Industrial Wood Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Mexico Floor Coatings Market
Coatings
In-Mold Coatings Market
Coatings
Hull Coatings Market
Coatings
E-Coat Market
Coatings
Global Mirror Coatings Market
Coatings
Stain Resistance Coatings Market
Coatings
US Protective Coatings Market
Coatings
Wire Enamels Market